
 Solid Tumor Market | 2026-2036
Solid Tumor Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Tumor Market Outlook
Combination therapy bundling is repositioning prescribing behavior across solid tumor care, as clinicians seek integrated regimens that reduce resistance and improve progression-free survival. F. Hoffmann-La Roche Ltd. leverages its cross-portfolio diagnostics-to-therapeutics pipeline to anchor combination strategies in HER2-positive and PD-L1 expressing indications. Bristol-Myers Squibb Company sustains leadership in checkpoint inhibitor combinations through broad clinical trial networks and label expansions. Merck & Co., Inc. dominates the PD-1 landscape with extensive real-world evidence generation that reinforces payer negotiations and formulary positioning.
Solid tumors constitute malignant neoplasms arising from epithelial tissues, characterized by abnormal cell proliferation, angiogenesis, and metastatic potential, with treatment paradigms governed by histology, molecular profiling, and staging systems such as TNM classification. Immunotherapy segments command premium reimbursement as PD-1/PD-L1 inhibitors demonstrate durable responses in melanoma and non-small cell lung cancer, though chemotherapy retains substantial volume in platinum-sensitive settings. Targeted therapy segments compete on biomarker-defined populations, with EGFR, ALK, and KRAS inhibitors occupying distinct molecular niches that limit direct substitution and protect margin pools.
The FDA's accelerated approval and breakthrough therapy designations compress regulatory timelines for solid tumor agents, while EMA's conditional marketing authorization and PRIME scheme create parallel European access pathways that manufacturers must navigate simultaneously. Reimbursement frameworks, including Medicare's coverage with evidence development and NICE's technology appraisals in the United Kingdom, increasingly predicate market access on comparative overall survival data and health technology assessments. Stakeholders must monitor evolving biomarker regulatory standards and real-world evidence requirements that will determine which therapeutic modalities secure sustainable formulary placement without traditional randomized trial endpoints.
Market Dynamics
Combination therapy bundling is compressing prescribing behavior across solid tumor care, as clinicians seek integrated regimens that reduce resistance and improve progression-free survival. This structural force is reshaping how manufacturers position portfolios and negotiate formulary access.
Growth Catalysts
- FDA Accelerated Approval:The breakthrough therapy designation compresses development timelines and expands patient access to novel modalities. Oncology departments in tertiary hospitals drive adoption as first-line treatment settings.
- Biomarker-Defined Populations:Molecular profiling enables precision targeting of HER2-positive and PD-L1 expressing indications. Companion diagnostics anchor reimbursement and prescribing decisions.
- Medicare Reimbursement Policies:Concentrated specialist networks in the United States sustain premium pricing for immunotherapy segments. Coverage with evidence development supports conditional market access.
Market Restraints
- Platinum-Resistant Settings:Chemotherapy retains substantial volume in platinum-sensitive indications, limiting rapid substitution by targeted agents. Resistance mechanisms constrain durable response rates.
- Comparative Overall Survival Requirements:NICE technology appraisals in the United Kingdom increasingly predicate reimbursement on head-to-head mortality data. Traditional randomized trial endpoints face pressure from real-world evidence standards.
- Biomarker Testing Infrastructure:Uneven EGFR, ALK, and KRAS testing penetration creates prescribing friction outside major academic centers. Community oncology practices lack molecular pathology capacity.
Strategic Opportunities
- Real-World Evidence Generation:Extensive patient registry data reinforces payer negotiations and formulary positioning for PD-1 inhibitors. Electronic health record integration enables post-market surveillance at scale.
- EMA Conditional Marketing Authorization:The PRIME scheme creates parallel European access pathways that manufacturers must navigate simultaneously with FDA submissions. Early dialogue with regulators accelerates label strategy.
- Resistance Mechanism Targeting:Next-generation sequencing identifies emergent bypass pathways in EGFR-mutant non-small cell lung cancer. Sequential therapy design opens new molecular niches.
Industry Challenges
- Trial Endpoint Evolution:Regulators and payers demand progression-free survival and quality-of-life metrics alongside overall survival. Biostatistical expertise in adaptive trial design remains scarce.
- Cross-Border Evidence Harmonization:Divergent biomarker regulatory standards between FDA and EMA complicate global development programs. Regional variation in companion diagnostic approval timelines fragments launch sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Tumor Market |
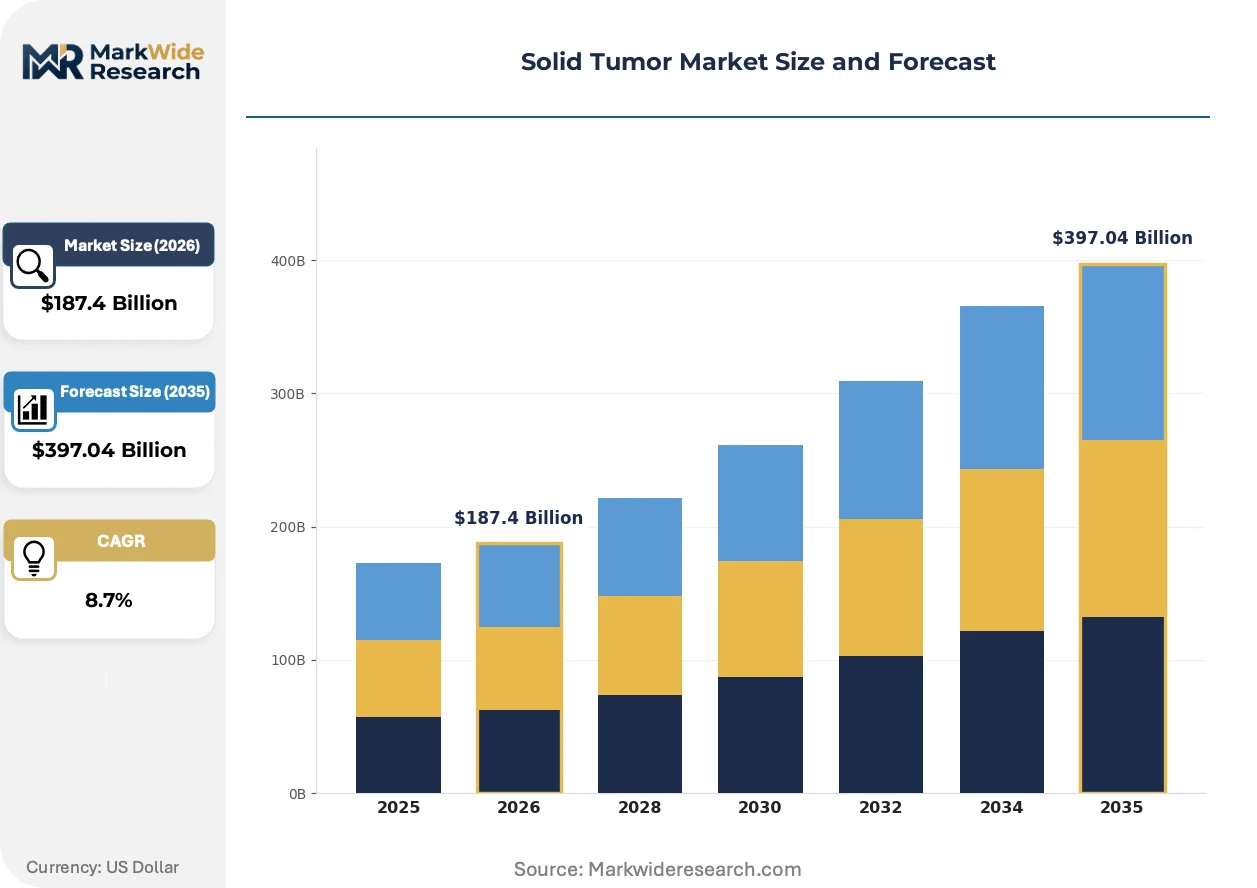
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Immunotherapy, Chemotherapy, Radiation Therapy Application: Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer End User: Hospitals, Cancer Treatment Centers, Research Institutes, Homecare Settings Technology: Genetic Testing, Biomarker Analysis, Imaging Techniques, Surgery |
| Companies Covered | F. Hoffmann-La Roche Ltd., AstraZeneca plc, Bristol-Myers Squibb Company, Pfizer Inc., Novartis AG, Amgen Inc., Eli Lilly and Company, Merck & Co., Inc., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Tumor Market Strategic Shifts
Artificial intelligence is reshaping drug discovery and clinical trial design in solid tumor development, compressing target identification timelines and enabling synthetic control arms. These shifts are altering competitive positioning across the therapeutic landscape.
Next-generation sequencing platforms are integrating multi-omic profiling into standard-of-care workflows. Academic medical centers in the United States and Germany deploy comprehensive genomic profiling at diagnosis. This convergence is enabling basket trial enrollment and compressing the gap between molecular identification and targeted therapy initiation.
EMA's PRIME scheme and FDA's breakthrough therapy designation are creating parallel accelerated pathways that compress regulatory review timelines. Manufacturers must navigate simultaneous submissions with divergent evidence requirements. Small and mid-cap developers face particular strain in managing multi-jurisdictional health technology assessment preparations.
Hospital procurement is consolidating oncology drug purchasing through specialty pharmacy networks and group purchasing organizations. Integrated delivery networks in the United States negotiate bundled reimbursement for combination regimens. This concentration shifts bargaining power toward institutional buyers and pressures traditional physician-administered drug margins.
Solid Tumor Market Segmentation
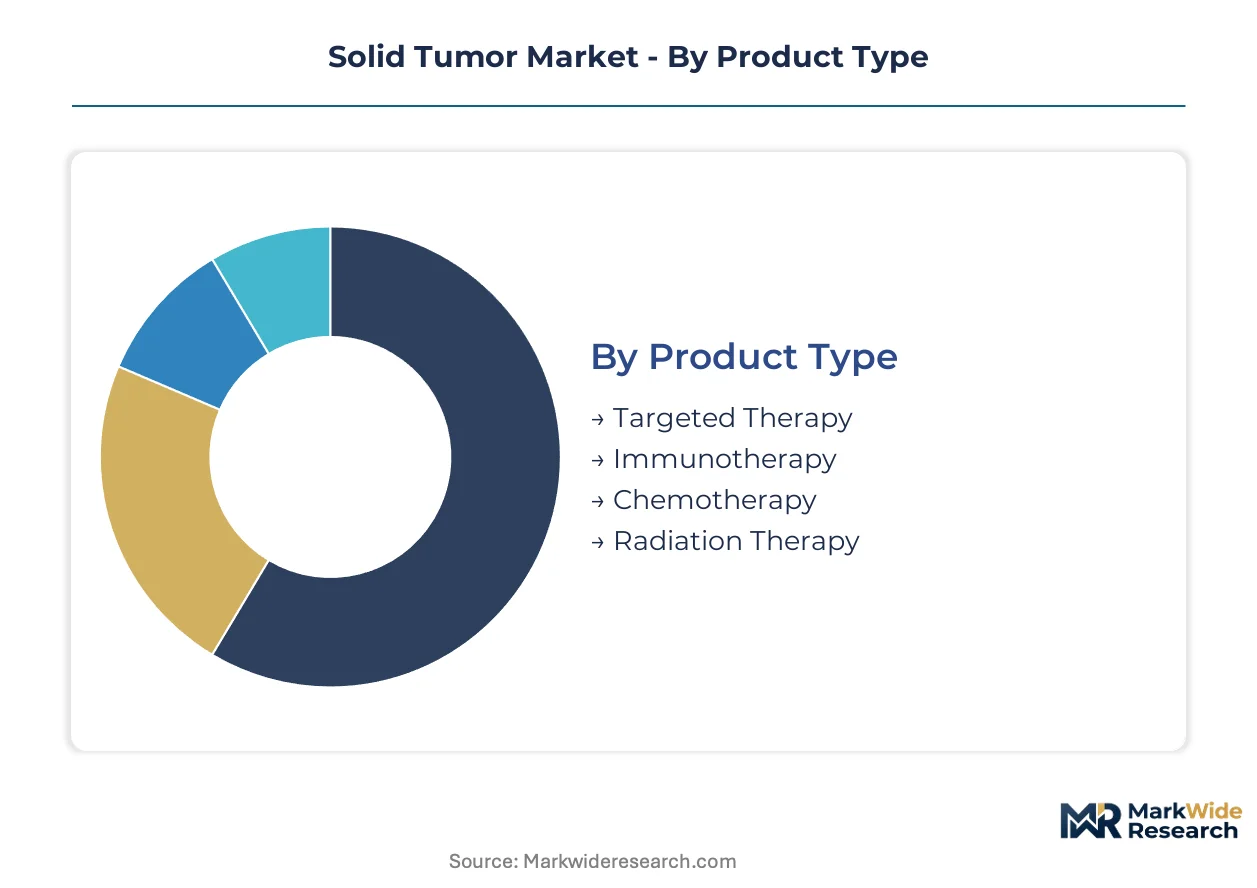
Molecular stratification and site-of-care economics fragment the solid tumor market into distinct commercial battlegrounds. Each segmentation dimension carries unique regulatory, reimbursement, and competitive dynamics that shape portfolio prioritization and go-to-market sequencing.
Product Type:
FDA breakthrough therapy designation and EMA PRIME eligibility vary sharply across modalities, with immunotherapy and targeted therapy commanding accelerated pathways while chemotherapy faces compressed development incentives.
- Targeted Therapy:Small-molecule inhibitors and monoclonal antibodies directed against EGFR, ALK, KRAS, and HER2 molecular alterations. Demand concentrates in academic medical centers with integrated molecular pathology laboratories, where companion diagnostic co-approval with FDA accelerates formulary placement.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 and CTLA-4 pathways, plus emerging bispecific constructs. PD-1 inhibitors dominate prescribing in melanoma and non-small cell lung cancer, with Medicare reimbursement sustaining premium pricing despite biosimilar entry pressures in European markets.
- Chemotherapy:Platinum agents, taxanes, and antimetabolites retain substantial volume in platinum-sensitive ovarian and testicular malignancies. Community oncology practices depend on these agents where molecular testing infrastructure remains underdeveloped.
- Radiation Therapy:External beam, brachytherapy, and stereotactic ablative modalities delivered through hospital-based linear accelerators. Capital equipment requirements limit site expansion and concentrate treatment in tertiary referral networks.
Leading the category by volume: Chemotherapy. Growing fastest: Immunotherapy.
Application:
Incidence patterns and screening penetration create divergent addressable patient pools across malignancy types, with lung and breast cancers offering the largest commercial opportunities.
- Breast Cancer:Hormone receptor-positive, HER2-positive, and triple-negative subtypes each demand distinct therapeutic approaches. HER2-targeted agents anchor premium pricing in academic centers, while CDK4/6 inhibitors expand the addressable population in hormone receptor-positive disease.
- Lung Cancer:Non-small cell histology dominates, with EGFR-mutant and ALK-rearranged subsets driving targeted therapy adoption. Screening programs in the United States and Germany are shifting stage distribution toward earlier diagnoses.
- Colorectal Cancer:MSI-high status determines immunotherapy eligibility in metastatic settings. KRAS G12C inhibitors are penetrating second-line therapy after chemotherapy progression.
- Prostate Cancer:Androgen receptor pathway inhibitors and PARP inhibitors compete across castration-resistant settings. PSMA-targeted radioligand therapy is reshaping late-line treatment algorithms.
Highest revenue concentration: Lung Cancer. Steepest expansion trajectory: Breast Cancer immunotherapy combinations.
End User:
Site-of-care economics and reimbursement mechanics fragment purchasing authority across institutional settings with divergent formulary control and infusion capacity.
- Hospitals:Tertiary academic medical centers anchor first-line adoption of novel agents through 340B pricing advantages and integrated specialty pharmacy operations. Inpatient infusion capacity constrains rapid volume scaling.
- Cancer Treatment Centers:Dedicated oncology networks concentrate phase I trial enrollment and early access programs. Community-based centers depend on group purchasing organizations for drug procurement leverage.
- Research Institutes:NCI-designated cancer centers drive biomarker discovery and basket trial infrastructure. Preclinical and translational research collaborations shape pipeline prioritization for manufacturers.
- Homecare Settings:Oral targeted agents and subcutaneous immunotherapy formulations enable administration outside infusion centers. Reimbursement complexity limits penetration for physician-administered products.
Dominant by patient volume: Hospitals. Expanding most quickly: Cancer Treatment Centers.
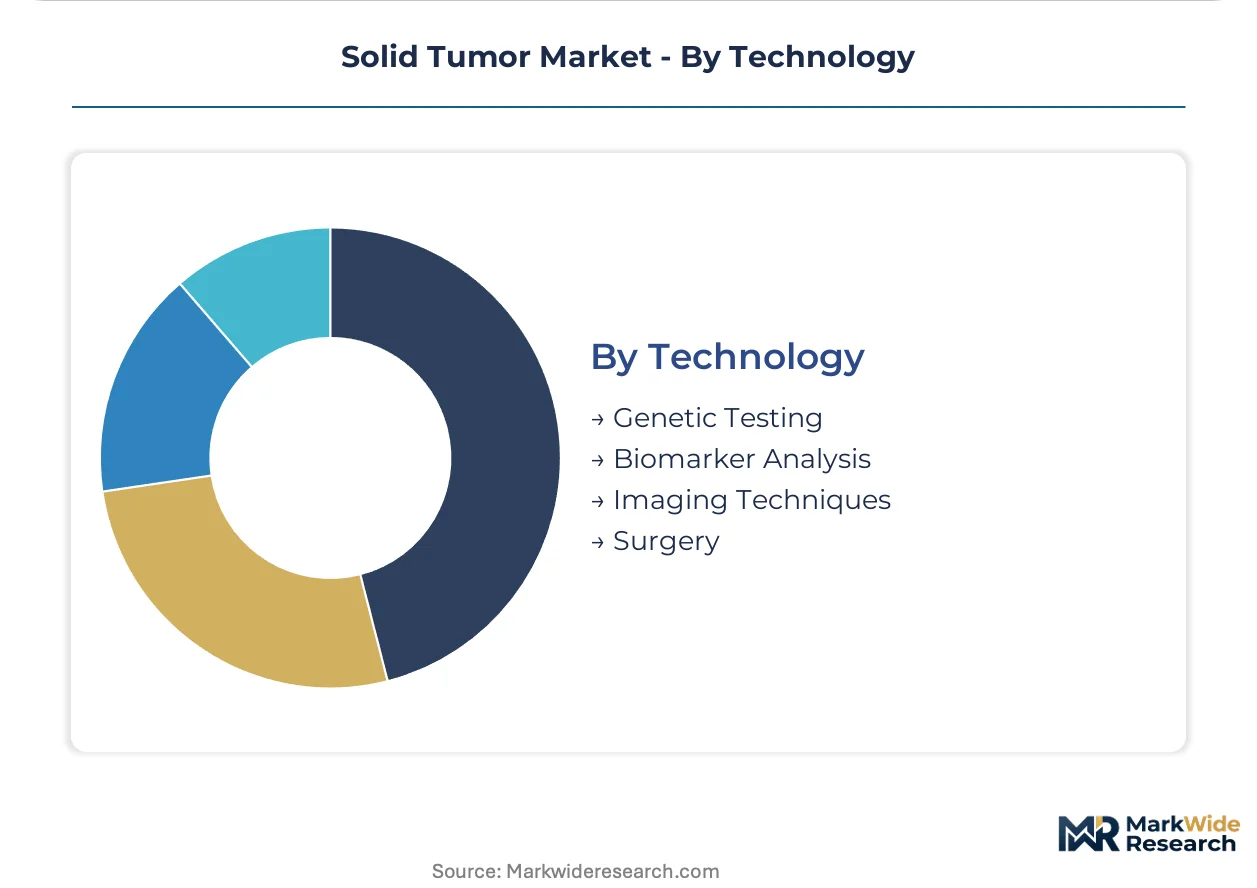
Technology:
Diagnostic and therapeutic technology convergence determines treatment sequencing and creates dependencies between platform vendors and drug manufacturers.
- Genetic Testing:Next-generation sequencing panels identify actionable alterations across solid tumor types. Comprehensive genomic profiling at diagnosis enables precision therapy matching in academic centers.
- Biomarker Analysis:PD-L1 immunohistochemistry and microsatellite instability testing gate immunotherapy access. Companion diagnostic co-development with FDA streamlines label alignment.
- Imaging Techniques:PET-CT and MRI guide staging and response assessment. Radiomics and artificial intelligence applications are emerging in trial endpoint quantification.
- Surgery:Resection remains curative-intent standard for localized disease. Minimally invasive and robotic approaches reduce recovery timelines and expand eligible patient pools.
Widest installed base: Imaging Techniques. Gaining share fastest: Genetic Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and the Greater Boston biotechnology corridor concentrate early-stage solid tumor drug development, with tax-advantaged zones accelerating clinical infrastructure buildout across multiple jurisdictions.
United States
Medicare reimbursement policies sustain premium pricing for PD-1 inhibitors, while the FDA's breakthrough therapy designation compresses regulatory timelines for novel modalities. The 340B drug pricing program enables tertiary academic medical centers to capture margin on infused oncology therapies. NCI-designated cancer centers in Houston and Seattle anchor basket trial enrollment and biomarker discovery pipelines.
Germany
Comprehensive genomic profiling at diagnosis is shifting treatment sequencing in non-small cell lung cancer, with statutory health insurance funds negotiating outcomes-based contracts for CAR-T and bispecific constructs. The Federal Joint Committee (G-BA) early benefit assessment mandates comparative effectiveness data for reimbursement. Heidelberg and Munich academic clusters concentrate phase I trial infrastructure and molecular pathology laboratories.
China
Domestic PD-1 developers are capturing share in esophageal and nasopharyngeal carcinoma indications, with NMPA priority review pathways accelerating approval for therapies addressing high unmet need. National reimbursement drug list (NRDL) negotiations compress pricing for imported innovators while expanding patient access. Shanghai Zhangjiang Hi-Tech Park anchors contract development and manufacturing capacity for biologics.
United Kingdom
NICE technology appraisals predicate market access on comparative overall survival data, with the Cancer Drugs Fund enabling conditional reimbursement pending real-world evidence generation. NHS England's specialized commissioning framework concentrates high-cost immunotherapy administration in designated cancer centers. The Cambridge-London corridor integrates genomic medicine centers with early-phase clinical trial units.
Japan
PMDA's sakigake designation accelerates review for regenerative medicines and breakthrough oncology therapies, with pricing premiums awarded for comparative clinical benefit demonstrated against standard of care. The Ministry of Health, Labour and Welfare's Chuikyo pricing council is revising reimbursement methodology to incorporate cost-effectiveness thresholds. Osaka and Tokyo metropolitan areas concentrate phase I/II trial enrollment capacity and molecular diagnostic laboratory networks.
Solid Tumor Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the solid tumor landscape, creating a tiered competitive structure where scale advantages in regulatory affairs and real-world evidence generation offset the agility of mid-cap developers. Large-cap pharmaceutical companies anchor combination therapy bundling through cross-portfolio diagnostics-to-therapeutics integration. Mid-cap biotechs occupy molecularly defined niches in EGFR, ALK, and KRAS inhibitor development. Strategic moves concentrate on companion diagnostic co-development partnerships and adaptive licensing negotiations with FDA and EMA.
Among Swiss-diversified pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd. and Novartis AG exemplify the integrated diagnostics-therapeutics archetype. Bristol-Myers Squibb Company and Merck & Co., Inc. occupy positions within the checkpoint inhibitor leadership tier, representing the scale-driven competitive vector where extensive clinical trial networks reinforce formulary positioning.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| AstraZeneca plc |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Novartis AG |
| Amgen Inc. |
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Sanofi |
| Others |
Value Chain & Pricing Dynamics
Oncology biostatistician concentrations in Research Triangle Park and Greater Boston create labor-cost differentials that widen pricing-tier spreads between premium combination regimens and commoditized chemotherapy backbones.
Pricing Analysis
Lead-time-driven pricing angles dominate solid tumor procurement, with premium positioning for FDA breakthrough-designated agents with compressed regulatory timelines and discounted spot inventory for platinum-taxane combinations nearing patent expiry. Three-tier pricing structure across premium, standard, and economy levels separates PD-1/PD-L1 immunotherapy from targeted small molecules from generic chemotherapy, with price differentiation anchored in companion diagnostic co-approval status and Medicare coverage determination speed. Pricing pressure stems from NRDL negotiations in China and NICE technology appraisals in the United Kingdom demanding comparative overall survival data. Community oncology practices exhibit highest price sensitivity due to thin infusion margins, while tertiary academic centers with 340B pricing advantages absorb premium novel agents.
Supply Chain Analysis
Dual-sourcing requirements from hospital procurement committees mandate multi-supplier qualification for critical biologics, forcing manufacturers to maintain redundant fill-finish capacity across contract manufacturing networks. Supply concentrates in the United States for monoclonal antibody drug substance, Switzerland for fill-finish of high-value oncology injectables, and China for active pharmaceutical ingredients in small-molecule targeted agents. Raw material dependencies include recombinant cell culture media, single-use bioreactor bags, and cytotoxic containment infrastructure. Single-source vulnerability in cold-chain logistics for temperature-sensitive biologics creates supply risk. Distribution runs through specialty pharmacy networks and group purchasing organizations that consolidate oncology drug purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solid tumor market functions as a cost-of-compliance story where FDA's breakthrough therapy designation and EMA's PRIME scheme erect barrier-to-entry moats favoring manufacturers with established regulatory affairs infrastructure and real-world evidence generation capabilities.
For Market Incumbents: Anchor formulary positioning through companion diagnostic co-development partnerships that gate access to biomarker-defined populations, while expanding real-world evidence registries to defend against biosimilar entry in European markets. Vertical integration into multi-omic profiling platforms offsets margin pressure from institutional buyer consolidation. Capacity addition in Shanghai Zhangjiang Hi-Tech Park secures supply chain redundancy for Asia-Pacific volume scaling. For New Entrants and Emerging Players: AI-enabled clinical trial design offers a technology-first wedge to compress development timelines and reduce biostatistical expertise barriers that constrain adaptive trial execution. Underpenetrated community oncology practices in the United States represent the most penetrable segment, lacking molecular pathology capacity for EGFR, ALK, and KRAS testing. Licensing agreements with NCI-designated cancer centers provide go-to-market credibility for basket trial enrollment. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap developers possessing FDA breakthrough-designated assets in resistance mechanism targeting, given the catalyst of sequential therapy design opening new molecular niches in EGFR-mutant non-small cell lung cancer. Long-term viability favors platforms with integrated diagnostics-to-therapeutics pipelines over single-asset developers. Watch for inflection in EMA conditional marketing authorization conversion rates to full approval as signal of regulatory execution quality.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA co-approval accelerates formulary placement in academic medical centers with integrated molecular pathology laboratories. |
| Real-World Evidence Registry Expansion | Electronic health record integration reinforces payer negotiations and defends premium positioning against biosimilar entry. |
| Multi-Jurisdictional Regulatory Submission | Simultaneous FDA and EMA filings compress review timelines and capture priority market access windows. |
| Specialty Pharmacy Network Partnership | Integrated delivery network bundling shifts procurement leverage toward institutional buyers requiring channel control. |
| Resistance Mechanism Pipeline Diversification | Next-generation sequencing-identified bypass pathways in EGFR-mutant disease open sequential therapy molecular niches. |
Study Parameters
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from CMS Medicare reimbursement data, NICE technology appraisal documentation, and GPO contract records. Bottom-up patient-flow modeling and top-down market sizing triangulated volume and value estimates.
Cross-reference approaches integrated historical approval trajectory analysis with expert panel input on regulatory pathway probability and reimbursement negotiation outcomes. Segmentation dimensions modeled include treatment line, molecular alteration status, administration route, and regional regulatory cluster across the analysis window. CAGRs derived from patient incidence projections, therapy penetration curves, and pricing elasticity assumptions. Forecast inputs incorporated biomarker testing infrastructure buildout rates and companion diagnostic adoption timelines.
Several conditions sit outside the modeled scope, including unforeseen resistance mechanism biology shifts, abrupt regulatory standard changes for real-world evidence acceptance, and major therapeutic class safety signals triggering label restrictions. Deviation in FDA breakthrough therapy designation conversion rates to full approval would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market
Oncology
Interventional Oncology Ablation Market
Oncology
Colorectal Cancer Screening Market
Oncology
Asia-Pacific Cancer Biomarkers Market
Oncology
Breast Cancer Brachytherapy Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
Metastatic Cancer Drug Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Internal Radiation Therapy Market
Oncology
Radiotherapy Market
Oncology
Metastatic Melanoma Market
Oncology
Europe Radiotherapy Patient Positioning Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Europe Tumor Ablation Market
Oncology
Testicular Cancer Treatment Market