
 Ustekinumab Market | 2026-2036
Ustekinumab Market Size, Share, and Industry Trends Forecast 2026-2036
Ustekinumab Market Analysis
Gastroenterology is shifting toward earlier biologic intervention, pulling demand from traditional dermatology-led prescribing. Johnson & Johnson anchors originator market presence through Stelara's established immunology franchise. Samsung Bioepis competes in the biosimilar lane with manufacturing scale across European and Asian markets. Celltrion leverages vertical bioprocessing capabilities to sustain cost positioning against reference-product pricing.
Ustekinumab is a human monoclonal antibody targeting the p40 subunit shared by interleukin-12 and interleukin-23 cytokines, administered via subcutaneous or intravenous routes for autoimmune modulation. The injectable product type dominates current revenue as prefilled syringe and pen formats reduce healthcare system administration burden. Biosimilar entrants are gaining fastest traction in European markets where tender-based procurement accelerates switching protocols. Therapy area concentration sits with psoriasis and Crohn's Disease, though ulcerative colitis label expansion is redirecting R&D investment toward gastrointestinal indications.
The FDA's biosimilar interchangeability standards and the EMA's biosimilar comparability guidelines shape product development timelines and commercial launch sequencing across North America and Europe. Health Canada's PMRA and the UK's MHRA maintain aligned but distinct approval pathways that fragment regulatory strategy for multi-market entrants. Stakeholders must monitor FDA interchangeability designation decisions and EMA extrapolation policy changes to anticipate competitive substitution velocity and pricing compression timing.
Market Dynamics
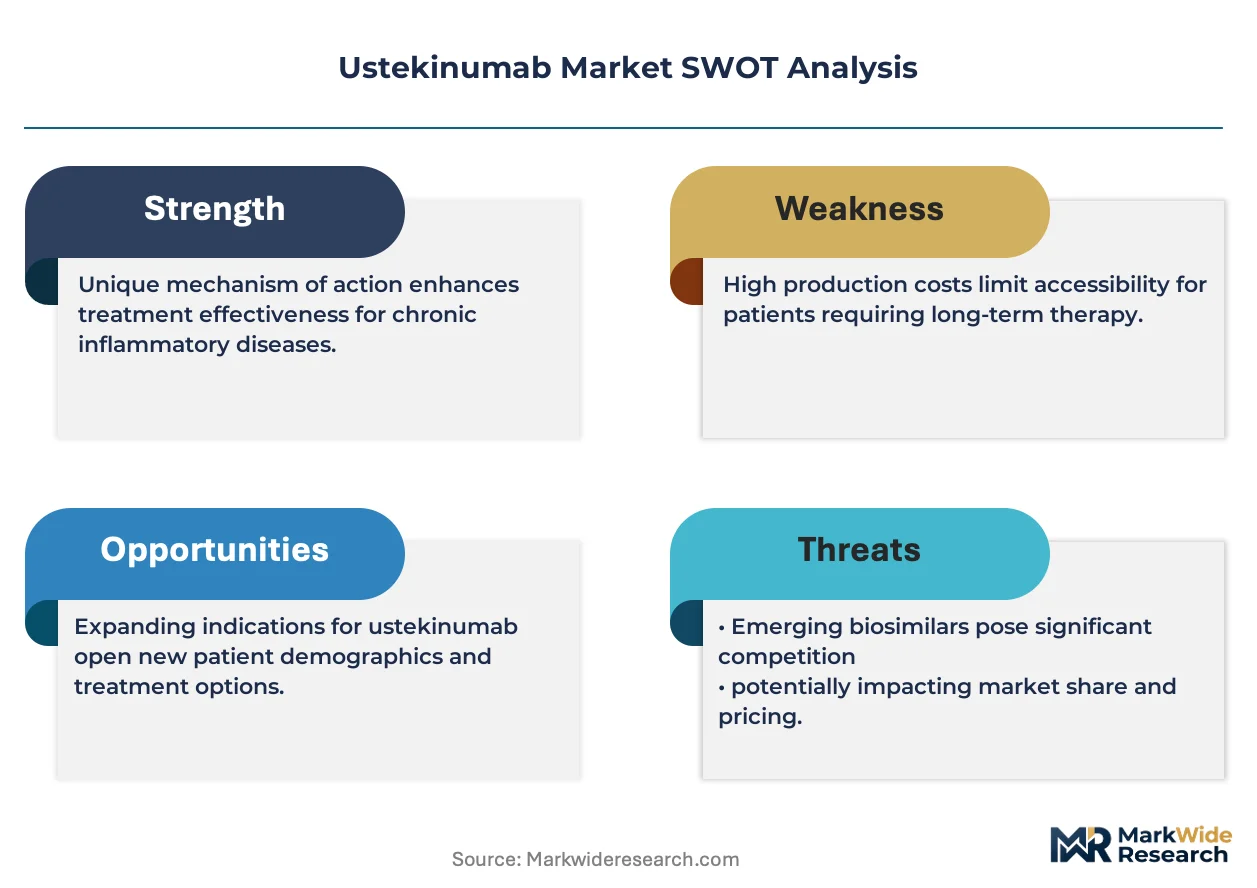
Gastroenterology clinics are accelerating biologic adoption timelines as ulcerative colitis and Crohn's disease indications reshape prescriber behavior away from traditional step-up protocols. The FDA's biosimilar interchangeability pathway and EMA's comparability frameworks are compressing competitive entry windows while fragmenting pricing power.
Growth Catalysts
- EMA Extrapolation Policy:The EMA's comparability guidelines enable biosimilar developers to leverage psoriasis efficacy data for Crohn's disease approvals, truncating clinical development timelines.
- Subcutaneous Pen Formats:Prefilled autoinjector devices are displacing intravenous infusion in maintenance therapy, reducing site-of-care costs and expanding patient self-administration.
- United States:Specialty pharmacy networks and prior authorization digitization are compressing time-to-therapy initiation for biologic-naive patients.
Market Restraints
- Plasmid DNA Supply Concentration:Contract manufacturing organizations in South Korea and Singapore control critical pDNA template supply for mammalian cell line development, creating single-source vulnerability.
- Protein A Resin Cost Volatility:Chromatography resin pricing fluctuations directly compress biosimilar manufacturing margins during scale-up phases.
- FDA Interchangeability Barriers:The FDA's switching study requirements for automatic substitution at pharmacy level delay biosimilar uptake velocity versus European tender markets.
Strategic Opportunities
- India:CDSCO's accelerated approval pathway for biosimilars with established reference product history creates first-mover positioning in an underpenetrated gastroenterology market.
- Home Infusion Services:Third-party logistics providers are building cold-chain direct-to-patient capabilities that bypass traditional hospital outpatient department economics.
- Interleukin-23 Selective Antagonists:Next-generation cytokine targeting is creating headroom for ustekinumab positioning in combination protocols and sequencing algorithms.
Industry Challenges
- Analytical Biosimilarity Assessment:Characterization of post-translational modifications and glycan profiling requires specialized mass spectrometry expertise that concentrates in contract research organizations.
- Legacy Refrigeration Infrastructure:Distribution networks in secondary United States markets lack validated 2-8°C storage capacity for biologics, forcing hub-and-spoke inventory models that extend lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ustekinumab Market |
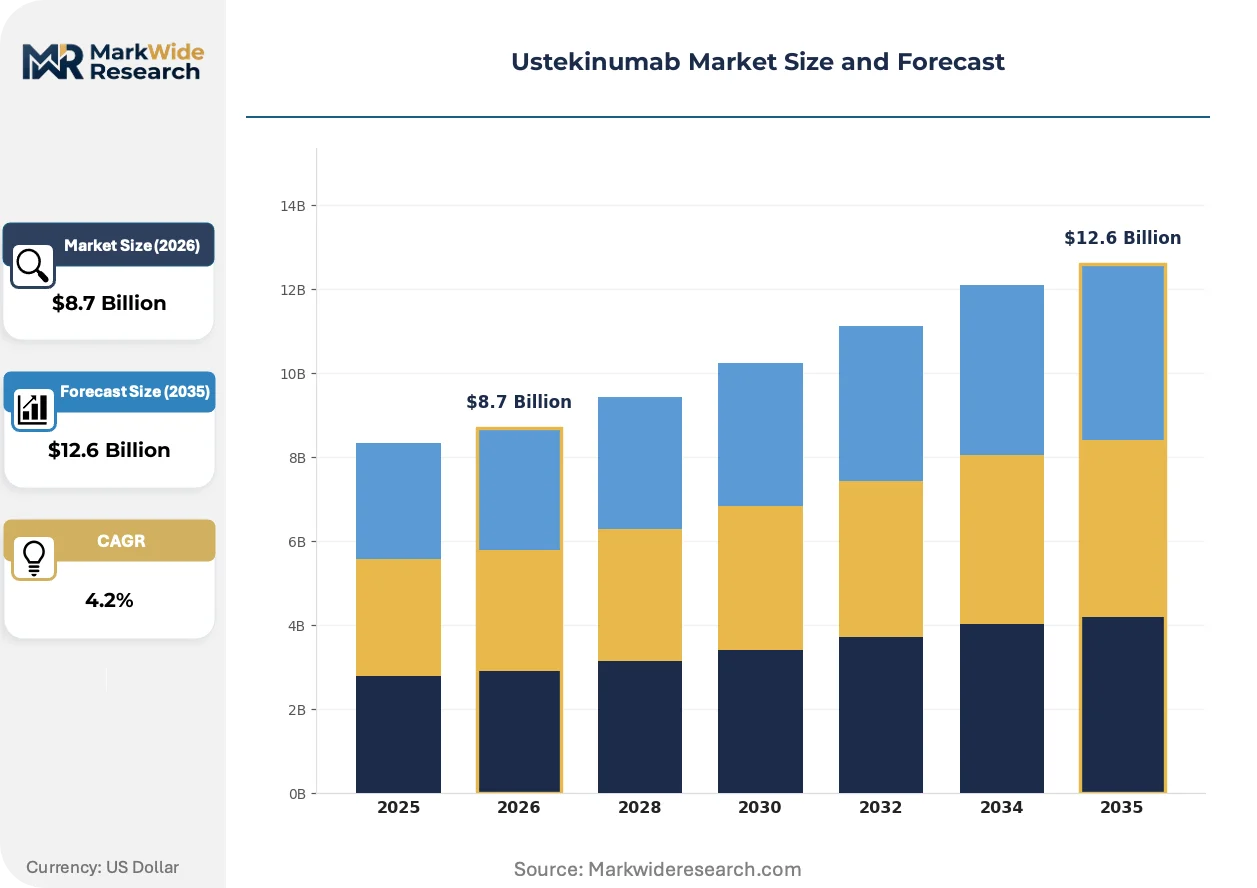
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Biosimilar, Combination Therapy Therapy Area: Psoriasis, Crohn's Disease, Ulcerative Colitis, Atopic Dermatitis Delivery Mode: Subcutaneous, Intravenous, Patch, Inhalation End User: Hospitals, Clinics, Specialty Pharmacies, Homecare Settings |
| Companies Covered | Celltrion, Biocon, Johnson & Johnson, Accord BioPharma, Alvotech, Amgen, Fresenius Kabi, Bio-Thera Solutions, Samsung Bioepis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ustekinumab Market Emerging Trajectories
Biologic manufacturing and patient access models are converging around decentralization, with technology and regulatory frameworks pulling in parallel directions. Three developments are compressing traditional value chain structures.
Continuous bioprocessing technology is displacing fed-batch stainless steel manufacturing in mammalian cell culture. Contract development organizations in Switzerland and Massachusetts are adopting perfusion-based upstream platforms that reduce facility footprint requirements. This manufacturing architecture is decentralizing production capacity toward regional fill-finish sites, shortening supply chains for temperature-sensitive biologics.
The FDA's biosimilar interchangeability designation pathway is reshaping pharmacy-level substitution protocols. Automatic substitution at retail pharmacy level, once granted, triggers state-level pharmacy board implementation timelines. United States commercial payers are responding with formulary tiering that favors interchangeable products over reference biologics in maintenance therapy populations.
Specialty pharmacy consolidation is compressing patient onboarding timelines. Large pharmacy benefit managers are acquiring independent specialty pharmacies to capture biologic dispensing margins previously retained by hospital outpatient departments. This channel shift is most visible in United States dermatology and gastroenterology practices, where prior authorization automation is reducing therapy initiation delays.
Ustekinumab Market Segmentation
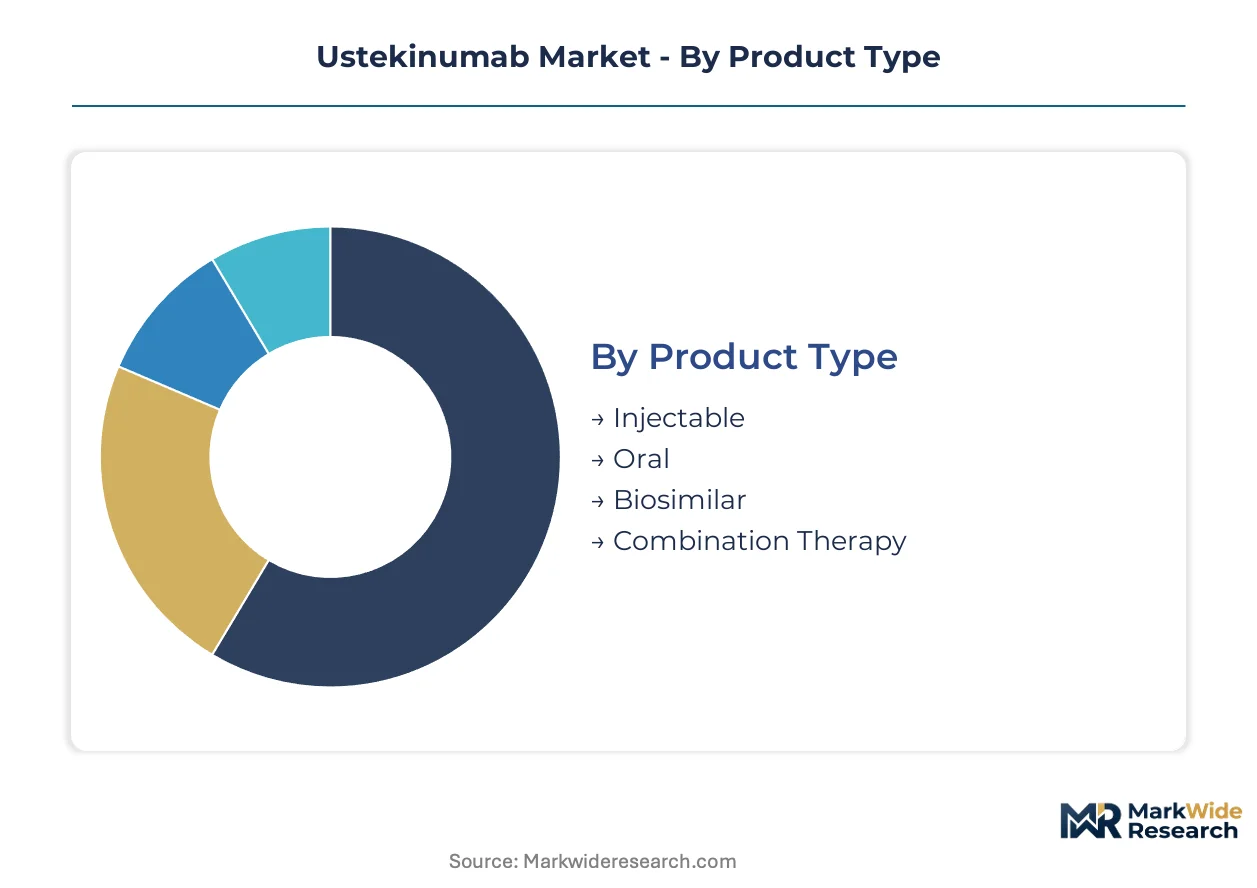
Ustekinumab's commercial architecture fragments across four critical dimensions: molecular format, therapeutic indication, administration route, and care setting. Each axis carries distinct margin profiles, regulatory requirements, and competitive entry barriers that reshape portfolio prioritization.
Product Type:
Injectable formulations anchor current revenue concentration through established immunology franchises.
- Injectable:Subcutaneous and intravenous formulations dominate commercial volume through prefilled syringe and pen devices. Gastroenterology clinics in the United States are accelerating maintenance therapy transitions to self-administered subcutaneous formats, compressing site-of-care costs.
- Biosimilar:EMA comparability guidelines and FDA interchangeability pathways are truncating development timelines for p40-targeting alternatives. Tender-based procurement in European markets is accelerating switching velocity versus United States prior authorization protocols.
- Oral:Small-molecule delivery remains preclinical for IL-12/23 pathway modulation.
- Combination Therapy:Sequencing protocols with methotrexate or TNF inhibitors are expanding in refractory Crohn's populations.
Mature deployment sits with Injectable formats. Newer deployment is concentrated in Biosimilar manufacturing scale-up.
Therapy Area:
Indication expansion is redirecting prescriber behavior from dermatology toward gastrointestinal specialties.
- Psoriasis:Plaque psoriasis established the reference product's efficacy profile through long-term safety databases. United States dermatology practices maintain high biologic penetration, though prior authorization automation is compressing initiation timelines.
- Crohn's Disease:Gastroenterology clinics are displacing traditional step-up protocols with earlier biologic intervention. The EMA's extrapolation policy enables psoriasis efficacy data to support Crohn's approvals, truncating biosimilar clinical development.
- Ulcerative Colitis:Label expansion is redirecting R&D investment toward colorectal immunology protocols.
- Atopic Dermatitis:Off-label utilization is emerging in refractory pediatric populations.
Mature deployment sits with Psoriasis. Newer deployment is concentrated in Crohn's Disease prescriber base conversion.
Delivery Mode:
Administration convenience is displacing infusion-center economics across maintenance populations.
- Subcutaneous:Prefilled autoinjector devices reduce healthcare system administration burden and expand patient self-administration. Specialty pharmacy networks in the United States are capturing dispensing margins previously retained by hospital outpatient departments.
- Intravenous:Induction dosing in biologic-naive patients maintains site-of-care requirements. Protein A resin cost volatility during scale-up phases directly compresses manufacturing margins for intravenous formulation batches.
- Patch:Transdermal delivery remains investigational for monoclonal antibody stability.
- Inhalation:Pulmonary targeting is not clinically validated for systemic immunomodulation.
Mature deployment sits with Intravenous induction protocols. Newer deployment is concentrated in Subcutaneous maintenance transitions.
End User:
Channel consolidation is redistributing economic value across the care continuum.
- Specialty Pharmacies:Large pharmacy benefit managers are acquiring independent dispensers to capture biologic margins. Prior authorization digitization is reducing therapy initiation delays for dermatology and gastroenterology practices.
- Hospitals:Infusion centers retain induction dosing for biologic-naive patients with complex comorbidities. Legacy refrigeration infrastructure in secondary United States markets forces hub-and-spoke inventory models.
- Clinics:Gastroenterology and dermatology offices are accelerating biologic adoption timelines.
- Homecare Settings:Third-party logistics providers are building cold-chain direct-to-patient capabilities that bypass traditional hospital economics.
Mature deployment sits with Hospital infusion centers. Newer deployment is concentrated in Homecare direct-to-patient logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty pharmacy networks and prior authorization digitization in the United States concentrate commercial value for ustekinumab distribution. Gastroenterology clinic expansion and biosimilar tender markets in Europe reshape competitive entry sequencing. Manufacturing scale-up in South Korea and India introduces new supply nodes for p40-targeting biologics.
United States
Specialty pharmacy consolidation captures biologic dispensing margins previously retained by hospital outpatient departments. The FDA's biosimilar interchangeability pathway shapes automatic substitution protocols at state pharmacy board level. The Boston-Cambridge biotech corridor anchors immunology R&D investment for next-generation cytokine targeting.
Germany
Tender-based procurement accelerates biosimilar switching velocity in statutory health insurance funds. The EMA's comparability guidelines enable extrapolation from psoriasis to Crohn's disease approvals, truncating clinical development timelines. The Rhine-Main biopharma cluster hosts contract manufacturing organizations scaling mammalian cell culture for European supply.
South Korea
Contract manufacturing organizations control critical plasmid DNA template supply for cell line development, creating single-source vulnerability in upstream bioprocessing. The MFDS maintains aligned biosimilar approval pathways with EMA standards. The Songdo biotech cluster concentrates perfusion-based manufacturing platforms for regional fill-finish capacity.
India
CDSCO's accelerated approval pathway for biosimilars with established reference product history creates first-mover positioning in underpenetrated gastroenterology markets. Domestic biopharma investment redirects toward monoclonal antibody manufacturing scale-up. The Hyderabad-Genome Valley corridor anchors analytical biosimilarity assessment capabilities for emerging market entry.
Switzerland
Continuous bioprocessing technology adoption in contract development organizations reduces facility footprint requirements for mammalian cell culture. Swissmedic maintains distinct but aligned biosimilar frameworks with EMA comparability standards. The Basel biopharma hub concentrates fill-finish capacity for temperature-sensitive biologics distribution across European markets.
Ustekinumab Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator franchises anchoring premium positioning and biosimilar developers compressing pricing through manufacturing scale. The competitive structure concentrates around three strategic archetypes: established immunology franchises with long-term safety databases, vertically integrated bioprocessors with captive resin supply, and emerging market biosimilar specialists with accelerated regulatory pathways. Dominant competitive moves include specialty pharmacy network acquisitions and continuous manufacturing technology licensing.
Among originator-anchored multinationals, Johnson & Johnson exemplifies the established immunology franchise archetype through its Stelara brand presence. Samsung Bioepis and Celltrion occupy positions within the vertically integrated bioprocessor tier, with manufacturing scale spanning European and Asian markets. These three companies represent distinct competitive positioning vectors: brand heritage, manufacturing integration, and cost-driven biosimilar entry.
| Leading Market Players |
|---|
| Celltrion |
| Biocon |
| Johnson & Johnson |
| Accord BioPharma |
| Alvotech |
| Amgen |
| Fresenius Kabi |
| Bio-Thera Solutions |
| Samsung Bioepis |
| Others |
Supply Flow & Price Mechanics
Protein A resin pricing volatility cascades through bioprocessing economics into three distinct pricing tiers for p40-targeting biologics. Manufacturers with captive chromatography supply command premium positioning against spot-market dependent competitors facing margin compression during scale-up phases.
Pricing Analysis
Short lead-time premiums separate originator Stelara positioning from biosimilar economy tiers in tender-based European markets. Pricing stratifies across premium originator, standard licensed biosimilar, and economy tender-award tiers based on interchangeability designation status and manufacturing scale. Cost compression in the standard tier intensifies as Samsung Bioepis and Celltrion expand perfusion-based capacity. Hospital procurement managers exhibit highest price sensitivity for maintenance therapy populations, while specialty pharmacies prioritize interchangeability premiums for pharmacy-level substitution eligibility.
Supply Chain Analysis
Reverse-logistics for temperature excursions drives hub-and-spoke inventory models in secondary United States markets lacking validated cold-chain infrastructure. Upstream bioprocessing concentrates in South Korea, Singapore, and Switzerland through contract manufacturing organizations controlling plasmid DNA template supply. Mammalian cell culture draws from Chinese hamster ovary lineages and perfusion-based platforms. Single-source vulnerability in pDNA supply creates structural risk for multi-product biologic manufacturers. Distribution runs through specialty pharmacy networks capturing dispensing margins previously retained by hospital outpatient departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around manufacturing scale and interchangeability designation, with FDA switching study requirements forcing sub-scale biosimilar developers toward partnership or exit.
For Market Incumbents: Cement originator positioning through preemptive interchangeability litigation and specialty pharmacy network acquisitions. Johnson & Johnson should accelerate prior authorization digitization partnerships to compress biosimilar switching velocity. Captive Protein A resin supply and continuous bioprocessing licensing represent critical defensive levers against vertically integrated Korean competitors.
For New Entrants and Emerging Players: The mid-tier price-point gap between European tender-awarded biosimilars and United States interchangeability premiums creates white-space opportunity. Target India's underpenetrated gastroenterology market through CDSCO's accelerated approval pathway for established reference products. Home infusion direct-to-patient logistics offers the most penetrable channel angle for bypassing hospital outpatient department economics.
For Investors and Strategic Acquirers: The window for entry favors contract manufacturing organizations with validated mammalian cell culture capacity and existing pDNA supply relationships. Long-term viability hinges on continuous bioprocessing technology adoption and regional fill-finish footprint. Monitor FDA interchangeability designation decisions for Stelara biosimilars as the inflection signal triggering formulary tiering shifts among United States commercial payers.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Perfusion-based platforms in Songdo and Basel reduce facility footprint for regional supply. |
| Regulatory Approval Pathway | EMA extrapolation policy truncates Crohn's disease development timelines for psoriasis-proven biosimilars. |
| Licensing Agreement | Technology transfers from Swiss CDMOs enable Indian manufacturers to enter p40-targeting markets. |
| Pipeline Diversification | IL-23 selective antagonist positioning creates combination protocol headroom against next-generation cytokine targeting. |
| Strategic Partnership | Specialty pharmacy acquisitions by large PBMs capture biologic dispensing margins from hospital systems. |
Methodological Framework
Multi-period observation of EMA extrapolation approvals, FDA interchangeability designations, and tender-award pricing anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA biosimilar filings, EMA comparability assessment reports, ClinicalTrials.gov protocols, and formulary database snapshots. Bottom-up patient-flow modeling and top-down revenue triangulation converged on segment-level estimates.
Segment-weighting across therapy area, product type, delivery mode, and end user channels calibrated volume and value outputs across the projection horizon. CAGRs were derived from indication expansion trajectories, biosimilar entry sequencing, and pricing compression curves specific to p40-targeting biologics. Forecast inputs incorporated specialty pharmacy dispensing data, prior authorization automation adoption rates, and continuous bioprocessing capacity build-out disclosures from contract manufacturing organizations.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in real-time tender-award pricing from statutory health insurance funds introduce uncertainty bands around European biosimilar penetration assumptions. Forecasts reflect documented assumptions regarding interchangeability designation timelines and plasmid DNA supply continuity. Practitioners should monitor MFDS biosimilar approval alignments and CDSCO accelerated pathway utilization for early signals of manufacturing capacity redistribution toward Asian supply nodes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Thymus Cancer Market
Oncology
Throat Cancer Market
Oncology
Non-Small Cell Lung Carcinoma (NSCLC) Market
Oncology
Global Interventional Oncology Market
Oncology
Vulvar Cancer Market
Oncology
Bone Metastasis Market
Oncology
Metastatic Breast Cancer Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Cancer API Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
Gynecological Cancer Drugs Market
Oncology
Intratumoral Cancer Therapies Market
Oncology
Particle Therapy Systems Market
Oncology
Adrenocortical Carcinoma Treatment Market