
 Global Oncology Clinical Trials Market | 2026-2036
Global Oncology Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oncology Clinical Trials Market Foresight
Biotech firms are redrawing oncology trial outsourcing patterns as precision medicine pipelines multiply and sponsor archetypes fragment. IQVIA leverages its site network density to anchor late-phase execution across immuno-oncology portfolios. Charles River Laboratories specializes in preclinical-to-Phase I translation for cell therapy sponsors. Medpace competes on therapeutic area depth, particularly in hematologic malignancies where protocol complexity demands dedicated oncology expertise.
Oncology clinical trials constitute structured investigational studies evaluating therapeutic interventions in cancer patients, typically spanning biomarker stratification, adaptive dosing cohorts, and progression-free survival endpoints as primary functional parameters. These trials generate the safety and efficacy evidence required for regulatory approval of anticancer agents. Phase I dose-escalation studies for novel biologics command premium pricing due to specialized pharmacokinetic monitoring and limited patient pools. Adaptive trial designs are expanding fastest as Bayesian protocols permit real-time arm modifications without compromising statistical integrity. Contract research organizations hold concentrated margin pools in Phase III execution where project duration and site management scale create substantial barriers to entry.
The FDA, EMA, and Japan's PMDA each enforce distinct oncology trial frameworks that shape protocol design and market access timelines for multinational sponsors. The FDA's Project Optimus mandate alters dose-selection methodology, while EMA's Clinical Trial Regulation streamlines cross-border study initiation across European Union member states. Stakeholders must monitor divergence between regulator expectations for patient-reported outcomes and digital endpoint acceptance as decentralized trial technologies challenge traditional site-based models.
Market Dynamics
Decentralized trial platforms are fragmenting site selection authority away from academic medical centers toward community oncology networks and direct-to-patient delivery models.
Growth Catalysts
- Adaptive Bayesian Protocols:Real-time arm modifications without statistical compromise accelerate dose-finding timelines for targeted biologics.
- FDA Project Optimus:The mandate for dose-optimization studies creates dedicated trial demand beyond traditional safety-first Phase I designs.
- Cell Therapy Pipelines:CAR-T and allogeneic platforms require specialized pharmacokinetic monitoring that commands premium CRO engagement.
Market Restraints
- Limited Patient Pools:Rare mutation subsets constrain enrollment velocity for biomarker-stratified protocols.
- Regulatory Divergence:EMA's Clinical Trial Regulation and FDA's digital endpoint acceptance standards create protocol design friction for multinational sponsors.
- Site Concentration Risk:United States NCI network dominance creates geographic dependency for immuno-oncology trial execution.
Strategic Opportunities
- Asia-Pacific Expansion:Japan's PMDA streamlined oncology pathways and South Korea's MFDS trial acceleration programs offer underpenetrated enrollment pools.
- Digital Endpoint Integration:Wearable-derived patient-reported outcomes create regulatory differentiation where FDA guidance permits novel efficacy measures.
- Community Site Activation:Direct-to-patient logistics bypass academic center bottlenecks in hematologic malignancy recruitment.
Industry Challenges
- Oncology Biostatistician Scarcity:Adaptive design expertise concentrates among limited specialist consultancies, inflating protocol development timelines.
- Legacy EDC Integration:Electronic data capture systems require reconfiguration for real-time Bayesian analysis, compressing vendor selection windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oncology Clinical Trials Market |
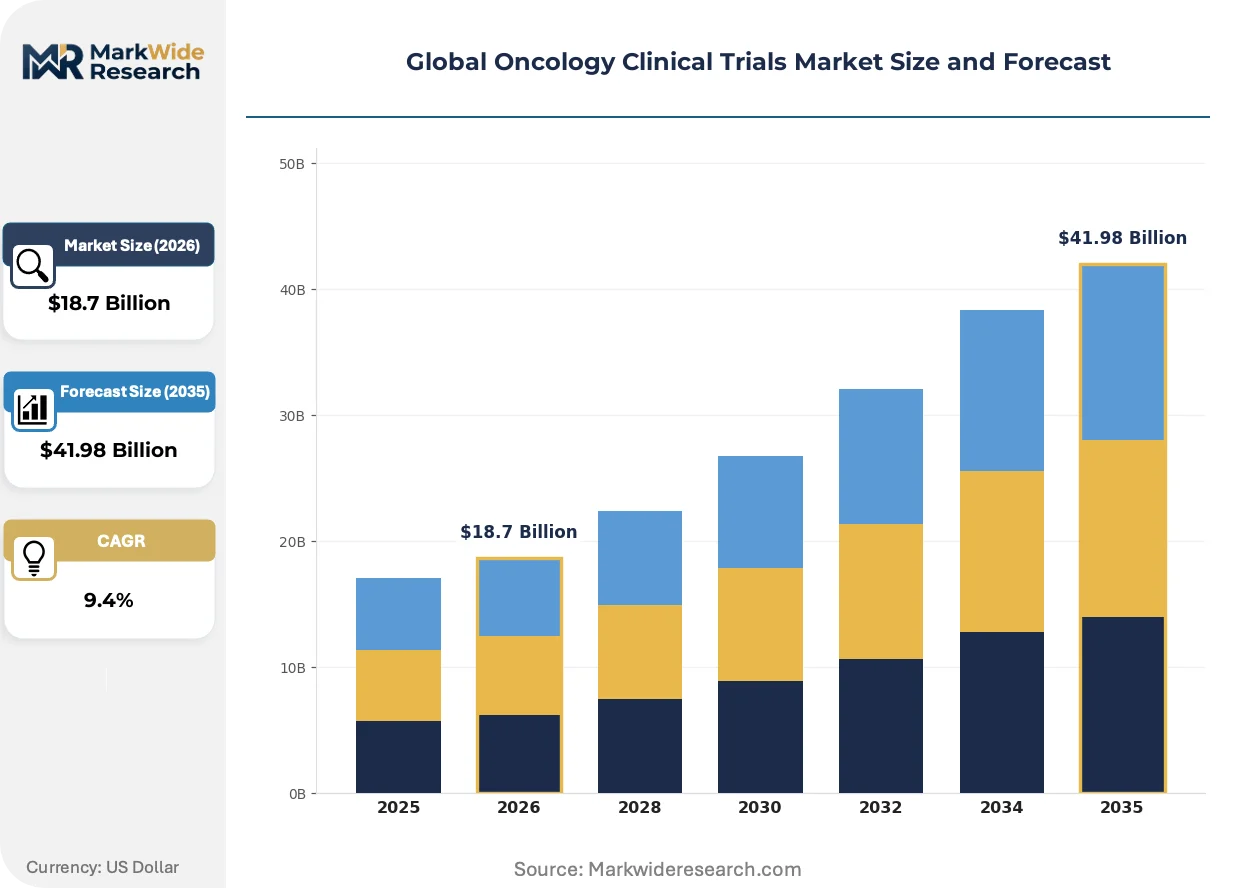
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trial Phase: Phase I, Phase II, Phase III, Phase IV, Expanded Access Cancer Type: Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer, Hematologic Malignancies Study Design: Randomized Controlled, Non-Randomized, Blinded, Open Label, Adaptive Key Stakeholder: Pharmaceutical Companies, Biotech Firms, Contract Research Organizations, Academic Institutions, Regulatory Agencies |
| Companies Covered | IQVIA, ICON plc, Charles River Laboratories, Syneos Health, Parexel International Corporation, Thermo Fisher Scientific, Medpace, Labcorp Drug Development, PRA Health Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oncology Clinical Trials Market Shifts & Advancements
Virtual trial infrastructure is collapsing the traditional site-visit model while biomarker stratification fragments protocols into smaller, more numerous cohorts.
Decentralized direct-to-patient platforms is displacing the academic medical center monopoly on oncology trial enrollment. Community oncology practices and home nursing networks now capture Phase II-III patient recruitment previously funneled through NCI-designated cancer centers. This shift compresses geographic enrollment barriers and accelerates diverse population access.
EMA's Clinical Trial Regulation harmonizes cross-border study initiation across European Union member states, eliminating redundant national ethics reviews. Sponsors now launch multi-country protocols through single submission portals, reducing administrative lag. France's ANSM and Germany's BfArM have synchronized their oncology trial assessment timelines under this framework.
Biomarker-driven protocol fragmentation is compressing average cohort sizes while multiplying total study arms. Sponsors now run parallel basket trials for rare mutation subsets rather than single large randomized studies. This pattern concentrates demand on CROs with dedicated hematologic malignancy expertise and specialized pharmacokinetic laboratory networks.
Global Oncology Clinical Trials Market Segmentation
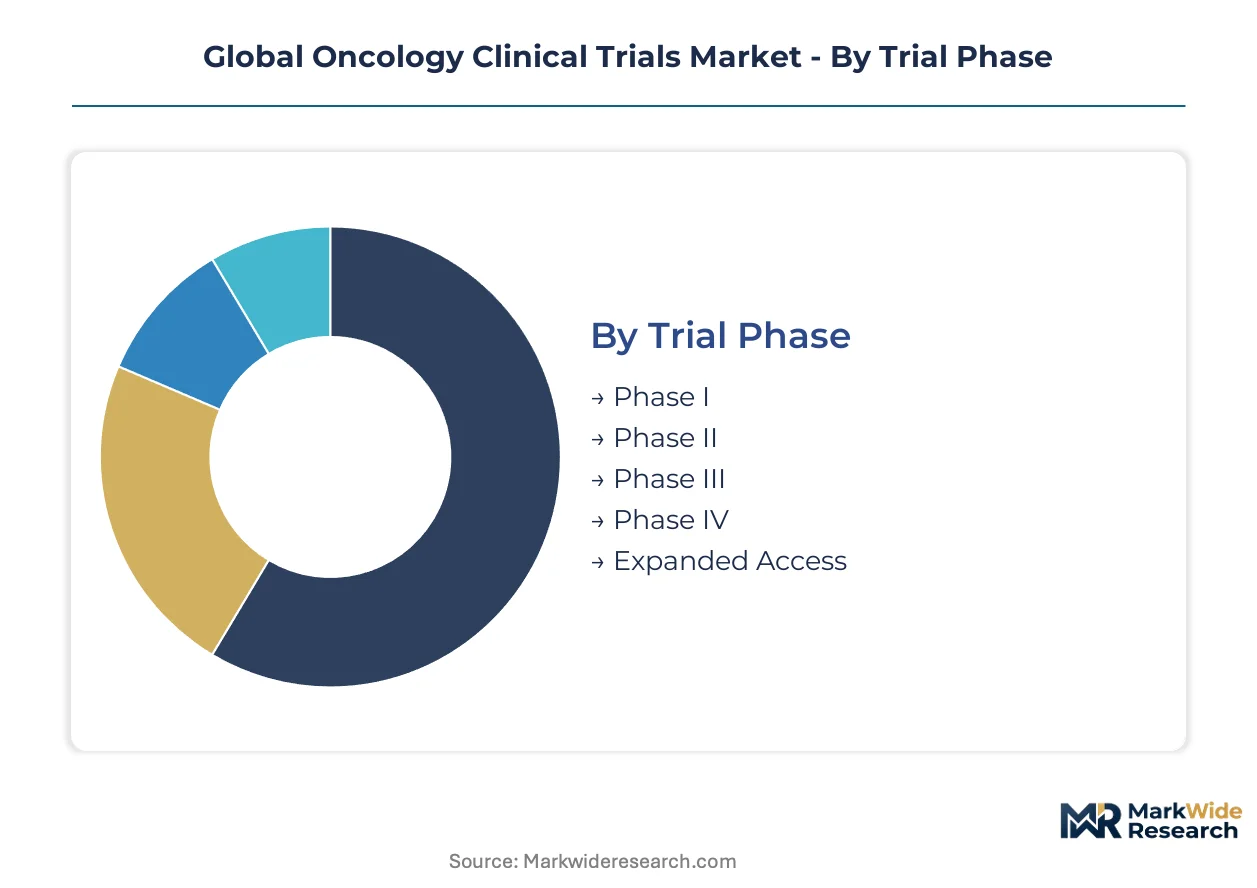
Oncology trial economics fragment sharply across phase boundaries and cancer indications, with margin pools concentrating where protocol complexity demands specialized infrastructure. Sponsors map segment selection against biomarker stratification density, regulatory pathway duration, and site network access requirements.
Trial Phase:
Margin pools concentrate in Phase I dose-escalation studies where specialized pharmacokinetic monitoring and limited patient pools command premium pricing.
- Phase I:Dose-escalation protocols for novel biologics require intensive pharmacokinetic sampling and dedicated safety monitoring infrastructure. Demand clusters with cell therapy sponsors in the United States where NCI-designated centers anchor early-phase execution.
- Phase II:Efficacy signal detection studies with biomarker stratification demand adaptive statistical frameworks and real-time endpoint adjudication. Enrollment velocity constrains timelines for rare mutation subsets across European Union member states.
- Phase III:Large-scale randomized controlled trials generate substantial project duration and site management scale barriers.
- Phase IV:Post-marketing surveillance studies capture real-world evidence for label expansion.
- Expanded Access:Compassionate use protocols bridge regulatory approval and commercial availability.
Phase I holds installed capacity. Phase II is rotating up the share rankings.
Cancer Type:
Application-specific protocol requirements drive cost tier differentiation, with hematologic malignancies commanding premium expertise premiums.
- Hematologic Malignancies:Leukemia and lymphoma trials require specialized flow cytometry laboratories and minimal residual disease assay validation. Protocol complexity concentrates demand with CROs maintaining dedicated oncology biostatistician teams in Japan and South Korea.
- Lung Cancer:Immuno-oncology combinations dominate pipeline activity with PD-L1 stratification mandating companion diagnostic integration. Site activation concentrates in China's tier-one cities where academic medical center density supports biomarker screening throughput.
- Breast Cancer:Endocrine and HER2-directed studies leverage established site networks.
- Colorectal Cancer:Microsatellite instability stratification fragments protocols into smaller cohorts.
- Prostate Cancer:Castration-resistant subtypes drive novel hormonal agent evaluation.
Lung Cancer anchors investigator-initiated volume. Hematologic Malignancies is climbing the fastest.
Study Design:
Customer type differentiation separates sponsors adopting Bayesian platforms from those locked in traditional frequentist frameworks.
- Adaptive:Real-time arm modification protocols permit dose-finding optimization without statistical compromise. FDA Project Optimus mandates reshape demand toward dose-optimization designs across United States-based sponsor portfolios.
- Randomized Controlled:Gold-standard comparative effectiveness studies retain regulatory preference for registration-enabling evidence.
- Non-Randomized:Single-arm designs accelerate enrollment for breakthrough therapy designated agents.
- Blinded:Masked endpoint assessment reduces observer bias in progression-free survival adjudication.
- Open Label:Unmasked designs suit immunotherapy trials where toxicity profiles require immediate recognition.
Randomized Controlled maintains protocol volume leadership. Adaptive is gaining share fastest.
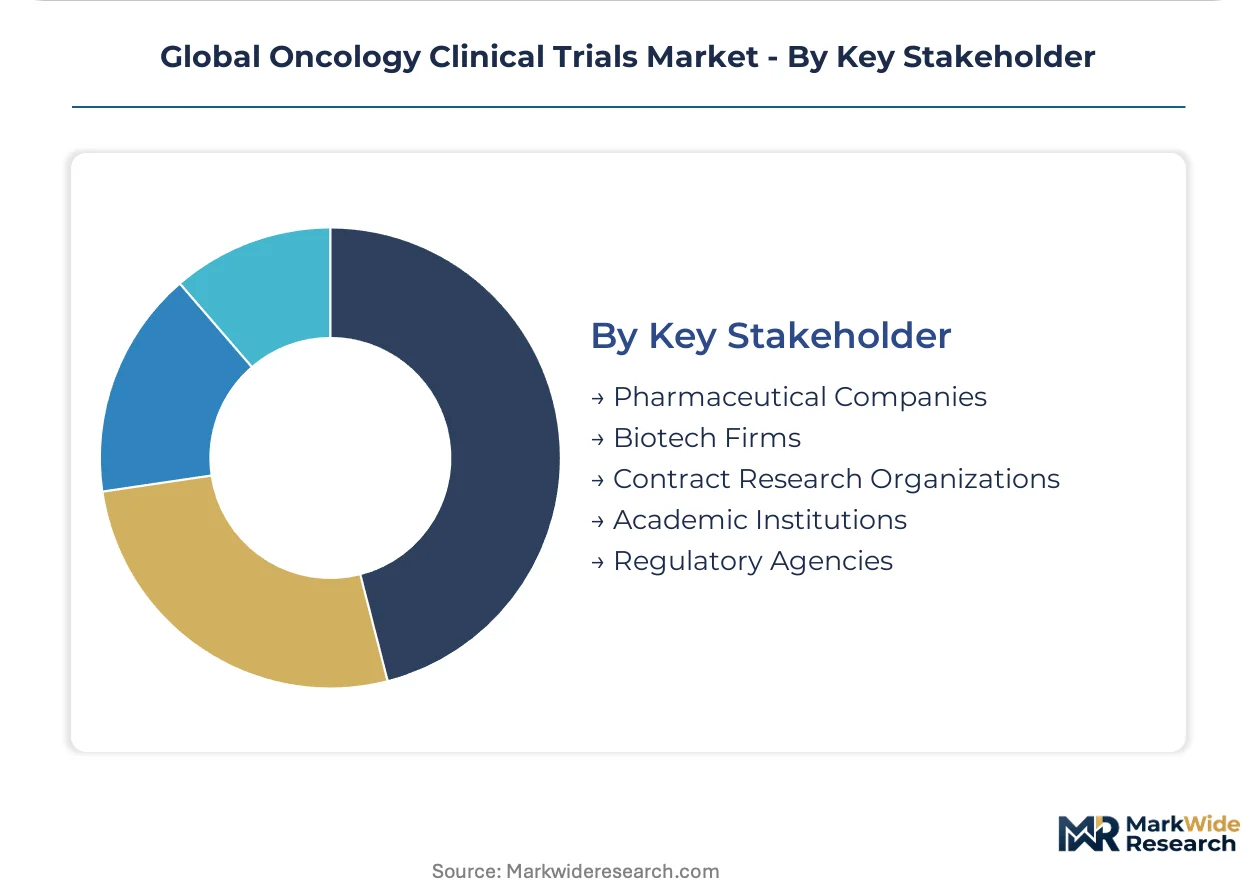
Key Stakeholder:
Supply concentration among contract research organizations creates tiered service differentiation based on therapeutic area depth.
- Contract Research Organizations:Full-service providers and niche oncology specialists compete on site network density and biostatistical capability. Charles River Laboratories anchors preclinical-to-Phase I translation while Medpace competes on hematologic malignancy expertise.
- Biotech Firms:Emerging sponsors drive outsourcing growth as precision medicine pipelines multiply and internal infrastructure constraints deepen.
- Pharmaceutical Companies:Large-cap sponsors retain selective in-house capabilities for flagship assets.
- Academic Institutions:NCI-designated cancer centers anchor investigator-initiated trial volume.
- Regulatory Agencies:FDA, EMA, and PMDA each enforce distinct framework requirements shaping protocol design.
Contract Research Organizations hold service capacity concentration. Biotech Firms is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based contract research organizations export clinical trial management services to European and Asian pharmaceutical sponsors seeking FDA-aligned protocol design and NCI network access for oncology drug development programs.
United States
The National Cancer Institute's trial network and concentrated academic medical center density create unmatched patient access for immuno-oncology studies. FDA Project Optimus mandates reshape dose-optimization protocols across sponsor portfolios. Boston and San Francisco anchor cell therapy translation hubs where specialized pharmacokinetic laboratories cluster.
Germany
Precision medicine pipelines from domestic biotech sponsors drive demand for adaptive trial infrastructure and biomarker stratification expertise. EMA's Clinical Trial Regulation harmonizes multi-country protocol initiation through Germany's BfArM assessment pathways. Munich and Heidelberg concentrate hematologic malignancy trial execution where flow cytometry laboratory networks validate minimal residual disease endpoints.
Japan
PMDA streamlined oncology approval pathways accelerate enrollment for targeted therapy sponsors seeking Asian patient diversity. The regulator's digital endpoint acceptance standards diverge from FDA frameworks, creating protocol design complexity for multinational studies. Tokyo and Osaka anchor investigator-initiated trial volume where academic medical centers maintain dedicated oncology biostatistician teams.
South Korea
MFDS trial acceleration programs attract CAR-T and allogeneic cell therapy sponsors requiring specialized pharmacokinetic monitoring infrastructure. The country's national pharmaceutical regulator synchronizes assessment timelines with PMDA pathways for Asia-Pacific portfolio coordination. Seoul anchors late-phase execution where community oncology networks expand decentralized trial enrollment beyond academic center bottlenecks.
United Kingdom
NHS cancer center integration with academic research infrastructure supports biomarker-driven basket trial execution for rare mutation subsets. MHRA post-Brexit regulatory divergence from EMA frameworks creates protocol submission friction for European Union-spanning studies. London and Manchester concentrate adaptive design expertise where Bayesian statistical consultancies serve multinational sponsor demand.
Global Oncology Clinical Trials Market Competitive Landscape
Listed leaders compete with private specialists across therapeutic area depth and site network density in oncology trial execution. Tiered service differentiation separates full-service contract research organizations from niche cell therapy and hematologic malignancy specialists. Three archetypes dominate: scale-driven global providers, preclinical-to-Phase I translation specialists, and dedicated oncology biostatistical consultancies. Consolidation through strategic acquisitions and organic site network expansion constitute the primary competitive vectors reshaping market structure.
Among scale-driven global providers, IQVIA anchors late-phase execution across immuno-oncology portfolios through site network density, while ICON plc exemplifies full-service breadth. Charles River Laboratories occupies a position within the preclinical-to-Phase I translation tier, and Medpace represents dedicated therapeutic area depth particularly in hematologic malignancies where protocol complexity demands specialized expertise.
| Leading Market Players |
|---|
| IQVIA |
| ICON plc |
| Charles River Laboratories |
| Syneos Health |
| Parexel International Corporation |
| Thermo Fisher Scientific |
| Medpace |
| Labcorp Drug Development |
| PRA Health Sciences |
| Others |
Supply & Pricing Matrix
Project-based capacity reservation contracts anchor oncology trial execution, locking CROs into dedicated site networks and sponsors into predictable cost visibility across multi-year protocol pipelines. These structures concentrate pricing power with full-service providers maintaining NCI-designated center access while fragmenting negotiation leverage among emerging biotech sponsors.
Pricing Analysis
Next-generation adaptive trial platforms command 40-60% premiums over legacy frequentist designs, while traditional Phase III randomized controlled studies face cost compression from site network commoditization. Project-based pricing dominates, with biomarker stratification density and pharmacokinetic monitoring intensity as primary differentiation drivers. Pricing pressure stems from biotech sponsor capital constraints and CRO capacity expansion in Asia-Pacific markets. Emerging biotech firms exhibit highest price sensitivity, while large-cap pharmaceutical sponsors prioritize speed-to-enrollment over per-patient costs.
Supply Chain Analysis
Strategic stockpiling of patient cohort access through multi-site master service agreements dominates over just-in-trial activation, reflecting enrollment velocity as the critical path constraint. Supply concentration rests in the United States (NCI network density), Germany (EMA harmonization infrastructure), and South Korea (MFDS acceleration pathways). Critical dependencies include specialized flow cytometry laboratories, biostatistical consultancy capacity, and decentralized logistics networks. Single-source vulnerability concentrates in adaptive design expertise pools. Distribution runs through sponsor-CRO direct contracting with limited intermediary layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oncology clinical trial demand is concentrating among mid-cap biotech sponsors, fragmenting buyer power while consolidating procurement volume with CROs offering therapeutic area depth. This buyer archetype shift intensifies price competition for standardized services while premiumizing specialized capabilities.
For Market Incumbents: Shield hematologic malignancy expertise through dedicated biostatistician team retention and minimal residual disease assay partnerships, as cell therapy pipelines multiply protocol complexity demands. Deepen backward integration into decentralized logistics networks to bypass academic center bottlenecks. Vertical control over patient recruitment infrastructure anchors margin defense against niche specialists.
For New Entrants and Emerging Players: Anchor in Asia-Pacific regulatory harmonization services, where PMDA-MFDS pathway synchronization creates white-space for protocol design consultancies. Target South Korean CAR-T sponsors requiring specialized pharmacokinetic monitoring infrastructure absent from global CRO footprints. Community oncology network activation offers the most penetrable site access angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CROs with embedded Phase I-III execution relationships and proprietary site networks, as sponsor switching costs compound across protocol portfolios. Long-term viability favors specialists with adaptive design capabilities and biomarker stratification expertise. Watch FDA Project Optimus implementation velocity as inflection signal for dose-optimization service demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Trial Platform Investment | FDA Project Optimus mandates reshape sponsor demand toward real-time dose-optimization capabilities. |
| Asia-Pacific Site Network Expansion | PMDA and MFDS pathway convergence creates enrollment access for multinational immuno-oncology portfolios. |
| Decentralized Logistics Integration | Direct-to-patient delivery models bypass academic medical center recruitment bottlenecks in hematologic malignancies. |
| Biomarker Stratification Expertise | Basket trial fragmentation multiplies protocol arm count and concentrates demand with specialized CROs. |
| Regulatory Harmonization Consulting | EMA-FDA-PMDA divergence in digital endpoint standards creates protocol design friction for global sponsors. |
Research Methodology
The analysis maps oncology trial phase economics, cancer indication complexity tiers, and CRO service differentiation, each validated through drug development executives, regulatory affairs leads, and hospital procurement managers. Primary interviews with site activation specialists and payer access specialists combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up protocol volume modeling and top-down service revenue triangulation anchored segmentation outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled trial phase, cancer type, study design architecture, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from protocol initiation velocity trends and sponsor outsourcing rate trajectories. Forecast inputs incorporated biomarker stratification adoption curves and decentralized trial platform penetration assumptions.
Material uncertainties — regulatory divergence in digital endpoint acceptance, biotech funding cycle volatility, and adaptive design talent scarcity — sit outside the modeled envelope. Forecasts reflect documented assumptions on sponsor archetype evolution and CRO capacity expansion timelines. Practitioners should keep alternative scenarios live as FDA Project Optimus implementation and Asia-Pacific regulatory harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Peritoneal Cancer Treatment Market
Oncology
Tumor Embolization Market
Oncology
North America Tumor Ablation Market
Oncology
Colorectal Cancer Treatment Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Europe Radiotherapy Market
Oncology
Oncology Devices Market
Oncology
Oncology Market
Oncology
Cancer Supportive Care Products Market
Oncology
Europe Tumor Ablation Market
Oncology
Colorectal Cancer Screening Market
Oncology
Throat Cancer Market
Oncology
Outpatient Oncology Infusion Market
Oncology
Europe Proton Therapy Market
Oncology
Europe Radiotherapy Patient Positioning Market