
 US Clinical Trials Market | 2026-2036
US Clinical Trials Market Size, Share, and Industry Trends Forecast 2026-2036
US Clinical Trials Market Intelligence
Oncology drug developers is pivoting toward adaptive platform trials that compress study timelines. IQVIA Holdings Inc leverages real-world evidence networks to anchor patient recruitment across community oncology sites. Charles River Laboratories International Inc specializes in early-phase oncology pharmacology, while Medpace Holdings Inc competes through therapeutic area concentration in central nervous system and metabolic studies.
Clinical trials are prospective biomedical or behavioral research studies involving human participants that test investigational drugs, devices, or treatment protocols under predefined eligibility criteria, data collection schedules, and safety monitoring boards. Their primary purpose is to generate statistically valid evidence of efficacy and safety for regulatory submission and clinical adoption. Phase III trials command the largest share of outsourced spending due to patient volume requirements and site management complexity. Oncology dominates therapy area allocation as immuno-oncology combinations expand protocol arms. Decentralized and hybrid study designs are gaining fastest within recruitment type as wearable sensors and telemedicine platforms reduce geographic barriers to participation.
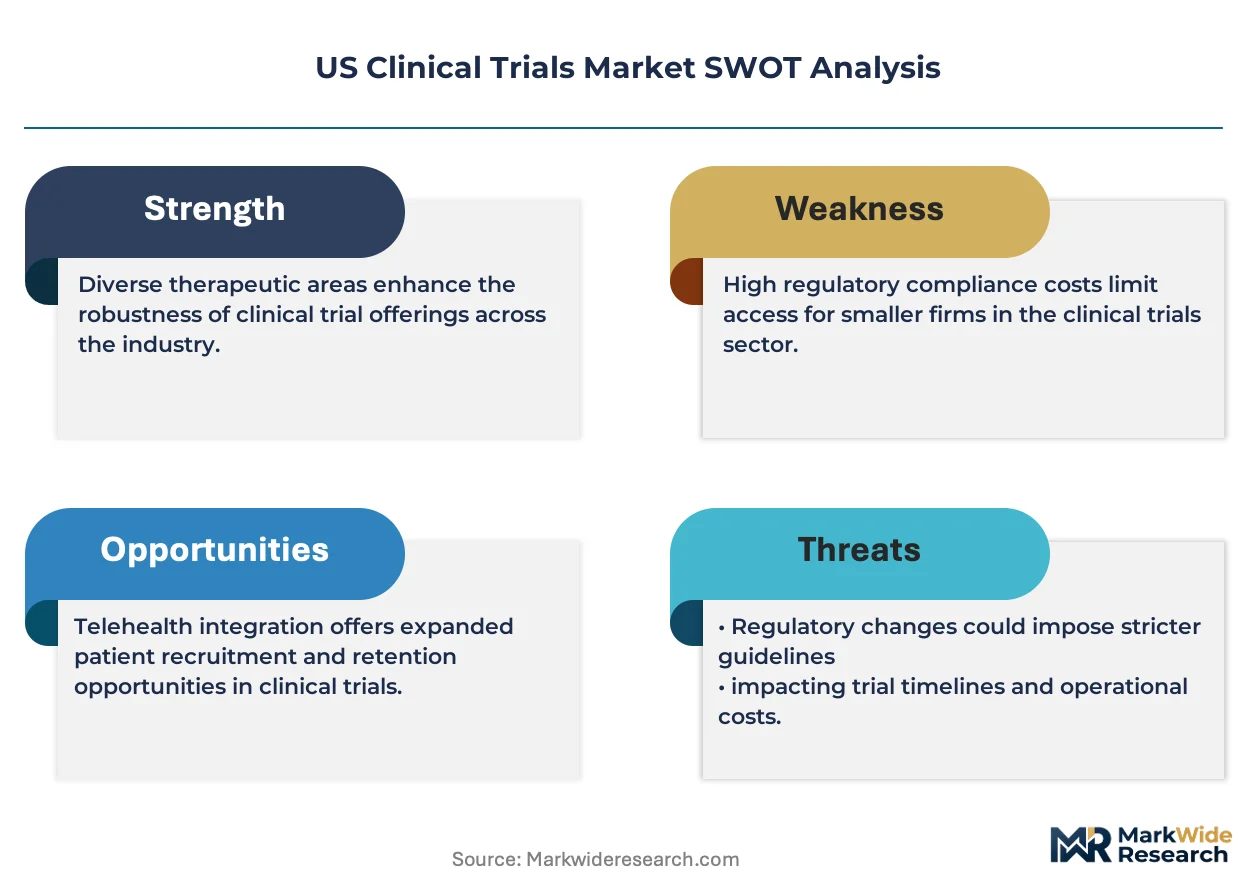
FDA 21 CFR Part 312 regulations govern investigational new drug applications, while HIPAA privacy rules constrain cross-site patient data sharing, and the 21st Century Cures Act provisions accelerate breakthrough therapy designations. These frameworks shape trial complexity, documentation burden, and sponsor decisions between internal execution and CRO partnership. Stakeholders must monitor evolving FDA guidance on artificial intelligence in clinical decision support and the agency's risk-based monitoring enforcement posture.
Market Dynamics
Decentralized trial infrastructure is compressing site activation timelines and redistributing patient recruitment from academic medical centers toward community-based networks. FDA digital health guidance and 21st Century Cures Act provisions are accelerating protocol amendments that embed wearable sensors and telemedicine endpoints.
Growth Catalysts
- Adaptive Platform Trial Adoption:Oncology sponsors are consolidating multiple investigational arms into single master protocols, reducing per-patient screening costs and accelerating comparator arm readouts.
- FDA Breakthrough Therapy Designation Pathway:Expedited review timelines for qualifying immuno-oncology candidates are compressing Phase II-to-III transition windows and expanding outsourced protocol design demand.
- Real-World Evidence Integration:EHR-derived endpoints and claims databases are supplementing traditional trial data, enabling external control arms that reduce placebo enrollment requirements.
Market Restraints
- Principal Investigator Scarcity:Qualified oncologists capable of serving as site principal investigators concentrate in Texas, California, and Massachusetts corridors, creating recruitment bottlenecks for multi-site oncology studies.
- HIPAA Cross-Site Data Friction:Privacy rule constraints on patient identifier sharing between community sites and coordinating centers add documentation burden and delay safety signal detection.
- Specialized Cold Chain Logistics:Cell and gene therapy protocols require cryogenic specimen transport that few regional courier networks can guarantee, limiting site selection flexibility.
Strategic Opportunities
- Underpenetrated Community Oncology Networks:Florida, Arizona, and Georgia host substantial patient populations with limited trial access, presenting recruitment expansion potential for hybrid trial models.
- AI-Enabled Protocol Optimization:Machine learning tools that predict enrollment velocity and adverse event clustering are converging with EHR interoperability standards to reduce protocol amendment rates.
- Diversity Enrollment Mandates:FDA guidance on representative trial populations is creating demand for decentralized recruitment platforms that reach rural and minority patient cohorts previously excluded from academic site catchments.
Industry Challenges
- Clinical Data Manager Talent Gap:Shortages of professionals trained in CDISC standards and FDA 21 CFR Part 11 compliance are extending database lock timelines and increasing CRO competition for qualified personnel.
- Legacy CTMS Integration Complexity:Sponsor investments in next-generation electronic data capture platforms face friction with decade-old clinical trial management systems that lack API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Clinical Trials Market |
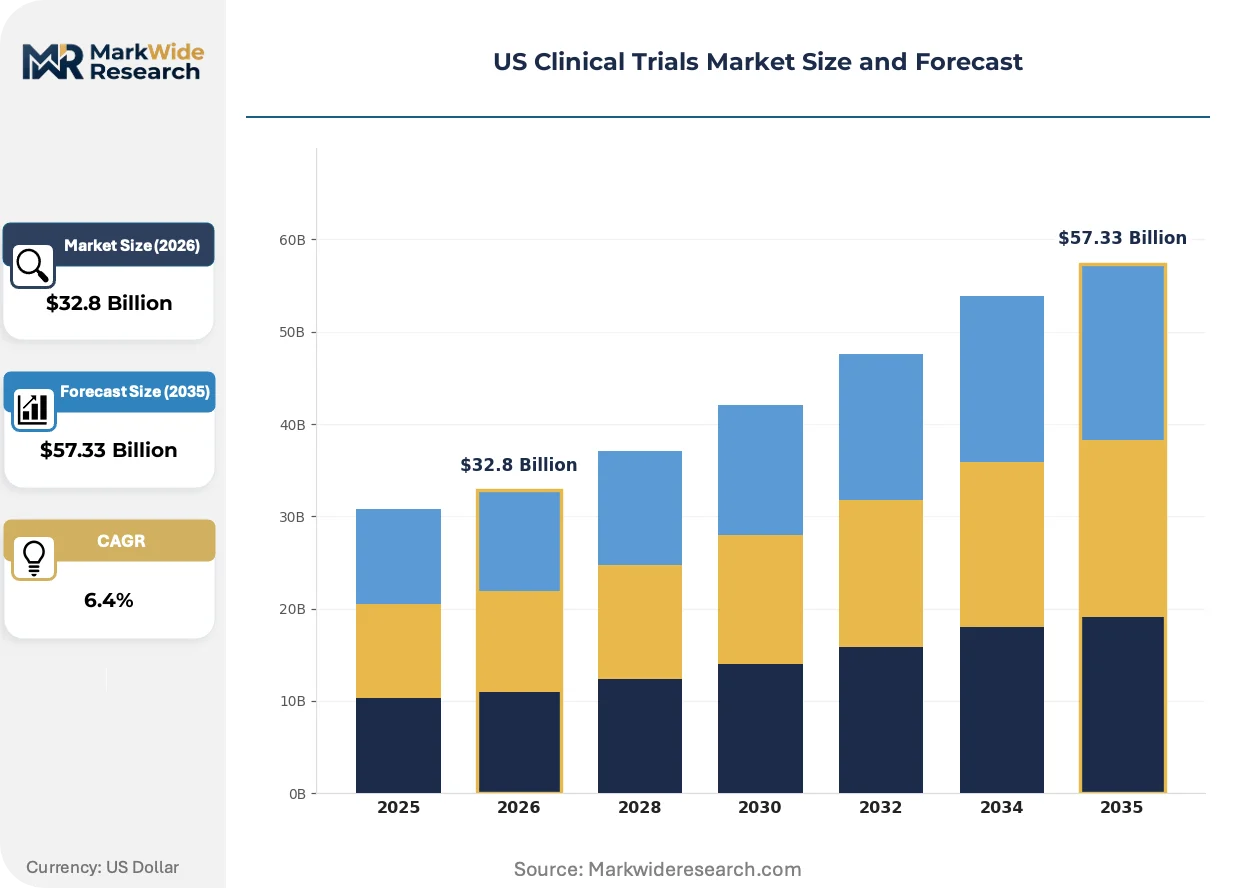
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Trial Phase: Phase I, Phase II, Phase III, Phase IV Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases Study Design: Randomized Controlled, Observational, Cohort, Case-Control Recruitment Type: Patient, Healthy Volunteer, Investigator, Registry |
| Companies Covered | IQVIA Holdings Inc, ICON PLC, Syneos Health, Parexel International Corp, Thermo Fisher Scientific Inc, Charles River Laboratories International Inc, Labcorp Holdings Inc, Medpace Holdings Inc, WuXi AppTec Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Clinical Trials Market Strategic Shifts & Innovations
Digital biomarker capture and remote patient monitoring are displacing traditional site-based assessment schedules. Trial sponsors are renegotiating site contracts to accommodate wearable-derived endpoints and virtual visit substitutions.
Wearable biosensors are absorbing functions previously performed by scheduled site visits, including continuous cardiac monitoring and activity-level tracking. Mid-sized biopharma sponsors are adopting these devices fastest for metabolic and cardiovascular indications. This technology is absorbing geographic barriers that previously excluded rural patients from eligibility pools.
FDA guidance on artificial intelligence in clinical decision support is clarifying algorithm validation requirements for diagnostic endpoints. The framework demands prospective algorithm performance data alongside traditional clinical outcomes. Oncology protocols employing AI-assisted radiographic response assessment are most affected, with sponsors adding algorithm training set documentation to investigational new drug submissions.
Site selection criteria are pivoting toward patient access convenience rather than investigator reputation alone. Community oncology practices with limited research experience are displacing academic centers for recruitment of common tumor types. This shift concentrates in Sun Belt states where retiree populations and lighter trial competition coincide.
US Clinical Trials Market Segmentation
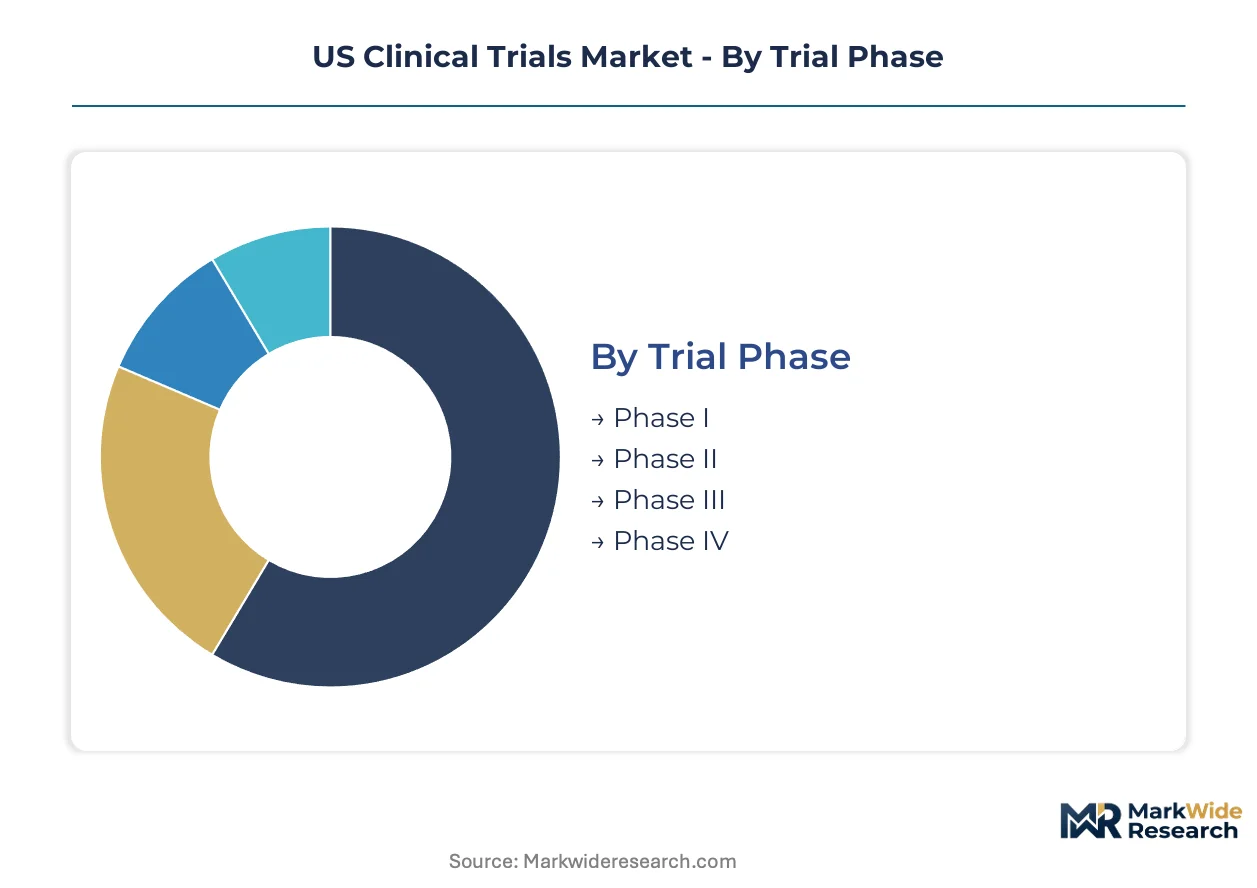
Sponsors allocate budgets across trial phases, therapy areas, and operational models based on regulatory risk tolerance and patient access requirements. Segmentation reveals where CRO partnerships concentrate versus internal execution, and which study designs attract decentralized technology investment.
Trial Phase:
Sponsor outsourcing intensity varies sharply by phase, driven by patient volume requirements and regulatory submission complexity.
- Phase III:These pivotal efficacy studies enroll thousands of participants across dozens of sites, demanding specialized project management and FDA submission documentation that pushes sponsors toward full-service CRO partnerships. Texas, California, and Massachusetts academic medical centers anchor the site networks for oncology Phase III programs.
- Phase I:First-in-human safety and pharmacokinetic studies require dedicated clinical pharmacology units with intensive monitoring capabilities. Charles River Laboratories and similar early-phase specialists capture sponsor spending here through purpose-built facilities in research corridors.
- Phase II:Proof-of-concept trials with adaptive designs allow sponsors to retain more internal control while testing biomarker-driven patient selection strategies.
- Phase IV:Post-marketing surveillance studies leverage existing prescription data and patient registries, reducing per-patient costs but requiring large-scale safety database management.
Phase III leads on scale; Phase I leads on momentum as cell and gene therapy pipelines expand first-in-human demand.
Therapy Area:
Protocol complexity and reimbursement potential determine where sponsors concentrate R&D investment and CRO selection.
- Oncology:Immuno-oncology combinations and adaptive platform trials dominate sponsor pipelines, with FDA breakthrough therapy designations compressing development timelines. California's Stanford and UCSF networks, Massachusetts' Dana-Farber corridor, and Texas' MD Anderson cluster anchor patient recruitment for solid tumor studies.
- Cardiovascular:Large endpoint trials with hard clinical outcomes require extensive site networks and long follow-up periods, favoring CROs with proven mortality event adjudication capabilities.
- Neurology:Subjective endpoints and high placebo response rates demand specialized raters and centralized assessment protocols, particularly for Alzheimer's and Parkinson's programs.
- Infectious Diseases:Antimicrobial resistance and emerging pathogen preparedness drive government-funded trial networks with distinct contracting structures from commercial biopharma.
Oncology leads on scale; neurology leads on momentum as disease-modifying therapies attract venture funding.
Study Design:
Regulatory acceptance and data quality requirements shape sponsor choices between experimental and observational architectures.
- Randomized Controlled:The gold standard for FDA approval maintains dominance despite rising costs, with sponsors embedding decentralized elements to reduce geographic barriers while preserving blinding integrity.
- Observational:Real-world evidence studies using EHR and claims data are expanding fastest as FDA guidance clarifies external control arm acceptability for rare disease applications.
- Cohort:Prospective disease registries enable natural history studies that accelerate patient identification for interventional trials.
- Case-Control:Retrospective designs persist in pharmacovigilance and safety signal investigation where randomized assignment is unethical.
Randomized controlled designs lead on scale; observational studies lead on momentum as digital health data streams mature.
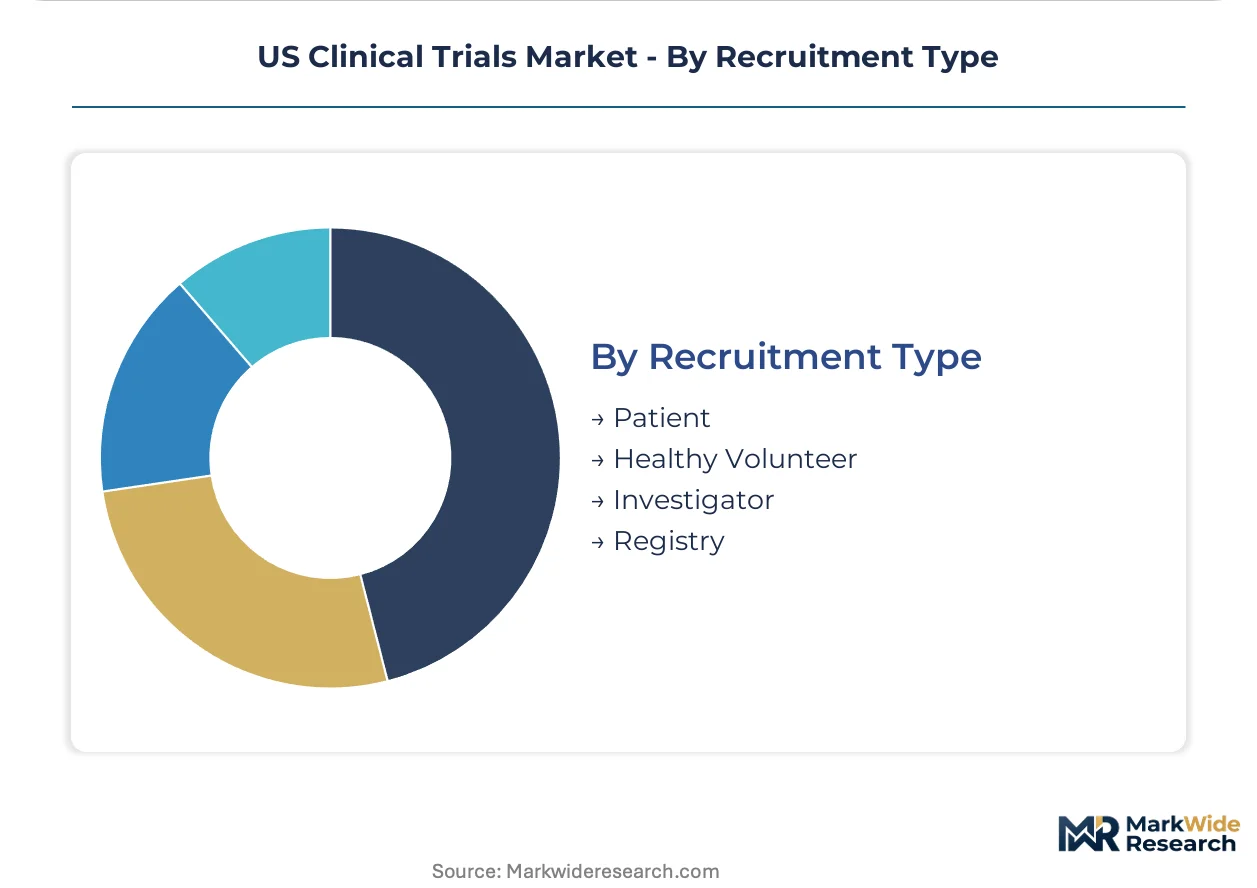
Recruitment Type:
Patient access strategies determine site selection criteria and technology infrastructure requirements.
- Patient:Disease-specific recruitment through community oncology networks and specialty clinics now dominates, with Florida, Arizona, and Georgia emerging as high-potential expansion markets given substantial populations and limited trial competition.
- Healthy Volunteer:Pharmacokinetic and bioequivalence studies rely on dedicated Phase I units with rapid enrollment capabilities and intensive safety monitoring.
- Investigator:Principal investigator-initiated studies funded by academic medical centers operate under distinct budget and timeline constraints from industry-sponsored trials.
- Registry:Pre-consented patient databases enable rapid screening and reduce per-patient recruitment costs for rare disease indications.
Patient recruitment leads on scale; registry-based approaches lead on momentum as EHR interoperability improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California, Massachusetts, and Texas anchor US clinical trial infrastructure through dense concentrations of academic medical centers, biopharma headquarters, and FDA-registered investigational sites.
California
Oncology and cell therapy protocols drive site demand across Stanford, UCSF, and Cedars-Sinai networks. FDA's 21 CFR Part 312 framework governs IND submissions from San Francisco and San Diego sponsor clusters. The Los Angeles-San Diego corridor hosts specialized Phase I units for immuno-oncology first-in-human studies.
Massachusetts
Genomic medicine and rare disease trials concentrate around Boston's Longwood Medical Area and Cambridge biotech corridor. Massachusetts General Hospital and Dana-Farber Cancer Institute anchor patient recruitment for hematologic malignancy studies. State-level life sciences tax incentives reinforce CRO facility expansion in Worcester and suburban Boston.
Texas
MD Anderson Cancer Center and UT Southwestern anchor the nation's largest oncology trial enrollment hub. Texas Medical Center's scale attracts decentralized trial platform deployments targeting Hispanic and rural patient access. Houston and Dallas-Fort Worth corridors specialize in cardiovascular and metabolic study execution.
Florida
Retiree demographics and limited trial competition create recruitment expansion opportunities for hybrid oncology and neurology protocols. Tampa's Moffitt Cancer Center and Miami's Sylvester Comprehensive Cancer Center anchor site networks. State medical licensing reciprocity agreements accelerate principal investigator activation across community oncology practices.
North Carolina
Research Triangle Park's contract research concentration supports late-phase trial management and biostatistics outsourcing. Duke University and UNC Chapel Hill anchor site networks for infectious disease and vaccine studies. RTP's CRO cluster specializes in FDA submission documentation and regulatory strategy services.
US Clinical Trials Market Key Industry Players
Strategic partnerships dominate the current landscape as full-service CROs integrate decentralized trial technology vendors and real-world evidence data providers. The vendor base concentrates among three tiers: global full-service organizations with therapeutic area depth, mid-sized specialists in early-phase or niche indications, and technology-enabled platform players. Consolidation pressures favor scale-driven entities capable of absorbing protocol complexity across oncology, neurology, and rare disease portfolios. Portfolio diversification and geographic site network expansion represent the two dominant competitive moves as sponsors demand single-provider accountability across trial phases.
Within the full-service tier, IQVIA Holdings Inc and ICON PLC exemplify scale-driven consolidation strategies, while Charles River Laboratories International Inc occupies a specialized position in early-phase pharmacology services. These three entities anchor distinct competitive archetypes: IQVIA represents integrated data and trial execution capabilities, ICON exemplifies cross-border site network density, and Charles River Laboratories anchors purpose-built Phase I facility investments. Medpace Holdings Inc sits within the mid-sized specialist tier, competing through therapeutic area concentration rather than scale. The competitive dynamic pits breadth against depth, with full-service providers absorbing technology partnerships to match specialist agility while retaining regulatory submission bandwidth.
| Leading Market Players |
|---|
| IQVIA Holdings Inc |
| ICON PLC |
| Syneos Health |
| Parexel International Corp |
| Thermo Fisher Scientific Inc |
| Charles River Laboratories International Inc |
| Labcorp Holdings Inc |
| Medpace Holdings Inc |
| WuXi AppTec Co Ltd |
| Others |
Cost & Logistics Intelligence
Decentralized trial platform deployment simultaneously compresses site activation economics and redistributes procurement power from academic medical centers toward community-based networks. Wearable sensor integration and telemedicine infrastructure investments are reshaping cost structures across sponsor-CRO contracts while concentrating vendor relationships among FDA-validated technology providers.
Pricing Analysis
Input-cost pass-through from specialized cold chain logistics and cryogenic specimen handling runs through Phase I oncology and cell therapy protocol pricing. CRO services stratify across premium, standard, and economy tiers based on therapeutic area specialization depth and FDA submission track record. Pricing pressure stems from sponsor consolidation of vendor relationships and demand for single-accountability contracting across trial phases. Emerging biopharma sponsors exhibit highest price sensitivity, while large-cap pharmaceutical companies prioritize regulatory submission bandwidth over per-patient cost minimization.
Supply Chain Analysis
Direct-to-sponsor channels handle enterprise-scale outsourcing demand from top-20 pharmaceutical companies, while regional site networks serve mid-cap sponsors through specialized therapeutic area partnerships. Investigational drug manufacturing concentrates in Massachusetts, California, and North Carolina biomanufacturing clusters. Cryogenic courier services, EHR interoperability platforms, and wearable biosensor hardware constitute critical input dependencies. Single-source vulnerability in qualified principal investigator pools across Texas and California corridors presents structural risk. Distribution runs through full-service CROs with integrated site activation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US clinical trials rests on decentralized technology adoption compressing per-patient site costs and sponsors accepting premium pricing for FDA breakthrough therapy pathway expertise. Cost-down drivers in wearable-enabled remote monitoring are shifting value capture toward platform-integrated CROs.
For Market Incumbents: To counter sponsor demand for single-provider accountability across decentralized and traditional trial formats, full-service CROs should acquire specialized community oncology site networks in Florida and Arizona while embedding AI-enabled protocol optimization tools. Vertical integration into wearable biosensor data validation capabilities anchors premium pricing power. For New Entrants and Emerging Players: Capture underpenetrated community oncology recruitment in Georgia and Sun Belt retiree corridors through hybrid trial models combining telemedicine infrastructure with local principal investigator partnerships. White-space concentration in neurology decentralized endpoints and rare disease registry-based recruitment offers fastest penetration paths. Go-to-market positioning as FDA diversity mandate specialists differentiates against established oncology-focused incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized CROs with therapeutic area concentration in central nervous system and metabolic studies but lacking decentralized platform integration. Long-term viability over the analysis window favors entities with proven FDA submission bandwidth and community site network density. Watch FDA guidance finalization on artificial intelligence in clinical decision support as inflection signal for algorithm-validation service demand.| Strategic Initiative | Industry Significance |
|---|---|
| Community Site Network Acquisition | Hybrid trial models in Florida and Arizona expand patient access beyond academic corridors. |
| AI Protocol Optimization Platform | Machine learning enrollment prediction reduces amendment rates for adaptive oncology designs. |
| Wearable Biosensor Integration | FDA-validated remote monitoring endpoints displace scheduled site visits in metabolic studies. |
| Real-World Evidence Partnership | EHR-derived external control arms reduce placebo enrollment for rare disease indications. |
| Diversity Enrollment Infrastructure | Decentralized platforms address FDA representative population mandates in minority cohorts. |
Research Approach
Coverage spans California, Massachusetts, Texas, Florida, and North Carolina research corridors, with primary inputs from each. The analysis combines structured interviews with drug development executives, regulatory affairs leads, principal investigators at academic medical centers, and CRO procurement officers with secondary validation against FDA 21 CFR Part 312 filings, ClinicalTrials.gov protocol registrations, CMS Medicare reimbursement databases, and SEC 10-K disclosures from publicly traded service providers. Bottom-up site-level enrollment data and top-down sponsor spending estimates undergo triangulation to anchor market sizing.
Rate-of-change decomposition across the analysis window separates volume effects from price-mix shifts in outsourced service spending. Segmentation dimensions include trial phase, therapy area concentration, study design architecture, and recruitment type. CAGRs derive from sponsor pipeline tracking, CRO backlog analysis, and FDA breakthrough therapy designation velocity. Forecast inputs incorporate decentralized technology adoption curves and principal investigator supply constraints in concentrated geographic markets.
Protocol amendment frequency, FDA guidance timeline shifts, and wearable sensor validation setbacks are the dominant revision risks. Forecasts reflect assumptions regarding regulatory acceptance of external control arms and telemedicine endpoint equivalence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
North America Contract Research Organization Market
Clinical Research
Non-Alcoholic Steatohepatitis Clinical Trials Market
Clinical Research
Global Clinical Trials Matching Software Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Real-World Evidence Analytics Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
Patient-Reported Outcome Data Monetization Market
Clinical Research
Pharmacovigilance Outsourcing Market
Clinical Research
Humanized Mice Model Market
Clinical Research
Clinical Trial Investigative Site Network Market
Clinical Research
HIV Clinical Trials Market
Clinical Research
Clinical Trials Market
Clinical Research
Healthcare Europe Clinical Data Analytics Market
Clinical Research
Preclinical CRO Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Clinical Trials Site Management Organizations Market