
 Tumor Infiltrating Lymphocytes Market | 2026-2036
Tumor Infiltrating Lymphocytes Market Size, Share, and Industry Trends Forecast 2026-2036
Tumor Infiltrating Lymphocytes Market Outlook
ISO 14644 cleanroom certification for cell manufacturing is collapsing the supplier base to a handful of qualified operators. Iovance Biotherapeutics anchors the commercial landscape with the first FDA-approved autologous TIL therapy for unresectable melanoma. Bristol-Myers Squibb leverages its immuno-oncology infrastructure to compete in combination regimens. Instil Bio specializes in next-generation manufacturing processes that reduce production timelines.
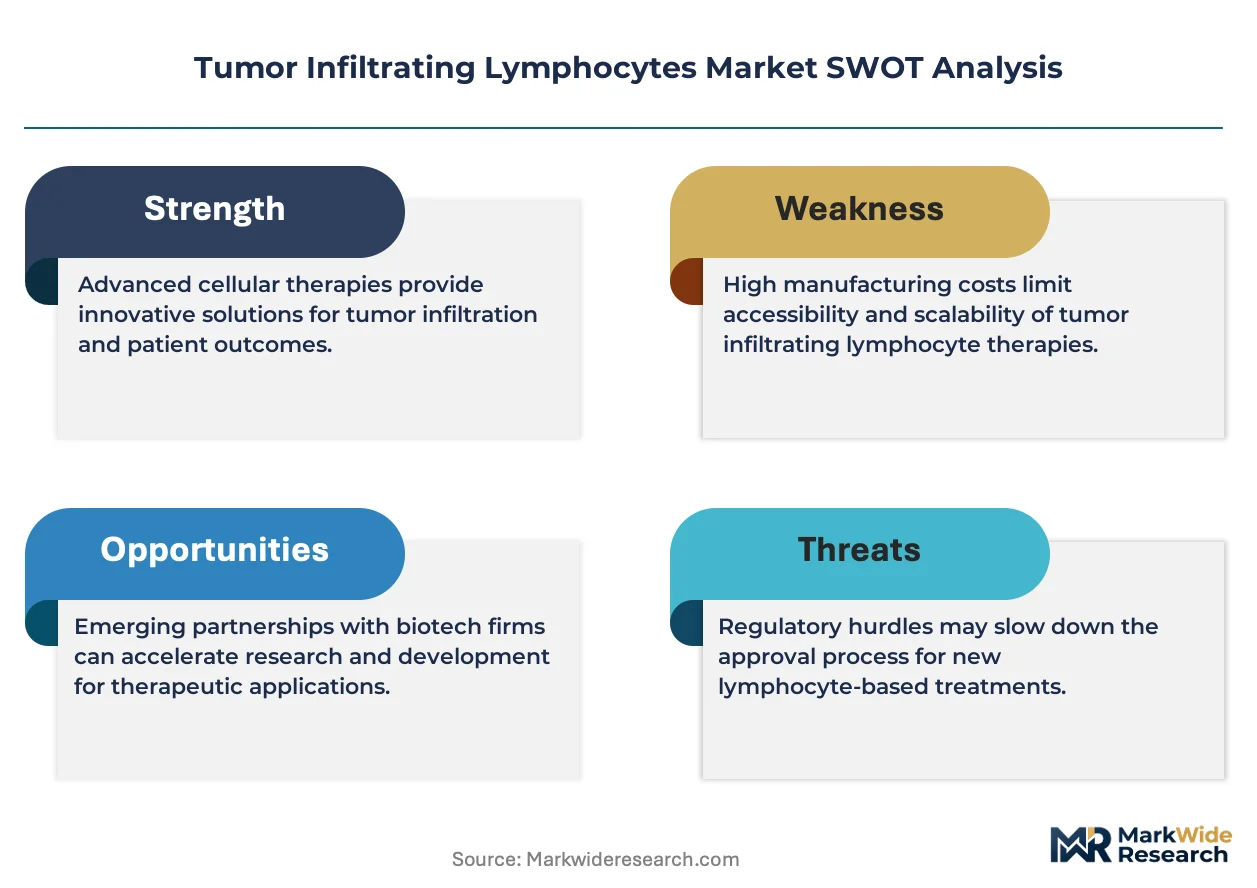
Tumor infiltrating lymphocytes are ex vivo expanded autologous T cells harvested from resected tumor tissue, typically cultured in IL-2 supplemented media for two to four weeks to achieve therapeutic cell counts exceeding one billion viable T cells. These cells recognize patient-specific tumor neoantigens and are reinfused following lymphodepleting chemotherapy to treat solid malignancies. Autologous TILs dominate current revenue as the only commercially approved product class, while engineered TILs with genetic modifications represent the fastest-growing segment as developers insert cytokine transgenes to improve persistence. Melanoma anchors therapy area demand through established clinical pathways, though lung cancer applications are expanding into Phase II trials.
The FDA's regenerative medicine advanced therapy designation and EMA's priority medicines scheme create parallel regulatory tracks that shape investment allocation between US and European development programs. HIPAA compliance requirements for patient-specific cell tracking impose data infrastructure costs that favor scaled operators over emerging entrants. Stakeholders must monitor FDA guidance on potency assay standardization, as inconsistent release criteria across manufacturing sites could fragment market access for otherwise clinically equivalent products.
Market Dynamics
ISO 14644 cleanroom certification requirements are compressing the supplier base for TIL manufacturing, collapsing qualified operators to a handful of scaled facilities capable of meeting FDA and EMA cell therapy standards.
Growth Catalysts
- Regenerative Medicine Advanced Therapy (RMAT) designation:The FDA's accelerated pathway compresses development timelines for autologous cell therapies, enabling faster commercialization of expanded TIL protocols.
- IL-2 cytokine engineering:Next-generation TIL products incorporating transgenic cytokine expression are improving in vivo persistence and expanding addressable patient populations beyond melanoma.
- German university hospital networks:Reimbursed oncology care pathways in Germany are integrating TIL protocols into standard metastatic melanoma treatment, creating concentrated demand for manufacturing capacity.
Market Restraints
- Autologous donor material constraints:Patient-specific tumor resection requirements limit batch scalability and create supply volatility for commercial manufacturing.
- Cleanroom infrastructure concentration:ISO 14644-compliant cell therapy facilities cluster in the United States and Western Europe, creating geographic supply risk and capacity bottlenecks.
- Lymphodepletion chemotherapy dependency:Required preconditioning regimens using cyclophosphamide and fludarabine introduce toxicity profiles that restrict eligible patient populations.
Strategic Opportunities
- Non-small cell lung cancer expansion:Phase II trials for TIL therapy in NSCLC represent the largest untapped solid tumor indication beyond established melanoma pathways.
- Allogeneic TIL platform development:Off-the-shelf engineered TIL products from healthy donors could eliminate patient-specific manufacturing delays and reduce cost of goods.
- EMA Priority Medicines scheme:Parallel European regulatory track accelerates market access for developers willing to establish EU manufacturing footprints alongside US facilities.
Industry Challenges
- Potency assay standardization gaps:Inconsistent release criteria across manufacturing sites create regulatory fragmentation and complicate multi-site clinical trials.
- HIPAA-compliant cell tracking infrastructure:Patient-specific chain-of-custody systems impose data architecture costs that disadvantage emerging entrants against scaled operators.
- Four-week manufacturing timelines:Extended ex vivo expansion periods create inventory risk and compress treatment windows for rapidly progressing metastatic disease.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumor Infiltrating Lymphocytes Market |
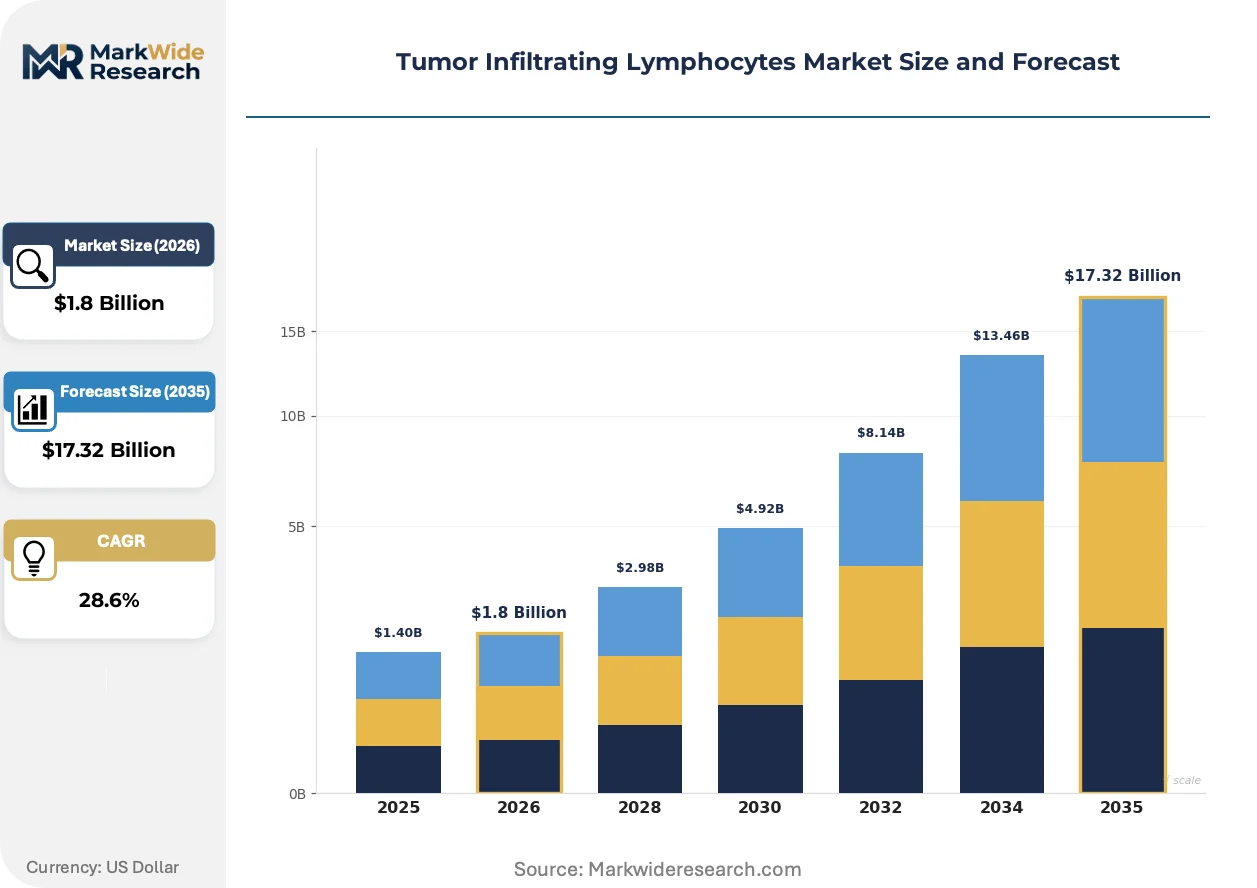
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous TILs, Engineered TILs, TIL Cell Therapy, Expanded TILs Therapy Area: Breast Cancer, Melanoma, Lung Cancer, Colorectal Cancer Delivery Mode: Intratumoral, Intravenous, Subcutaneous, Local Administration End User: Hospitals, Research Institutes, Clinics, Cancer Centers |
| Companies Covered | Bristol-Myers Squibb, Incyte Corporation, Iovance Biotherapeutics, Intima Bioscience, REPROCELL, Obsidian Therapeutics, Instil Bio, Lytix Biopharma, KSQ Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumor Infiltrating Lymphocytes Market Strategic Shifts
Manufacturing automation and genetic engineering are converging to reshape TIL therapy economics, compressing production timelines while expanding therapeutic applications beyond melanoma into broader solid tumor indications.
Non-viral electroporation systems for cytokine transgene insertion are supplanting viral vector approaches in next-generation TIL engineering. Contract development and manufacturing organizations in the United States and Germany are adopting these platforms to reduce regulatory complexity and improve batch consistency. The shift is enabling developers to pursue multi-cytokine modifications previously constrained by viral payload limits.
EMA's evolving guidance on genetically modified organism containment for cell therapy manufacturing is tightening facility requirements across European production sites. The industrial consequence is accelerated capital deployment into closed-system bioreactors and single-use containment technologies. German and Dutch manufacturing facilities are responding fastest, integrating these systems ahead of formal implementation deadlines to secure priority medicines designations.
Academic medical centers are consolidating TIL therapy referrals into designated excellence networks with captive manufacturing relationships. Traditional community oncology practices are losing access to these complex cell therapies as treatment concentrates in NCI-designated cancer centers and university hospitals. This consolidation is most visible in the United States, where Medicare reimbursement pathways increasingly require treatment at centers with on-site cell processing capabilities or established commercial partnerships.
Tumor Infiltrating Lymphocytes Market Segmentation
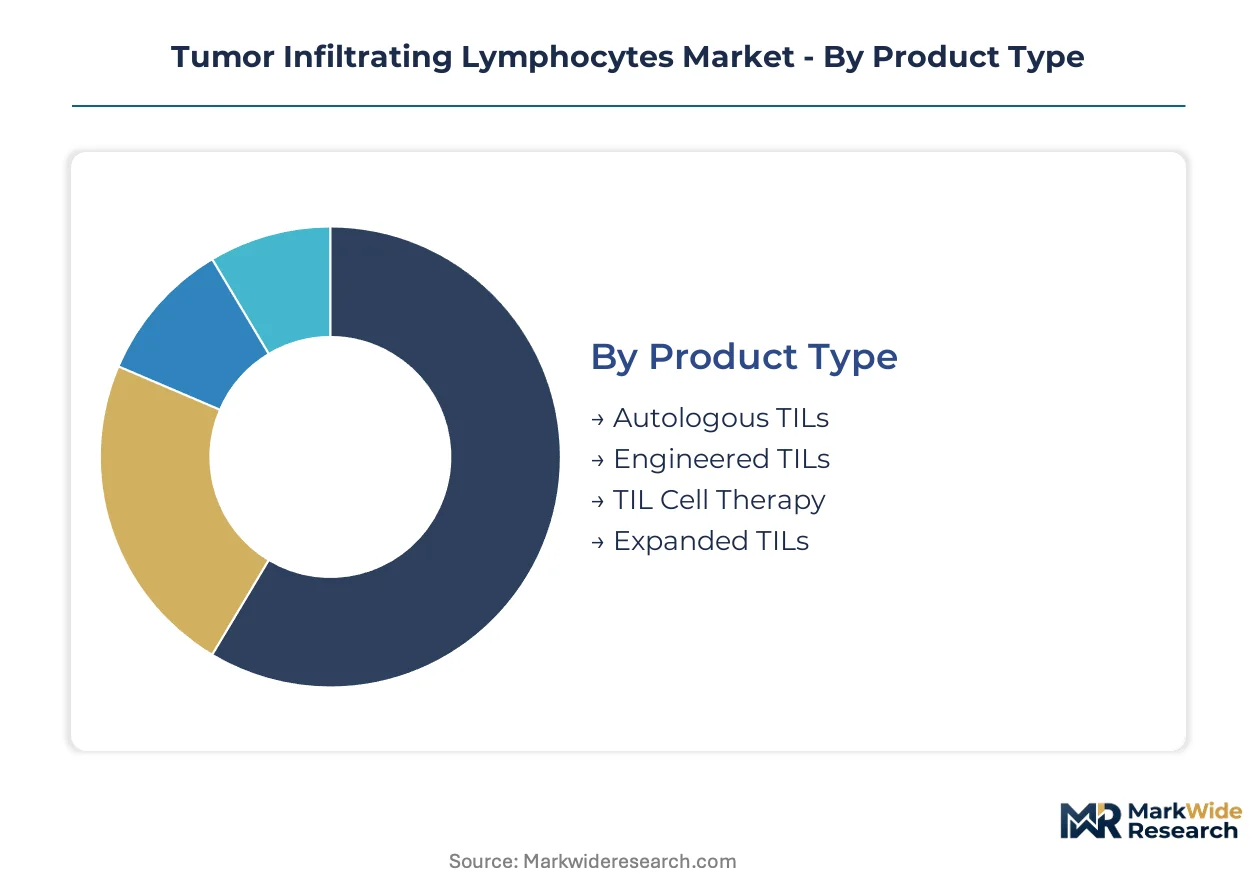
TIL therapy segmentation reveals how manufacturing constraints and clinical pathways fragment commercial opportunity across patient-specific and scalable product architectures. Category boundaries shift as genetic engineering collapses traditional distinctions between autologous and allogeneic platforms.
Product Type:
Engineered TILs exert the strongest substitution pressure on conventional autologous products, as cytokine transgene insertion addresses the persistence limitations that have restricted first-generation commercial penetration.
- Autologous TILs:Patient-derived T cells expanded ex vivo from resected tumor tissue using IL-2 supplemented media, requiring two to four weeks of culture to achieve therapeutic doses exceeding one billion viable cells. Demand concentrates in NCI-designated cancer centers across the United States, constrained by batch-to-batch variability and donor material scarcity that limits manufacturing scalability.
- Engineered TILs:Genetically modified TIL products incorporating transgenic cytokine expression or checkpoint modifications to enhance in vivo persistence and tumor penetration. German university hospital networks are driving early adoption, attracted by reduced lymphodepletion requirements and expanded addressable populations beyond melanoma.
- TIL Cell Therapy:Commercial-stage therapeutic products administered under regulated manufacturing standards with defined potency assays and release criteria. FDA regenerative medicine advanced therapy designations are accelerating development timelines for qualified developers.
- Expanded TILs:Rapid expansion protocols using alternative cytokine cocktails or feeder cell systems to compress manufacturing windows from four weeks toward ten days. Dutch and German contract manufacturers are piloting these platforms to reduce inventory risk for rapidly progressing metastatic disease.
Autologous TILs retain volume leadership; engineered TILs hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates melanoma's reimbursed clinical pathways from investigational indications where trial sponsorship determines patient access.
- Melanoma:Established solid tumor indication with FDA-approved TIL therapy and defined Medicare reimbursement pathways at US cancer centers. Clinical demand concentrates in metastatic or unresectable cases following checkpoint inhibitor failure.
- Lung Cancer:Non-small cell lung cancer represents the largest untapped solid tumor opportunity, with Phase II trials expanding TIL protocols beyond melanoma's established boundaries.
- Breast Cancer:Triple-negative and HER2-negative subtypes are emerging targets for TIL therapy development, though clinical pathways remain investigational without approved products.
- Colorectal Cancer:Microsatellite-stable disease presents antigenicity challenges that have limited TIL efficacy, restricting development to academic consortiums with specialized neoantigen identification capabilities.
Melanoma commands the premium reimbursement tier; lung cancer applications are climbing the fastest toward commercial feasibility.
Delivery Mode:
Application requirements dictate route selection, with intravenous administration dominating systemic disease and intratumoral approaches reserved for localized or oligometastatic presentations.
- Intravenous:Systemic infusion following lymphodepleting chemotherapy, enabling TIL trafficking to multiple metastatic sites. Standard for melanoma and lung cancer protocols at major academic medical centers.
- Intratumoral:Direct injection into accessible tumor deposits, reducing systemic cytokine exposure and enabling lower cell dose requirements. Applied in head and neck or cutaneous metastases with superficial lesions.
- Subcutaneous:Experimental delivery route under investigation for maintenance dosing or combination with checkpoint inhibitors, though clinical data remains limited.
- Local Administration:Regional perfusion or cavity-based delivery for peritoneal or pleural disease, requiring specialized interventional infrastructure available at select cancer centers.
Intravenous delivery retains volume leadership; intratumoral approaches hold the steepest expansion curve in combination regimens.
End User:
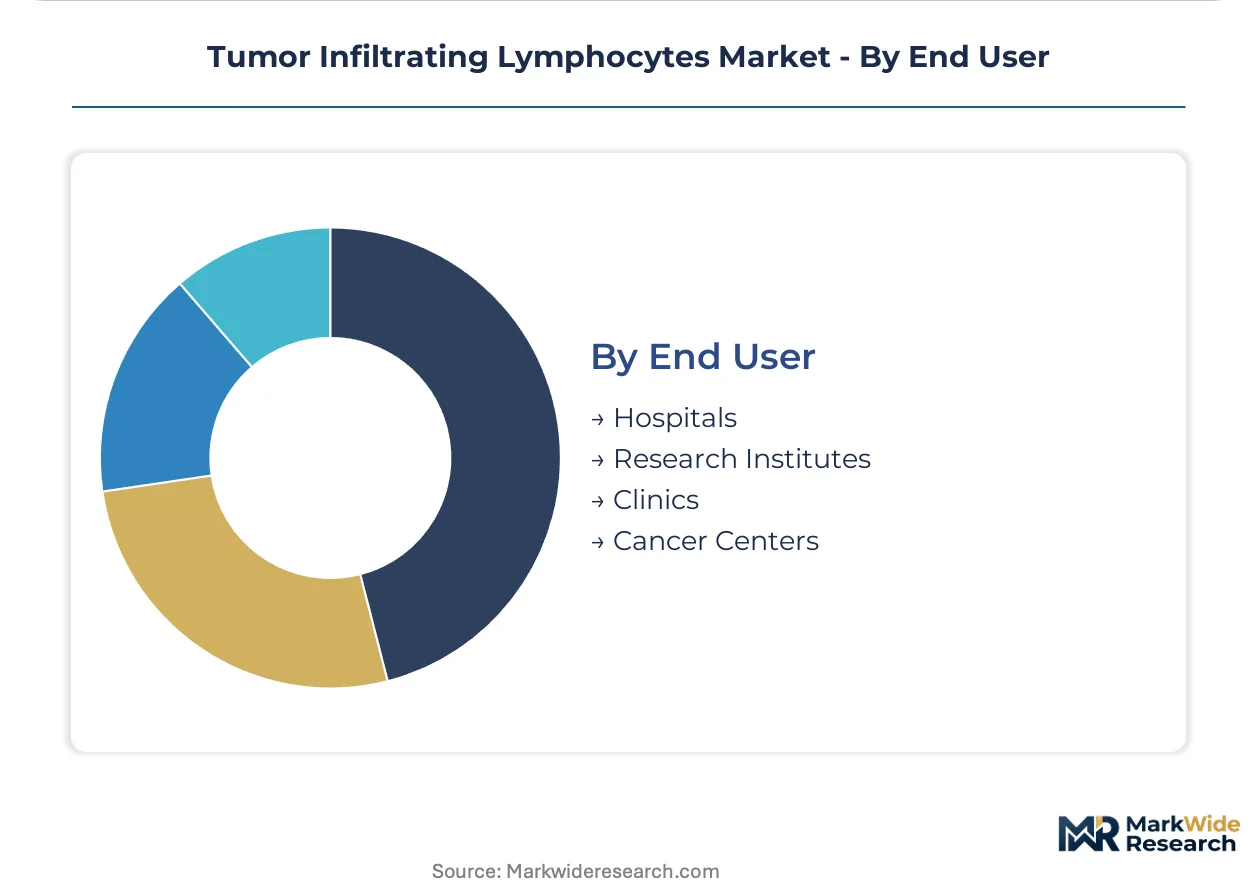
Customer type stratification reflects capability requirements, with cell processing infrastructure and regulatory accreditation determining site eligibility for TIL therapy administration.
- Cancer Centers:NCI-designated comprehensive cancer centers with on-site GMP manufacturing or established commercial partnerships, capturing the majority of reimbursed TIL therapy volume in the United States.
- Hospitals:Academic medical centers and tertiary care facilities integrating TIL protocols through centralized pharmacy and cell therapy units, particularly in Germany's university hospital networks.
- Research Institutes:Clinical trial sites and translational research facilities conducting investigator-sponsored studies of next-generation TIL engineering approaches.
- Clinics:Community oncology practices with limited access to TIL therapy, increasingly excluded as treatment concentrates in centers with captive manufacturing relationships or commercial partnerships.
Cancer centers retain volume leadership; research institutes hold the steepest expansion curve as engineering platforms advance toward clinical translation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers with GMP manufacturing capabilities concentrate TIL therapy demand across three continents. FDA regenerative medicine advanced therapy designations and EMA priority medicines schemes create parallel regulatory tracks that shape geographic investment patterns. Manufacturing infrastructure clusters in jurisdictions with established cell therapy reimbursement pathways.
United States
NCI-designated comprehensive cancer centers anchor domestic demand for autologous TIL therapy. FDA accelerated approval pathways compress development timelines for manufacturers establishing commercial manufacturing footprints. Boston and San Francisco biotech corridors host the majority of contract development organizations qualified for ISO 14644 cleanroom cell processing.
Germany
University hospital networks integrate TIL protocols into reimbursed oncology care for metastatic melanoma patients. EMA priority medicines designation accelerates market access for developers with EU manufacturing capabilities. Heidelberg and Munich academic medical centers concentrate Phase II trial activity for next-generation engineered TIL products.
United Kingdom
London and Cambridge cell therapy hubs attract venture investment for TIL manufacturing automation platforms. MHRA alignment with EMA cell therapy standards enables seamless regulatory navigation for US developers entering European markets. The NHS specialized commissioning framework restricts TIL therapy to designated cancer centers with established immuno-oncology infrastructure.
Netherlands
Leiden and Amsterdam bioclusters specialize in rapid expansion protocols that compress TIL manufacturing timelines. Dutch contract manufacturers pilot closed-system bioreactors ahead of EMA genetically modified organism containment deadlines. Rotterdam university hospitals participate in pan-European TIL therapy consortiums for lung cancer indications.
Japan
PMDA sakigake designation creates accelerated review pathways for TIL therapy developers targeting solid tumors. Tokyo and Osaka academic medical centers concentrate investigator-sponsored trials for engineered TIL products in gastric cancer. Japanese pharmaceutical conglomerates pursue licensing partnerships with US cell therapy specialists to access manufacturing know-how.
Tumor Infiltrating Lymphocytes Market Competitive Environment
Player mix skews toward integrated biopharmaceutical conglomerates with immuno-oncology infrastructure and specialized cell therapy developers with proprietary manufacturing platforms. Market structure concentrates around three strategic archetypes: large-cap pharmaceutical companies leveraging existing oncology sales networks, mid-cap cell therapy pure-plays with FDA-approved products, and emerging biotechnology firms engineering next-generation cytokine-modified TILs. Dominant competitive moves include capacity expansion into ISO 14644-compliant facilities and strategic partnerships between academic medical centers and commercial manufacturers.
Within the approved-product tier, Iovance Biotherapeutics anchors commercial positioning with the first FDA-cleared autologous TIL therapy for unresectable melanoma. Bristol-Myers Squibb occupies a position leveraging immuno-oncology infrastructure to pursue combination regimens. Among manufacturing-focused specialists, Instil Bio exemplifies the rapid-expansion archetype with processes targeting reduced production timelines.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Incyte Corporation |
| Iovance Biotherapeutics |
| Intima Bioscience |
| REPROCELL |
| Obsidian Therapeutics |
| Instil Bio |
| Lytix Biopharma |
| KSQ Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Non-viral electroporation systems replacing viral vector platforms in cytokine transgene insertion simultaneously shift manufacturing geography toward Dutch and German contract development organizations while collapsing per-batch production costs for engineered TIL products. This substitution dynamic concentrates pricing power among facilities with closed-system bioreactor capabilities, as ISO 14644 certification requirements eliminate lower-cost competitors from qualified supplier pools.
Pricing Analysis
Cost-plus contracts with IL-2 cytokine indexation dominate autologous TIL manufacturing agreements, insulating producers from raw material volatility while passing through cleanroom facility depreciation. Pricing stratifies across premium certified tiers (FDA RMAT-designated products), standard reimbursed pathways (German university hospital networks), and economy investigational protocols (academic consortiums without commercial partnerships). Cost compression in the standard tier intensifies as Medicare reimbursement rates fail to match four-week manufacturing timelines. Community oncology practices exhibit the highest price sensitivity, while NCI-designated cancer centers with captive GMP facilities demonstrate inelastic demand for premium-tier products.
Supply Chain Analysis
Strategic stockpiling of patient-derived tumor tissue precedes manufacturing campaigns, as just-in-time procurement proves impossible for autologous cell therapies with fixed biological starting material. Supply concentrates in the United States (Boston and San Francisco biotech corridors), Germany (Heidelberg and Munich academic medical centers), and the Netherlands (Leiden and Amsterdam bioclusters). The supply chain draws from resected tumor specimens, recombinant IL-2 cytokines, and single-use containment technologies. Single-source vulnerability permeates the viral vector segment as electroporation alternatives mature. Distribution runs through centralized pharmacy and cell therapy units at academic medical centers with GMP accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TIL therapy represents a high-growth disruption anchored by FDA regenerative medicine advanced therapy designation compressing development timelines from decade-long oncology norms toward accelerated cell therapy pathways. This regulatory inflection attracts capital allocation from immuno-oncology incumbents and specialized biotechnology investors alike.
For Market Incumbents: Fortify manufacturing capacity through backward integration into ISO 14644 cleanroom facilities in Germany and the Netherlands, securing priority medicines designation access as EMA tightens genetically modified organism containment requirements. Expand captive supply of IL-2 cytokines to offset substitution risk from next-generation cytokine engineering platforms. Channel control through exclusive partnerships with NCI-designated cancer centers defends against emerging allogeneic TIL developers threatening patient-specific manufacturing economics.
For New Entrants and Emerging Players: Differentiate on rapid expansion protocols targeting ten-day manufacturing windows for non-small cell lung cancer, the largest untapped solid tumor indication beyond melanoma. The most penetrable segment lies in Dutch and German contract manufacturing services, where EMA alignment creates regulatory arbitrage for US developers. A go-to-market angle through pan-European TIL therapy consortiums for lung cancer indications bypasses incumbent cancer center gatekeeping.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap cell therapy pure-plays with FDA-approved products and proprietary non-viral electroporation platforms, as these assets command premium valuations across the analysis window. Acquisition targets should demonstrate established manufacturing footprints in both US and EU jurisdictions. The signal to watch is potency assay standardization guidance from FDA, which would eliminate multi-site regulatory fragmentation and consolidate market access for scaled operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | ISO 14644 cleanroom expansion in Boston and San Francisco corridors anchors commercial TIL supply. |
| Regulatory Approval Pathway | FDA RMAT designation compresses development timelines for autologous cell therapy candidates. |
| Licensing Agreement | Japanese pharmaceutical conglomerates access US manufacturing know-through partnership structures. |
| Pipeline Diversification | Phase II trials for non-small cell lung cancer expand TIL protocols beyond melanoma boundaries. |
| Clinical Trial Advancement | Heidelberg and Munich academic centers concentrate engineered TIL activity for priority medicines designation. |
Study Parameters
Cross-validation between primary interviews with cell therapy manufacturing executives, regulatory affairs specialists at FDA and EMA, hospital procurement managers at NCI-designated cancer centers, and payer access directors anchors the qualitative findings. Secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov registries, and Medicare reimbursement databases. Bottom-up patient population modeling and top-down market sizing triangulate volume estimates across autologous and engineered TIL segments.
Sensitivity analysis around manufacturing timeline compression and cytokine cost trajectories informs the analytical framework across the projection horizon. Segmentation dimensions include product type (autologous versus engineered), therapy area (melanoma, lung cancer, breast cancer, colorectal cancer), delivery mode, and end-user capability tier. CAGRs derive from patient flow modeling through checkpoint inhibitor failure pathways and manufacturing capacity expansion curves. Industry-specific inputs capture IL-2 cytokine pricing volatility and cleanroom facility utilization rates.
The analysis sits within stated boundaries; outcomes outside FDA potency assay standardization or EMA genetically modified organism containment implementation would require recalibration. Forecasts reflect assumptions regarding reimbursement pathway stability and academic medical center consolidation trends. Revision becomes warranted when allogeneic TIL platform clinical data crosses efficacy thresholds that threaten autologous manufacturing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Liposarcoma Treatment Market
Oncology
Particle Therapy Systems Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Colorectal Cancer Screening Market
Oncology
Precision Oncology Market
Oncology
Tumor Lysis Syndrome Treatment Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market
Oncology
Global Proton Therapy Market
Oncology
Head and Neck Cancer Drugs Market
Oncology
Angiosarcomas Treatment Market
Oncology
Ustekinumab Market
Oncology
Lung Cancer Treatment Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Vulvar Cancer Market
Oncology
Tumor Lysis Syndrome Market
Oncology
Europe Tumor Ablation Market