
 Triple-Negative Breast Cancer Market | 2026-2036
Triple-Negative Breast Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Triple-Negative Breast Cancer Market Intelligence
Advanced efficacy benchmarks in metastatic settings is bifurcating the competitive landscape between legacy chemotherapy portfolios and next-generation biologics. AstraZeneca leverages its antibody-drug conjugate pipeline to sustain leadership in HER2-negative expansion indications. Pfizer anchors its position through targeted small-molecule investments that compete directly with immunotherapy combinations. F. Hoffmann-La Roche differentiates via companion diagnostic integration that controls patient selection workflows across major markets.
Triple-negative breast cancer denotes a molecular subtype lacking estrogen receptor, progesterone receptor, and HER2/neu expression, characterized by high histologic grade, basal-like gene expression profiles, and elevated Ki-67 proliferative indices; its clinical management demands cytotoxic or immune-mediated intervention given the absence of hormone-driven therapeutic targets. Immunotherapy segments are capturing disproportionate investment as checkpoint inhibitors reshape first-line standards, while chemotherapy retains volume dominance in neoadjuvant and salvage settings. Targeted therapy occupies a narrower but high-margin niche where PARP inhibitors and AKT pathway modulators concentrate prescriber attention in BRCA-mutated or PIK3CA-altered populations.
The FDA's breakthrough therapy designation and the EMA's priority medicines scheme jointly accelerate market access for novel TNBC agents, compressing the gap between pivotal trial readout and commercial availability. ISO 14155 clinical investigation standards and ICH-GCP frameworks enforce data integrity requirements that shape trial design costs and multinational enrollment feasibility. Stakeholders must monitor evolving biomarker definitions and payer evidence thresholds as the field transitions from histologic to genomic patient stratification.
Market Dynamics
Checkpoint inhibitor combinations are displacing first-line chemotherapy standards in metastatic triple-negative breast cancer, compressing prescriber workflows and reshaping formulary access negotiations across major oncology networks.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The accelerated approval pathway compresses development timelines for novel immunotherapy agents, enabling earlier commercial access for patients with limited therapeutic options.
- Companion Diagnostic Integration:PD-L1 testing platforms are standardizing patient selection workflows, expanding eligible populations for checkpoint inhibitor therapy across academic medical centers.
- Neoadjuvant Immunotherapy Expansion:Pathologic complete response endpoints are driving adoption of pre-surgical immune-mediated protocols in early-stage disease management.
Market Restraints
- Biomarker Testing Infrastructure Gaps:Community oncology practices lack standardized PD-L1 assay platforms, creating access disparities between academic and non-academic treatment settings.
- Reimbursement Uncertainty:Private payer prior authorization requirements for novel biologics generate treatment delays and administrative burden for prescribing oncologists.
- Chemotherapy Substitution Pressure:Generic taxane and platinum agent availability maintains cost-competitive alternatives in salvage therapy settings.
Strategic Opportunities
- Antibody-Drug Conjugate Expansion:TROP2-directed payloads are capturing prescriber attention in post-immunotherapy progression settings, creating new line-of-therapy positioning.
- PARP Inhibitor Combinations:BRCA-mutated subpopulations represent addressable niches where synthetic lethality mechanisms differentiate from standard cytotoxic approaches.
- Real-World Evidence Generation:Flatiron Health and similar oncology data networks enable post-marketing efficacy documentation that supports payer value demonstrations.
Industry Challenges
- Trial Enrollment Competition:Patient recruitment for combination therapy studies competes across overlapping eligibility criteria, prolonging study timelines.
- Biomarker Definition Evolution:Shifting PD-L1 scoring algorithms and assay platform heterogeneity complicate cross-trial comparability and regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triple-Negative Breast Cancer Market |
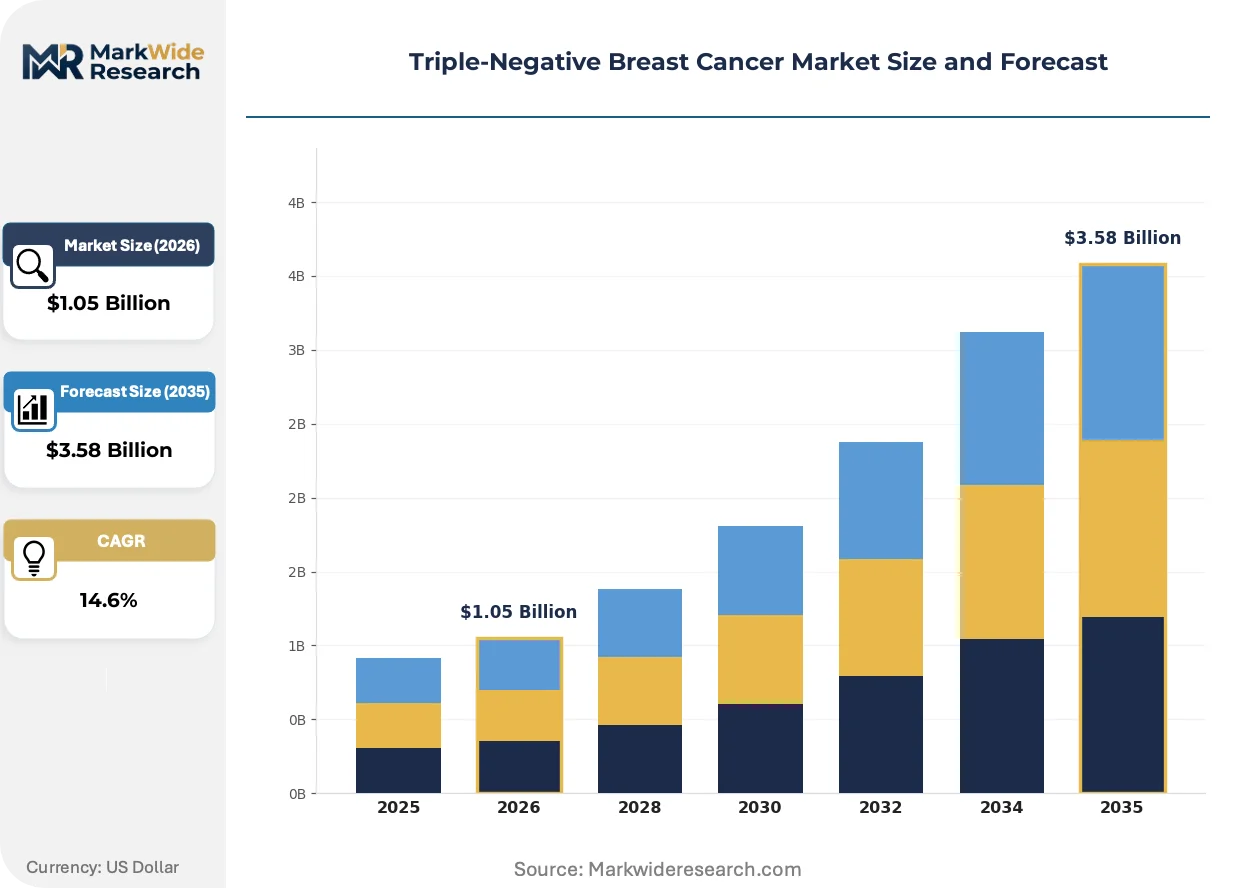
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $3.58 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiation Therapy Therapy Area: Oncology, Hematology, Palliative Care, Clinical Trials End User: Hospitals, Clinics, Research Institutions, Home Care Delivery Mode: Intravenous, Subcutaneous, Oral, Topical |
| Companies Covered | AstraZeneca, Pfizer, F. Hoffmann-La Roche, Novartis, Eli Lilly and Company, Bristol-Myers Squibb, Gilead Sciences, Merck & Co., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triple-Negative Breast Cancer Market Strategic Shifts & Innovations
Immunotherapy mechanism diversification and biomarker-driven patient stratification are compressing traditional histology-based treatment algorithms, forcing portfolio repositioning across development pipelines.
Antibody-drug conjugates targeting TROP2 are displacing conventional chemotherapy in second-line metastatic settings, with academic medical centers in the United States and Germany adopting these payloads ahead of community oncology networks. The structural consequence is a narrowing addressable window for legacy cytotoxic portfolios as prescribers prioritize targeted toxicity profiles.
The FDA's Project Optimus initiative is reshaping dose-selection methodologies for oncology agents, mandating randomized dose-finding studies rather than maximum-tolerated-dose paradigms. This regulatory pivot extends early-phase development timelines but improves probability of technical success in registrational trials. Small-molecule developers are responding by front-loading pharmacokinetic modeling to justify dose selections.
Consolidation of infusion center networks into hospital-based oncology departments is concentrating purchasing authority and compressing vendor access for specialty pharmacy distributors. This channel shift is most pronounced in United States metropolitan markets where vertical integration between payers and provider systems limits independent oncology practice autonomy.
Triple-Negative Breast Cancer Market Segmentation
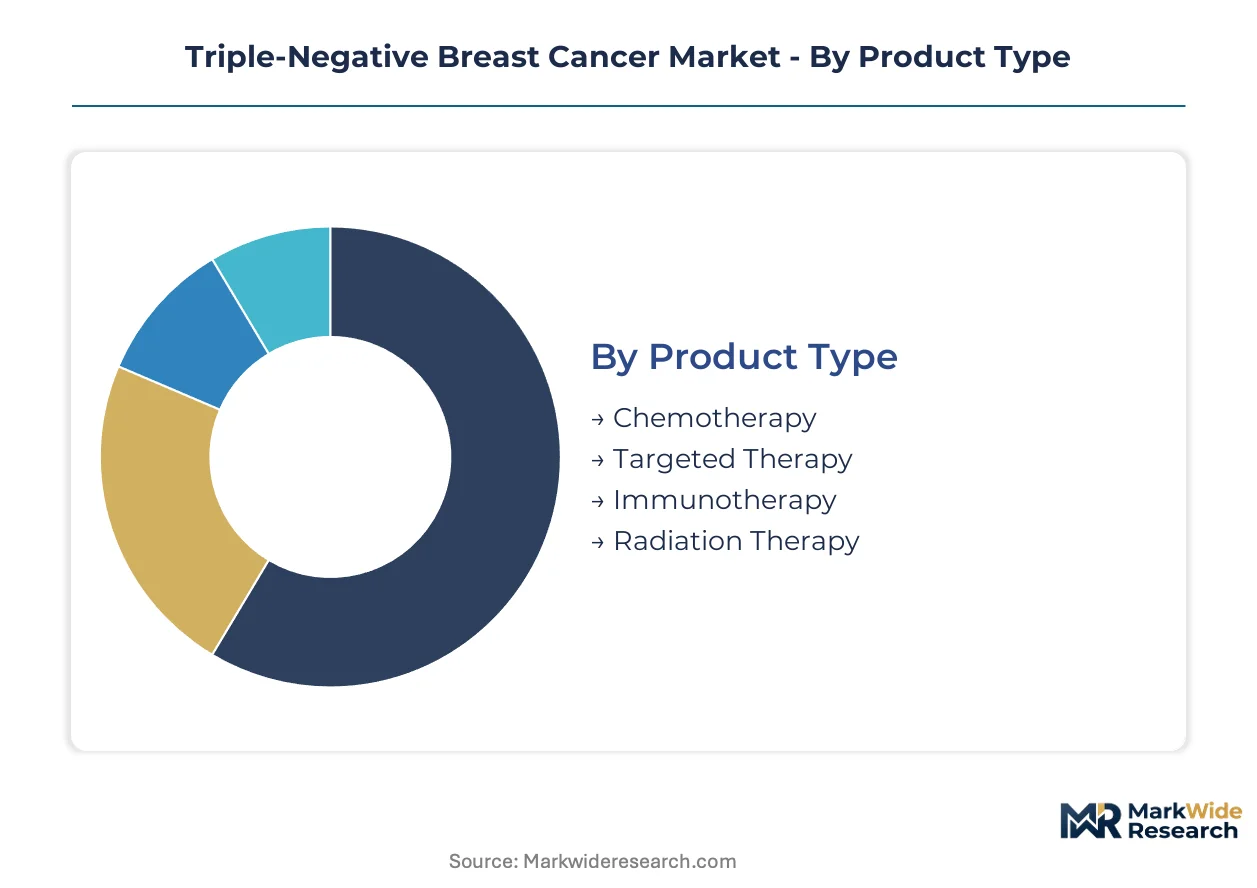
Triple-negative breast cancer treatment selection hinges on molecular profiling, disease stage, and prescriber access to specialized infrastructure. Segmentation reveals how margin pools concentrate in immunotherapy and targeted therapy despite chemotherapy retaining volume dominance. Understanding these splits enables portfolio positioning across academic medical centers and community oncology networks.
Product Type:
Margin concentration skews heavily toward biologics with companion diagnostic requirements, while generic cytotoxics compete on access and price.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways command premium positioning in first-line metastatic settings. Academic medical centers in the United States and Germany drive demand concentration as PD-L1 testing platforms standardize patient selection workflows.
- Targeted Therapy:PARP inhibitors and AKT pathway modulators address BRCA-mutated or PIK3CA-altered subpopulations through synthetic lethality mechanisms. These agents capture concentrated prescriber attention where companion diagnostics enable precise patient stratification.
- Chemotherapy:Taxane and platinum-based regimens retain neoadjuvant and salvage setting volume through established reimbursement pathways.
- Radiation Therapy:Adjuvant and palliative applications integrate with systemic protocols in early-stage and metastatic disease management.
The dominant share belongs to chemotherapy, while immunotherapy is closing the gap fastest.
Therapy Area:
Clinical trial infrastructure and regulatory designation pathways determine where development investment concentrates across therapeutic domains.
- Oncology:Medical oncology departments anchor TNBC treatment delivery, with FDA breakthrough therapy designations compressing development-to-commercial timelines for novel agents.
- Clinical Trials:Academic medical center networks compete for patient enrollment in combination therapy studies, with overlapping eligibility criteria prolonging recruitment timelines across investigational protocols.
- Hematology:Cross-disciplinary protocols address overlapping patient populations where hematologic complications intersect with solid tumor management.
- Palliative Care:Symptom management and quality-of-life endpoints integrate with disease-modifying therapy in advanced disease settings.
Oncology commands the largest addressable base, though clinical trials are gaining share fastest as pipeline density increases.
End User:
Purchasing authority consolidation and reimbursement complexity shape where novel agents achieve formulary access.
- Hospitals:Hospital-based oncology departments concentrate infusion center networks and purchasing authority, with vertical integration between payers and provider systems limiting independent practice autonomy in United States metropolitan markets.
- Research Institutions:Academic medical centers standardize biomarker testing workflows and control patient selection for clinical trial enrollment across major oncology networks.
- Clinics:Community oncology practices face infrastructure gaps in standardized PD-L1 assay platforms, creating access disparities versus academic settings.
- Home Care:Oral agent availability and subcutaneous delivery expansion enable treatment administration outside traditional infusion centers.
Hospitals retain the dominant share, while research institutions are expanding their role fastest through clinical trial integration.
Delivery Mode:
Route selection balances pharmacokinetic optimization with patient convenience and healthcare resource utilization.
- Intravenous:Infusion center dependency concentrates treatment delivery in hospital-based settings, with consolidation of networks compressing vendor access for specialty pharmacy distributors.
- Oral:Small-molecule targeted agents enable outpatient administration, with FDA Project Optimus initiatives reshaping dose-selection methodologies toward randomized studies rather than maximum-tolerated-dose paradigms.
- Subcutaneous:Reduced infusion time requirements and lower healthcare resource utilization support adoption in community oncology settings.
- Topical:Limited application in cutaneous metastases and symptom management within palliative care protocols.
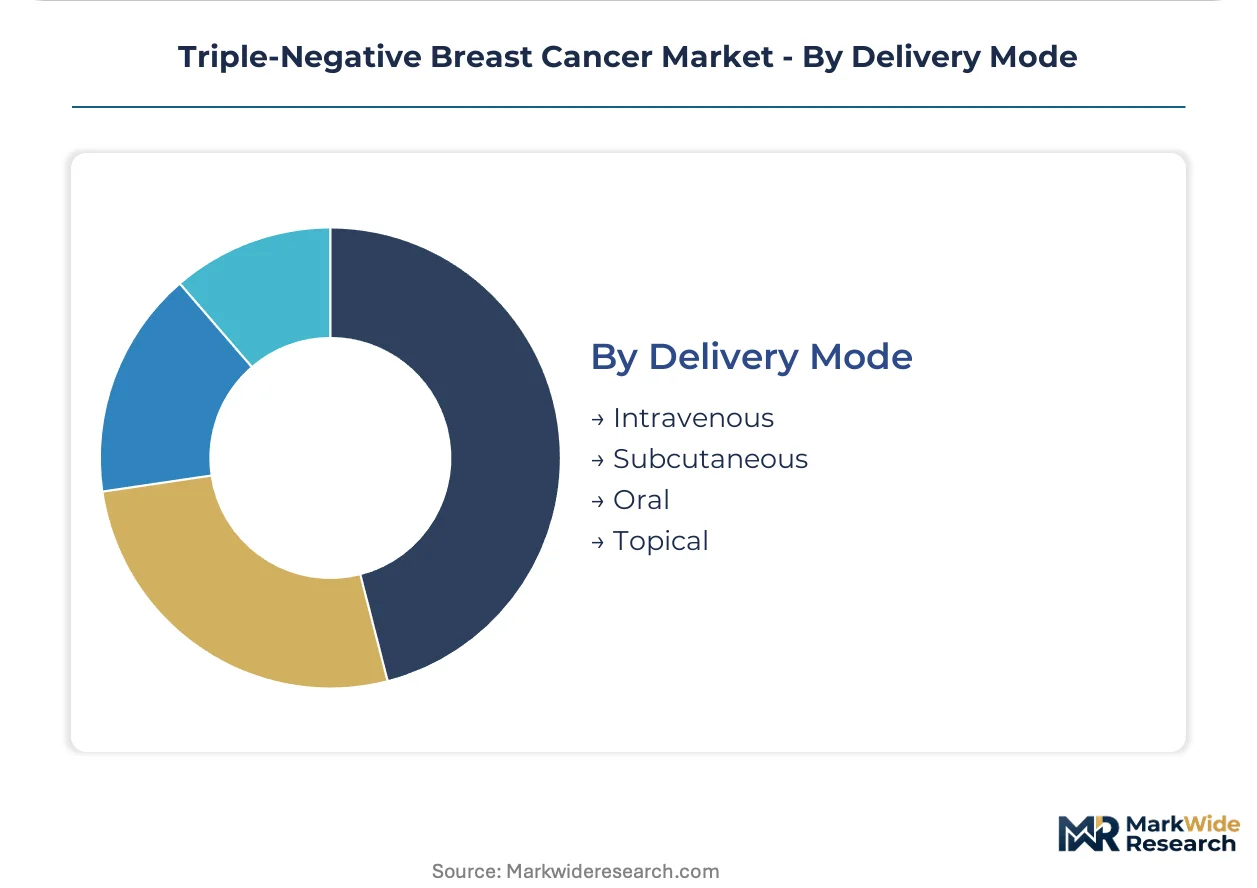
Intravenous delivery maintains the largest share, while oral formulations are climbing the fastest as small-molecule pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in triple-negative breast cancer therapeutics skew heavily toward import-dependent markets, with domestic manufacturing capacity concentrated in the United States, Germany, and Switzerland. Export intensity tracks patent-protected biologics and companion diagnostic platforms rather than commodity formulations.
United States
Academic medical center networks in Boston, New York, and Houston drive demand for checkpoint inhibitor combinations and TROP2-directed antibody-drug conjugates. FDA breakthrough therapy designations compress commercialization timelines, attracting development-stage investment toward U.S. pivotal trials. The National Cancer Institute's clinical trial infrastructure anchors patient recruitment density in the Mid-Atlantic and Southwest corridors.
Germany
University hospital oncology departments in Munich, Heidelberg, and Berlin standardize PD-L1 testing workflows and control access to neoadjuvant immunotherapy protocols. EMA priority medicines schemes align with national reimbursement pathways through the Federal Joint Committee. The Rhine-Main cluster concentrates Phase I-II investigator-initiated studies for PARP inhibitor combinations.
Japan
Metropolitan treatment centers in Tokyo and Osaka prioritize companion diagnostic integration for PD-L1 expression scoring prior to checkpoint inhibitor authorization. PMDA Sakigake designation accelerates review timelines for locally conducted pivotal trials. The Kanto region hosts concentrated contract research organization capacity supporting multinational oncology studies.
United Kingdom
NHS England's specialized commissioning frameworks concentrate high-cost biologic access through designated cancer centers in London, Manchester, and Birmingham. NICE technology appraisals determine reimbursement eligibility for novel immunotherapy agents ahead of EMA centralized approval. The Cambridge-Oxford-London triangle anchors early-phase biotechnology development.
China
Class A tertiary hospitals in Beijing, Shanghai, and Guangzhou drive demand for imported checkpoint inhibitors pending domestic biosimilar availability. NMPA priority review pathways accelerate market access for agents with China-inclusive global registration trials. The Yangtze River Delta hosts concentrated clinical research organization capacity serving multinational sponsors.
Triple-Negative Breast Cancer Market Key Industry Players
Concentration sits with integrated biopharmaceutical conglomerates commanding antibody-drug conjugate platforms, checkpoint inhibitor franchises, and companion diagnostic ecosystems. The competitive structure divides between legacy oncology portfolios anchored in cytotoxic chemotherapy and next-generation biologics reshaping prescriber workflows in metastatic settings. Three archetypes dominate: diversified conglomerates with diagnostic-therapeutic integration, mid-cap specialists with single-mechanism depth, and emerging entrants with differentiated payload technologies. Portfolio diversification and strategic partnerships constitute the dominant competitive moves, with M&A activity targeting TROP2-directed and HER2-low expansion indications.
Among diversified biopharmaceutical conglomerates, AstraZeneca, Pfizer, and F. Hoffmann-La Roche represent the archetype of integrated therapeutic-diagnostic platforms. AstraZeneca occupies a position defined by antibody-drug conjugate pipeline breadth in HER2-negative indications. Pfizer exemplifies targeted small-molecule investment competing directly with immunotherapy combination standards. F. Hoffmann-La Roche anchors the companion diagnostic integration tier, controlling patient selection workflows through centralized testing platforms across major markets.
| Leading Market Players |
|---|
| AstraZeneca |
| Pfizer |
| F. Hoffmann-La Roche |
| Novartis |
| Eli Lilly and Company |
| Bristol-Myers Squibb |
| Gilead Sciences |
| Merck & Co. |
| Sanofi |
| Others |
Cost & Logistics Intelligence
FDA breakthrough therapy designation and companion diagnostic certification requirements gate both manufacturer qualification and price differentiation simultaneously, concentrating pricing power with integrated biopharmaceutical conglomerates that control testing-platform ecosystems while compressing margins for undifferentiated chemotherapy portfolios.
Pricing Analysis
Hospital-based oncology departments anchor three-tier pricing structure across premium, standard, and economy levels in the triple-negative breast cancer market. Price differentiation rests on PD-L1 companion diagnostic integration and infusion-center network access rather than molecule class alone. Pricing pressure stems from generic taxane availability in salvage settings and biosimilar checkpoint inhibitor entry. Community oncology practices exhibit highest price sensitivity due to prior authorization administrative burden, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
The United States, Germany, and Switzerland anchor biologics manufacturing and companion diagnostic production for triple-negative breast cancer therapeutics. Active pharmaceutical ingredients for checkpoint inhibitors draw from specialized fermentation facilities in Ireland and Singapore, while antibody-drug conjugate payloads source from contract manufacturing organizations in the Netherlands. Single-source vulnerability concentrates in sterile fill-finish capacity for intravenous biologics. Distribution runs through hospital-based infusion center networks and specialty pharmacy channels with cold-chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital system consolidation and vertical payer-provider integration, fragmenting community oncology practice autonomy while concentrating formulary decision authority in metropolitan health systems.
For Market Incumbents: Shield checkpoint inhibitor franchise value by deepening companion diagnostic ecosystem control and securing long-term hospital system purchasing agreements. Generic chemotherapy substitution in salvage therapy settings and emerging TROP2-directed antibody-drug conjugate entrants threaten legacy positioning. Prioritize manufacturing capacity addition in FDA-inspected facilities to ensure supply continuity during breakthrough therapy demand surges. For New Entrants and Emerging Players: Lead with biomarker-defined patient stratification capabilities in BRCA-mutated and PIK3CA-altered subpopulations where synthetic lethality mechanisms differentiate from crowded immunotherapy combinations. Japan and Germany represent most penetrable regulatory markets for novel mechanism submissions ahead of U.S. commercialization. Deploy real-world evidence generation partnerships with oncology data networks as primary go-to-market angle to demonstrate value to hospital pharmacy and therapeutics committees. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap biotech specialists holding Phase II-ready antibody-drug conjugate platforms or differentiated payload technologies. Long-term viability over the coming decade hinges on pipeline optionality across HER2-low and HER2-negative expansion indications. Watch for pathologic complete response rate inflection in neoadjuvant immunotherapy trials as signal for first-line metastatic positioning durability.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | FDA-cleared PD-L1 assays from Roche and Agilent control patient selection workflows across major oncology networks. |
| Neoadjuvant Trial Expansion | Pathologic complete response endpoints in early-stage disease reshape prescriber adoption curves and reimbursement negotiations. |
| Antibody-Drug Conjugate Development | TROP2-directed payloads from AstraZeneca and Gilead capture post-immunotherapy progression settings with targeted toxicity profiles. |
| Real-World Evidence Partnership | Flatiron Health and similar oncology data networks enable post-marketing efficacy documentation supporting payer value demonstrations. |
| Manufacturing Scale-Up | Biologics capacity expansion in FDA-inspected facilities ensures supply continuity during breakthrough therapy demand acceleration. |
Research Approach
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down market sizing triangulation ensured cross-verification of volume and value estimates across the analysis window.
Sensitivity analysis framed the quantitative approach, with segmentation dimensions spanning treatment line, administration route, biomarker-defined patient population, and regional regulatory cluster. CAGRs derived from epidemiological trend extrapolation, therapy adoption curve modeling, and pricing trajectory assumptions. Forecast inputs incorporated clinical trial readout timelines and companion diagnostic approval pathways specific to oncology therapeutic development.
The analysis sits within stated boundaries; outcomes outside assumed regulatory approval success rates, reimbursement pathway clarity, and biomarker testing infrastructure expansion would require recalibration. Forecasts reflect documented assumptions regarding checkpoint inhibitor combination adoption curves and antibody-drug conjugate positioning sequences. Recalibration cycles align with material shifts in FDA breakthrough therapy designations and EMA priority medicines scheme decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Oncology Market
Oncology
Stomach Cancer Treatment Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Glottic Cancer Treatment Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Asia-Pacific Proton Therapy Market
Oncology
Esophageal Cancer Drugs Market
Oncology
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
North America Proton Therapy Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Cancer Cachexia Market
Oncology
Outpatient Oncology Infusion Market
Oncology
Breast Cancer Therapy Market
Oncology
Germany Radiotherapy Market