
 Immuno-Oncology Market | 2026-2036
Immuno-Oncology Market Size, Share, and Industry Trends Forecast 2026-2036
Immuno-Oncology Market Outlook
Buyer concentration among hospital systems and integrated cancer networks is shifting as community oncology practices consolidate into larger delivery organizations. Bristol Myers Squibb anchors its position through deep manufacturing scale in checkpoint inhibitor production. Merck competes aggressively with pembrolizumab-based combination strategies across solid tumor indications. BioNTech leverages mRNA manufacturing expertise to expand into individualized neoantigen vaccines.
Immuno-oncology encompasses therapeutic modalities that mobilize the patient's immune system to recognize and eliminate malignant cells, including monoclonal antibodies engineered with Fc-optimized effector functions and immune checkpoint inhibitors targeting PD-1, PD-L1, and CTLA-4 pathways. These biologics require cold-chain distribution, sterile parenteral manufacturing, and potency assays measuring T-cell activation markers to ensure clinical efficacy. Monoclonal antibodies and immune checkpoint inhibitors command the dominant share of current revenue, reflecting mature reimbursement pathways and broad label expansions. Cancer vaccines represent the fastest-expanding category, driven by mRNA platform validation and personalized neoantigen targeting, while cytokines remain a niche margin pool constrained by toxicity management requirements.
FDA accelerated approval pathways and EMA conditional marketing authorizations compress development timelines but mandate rigorous confirmatory trials, reshaping how sponsors allocate Phase IV investment. The FDA's Project Optimus and EMA's dose-finding guidance push manufacturers toward more sophisticated pharmacokinetic modeling earlier in development. Stakeholders must monitor how CMS national coverage determinations and NICE technology appraisals reconcile with increasingly complex biomarker-defined patient populations.
Market Dynamics
Hospital procurement of checkpoint inhibitors is pivoting toward combination regimens as FDA accelerated approvals compress confirmatory trial timelines and reshape sponsor investment patterns.
Growth Catalysts
- PD-1/PD-L1 pathway expansion:Bristol Myers Squibb and Merck are broadening label indications into earlier treatment lines across solid tumor settings, pulling volume from chemotherapy backbones.
- CAR-T manufacturing scale-up:Academic medical centers in the United States are building dedicated cell therapy suites to capture Medicare reimbursement for autologous T-cell products.
- mRNA platform validation:EMA conditional marketing authorizations for individualized neoantigen vaccines are validating BioNTech's manufacturing approach and attracting platform licensing interest.
Market Restraints
- Cold-chain distribution costs:Sterile parenteral biologics require continuous temperature monitoring from fill-finish through infusion, elevating logistics spend 40-60% above small-molecule benchmarks.
- Toxicity management protocols:Immune-related adverse events from checkpoint inhibitors demand specialized nursing staff and extended monitoring, constraining community oncology adoption.
- Confirmatory trial failure risk:FDA Project Optimus dose-finding requirements are extending Phase IV timelines and threatening accelerated approval withdrawals.
Strategic Opportunities
- Community oncology consolidation:Integrated cancer networks in Texas and Florida are acquiring independent practices to centralize infusion capacity and capture biologic margin.
- Bispecific antibody platforms:T-cell engagers targeting CD3 and tumor antigens simultaneously are expanding into hematologic malignancies with reduced cytokine release profiles.
- NCI funding prioritization:National Cancer Institute grants for combination immunotherapy trials are steering investigator-initiated studies toward novel mechanism pairings.
Industry Challenges
- Potency assay standardization:T-cell activation marker quantification lacks harmonized methods across contract manufacturing organizations, creating batch release bottlenecks.
- Talent scarcity in cell therapy:Vector production and aseptic processing expertise concentrates at a handful of academic centers, constraining workforce expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immuno-Oncology Market |
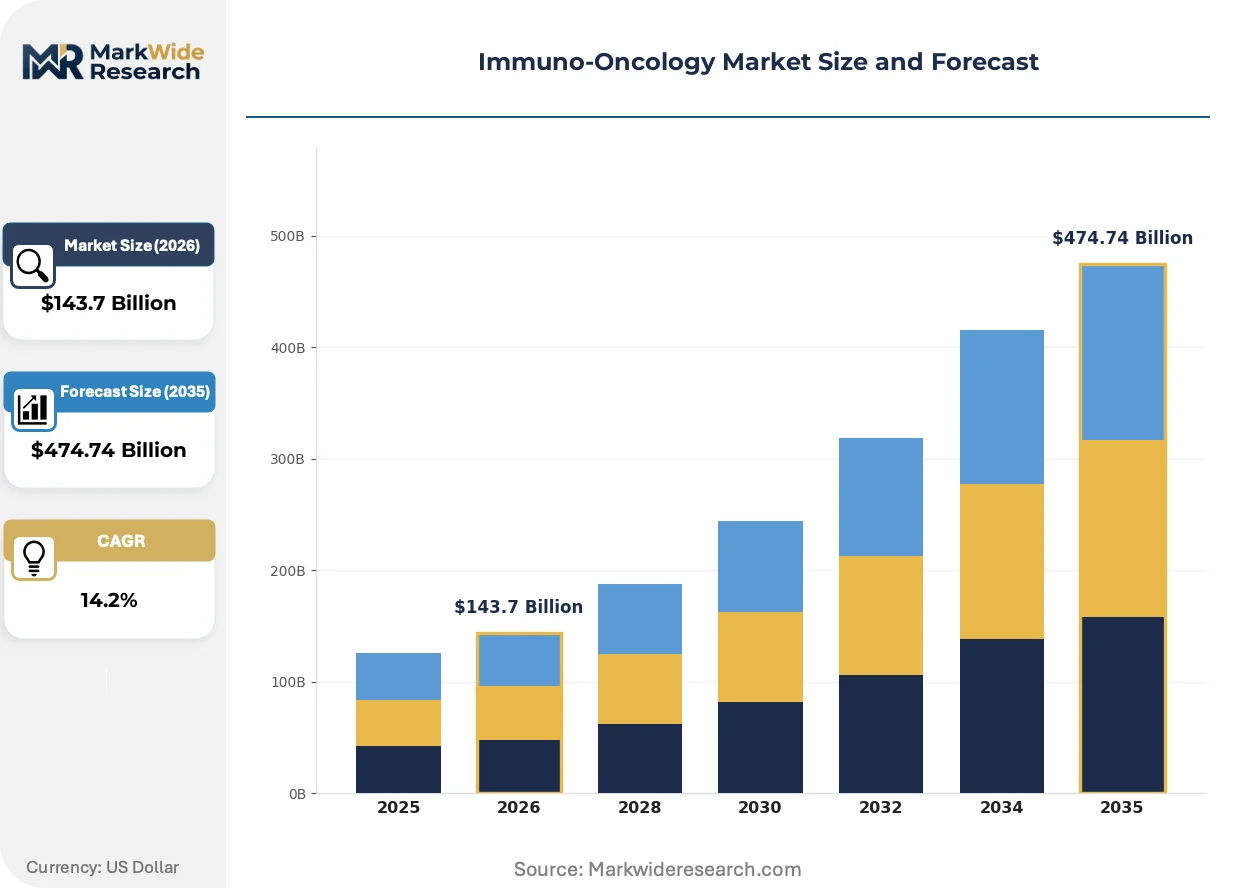
| Market Size in 2026 | $143.7 Billion |
| Market Size in 2035 | $474.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Immune Checkpoint Inhibitors, Cancer Vaccines, Cytokines Treatment Type: Combination Therapy, Monotherapy, Adjuvant Therapy, Neoadjuvant Therapy End User: Hospitals, Research Institutes, Cancer Treatment Centers, Homecare Settings Administration Route: Intravenous, Subcutaneous, Oral, Intramuscular |
| Companies Covered | CureVac, Bristol Myers Squibb, Moderna, Merck, Johnson & Johnson, BioNTech, AbbVie, Thermo Fisher Scientific, Arcturus Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immuno-Oncology Market Strategic Shifts
Immuno-oncology development is compressing toward biomarker-defined patient populations as sponsors abandon broad-label strategies in favor of registrational trials with companion diagnostics.
Individualized neoantigen vaccines are expanding into late-stage melanoma and non-small cell lung cancer as manufacturing automation reduces lead times from tumor sequencing to product release. Academic medical centers with dedicated GMP facilities are adopting these platforms for investigator-initiated protocols. The structural consequence is that mRNA manufacturing expertise is expanding into personalized therapeutics, displacing one-size-fits-all checkpoint inhibitor protocols in select indications.
EMA's dose-finding guidance and FDA's Project Optimus are forcing sponsors to conduct more sophisticated pharmacokinetic modeling in Phase I, extending development timelines but reducing Phase III failure rates. Manufacturers must now justify every dose level with exposure-response relationships rather than maximum tolerated dose selection. Oncology sponsors with established modeling capabilities are capturing competitive advantage in registrational trial design.
Hospital systems are consolidating infusion capacity into dedicated immuno-oncology centers of excellence, unbundling routine chemotherapy administration from complex biologic monitoring. Community oncology practices without on-site pharmacy capabilities are referring checkpoint inhibitor patients to affiliated hospital outpatient departments. This concentration is most visible in Medicare Advantage penetration markets where prior authorization requirements favor integrated delivery networks.
Immuno-Oncology Market Segmentation
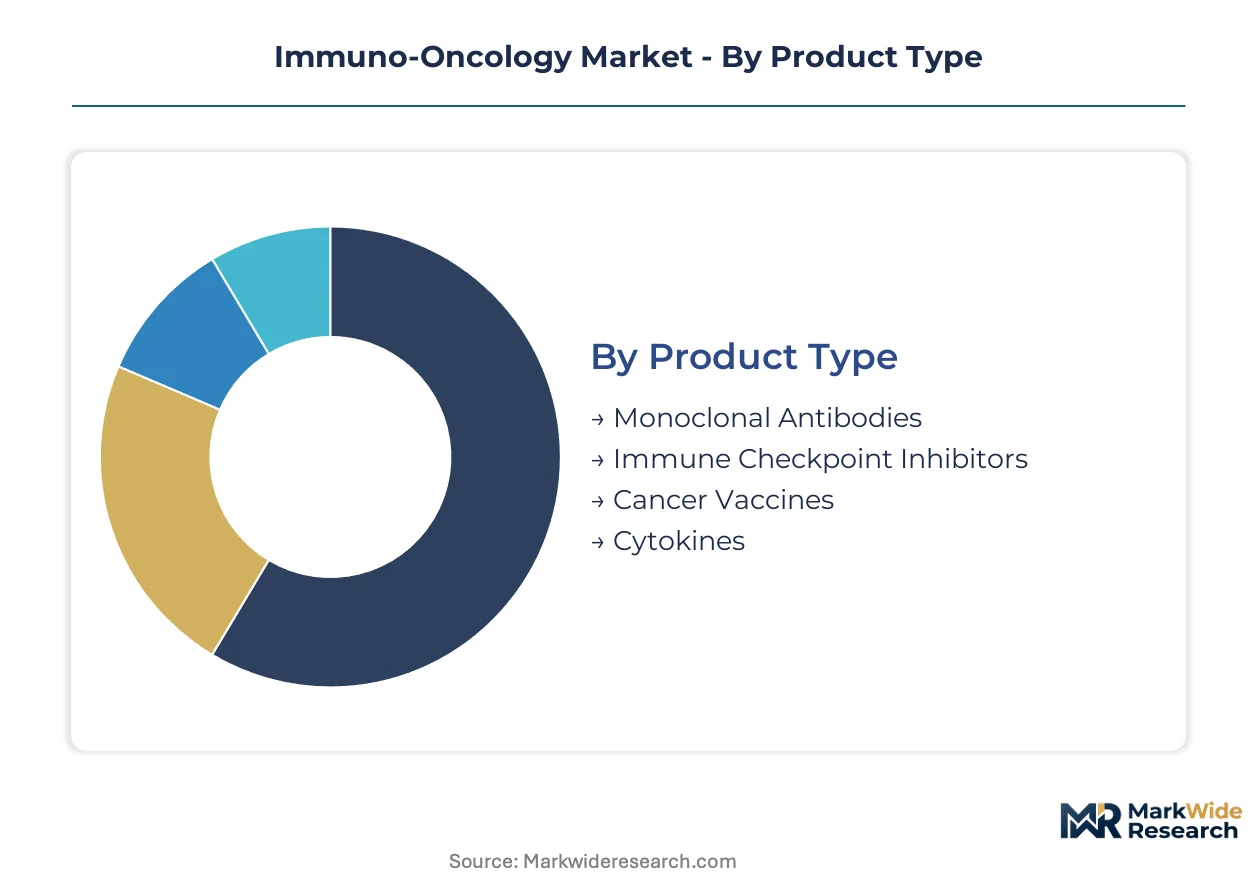
Therapeutic modality selection in immuno-oncology hinges on manufacturing scalability, biomarker specificity, and reimbursement pathway maturity. Segmentation reveals where capital deployment concentrates across standardized platform technologies versus individualized production approaches.
Product Type:
Standardized mass production dominates monoclonal antibodies and checkpoint inhibitors, while cancer vaccines require bespoke manufacturing workflows tailored to individual tumor sequencing.
- Monoclonal Antibodies:Engineered biologics with Fc-optimized effector functions trigger antibody-dependent cellular cytotoxicity against tumor cells. Demand concentrates in academic medical centers with established infusion protocols and dedicated pharmacy capacity for sterile parenteral handling.
- Immune Checkpoint Inhibitors:PD-1, PD-L1, and CTLA-4 pathway blockers command the largest revenue pool due to broad label expansions and mature Medicare reimbursement. Procurement at integrated cancer networks is pivoting toward combination regimens as FDA accelerated approvals compress confirmatory trial timelines.
- Cancer Vaccines:mRNA platforms and individualized neoantigen targeting require tumor sequencing-to-product release workflows. EMA conditional marketing authorizations are validating manufacturing automation investments.
- Cytokines:Interleukin and interferon therapies remain constrained by toxicity management requirements and narrow therapeutic indices.
Most installed capacity flows through Immune Checkpoint Inhibitors. Expansion is steepest in Cancer Vaccines.
Treatment Type:
Cost tier stratification separates high-complexity combination protocols from streamlined monotherapy administration in community oncology settings.
- Combination Therapy:Checkpoint inhibitor pairings or chemo-immunotherapy sequences require sophisticated nursing staff and extended monitoring infrastructure. NCI funding priorities are steering investigator-initiated studies toward novel mechanism pairings at academic medical centers.
- Monotherapy:Single-agent PD-1/PD-L1 blockers suit community oncology practices with limited on-site pharmacy capabilities. Prior authorization requirements in Medicare Advantage penetration markets favor streamlined protocols.
- Adjuvant Therapy:Post-surgical immunotherapy protocols target minimal residual disease in melanoma and non-small cell lung cancer.
- Neoadjuvant Therapy:Pre-operative immune priming is expanding into early-stage triple-negative breast cancer and muscle-invasive bladder cancer.
Revenue concentration sits with Combination Therapy. Volume growth is climbing fastest in Neoadjuvant Therapy.
End User:
Customer type fragmentation reflects divergent capabilities for cold-chain distribution, sterile compounding, and immune-related adverse event management.
- Hospitals:Integrated delivery networks with dedicated immuno-oncology centers of excellence capture biologic margin through centralized infusion capacity. Consolidation in Texas and Florida markets is acquiring independent practices to unbundle complex biologic monitoring from routine chemotherapy.
- Cancer Treatment Centers:Specialized outpatient facilities with on-site GMP cell therapy suites capture Medicare reimbursement for autologous CAR-T products.
- Research Institutes:Academic medical centers with dedicated GMP facilities are adopting individualized neoantigen vaccine platforms for investigator-initiated protocols.
- Homecare Settings:Subcutaneous checkpoint inhibitor formulations are enabling limited administration outside institutional settings.
Patient volume concentrates in Hospitals. Infrastructure investment is accelerating most quickly in Cancer Treatment Centers.
Administration Route:
Supply concentration varies by route complexity, with intravenous requiring continuous cold-chain monitoring and subcutaneous enabling broader site-of-care expansion.
- Intravenous:Infusion-dependent biologics require sterile parenteral manufacturing, potency assays measuring T-cell activation markers, and continuous temperature monitoring from fill-finish through administration. Logistics spend runs 40-60% above small-molecule benchmarks.
- Subcutaneous:Self-administration potential and reduced infusion center burden are attracting formulation investment from sponsors seeking community oncology expansion.
- Oral:Small-molecule immune modulators remain limited by bioavailability challenges and first-pass metabolism.
- Intramuscular:mRNA vaccine platforms leverage established delivery infrastructure from infectious disease applications.
Dose administration flows predominantly through Intravenous channels. Subcutaneous formulations are gaining share fastest as site-of-care economics shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell therapy manufacturing talent clusters in the United States, Switzerland, and Germany anchor regional competitive positioning. Academic medical centers with dedicated GMP facilities concentrate where regulatory pathways and reimbursement infrastructure align.
United States
Academic medical centers in Boston and Houston drive CAR-T manufacturing scale-up as Medicare reimbursement policies reward autologous cell therapy suites. FDA accelerated approval pathways compress confirmatory trial timelines, pulling sponsor investment toward combination regimens. The National Cancer Institute's funding priorities steer investigator-initiated studies toward novel mechanism pairings at centers like MD Anderson and Memorial Sloan Kettering.
Germany
BioNTech's manufacturing expertise in Mainz validates mRNA platform approaches for individualized neoantigen vaccines. EMA conditional marketing authorizations attract platform licensing interest from global sponsors seeking European market entry. The Rhine-Main biotech corridor concentrates sterile parenteral manufacturing capacity for cold-chain biologics distribution across the continent.
Switzerland
Roche's Basel operations anchor monoclonal antibody production with Fc-optimized effector functions for antibody-dependent cellular cytotoxicity. Swissmedic's regulatory framework supports early-access programs for checkpoint inhibitors in melanoma and lung cancer indications. The Greater Zurich Area concentrates precision medicine talent for biomarker-defined patient stratification.
China
Domestic sponsors in Shanghai and Suzhou scale PD-1/PD-L1 inhibitor production as NMPA reform accelerates oncology biologic approvals. The country's national pharmaceutical regulator aligns with international ICH guidelines, reducing regulatory friction for multinational trial participation. Yangtze River Delta biotech parks attract venture capital for bispecific antibody platform development.
United Kingdom
London's cancer research institutes pioneer neoadjuvant immunotherapy protocols for early-stage triple-negative breast cancer. NICE technology appraisals reconcile cost-effectiveness thresholds with biomarker-defined patient populations. The Golden Triangle corridor between London, Oxford, and Cambridge concentrates early-phase clinical trial infrastructure for immune-oncology combinations.
Immuno-Oncology Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across therapeutic modality boundaries. The market structure tiers between large-cap pharmaceutical companies with checkpoint inhibitor scale and emerging biotech platforms with novel mechanism assets. Three archetypes dominate: diversified oncology giants with manufacturing depth, mRNA platform specialists with personalized vaccine capabilities, and cell therapy innovators with autologous production expertise. Competitive intensity centers on M&A activity for novel targets and strategic partnerships for manufacturing capacity access.
Among diversified pharmaceutical conglomerates, Bristol Myers Squibb and Merck occupy positions defined by checkpoint inhibitor manufacturing scale and combination regimen portfolios. BioNTech exemplifies the mRNA platform specialist archetype, leveraging individualized neoantigen vaccine workflows validated through EMA conditional marketing authorizations. These three companies represent distinct strategic vectors: large-scale biologic production, personalized therapeutic manufacturing, and platform technology licensing.
| Leading Market Players |
|---|
| CureVac |
| Bristol Myers Squibb |
| Moderna |
| Merck |
| Johnson & Johnson |
| BioNTech |
| AbbVie |
| Thermo Fisher Scientific |
| Arcturus Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement consolidation into integrated cancer networks is compressing price tolerance for checkpoint inhibitors and forcing manufacturers toward outcome-based contracting models that tie reimbursement to biomarker-confirmed response rates.
Pricing Analysis
Capacity additions in Switzerland and Germany are reshaping price floors for sterile parenteral biologics as BioNTech and Roche expand GMP manufacturing footprints. Three-tier pricing structure across premium combination regimens, standard monotherapy protocols, and economy-positioned biosimilar entrants reflects differentiation by clinical data maturity and biomarker specificity. Cost compression in community oncology channels is intensifying because Medicare Advantage prior authorization requirements favor streamlined protocols. Community practices without infusion capabilities demonstrate highest price sensitivity, while academic medical centers with dedicated pharmacy capacity prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale demand from integrated delivery networks, bypassing wholesale distributors for temperature-sensitive biologics. Manufacturing concentration sits with the United States, Switzerland, and Germany, where sterile parenteral capacity and cell therapy suites cluster near major academic medical centers. Cold-chain logistics draws from specialized courier networks with continuous temperature monitoring, while fill-finish operations rest on single-source fill-finish equipment suppliers. Single-source vulnerability in viral vector production constrains CAR-T expansion. Distribution runs through manufacturer-controlled specialty pharmacy networks with patient-specific lot tracking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where survival depends on manufacturing reliability and biomarker precision, justified by hospital procurement's decisive shift toward companion diagnostic-linked reimbursement protocols.
For Market Incumbents: Deploy manufacturing scale as the primary defensive lever. Bristol Myers Squibb and Merck should deepen backward integration into fill-finish capacity to secure batch release autonomy against contract manufacturing bottlenecks. Accelerate investment in potency assay harmonization to preempt FDA enforcement actions on T-cell activation marker quantification. The emerging threat of mRNA platform displacement in melanoma and lung cancer indications demands rapid label expansion into earlier treatment lines. For New Entrants and Emerging Players: Bispecific antibody platforms offer the most penetrable wedge for specialized indications with reduced cytokine release profiles. White-space opportunities concentrate in neoadjuvant therapy for triple-negative breast cancer and muscle-invasive bladder cancer, where checkpoint inhibitor penetration remains incomplete. Community oncology practices in Texas and Florida present acquisition targets for integrated networks seeking infusion capacity. A technology-first go-to-market angle should emphasize subcutaneous formulation development to bypass hospital outpatient dependency. For Investors and Strategic Acquirers: Asymmetric upside sits with cell therapy innovators possessing autologous manufacturing expertise and established academic medical center relationships. Long-term viability across the analysis window favors platform specialists with validated EMA conditional marketing authorizations over single-asset developers. Acquisition target archetype: mid-cap biotech with Phase II bispecific assets and existing GMP cell therapy suites. The signal to watch is NCI funding reallocation toward combination immunotherapy trials as an indicator of investigator-initiated protocol momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Expands sterile parenteral capacity to capture Medicare reimbursement for hospital outpatient infusion. |
| Regulatory Approval Pathway | EMA conditional marketing authorizations validate mRNA platforms for individualized neoantigen vaccines. |
| Pipeline Diversification | Bispecific antibody development reduces cytokine release syndrome risk versus first-generation CAR-T. |
| Strategic Partnership | Academic medical center alliances secure investigator-initiated trial access and cell therapy suite utilization. |
| Reimbursement Strategy | Companion diagnostic co-development aligns with CMS national coverage determination requirements. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded qualitative insights in operational reality. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital formulary databases. Bottom-up and top-down triangulation reconciled manufacturer-reported capacity expansion plans with Medicare claims data on infusion administration patterns.
Bottom-up modeling anchored volume projections to patient population incidence, biomarker prevalence, and treatment line penetration assumptions across the projection horizon. Segmentation dimensions included therapeutic modality, treatment type, end user facility type, and administration route. CAGRs were derived from slope analysis of historical approval trajectories and sponsor pipeline disclosure patterns. Forecast inputs incorporated NCI funding allocation trends and FDA Project Optimus implementation timelines.
The model holds under stable Medicare reimbursement policies and continued EMA conditional marketing authorization pathways; deviation in accelerated approval withdrawal rates or confirmatory trial failure frequency would shift volume trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Metastatic Cancer Drug Market
Oncology
Ustekinumab Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
Asia Pacific Cancer Immunotherapy Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Small Cell Lung Cancer (SCLC) Therapeutics Market
Oncology
Glioblastoma Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
AI in Oncology Market
Oncology
Thymus Cancer Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
North America Proton Therapy Market