
 ICT Investment in Government Market | 2026-2036
ICT Investment in Government Market Size, Share, and Industry Trends Forecast 2026-2036
ICT Investment in Government Market Intelligence
India's national cloud infrastructure build-out is narrowing the capability gap between legacy state data centers and hyperscale alternatives. Microsoft Corporation leverages its Azure Government cloud stack to anchor public sector contracts across multiple continents. IBM Corporation sustains deep integration with defense and intelligence workflows through its hybrid cloud and quantum-safe encryption portfolios. Amazon Web Services competes aggressively on FedRAMP-authorized regions while extending sovereign cloud offerings to European governments.
ICT investment in government encompasses the acquisition, deployment, and modernization of digital infrastructure, software platforms, and specialized services by public sector entities, typically requiring compliance with stringent security protocols such as FIPS 140-2 encryption standards and ISO 27001 certification. Its primary purpose is to enhance citizen service delivery, strengthen national cybersecurity posture, and enable data-driven policy formulation. Software and services segments command the dominant margin pools as governments shift from capital-intensive hardware ownership toward subscription-based cloud consumption. Cybersecurity and cloud computing usage categories are absorbing the fastest investment growth as ransomware threats and remote workforce mandates reshape procurement priorities.
The US Federal Risk and Authorization Management Program (FedRAMP) and the European Union's Cybersecurity Act create dual compliance architectures that vendors must satisfy for market access, effectively segmenting the competitive landscape by geography. India's Ministry of Electronics and Information Technology (MeitY) imposes data localization requirements through its cloud computing guidelines, redirecting foreign vendor strategies toward in-country infrastructure partnerships. Stakeholders must monitor the divergence between US-centric security frameworks and emerging EU digital sovereignty requirements when allocating R&D and compliance resources.
Market Dynamics
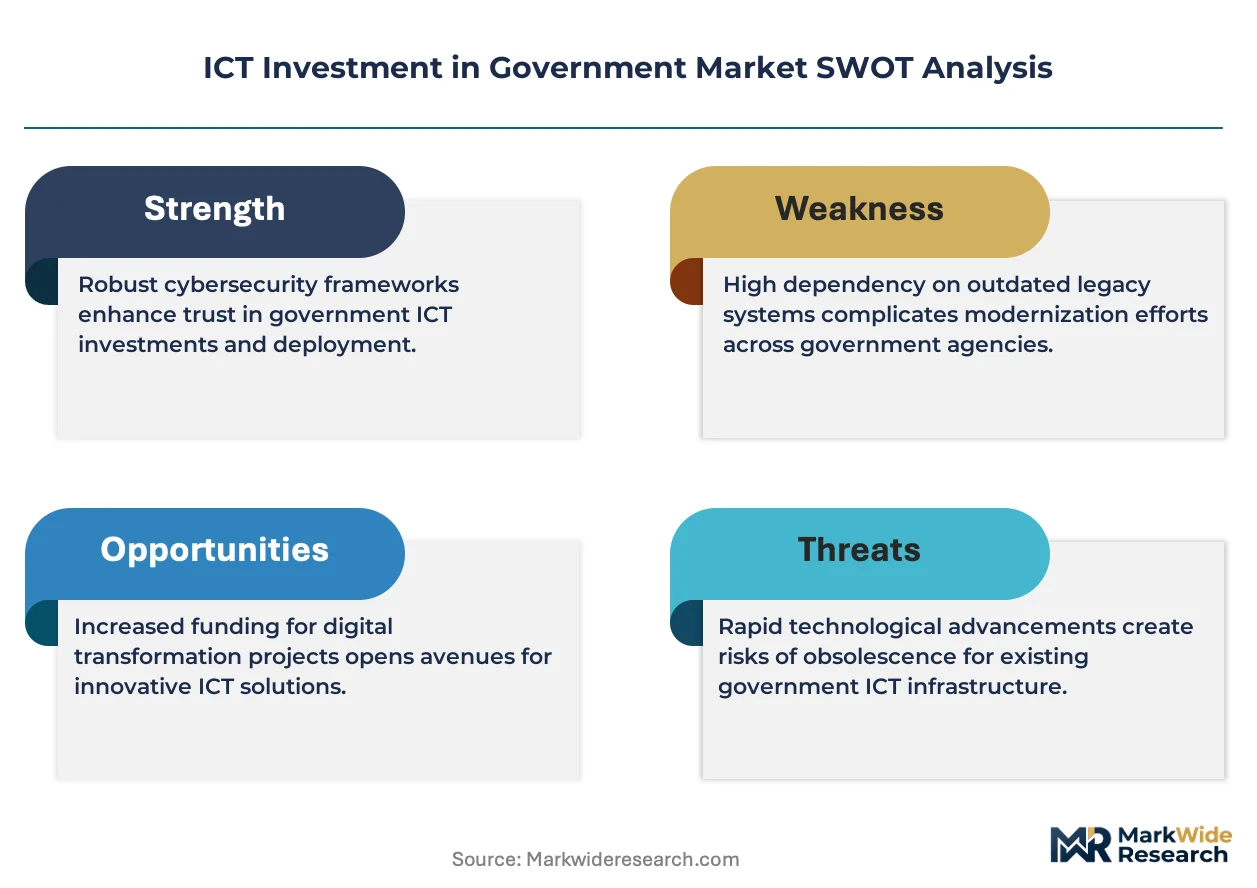
Sovereign cloud mandates are fragmenting procurement architectures as governments prioritize data localization over cost optimization, forcing vendors to rebuild infrastructure within jurisdictional boundaries rather than leveraging centralized hyperscale efficiency.
Growth Catalysts
- FedRAMP authorization expansion:US federal agencies are accelerating cloud migration timelines through streamlined security certification pathways, compressing vendor onboarding cycles from 18 months to under 6 months for pre-authorized platforms.
- EU AI Act compliance infrastructure:Public sector AI deployments now require auditable risk management systems, generating dedicated budget lines for governance tooling and automated compliance monitoring across member state procurement frameworks.
- Quantum-safe cryptography migration:Defense and intelligence agencies in Germany, France, and the United Kingdom are mandating post-quantum encryption standards ahead of commercial availability, creating premature upgrade cycles in classified network infrastructure.
Market Restraints
- Specialized workforce scarcity:Security-cleared cloud architects and compliance engineers command premium compensation that exceeds fixed government salary bands, constraining deployment velocity for complex multi-tenant environments.
- Supply concentration in sovereign infrastructure:Domestic cloud providers in India, Germany, and France lack hyperscale redundancy, exposing continuity risks when single-nationality vendors face technical or political disruption.
- Legacy system integration debt:COBOL-based entitlement systems and paper-filed record archives in aging federal agencies impose translation-layer costs that consume 40-60% of modernization budgets before new capabilities deploy.
Strategic Opportunities
- Interoperable e-government platforms:Germany's federal digitalization programs are creating reference architectures for cross-border service integration that neighboring Austria, Switzerland, and Benelux states are adopting through bilateral procurement agreements.
- AI-powered citizen service automation:Chatbot and predictive case routing deployments in tax, benefits, and licensing agencies are reducing human touchpoint costs while improving 24-hour availability metrics.
- Green data center mandates:The EU Green Deal's carbon reporting requirements for public procurement are advantaging vendors with renewable energy matching and liquid cooling technologies in Nordic and Baltic state tenders.
Industry Challenges
- Cross-domain security clearance pipelines:Personnel vetting backlogs in defense and intelligence agencies extend project staffing timelines by 8-14 months, delaying critical infrastructure deployments regardless of technical readiness.
- Multi-jurisdictional compliance stacking:Vendors serving NATO-aligned governments must simultaneously satisfy FedRAMP, EUCS, and national certification schemes, multiplying audit costs without reciprocal recognition agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ICT Investment in Government Market |
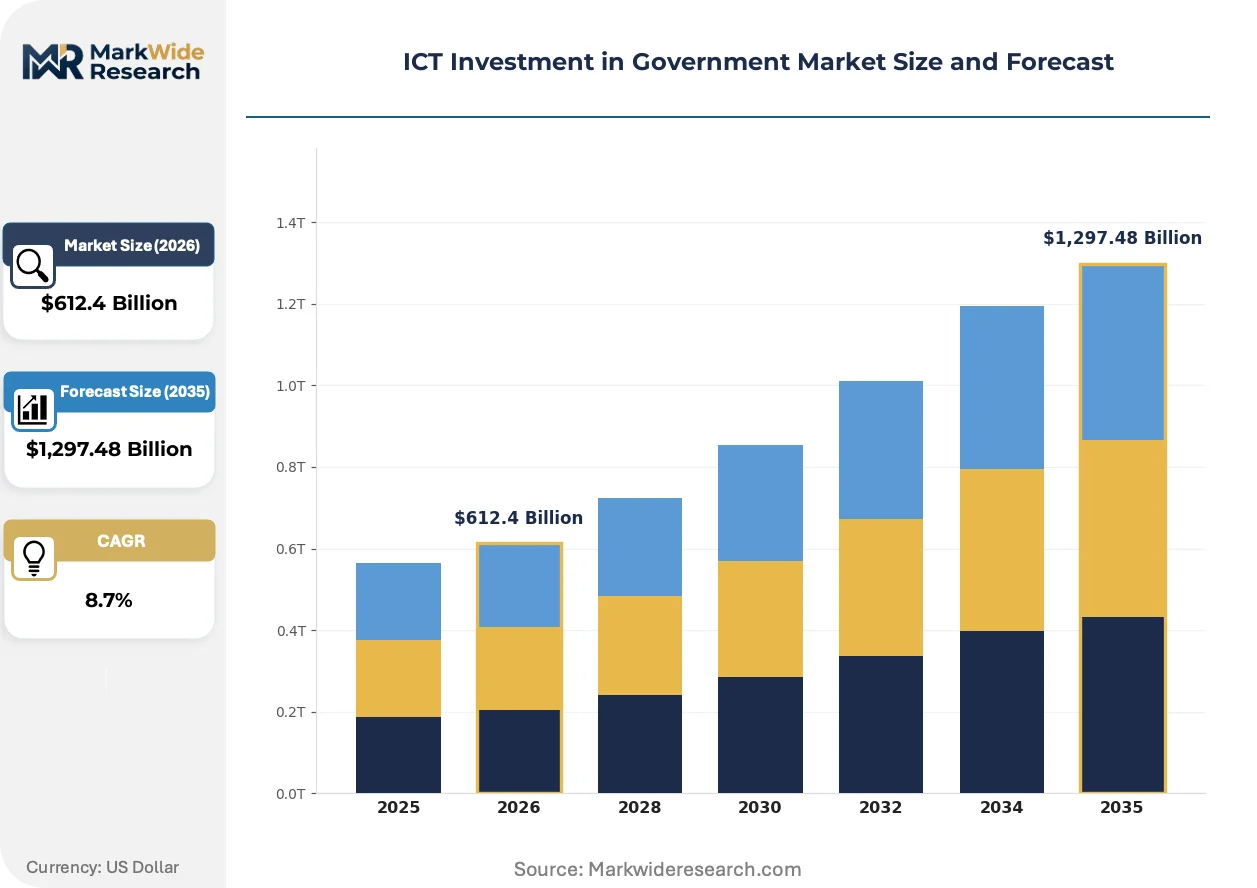
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,297.48 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Type: Infrastructure, Software, Services, Hardware Usage Category: Cybersecurity, Cloud Computing, Data Management, E-Governance Client Sector: Public Agencies, Municipalities, Defense, Education Departments Technology Focus: AI, Blockchain, IoT, Big Data |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, Cisco Systems, Accenture, SAP SE, Hewlett Packard Enterprise, Amazon Web Services, Capgemini SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ICT Investment in Government Market Strategic Shifts & Innovations
Computational sovereignty is displacing efficiency as the primary architectural criterion, with governments accepting 15-30% cost premiums for infrastructure that guarantees jurisdictional control over data residency and encryption key management.
Confidential computing hardware is hybridizing security boundaries between cloud tenants by enabling encrypted processing within processor enclaves. Defense agencies and financial regulators are piloting these capabilities for multi-party analytics on sensitive datasets. The technology is compressing the traditional air-gap requirement for classified workloads, allowing controlled cloud migration without full infrastructure replication.
The EU AI Act's risk-based classification system is mandating human oversight documentation and bias testing for high-stakes public sector algorithms. Vendors must now embed explainability tooling and audit trails into procurement deliverables. Law enforcement and judicial applications face the strictest compliance timelines, with deployment freezes pending conformity assessment completion.
Subscription consumption models are displacing perpetual licensing in enterprise software procurement for government agencies. Finance ministries in the Netherlands, Denmark, and Australia are consolidating vendor relationships through centralized SaaS marketplaces with pre-negotiated terms. This concentration is compressing the competitive field to providers capable of meeting aggregated demand volumes and unified security requirements.
ICT Investment in Government Market Segmentation
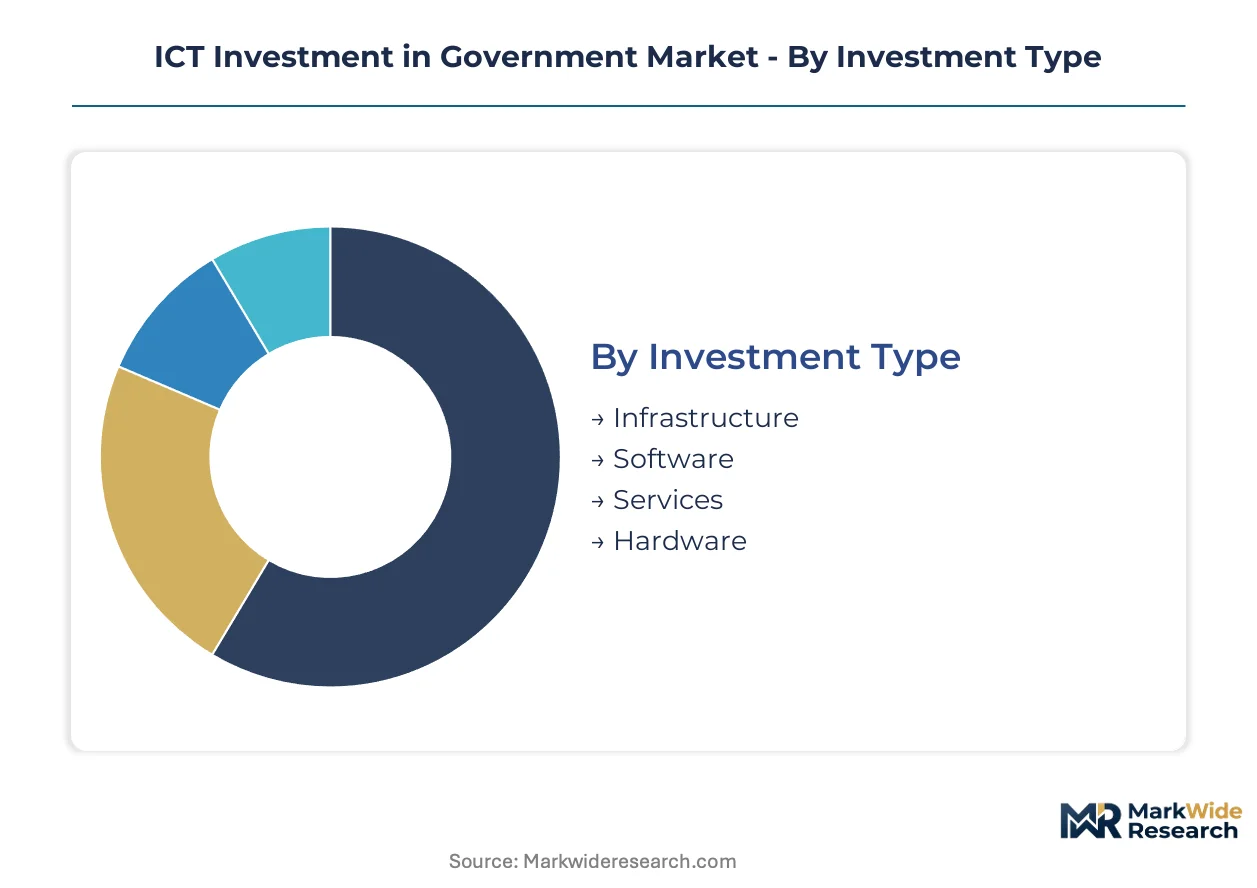
ICT procurement in government splits across investment modalities, operational applications, institutional end-users, and underlying technology stacks. Each dimension carries distinct compliance burdens and vendor qualification requirements that reshape competitive positioning.
Investment Type:
Mature capital-heavy segments coexist with emerging consumption-based alternatives across the procurement landscape.
- Infrastructure:Data center construction, network backbone modernization, and sovereign cloud facilities absorb the largest absolute budget allocations. Germany's federal digitalization programs and India's national cloud build-out channel substantial capital into domestically sited server farms and edge computing nodes, driven by data localization mandates that override cost optimization priorities.
- Software:Subscription-based platforms for enterprise resource planning, constituent relationship management, and specialized regulatory workflows command expanding recurring revenue pools. The EU AI Act's risk classification system now embeds compliance tooling and audit trail capabilities as mandatory procurement deliverables for algorithmic decision systems.
- Services:Systems integration, managed security operations, and compliance consulting fill capability gaps where cleared personnel shortages constrain in-house deployment velocity.
- Hardware:Confidential computing-enabled processors and quantum-safe encryption modules represent premature upgrade cycles in classified environments.
Infrastructure retains volume leadership; Software holds the steepest expansion curve.
Usage Category:
Security-centric applications attract premium pricing while administrative digitization drives volume scale.
- Cybersecurity:Zero-trust architecture deployment, threat intelligence platforms, and post-quantum cryptography migration absorb disproportionate budget growth. Defense agencies across NATO member states mandate encrypted processing capabilities ahead of commercial availability, compressing procurement timelines for next-generation security stacks.
- Cloud Computing:FedRAMP-authorized and EUCS-certified sovereign cloud instances displace legacy on-premise infrastructure. Multi-jurisdictional vendors must replicate infrastructure within national boundaries, accepting efficiency penalties for jurisdictional control over data residency and encryption key management.
- Data Management:Interoperable e-government platforms and cross-agency data lakes enable predictive policy analytics while satisfying GDPR and sector-specific retention requirements.
- E-Governance:Citizen-facing service portals, digital identity systems, and automated licensing workflows reduce human touchpoint costs while improving 24-hour availability metrics.
Cybersecurity captures the highest marginal investment growth; E-Governance delivers the broadest citizen-facing deployment base.
Client Sector:
Institutional scale and security classification tier determine procurement sophistication and vendor qualification barriers.
- Defense:Classified networks and intelligence workflows impose the most stringent vendor vetting, requiring security-cleared personnel and air-gapped or confidential computing architectures. Quantum-safe encryption mandates in Germany, France, and the United Kingdom accelerate premature infrastructure refresh cycles.
- Public Agencies:Federal civilian departments balance modernization imperatives against legacy system integration debt, with COBOL-based entitlement systems consuming substantial translation-layer budgets before new capabilities deploy.
- Municipalities:Local government digitization concentrates in interoperable platforms that neighboring jurisdictions adopt through bilateral procurement agreements.
- Education Departments:Student data protection requirements and remote learning infrastructure sustain steady demand for compliant cloud storage and collaboration platforms.
Defense commands the highest per-contract value; Public Agencies generate the aggregate procurement volume.
Technology Focus:
Established analytics platforms anchor current spending while experimental architectures capture exploratory budgets.
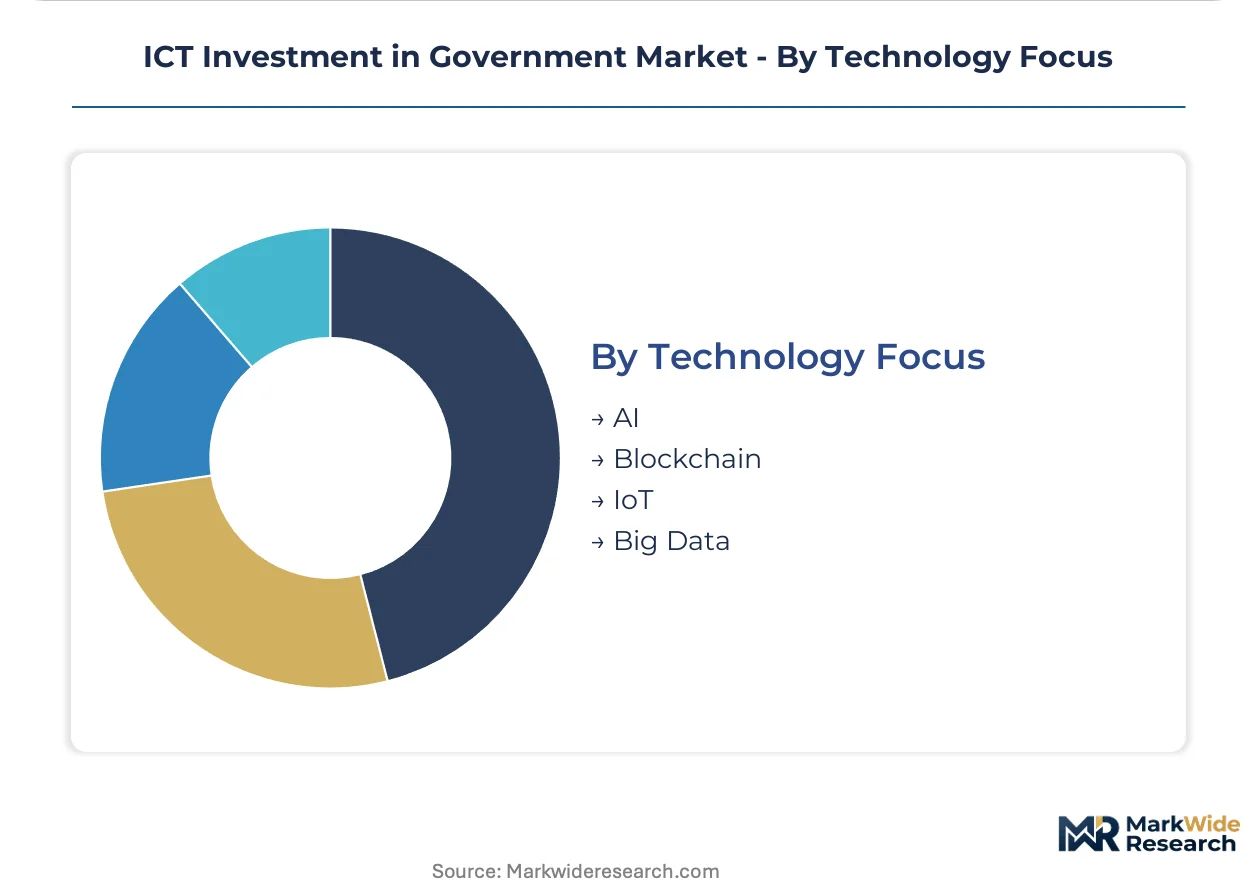
- AI:Machine learning models for predictive case routing, fraud detection, and benefits eligibility require embedded explainability tooling and bias testing documentation under EU AI Act mandates. Law enforcement and judicial applications face deployment freezes pending conformity assessment completion.
- Big Data:Cross-agency analytics platforms and real-time policy dashboards leverage existing data lake investments with lower regulatory friction than algorithmic decision systems.
- IoT:Smart city sensor networks and infrastructure monitoring systems expand at municipal level, constrained by fragmented procurement authority and cybersecurity certification gaps.
- Blockchain:Distributed ledger pilots for credential verification and procurement transparency remain experimental with limited production deployment.
Big Data sustains the installed base expansion; AI climbs the fastest despite regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU's Gaia-X federated data infrastructure underwrites Europe's sovereign cloud build-out, channeling public investment into nationally sited server farms that guarantee jurisdictional control over encryption key management and data residency.
United States
FedRAMP-authorized cloud regions absorb the bulk of federal civilian migration budgets, with defense agencies mandating air-gapped or confidential computing architectures for classified workloads. The US Federal Risk and Authorization Management Program compresses vendor onboarding from 18 months to under 6 months for pre-authorized platforms. The National Capital Region concentrates secure cloud procurement, with Virginia's data center corridor hosting hyperscale government-dedicated facilities.
Germany
Federal digitalization programs channel investment into interoperable e-government platforms that neighboring Austria, Switzerland, and Benelux states adopt through bilateral procurement agreements. The EU AI Act's risk-based classification system mandates auditable governance tooling for public sector algorithmic systems. Berlin and Munich anchor quantum-safe cryptography migration, with defense agencies mandating post-quantum encryption standards ahead of commercial availability.
India
MeitY's data localization guidelines redirect foreign vendor strategies toward in-country infrastructure partnerships, narrowing the capability gap between legacy state data centers and hyperscale alternatives. The Ministry of Electronics and Information Technology imposes cloud computing guidelines that require domestic data residency for sensitive government workloads. Bengaluru and Hyderabad concentrate national cloud build-out, with state-level digitalization programs channeling investment into edge computing nodes.
United Kingdom
Intelligence workflows impose stringent vendor vetting requirements, with GCHQ's National Cyber Security Centre certifying cloud platforms for classified processing. The UK Cyber Security Council mandates professional standards for security-cleared cloud architects that exceed fixed government salary bands. London and Cheltenham anchor defense and intelligence procurement, with quantum-safe encryption mandates accelerating premature infrastructure refresh cycles.
France
ANSSI-certified sovereign cloud offerings compete with EUCS-certified alternatives for defense and civilian agency contracts, with data residency requirements overriding cost optimization priorities. The French national cybersecurity agency imposes strict certification timelines that delay deployment regardless of technical readiness. Paris and Toulouse concentrate defense cloud procurement, with confidential computing pilots enabling controlled migration of classified workloads.
ICT Investment in Government Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical anchoring. The vendor base concentrates around three tiers: hyperscale cloud providers with government-dedicated regions, systems integrators with security-cleared personnel pipelines, and specialized cybersecurity vendors with quantum-safe encryption portfolios. Dominant competitive moves include geographic replication of sovereign infrastructure to satisfy data localization mandates and strategic partnerships with domestic carriers to meet national certification requirements.
Within the hyperscale platform tier, Microsoft Corporation and Amazon Web Services anchor multi-continental government cloud offerings, each replicating infrastructure within jurisdictional boundaries to satisfy FedRAMP and EUCS requirements. IBM Corporation occupies a position bridging hybrid cloud integration with defense-grade security architectures. These three exemplify the competitive imperative to trade centralized efficiency for jurisdictional control, accepting 15-30% cost premiums to guarantee sovereign data governance.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| Cisco Systems |
| Accenture |
| SAP SE |
| Hewlett Packard Enterprise |
| Amazon Web Services |
| Capgemini SE |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud concentration in the United States anchors margin capture downstream in European and Asian procurement markets, where data localization mandates force buyers to absorb 15-30% premiums for jurisdictional control over encryption key management.
Pricing Analysis
FedRAMP authorization dictates the pricing tier structure across US federal procurement, separating pre-authorized platforms from provisional pathways that carry compliance risk premiums. Three-tier pricing structure across premium, standard, and economy levels aligns with security classification tiers, with confidential computing-enabled workloads commanding the highest bracket. Cost compression in standard-tier SaaS subscriptions is intensifying because finance ministries are consolidating vendor relationships through centralized marketplaces. Municipal governments exhibit the greatest price sensitivity, while defense agencies prioritize sovereign control over unit economics.
Supply Chain Analysis
Extended payment terms from systems integrators to cleared personnel agencies are stretching working capital cycles across multi-year government contracts. Hardware supply concentrates in Taiwan, South Korea, and the United States for confidential computing processors and quantum-safe encryption modules. Software licensing draws from Ireland, Singapore, and domestic data centers under data residency requirements. Single-source vulnerability in security-cleared talent pipelines poses continuity risk. Distribution runs through prime contractor networks with subcontractor tiers for specialized compliance consulting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's interoperable e-government platforms are creating network effects that reward early ecosystem participation, with cross-border service integration locking in neighboring jurisdictions through bilateral procurement dependencies.
For Market Incumbents: Entrench position by deepening sovereign cloud infrastructure replication in India and EU member states ahead of accelerating data localization mandates. Acquire security-cleared talent pipelines to offset personnel vetting backlogs that delay competitor deployments. FedRAMP authorization expansion compresses onboarding windows for pre-authorized vendors, creating defensive moats against provisional challengers. For New Entrants and Emerging Players: Build out specialized compliance tooling for EU AI Act risk classification systems, where auditable governance capabilities face supply shortages against deployment deadlines. Municipal e-government platforms in Central and Eastern Europe offer the most penetrable entry point, with bilateral adoption patterns from German reference architectures lowering sales cycle friction. Partner with domestic carriers to satisfy national certification requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed systems integrators holding security-cleared personnel pipelines and established prime contractor relationships. Long-term viability hinges on quantum-safe cryptography migration mandates that will refresh classified infrastructure regardless of commercial readiness. Watch for deployment freezes in law enforcement AI applications as conformity assessment bottlenecks create distressed capability gaps.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Replication | EUCS certification in France and Germany satisfies data residency requirements for defense procurement. |
| Quantum-Safe Cryptography Migration | Berlin and Munich defense agencies mandate post-quantum standards ahead of commercial availability. |
| AI Governance Tooling Development | Embedded explainability capabilities satisfy EU AI Act audit trail requirements for public sector algorithms. |
| Security-Cleared Talent Acquisition | GCHQ-certified personnel pipelines accelerate UK intelligence workflow deployments regardless of technical readiness. |
| Interoperable Platform Partnership | Bilateral agreements with German federal programs create reference architecture adoption in Austria and Switzerland. |
Research Approach
A standing panel of government CTOs, procurement officers, FedRAMP authorization leads, and systems integration architects provided ongoing calibration against operating reality. Primary interviews combined with secondary validation from SEC filings of hyperscale cloud providers, MeitY cloud computing guidelines, EU AI Act implementation documents, and NATO procurement databases. Bottom-up deployment tracking and top-down budget appropriation analysis triangulated segment-level estimates.
Scenario-bracketing around regulatory implementation timelines and sovereign cloud build-out velocities bounded the projection range. Segmentation dimensions modeled include investment type, usage category, client sector, and technology focus across the analysis window. CAGRs derived from deployment velocity curves weighted by compliance pipeline congestion. Forecast inputs incorporated security clearance backlogs, legacy system integration debt ratios, and confidential computing hardware availability.
The forecast holds incumbent behavior within observed patterns; aggressive moves by domestic cloud providers in India or Gaia-X consortium members would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
Digital Shelf Market
Digital Solutions
Video Management System Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Mobile Campaign Management Platform Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Digital Metronome Market
Digital Solutions
Global Interactive Whiteboard (IWB) Market
Digital Solutions
Service Mesh Market
Digital Solutions
Global DDI Market
Digital Solutions
Queue Management System (QMS) Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Online Voting System Market