
 Queue Management System (QMS) Market | 2026-2036
Queue Management System (QMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Queue Management System (QMS) Market Analytics
Healthcare administrators is unwinding decades of reliance on retail-first queue architectures. Qmatic leverages its Nordic engineering heritage to sustain dominance in hospital patient-journey orchestration across Northern Europe. Wavetec anchors its competitive position through captive manufacturing of LED ticketing hardware and signage systems in the Middle East. QLess differentiates by specializing in SMS-first virtual queuing for municipal service bureaus in North American metropolitan clusters.
A Queue Management System orchestrates customer or patient flow through algorithmic sequencing, real-time status broadcasting, and service-point routing, typically integrating touchscreen kiosks, digital signage, and mobile notification gateways to minimize perceived wait duration and maximize throughput per service agent. Cloud-based deployments now lead technology adoption due to lower capital barriers and API extensibility into CRM and workforce management platforms, while hybrid systems represent the fastest-growing product configuration as institutions phase out legacy on-premise servers without surrendering local data custody. Mobile apps capture concentrated margin pools in retail and banking segments where brand-owned applications already command habitual user engagement.
FDA cybersecurity guidance for networked healthcare devices shapes product development roadmaps for hospital-grade QMS vendors, while HIPAA compliance requirements dictate encryption standards for patient-identifiable queue data in US installations. GDPR data-localization obligations in Europe compel cloud providers to maintain regional server infrastructure, adding operational complexity for vendors with centralized US or Asian data architectures. Stakeholders must monitor evolving interoperability mandates from national health IT authorities as these regulations will determine which platform architectures achieve sustainable market access across regulated end-use environments.
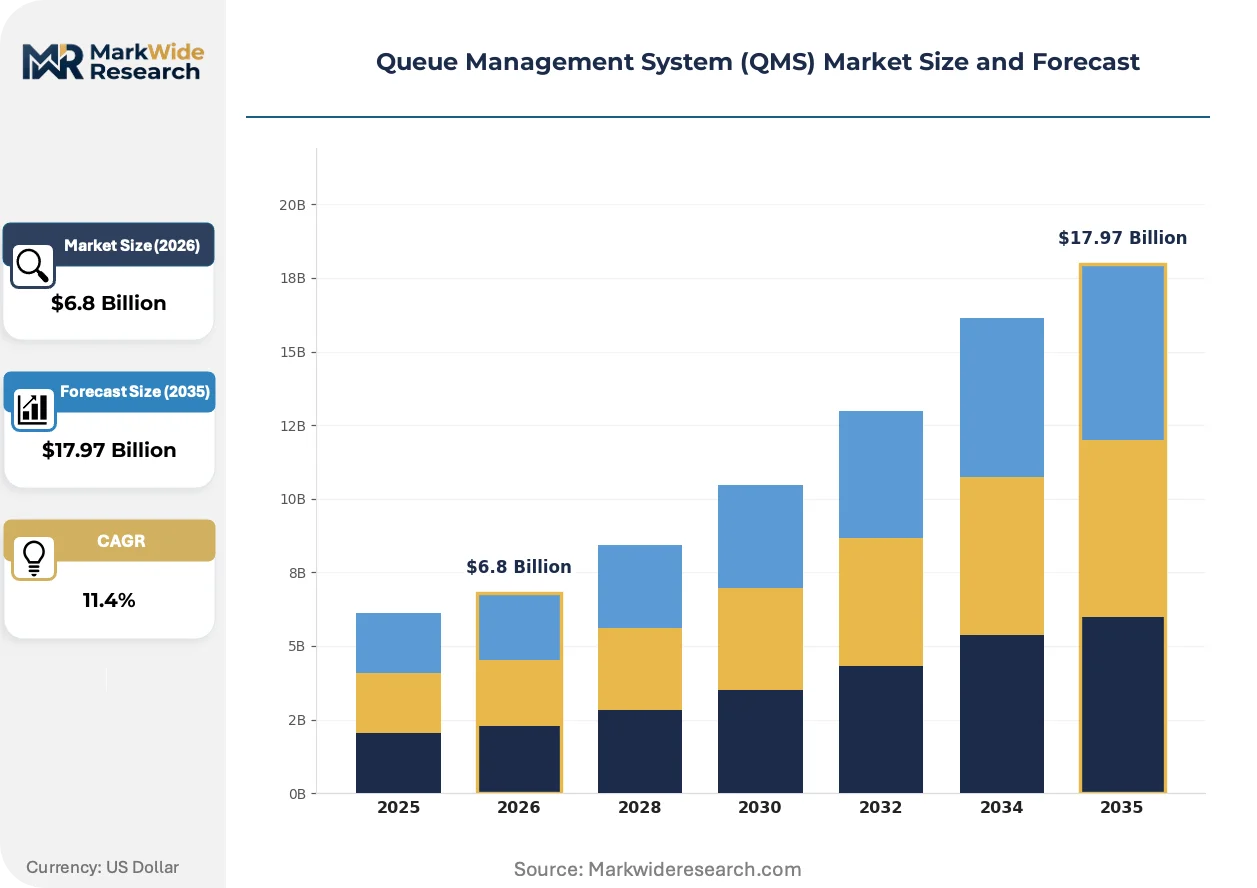
Market Dynamics
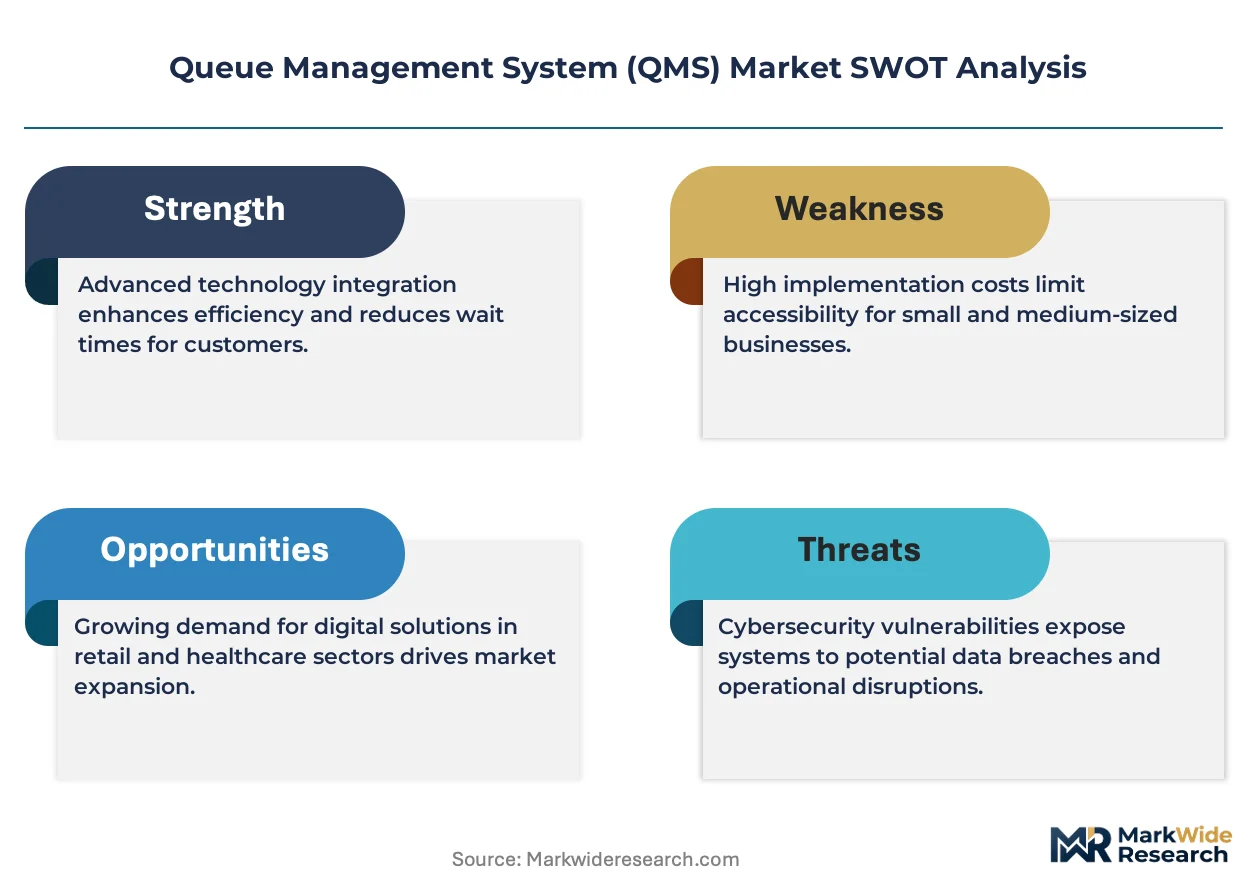
Cloud-native architectures are compressing deployment timelines from quarters to weeks, forcing legacy on-premise vendors to reengineer data sovereignty features or cede municipal and hospital contracts to API-first competitors.
Growth Catalysts
- HIPAA-mandated encryption:Healthcare providers in the United States must replace legacy ticketing with compliant digital platforms, creating replacement demand across hospital networks.
- LED hardware manufacturing clusters:Captive production of digital signage and kiosk components in the Middle East reduces unit costs for government service bureaus modernizing citizen-facing infrastructure.
- SMS notification infrastructure:Municipal service departments in North American metropolitan areas deploy virtual queuing to reduce physical footprint and labor costs at permit and licensing counters.
Market Restraints
- Semiconductor input volatility:Touchscreen controller and LED driver chip supply concentrates in East Asian foundries, exposing hardware vendors to allocation risk and price spikes.
- GDPR data-localization mandates:European cloud deployments require regional server infrastructure, adding operational complexity for vendors with centralized US or Asian data architectures.
- Legacy system integration friction:Hospital IT environments retain decades-old patient record systems with non-standard APIs, extending implementation timelines and professional services costs.
Strategic Opportunities
- Brazilian public sector modernization:Federal and state governments are digitizing service delivery infrastructure, creating procurement windows for queue orchestration platforms with Portuguese-language interfaces.
- API convergence with workforce management:Real-time queue data integration into shift-scheduling software creates bundled value propositions for retail and banking chains.
- India's Smart Cities Mission:Urban local bodies receive central funding for citizen service centers, specifying digital queue systems as core infrastructure components.
Industry Challenges
- Interoperability certification timelines:National health IT authorities in multiple geographies issue evolving data exchange standards, forcing vendors to maintain parallel compliance tracks.
- Cybersecurity skill scarcity:FDA guidance for networked healthcare devices requires specialized firmware and network security expertise that outstrips available talent pools.
- Hybrid deployment complexity:Institutions phasing out on-premise servers demand seamless cloud migration without service interruption, stretching implementation engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Queue Management System (QMS) Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Queuing, Physical Queuing, Hybrid Systems, Mobile Apps Technology: Cloud-Based, On-Premise, SMS Notifications, Mobile Check-In End User: Retail Stores, Hospitals, Banks, Government Offices Application: Check-In Management, Appointment Scheduling, Customer Flow Control, Staff Management |
| Companies Covered | Qminder, WaitWell, Qmatic, Tensator, NEMO-Q, Wavetec, Qtrac, Verint, QLess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Queue Management System (QMS) Market Evolving Landscape
Algorithmic routing engines and biometric identification are redrawing competitive boundaries between hardware-centric and software-native vendors, compressing margins in commoditized signage while concentrating value in data analytics layers.
Edge computing nodes embedded within queue kiosks are fragmenting traditional cloud-dependent architectures. Hospital networks and high-throughput retail chains deploy localized processing to reduce latency for real-time patient and customer routing decisions. This distributed topology is fragmenting vendor competitive sets, separating specialists with firmware depth from pure-play SaaS providers lacking hardware integration capabilities.
GDPR enforcement actions by CNIL and fellow European regulators are tightening consent requirements for biometric queue data collection. Vendors must now implement granular opt-in workflows and automated deletion schedules, raising engineering costs for platforms serving European healthcare and government clients. France and Germany lead enforcement stringency, with fines compelling architectural redesigns for non-compliant legacy installations.
Subscription pricing for queue analytics is displacing perpetual licensing in municipal procurement. City service bureaus prefer operational expenditure models that align software costs with seasonal demand fluctuation, particularly for tax and permit windows. This preference shift is most visible in North American metropolitan clusters where finance departments mandate cloud-first vendor selection criteria.
Queue Management System (QMS) Market Segmentation
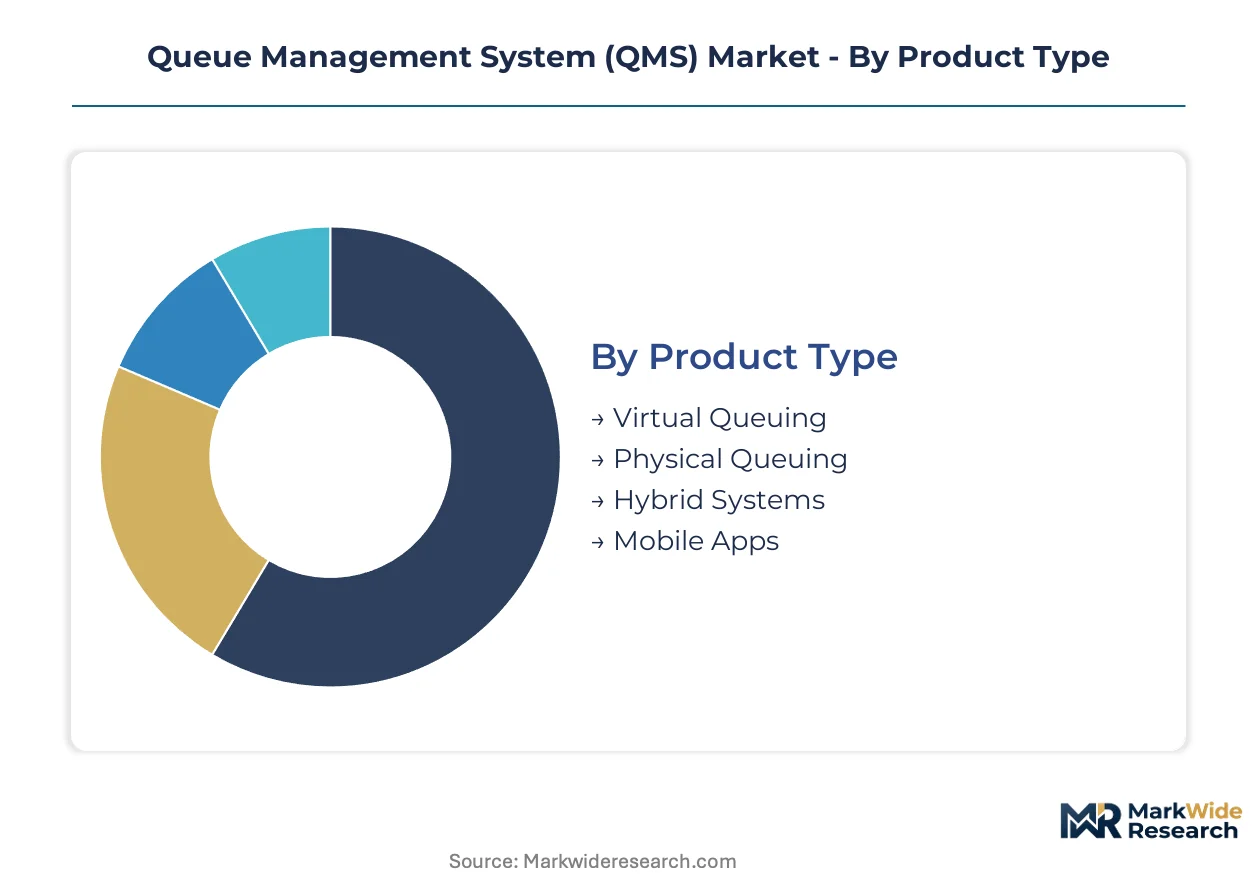
Queue Management System vendors structure product portfolios around deployment topology, connectivity architecture, and operational workflow integration. Segmentation choices determine compliance burden, capital intensity, and recurring revenue potential across healthcare, retail, and public sector procurement cycles.
Product Type:
FDA cybersecurity guidance and HIPAA encryption mandates favor architectures with localized data custody, while GDPR data-localization obligations in Europe compel regional server infrastructure for cloud-dependent formats.
- Virtual Queuing:SMS-first and app-based remote check-in eliminates physical ticketing infrastructure. Municipal service bureaus in North American metropolitan clusters deploy this format to reduce counter footprint and labor costs during tax and permit windows.
- Physical Queuing:Touchscreen kiosks and LED ticketing hardware with embedded edge computing nodes process routing decisions locally. Hospital networks favor this architecture for latency-sensitive patient flow where FDA cybersecurity guidance for networked devices demands firmware-level controls.
- Hybrid Systems:Combines on-premise data sovereignty with cloud analytics layers. Institutions phasing out legacy servers without surrendering local custody drive fastest adoption as compliance requirements harden across healthcare and government verticals.
- Mobile Apps:Brand-owned applications with biometric check-in and push notification gateways. Retail and banking chains with habitual user engagement capture concentrated margin pools through subscription analytics pricing.
Physical queuing handles the majority of throughput in regulated healthcare environments; hybrid systems are expanding most quickly as institutions navigate cloud migration without service interruption.
Technology:
Deployment timelines compress from quarters to weeks as API extensibility into CRM and workforce management platforms becomes a procurement evaluation criterion.
- Cloud-Based:Lower capital barriers and automatic software updates attract municipal and mid-market retail procurement. European installations require regional server infrastructure to satisfy GDPR data-localization obligations, adding operational complexity for vendors with centralized US architectures.
- On-Premise:Legacy server installations with full data custody retained within institutional firewalls. Hospital IT environments with decades-old patient record systems extend implementation timelines due to non-standard API integration friction.
- SMS Notifications:Text-based status broadcasting reaches feature-phone users and minimizes digital literacy barriers. Government service bureaus in India and Brazil prioritize this channel for citizen-facing infrastructure modernization.
- Mobile Check-In:Geofenced arrival detection and queue position tracking through smartphone applications. High-throughput retail chains deploy this technology to maximize throughput per service agent during peak demand windows.
Cloud-based deployments dominate new procurement volumes; mobile check-in is gaining share fastest in retail and banking segments with established app ecosystems.
End User:
Compliance requirements and procurement funding mechanisms create divergent technology preferences across verticals.
- Retail Stores:Seasonal demand fluctuation drives preference for operational expenditure models. Finance departments in North American metropolitan clusters mandate cloud-first vendor selection criteria with subscription pricing aligned to transaction volumes.
- Hospitals:HIPAA-mandated encryption and FDA cybersecurity guidance dictate product development roadmaps. Replacement demand accelerates as US healthcare networks unwind decades of reliance on retail-first queue architectures.
- Banks:Integration with existing CRM platforms and workforce management software creates bundled value propositions. Real-time queue data feeds into shift-scheduling algorithms to optimize teller allocation.
- Government Offices:Central funding mechanisms in India's Smart Cities Mission specify digital queue systems as core infrastructure. Brazilian federal and state modernization programs create procurement windows for platforms with Portuguese-language interfaces.
Hospitals generate the highest compliance-driven replacement cycle; government offices are climbing the fastest on share as public sector digitization accelerates in emerging economies.
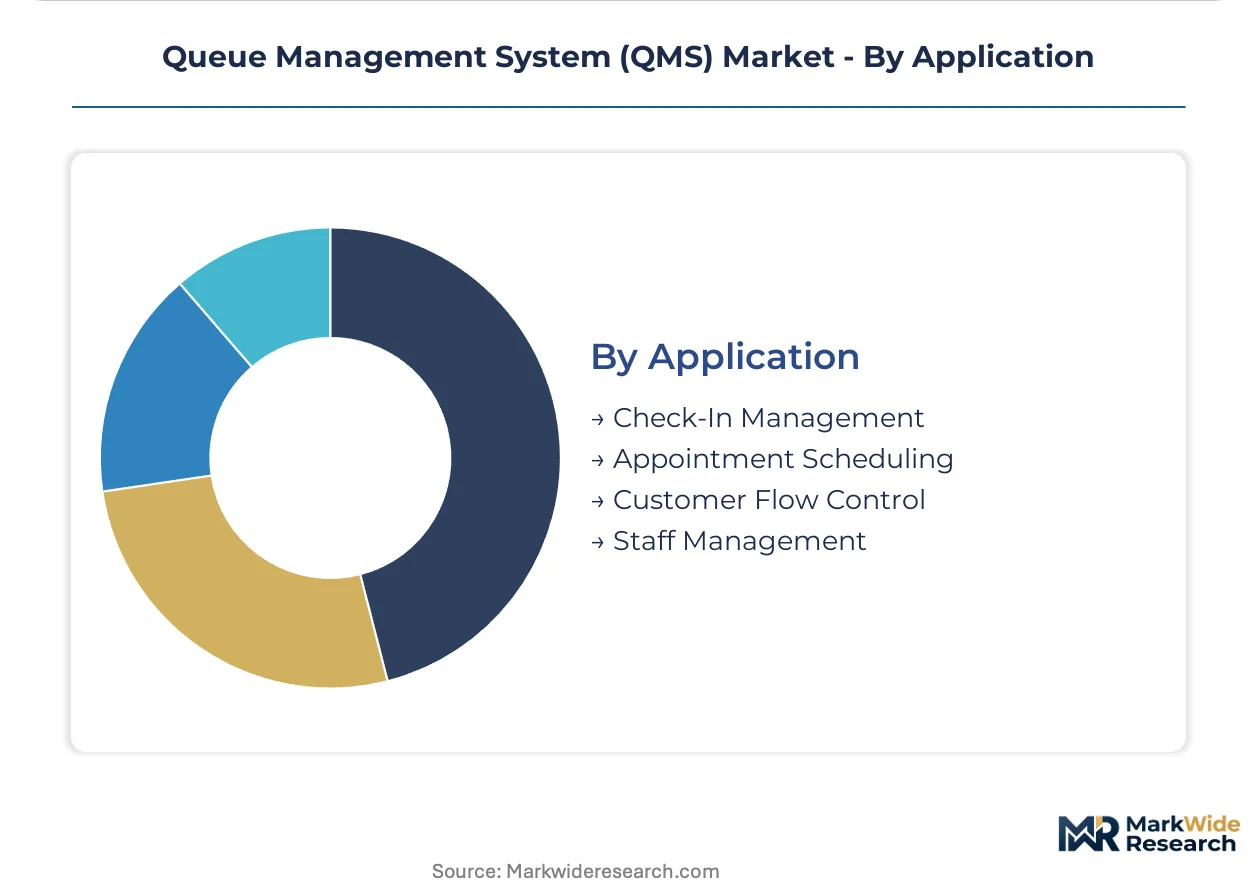
Application:
Workflow orchestration depth determines whether implementations reduce perceived wait duration or achieve full operational transformation.
- Check-In Management:Initial patient or customer capture through kiosk, SMS, or biometric identification. CNIL and European regulators enforce granular opt-in workflows and automated deletion schedules for biometric data collection.
- Appointment Scheduling:Calendar integration with predictive no-show algorithms and automated rescheduling. Hospital patient-journey orchestration platforms leverage Nordic engineering heritage for deterministic routing precision.
- Customer Flow Control:Real-time status broadcasting and service-point routing to minimize perceived wait duration. LED hardware manufacturing clusters in the Middle East reduce unit costs for high-volume government deployments.
- Staff Management:Queue depth triggers integrated into shift-scheduling software for labor optimization. Retail and banking chains bundle this capability with workforce management platforms to justify premium pricing tiers.
Check-in management anchors the majority of installed base; staff management is the fastest mover on share as workforce optimization becomes a procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware manufacturing clusters concentrate in the Middle East and South Asia, while software development gravity pulls toward Northern Europe and North American metropolitan corridors. Cloud infrastructure deployment faces divergent data sovereignty requirements across jurisdictions.
United States
HIPAA-mandated encryption drives healthcare provider replacement of legacy ticketing systems across hospital networks. FDA cybersecurity guidance for networked devices shapes vendor product roadmaps. New York and Boston metropolitan clusters anchor municipal virtual queuing deployments for service bureaus.
Germany
GDPR data-localization obligations compel cloud providers to maintain regional server infrastructure for European installations. CNIL and German data protection authorities enforce granular consent requirements for biometric queue data. Bavaria and North Rhine-Westphalia concentrate hospital IT procurement for patient-journey orchestration platforms.
India
Central funding through the Smart Cities Mission specifies digital queue systems as core infrastructure for urban local bodies. TRAI regulations shape SMS notification infrastructure deployment. Maharashtra and Karnataka lead citizen service center modernization in Mumbai and Bangalore metropolitan regions.
Brazil
Federal and state government digitization programs create procurement windows for queue orchestration platforms with Portuguese-language interfaces. ANVISA oversight applies to healthcare device integrations. São Paulo and Rio de Janeiro anchor public sector modernization for service delivery infrastructure.
United Arab Emirates
Government service bureau modernization drives demand for LED ticketing hardware and digital signage systems. MOHAP regulations influence healthcare facility queue management specifications. Dubai and Abu Dhabi concentrate captive manufacturing clusters for kiosk components serving Middle Eastern markets.
Queue Management System (QMS) Market Competitive Landscape
Concentration sits with Nordic engineering specialists and Middle Eastern hardware fabricators competing against North American SaaS-native platforms. The vendor base spans three distinct tiers: legacy on-premise system integrators, cloud-first API platforms, and vertically integrated signage manufacturers. Strategic moves center on hybrid deployment capabilities and workforce management API convergence.
Among Nordic engineering heritage platforms, Qmatic exemplifies hospital patient-journey orchestration specialization. Wavetec anchors the Middle Eastern hardware tier with captive LED manufacturing positioning. QLess represents the North American virtual queuing archetype with SMS-first municipal deployment focus.
| Leading Market Players |
|---|
| Qminder |
| WaitWell |
| Qmatic |
| Tensator |
| NEMO-Q |
| Wavetec |
| Qtrac |
| Verint |
| QLess |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with Middle Eastern LED manufacturers lock in hardware unit costs for government service bureaus while insulating procurement officers from semiconductor foundry volatility. These arrangements tether pricing visibility to captive production clusters in Dubai and Abu Dhabi, creating divergent cost structures between hardware-centric and software-native vendor tiers.
Pricing Analysis
Volume-discount tiering structures separate enterprise hospital networks from municipal service bureaus and mid-market retail chains. SaaS subscription models with per-location pricing dominate cloud-native deployments, while project-based licensing persists for hybrid systems requiring on-premise data sovereignty. HIPAA certification tiers command premiums over standard encryption offerings. Cost compression in LED hardware intensifies as Wavetec's captive manufacturing scales, eroding margins for third-party signage integrators. Municipal procurement teams exhibit highest price sensitivity due to seasonal demand fluctuation and budget cycle constraints.
Supply Chain Analysis
Strait of Hormuz transit underwrites kiosk component flows from UAE manufacturing clusters to Saudi and Egyptian government clients. Taiwan and South Korea supply touchscreen controllers and LED driver chips. Aluminum extrusions for kiosk enclosures draw from Chinese smelters. Single-source vulnerability concentrates in East Asian semiconductor foundries, exposing hardware vendors to allocation risk during demand spikes. Distribution runs through systems integrators with regional service capabilities rather than direct vendor-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment topologies creates specialized niches as institutions phase out legacy servers without surrendering local data custody. Compliance divergence between HIPAA-mandated healthcare encryption and GDPR localization obligations splits vendor addressable markets.
For Market Incumbents: Consolidate hybrid deployment engineering capabilities to defend municipal and hospital contracts against API-first competitors. Acquire edge computing firmware specialists to counter pure-play SaaS platforms lacking hardware integration depth. Vertical integration into LED signage manufacturing, following Wavetec's captive production model, secures margin control against semiconductor input volatility. For New Entrants and Emerging Players: Anchor in Brazilian federal and state digitization programs where Portuguese-language interfaces create procurement barriers for incumbent vendors. Target India's Smart Cities Mission urban local bodies receiving central infrastructure funding. Deploy SMS-first virtual queuing to bypass app ecosystem dependencies in emerging market government offices. For Investors and Strategic Acquirers: Nordic engineering heritage platforms with hospital patient-journey orchestration specialization offer durable competitive moats as FDA cybersecurity guidance hardens. Cloud-native vendors with workforce management API convergence demonstrate clearest expansion vectors. Monitor ANVISA enforcement patterns in Brazilian healthcare as inflection indicator for regional compliance complexity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Capability Buildout | Captures institutional cloud migration demand without service interruption across hospital networks. |
| Workforce Management API Integration | Creates bundled value propositions for retail and banking chains optimizing labor allocation. |
| Regional Server Infrastructure Expansion | Satisfies GDPR data-localization mandates for European healthcare and government procurement. |
| Edge Computing Firmware Development | Enables latency-sensitive patient routing decisions in FDA-regulated hospital environments. |
| Portuguese-Language Platform Localization | Unlocks Brazilian federal and state government digitization procurement windows. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital IT directors, municipal procurement officers, retail operations executives, and queue system integration specialists. Secondary validation drew from FDA cybersecurity guidance documents, HIPAA compliance advisories, GPO contract databases, and Smart Cities Mission infrastructure specifications. Bottom-up installation tracking across deployment topologies triangulated against top-down vendor revenue segmentation.
Across the analysis window, forecasts modeled deployment topology, end-use vertical, technology architecture, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation with macroeconomic healthcare IT spending indicators. Inputs included hospital capital expenditure cycles, municipal budget authorization patterns, and semiconductor foundry capacity utilization trends.
Material uncertainties — semiconductor allocation disruptions, evolving interoperability mandates from national health IT authorities, and GDPR enforcement escalation — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as biometric consent requirements and edge computing adoption curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America API Management Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Australia Cloud OSS BSS Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Open-Source Intelligence (OSINT) Market
Digital Solutions
Lecture Capture Systems Market
Digital Solutions
Cloud-Based POS Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Electronic Discovery Market
Digital Solutions
Latin America IT Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Global Service Integration and Management Market
Digital Solutions
Marketing Automation Market
Digital Solutions
Asia-Pacific Desktop Virtualization Market
Digital Solutions
Australia System Integration Market