
 Brazil Data Center Cooling Market | 2026-2036
Brazil Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Data Center Cooling Market Insights
Brazilian colocation providers is shifting capacity planning toward liquid-ready designs as GPU clusters exceed 30 kW per rack. Schneider Electric SE leverages its local manufacturing footprint to anchor project delivery timelines. Vertiv Group Corp. competes on thermal management software integration. Stulz GmbH specializes in precision air conditioning for financial services facilities in São Paulo state.
Data center cooling encompasses engineered systems that regulate temperature, humidity, and airflow within mission-critical IT environments, typically maintaining inlet conditions between 18°C and 27°C per ASHRAE guidelines while dissipating heat densities from 5 kW to over 50 kW per cabinet. Liquid cooling and immersion cooling segments capture premium margins as hyperscale operators deploy direct-to-chip cold plates for NVIDIA H100 clusters. Air cooling retains volume leadership in enterprise and government installations where retrofit economics favor incremental upgrades. CRAC units and chilled water systems dominate the solution layer, though direct expansion systems gain traction in edge locations with constrained mechanical infrastructure.
ANVISA governs electromagnetic compatibility certification for cooling equipment with integrated control systems, while ABNT NBR standards establish minimum efficiency ratios for commercial refrigeration applied to data center contexts. The national electricity regulator ANEEL structures tariff incentives that reward facilities achieving power usage effectiveness below 1.4. Stakeholders must monitor proposed updates to Brazil's climate framework law that would mandate refrigerant phase-down timelines affecting chiller replacement cycles.
Market Dynamics
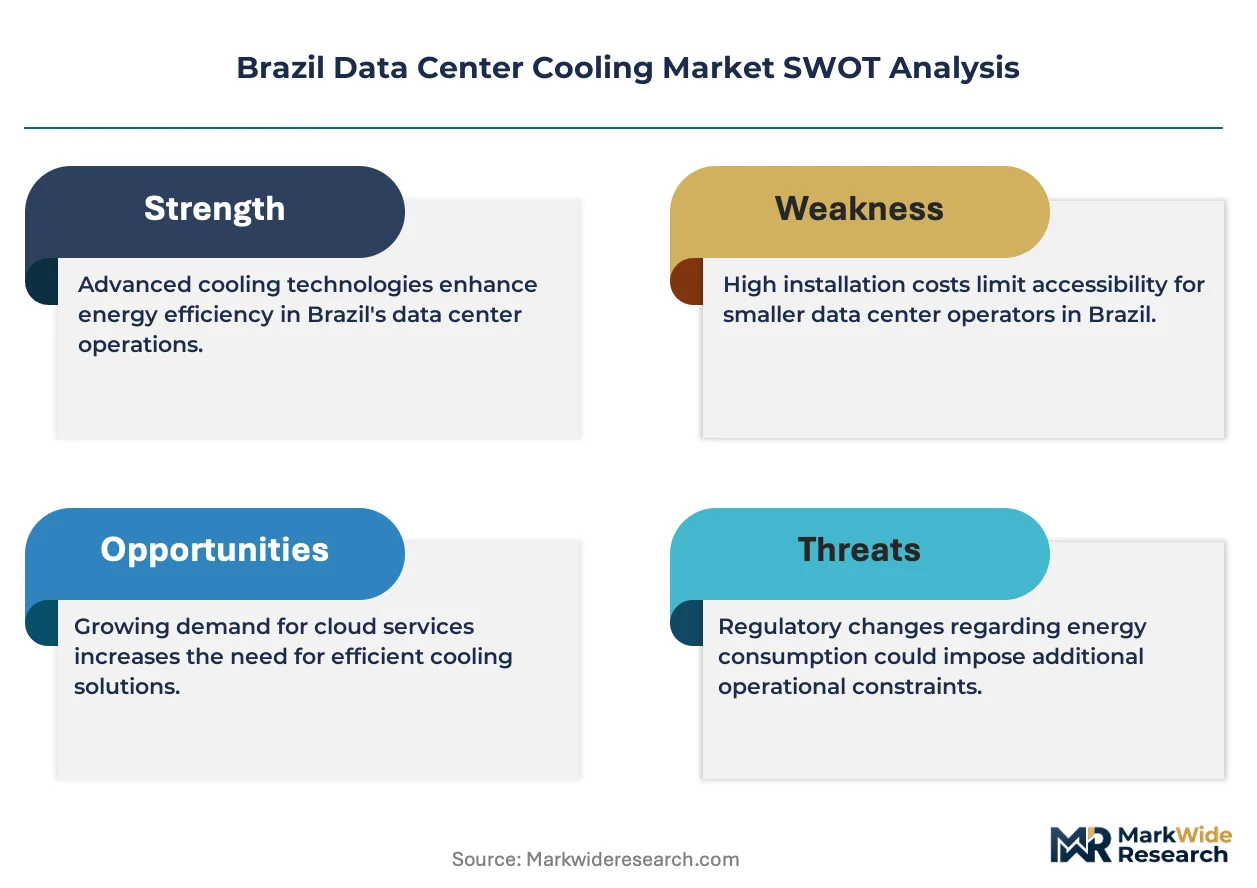
GPU rack densities exceeding 30 kW are forcing Brazilian operators to abandon legacy air-cooled architectures before depreciation cycles complete, triggering premature infrastructure refresh timelines and liquid cooling retrofit urgency.
Growth Catalysts
- ANEEL tariff incentives:Facilities achieving power usage effectiveness below 1.4 unlock preferential electricity rates, accelerating efficiency investments across São Paulo state.
- AI training clusters:Hyperscale deployment of NVIDIA H100 infrastructure demands direct-to-chip thermal management, expanding addressable market for precision cooling vendors.
- Campinas corridor concentration:São Paulo's fiber-rich sub-region attracts cloud provider buildouts, creating localized demand density for advanced cooling systems.
Market Restraints
- Copper and aluminum input volatility:Cold plate and heat exchanger fabrication costs fluctuate with commodity markets, compressing project margins for system integrators.
- Refrigerant phase-down uncertainty:Proposed updates to Brazil's climate framework law lack implementation timelines, freezing long-term chiller procurement decisions.
- Limited local dielectric fluid supply:Single-source dependency for immersion cooling liquids creates supply security risk for early adopters.
Strategic Opportunities
- Porto Maravilha edge zones:Rio de Janeiro's port redevelopment offers brownfield sites for liquid-cooled micro data centers serving financial services latency requirements.
- ABNT efficiency standard convergence:Anticipated alignment with international energy performance certifications creates first-mover advantage for pre-certified equipment suppliers.
- Direct expansion edge penetration:Distributed AI inference nodes in secondary cities require self-contained cooling without chilled water infrastructure.
Industry Challenges
- Thermal-fluid engineering talent scarcity:Local universities lack specialized curricula in two-phase heat transfer and dielectric system design, forcing vendors to import technical personnel.
- ANVISA electromagnetic compatibility certification:Integrated control system validation extends product launch timelines by four to six months versus non-certified markets.
- Legacy facility retrofit complexity:Existing raised-floor architectures constrain pipe routing for liquid cooling manifolds, requiring structural modifications that trigger building code reviews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Data Center Cooling Market |
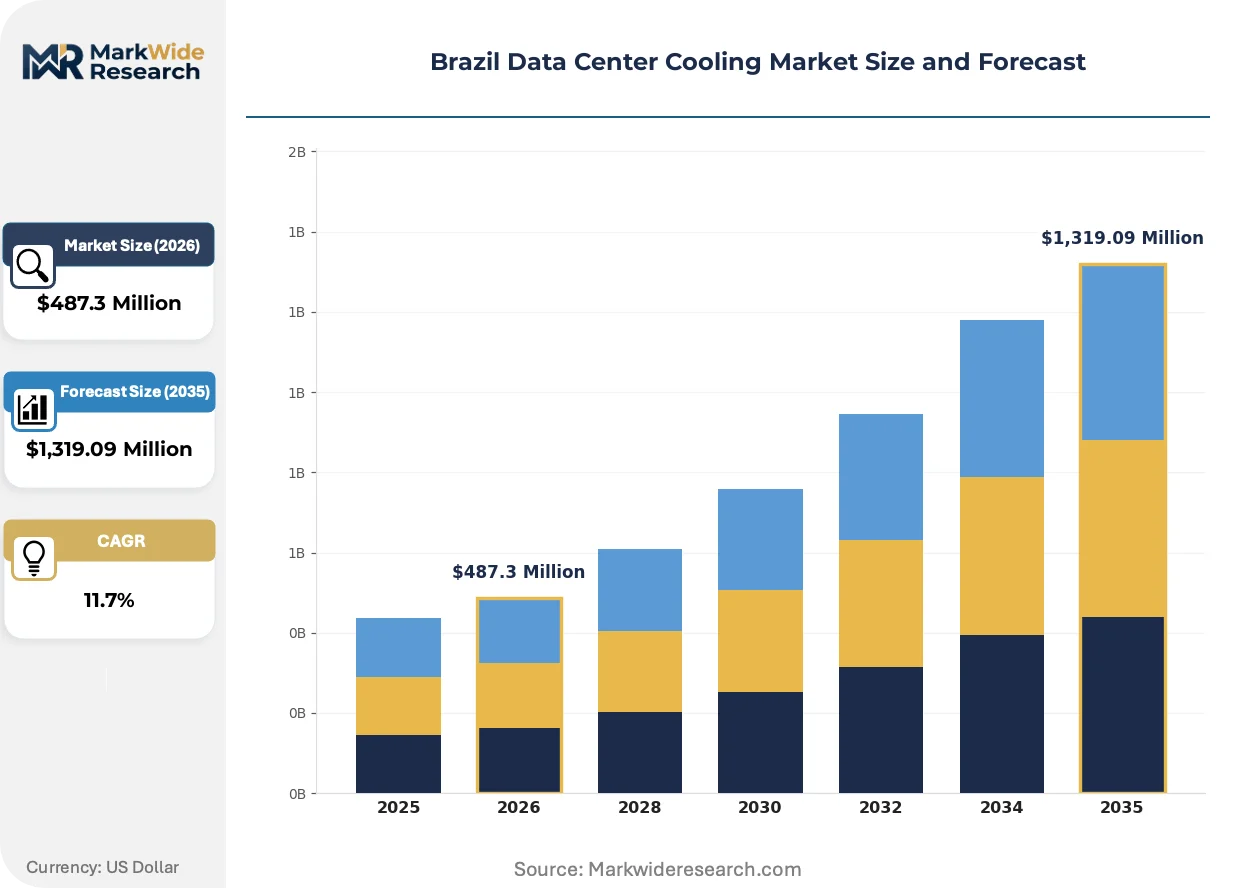
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: Air Cooling, Liquid Cooling, Immersion Cooling, Evaporative Cooling End User: IT Sector, Telecommunication, BFSI, Government Solution: Chilled Water Systems, Direct Expansion Systems, Heat Exchangers, CRAC Units Service Type: Installation, Maintenance, Consulting, Lease |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp., Stulz GmbH, Rittal GmbH & Co. KG, Mitsubishi Electric Corporation, Johnson Controls International PLC, Daikin Industries, Emerson Electric, CoolIT Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Data Center Cooling Market Trends and Innovations
Direct-to-chip liquid cooling architectures are compressing the competitive window for incumbent air-cooled suppliers while regulatory pressure on refrigerant chemistry accelerates equipment replacement cycles.
Immersion cooling using engineered dielectric fluids is electrifying thermal design strategies for GPU-intensive workloads. Hyperscale operators in São Paulo state are piloting single-phase tank systems for training clusters exceeding 50 kW per rack. This technology is electrifying vendor R&D allocation toward fluid chemistry and tank manufacturing capabilities previously absent in the regional supply base.
ANVISA's electromagnetic compatibility certification requirements for cooling equipment with integrated control systems are tightening market entry barriers. Foreign manufacturers must complete in-country testing protocols that add four to six months to product launch timelines. Domestic assembly operations gain relative advantage by leveraging existing certification relationships and local technical representation.
Hyperscale operators are consolidating vendor relationships around full-stack thermal management partnerships rather than discrete equipment procurement. Brazilian colocation providers now specify performance-based service agreements covering cooling availability and energy efficiency guarantees. This contracting evolution is most visible in São Paulo's Campinas corridor, where cloud providers negotiate ten-year operational commitments with liquid-ready infrastructure requirements.
Brazil Data Center Cooling Market Segmentation
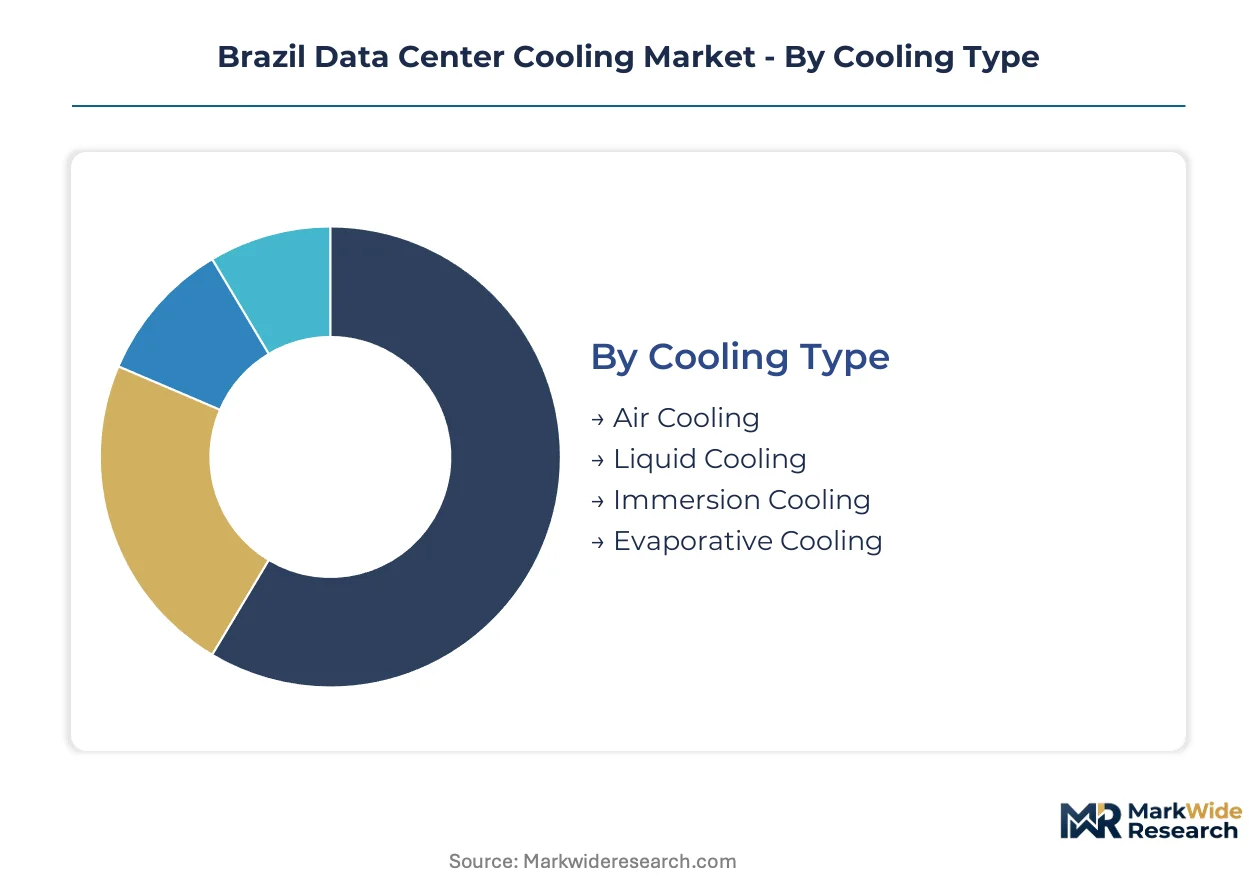
Segmentation in Brazil's data center cooling market reveals how infrastructure investments bifurcate between legacy air-cooled retrofits and liquid-ready new builds. Understanding these divisions exposes where procurement budgets concentrate and which technologies command premium pricing.
Cooling Type:
Volume leadership sits with established air architectures while premium margins flow to liquid and immersion systems addressing GPU-intensive workloads.
- Air Cooling:Conventional CRAC and raised-floor configurations dominate enterprise and government installations across São Paulo state. Campinas corridor colocation providers favor incremental air-cooled upgrades to preserve depreciation schedules while meeting ANEEL efficiency thresholds.
- Liquid Cooling:Direct-to-chip cold plate systems dissipate heat densities exceeding 30 kW per rack for NVIDIA H100 clusters. Hyperscale operators in Rio de Janeiro's Porto Maravilha zone specify liquid-ready infrastructure to minimize latency for financial services workloads.
- Immersion Cooling:Single-phase dielectric tank systems pilot at training facilities exceeding 50 kW per rack, constrained by limited local fluid supply.
- Evaporative Cooling:Adiabatic designs exploit Brazil's humidity ranges for edge locations lacking mechanical infrastructure in secondary cities.
Today's leader: Air Cooling. Tomorrow's challenger: Liquid Cooling.
End User:
Customer archetypes range from latency-sensitive financial institutions to compliance-heavy government facilities with divergent procurement cycles.
- IT Sector:Cloud service providers and colocation operators drive liquid cooling adoption as rack densities climb. São Paulo state accounts for concentrated demand from hyperscale buildouts requiring ten-year operational commitments.
- Telecommunication:Edge data centers for 5G infrastructure deploy direct expansion systems in secondary cities without chilled water infrastructure.
- BFSI:Banking and insurance facilities in Rio de Janeiro prioritize precision cooling for trading floor latency requirements.
- Government:Federal data centers face ABNT efficiency mandates that accelerate replacement of legacy refrigerant-based chillers.
IT Sector commands current procurement volume. Telecommunication infrastructure expansion offers the steepest trajectory.
Solution:
Equipment categories reflect a maturity gradient from standardized CRAC units to customized heat exchanger assemblies.
- Chilled Water Systems:Centralized plant architectures serve large campus facilities in Campinas with economies of scale for cooling capacity exceeding 10 MW.
- Direct Expansion Systems:Self-contained DX units gain traction at edge locations and retrofit-constrained facilities where mechanical room expansion is prohibited.
- Heat Exchangers:Custom plate-and-frame assemblies interface between liquid cooling loops and facility water systems, requiring thermal-fluid engineering expertise scarce in local labor markets.
- CRAC Units:Computer room air conditioning retains installed base dominance in raised-floor environments where pipe routing modifications trigger building code reviews.
Chilled Water Systems anchor large-scale deployments. Direct Expansion Systems capture edge growth.
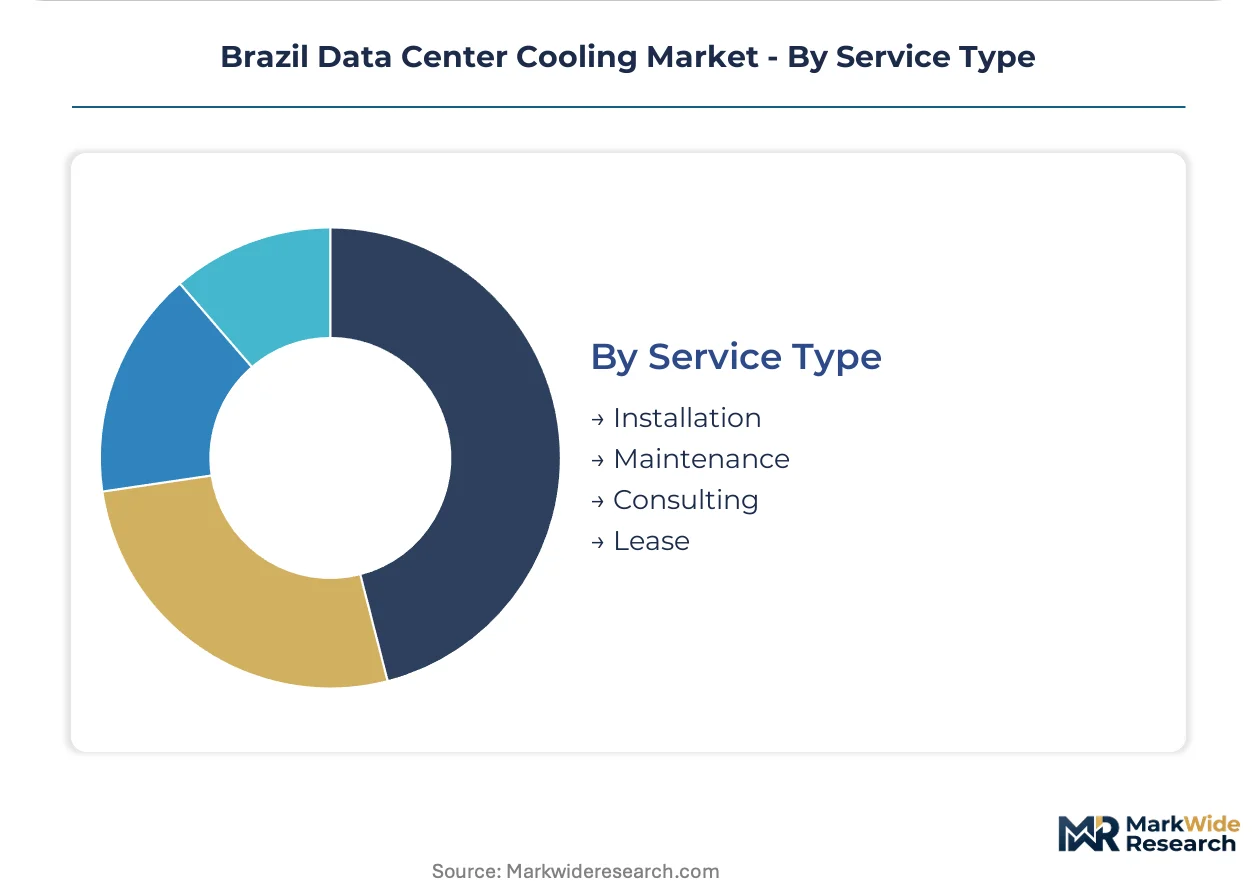
Service Type:
Revenue streams shift from discrete equipment sales toward performance-guaranteed operational contracts.
- Installation:Project execution timelines compress as ANVISA electromagnetic compatibility certification extends product launch cycles by four to six months for imported equipment.
- Maintenance:Ten-year service agreements covering cooling availability and energy efficiency guarantees consolidate vendor relationships in São Paulo's cloud provider segment.
- Consulting:Thermal design advisory addresses liquid cooling retrofits for legacy facilities where structural modifications complicate manifold routing.
- Lease:Operational expenditure models emerge for edge micro data centers in Porto Maravilha brownfield sites.
Installation generates immediate revenue. Maintenance contracts build recurring value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's data center cooling infrastructure outpaces Argentina's installed base by a factor of five, yet Chile's regulatory clarity attracts more foreign direct investment per capita than either neighbor.
São Paulo
Campinas corridor hyperscale buildouts drive liquid cooling procurement as NVIDIA H100 clusters exceed 30 kW per rack. ANEEL tariff incentives reward facilities achieving power usage effectiveness below 1.4 with preferential electricity rates. São Paulo state concentrates cloud provider demand for ten-year operational commitments with liquid-ready infrastructure specifications.
Rio de Janeiro
Porto Maravilha brownfield redevelopment attracts edge micro data centers serving financial services latency requirements. ABNT efficiency standards reshape equipment procurement criteria for banking and insurance facilities. The port zone enables submarine cable landing stations that anchor low-latency cooling infrastructure for trading floor applications.
Minas Gerais
Belo Horizonte's emerging tech corridor hosts secondary cloud regions with direct expansion cooling systems avoiding chilled water infrastructure. ANVISA electromagnetic compatibility certification extends product launch timelines for imported equipment. The state's mining sector legacy creates industrial zones with surplus power capacity attractive to data center developers.
Rio Grande do Sul
Porto Alegre's enterprise data center base sustains air-cooled CRAC unit replacement cycles amid refrigerant phase-down uncertainty. Proposed updates to Brazil's climate framework law lack implementation timelines, freezing long-term chiller procurement decisions. The state's manufacturing heritage supports domestic assembly operations that leverage existing certification relationships.
Paraná
Curitiba's government data center consolidation faces ABNT efficiency mandates accelerating legacy refrigerant-based chiller replacement. Federal facilities must navigate ANVISA certification requirements for cooling equipment with integrated control systems. The city's planned economy legacy provides grid infrastructure with reliability metrics attractive to disaster recovery site operators.
Brazil Data Center Cooling Market Competitive Landscape
European producers anchor one tier; North American specialists hold differentiated positions in thermal management software integration. The vendor base stratifies across three layers: diversified electrical conglomerates with local manufacturing footprints, precision cooling pure-plays targeting financial services verticals, and emerging liquid cooling technology licensors. Consolidation pressure intensifies as hyperscale operators demand full-stack thermal management partnerships rather than discrete equipment procurement. Strategic moves center on geographic expansion through domestic assembly operations and technology licensing agreements that compress ANVISA certification timelines.
Within the diversified industrial tier, Schneider Electric SE represents the integrated electrical infrastructure archetype with established Brazilian manufacturing presence. Vertiv Group Corp. exemplifies the critical power and thermal management specialist model competing on software-defined cooling orchestration. Stulz GmbH occupies the precision air conditioning niche for mission-critical financial services facilities, anchoring the European specialist position in São Paulo state's high-density corridor.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp. |
| Stulz GmbH |
| Rittal GmbH & Co. KG |
| Mitsubishi Electric Corporation |
| Johnson Controls International PLC |
| Daikin Industries |
| Emerson Electric |
| CoolIT Systems |
| Others |
Pricing and Supply Chain Analysis
Hyperscale operators' consolidation around ten-year liquid-ready infrastructure specifications in São Paulo state is compressing supplier negotiation windows and forcing equipment vendors to absorb certification delays into project pricing. ANVISA electromagnetic compatibility testing adds four to six months to product launches, embedding time-cost premiums into cold plate and heat exchanger quotations.
Pricing Analysis
Distributor margins for imported precision cooling equipment run 15-25 points above domestic assembly alternatives, creating a two-tier structure where local manufacturing commands premium positioning. Price differentiation hinges on ANVISA pre-certification status and thermal management software integration depth. Cost compression in air-cooled CRAC segments is intensifying as retrofit demand saturates São Paulo's enterprise base. Government facilities exhibit highest price sensitivity due to fixed-budget procurement cycles, while hyperscale cloud providers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Refurbishment flows for legacy chilled water systems are extending equipment lifecycles in Rio Grande do Sul and Paraná, delaying replacement demand for new installations. Manufacturing concentration rests on Germany, China, and domestic Brazilian assembly operations for CRAC and direct expansion units. Copper and aluminum cold plate fabrication draws from Chilean and Peruvian mining supply. Single-source dependency for engineered dielectric fluids creates vulnerability for immersion cooling pilots. Distribution runs through authorized integrators with ANVISA certification relationships, bypassing open-channel wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's data center cooling market offers margin expansion through liquid cooling premiumization as GPU rack densities displace commodity air-cooled volumes. ANEEL efficiency incentives and ABNT standard convergence reward early movers with tariff advantages and specification lock-in.
For Market Incumbents: Deploy thermal-fluid engineering talent acquisition programs to address scarcity in two-phase heat transfer design. Schneider Electric and Vertiv should anchor Campinas corridor relationships through direct-to-chip cold plate manufacturing localization. Stulz GmbH must defend precision air conditioning share in BFSI verticals against liquid cooling displacement by embedding predictive maintenance software into service contracts. Certification investment in ANVISA pre-approval accelerates product launch timelines versus import-dependent competitors. For New Entrants and Emerging Players: ABNT efficiency standard convergence with international energy performance certifications opens a window for pre-certified European equipment suppliers to bypass incumbent certification backlogs. Target Minas Gerais and Rio Grande do Sul secondary cloud regions where direct expansion cooling avoids chilled water infrastructure constraints. Edge micro data centers in Porto Maravilha brownfield sites offer lowest competitive density for liquid-cooled latency-sensitive deployments. Go-to-market through operational lease models aligns with OPEX preferences among financial services entrants. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic assembly operations possessing existing ANVISA certification relationships and local technical representation. Long-term viability centers on full-stack thermal management partnerships displacing discrete equipment procurement. Acquisition targets include precision cooling pure-plays with financial services vertical penetration and liquid cooling technology licensors with dielectric fluid chemistry IP. Monitor ANVISA certification queue lengths and ABNT standard implementation timelines as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Localization | Compresses ANVISA certification timelines by leveraging existing in-country testing protocols. |
| Thermal Management Software Integration | Vertiv and Schneider differentiate through cooling orchestration platforms binding ten-year operational commitments. |
| Liquid Cooling Technology Licensing | CoolIT Systems and immersion specialists capture premium margins as GPU clusters exceed 30 kW per rack. |
| Dielectric Fluid Supply Security Agreements | Addresses single-source dependency constraining immersion cooling pilot expansion in São Paulo state. |
| Performance-Based Service Contracting | ANEEL PUE incentives align vendor revenue with customer efficiency outcomes across Campinas corridor. |
Research Methodology
Coverage spans São Paulo, Rio de Janeiro, Minas Gerais, Rio Grande do Sul, and Paraná, with primary inputs from each state informing regional demand calibration. The analysis combines structured interviews with data center facility directors, thermal engineering consultants, ANVISA certification specialists, and procurement officers at hyperscale operators. Secondary validation draws from ANEEL tariff filings, ABNT standard documentation, ANVISA electromagnetic compatibility registries, and customs trade data for cooling equipment imports. Bottom-up installation tracking and top-down electricity consumption modeling triangulate market sizing.
Granularity-level modeling distinguishes liquid-ready new builds from legacy air-cooled retrofits across cooling type, end user vertical, solution category, and service type dimensions. CAGRs derive from rack-density trajectory assumptions tied to NVIDIA H100 deployment patterns and ANEEL efficiency incentive uptake curves. Forecast inputs include commodity price sensitivity for copper and aluminum, refrigerant phase-down regulatory scenarios, and hyperscale capex commitment disclosures.
Revisions become necessary when ANVISA certification timelines extend beyond modeled parameters or ABNT efficiency standards diverge from international convergence assumptions. Forecasts reflect documented assumptions regarding GPU adoption curves and tariff incentive continuity. Practitioners should monitor proposed climate framework law implementation schedules and local dielectric fluid supply development for early signals of demand trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Netherlands Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
India Data Center Cooling Market
Data Center Cooling
Global Laptop Cooling Pads Market
Data Center Cooling
Switzerland Data Center Cooling Market
Data Center Cooling
Middle East and Africa Data Center Cooling Market
Data Center Cooling
Austria Data Center Cooling Market
Data Center Cooling
Data Center Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Saudi Arabia Study of Data Center Water Consumption Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
APAC Data Center Cooling Market
Data Center Cooling
China Data Center Cooling Market
Data Center Cooling
Adiabatic Dry Cooler Market
Data Center Cooling
Saudi Arabia Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market