
 Global Personalization Engines Market | 2026-2036
Global Personalization Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personalization Engines Market Foresight
Retail and e-commerce is decoupling from legacy batch-processing personalization approaches. SAP Emarsys leverages integrated customer data platform architecture to anchor enterprise retail deployments across European markets. Dynamic Yield (Mastercard) competes on payment-adjacent behavioral targeting, while Braze specializes in cross-channel messaging orchestration for mobile-first brands.
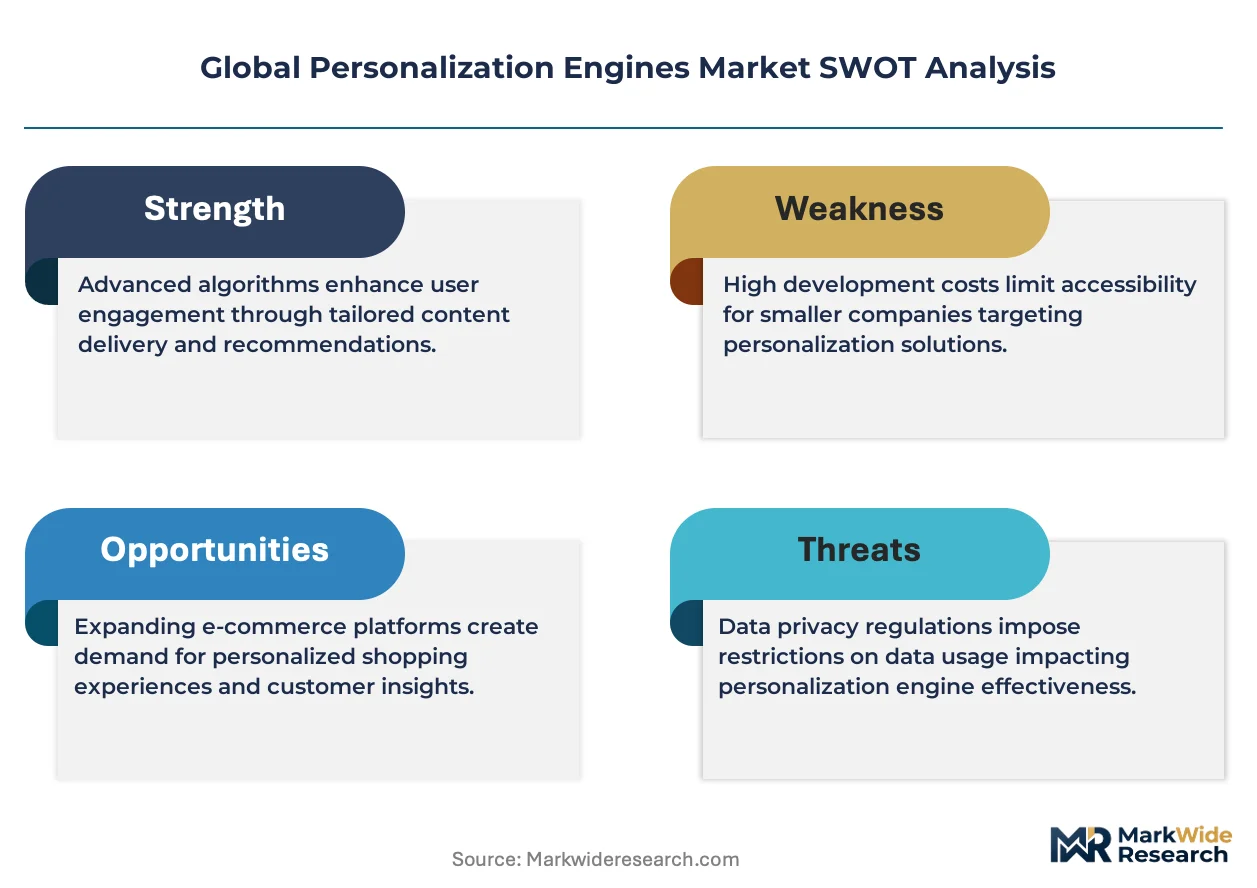
Personalization engines are software systems that apply machine learning algorithms, natural language processing, and predictive analytics to real-time behavioral data in order to dynamically adapt content, recommendations, and user interfaces to individual profiles. These systems process clickstreams, purchase histories, and contextual signals through cloud-native architectures to deliver sub-second latency in experience optimization. Cloud-based deployment dominates current infrastructure spend, though hybrid configurations are capturing margin pools from regulated industries with data residency constraints. Recommendation systems lead solution-type revenue, while experience optimization represents the fastest-growing category as brands prioritize full-journey orchestration over isolated product suggestions.
The EU AI Act imposes risk-classification and transparency obligations on automated profiling systems, directly shaping product roadmaps for vendors serving European enterprise clients. The Federal Trade Commission in the United States and the Personal Information Protection Commission in Japan are tightening enforcement against opaque data practices, raising compliance costs for cross-border deployment. Stakeholders must monitor evolving algorithmic accountability frameworks to determine whether to standardize on explainable models or maintain region-specific product variants.
Market Dynamics
Real-time recommendation engines are displacing batch-processing personalization architectures as e-commerce platforms prioritize sub-second latency in customer experience delivery. Cloud-native deployment models now dominate infrastructure decisions, though data residency requirements in regulated industries sustain hybrid configuration demand.
Growth Catalysts
- EU AI Act transparency mandates:Automated profiling systems face new risk-classification and explainability obligations, accelerating vendor investment in interpretable machine learning frameworks for European enterprise clients.
- First-party data activation:Large retail enterprises in the United States are consolidating customer data platforms to replace deprecating third-party cookie signals with owned behavioral datasets.
- Cross-channel orchestration:Mobile-first brands demand unified messaging across push notifications, email, and in-app experiences, expanding addressable market for journey-optimization software.
Market Restraints
- Algorithmic audit costs:The EU AI Act and FTC enforcement actions in the United States impose compliance expenditures that disproportionately burden mid-market vendors without dedicated governance infrastructure.
- Cloud compute concentration:AWS, Azure, and Google Cloud control infrastructure supply for personalization engine deployment, creating vendor lock-in risk and margin pressure from hyperscaler pricing power.
- Legacy system integration friction:Enterprise retail IT environments retain decades-old customer databases and ERP architectures that resist real-time API connectivity without expensive middleware development.
Strategic Opportunities
- Japan's PIPC enforcement gap:The Personal Information Protection Commission's tightening opacity penalties create first-mover advantage for vendors offering pre-built compliance tooling in a market with localized incumbent weakness.
- Experience optimization convergence:Natural language processing and computer vision are fusing into multimodal personalization that adapts search, content, and interface layout simultaneously rather than siloed product recommendations.
- India's BIS data localization:Bureau of Indian Standards guidelines and RBI financial data rules are mandating in-country processing, opening captive deployment opportunities for hybrid architecture specialists.
Industry Challenges
- MLOps talent scarcity:Production-grade feature engineering and model monitoring capabilities remain concentrated among engineers with platform-scale experience, constraining vendor delivery timelines.
- ISO/IEC 42001 certification timelines:The new artificial intelligence management system standard requires 12-18 month implementation cycles that delay enterprise sales cycles and inflate pre-revenue costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personalization Engines Market |
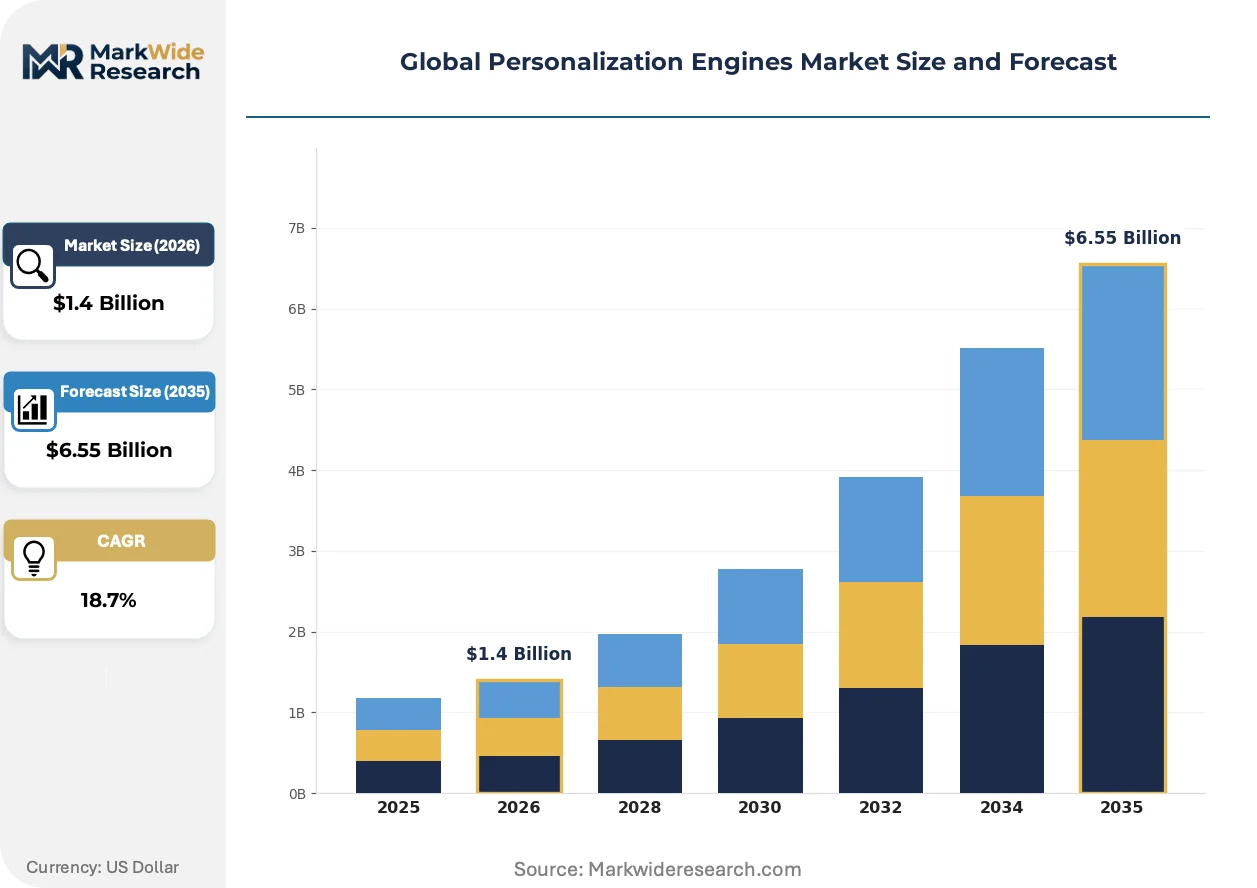
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $6.55 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Service End User: Retail, E-Commerce, Media & Entertainment, Travel Solution Type: Content Personalization, Customer Insights, Recommendation Systems, Experience Optimization Technology: Machine Learning, Natural Language Processing, Predictive Analytics, A/B Testing |
| Companies Covered | Insider One, SAP Emarsys, Dynamic Yield (Mastercard), Twilio Segment, CleverTap, Optimizely, Braze, Blueshift, Adobe Target, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personalization Engines Market Shifts & Advancements
Foundation model architectures are reshaping how personalization engines process unstructured behavioral signals. Vendors now embed large language models for content generation and semantic understanding alongside traditional collaborative filtering.
Transformer-based recommendation systems are absorbing natural language queries, image inputs, and session context into unified embedding spaces. Fashion and home décor retailers in Germany and France are piloting these multimodal engines for visual search personalization. The technology is absorbing budget share from legacy matrix factorization approaches that cannot interpret product descriptions or user-generated content.
The EU AI Act's risk-tier classification system is forcing vendors to document training data provenance and model performance metrics for high-risk profiling applications. Deployment contracts now require algorithmic impact assessments as standard terms. Financial services and employment platforms face the strictest scrutiny, with several European banks pausing behavioral scoring rollouts pending legal interpretation.
Enterprise procurement of personalization software is consolidating around outcome-based pricing tied to revenue attribution rather than seat-based or usage-tier models. Retailers in the United Kingdom and Netherlands are demanding pilot-to-scale contracts with guaranteed lift thresholds. This compression of commercial risk onto vendors is filtering smaller competitors from RFP processes and elongating enterprise sales cycles.
Global Personalization Engines Market Segmentation
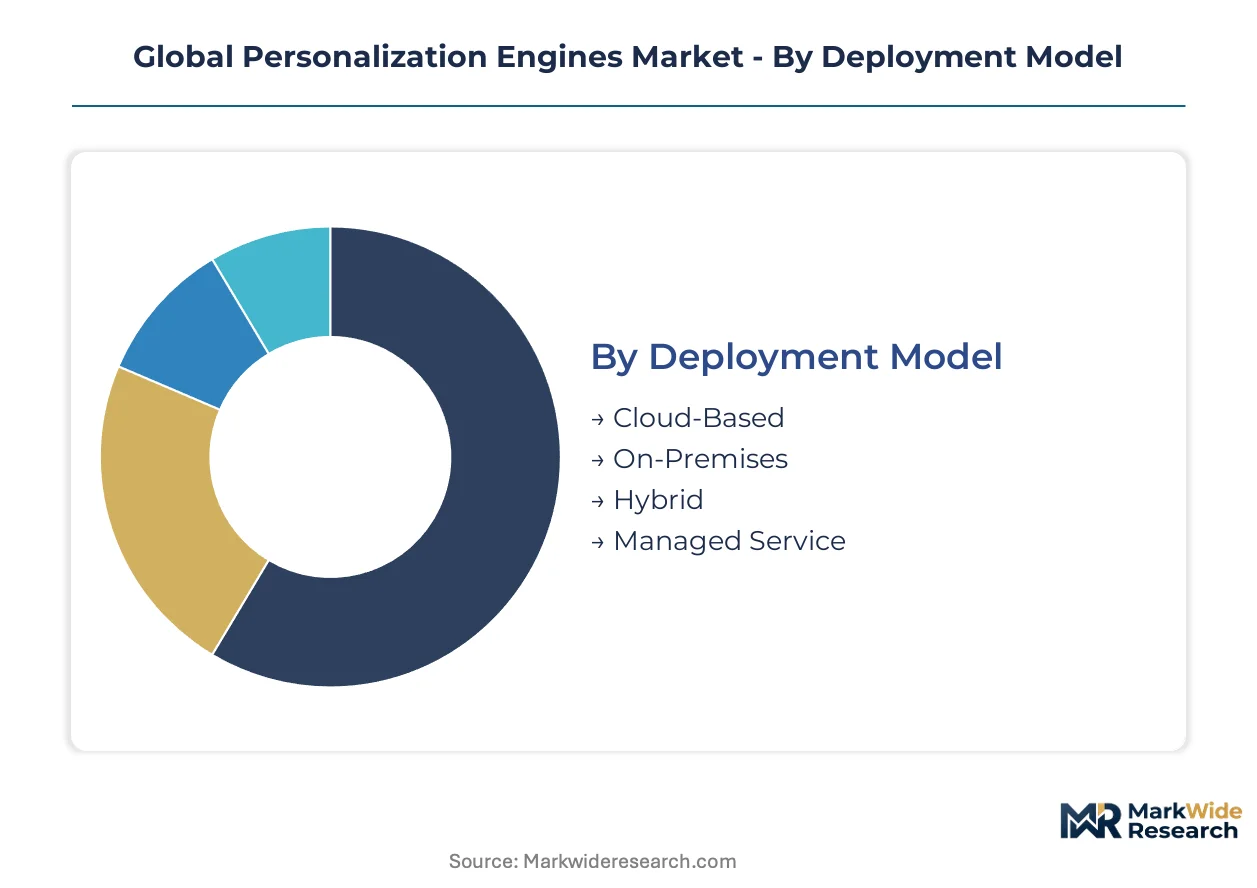
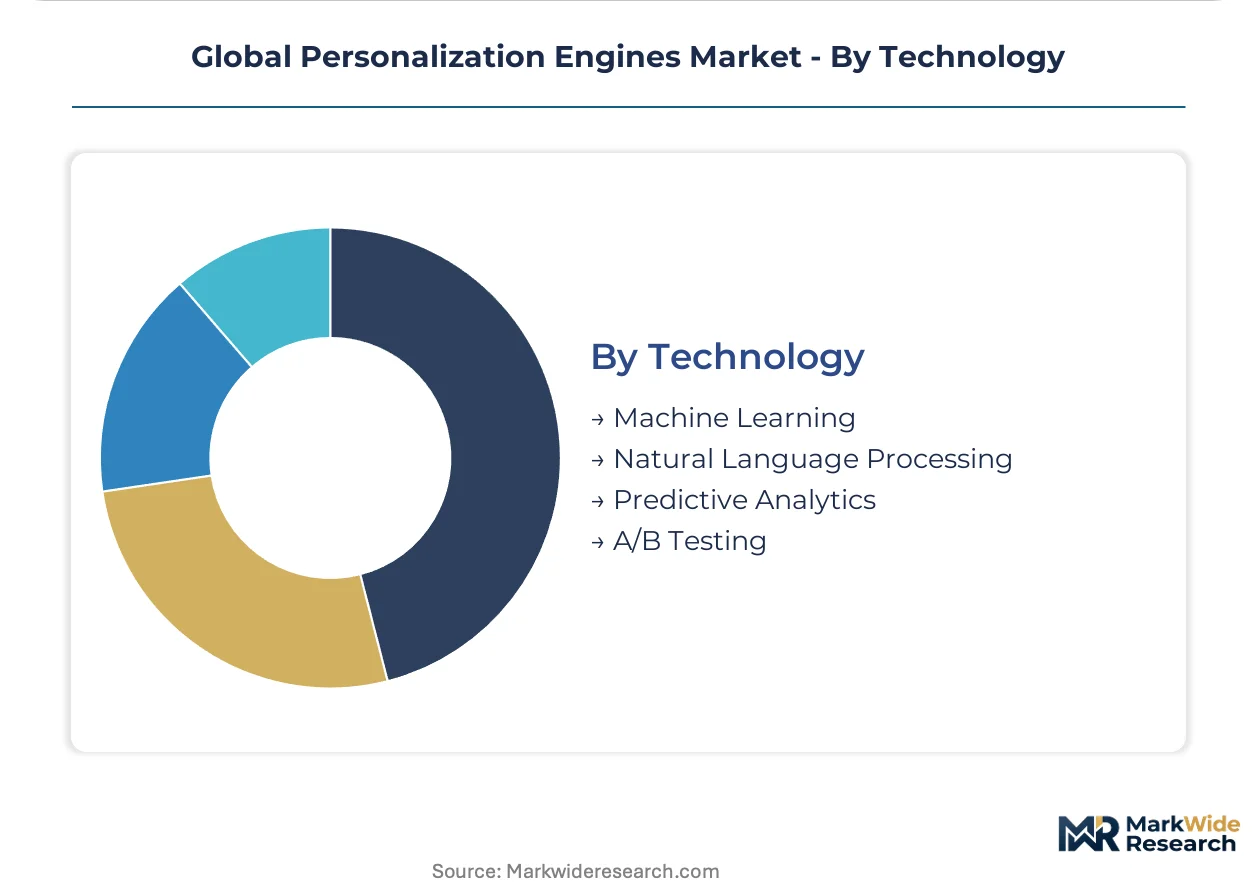
Personalization engines fragment across four critical dimensions that shape procurement decisions. Deployment architecture determines compliance posture and latency performance. End-user verticals dictate feature requirements and integration complexity. Solution types reflect maturity of buyer data infrastructure. Technology stacks differentiate vendor capabilities in model interpretability and real-time processing.
Deployment Model:
Buyer risk tolerance and data residency obligations drive deployment architecture selection.
- Cloud-Based:Cloud-native architectures deliver sub-second latency through distributed edge computing nodes. Demand concentrates among mid-market retailers in the United States seeking rapid deployment without capital expenditure.
- On-Premises:Self-managed infrastructure retains complete data sovereignty and enables custom hardware acceleration for high-throughput recommendation serving. European financial services and healthcare platforms favor this model to satisfy GDPR and EU AI Act documentation requirements.
- Hybrid:Split architectures process sensitive identity data locally while pushing anonymized behavioral signals to cloud analytics layers. India's BIS localization mandates and RBI financial data rules are accelerating hybrid adoption among domestic e-commerce platforms.
- Managed Service:Vendor-operated private cloud deployments combine operational outsourcing with dedicated tenancy. Japanese enterprises facing PIPC enforcement pressure are migrating toward managed services to transfer algorithmic audit liability.
Cloud-Based leads on scale; Hybrid leads on momentum.
End User:
Vertical-specific use cases determine model complexity and integration touchpoints.
- Retail:Enterprise merchants deploy full-journey orchestration across physical and digital channels, requiring real-time inventory synchronization and unified customer profiles. Large United States retailers are consolidating first-party data platforms to replace deprecating third-party cookies.
- E-Commerce:Pure-play digital marketplaces prioritize recommendation systems with session-based adaptation and visual search capabilities. German and French fashion retailers are piloting multimodal engines that absorb product images alongside text descriptions.
- Media & Entertainment:Streaming platforms and publishers optimize content sequencing and subscription retention through behavioral prediction models. This segment demands high-volume event ingestion and content metadata enrichment pipelines.
- Travel:Airlines and hospitality brands personalize pricing, ancillary offers, and loyalty experiences across fragmented booking channels. Complex supplier integrations and dynamic inventory constraints distinguish travel deployments.
Retail dominates current revenue; E-Commerce shows the steepest expansion trajectory.
Solution Type:
Buyers progress from isolated point solutions toward integrated experience platforms as data maturity advances.
- Recommendation Systems:Collaborative filtering and content-based algorithms power product, content, and next-best-action suggestions. This foundational capability anchors most initial personalization investments.
- Experience Optimization:Full-journey orchestration unifies messaging, layout, and timing decisions across touchpoints. United Kingdom and Netherlands retailers are demanding outcome-based contracts with guaranteed lift thresholds.
- Content Personalization:Dynamic assembly of headlines, imagery, and copy variants based on individual profiles. Foundation model integration is expanding automation of creative production.
- Customer Insights:Predictive segmentation and propensity scoring enable marketing strategy and audience planning. These tools often serve as entry points for organizations building data science capabilities.
Recommendation Systems anchor current spend; Experience Optimization is gaining share fastest.
Technology:
Core algorithmic approaches differentiate vendor performance on accuracy, latency, and explainability.
- Machine Learning:Supervised and unsupervised learning frameworks power behavioral prediction, clustering, and ranking. Transformer architectures are displacing matrix factorization for sequence modeling.
- Natural Language Processing:Semantic understanding of search queries, reviews, and content enables intent-based personalization. Large language models are embedding into production pipelines for content generation.
- Predictive Analytics:Statistical forecasting of churn, lifetime value, and conversion probability informs resource allocation. These methods require structured historical data and feature engineering expertise.
- A/B Testing:Controlled experimentation infrastructure validates personalization impact and enables continuous optimization. Tight integration with delivery systems distinguishes mature platforms.
Machine Learning commands the largest investment base; Natural Language Processing shows the strongest technology momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor deployment strategies as compliance cost differentials widen between jurisdictions. The EU AI Act's documentation burdens are pushing mid-market vendors toward hybrid architectures that isolate sensitive processing within lower-cost regions while maintaining European market access.
United States
Enterprise retailers are consolidating first-party data platforms to replace deprecating third-party cookie infrastructure. FTC enforcement actions against opaque data practices are tightening consent requirements for behavioral profiling. New York and San Francisco metro areas anchor the largest concentration of personalization engine deployments, with financial services firms in Manhattan driving demand for explainable model architectures.
Germany
Automotive and industrial manufacturers are piloting multimodal personalization for B2B customer portals and after-sales platforms. The EU AI Act's risk-tier classification imposes strict documentation requirements on high-risk profiling applications. Munich and Stuttgart industrial clusters host the densest concentration of vendor R&D facilities serving European automotive clients.
United Kingdom
Retailers are demanding outcome-based pricing contracts with guaranteed revenue lift thresholds, compressing commercial risk onto vendors. The Information Commissioner's Office is tightening guidance on automated decision-making transparency. London's fintech and media sectors are deploying real-time recommendation systems for subscription retention and content sequencing.
India
Domestic e-commerce platforms are expanding adoption of real-time recommendation engines as digital payment penetration deepens. BIS data localization guidelines and RBI financial data rules mandate in-country processing for sensitive behavioral datasets. Bangalore and Mumbai host the primary engineering centers developing hybrid deployment architectures for regulated sectors.
Japan
Enterprises are migrating toward managed service deployments to transfer algorithmic audit liability under tightening PIPC enforcement. Mobile-first brands in Tokyo and Osaka are prioritizing cross-channel messaging orchestration across LINE, email, and in-app experiences. The PIPC's opacity penalties are creating first-mover advantage for vendors offering pre-built compliance tooling.
Global Personalization Engines Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise retail consolidating around integrated platform vendors while mid-market buyers favor modular point solutions. The vendor landscape exhibits moderate concentration at the top tier, with three to four platforms capturing disproportionate enterprise procurement volume. Strategic archetypes include customer data platform-anchored suites, payment-adjacent behavioral targeting specialists, and cross-channel messaging orchestrators. Dominant competitive moves encompass outcome-based pricing restructuring and hybrid deployment capability expansion to satisfy data residency mandates.
Among the named platform vendors, SAP Emarsys exemplifies the enterprise suite archetype with integrated CDP architecture, while Dynamic Yield represents payment-adjacent behavioral targeting following its Mastercard acquisition. Braze occupies a position within the cross-channel messaging tier, serving mobile-first brands with unified push, email, and in-app orchestration.
| Leading Market Players |
|---|
| Insider One |
| SAP Emarsys |
| Dynamic Yield (Mastercard) |
| Twilio Segment |
| CleverTap |
| Optimizely |
| Braze |
| Blueshift |
| Adobe Target |
| Others |
Supply & Pricing Matrix
Captive cloud infrastructure investments by hyperscalers anchor supply positioning and pricing power for personalization engine vendors. AWS, Azure, and Google Cloud control compute supply, creating vendor lock-in risk that feeds through to margin pressure on mid-market software providers without dedicated infrastructure.
Pricing Analysis
Direct-to-enterprise discounts dominate large retail procurement, while seat-based SaaS tiers persist among mid-market buyers. Price differentiation hinges on outcome-based revenue attribution guarantees versus standard usage-tier models, with United Kingdom and Netherlands retailers demanding pilot-to-scale contracts with guaranteed lift thresholds. Cost compression in mid-market segments intensifies because algorithmic audit expenditures from EU AI Act compliance disproportionately burden vendors without dedicated governance infrastructure. Mid-market retailers exhibit highest price sensitivity; enterprise financial services firms show least sensitivity due to regulatory compliance premiums.
Supply Chain Analysis
Dual-sourcing requirements from European financial services clients mandate multi-cloud qualification across AWS and Azure at minimum. Geographic supply concentrates in the United States, Ireland, and Singapore, where hyperscaler regions anchor latency performance for real-time recommendation serving. Raw material dependencies span GPU accelerators, high-bandwidth memory modules, and specialized networking hardware. Single-source vulnerability runs through NVIDIA's datacenter GPU dominance. Distribution runs through direct vendor sales organizations and systems integrator partnerships for enterprise deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in experience optimization tiers where foundation model integration commands premium pricing. Cost-down potential rests on MLOps automation reducing production-grade feature engineering labor intensity.
For Market Incumbents: Lock in hybrid deployment capabilities to satisfy India's BIS localization mandates and EU AI Act data residency requirements simultaneously. Deepen upstream control over edge computing infrastructure to defend against hyperscaler pricing power. Prioritize ISO/IEC 42001 certification investment to accelerate enterprise sales cycles constrained by governance due diligence. For New Entrants and Emerging Players: The premium-economy price-point gap in experience optimization creates white-space opportunity for vendors offering modular journey-orchestration without full CDP anchoring. Japan's PIPC enforcement gap represents the most penetrable geography, where pre-built compliance tooling addresses localized incumbent weakness. Target mobile-first brands in Tokyo and Osaka with LINE-integrated cross-channel messaging as the initial go-to-market wedge. For Investors and Strategic Acquirers: Consolidation pressure builds where MLOps talent scarcity constrains vendor delivery timelines and elongates pre-revenue costs. Long-term viability favors platforms with integrated CDP architecture and explainable model frameworks over point-solution specialists. Watch ISO/IEC 42001 certification velocity as the inflection signal separating enterprise-viable vendors from mid-market casualties.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Architecture Expansion | Addresses India's BIS mandates and EU AI Act residency requirements simultaneously. |
| Foundation Model Integration | Enables multimodal personalization fusing NLP, computer vision, and collaborative filtering. |
| Outcome-Based Pricing Restructuring | Aligns vendor compensation with revenue attribution guarantees demanded by United Kingdom retailers. |
| ISO/IEC 42001 Certification Investment | Accelerates enterprise procurement cycles constrained by AI governance due diligence. |
| Pre-Built Compliance Tooling Development | Captures first-mover advantage in Japan's PIPC enforcement tightening. |
Research Methodology
Coverage spans the United States, Germany, United Kingdom, India, and Japan, with primary inputs from each regional cluster. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie mobile analytics, and EU regulatory documentation. Bottom-up deployment volume estimates triangulated against top-down software spend data.
Rate-of-change decomposition separates baseline adoption velocity from regulatory acceleration effects and technology substitution impacts across the analysis window. Segmentation dimensions modeled include deployment architecture, end-user vertical, solution type maturity, and technology stack complexity. CAGRs derived from logistic diffusion curves fitted to enterprise adoption patterns, with inputs from real-time latency requirements and data residency constraint intensification.
Caveats apply where EU AI Act legal interpretation shifts or FTC enforcement escalation could materially shift the outlook. Forecasts reflect assumptions about third-party cookie deprecation timelines and foundation model cost trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
POS Restaurant Management System Market
Digital Solutions
Digital Assistant Market
Digital Solutions
Global Industrial Design Market
Digital Solutions
Lead Generation Solutions Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Outsourced Digital Workplace Service Market
Digital Solutions
Global Space Planning Software Market
Digital Solutions
Agriculture Software Market
Digital Solutions
Supply Side Platform (SSP) Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Cannabis POS System Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
India PLM Market