
 Austria ICT Market | 2026-2036
Austria ICT Market Size, Share, and Industry Trends Forecast 2026-2036
Austria ICT Market Outlook
The capability gap between cloud-native specialists and legacy systems integrators is reorganizing competitive dynamics across Austria's technology sector. Bundesrechenzentrum GmbH leverages its sovereign infrastructure position to dominate public-sector procurement cycles. A1 Telekom Austria AG anchors the connectivity layer through nationwide 5G and fiber investments. Microsoft Österreich GmbH competes by extending hyperscale cloud capacity into regulated Austrian data residency zones.
Information and communications technology encompasses the hardware, software, and services enabling data processing, transmission, and storage across enterprise and institutional networks, typically operating through layered architectures spanning edge devices, core infrastructure, and application platforms. Cloud Services within the Solution Type dimension leads current investment flows as Austrian enterprises migrate on-premises workloads. Cybersecurity commands expanding margin pools as EU-wide resilience mandates harden procurement specifications. The End User segment shows Government and Healthcare applications growing fastest, driven by federal digitization programs and hospital interoperability mandates.
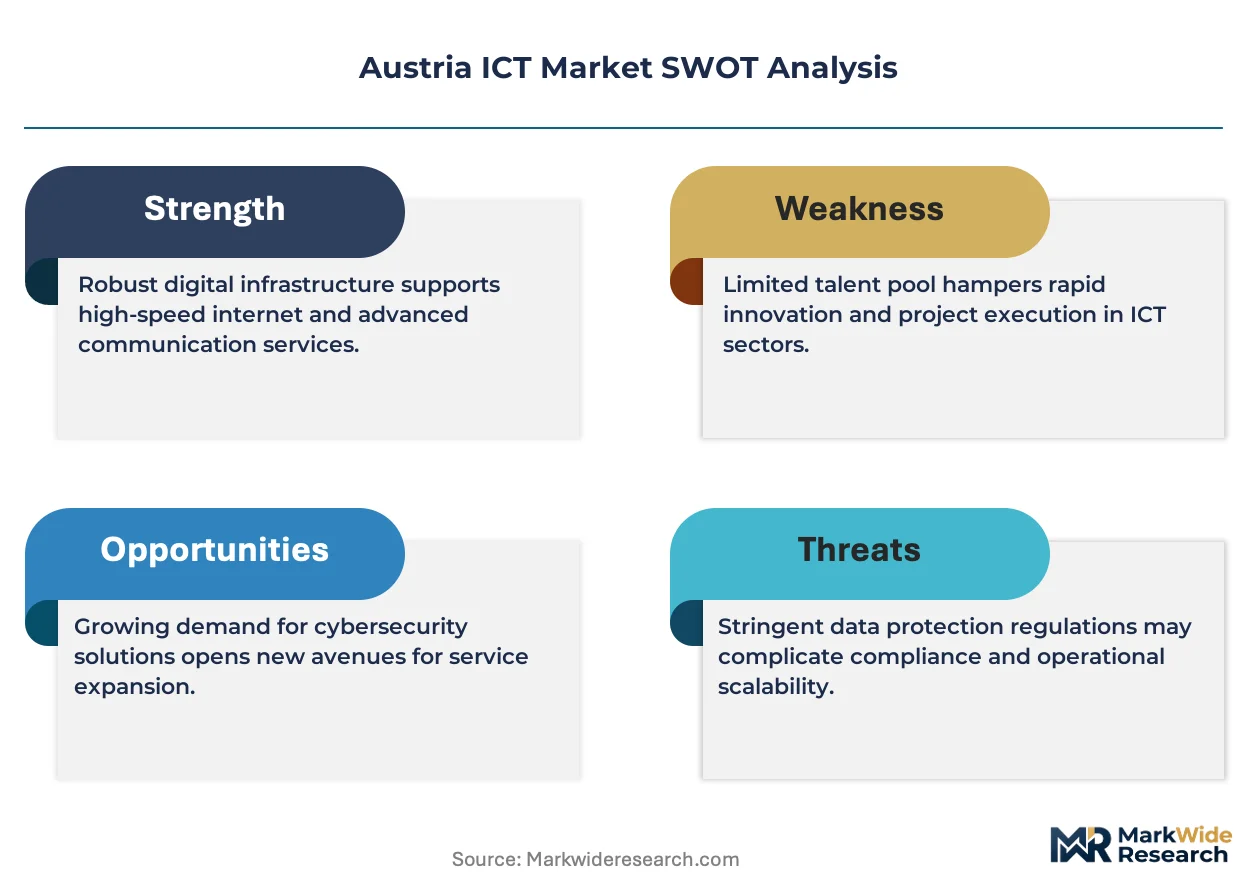
BIS standards alignment, GDPR data governance requirements, and the EU AI Act's risk-based classification framework collectively shape product certification pathways and vendor qualification criteria for Austrian ICT deployments. The national telecom regulator and the Austrian Data Protection Authority enforce sector-specific compliance thresholds that filter market access. Stakeholders must monitor how forthcoming EU cybersecurity certification schemes restructure procurement eligibility for critical infrastructure suppliers.
Market Dynamics
The EU AI Act's risk-based classification framework is forcing Austrian enterprises to requalify algorithmic procurement pipelines, while sovereign cloud mandates from Bundesrechenzentrum GmbH concentrate public-sector infrastructure decisions.
Growth Catalysts
- Federal Digitization Programs:Hospital interoperability mandates under the ELGA health records framework accelerate healthcare IT procurement cycles across Vienna, Graz, and Linz.
- GDPR-Compliant Cloud Migration:Austrian banks facing ECB supervisory scrutiny expand spending on data-residency-certified infrastructure to satisfy cross-border data governance requirements.
- 5G Network Densification:A1 Telekom Austria AG's nationwide fiber-to-the-home rollout enables edge computing deployments for manufacturing automation in Styria and Upper Austria industrial corridors.
Market Restraints
- Specialized Talent Scarcity:Vienna's enterprise software corridor faces acute shortages of cloud-native architects and AI/ML engineers, inflating project delivery timelines.
- Hyperscale Dependency:Austrian mid-market enterprises rely on Frankfurt and Zurich hyperscale regions for elastic compute, creating latency and data sovereignty exposure.
- Legacy System Inertia:Provincial government agencies maintain COBOL-based administrative cores that resist API-first modernization without multi-year parallel-run investments.
Strategic Opportunities
- Tyrol and Salzburg SME Digitization:Alpine tourism and precision manufacturing clusters remain underpenetrated for managed security services and IoT predictive maintenance platforms.
- EU Cybersecurity Certification Schemes:Forthcoming ENISA common criteria for critical infrastructure suppliers will filter procurement eligibility, favoring pre-certified domestic vendors.
- AI-Edge Convergence:Federated learning architectures combined with 5G MEC nodes enable real-time quality control for Carinthian semiconductor packaging facilities without raw data egress.
Industry Challenges
- Certification Timeline Compression:BIS standards alignment for federal IT procurement now requires concurrent GDPR, ISO 27001, and emerging EU AI Act conformity assessments, extending vendor qualification to 14-18 months.
- Intergenerational Workforce Transition:Systems integrators struggle to upskill mainframe specialists into Kubernetes platform engineering roles, creating delivery bottlenecks for hybrid cloud migrations.
- Supply Chain Reconfiguration:Network hardware vendors face component sourcing friction as EU Chip Act incentives redirect semiconductor allocation toward automotive and defense contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Austria ICT Market |
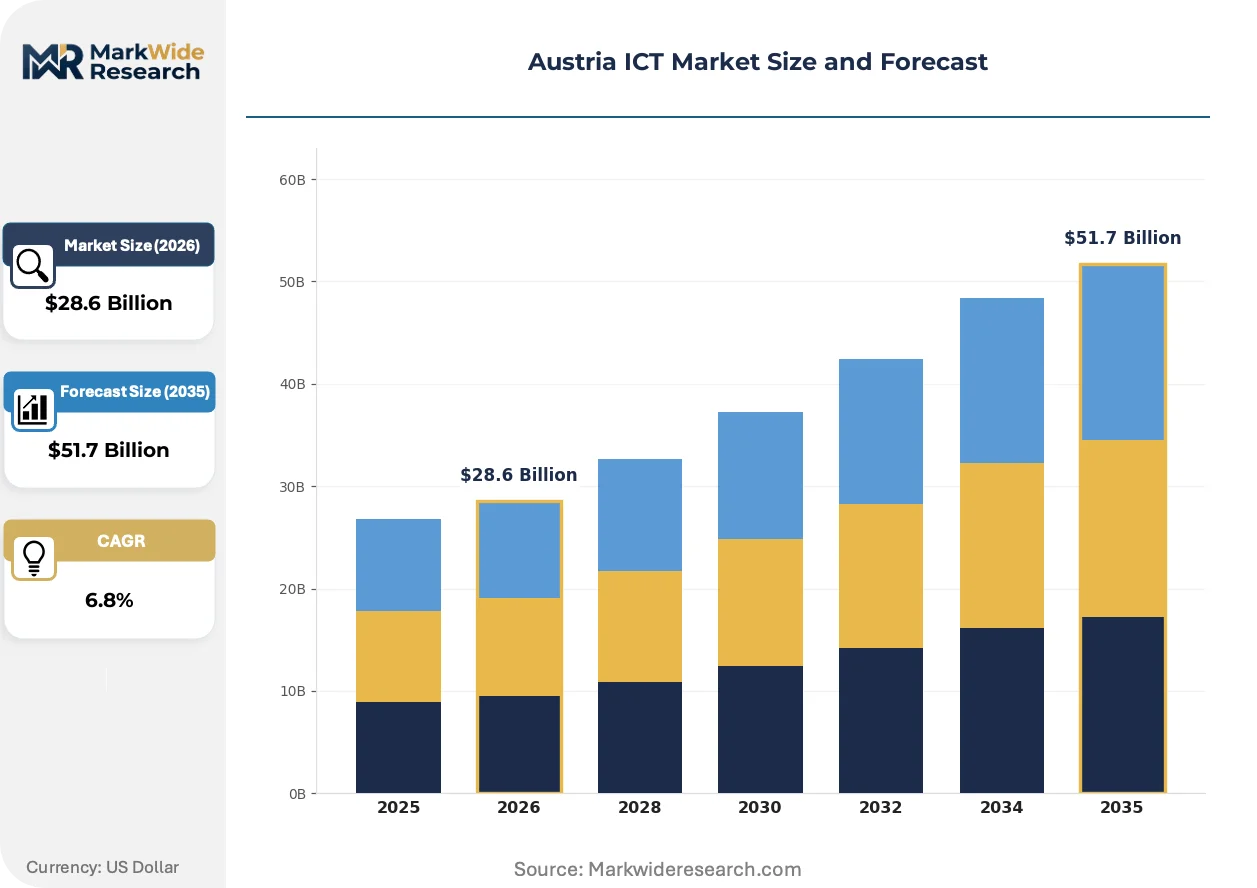
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
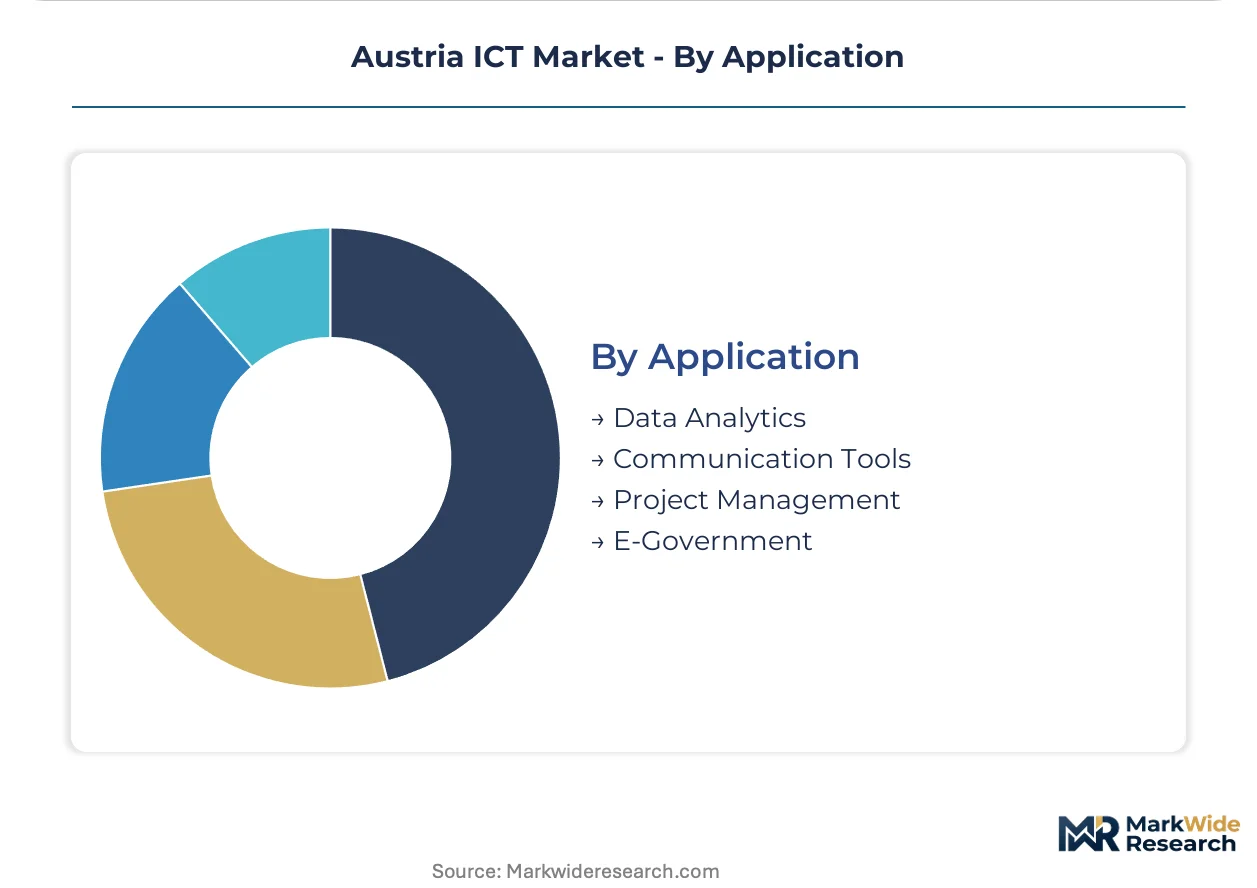
| Segmentation | Solution Type: Cloud Services, Cybersecurity, Networking Solutions, Software Development End User: Government, BFSI, Healthcare, Education Technology: Artificial Intelligence, Blockchain, Internet of Things, Machine Learning Application: Data Analytics, Communication Tools, Project Management, E-Government |
| Companies Covered | Bundesrechenzentrum GmbH, ATOS Technologies Austria GmbH, A1 Telekom Austria AG, Microsoft Österreich GmbH, Kapsch BusinessCom AG, Kontron AG, SAP Österreich GmbH, IBM Österreich GmbH, Erste Digital GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Austria ICT Market Strategic Shifts
Sovereign infrastructure requirements and algorithmic accountability mandates are restructuring how Austrian enterprises evaluate vendor risk and architect data flows.
Confidential computing is fragmenting the traditional perimeter-based security model by enabling encrypted data processing within hardware-isolated enclaves. Austrian financial services regulators now recognize confidential computing as a compensating control for sensitive analytics workloads. This technology is fragmenting procurement patterns as CISOs separate infrastructure decisions from application security ownership.
The EU AI Act's implementation timeline is compressing algorithmic system documentation requirements across high-risk deployment categories. Austrian healthcare providers must maintain technical files and conformity assessments for diagnostic AI tools previously governed only by medical device directives. Radiology departments in Vienna's university hospitals are restructuring vendor contracts to embed ongoing post-market monitoring obligations.
Consumption-based infrastructure financing is displacing capital-intensive on-premises ownership among mid-market manufacturers. Tyrolean industrial equipment suppliers now subscribe to edge-as-a-service platforms with performance guarantees rather than depreciating server assets. This shift concentrates procurement authority within CFO functions and away from traditional IT operations teams.
Austria ICT Market Segmentation
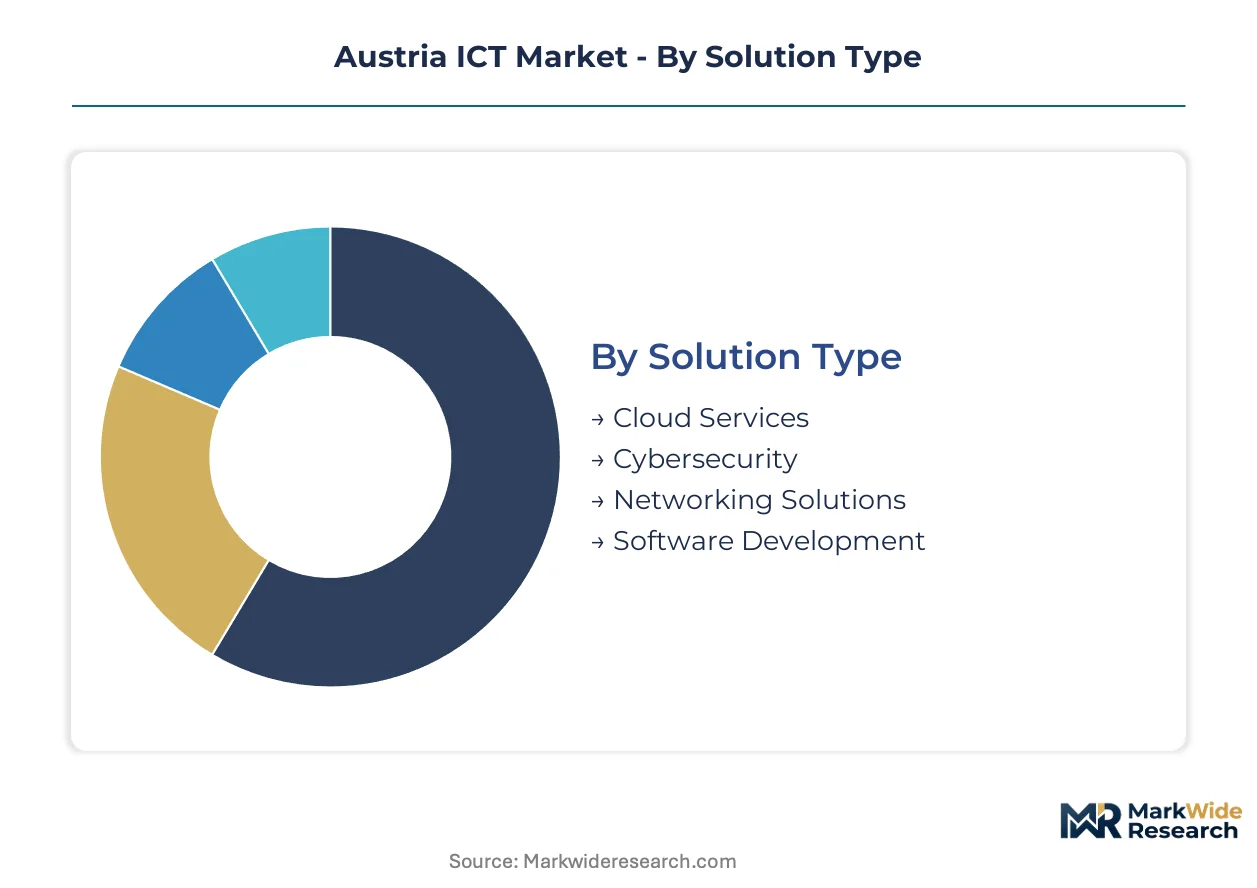
Austria's ICT market fragments across four critical dimensions that determine procurement pathways and vendor qualification requirements. Solution Type governs infrastructure investment cycles, while End User segmentation shapes compliance thresholds under federal and EU mandates.
Solution Type:
Channel mix varies sharply by solution category, with hyperscale cloud providers dominating elastic compute while specialized security vendors capture managed services through systems integrator partnerships.
- Cloud Services:Multi-tenant infrastructure with data-residency certification enables Austrian banks to satisfy ECB cross-border data governance requirements. Vienna's enterprise software corridor concentrates demand as manufacturers migrate ERP workloads from on-premises data centers.
- Cybersecurity:Zero-trust architectures and managed detection-and-response platforms address EU NIS2 directive mandates for critical infrastructure operators. Federal procurement cycles under Bundesrechenzentrum GmbH specifications favor vendors with ISO 27001 and BSI certification.
- Networking Solutions:SD-WAN and SASE deployments serve distributed manufacturing sites in Styria and Upper Austria.
- Software Development:Low-code platforms and DevOps tooling accelerate application delivery for mid-market enterprises in Salzburg and Tyrol.
Cloud Services dominates installed base. Cybersecurity is where expansion concentrates.
End User:
Cost tier stratification separates sovereign-grade federal deployments from standardized commercial licensing, with healthcare and BFSI commanding premium pricing for compliance-heavy implementations.
- Government:Bundesrechenzentrum GmbH operates as the central procurement authority for federal digitization programs, mandating BIS standards alignment and GDPR data governance. Provincial agencies in Lower Austria and Styria lag Vienna's interoperability maturity.
- BFSI:Austrian banks under ECB supervisory scrutiny invest heavily in data-residency-certified infrastructure and confidential computing for sensitive analytics. Erste Group and Raiffeisen Bank International anchor procurement volumes.
- Healthcare:ELGA health records framework drives hospital IT modernization across Vienna, Graz, and Linz academic medical centers.
- Education:Federal and state-level learning management platforms serve universities and vocational training institutions.
BFSI commands premium pricing tiers. Healthcare is climbing the fastest.
Technology:
Application intensity varies by industrial maturity, with AI and IoT penetrating manufacturing automation while blockchain remains confined to supply chain pilot programs.
- Artificial Intelligence:Diagnostic imaging tools and predictive maintenance algorithms face EU AI Act risk-based classification requirements. Vienna's university hospitals restructure vendor contracts to embed post-market monitoring obligations for high-risk deployments.
- Machine Learning:Federated learning architectures combined with 5G MEC nodes enable real-time quality control for Carinthian semiconductor packaging without raw data egress.
- Internet of Things:Industrial sensor networks and predictive maintenance platforms serve precision manufacturing clusters in Tyrol.
- Blockchain:Supply chain traceability and digital identity pilots remain experimental across Austrian logistics operators.
Machine Learning anchors manufacturing investment. Artificial Intelligence is gaining share fastest.
Application:
Volume concentration tracks federal digitization momentum, with E-Government and Data Analytics absorbing disproportionate procurement spend relative to communication and collaboration tooling.
- Data Analytics:Business intelligence platforms and customer data platforms serve retail banking and tourism marketing functions. Confidential computing recognition by Austrian financial regulators accelerates sensitive analytics workload migration.
- E-Government:Federal digitization programs mandate interoperable service delivery platforms across municipal and provincial administrative tiers. The Austrian Data Protection Authority enforces sector-specific compliance thresholds.
- Communication Tools:Unified communications and contact center platforms standardize across distributed enterprises.
- Project Management:SaaS-based collaboration tools penetrate professional services and construction sectors.
Data Analytics dominates enterprise licensing value. E-Government shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vienna commands premium pricing for sovereign-grade cloud deployments while Tyrolean manufacturing clusters absorb standardized edge-computing services at compressed margins. This asymmetry reflects divergent compliance burdens and procurement authority concentration across Austrian sub-regions.
Vienna
Federal digitization programs and ECB-supervised banking infrastructure anchor enterprise software demand. The Austrian Data Protection Authority enforces GDPR thresholds that filter vendor access to public-sector contracts. Vienna's enterprise software corridor concentrates procurement for ELGA health records and Bundesrechenzentrum GmbH sovereign cloud mandates.
Upper Austria
Industrial automation and semiconductor packaging facilities drive edge-computing investments. A1 Telekom Austria AG's fiber-to-the-home rollout enables 5G MEC deployments for real-time quality control. Linz anchors manufacturing digitization with federated learning architectures for Carinthian supplier networks.
Styria
Precision manufacturing clusters in Graz generate demand for predictive maintenance platforms and IoT sensor networks. Provincial agencies lag Vienna's interoperability maturity, creating parallel-run modernization bottlenecks. The region's automotive supply chain accelerates API-first infrastructure replacement.
Tyrol
Alpine tourism and mid-market manufacturing remain underpenetrated for managed security services. Consumption-based edge-as-a-service platforms displace capital-intensive server ownership among industrial equipment suppliers. Innsbruck's procurement authority concentrates CFO-driven SaaS decisions away from traditional IT operations.
Salzburg
Professional services and construction sectors standardize on SaaS-based collaboration tools. Low-code platforms accelerate application delivery for distributed enterprises without specialized cloud-native talent. The region absorbs standardized commercial licensing below federal premium tiers.
Austria ICT Market Competitive Environment
Concentration sits with sovereign infrastructure operators and hyperscale cloud providers that have secured data-residency certification. The vendor base organizes into three tiers: public-sector procurement gatekeepers, connectivity-layer incumbents with nationwide 5G assets, and international software licensors with localized compliance teams. Competitive moves center on strategic partnerships for edge-computing deployment and portfolio diversification into AI governance tooling.
Within the sovereign infrastructure tier, Bundesrechenzentrum GmbH occupies the central procurement authority position for federal digitization programs. A1 Telekom Austria AG anchors connectivity-layer competition through nationwide fiber and 5G investments. Microsoft Österreich GmbH represents the hyperscale archetype, extending cloud capacity into Austrian data residency zones to satisfy ECB cross-border governance requirements.
| Leading Market Players |
|---|
| Bundesrechenzentrum GmbH |
| ATOS Technologies Austria GmbH |
| A1 Telekom Austria AG |
| Microsoft Österreich GmbH |
| Kapsch BusinessCom AG |
| Kontron AG |
| SAP Österreich GmbH |
| IBM Österreich GmbH |
| Erste Digital GmbH |
| Others |
Value Chain & Pricing Dynamics
Fourteen-to-eighteen-month vendor qualification timelines for BIS standards alignment compress procurement cycles and concentrate pricing power with pre-certified domestic integrators serving Bundesrechenzentrum GmbH sovereign cloud mandates. This lead-time band separates premium-compliant deployments from standardized commercial licensing tiers.
Pricing Analysis
The customization-premium spread between configured-to-order sovereign cloud deployments and standardized SaaS licensing separates federal procurement from mid-market commercial adoption. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, data residency guarantees, and after-sales support bundling. Cost compression in the standard tier intensifies as Tyrolean manufacturers subscribe to edge-as-a-service platforms with CFO-driven procurement authority. Provincial government agencies exhibit highest price sensitivity due to legacy system parallel-run investments, while ECB-supervised banks accept premium tiers for confidential computing recognition.
Supply Chain Analysis
Germany and the Netherlands anchor enterprise software licensing distribution into Vienna's corridor, while Taiwan and South Korea supply semiconductor components for edge computing hardware. Austrian ICT infrastructure draws from EU-based hyperscale regions for elastic compute, with component sourcing friction emerging as EU Chip Act incentives redirect semiconductor allocation. Single-source vulnerability concentrates in legacy mainframe maintenance parts for provincial COBOL systems. Distribution runs through systems integrator partnerships for cybersecurity managed services and direct hyperscale contracting for cloud infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of cloud-native architects and AI/ML engineers across Vienna's enterprise software corridor creates a capability bottleneck that reshapes competitive dynamics. Organizations that secure specialized talent pools or automated delivery platforms will outpace rivals constrained by workforce transition timelines.
For Market Incumbents: Compound defensive positioning through backward integration into sovereign infrastructure operations and ISO 27001 certification pre-emption ahead of ENISA common criteria finalization. Bundesrechenzentrum GmbH's procurement gatekeeper role threatens margin compression for uncertified vendors. Capacity addition in Tyrolean edge computing nodes captures manufacturing automation demand before hyperscale entrants localize.
For New Entrants and Emerging Players: EU Cybersecurity Certification fast-track pathways for critical infrastructure suppliers filter procurement eligibility and create accessible entry points. Underpenetrated managed security services in Alpine tourism clusters offer the most penetrable white-space target. Channel partnerships with A1 Telekom Austria AG's 5G MEC distribution network provide go-to-market leverage without direct federal sales force investment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across consumption-based edge-as-a-service platforms as CFO-driven financing displaces capital-intensive server ownership. Long-term viability favors asset-light delivery models with recurring revenue streams over hardware-dependent depreciation cycles. Acquisition target archetype: domestic vendors with pre-certified BIS alignment and existing Bundesrechenzentrum GmbH contract relationships. Monitor ENISA certification scheme publication as inflection signal for procurement eligibility restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Investment | Pre-emptive BIS alignment secures Bundesrechenzentrum GmbH procurement cycles before ENISA criteria harden. |
| Edge-as-a-Service Platform Launch | Consumption-based financing captures Tyrolean manufacturing CFO procurement authority from traditional IT operations. |
| AI Governance Tooling Integration | EU AI Act technical file automation addresses Vienna hospital radiology department post-market monitoring obligations. |
| 5G MEC Partnership Expansion | A1 Telekom Austria AG fiber infrastructure enables Carinthian semiconductor packaging federated learning deployments. |
| Legacy Modernization Services Acquisition | COBOL-to-API transition capabilities unlock provincial government agency parallel-run modernization budgets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC hyperscaler filings, ECB supervisory disclosure frameworks, and Austrian federal procurement databases. Primary interviews engaged cloud infrastructure architects, federal IT procurement officers at Bundesrechenzentrum GmbH, healthcare CIOs managing ELGA interoperability mandates, and cybersecurity channel partners serving Styrian manufacturing clusters. Bottom-up triangulation across vendor revenue disclosures and top-down reconciliation against national ICT expenditure surveys validate market sizing.
Segmentation dimensions modeled span solution type, end user vertical, technology application, and regional adoption pattern across the analysis window. Deployment complexity tiers and compliance certification depth further differentiate forecast outputs. CAGRs derive from elasticity-adjusted expenditure projections incorporating EU AI Act implementation timelines and federal digitization program budget allocations. Confidential computing regulatory recognition and sovereign cloud mandate expansion serve as scenario-weighting inputs.
Decision-makers should treat outputs as directional under sustained EU regulatory harmonization and stable federal procurement commitment assumptions; material deviation would warrant model refresh. Specific risk factors include ENISA certification scheme acceleration, hyperscale data residency zone expansion, and intergenerational workforce transition bottlenecks. Recalibration cycles align with material shifts in EU AI Act enforcement thresholds and Bundesrechenzentrum GmbH specification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
TD-LTE Ecosystem Market
Telecommunications
Asia-Pacific IPTV Market
Telecommunications
Bangladesh Telecommunication Industry Market
Telecommunications
Global LTE Market
Telecommunications
Asia Pacific Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Iran Telecom Market
Telecommunications
Canada Hosted PBX Market
Telecommunications
United Arab Emirates Telecom Market
Telecommunications
Global Hosted PBX Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
IP DECT Phones Market
Telecommunications
Brazil Telecom Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Global IP Phone Market
Telecommunications
Smart SIM Market
Telecommunications
MVNO Market