
 Service Mesh Market | 2026-2036
Service Mesh Market Size, Share, and Industry Trends Forecast 2026-2036
Service Mesh Market Outlook
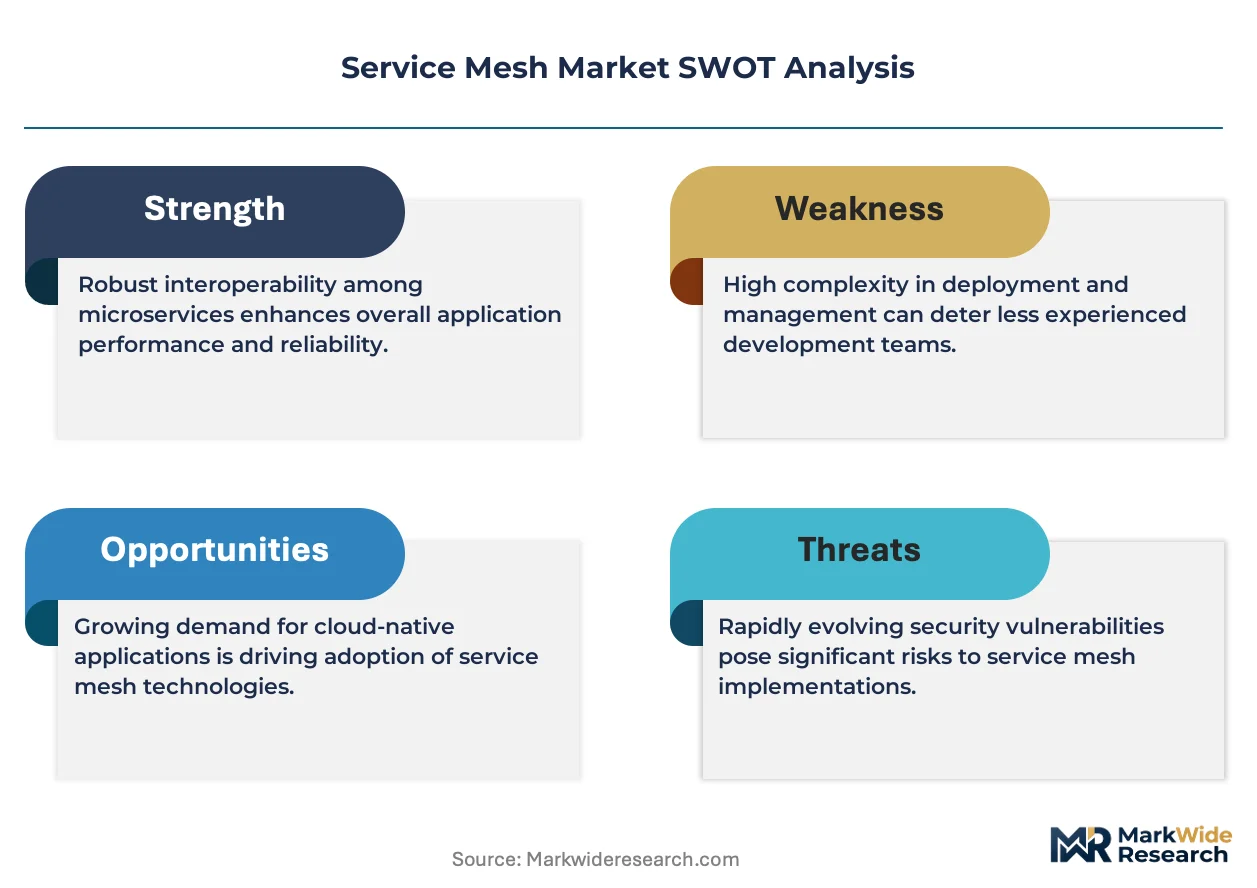
Cloud infrastructure investment from hyperscale providers in the United States is shifting toward dedicated service mesh engineering teams. Buoyant sustains technology leadership through its Linkerd-focused specialization in lightweight, security-optimized data planes. HashiCorp Inc. leverages its Consul platform to anchor enterprise adoption across hybrid cloud footprints. Solo.io competes by extending Istio's capabilities with developer-centric tooling for multi-cluster environments.
Service mesh denotes a dedicated infrastructure layer that manages service-to-service communication through sidecar proxies, typically operating at Layer 4/7 with support for mTLS encryption, traffic splitting, and observability telemetry. Its primary purpose is to decouple networking logic from application code, enabling resilient microservices orchestration without source modification. Public cloud deployment dominates volume as enterprises migrate containerized workloads to managed Kubernetes services, while hybrid cloud configurations capture disproportionate margin pools from regulated industries requiring data residency controls. API gateway and service discovery components within the service type dimension lead adoption curves, though circuit breaker functionality is accelerating fastest among latency-sensitive financial applications.
FCC guidelines on communications infrastructure security intersect with NIST zero-trust architecture mandates to shape procurement specifications for federal service mesh deployments. The EU AI Act and GDPR impose cross-border data governance requirements that filter into product roadmaps through automated policy enforcement features. Enterprises must evaluate sidecar versus sidecar-less architectural models against their specific compliance jurisdictions and operational complexity thresholds.
Market Dynamics
Zero-trust security mandates from federal agencies and the EU AI Act are compressing procurement cycles for service mesh infrastructure, forcing enterprises to embed policy enforcement directly into data plane architectures rather than retrofitting compliance later.
Growth Catalysts
- NIST Zero-Trust Architecture:Federal agencies in the United States now require mTLS encryption and identity-aware proxies for all containerized workloads, accelerating service mesh deployment across defense contractors and civilian departments.
- Financial Services Microservices Density:High-frequency trading platforms and payment processors in New York and London are adopting sidecar proxies to manage east-west traffic without application code changes.
- EU AI Act Cross-Border Data Rules:Automated policy enforcement features in service meshes enable enterprises to tag and route AI training data according to GDPR residency requirements.
Market Restraints
- Specialized Engineering Talent Scarcity:Envoy proxy configuration expertise and Istio control plane management skills command premium compensation, inflating implementation costs for mid-market enterprises.
- Sidecar Resource Overhead:Memory and CPU consumption from per-pod proxies constrains deployment density on edge nodes and resource-constrained IoT gateways.
- Hybrid Cloud Complexity:Multi-cluster federation across on-premises VMware Tanzu and Amazon EKS environments requires custom automation that extends deployment timelines.
Strategic Opportunities
- eBPF-Based Sidecar-Less Architectures:Kernel-level packet inspection technologies from Isovalent and Solo.io reduce latency overhead while maintaining observability telemetry.
- India's Digital Public Infrastructure:The country's account aggregator framework and open credit enablement network create demand for secure inter-service communication in fintech stacks.
- Platform Engineering Internal Marketplaces:Self-service mesh provisioning portals let developer teams consume networking capabilities without platform team bottlenecks.
Industry Challenges
- Control Plane Upgrade Coordination:Canary deployments of Istio or Linkerd versions across hundreds of clusters require sophisticated fleet management tooling that most enterprises lack.
- Certificate Rotation at Scale:Automated mTLS certificate lifecycle management fails silently in environments with heterogeneous PKI hierarchies and legacy Windows Certificate Authority integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Service Mesh Market |
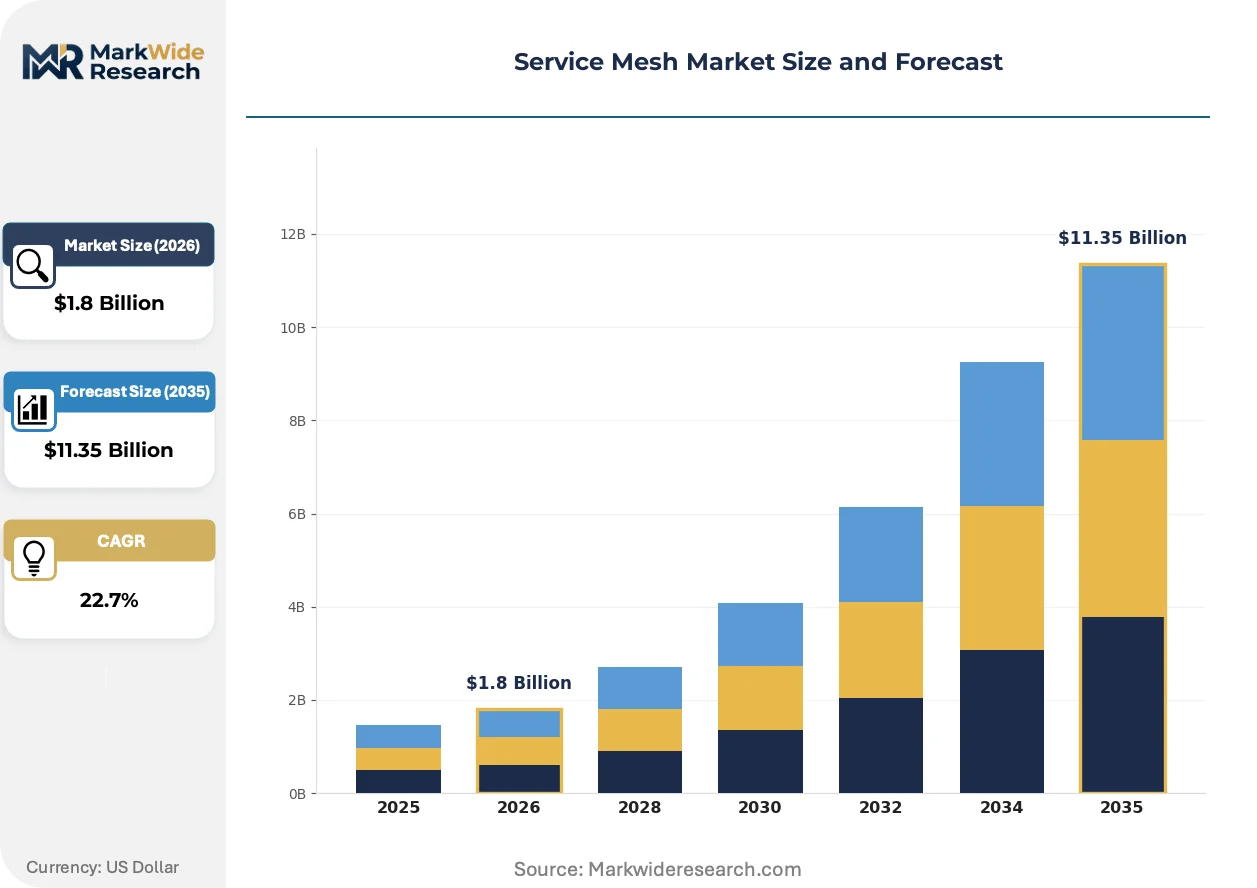
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: API Gateway, Load Balancer, Circuit Breaker, Service Discovery User Type: SMEs, Large Enterprises, Startups, Government Organizations Integration Level: Microservices, Monolithic, Serverless, Legacy Systems |
| Companies Covered | Kong Inc., Tetrate, Buoyant, Traefik Labs, Amazon Web Services, HashiCorp Inc., Solo.io, A10 Networks, F5, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Service Mesh Market Strategic Shifts
Service mesh architectures are fragmenting into competing implementation models as kernel-level networking advances challenge traditional sidecar assumptions. Vendors are racing to reduce operational burden while preserving security guarantees.
Gateway API standardization is automating traffic management configuration across Kubernetes clusters. Platform teams at cloud-native enterprises are replacing Ingress controllers with vendor-neutral resource definitions that abstract Envoy and NGINX implementations. This shift compresses the time required to expose services externally from days to minutes.
The EU AI Act's automated decision-system documentation requirements are reshaping observability investments. Financial institutions in Frankfurt and Paris are mandating distributed tracing retention policies that capture inference request provenance. Service mesh vendors are embedding OpenTelemetry collectors directly into data planes to satisfy these audit trails without application instrumentation.
Buyer preferences are hardening around managed control planes over self-hosted alternatives. Engineering leadership at Series C software companies are rejecting operational ownership of Istio upgrades and certificate authority maintenance. Amazon Web Services, Google Cloud, and Azure are capturing this demand through fully managed mesh offerings that bundle support into existing Kubernetes contracts.
Service Mesh Market Segmentation
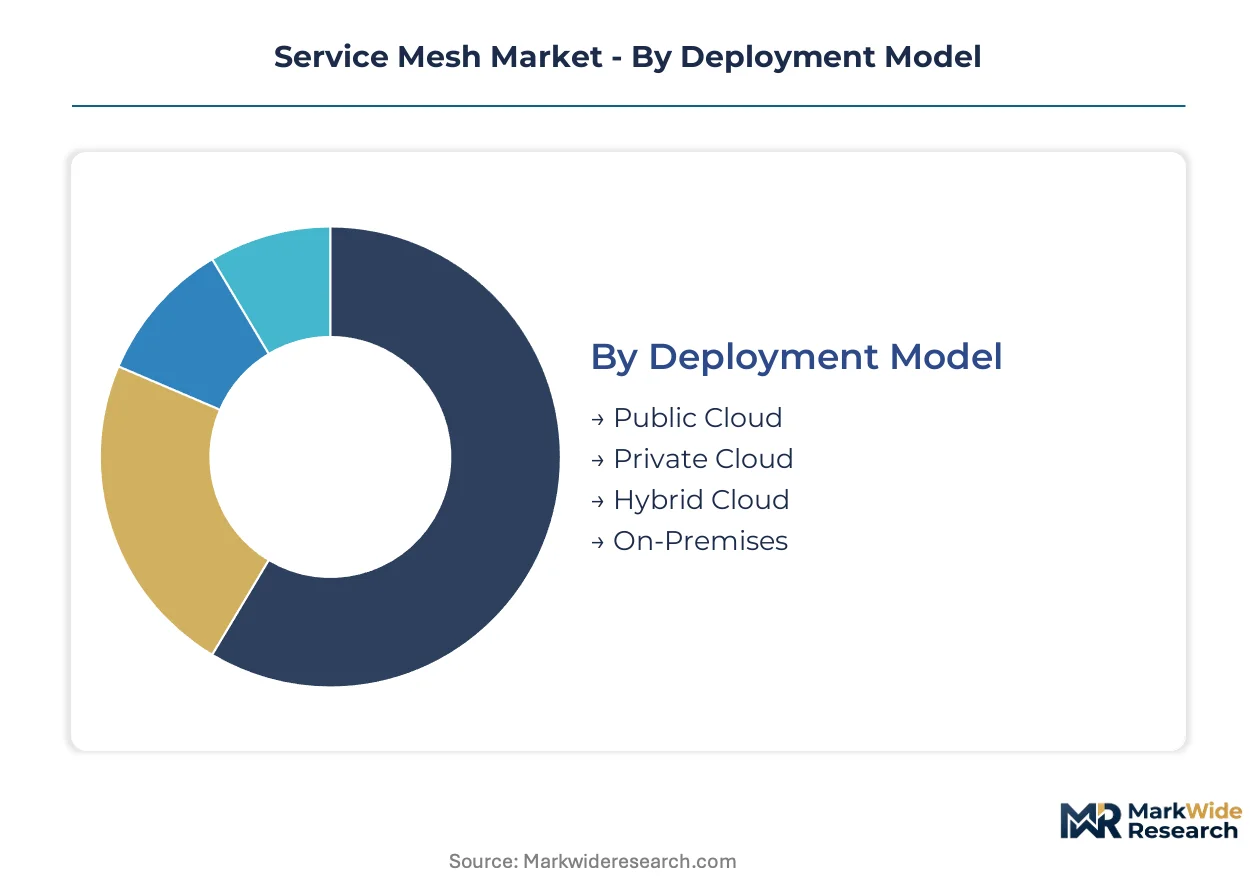
Service mesh procurement patterns diverge sharply across operational contexts. Deployment topology, architectural integration depth, and organizational scale each reshape vendor selection criteria and implementation complexity thresholds.
Deployment Model:
Standardization pressure intensifies as enterprises migrate from self-managed control planes toward hyperscale-managed offerings, yet regulatory data residency mandates preserve customization requirements in regulated sectors.
- Public Cloud:Managed control planes from AWS, Google Cloud, and Azure dominate procurement volume. Financial services firms in New York and London favor this model for rapid scaling of payment processing workloads without platform engineering overhead.
- Hybrid Cloud:Spanning on-premises VMware Tanzu and Amazon EKS environments, this architecture captures premium margins from defense contractors and EU banks requiring GDPR-compliant data sovereignty controls alongside burst capacity to public infrastructure.
- Private Cloud:Air-gapped deployments satisfy NIST zero-trust mandates for federal agencies and classified workloads. OpenShift Container Platform and Rancher Kubernetes Engine anchor most implementations.
- On-Premises:Bare-metal installations persist in manufacturing and energy sectors with legacy SCADA integration requirements. Custom Istio builds predominate.
Most installed capacity flows through Public Cloud deployments. Expansion is steepest in Hybrid Cloud configurations.
Service Type:
Functional specialization within the data plane correlates with application latency sensitivity and traffic pattern complexity.
- API Gateway:North-south traffic management with rate limiting and authentication offloading. Gateway API standardization is displacing Ingress controllers at cloud-native enterprises in Silicon Valley.
- Circuit Breaker:Automated failure isolation for cascading dependency protection. High-frequency trading platforms in Chicago and Frankfurt mandate sub-millisecond failover thresholds.
- Service Discovery:Dynamic endpoint registration for ephemeral workloads. Kubernetes-native DNS integration dominates though Consul maintains footholds in VM-heavy estates.
- Load Balancer:Layer 4/7 traffic distribution with health check integration. Envoy's weighted routing algorithms satisfy canary deployment requirements at scale.
API Gateway deployments constitute the largest installed base. Circuit Breaker functionality is climbing the fastest as financial services densify microservices architectures.
User Type:
Budget elasticity and compliance exposure segment buyer behavior across organizational scale and sector.
- Large Enterprises:Platform engineering teams with 50+ Kubernetes clusters demand fleet management automation and enterprise support SLAs. Fortune 500 technology and financial services companies anchor this segment.
- SMEs:Managed mesh offerings from cloud providers eliminate control plane operational burden. Series B software companies in Austin and Berlin prioritize developer velocity over customization.
- Government Organizations:FedRAMP authorization and IL5 certification requirements filter vendor pools. US Department of Defense and civilian agencies drive federal procurement specifications.
- Startups:Sidecar-less eBPF architectures from Isovalent and Solo.io reduce resource overhead for pre-revenue companies optimizing cloud spend.
Large Enterprises command the majority of current deployments. Startups are gaining share fastest as eBPF technologies lower operational barriers.
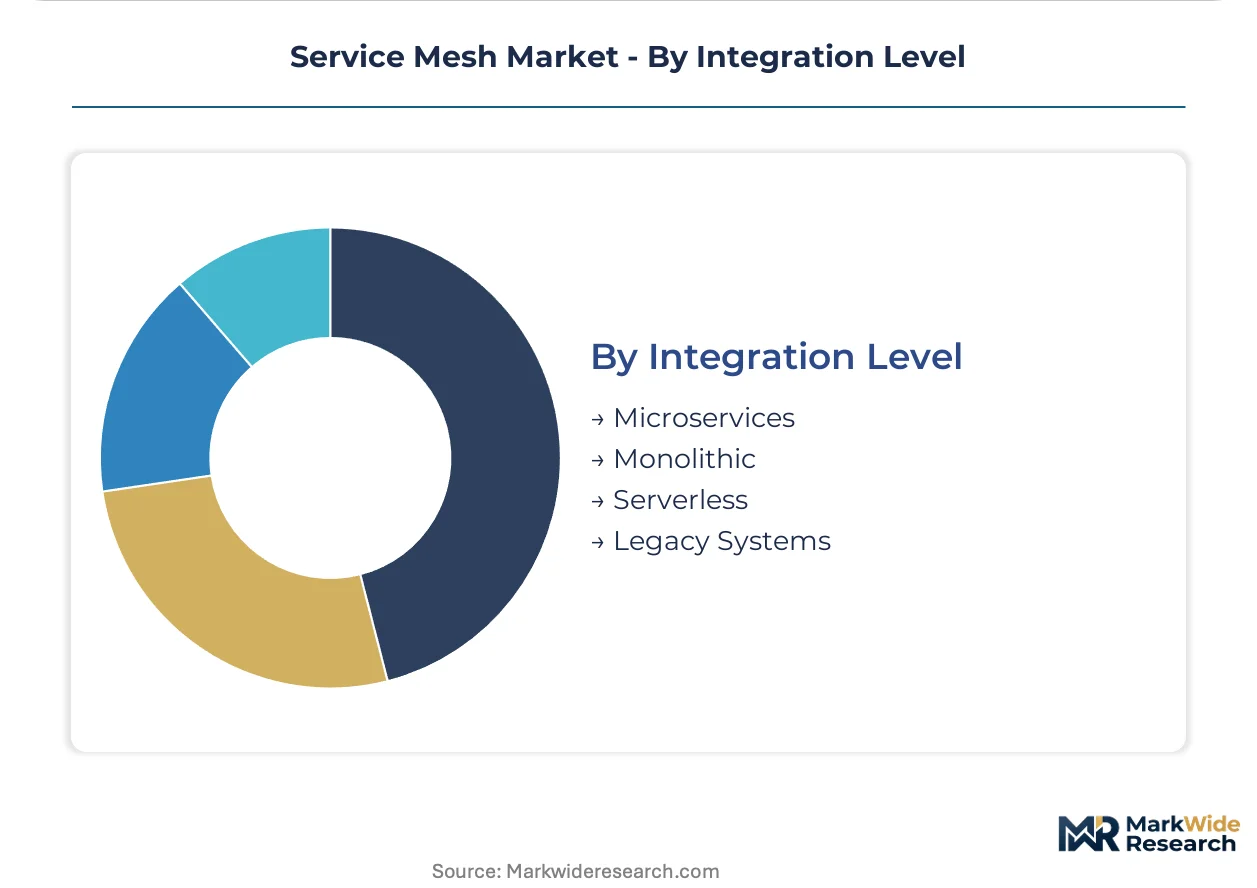
Integration Level:
Application modernization stage determines architectural compatibility requirements and migration pathway complexity.
- Microservices:Container-native sidecar injection with mTLS encryption by default. Cloud-native financial services and SaaS providers in San Francisco and Singapore standardize on this model.
- Serverless:Knative and AWS App Mesh integration for scale-to-zero workloads. Event-driven payment processors in Mumbai and São Paulo adopt this for cost optimization.
- Monolithic:Strangler fig patterns using mesh ingress to gradually decompose .NET and Java EE applications. European insurance conglomerates pursue this path.
- Legacy Systems:VM-based proxy deployment without Kubernetes orchestration. Mainframe-connected banking cores in Tokyo and Zurich require this bridge architecture.
Microservices integration anchors current deployment volume. Serverless mesh adoption is expanding most quickly as Knative matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping service mesh procurement patterns as enterprises relocate containerized workloads toward jurisdictions with clearer zero-trust compliance frameworks. The cost-of-compliance gap between fragmented national standards and unified federal mandates is accelerating cross-border infrastructure investment.
United States
NIST zero-trust architecture mandates and FCC communications security guidelines are compressing federal procurement cycles for mTLS-enabled service meshes. Defense contractors in Northern Virginia and civilian agencies in Washington D.C. are deploying air-gapped Linkerd and Istio configurations to satisfy FedRAMP authorization requirements. Silicon Valley cloud-native enterprises in San Francisco and San Jose are standardizing on managed control planes from hyperscale providers to eliminate operational overhead.
Germany
GDPR data residency requirements and the EU AI Act's automated decision-system documentation rules are driving demand for policy-enforced mesh architectures. Frankfurt's high-frequency trading infrastructure and Munich's automotive software clusters are adopting sidecar-less eBPF implementations to reduce latency while maintaining observability telemetry. The country's central bank is mandating distributed tracing retention for payment system audit trails.
United Kingdom
Post-Brexit data governance divergence from EU frameworks is creating hybrid compliance complexity for financial services firms. London's payment processors and Edinburgh's fintech clusters are deploying multi-cluster Istio federation to route AI training data according to evolving cross-border rules. The Financial Conduct Authority's operational resilience requirements are accelerating circuit breaker adoption for latency-sensitive trading platforms.
India
The Reserve Bank of India's account aggregator framework and the open credit enablement network are generating demand for secure inter-service communication in fintech stacks. Mumbai's payment infrastructure and Bangalore's SaaS providers are adopting lightweight service meshes to optimize cloud spend while satisfying data localization mandates. The country's central bank is tightening API security standards for digital lending platforms.
Singapore
Monetary Authority of Singapore guidelines on cloud risk management and technology outsourcing are shaping procurement specifications for regional banking headquarters. The city's wealth management technology clusters and maritime logistics software providers are deploying hybrid cloud mesh configurations to satisfy data sovereignty requirements across ASEAN operations. Singapore's regulator is mandating granular observability for systemically important payment infrastructures.
Service Mesh Market Competitive Environment
United States hyperscalers anchor the managed control plane tier; European and Indian specialists hold positions in lightweight data plane optimization and developer-centric tooling. The vendor structure fragments across three distinct capability layers: kernel-level networking innovators, enterprise platform consolidators, and cloud-native workflow optimizers. Two dominant competitive moves are reshaping positioning: strategic partnerships between mesh vendors and hyperscale Kubernetes providers, and technology licensing arrangements that embed proxy functionality into broader infrastructure stacks.
Within the cloud-native specialization tier, Buoyant and Solo.io exemplify divergent architectural philosophies. Buoyant occupies a position representing Linkerd-focused minimalism for security-optimized environments. Solo.io sits within the Istio-extension archetype, anchoring developer-centric multi-cluster tooling. HashiCorp Inc. represents the enterprise platform consolidation model, leveraging existing infrastructure automation relationships to anchor hybrid cloud mesh adoption across VMware and public cloud footprints.
| Leading Market Players |
|---|
| Kong Inc. |
| Tetrate |
| Buoyant |
| Traefik Labs |
| Amazon Web Services |
| HashiCorp Inc. |
| Solo.io |
| A10 Networks |
| F5, Inc. |
| Others |
Value Chain & Pricing Dynamics
Defense contractors and civilian agencies under NIST zero-trust mandates anchor pricing power for FedRAMP-authorized mesh configurations, compressing procurement cycles while sustaining premium tiers for air-gapped deployments.
Pricing Analysis
Direct-to-enterprise discounts dominate the channel structure, with hyperscale providers bundling managed control planes into existing Kubernetes contracts at volume-scaled rates. Pricing stratifies across FedRAMP-authorized premium tiers, standard cloud-managed offerings, and economy-grade open-source self-hosted options. Cost compression in the self-managed tier is intensifying because mid-market enterprises lack specialized Envoy configuration expertise. Series B software companies in Austin and Berlin exhibit highest price sensitivity, while Fortune 500 financial services firms prioritize SLA guarantees over unit economics.
Supply Chain Analysis
India's data localization mandates under RBI guidelines are reshaping sourcing patterns for fintech-focused mesh implementations, pushing vendors toward in-country engineering presence. Control plane development concentrates in the United States, Germany, and India, with kernel-level eBPF innovation centering on European specialists. Raw material dependencies include cloud compute instances, TLS certificate authority infrastructure, and observability telemetry pipelines. Single-source vulnerability in certificate rotation tooling creates systemic risk for heterogeneous PKI environments. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as zero-trust security mandates harden into procurement specifications across federal and financial services verticals.
For Market Incumbents: Hedge against eBPF-based sidecar-less disruption by embedding kernel-level packet inspection into managed control plane roadmaps. Acquire boutique eBPF engineering teams in Germany or India before talent scarcity inflates compensation premiums. Prioritize FedRAMP authorization maintenance as defense contractors consolidate vendor pools. For New Entrants and Emerging Players: Launch via India's account aggregator framework and open credit enablement network, where RBI data localization rules create protected demand for lightweight mesh architectures. Target Mumbai payment infrastructure and Bangalore SaaS providers with developer-centric tooling that eliminates platform engineering bottlenecks. Position against hyperscale bundling through transparent per-workload pricing. For Investors and Strategic Acquirers: Hyperscale cloud providers are the most active acquirers in this space, seeking to anchor managed mesh offerings within existing Kubernetes contracts. The five-to-ten year viability window favors platform engineering automation specialists over pure proxy vendors. Acquisition target archetypes include eBPF kernel networking innovators and multi-cluster fleet management tooling providers. The signal to watch is canary deployment coordination tooling adoption across Fortune 500 platform engineering teams.| Strategic Initiative | Industry Significance |
|---|---|
| Sidecar-Less eBPF Migration | Kernel-level packet inspection from Isovalent and Solo.io reduces latency overhead for Frankfurt trading platforms. |
| FedRAMP Authorization Investment | Air-gapped Linkerd and Istio configurations satisfy NIST mandates for Northern Virginia defense contractors. |
| Multi-Cluster Fleet Management | Platform engineering teams at Series C software companies reject operational ownership of control plane upgrades. |
| India Market Engineering Presence | RBI account aggregator framework creates localized demand for secure inter-service communication in fintech stacks. |
| OpenTelemetry Collector Embedding | EU AI Act audit trail requirements push Frankfurt and Paris financial institutions toward distributed tracing retention policies. |
Study Parameters
Bottom-up platform engineering deployment modeling reconciled against top-down hyperscale capex tracking forms the analytical core of this study. Primary interviews with CTOs, platform engineering directors, Kubernetes cluster operators, and cloud procurement officers informed segmentation assumptions. Secondary validation drew from SEC 10-K filings, hyperscaler infrastructure investment disclosures, NIST zero-trust architecture publications, and EU AI Act implementation guidance. Triangulation between self-reported enterprise deployment scales and vendor-reported control plane licensing volumes anchored volume estimates.
Input-output matrices map control plane provisioning rates against containerized workload density across deployment models, organization sizes, vertical sectors, integration complexity tiers, and regional regulatory clusters. CAGRs derive from segmented adoption curve fitting against compliance mandate enforcement timelines. Forecast inputs include NIST zero-trust procurement cycle compression rates and EU AI Act automated policy enforcement feature penetration across the analysis window.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated eBPF technology disruption or prolonged certificate rotation tooling fragmentation. Assumptions reflect current regulatory enforcement trajectories and hyperscale managed service bundling strategies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Kubernetes Solutions Market
Digital Solutions
Hiking Apps Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Global Data Collection and Labeling Market
Digital Solutions
Dating Services Market
Digital Solutions
Advanced Process Control (APC) and Online Optimization Market
Digital Solutions
Location-Based Services (LBS) Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Global DDI Market
Digital Solutions
Cloud MFT Services Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
Global Commerce Cloud Solution Market
Digital Solutions
Route Optimization Software Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Enterprise Manufacturing Intelligence Market
Digital Solutions
Contactless Ticketing Solutions Market