
 Mainframe Modernization Services Market | 2026-2036
Mainframe Modernization Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mainframe Modernization Services Market Outlook
India's services corridor is reshaping delivery capacity for mainframe modernization, with Bangalore and Hyderabad expanding technical workforce pools for legacy-to-cloud transitions. IBM Corporation leverages its zSystems hardware heritage and proprietary compiler technology to sustain entrenched relationships with Fortune 500 accounts. Accenture anchors its position through proprietary automation frameworks that accelerate COBOL-to-Java conversion timelines. HCLTech competes aggressively on price-performance ratios for managed mainframe operations across North American banking clients.
Mainframe modernization services encompass the assessment, migration, refactoring, and operational transformation of legacy centralized computing environments, typically involving the conversion of COBOL, PL/I, and Assembler codebases to distributed or cloud-native architectures while preserving transactional integrity through emulation layers or API encapsulation. The primary purpose is to extend the functional lifespan of mission-critical business logic while reducing dependency on scarce specialized skills and proprietary hardware maintenance contracts. Rehosting services currently dominate transaction volumes as banks seek risk-minimized lift-and-shift pathways, though rearchitecting engagements command substantially higher margin pools due to custom engineering intensity. Cloud deployment models are expanding fastest as hyperscaler partnerships enable mainframe-compatible runtime environments, while hybrid configurations retain stronghold status among institutions with regulatory latency constraints.
The EU Digital Operational Resilience Act mandates stringent ICT risk management protocols that directly accelerate mainframe replacement timelines for European financial institutions. In the United States, the Federal Financial Institutions Examination Council maintains examination standards that implicitly penalize concentration in unsupported legacy platforms, while NIST cybersecurity frameworks shape technical specifications for modernized environments. Stakeholders must monitor evolving mainframe-compatible containerization standards and assess whether skill scarcity in COBOL and JCL will force accelerated replacement timelines or sustain rehosting demand.
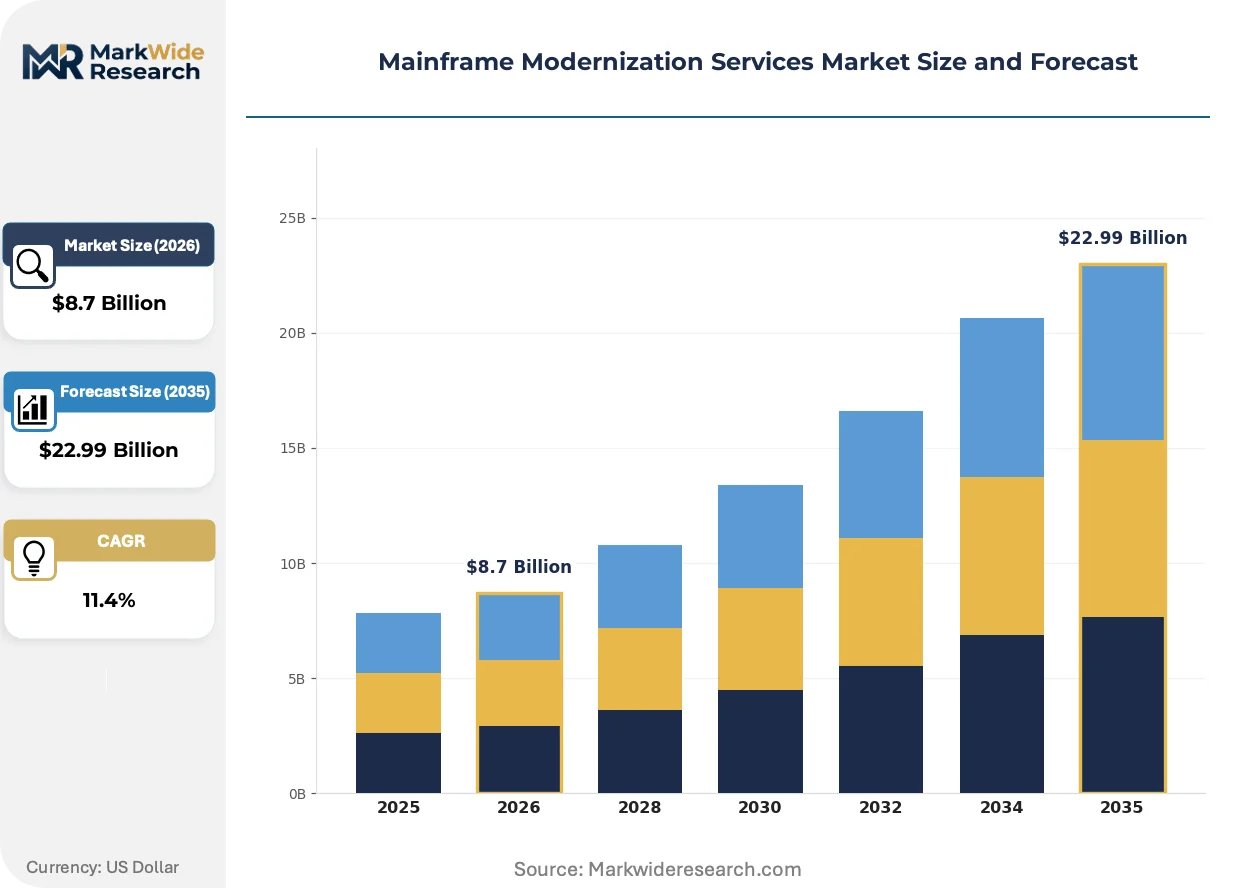
Market Dynamics
Cloud-native containerization is collapsing the traditional rehosting-rearchitecting divide, forcing service providers to engineer hybrid delivery models that preserve IBM zSystems transactional integrity while enabling hyperscaler elasticity.
Growth Catalysts
- EU Digital Operational Resilience Act:European banking regulators now mandate ICT risk management protocols that explicitly penalize unsupported legacy infrastructure, compelling institutions to accelerate replacement timelines.
- COBOL-to-Java automation tooling:Proprietary compiler frameworks from established vendors have compressed conversion project durations from multi-year engagements to 12-18 month execution windows.
- Federal banking examination standards:The Federal Financial Institutions Examination Council in the United States implicitly disadvantages concentration in end-of-life platforms during supervisory reviews.
Market Restraints
- Scarce JCL and Assembler expertise:The contracting talent pool for proprietary IBM mainframe languages inflates labor rates and extends project timelines for complex refactoring engagements.
- Hardware maintenance contract lock-in:IBM zSystems proprietary firmware and microcode dependencies create switching costs that delay full cloud migration decisions.
- Transactional integrity verification:Mission-critical financial workloads require exhaustive regression testing that adds 30-40% overhead to modernization project budgets.
Strategic Opportunities
- API encapsulation services:Financial institutions in Germany and France are prioritizing incremental modernization pathways that expose legacy COBOL business logic through REST interfaces without full codebase replacement.
- Hyperscaler mainframe runtime partnerships:Cloud providers are engineering zSystems-compatible execution environments that enable lift-and-shift migration without hardware dependency.
- Regulatory latency arbitrage:Institutions with complex cross-border compliance requirements are adopting hybrid configurations that retain on-premise transaction processing for sensitive data while offloading analytics workloads.
Industry Challenges
- Skill pipeline collapse:University computer science programs have eliminated COBOL and PL/I curricula, forcing service providers to rely on internal apprenticeship models for legacy language competency.
- Parallel run validation:Banking regulators require extended dual-system operation periods that strain operational budgets and delay decommissioning of legacy hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mainframe Modernization Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Rehosting, Refactoring, Rearchitecting, Replacing Deployment Model: On-Premises, Cloud, Hybrid, Managed Services End User Type: Government, Banking, Insurance, Healthcare Technology: Containerization, Microservices, API Management, DevOps |
| Companies Covered | Capgemini, Wipro, DXC Technology, Infosys Limited, HCLTech, Accenture, Cognizant, TATA Consultancy Services, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mainframe Modernization Services Market Strategic Shifts
Containerization standards are rewriting the technical architecture of mainframe migration, enabling modular decomposition of monolithic COBOL applications into microservices without full codebase reconstruction.
Emulation-layer technology is collapsing the distinction between rehosting and rearchitecting approaches by enabling IBM zSystems workloads to execute on standard x86 cloud infrastructure with near-native performance characteristics. Major North American banks are piloting these environments for non-production workloads before committing production transaction processing. The structural consequence is compression of vendor lock-in duration from decade-long hardware cycles to renewable software licensing terms.
The EU Digital Operational Resilience Act has established mandatory ICT risk management frameworks that directly accelerate mainframe replacement timelines for European financial institutions. Supervisory authorities now require documented exit strategies from unsupported legacy platforms as a condition of operating authorization. Asset managers and insurance carriers in France, Germany, and the Netherlands are responding with dedicated transformation budgets and board-level oversight of modernization roadmaps.
Buyer procurement patterns are fragmenting from single-vendor transformation contracts toward modular service unbundling that separates assessment, migration execution, and post-transition managed services. Large commercial banks in the United States are increasingly sourcing refactoring engineering from Indian delivery centers while retaining domestic vendors for regulatory compliance and production support. This geographic disaggregation of service procurement is most visible among Fortune 500 institutions with established captive offshore development centers.
Mainframe Modernization Services Market Segmentation
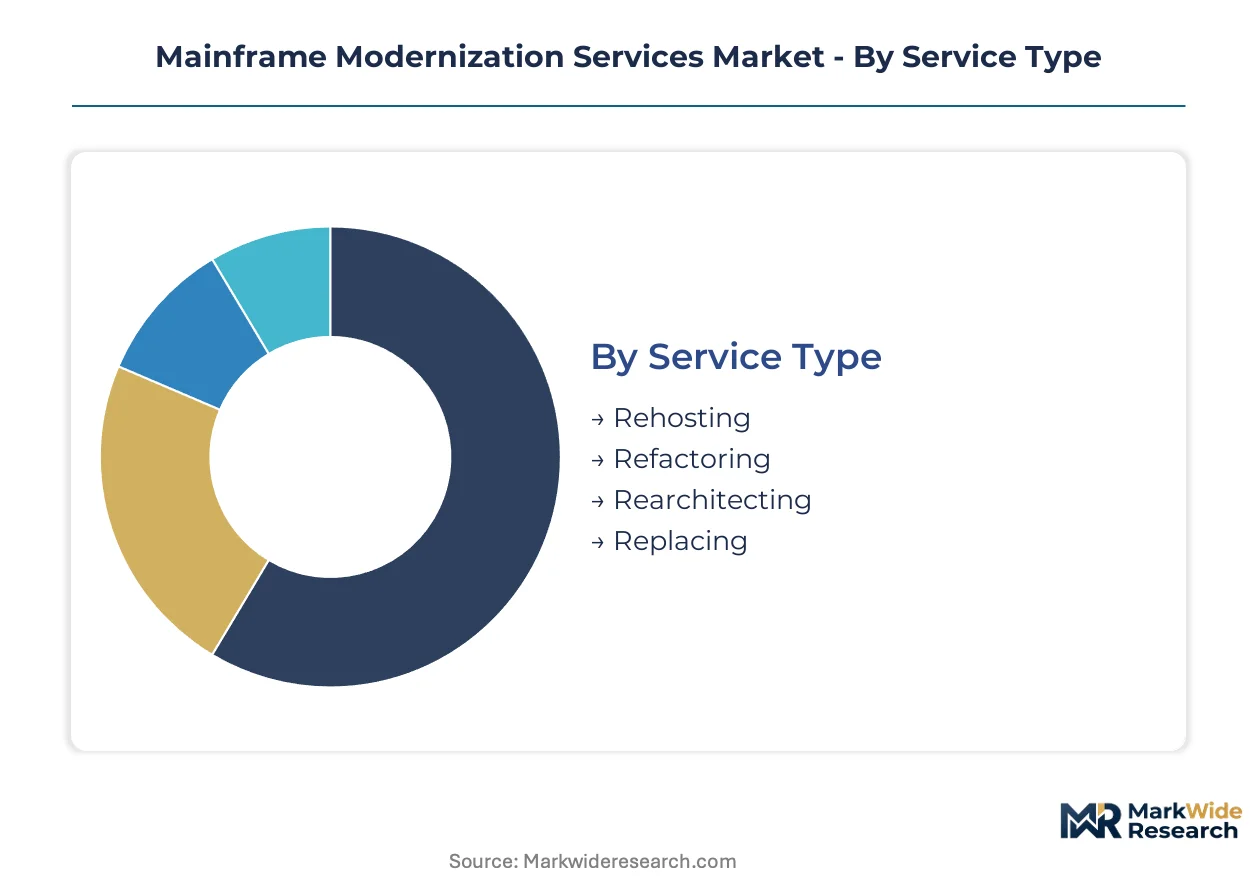
Mainframe modernization services fragment across four critical dimensions that determine project scope, delivery complexity, and commercial structure. Service type governs technical approach and margin profile. Deployment model shapes infrastructure ownership and regulatory exposure. End user concentration drives demand timing and procurement patterns. Technology selection determines workforce requirements and partner ecosystem dependencies.
Service Type:
Cost tier differentiation separates risk-averse lift-and-shift pathways from engineering-intensive transformation engagements.
- Rehosting:Emulation-layer migration preserves COBOL bytecode execution on x86 or cloud infrastructure without source code modification. United States federal agencies prioritize this pathway to minimize regression testing overhead and maintain audit trail continuity for mission-critical entitlement systems.
- Refactoring:Automated language translation converts COBOL, PL/I, and Assembler to Java or C# while preserving business logic structure. North American commercial banks concentrate procurement here as compressed timelines align with hardware maintenance contract renewal cycles and examiner pressure on legacy concentration.
- Rearchitecting:Decomposition of monolithic applications into cloud-native microservices with full codebase reconstruction.
- Replacing:Complete retirement of legacy systems in favor of packaged software or SaaS alternatives.
Rehosting holds installed capacity. Refactoring is rotating up the share rankings.
Deployment Model:
Application criticality and data sovereignty requirements determine infrastructure location and operational control distribution.
- Cloud:Hyperscaler-hosted execution environments enable elastic capacity scaling and consumption-based economics. European banking institutions under EU Digital Operational Resilience Act mandates are expanding cloud procurement fastest as supervisory authorities require documented exit strategies from unsupported on-premise platforms.
- Hybrid:Split workload architecture retains transaction processing on controlled infrastructure while offloading analytics and development to cloud. German and French asset managers favor this model to satisfy cross-border regulatory latency constraints without full data center consolidation.
- On-Premises:Modernized systems deployed within client-controlled data centers.
- Managed Services:Third-party operational responsibility for modernized infrastructure.
Hybrid configurations hold installed capacity. Pure cloud deployment is rotating up the share rankings.
End User Type:
Customer type segmentation reflects regulatory intensity, system complexity, and budget scale variations across institutional categories.
- Banking:Core banking, payments, and lending platforms with highest modernization urgency due to examiner scrutiny and competitive pressure from fintech challengers. United States commercial banks and European universal banks drive transaction volumes as hardware maintenance costs and skill scarcity compound operational risk.
- Insurance:Policy administration and claims processing systems with complex actuarial calculations embedded in legacy code. French and Dutch carriers are accelerating transformation timelines under DORA-mandated board-level oversight of ICT risk management.
- Government:Federal and state entitlement, tax, and benefits administration systems.
- Healthcare:Claims processing and patient record management platforms.
Banking holds installed capacity. Insurance is rotating up the share rankings.
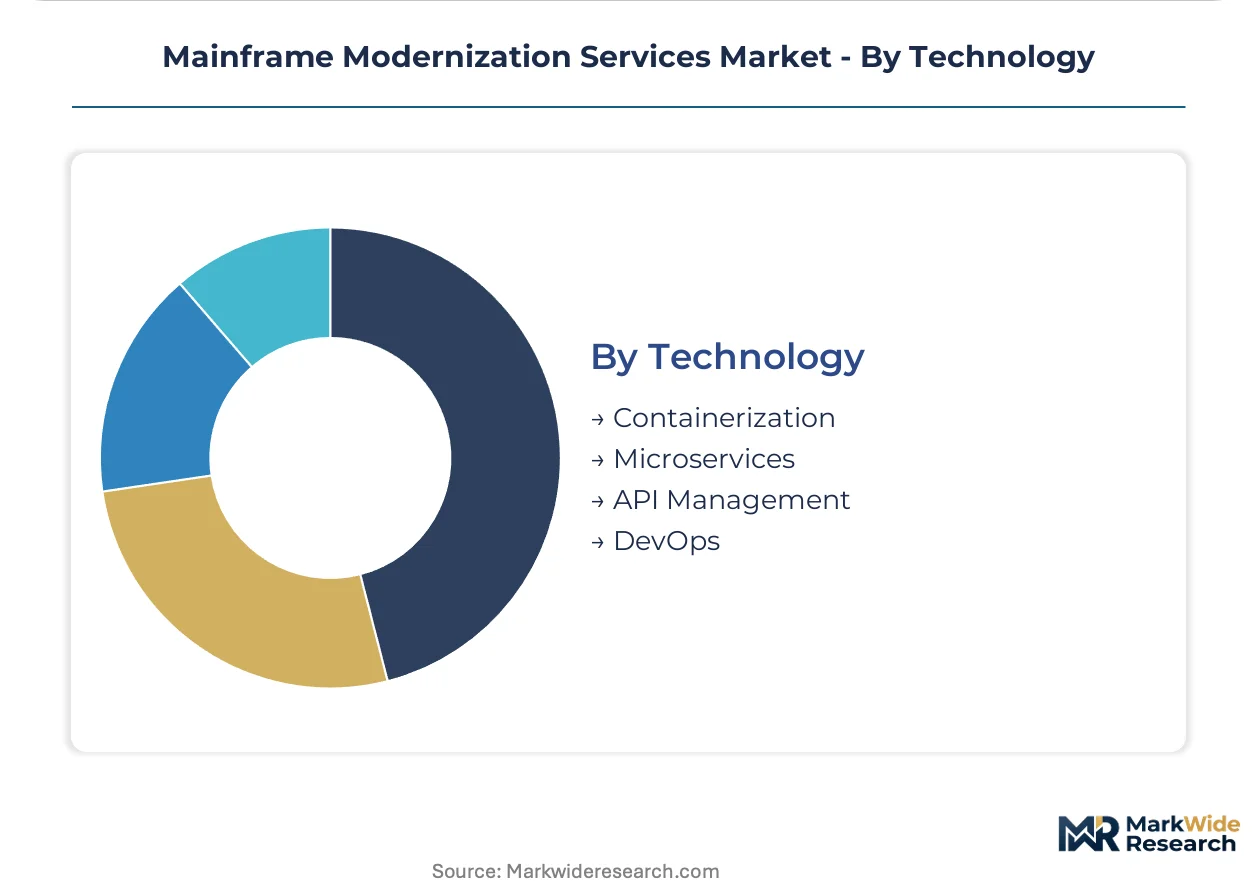
Technology:
Technology selection governs architectural flexibility, integration complexity, and vendor dependency structure.
- Containerization:Docker and Kubernetes orchestration of legacy application components enables modular deployment without full rearchitecting. Bangalore and Hyderabad delivery centers are building specialized practices around containerized mainframe workload migration for North American banking clients.
- API Management:REST and GraphQL interface layers expose legacy business logic to modern channel applications without codebase replacement. German financial institutions prioritize this pathway for incremental modernization that defers full transformation capital commitment.
- Microservices:Fine-grained service decomposition of monolithic applications.
- DevOps:Continuous integration and deployment pipelines for modernized codebases.
API Management holds installed capacity. Containerization is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IBM zSystems hardware heritage concentrates delivery capacity in the United States, where federal agencies and commercial banks maintain the world's largest installed base. Service providers have built technical workforce pools in Bangalore and Hyderabad to support legacy-to-cloud transitions for North American banking clients.
United States
The Federal Financial Institutions Examination Council implicitly disadvantages concentration in end-of-life platforms during supervisory reviews. Commercial banks in New York and Chicago drive refactoring procurement as compressed timelines align with hardware maintenance contract renewal cycles. Federal agencies prioritize rehosting pathways to minimize regression testing overhead for mission-critical entitlement systems.
Germany
Asset managers and insurance carriers in Frankfurt and Munich are accelerating transformation timelines under EU Digital Operational Resilience Act-mandated board-level oversight. The Federal Financial Supervisory Authority requires documented exit strategies from unsupported legacy platforms as a condition of operating authorization. German institutions favor hybrid configurations to satisfy cross-border regulatory latency constraints without full data center consolidation.
India
Bangalore and Hyderabad delivery centers are expanding technical workforce pools for legacy-to-cloud transitions and building specialized practices around containerized mainframe workload migration. The Reserve Bank of India's cybersecurity guidelines shape technical specifications for modernized banking environments. Indian service providers compete aggressively on price-performance ratios for managed mainframe operations across North American banking clients.
France
French universal banks and insurance carriers are responding to DORA mandates with dedicated transformation budgets and board-level oversight of modernization roadmaps. The Autorité de Contrôle Prudentiel et de Résolution enforces stringent ICT risk management protocols that penalize unsupported legacy infrastructure. Paris-based financial institutions prioritize API encapsulation services for incremental modernization that defers full transformation capital commitment.
United Kingdom
London-based commercial banks concentrate procurement in refactoring engagements as examiner pressure on legacy concentration intensifies. The Prudential Regulation Authority maintains examination standards that implicitly penalize concentration in unsupported platforms. UK institutions are sourcing refactoring engineering from Indian delivery centers while retaining domestic vendors for regulatory compliance and production support.
Mainframe Modernization Services Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with proprietary automation tooling. The vendor base organizes around three strategic archetypes: global consulting firms with proprietary compiler frameworks, India-headquartered services providers with price-competitive delivery models, and hardware incumbents leveraging entrenched client relationships. Competitive dynamics center on M&A activity to acquire automation IP and strategic partnerships with hyperscalers to enable mainframe-compatible runtime environments.
Within the global consulting tier, Accenture and Capgemini exemplify platform integrators that anchor transformation engagements through proprietary automation frameworks. HCLTech and TATA Consultancy Services represent the India-based delivery archetype, occupying positions that compete aggressively on price-performance ratios for managed operations. IBM Corporation sits within the hardware heritage tier, sustaining relationships through proprietary compiler technology and zSystems firmware dependencies that create structural switching costs.
| Leading Market Players |
|---|
| Capgemini |
| Wipro |
| DXC Technology |
| Infosys Limited |
| HCLTech |
| Accenture |
| Cognizant |
| TATA Consultancy Services |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on IBM zSystems firmware and microcode creates structural switching costs that compress margin pools for service providers while inflating hardware maintenance contract values for end users. The EU Digital Operational Resilience Act and Federal Financial Institutions Examination Council standards together determine pricing tier spreads by mandating documented exit strategies that accelerate rehosting procurement timelines.
Pricing Analysis
The EU Digital Operational Resilience Act dictates the pricing tier structure by penalizing unsupported legacy infrastructure concentration and compelling European institutions toward premium rearchitecting engagements. Three-tier pricing structure across premium, standard, and economy levels separates full codebase transformation from emulation-layer rehosting from managed operations-only contracts. Price differentiation hinges on automation tooling maturity and regulatory compliance bundling. Cost compression in standard-tier refactoring is intensifying because proprietary compiler frameworks from established vendors have compressed project durations. Mid-tier North American commercial banks exhibit highest price sensitivity due to examiner pressure alignment with hardware renewal cycles, while federal agencies prioritize audit trail continuity over cost optimization.
Supply Chain Analysis
Tariff exposure between the United States and India dominates supply chain risk as service procurement fragments across geographic delivery centers. Workforce concentration in Bangalore and Hyderabad draws from domestic computer science graduates and internal apprenticeship pipelines for COBOL and JCL competency. Raw material dependencies rest on IBM proprietary compiler licenses, hyperscaler cloud infrastructure, and scarce legacy language expertise. Single-source vulnerability in IBM zSystems firmware creates structural lock-in that delays full migration decisions. Distribution runs through direct enterprise sales channels for transformation engagements and partner-led managed services for ongoing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mainframe modernization services market sits in a cyclical recovery phase driven by regulatory mandate acceleration across European and North American banking jurisdictions. Hardware maintenance contract renewal cycles and examiner pressure on legacy concentration create predictable demand waves.
For Market Incumbents: Pre-empt margin erosion in standard-tier refactoring by acquiring proprietary automation IP that compresses COBOL-to-Java conversion timelines. Deepen backward integration into compiler technology to reduce dependency on IBM licensing structures. Establish captive delivery capacity in Indian technical workforce pools before competitor expansion saturates Bangalore and Hyderabad talent markets.
For New Entrants and Emerging Players: API encapsulation services for German and French asset managers represent the most penetrable entry point, offering incremental modernization pathways without full transformation capital commitment. Containerized mainframe workload migration for mid-tier North American banks provides a second white-space target with lower incumbent saturation. Lead with hyperscaler partnership credentials to bypass IBM hardware heritage barriers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with proprietary automation frameworks over pure-play staffing models. Long-term viability over the next decade hinges on containerization standard adoption and regulatory mandate durability. Monitor EU Digital Operational Resilience Act enforcement intensity across French and German supervisory authorities as the primary inflection indicator for European demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Automation IP | Proprietary compiler frameworks from established vendors compress COBOL-to-Java conversion timelines from multi-year to 12-18 month windows. |
| Hyperscaler Partnership Formation | Cloud providers engineering zSystems-compatible execution environments enable lift-and-shift migration without hardware dependency lock-in. |
| Indian Delivery Center Expansion | Bangalore and Hyderabad technical workforce pools support legacy-to-cloud transitions for North American banking clients at price-competitive ratios. |
| API Encapsulation Service Launch | German and French financial institutions prioritize REST interface layers that expose legacy COBOL logic without full codebase replacement. |
| Regulatory Compliance Bundling | EU Digital Operational Resilience Act mandates create board-level oversight requirements that accelerate procurement of documented exit strategies. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with banking transformation executives, federal agency IT directors, service provider delivery heads, and regulatory compliance officers. Secondary validation drew from SEC 10-K filings, EU regulatory mandate documentation, hyperscaler partnership announcements, and IBM zSystems hardware disclosure data. Bottom-up project pipeline analysis triangulated against top-down market sizing from installed base estimates and maintenance contract renewal patterns.
Calibration against historical conversion project timelines and regulatory implementation schedules anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, deployment model, end user category, and technology selection with regional regulatory cluster overlay. CAGRs were derived from trajectory fitting to documented transformation budget allocations and examiner pressure intensity indices. Workforce scarcity metrics and containerization standard maturity served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting bank capital expenditure budgets or geopolitical friction affecting Indian delivery center access would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and proprietary automation tooling advancement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America Digital Pen Market
Digital Solutions
Electronic Records Management Solutions Market
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Global Interactive Voice Response Market
Digital Solutions
Global Service Delivery Platform Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
Product Data Management Market
Digital Solutions
Cloud Electronic Design Automation Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Global Cloud Supply Chain Management Market
Digital Solutions
UAE ICT Market
Digital Solutions
Global Data Quality Tool Market
Digital Solutions
Bahrain ICT Market
Digital Solutions
System Integration Market
Digital Solutions
Global E-Signature Platform Market