
 Chatbot Market | 2026-2036
Chatbot Market Size, Share, and Industry Trends Forecast 2026-2036
Chatbot Market Analysis
The pool of engineers proficient in large language model fine-tuning and retrieval-augmented generation is collapsing relative to enterprise demand, creating a talent bottleneck that favors well-capitalized incumbents. OpenAI leverages its first-mover position in generative AI to anchor premium pricing for API access and enterprise licensing. Google sustains competitive pressure through deep integration of its Bard and Gemini technologies across Workspace and Cloud infrastructure. Microsoft dominates the enterprise deployment channel by embedding Copilot throughout Office 365 and Dynamics, converting existing software relationships into conversational AI adoption.
A chatbot is a software application that simulates human conversation through text or voice interfaces, typically employing natural language processing engines with transformer architectures, token context windows exceeding 100,000 tokens, and retrieval-augmented generation to ground responses in proprietary knowledge bases. Its primary commercial purpose is automating interactive tasks—customer inquiry resolution, appointment scheduling, transactional support—that previously required human labor. Cloud-based deployment leads the market in revenue contribution due to lower infrastructure barriers and faster scaling, while AI-driven technology segments capture the fastest growth as rule-based systems lose share to neural approaches. Customer support applications currently occupy the largest share of end-user spending, though lead generation is emerging as a higher-margin use case where conversion attribution justifies premium pricing.
The EU AI Act classifies chatbots deployed in high-risk domains such as healthcare and credit scoring as subject to conformity assessments, transparency obligations, and human oversight mandates, directly shaping product roadmaps for vendors seeking European market access. In the United States, the FTC has signaled intensified scrutiny of deceptive AI claims and algorithmic bias in consumer-facing automated systems, while HIPAA governs chatbot interactions handling protected health information. Stakeholders must monitor evolving jurisdictional fragmentation in AI governance, as divergent compliance requirements between Brussels and Washington threaten to segment the addressable market by regulatory compatibility rather than technical capability alone.
Market Dynamics
Transformer architectures with expanded context windows are compressing competitive differentiation in conversational AI, forcing vendors to compete on retrieval-augmented generation implementation and proprietary knowledge integration rather than base model capability alone.
Growth Catalysts
- EU AI Act compliance mandates:High-risk deployment classifications in healthcare and credit scoring create captive demand for auditable, human-in-the-loop chatbot architectures that meet conformity assessment requirements.
- Retrieval-augmented generation maturation:Vector database integration with large language models enables enterprise buyers to ground responses in proprietary documentation, reducing hallucination risk in regulated industries.
- Fortune 500 customer support automation:Labor cost pressures in banking, retail, and telecommunications operations are accelerating replacement of tier-one human agents with conversational AI handling routine inquiries.
Market Restraints
- GPU compute cost volatility:Training and inference workloads for billion-parameter models remain tethered to NVIDIA datacenter supply allocations, creating margin pressure for API-first vendors.
- Jurisdictional fragmentation:Divergent algorithmic accountability requirements between Brussels and Washington threaten to segment product roadmaps, raising engineering overhead for multi-territory deployments.
- Rule-based system substitution:Simple intent-classification chatbots with deterministic response trees satisfy low-complexity use cases at fraction of neural system cost, capping addressable market expansion.
Strategic Opportunities
- Lead generation application expansion:Conversion attribution capabilities in conversational interfaces justify premium pricing models unavailable in cost-center customer support deployments.
- Voice-to-text multimodal convergence:Integration of automatic speech recognition with generative response engines opens automotive and smart home channels previously served by narrow-purpose assistants.
- India enterprise digitization:PLI scheme incentives for IT services and BFSI modernization create procurement tailwinds for English-Hindi bilingual conversational platforms in banking and insurance workflows.
Industry Challenges
- LLM fine-tuning talent scarcity:Engineers capable of parameter-efficient adaptation and reinforcement learning from human feedback command compensation premiums that concentrate capability at well-capitalized incumbents.
- HIPAA compliance architecture:Healthcare deployments require Business Associate Agreement negotiations, encrypted data residency, and audit logging that extend sales cycles and implementation timelines.
- Legacy CRM integration friction:Enterprise buyers demand bidirectional synchronization with Salesforce, ServiceNow, and Dynamics instances, forcing vendors to maintain expensive connector ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chatbot Market |
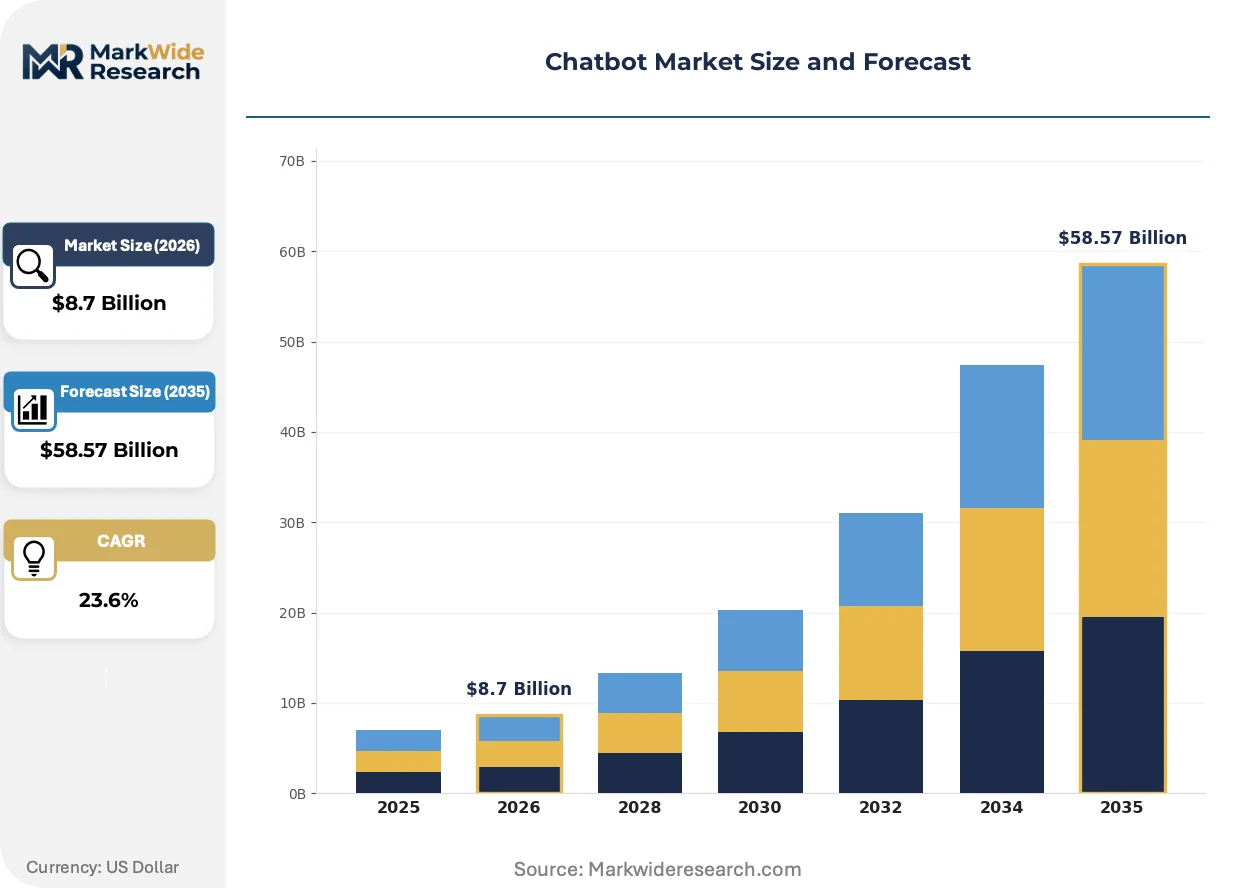
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $58.57 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Open Source Technology: Natural Language Processing, Machine Learning, Rule-Based, AI-Driven Application: Customer Support, E-Commerce, Personal Assistant, Lead Generation End User: Retail, BFSI, Healthcare, Travel |
| Companies Covered | OpenAI, Google, Microsoft, Meta, Anthropic, IBM, Salesforce, ServiceNow, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chatbot Market Emerging Trajectories
Conversational AI is bifurcating into commodity inference layers and premium orchestration platforms, with value capture shifting toward systems that manage multi-model routing, knowledge retrieval, and compliance auditing as unified services.
Multimodal transformer architectures capable of processing text, image, and structured data inputs are fragmenting the historical dominance of text-only chatbot interfaces. Manufacturing quality control and insurance claims processing teams are deploying these systems to interpret visual documentation alongside conversational queries. The structural consequence is compressing standalone computer vision and natural language processing vendor margins into unified platform pricing.
The EU AI Act's risk-tier classification system is mandating conformity assessments for chatbots deployed in credit scoring and medical diagnostic support functions. Vendors must now maintain technical documentation, human oversight protocols, and bias testing regimens to access European healthcare and financial services procurement channels. German and French healthcare systems are prioritizing vendors with existing notified body relationships, creating first-mover accreditation advantages.
Enterprise procurement of conversational AI is consolidating through cloud marketplaces and existing SaaS relationships rather than direct API contracting. Microsoft's embedding of Copilot across Office 365 and Dynamics is capturing conversational AI budgets through software renewal negotiations rather than competitive evaluation. United States Fortune 500 technology procurement teams are increasingly treating chatbot capabilities as infrastructure features rather than standalone software categories.
Chatbot Market Segmentation
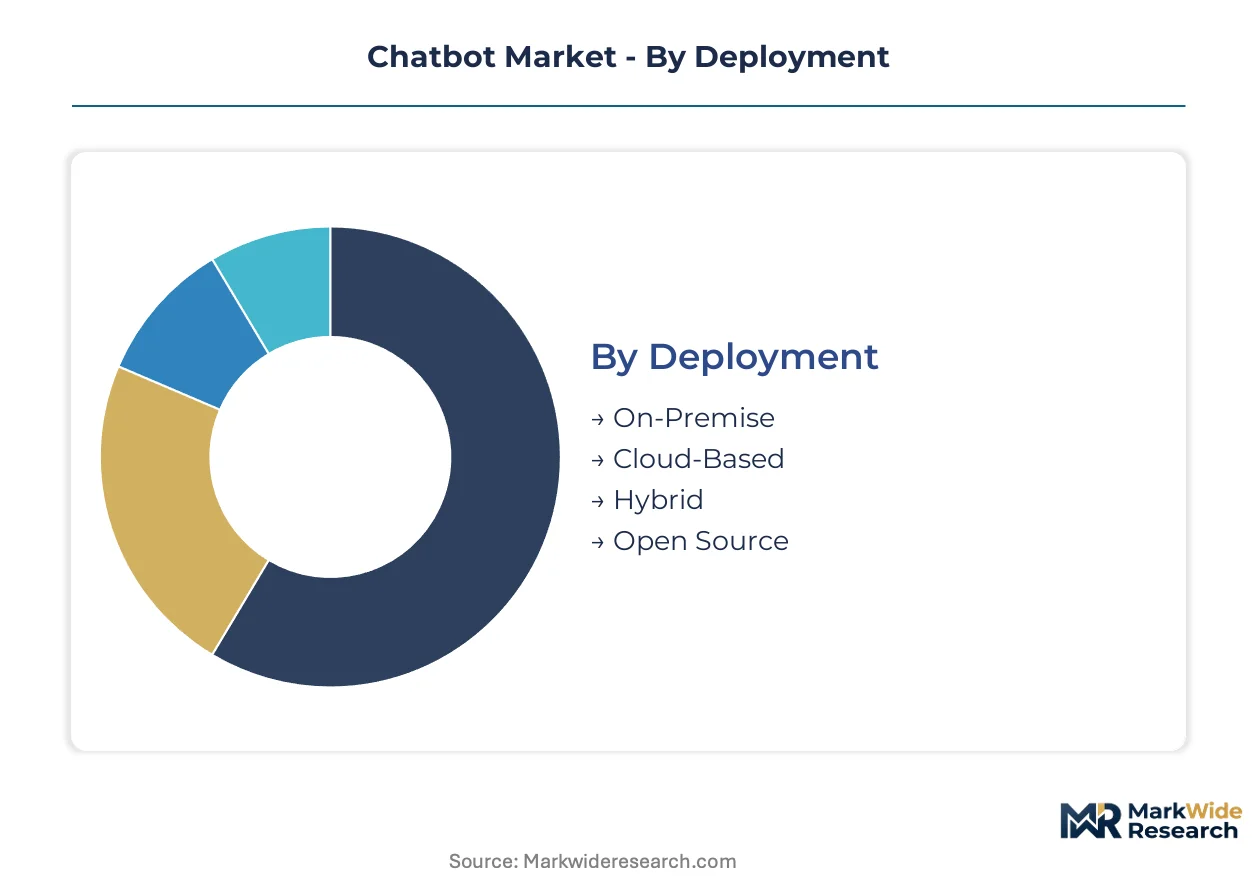
Segmentation in the chatbot market reveals distinct margin architectures across deployment models, technology stacks, and application verticals. Procurement patterns diverge sharply between cost-sensitive automation projects and premium compliance-driven deployments in regulated industries.
Deployment:
Margin pools concentrate in subscription-based cloud offerings where recurring revenue and reduced infrastructure overhead sustain pricing power. On-premise deployments command higher upfront fees but carry extended implementation timelines that compress vendor returns.
- Cloud-Based:Multi-tenant SaaS architectures with API-first delivery dominate enterprise procurement through Microsoft Azure, AWS, and Google Cloud marketplaces. United States Fortune 500 technology teams prioritize this model for rapid scaling without datacenter capital expenditure, though egress fees and token-based consumption pricing create unpredictable cost trajectories at scale.
- Hybrid:Split architectures process sensitive queries on-premise while routing general inquiries to cloud inference endpoints. German automotive manufacturers and French healthcare systems favor this configuration for EU AI Act compliance, accepting 40-60% cost premiums for data sovereignty guarantees.
- On-Premise:Air-gapped deployments in defense and classified government environments require specialized hardware provisioning and dedicated support contracts.
- Open Source:Self-hosted frameworks like Rasa and Botpress attract mid-market buyers with technical teams capable of custom integration work.
The dominant share belongs to Cloud-Based deployment, while Hybrid configurations are closing the gap fastest as European regulatory pressure intensifies.
Technology:
Technology selection determines whether chatbot implementations function as cost-center automation or revenue-generating conversion tools. Neural approaches capture expanding budgets as deterministic systems face replacement pressure.
- AI-Driven:Transformer-based architectures with retrieval-augmented generation and billion-parameter foundation models enable contextual reasoning across extended conversation threads. United States banking and healthcare operations deploy these systems for complex inquiry resolution where hallucination risk is mitigated through proprietary knowledge base grounding.
- Natural Language Processing:Intent classification and entity extraction pipelines with named-entity recognition and sentiment analysis serve mid-complexity use cases in retail and telecommunications.
- Machine Learning:Statistical approaches with supervised training on historical conversation logs support predictive routing and escalation triggers.
- Rule-Based:Deterministic decision trees with scripted response flows retain share in simple FAQ and appointment scheduling applications where neural inference costs cannot be justified.
AI-Driven technology commands the largest investment share, with Natural Language Processing expanding most quickly in mid-market customer support consolidation.
Application:
Application segmentation separates cost-reduction deployments from revenue-attachment opportunities, with lead generation commanding pricing multiples unavailable to support automation.
- Customer Support:Tier-one inquiry deflection and ticket routing for banking, telecommunications, and e-commerce operations. United States retail chains deploy these systems to reduce contact center headcount during seasonal volume spikes.
- Lead Generation:Conversational qualification and appointment booking with conversion attribution tracking. B2B software vendors and real estate platforms accept premium per-conversation pricing where pipeline contribution can be demonstrated.
- E-Commerce:Product recommendation and cart recovery through messaging interfaces integrated with Shopify and Salesforce Commerce Cloud.
- Personal Assistant:Calendar management and task delegation for executive productivity in professional services firms.
Customer Support retains the dominant deployment volume, while Lead Generation is climbing the fastest as attribution capabilities mature.
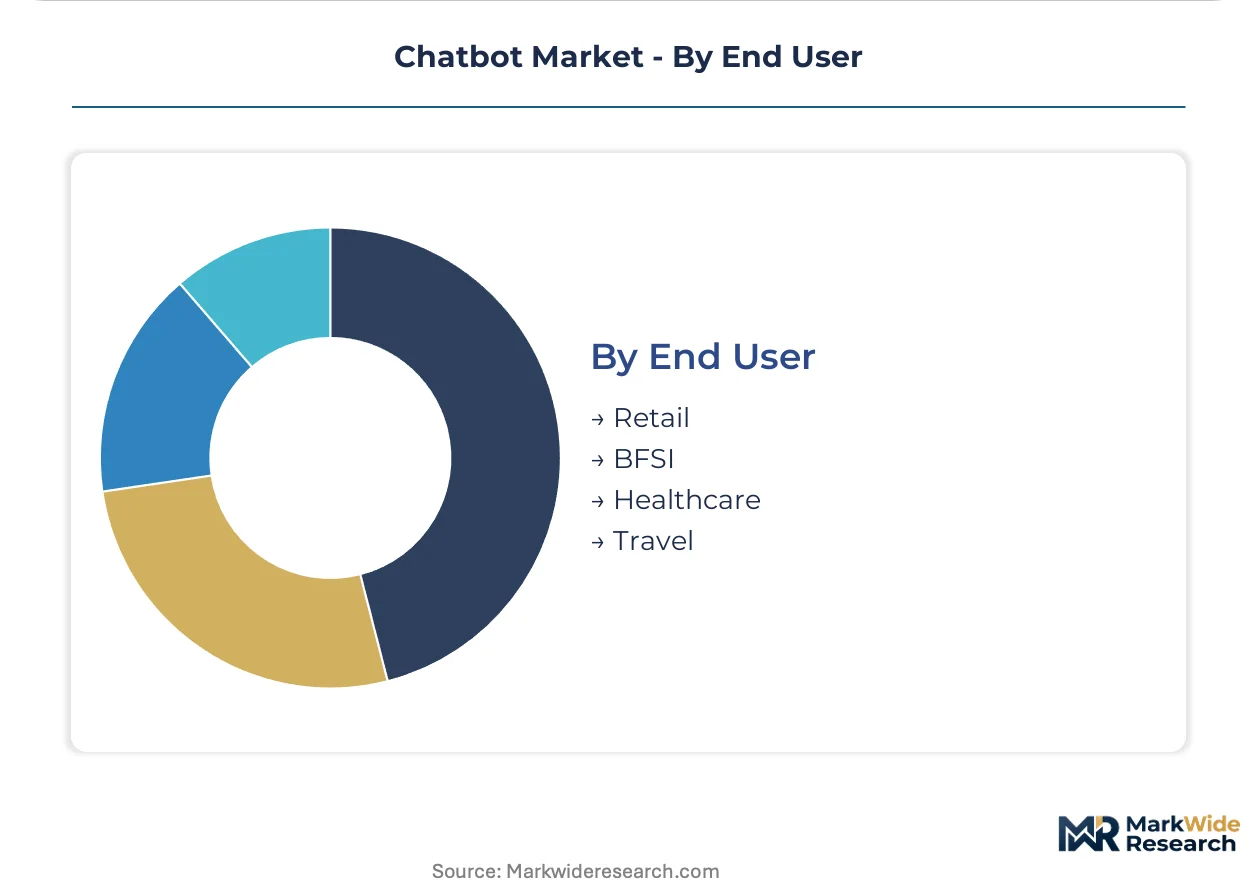
End User:
End-user verticals exhibit divergent procurement sophistication, with healthcare and BFSI buyers imposing compliance requirements that filter vendor eligibility.
- BFSI:Credit scoring assistance, fraud alert handling, and wealth management triage subject to SEC scrutiny and fair lending audits. United States regional banks prioritize vendors with existing core banking integrations.
- Healthcare:Patient scheduling, symptom triage, and medication adherence with HIPAA Business Associate Agreement requirements. German and French hospital systems demand EU AI Act conformity assessments for diagnostic support functions.
- Retail:Order tracking, returns processing, and promotional engagement with seasonal elasticity requirements.
- Travel:Booking modification, loyalty program inquiry, and disruption rebooking for airlines and hospitality chains.
BFSI verticals command the largest technology spend, with Healthcare posting the steepest expansion trajectory as clinical workflow integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FTC enforcement actions in the United States are establishing de facto standards for algorithmic accountability that ripple through procurement requirements across multiple jurisdictions. Enterprise buyers in regulated industries now demand audit trails and bias documentation regardless of local mandate status. This regulatory gravitational pull concentrates vendor investment in compliance architectures that satisfy the strictest applicable framework.
United States
Fortune 500 technology procurement teams at JPMorgan Chase and Walmart are deploying conversational AI for customer support automation at scale. FTC scrutiny of deceptive AI claims and algorithmic bias in consumer-facing systems is tightening vendor qualification requirements. Silicon Valley clusters in San Francisco and Seattle anchor foundation model development, with OpenAI and Anthropic headquarters driving talent concentration and venture deployment.
Germany
Automotive manufacturers BMW and Mercedes-Benz are implementing hybrid chatbot architectures for supply chain inquiry resolution and quality documentation retrieval. EU AI Act conformity assessment mandates for high-risk deployments are filtering vendor eligibility through notified body relationships. Industrial automation corridors in Bavaria and Baden-Württemberg concentrate procurement budgets for auditable, human-in-the-loop conversational systems.
France
BFSI operators BNP Paribas and AXA are deploying retrieval-augmented generation systems for wealth management triage and claims processing automation. CNIL guidance on automated decision-making transparency is shaping technical documentation requirements for domestic deployments. Paris-based fintech clusters and Lyon healthcare systems are prioritizing vendors with existing EU AI Act accreditation pathways.
India
IT services exporters TCS and Infosys are building bilingual English-Hindi conversational platforms for banking and insurance workflow modernization. PLI scheme incentives for digital infrastructure and BFSI digitization are accelerating enterprise procurement timelines. Bengaluru and Hyderabad technology corridors concentrate development talent for parameter-efficient model adaptation and reinforcement learning from human feedback implementation.
United Kingdom
HSBC and Lloyds Banking Group are deploying conversational AI for fraud alert handling and credit scoring assistance subject to FCA algorithmic accountability expectations. The Information Commissioner's Office guidance on automated decision-making is extending GDPR transparency requirements to chatbot deployments. London financial services clusters and Manchester healthcare systems are driving demand for explainable, auditable conversational architectures.
Chatbot Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer commanding API pricing power and enterprise licensing premiums through foundation model control. The middle tier competes on retrieval-augmented generation implementation and vertical-specific knowledge integration. Three archetypes dominate: cloud hyperscalers embedding conversational AI through existing software relationships, pure-play foundation model providers monetizing API access, and enterprise SaaS vendors layering conversational interfaces atop CRM and service management platforms. Competitive moves concentrate on strategic partnerships for distribution reach and technology licensing for model access.
Within the foundation model provider tier, OpenAI and Anthropic exemplify the API-first monetization archetype, with geographic anchoring in San Francisco reflecting talent concentration in large language model research. Microsoft occupies a distinctive position spanning both cloud infrastructure and application software embedding, converting Office 365 and Dynamics relationships into conversational AI adoption without standalone procurement cycles. These three entities represent the competitive poles around which vendor positioning strategies organize.
| Leading Market Players |
|---|
| OpenAI |
| Microsoft |
| Meta |
| Anthropic |
| IBM |
| Salesforce |
| ServiceNow |
| Oracle |
| Others |
Supply Flow & Price Mechanics
EU AI Act conformity assessments gate both vendor qualification and price differentiation in European procurement channels, forcing compliance investment as a prerequisite for premium positioning while compressing margins for non-accredited suppliers locked out of high-risk deployment categories.
Pricing Analysis
United States enterprise buyers pay premiums of 35-50% above Indian mid-market rates for equivalent AI-driven chatbot implementations. Pricing stratifies across premium, standard, and economy tiers based on EU AI Act certification status and vector database integration depth. Cost compression in the rule-based tier is intensifying because simple intent-classification systems face displacement by open-source neural alternatives. Healthcare and BFSI buyers demonstrate lowest price sensitivity where HIPAA and SEC compliance requirements filter vendor pools.
Supply Chain Analysis
United States and China anchor foundation model development and GPU cloud infrastructure provisioning for conversational AI training workloads. Taiwan and South Korea supply advanced logic semiconductors that underpin inference acceleration. Supply chain risk centers on NVIDIA datacenter allocation bottlenecks that tether vendor margins to single-source silicon dependency. Distribution runs through hyperscaler marketplaces and embedded SaaS renewals rather than direct API contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment, where EU AI Act accreditation creates switching costs that cement incumbent positions across European healthcare and financial services procurement channels.
For Market Incumbents: Secure notified body relationships in Germany and France to maintain EU AI Act conformity assessment advantages against emerging API-first challengers. Deepen vertical integration into proprietary vector database architectures to differentiate retrieval-augmented generation implementations from commodity inference layers. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized BFSI digitization wave, where bilingual English-Hindi conversational platforms face limited competition from Western vendors. Target mid-market manufacturing quality control applications with multimodal vision-language architectures that compress standalone computer vision margins. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward vendors with existing high-risk deployment accreditation and human-in-the-loop technical documentation. Long-term viability favors orchestration platforms managing multi-model routing and compliance auditing over pure inference providers. Watch for FTC enforcement actions establishing de facto algorithmic accountability standards as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Notified body relationships in Germany unlock high-risk healthcare procurement channels. |
| Retrieval-Augmented Generation Platform | Vector database integration reduces hallucination risk in SEC-regulated wealth management triage. |
| Hyperscaler Marketplace Embedding | Microsoft Azure and AWS listings capture Fortune 500 procurement budgets through renewal cycles. |
| Multimodal Vision-Language Convergence | Insurance claims processing teams deploy unified platforms for visual documentation interpretation. |
| India BFSI Localization | PLI scheme incentives accelerate bilingual platform adoption in Mumbai and Hyderabad banking corridors. |
Methodological Framework
A standing panel of conversational AI product managers, enterprise IT procurement officers, HIPAA compliance architects, and EU regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, EU AI Act technical documentation requirements, and hospital procurement database records. Bottom-up deployment estimates triangulated against top-down enterprise software spending benchmarks.
Consistency checks validated volume and value outputs against external hyperscaler revenue disclosures and notified body accreditation tallies across the projection horizon. Segmentation dimensions modeled include deployment architecture, technology stack, application vertical, end-user industry, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to historical cloud software penetration patterns, with inputs including GPU supply allocation forecasts and EU AI Act implementation timelines.
Material uncertainties — foundation model capability breakthroughs, FTC enforcement intensity, and datacenter energy regulation — sit outside the modeled envelope. Forecasts reflect documented assumptions about enterprise automation willingness-to-pay and regulatory fragmentation trajectories. Recalibration cycles align with material shifts in GPU supply availability and EU AI Act delegated act publications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Embedded AI Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Pharmaceutical Market
Artificial Intelligence (AI)
United States Conversational AI Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Voice Recognition Market
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
Global AI in Social Media Market
Artificial Intelligence (AI)
Connectivity Constraint Computing Market
Artificial Intelligence (AI)
NLP in Healthcare and Life Sciences Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in BFSI Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Social Media Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
Intelligent Assistant Embedded Consumer Devices Market
Artificial Intelligence (AI)
AI Orchestration Market