
 Desktop Virtualization Market | 2026-2036
Desktop Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
Desktop Virtualization Market Intelligence
The direct sales channel is narrowing as hyperscale cloud marketplaces capture enterprise procurement workflows for virtual desktop workloads. Citrix DaaS leverages its established channel partnerships to sustain on-premises migration services. Microsoft Azure Virtual Desktop anchors the cloud-native segment through native Windows licensing integration. Amazon WorkSpaces competes on pay-as-you-go flexibility for mid-market customers.
Desktop virtualization separates computing workloads from physical endpoint hardware, streaming encrypted desktop sessions over IP networks with latency thresholds typically below 150 milliseconds for acceptable user experience. Virtual Desktop Infrastructure remains the dominant solution type, though Desktop-as-a-Service expands fastest as organizations outsource data center capital to hyperscale operators. Cloud-Based deployment leads volume while Hybrid architectures capture premium margins from regulated industries requiring split custody of sensitive data.
FISMA and NIST SP 800-207 zero-trust principles shape federal procurement specifications, while HIPAA security rules mandate audit logging and access controls for healthcare virtual desktop implementations. The EU AI Act and GDPR cross-border data restrictions complicate multi-tenant European deployments for US-based cloud providers. Stakeholders must monitor evolving endpoint detection and response mandates from CISA, as these requirements increasingly dictate minimum viable security configurations for government and critical infrastructure virtual desktop contracts.
Market Dynamics
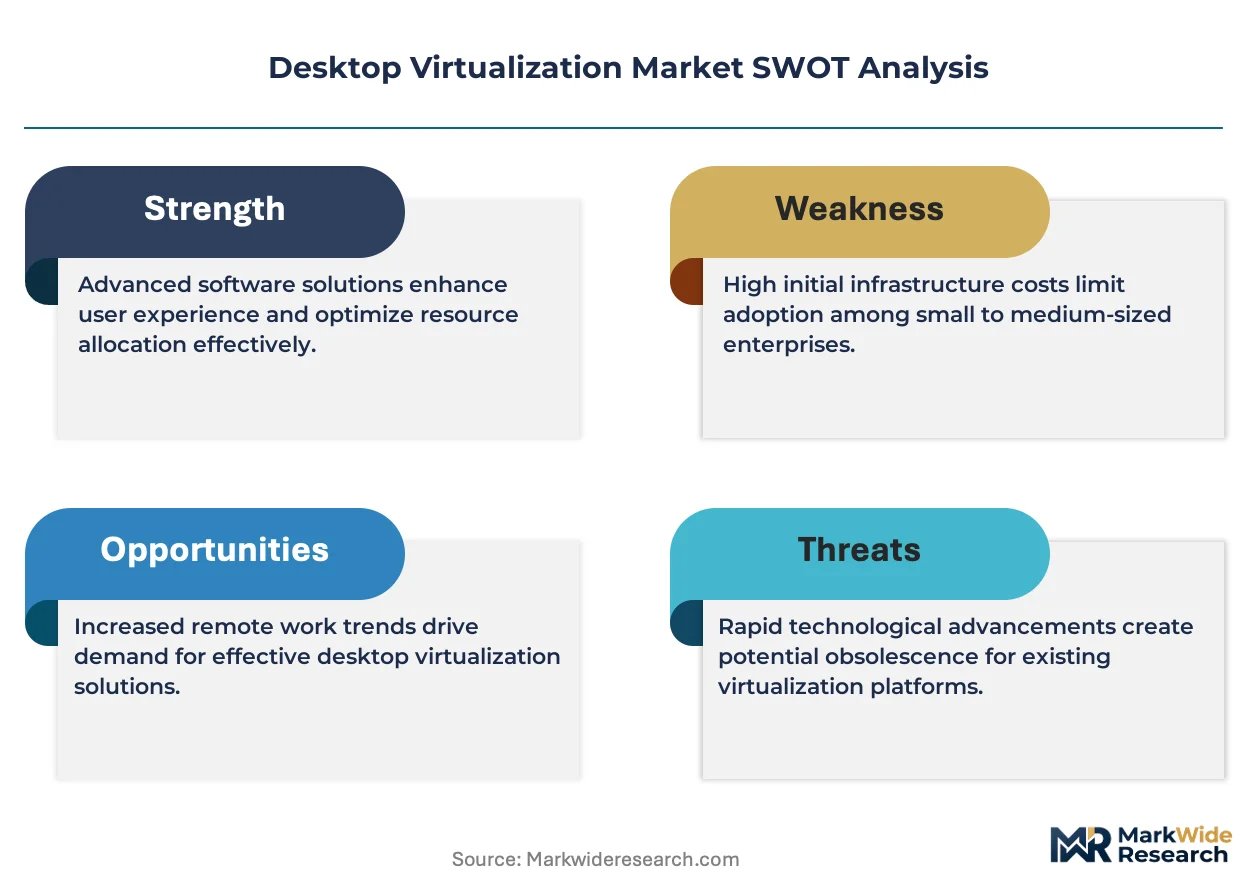
Federal zero-trust mandates are restructuring procurement priorities across defense and healthcare sectors, compressing legacy perimeter-security architectures into identity-centric access models that demand continuous verification.
Growth Catalysts
- NIST SP 800-207:Zero-trust architecture mandates from the US federal government accelerate security-hardened VDI procurement across civilian agencies and defense contractors requiring FISMA-compliant remote access.
- Clinical workstation mobility:Healthcare providers expand virtual desktop deployments to enable secure roaming access for physicians and nursing staff across multiple care sites and shift patterns.
- GPU virtualization:NVIDIA vGPU and AMD MxGPU technologies enable graphics-intensive workloads in virtualized environments, opening VDI to engineering, media production, and scientific computing use cases previously restricted to physical workstations.
Market Restraints
- Hyperscale cloud egress fees:Data transfer costs from AWS, Azure, and Google Cloud impose structural cost penalties on hybrid and multi-cloud desktop virtualization architectures.
- Network latency thresholds:Sub-150 millisecond round-trip requirements for acceptable user experience restrict viable deployment geographies and exclude rural broadband markets.
- Windows licensing complexity:Microsoft's per-user and per-device licensing rules create compliance friction and cost uncertainty for organizations operating mixed on-premises and cloud desktop estates.
Strategic Opportunities
- Edge computing convergence:Integration of 5G network slicing with micro-datacenter deployments enables low-latency virtual desktops for field engineering and mobile healthcare in underserved geographies.
- India's digital infrastructure:The country's National Broadband Mission and data center PLI scheme create whitespace for cloud-native DaaS providers targeting mid-market manufacturing and IT services sectors.
- Confidential computing:AMD SEV-SNP and Intel TDX technologies enable encrypted virtual machine memory, addressing data residency requirements for European financial services and public sector deployments.
Industry Challenges
- Identity architect scarcity:Shortage of engineers skilled in zero-trust implementation, conditional access policy design, and privileged access management complicates enterprise deployment timelines.
- Legacy application compatibility:16-bit and 32-bit Windows applications, ActiveX controls, and custom peripherals resist virtualization, forcing parallel physical infrastructure maintenance.
- Audit logging standardization:Divergent requirements between HIPAA, SOX, and FedRAMP create compliance engineering overhead for healthcare and financial services organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desktop Virtualization Market |
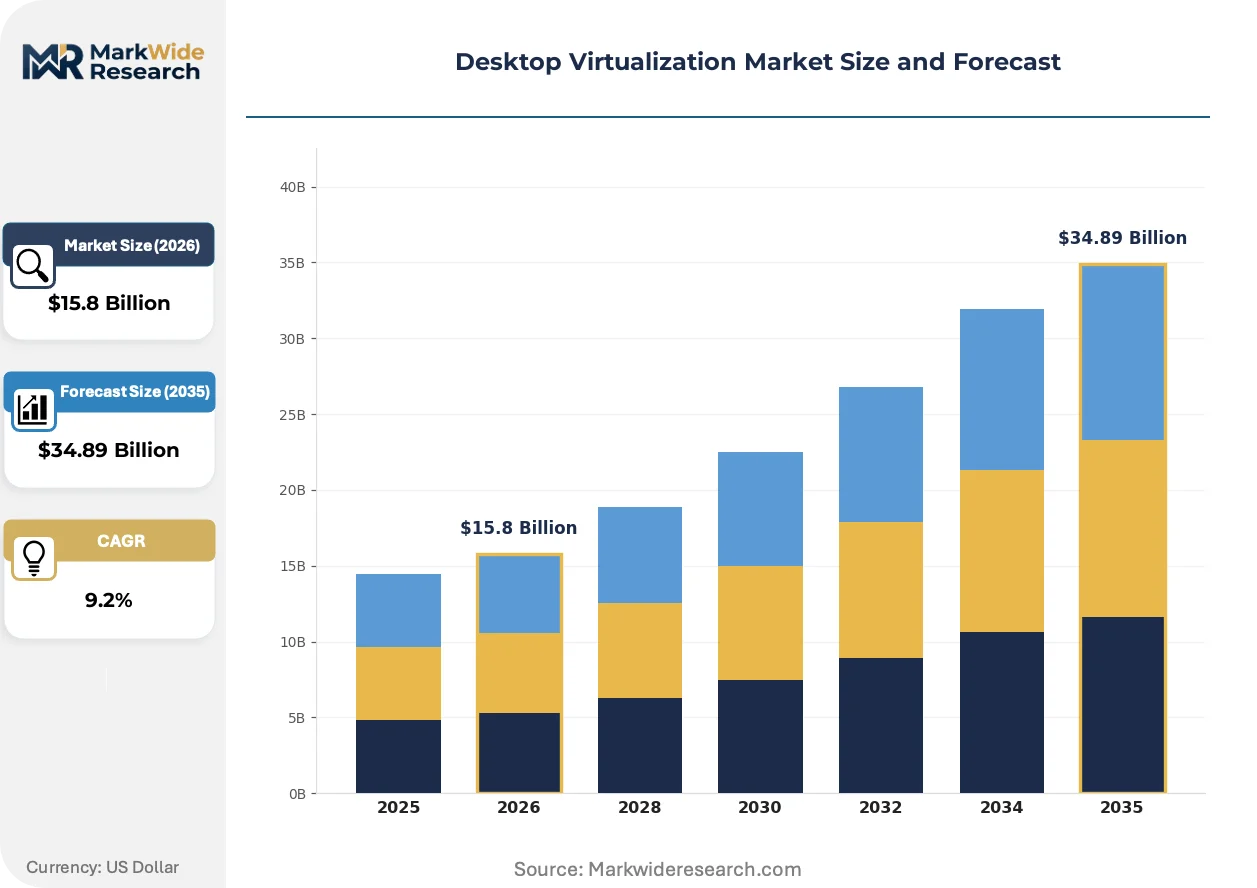
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $34.89 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Virtual Desktop Infrastructure, Desktop-as-a-Service, Application Virtualization, Session-Based Computing End User Industry: Information Technology, Banking & Finance, Education, Manufacturing, Government Access Device: Thin Clients, Laptops, Tablets, Smartphones, Zero Clients |
| Companies Covered | Omnissa Horizon, Inuvika OVD Enterprise, Amazon WorkSpaces, Nutanix Xi Frame, Ericom, Citrix DaaS, Windows 365, vDeskWorks, Microsoft Azure Virtual Desktop, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desktop Virtualization Market Strategic Shifts & Innovations
Browser-based streaming protocols and AI-assisted session optimization are compressing the technical boundary between native and virtualized desktop experiences. These developments are reshaping how organizations evaluate endpoint hardware refresh cycles and remote work infrastructure investments.
WebRTC-based display protocols are rendering obsolete traditional thick-client VDI agents that require local installation and maintenance. Healthcare systems and federal agencies now pilot browser-only virtual desktop access for contractor and temporary staff, eliminating endpoint preparation overhead. This shift compresses deployment timelines from weeks to hours and expands addressable user populations to unmanaged devices.
The EU AI Act's risk classification framework imposes documentation and human oversight requirements on automated decision systems embedded in virtual desktop management platforms. European financial institutions and healthcare providers must now assess whether AI-driven session optimization, anomaly detection, or predictive scaling triggers high-risk system designations. This regulatory friction is accelerating investment in explainable automation and human-in-the-loop governance structures among DaaS providers operating EU data centers.
Consumption-based licensing models are displacing perpetual enterprise agreements for virtual desktop infrastructure. Mid-market organizations in manufacturing and professional services now procure capacity through hyperscale marketplaces rather than direct vendor negotiations, compressing sales cycles and shifting technical evaluation criteria toward API interoperability and identity federation capabilities. This pattern is most visible in Germany's Mittelstand sector and US defense industrial base subcontractors.
Desktop Virtualization Market Segmentation
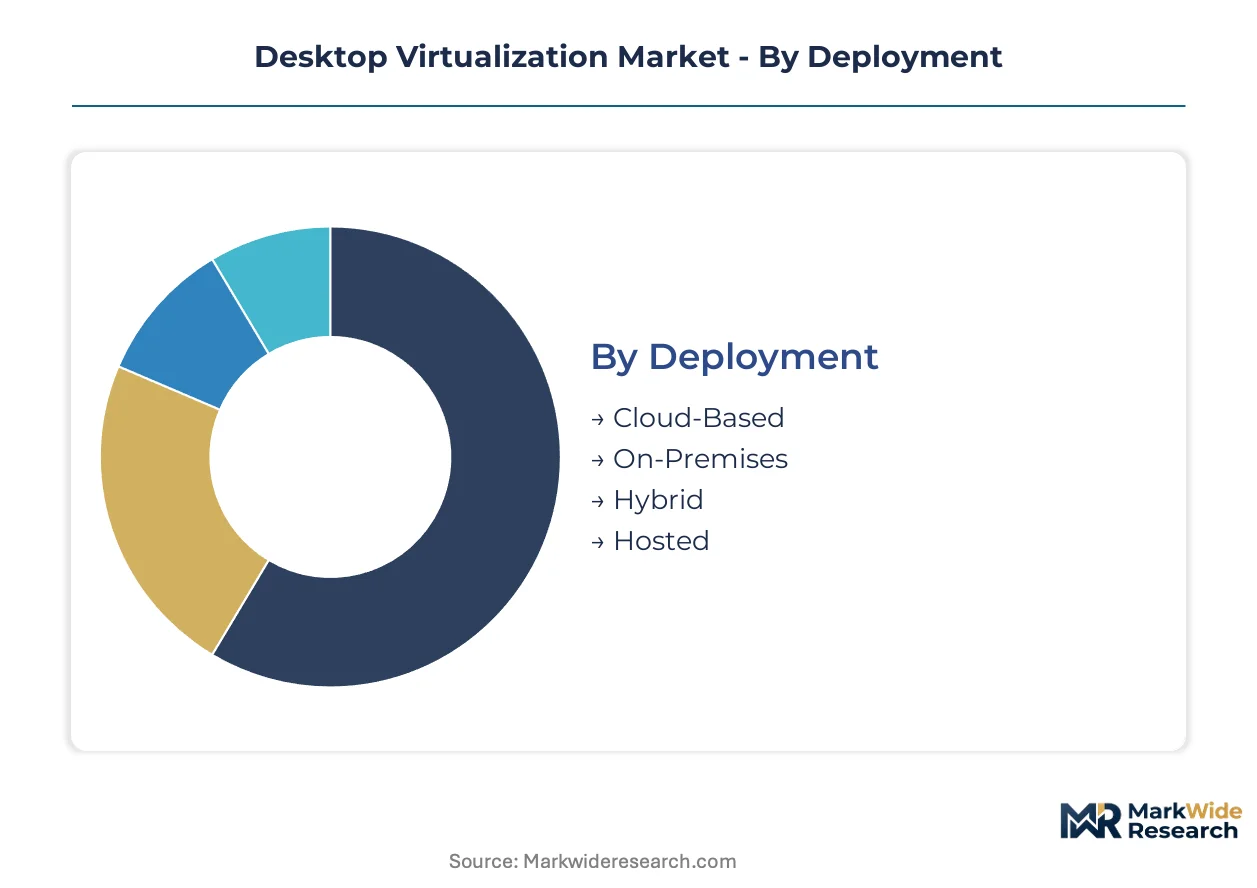
Desktop virtualization procurement patterns diverge sharply across deployment architectures, solution maturity, and endpoint hardware profiles. Understanding these fault lines reveals where hyperscale cloud providers capture volume versus where specialized vendors defend premium pricing through compliance depth.
Deployment:
Cost tier determines infrastructure ownership models and capital commitment intensity for virtual desktop estates.
- Cloud-Based:Hyperscale operators provision compute, storage, and networking as metered services, eliminating data center capital expenditure. United States hospital systems and defense contractors gravitate here for elastic capacity during surge events and contractor onboarding waves.
- Hybrid:Organizations maintain sensitive workloads on-premises while bursting non-critical sessions to public cloud, satisfying split-custody requirements for regulated data. Financial services firms in Germany and healthcare networks in France deploy this architecture to reconcile GDPR data residency with operational flexibility.
- On-Premises:Enterprises retain full infrastructure control within owned or colocated facilities.
- Hosted:Managed service providers operate dedicated single-tenant infrastructure on behalf of clients.
Cloud-Based holds installed capacity. Hybrid is rotating up the share rankings.
Solution Type:
Application workload characteristics and IT staff sophistication determine whether organizations build, buy, or outsource virtual desktop platforms.
- Virtual Desktop Infrastructure:Organizations deploy hypervisor clusters, connection brokers, and profile management tools on owned hardware, preserving granular control over security configurations. United States federal agencies under FISMA mandates favor VDI for audit trail completeness and encryption key custody.
- Desktop-as-a-Service:Cloud-native delivery abstracts all infrastructure management to provider operations teams, converting capital expenditure to operational spend. India's mid-market IT services sector and US professional services firms adopt DaaS to accelerate remote work enablement without data center construction.
- Application Virtualization:Streaming individual applications rather than full desktops reduces resource overhead for task-specific user populations.
- Session-Based Computing:Multi-user operating system instances serve lightweight productivity workloads at lowest per-seat cost.
Virtual Desktop Infrastructure holds installed capacity. Desktop-as-a-Service is climbing the fastest.
End User Industry:
Regulatory exposure and workforce mobility requirements concentrate demand unevenly across vertical markets.
- Information Technology:Technology vendors and enterprise IT departments deploy virtual desktops for developer workstation standardization, secure contractor access, and disaster recovery posture. Silicon Valley software firms and Bangalore development centers drive GPU-enabled virtualization for machine learning and graphics workloads.
- Government:Civilian agencies and defense contractors mandate zero-trust architectures with continuous identity verification, privileging vendors with FedRAMP authorization and NIST SP 800-207 alignment. United States procurement specifications increasingly exclude perimeter-VPN alternatives.
- Banking & Finance:Institutions balance trader mobility against market data confidentiality and SEC audit requirements.
- Education:Universities and K-12 districts seek low-cost endpoint refresh strategies for student device programs.
- Manufacturing:Factory floor and engineering office convergence demands ruggedized endpoint compatibility.
Information Technology holds installed capacity. Government is gaining share fastest.
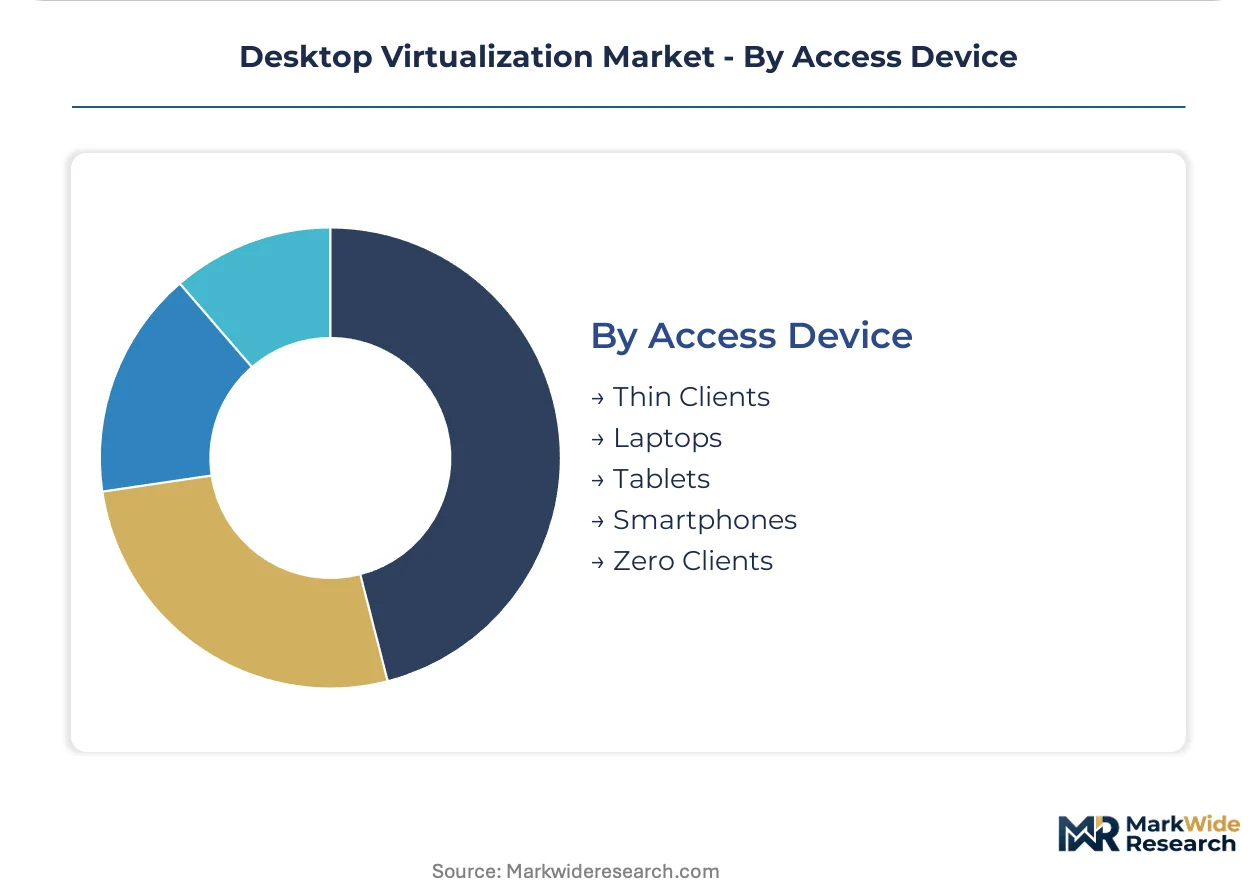
Access Device:
Endpoint hardware selection shapes user experience thresholds, security attack surface, and total cost of ownership calculations.
- Thin Clients:Stripped-down Linux or Windows Embedded devices execute display protocols while centralizing compute on servers, minimizing local malware exposure. Healthcare systems in the United Kingdom and Japan deploy thin clients for nursing station reliability and rapid replacement during hardware failure.
- Zero Clients:Firmware-locked endpoints with no local operating system eliminate patch management burden entirely. United States federal facilities and financial trading floors favor zero clients for highest-assurance environments where USB redirection and local storage present unacceptable risk.
- Laptops:Full-capability mobile computers retain local processing for offline productivity.
- Tablets:Touch-native form factors suit clinical rounding and field inspection workflows.
- Smartphones:Pocket-sized emergency access extends virtual desktop reach to executive and on-call populations.
Thin Clients holds installed capacity. Zero Clients is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NIST SP 800-207 mandates from the United States federal government anchor procurement specifications across the desktop virtualization landscape. FISMA-compliant architectures and zero-trust principles now dictate infrastructure decisions in civilian agencies, defense contractors, and allied healthcare systems. Geographic demand clusters around regulatory complexity, data residency requirements, and workforce mobility patterns.
United States
Defense contractors and hospital systems drive security-hardened VDI procurement under federal mandates. FedRAMP authorization requirements filter vendor eligibility for civilian agency contracts. Northern Virginia's data center corridor hosts concentrated hyperscale capacity serving intelligence community and Pentagon workloads.
Germany
GDPR data residency rules and the EU AI Act shape financial services and manufacturing deployments. Germany's Mittelstand sector adopts consumption-based DaaS through hyperscale marketplaces. Frankfurt's financial district anchors confidential computing investments for encrypted virtual machine memory.
United Kingdom
NHS digital transformation programs expand thin client deployments across nursing stations and clinical workstations. UK government zero-trust guidelines align with NIST frameworks for contractor remote access. London's health technology cluster pilots browser-only virtual desktop access for temporary clinical staff.
India
The National Broadband Mission and data center PLI scheme create whitespace for cloud-native DaaS providers. Mid-market IT services and manufacturing sectors accelerate remote work enablement without capital-intensive infrastructure. Bangalore's technology corridor drives GPU-enabled virtualization for machine learning development environments.
France
Healthcare networks deploy hybrid architectures to reconcile GDPR data residency with operational flexibility. French financial institutions assess AI Act risk classifications for automated session optimization tools. Paris banking clusters invest in explainable automation for virtual desktop management platforms.
Desktop Virtualization Market Key Industry Players
Hyperscale cloud operators and legacy virtualization specialists split the market across deployment architecture preferences. Consolidation pressures intensify as enterprise procurement workflows migrate to cloud marketplaces, compressing direct sales channel viability. Three archetypes dominate: hyperscale platform operators with native licensing integration, established virtualization vendors sustaining migration services through channel partnerships, and emerging specialists targeting compliance-heavy verticals. Competitive moves center on strategic partnerships for identity federation capabilities and portfolio diversification into edge computing convergence.
Within the hyperscale tier, Microsoft Azure Virtual Desktop and Amazon WorkSpaces occupy positions shaped by native cloud integration and pay-as-you-go flexibility respectively. Citrix DaaS anchors the established vendor archetype, representing sustained channel-driven migration from on-premises estates. These three exemplify how licensing complexity and egress cost structures dictate competitive positioning across enterprise segments.
| Leading Market Players |
|---|
| Omnissa Horizon |
| Inuvika OVD Enterprise |
| Amazon WorkSpaces |
| Nutanix Xi Frame |
| Ericom |
| Citrix DaaS |
| Windows 365 |
| vDeskWorks |
| Microsoft Azure Virtual Desktop |
| Others |
Cost & Logistics Intelligence
Hyperscale cloud infrastructure concentration in the United States, Northern Virginia, and Frankfurt funnels margin pools toward providers with FedRAMP authorization and NIST SP 800-207 compliance depth. Windows licensing complexity and egress fee structures create pricing power asymmetries that favor integrated platform operators over pure-play virtualization vendors.
Pricing Analysis
Geographic price spreads widen between FISMA-compliant federal deployments and standard commercial cloud workloads. Pricing stratifies across premium, standard, and economy tiers based on certification grade and identity federation capabilities. Cost compression in mid-market segments intensifies as hyperscale marketplaces displace direct vendor negotiations. Healthcare systems show highest price sensitivity due to constrained capital budgets, while defense contractors absorb premium pricing for zero-trust architectures.
Supply Chain Analysis
Extended payment terms from hyperscale operators strain smaller channel partners and managed service providers. Supply concentrates in the United States, Ireland, and Singapore for data center infrastructure, with Taiwan and South Korea anchoring GPU virtualization components. Raw material dependencies include server-grade silicon, high-bandwidth memory modules, and specialized networking ASICs. Single-source vulnerability around NVIDIA vGPU licensing creates supply chain risk. Distribution runs through hyperscale marketplaces, systems integrators, and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation is accelerating as zero-trust mandates splinter procurement specifications across federal, healthcare, and financial verticals, creating defendable niches for compliance-specialist vendors.
For Market Incumbents: Build certification moats around FedRAMP High and StateRAMP authorizations to exclude unqualified competitors. Deepen vertical integration into identity federation capabilities through strategic partnerships with Okta and Ping Identity. Channel control investments in defense contractor ecosystems counter hyperscale marketplace erosion. For New Entrants and Emerging Players: Establish a beachhead in India's mid-market IT services sector where data center PLI incentives reduce infrastructure capital requirements. Target manufacturing verticals in Germany's Mittelstand with confidential computing offerings that satisfy GDPR data residency. A consumption-based go-to-market through AWS Marketplace accelerates sales velocity without direct enterprise selling overhead. For Investors and Strategic Acquirers: Capital is best deployed toward specialists with zero-trust implementation expertise and existing FedRAMP authorization pipelines. Long-term viability hinges on identity-centric access models displacing legacy perimeter-VPN architectures. Watch CISA endpoint detection mandates as the inflection signal for minimum viable security configuration standards.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Certification | FedRAMP authorization opens civilian agency and defense contractor procurement pipelines. |
| Confidential Computing Partnership | AMD SEV-SNP integration addresses European financial services data residency requirements. |
| Hyperscale Marketplace Listing | AWS and Azure marketplace presence compresses sales cycles for mid-market DaaS adoption. |
| GPU Virtualization Expansion | NVIDIA vGPU enablement captures engineering and scientific computing workloads from physical workstations. |
| Edge Computing Convergence | 5G network slicing integration enables low-latency deployments in rural healthcare and field engineering. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chief information security officers, federal procurement officers, healthcare IT directors, cloud solution architects, and channel partner principals. Secondary validation drew from FedRAMP marketplace listings, NIST SP 800-207 implementation guidance, hyperscaler capex disclosures, hospital procurement databases, and GSA schedule contract awards. Bottom-up deployment estimates triangulated against top-down infrastructure spending projections.
Calibration against historical VDI and DaaS adoption curves anchored growth assumptions across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution type, end-user industry, and access device profile. CAGRs derived from elasticity-adjusted penetration rates in regulated verticals. Industry-specific inputs encompassed NIST zero-trust implementation timelines, Windows licensing rule changes, and GPU virtualization cost curves.
Stress conditions across federal budget sequestration, hyperscale egress fee escalation, and identity architect labor shortages were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and cloud migration velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Experience Optimization Platforms Market
Digital Solutions
Community Forum Market
Digital Solutions
Cloud Logistics Software Market
Digital Solutions
Self-Service Kiosk Market
Digital Solutions
Interactive Response Technology Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
Legaltech Market
Digital Solutions
Digital Rights Management (DRM) Market
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Asia-Pacific Multichannel Order Management Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Trade Management Software Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
Social Computing Market
Digital Solutions
Data Governance Market
Digital Solutions
Global E-Filing Platforms Market