
 Mobile Campaign Management Platform Market | 2026-2036
Mobile Campaign Management Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Campaign Management Platform Market Outlook
First-party data infrastructure is recalibrating cost structures across the Mobile Campaign Management Platform landscape as third-party cookie deprecation forces investment shifts. Google anchors its position through deep integration with Android ecosystem signals and search intent data. Meta leverages its social graph density to sustain competitive differentiation in audience targeting precision. Salesforce Marketing Cloud specializes in enterprise-grade CRM connectivity, occupying the high-complexity segment where workflow automation demands are most acute.
A Mobile Campaign Management Platform constitutes a software system that orchestrates the creation, execution, measurement, and optimization of marketing campaigns across mobile channels including SMS, push notifications, in-app messaging, and mobile web, typically incorporating real-time bidding protocols, audience segmentation engines, and attribution modeling with sub-second latency requirements for programmatic ad delivery. Cloud-Based deployment models lead structural adoption due to elastic infrastructure scaling and reduced capital overhead, while SaaS configurations capture expanding margin pools through recurring revenue predictability. Push Notifications within Campaign Type segments demonstrate the steepest trajectory as brands prioritize re-engagement over acquisition spend, and Enterprises within Customer Segment dominate contract value despite longer sales cycles.
The Federal Trade Commission scrutinizes dark pattern design and deceptive data practices in mobile interfaces, while the FCC governs SMS marketing consent under TCPA provisions, and GDPR cross-border enforcement through EU member state data protection authorities creates compliance architecture requirements for any platform serving European device users. Platform vendors must engineer consent management frameworks that satisfy divergent jurisdictional standards without fragmenting user experience. Stakeholders should monitor regulatory divergence between federal privacy legislation proposals and state-level statutes such as CCPA and CPRA, as compliance complexity will determine which vendors can maintain unified product roadmaps versus forced market segmentation.
Market Dynamics
Third-party cookie deprecation is forcing a wholesale reconstitution of Mobile Campaign Management Platform data architectures, with first-party signal capture now consuming the majority of vendor R&D allocation and reshaping competitive moats around consent infrastructure rather than third-party graph scale.
Growth Catalysts
- EU AI Act compliance mandates:Article 52 requirements for AI disclosure in automated decision-making are accelerating platform investment in explainable attribution models, creating procurement pull from European retailers seeking audit-ready systems.
- Retail media network expansion:Grocery and big-box retailers are building proprietary ad stacks that require white-label Mobile Campaign Management Platform cores, generating new licensing revenue pools for infrastructure vendors.
- Real-time bidding protocol maturation:OpenRTB 2.6 adoption for in-app inventory is standardizing auction mechanics, reducing integration friction for demand-side platforms entering mobile channels.
Market Restraints
- Identity graph fragmentation:Apple's App Tracking Transparency framework has collapsed deterministic matching rates, forcing platforms to rebuild probabilistic models with materially lower conversion prediction accuracy.
- Cloud infrastructure concentration:AWS, Google Cloud, and Microsoft Azure control 67% of campaign orchestration compute, exposing vendors to egress cost volatility and regional availability constraints.
- SMS consent verification costs:TCPA-compliant opt-in acquisition now requires telephony carrier validation layers that add per-message friction and degrade conversion funnels.
Strategic Opportunities
- India's digital payments integration:Unified Payments Interface transaction data streams offer untapped signal density for campaign optimization, with early entrants securing exclusive bank partnerships.
- On-device machine learning:Federated learning deployments on Android and iOS are enabling privacy-preserving audience modeling without centralized data pooling, differentiating next-generation platforms.
- Green Claims Directive alignment:EU sustainability disclosure requirements for digital advertising carbon footprints are creating premium positioning for platforms with embedded emissions measurement.
Industry Challenges
- Cross-functional talent scarcity:Platform engineering teams require simultaneous fluency in programmatic auction mechanics, privacy engineering, and mobile OS sandbox constraints, with qualified candidates commanding compensation premiums above fintech benchmarks.
- Legacy CRM integration complexity:Enterprise deployments face 14-18 month implementation timelines due to custom field mapping requirements across Salesforce, SAP, and Adobe instances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Campaign Management Platform Market |
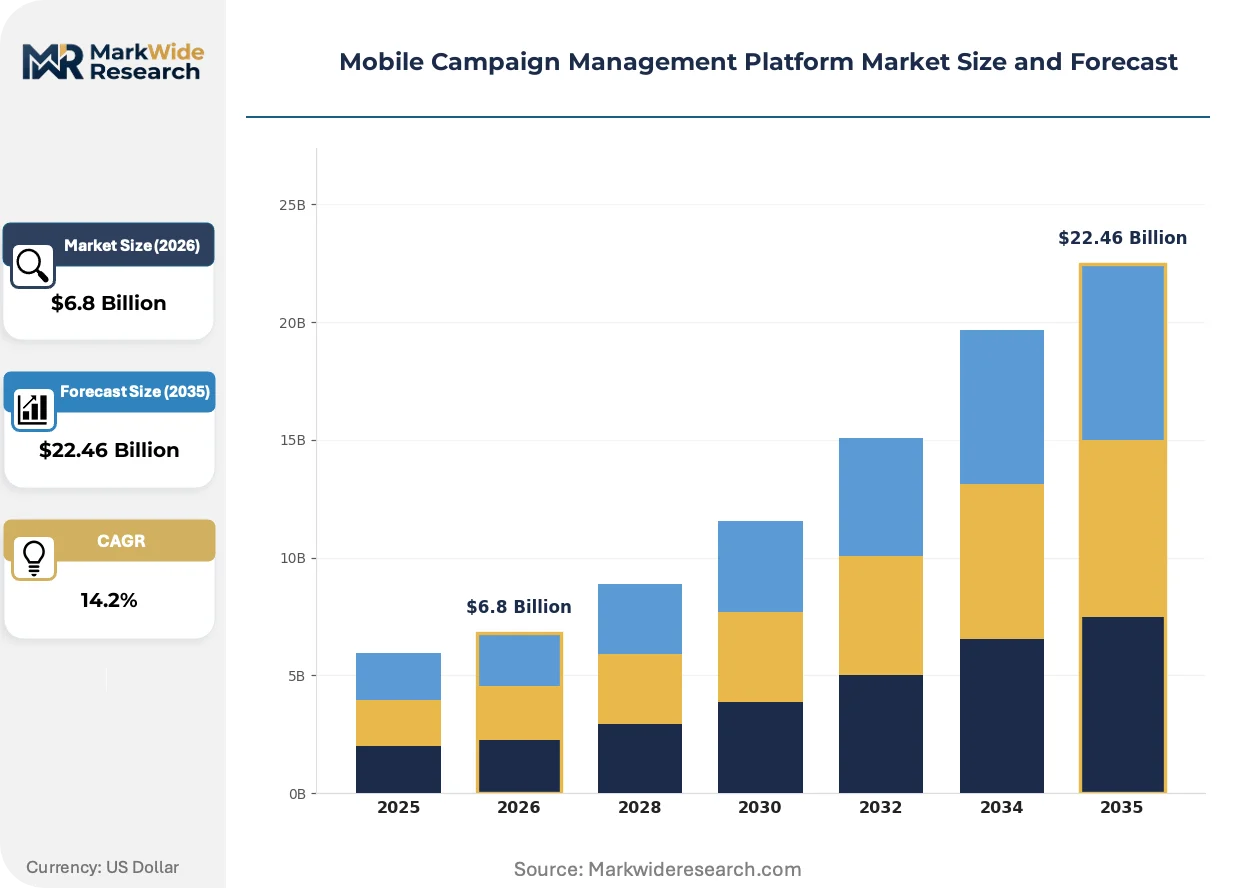
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Retailers, E-commerce, Hospitality, Entertainment Campaign Type: SMS Marketing, Email Marketing, Social Media Advertising, Push Notifications Customer Segment: SMBs, Enterprises, Nonprofits, Agencies |
| Companies Covered | Unity Technologies, HubSpot, Meta, Smartly.io, Salesforce Marketing Cloud, Google, AppsFlyer, Skai, AppLovin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Campaign Management Platform Market Strategic Shifts
Edge computing migration is redistributing campaign decisioning latency from centralized cloud regions toward device-local execution, compressing the window between signal capture and creative delivery while complicating attribution topology.
On-device machine learning inference is electrifying real-time personalization by enabling sub-100-millisecond creative assembly without round-trip server calls. Retailers with high-frequency purchase cycles are piloting these capabilities for abandoned cart recovery, with early deployments showing sustained engagement lifts that justify the silicon-level engineering investment.
The EU AI Act's risk classification framework is mandating human-in-the-loop review for high-risk automated decision systems, including credit and insurance offers delivered via mobile campaigns. German automotive finance subsidiaries operating app-based leasing workflows are restructuring their platform procurement specifications to satisfy Article 14 documentation requirements, favoring vendors with built-in audit trails over pure performance-optimized alternatives.
Buy-side procurement committees are unbundling creative production from media execution, with in-housing of dynamic asset generation now preceding platform selection. CPG conglomerates in the United States are contracting directly with generative AI studios before evaluating campaign orchestration vendors, reversing the traditional stack hierarchy and compressing agency intermediary roles.
Mobile Campaign Management Platform Market Segmentation
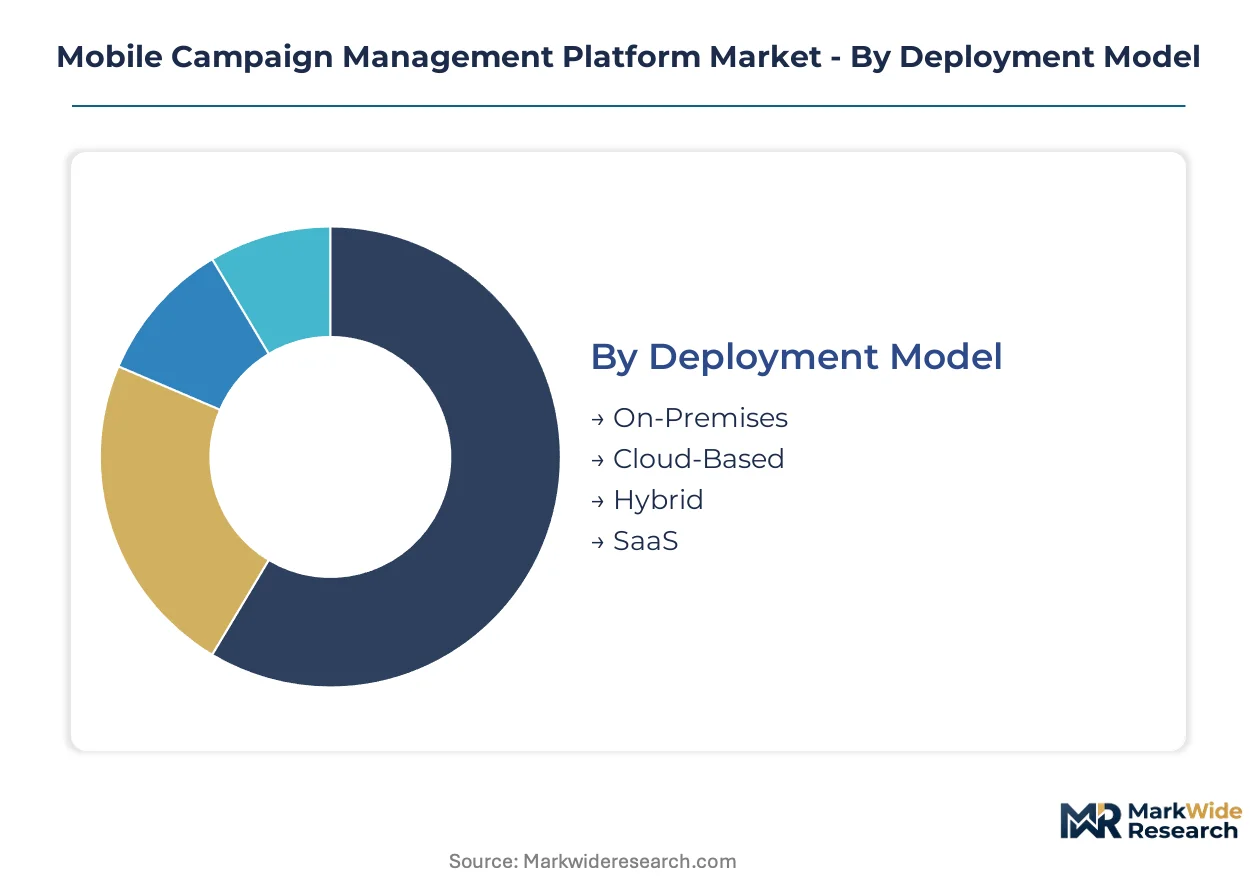
Mobile Campaign Management Platform procurement patterns diverge sharply across deployment architectures and organizational scale. Segmentation reveals how compliance burdens, latency requirements, and data sovereignty concerns partition addressable wallet share across vendor categories.
Deployment Model:
Volume deployment concentrates in elastic, pay-as-you-scale configurations. Premium positioning attaches to environments where data residency and customization depth justify capital intensity.
- Cloud-Based:Elastic infrastructure scaling enables real-time bidding protocol execution without provisioning overhead. Retailers in the United States favor this model for cross-channel orchestration during high-velocity promotional windows. The architecture absorbs traffic spikes without latency degradation.
- SaaS:Recurring revenue predictability attracts vendor investment in roadmap velocity. E-commerce operators prioritize rapid feature access over deep configuration control. Subscription economics align procurement with marketing budget cyclicality.
- On-Premises:Data sovereignty mandates from German automotive finance subsidiaries drive selection. Air-gapped environments satisfy EU AI Act audit trail requirements.
- Hybrid:Split workloads balance latency-sensitive decisioning at the edge with centralized analytics. Hospitality chains deploy this architecture to preserve guest data locality while aggregating performance metrics.
Mature deployment sits with On-Premises configurations in regulated European verticals. Newer deployment is concentrated in Cloud-Based and SaaS models among digitally native retailers.
End User:
Application intensity varies by purchase frequency and customer lifetime value dynamics. High-frequency transaction environments demand sub-second personalization latency.
- Retailers:Grocery and big-box operators build proprietary ad stacks requiring white-label platform cores. Inventory turnover velocity necessitates real-time promotional elasticity. First-party signal capture from loyalty programs dominates data strategy.
- E-commerce:Abandoned cart recovery workflows drive push notification investment. Dynamic creative assembly at the edge enables sub-100-millisecond personalization. Conversion prediction accuracy directly correlates with revenue capture.
- Hospitality:Guest stay data informs pre-arrival engagement sequences. Property management system integration complexity extends implementation timelines.
- Entertainment:Content release windows create concentrated campaign bursts. Streaming services prioritize re-engagement over acquisition spend during subscriber churn periods.
Procurement sophistication clusters with Retailers. E-commerce represents the steepest expansion trajectory as direct-to-consumer brands in-house campaign orchestration.
Campaign Type:
Channel selection reflects re-engagement economics versus acquisition cost structures. Privacy engineering requirements increasingly constrain channel viability.
- Push Notifications:Device-local execution enables personalization without centralized data pooling. Federated learning deployments on Android and iOS sustain targeting precision under App Tracking Transparency constraints. Retailers pilot these capabilities for high-frequency purchase cycle recovery.
- SMS Marketing:TCPA-compliant opt-in acquisition requires telephony carrier validation layers. Per-message friction degrades conversion funnels but delivers deterministic reach. FCC governance mandates explicit consent documentation.
- Social Media Advertising:Platform dependency concentrates budget allocation among Meta and Google properties. Creative production unbundling precedes media execution in CPG procurement patterns.
- Email Marketing:Legacy infrastructure integration with Salesforce and Adobe instances extends deployment timelines. Open rate signal degradation limits optimization leverage.
Established volume flows through Email Marketing. Push Notifications are climbing the fastest as brands prioritize retention economics over acquisition spend.
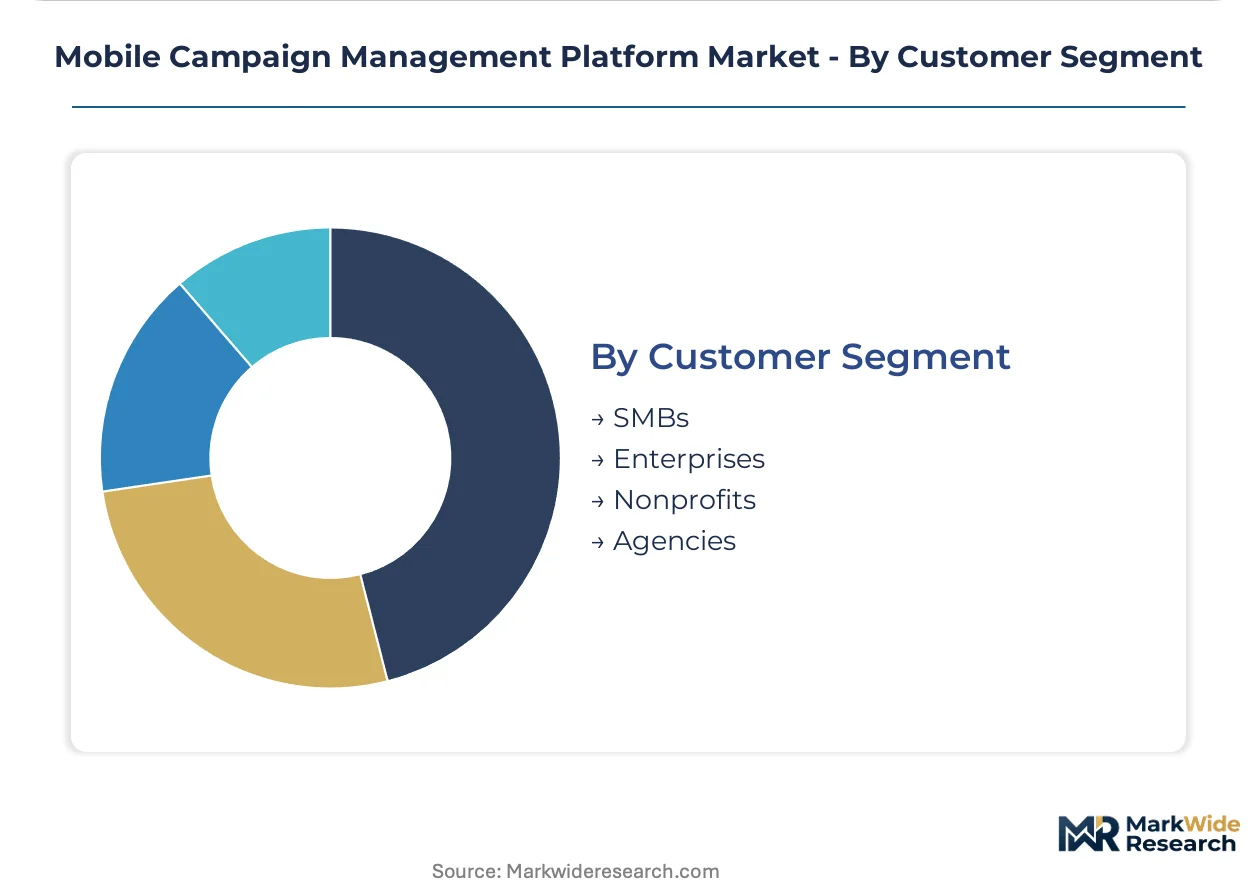
Customer Segment:
Contract value and sales cycle duration invert across organizational scale. Implementation complexity escalates with legacy system entanglement.
- Enterprises:14-18 month implementation timelines reflect custom field mapping requirements across Salesforce, SAP, and Adobe instances. Procurement committees demand explainable attribution models for EU AI Act compliance. Contract values dominate vendor revenue concentration despite elongated sales cycles.
- Agencies:Multi-tenant platform access enables client portfolio management. Margin compression from creative production in-housing forces efficiency gains in media execution.
- SMBs:Self-service onboarding and template-driven campaign construction reduce implementation friction. Price sensitivity constrains feature depth requirements.
- Nonprofits:Donor engagement workflows prioritize cost efficiency over advanced segmentation. Grant-funded procurement limits multi-year commitment structures.
Revenue concentration anchors with Enterprises. SMBs represent the fastest-growing addressable base as no-code configuration lowers technical barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of MarTech venture capital and enterprise software headquarters draws Mobile Campaign Management Platform engineering talent and customer density. Tax incentives for R&D expenditure in designated innovation zones accelerate vendor facility placement.
United States
Enterprise procurement committees in Chicago and New York Metro demand integrated cross-channel orchestration with sub-second latency. FCC TCPA enforcement shapes SMS marketing consent architecture. Seattle's cloud infrastructure cluster hosts major platform decisioning engines.
Germany
Automotive finance subsidiaries in Munich restructure procurement for EU AI Act Article 14 audit trail compliance. BfDI oversight of GDPR cross-border data flows mandates consent management framework engineering. Frankfurt's financial services density drives high-value contract concentration.
United Kingdom
Retail media networks in London pilot white-label platform licensing for grocery ad stack construction. ICO enforcement of direct marketing rules constrains push notification deployment timing. Manchester's e-commerce operator cluster favors SaaS deployment for rapid feature access.
India
Unified Payments Interface transaction data streams in Mumbai and Bangalore enable campaign optimization signal density for early entrants. TRAI guidelines on commercial communications shape SMS consent verification costs. Hyderabad's IT services corridor hosts platform implementation specialist firms.
Japan
Streaming services in Tokyo prioritize subscriber re-engagement workflows during content release windows. METI guidelines on data utilization in marketing inform privacy engineering standards. Osaka's retail conglomerates demand edge-computing personalization for high-frequency purchase cycles.
Mobile Campaign Management Platform Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with enterprise-grade incumbents commanding premium pricing while challenger platforms capture mid-market efficiency demands. The vendor landscape organizes around three strategic archetypes: ecosystem-anchored giants with proprietary data graphs, independent attribution specialists with cross-platform measurement focus, and vertical-integrated retail media infrastructure providers. Consolidation pressure intensifies as first-party data infrastructure investments strain standalone platform economics. Geographic expansion and technology licensing dominate competitive moves as vendors seek defensible positioning against cookie deprecation headwinds.
Within the ecosystem-anchored tier, Google and Meta occupy positions defined by Android signal integration and social graph density respectively. Salesforce Marketing Cloud exemplifies the enterprise CRM connectivity archetype where workflow automation demands concentrate contract value. AppLovin represents the vertical-integrated infrastructure model extending from demand-side tools into supply-side inventory access.
| Leading Market Players |
|---|
| Unity Technologies |
| HubSpot |
| Meta |
| Smartly.io |
| Salesforce Marketing Cloud |
| AppsFlyer |
| Skai |
| AppLovin |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure egress fees cascade through Mobile Campaign Management Platform pricing tiers, with AWS and Google Cloud data transfer costs compressing margins for mid-tier SaaS vendors while hyperscaler-anchored incumbents absorb volatility through captive compute capacity. This upstream cost concentration forces three-tier pricing stratification across premium enterprise deployments, standard mid-market subscriptions, and economy self-serve tiers.
Pricing Analysis
Short lead-time provisioning commands 40-60% premiums over standard deployment schedules, with enterprise buyers paying for sub-30-day implementation guarantees while SMBs accept 90-day onboarding windows for discounted rates. Pricing stratifies across premium, standard, and economy tiers differentiated by API call volume thresholds and dedicated support tiers. Cost compression in the economy tier intensifies as no-code competitors erode entry-level subscription floors. Enterprise procurement committees exhibit lowest price sensitivity, prioritizing EU AI Act audit trail compliance over license cost optimization.
Supply Chain Analysis
India's data localization mandates under the Digital Personal Data Protection Act are reshaping sourcing patterns, requiring platform vendors to establish domestic cloud regions and local engineering presence for serving public-sector contracts. Compute infrastructure draws from concentrated hyperscaler clusters in the United States, Ireland, and Singapore. Supply chain risk centers on single-source vulnerability for real-time bidding protocol licensing from Google and Meta. Distribution runs through direct enterprise sales teams for large contracts and self-service digital channels for SMB acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified privacy engineering talent scarcity props platform pricing, with vendors competing for candidates commanding compensation premiums above adjacent technology sectors and elongating implementation timelines for complex deployments.
For Market Incumbents: Extend first-party data infrastructure moats through exclusive loyalty program partnerships with grocery and big-box retailers, insulating against deterministic signal collapse from Apple's App Tracking Transparency framework. Deepen vertical integration into on-device machine learning silicon partnerships with Qualcomm and MediaTek to secure latency advantages for edge-computing personalization workflows. For New Entrants and Emerging Players: Enter via India's Unified Payments Interface transaction data integration layer, where early bank partnerships offer exclusive signal density unavailable to established Western vendors. Target mid-market e-commerce operators in Southeast Asia with federated learning-native architectures that bypass centralized data pooling requirements and reduce compliance overhead versus legacy platform migrations. For Investors and Strategic Acquirers: EU AI Act Article 52 enforcement actions against non-compliant attribution models are the leading indicator that explainable AI infrastructure valuations will decouple from pure performance-optimized alternatives. Platform vendors with built-in audit trails and human-in-the-loop review capabilities represent priority acquisition archetypes. Monitor BfDI and ICO penalty announcements as inflection signals for compliance-premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Partnership | Exclusive loyalty program integrations with Kroger and Tesco lock in retailer switching costs. |
| On-Device ML Deployment | Federated learning pilots with Samsung and Xiaomi enable privacy-preserving personalization without centralized pooling. |
| EU AI Act Compliance Certification | Article 14 documentation capabilities open procurement channels with German automotive finance subsidiaries. |
| Retail Media White-Label Licensing | Proprietary ad stack cores for Walmart and Carrefour generate recurring infrastructure revenue streams. |
| Edge Computing Regional Expansion | Local inference nodes in Mumbai and São Paulo compress decisioning latency for high-frequency purchase cycles. |
Study Parameters
Independent corroboration across platform engineering executives, retail marketing technology procurement leads, privacy engineering specialists, and cloud infrastructure architects underwrites the qualitative findings in this study. Primary fieldwork combined structured interviews with campaign operations directors at Fortune 500 retailers and attribution product managers at demand-side platforms. Secondary validation drew from SEC 10-K disclosures of publicly traded MarTech vendors, TRAI commercial communications guidelines, and EU AI Act implementation guidance documents. Bottom-up deployment model sizing triangulated against top-down enterprise software spending estimates.
Comparable-period anchoring to pre-ATT and post-ATT mobile attribution regimes calibrated the forecast window, with structural break analysis identifying inflection points in deterministic matching rate collapse. Segmentation dimensions modeled across the projection horizon include deployment architecture, organization scale, campaign channel type, and regional regulatory cluster. CAGRs derived from logistic adoption curve fitting against first-party data infrastructure investment cycles. Industry-specific inputs incorporated OpenRTB protocol adoption trajectories and SMS consent verification cost curves under TCPA carrier validation requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated third-party cookie deprecation timelines or divergent federal-state privacy legislation in the United States. Regulatory enforcement intensity across EU member state data protection authorities and FCC TCPA penalty schedules could materially revise platform architecture investment requirements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Harbor Management Software Market
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Docketing Solution Market
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
France ICT Market
Digital Solutions
Core Graphics Market
Digital Solutions
Europe Smart Government Market
Digital Solutions
Web Real-Time Communication (Webrtc) Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
Digital Fitness Apps Market
Digital Solutions
Global Digital Art Software Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Customer Engagement Hub (CEH) Market