
 Foot Traffic and Customer Location Intelligence Solution Market | 2026-2036
Foot Traffic and Customer Location Intelligence Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Foot Traffic and Customer Location Intelligence Solution Market Analysis
Data science talent scarcity is redrawing competitive boundaries in location intelligence, forcing vendors to build automated platforms that reduce manual geospatial analysis. Foursquare leverages its proprietary Places dataset to sustain developer loyalty across mobile SDK deployments. SafeGraph anchors enterprise demand through granular point-of-interest coverage in North America. HERE Technologies competes on automotive-grade positioning accuracy, extending its footprint into traffic monitoring systems for transportation agencies.
Foot traffic and customer location intelligence solutions capture, process, and analyze spatial movement patterns using Wi-Fi probe requests, GPS signals, and Bluetooth beacon transmissions to generate dwell-time metrics, visit frequency scores, and pedestrian flow visualizations. These systems serve commercial and municipal decision-makers seeking to optimize physical asset performance, allocate security resources, and design transit networks. Wi-Fi Analytics and GPS Tracking dominate solution architecture due to their compatibility with existing infrastructure, while Mobile SDK deployments represent the fastest-expanding segment as app publishers embed location permissions into loyalty and payment workflows. Predictive Analytics commands the strongest margin pool because retail chains and hospitality operators pay premiums for demand-forecasting modules that integrate weather, event, and demographic variables.
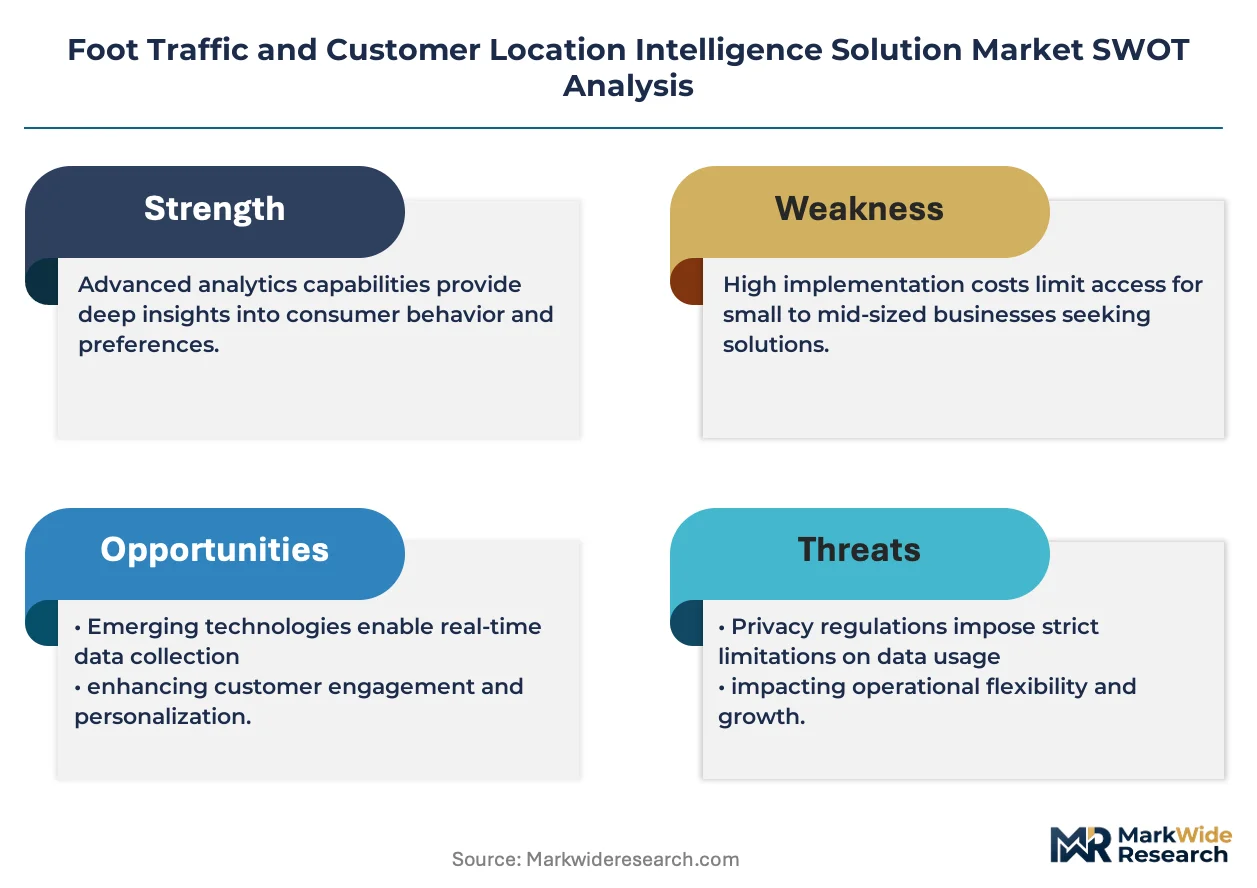
The Federal Trade Commission enforces Section 5 unfair-practice provisions against deceptive location-data collection in the United States, while the European Data Protection Board interprets GDPR Article 6 lawful-basis requirements for Wi-Fi tracking in public spaces. China's Personal Information Protection Law imposes consent and purpose-limitation rules on GPS and beacon deployments by domestic app operators. Stakeholders must monitor evolving consent-framework interpretations across jurisdictions to avoid enforcement actions that would restrict data supply and degrade model accuracy.
Market Dynamics
Data privacy enforcement is fragmenting data collection architectures across jurisdictions, forcing vendors to rebuild consent infrastructure for each regulatory regime while maintaining cross-border analytics continuity.
Growth Catalysts
- Smart city infrastructure mandates:Municipal governments in Germany, China, and the United States are deploying sensor networks for traffic optimization and public safety resource allocation.
- GDPR Article 6 compliance frameworks:Lawful-basis interpretations for Wi-Fi tracking in public spaces are clarifying, reducing legal uncertainty for European retail deployments.
- Mobile SDK integration:App publishers are embedding location permissions into loyalty and payment workflows, expanding passive data capture at scale.
Market Restraints
- Silicon supply concentration:Bluetooth beacon and Wi-Fi sensor manufacturing depends on semiconductor fabrication concentrated in East Asian foundries.
- GDPR and state-level US privacy laws:Consent requirements and purpose-limitation rules restrict data retention periods and degrade longitudinal dataset completeness.
- Opt-in friction:Consumer location permission denial rates in iOS ecosystems limit addressable sample sizes for pedestrian flow modeling.
Strategic Opportunities
- India smart city programs:Underpenetrated urban digitization initiatives in Tier-2 and Tier-3 municipalities create first-mover positioning for infrastructure vendors.
- EU AI Act compliance automation:Automated bias auditing and explainability modules for predictive foot-traffic models represent premium service attachment potential.
- Edge computing convergence:On-device inference for GPS and beacon signal processing reduces cloud transmission costs and latency for real-time applications.
Industry Challenges
- Geospatial data science specialization:Scarce talent pools in spatial statistics and movement-pattern modeling force vendors toward automated platform development.
- Cross-jurisdiction consent orchestration:Reconciling FTC Section 5 enforcement, GDPR lawful-basis requirements, and China's Personal Information Protection Law creates compliance engineering complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foot Traffic and Customer Location Intelligence Solution Market |
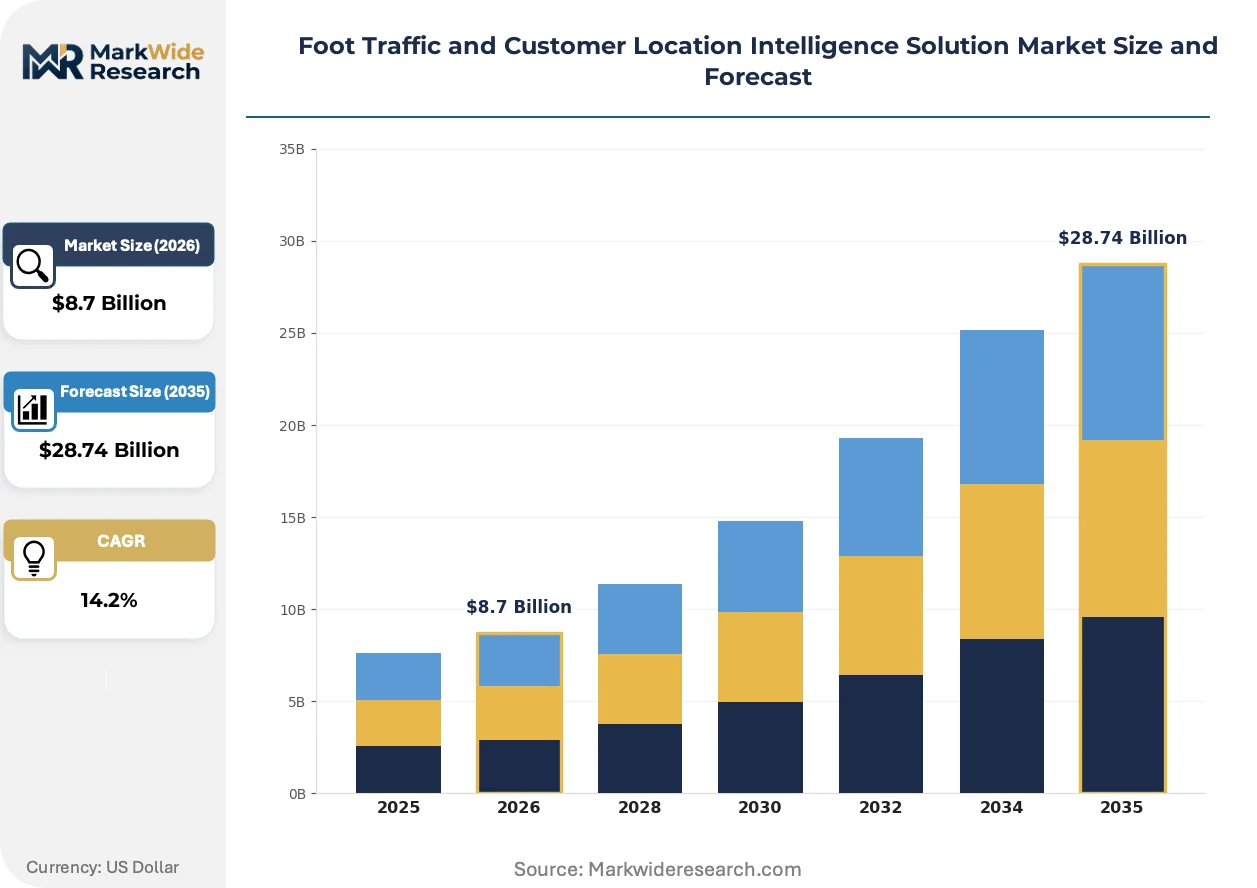
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi Analytics, Mobile SDK, Beacons, GPS Tracking Application: Retail Analytics, Smart Cities, Event Management, Traffic Monitoring End User: Retail Chains, Event Organizers, Transportation Agencies, Hospitality Sector Solution: Data Visualization, Predictive Analytics, Reporting Tools, Location-Based Services |
| Companies Covered | SafeGraph, Crowd Connected, Foursquare, ESRI, Precisely, Placer Labs, Unacast, HERE Technologies, RetailNext, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foot Traffic and Customer Location Intelligence Solution Market Emerging Trajectories
Location intelligence architectures are pivoting from centralized cloud processing toward distributed edge inference, driven by latency requirements for real-time applications and escalating data sovereignty constraints.
Wi-Fi probe request analytics is decomposing traditional hardware-dependent deployment models. Retail chains and transportation agencies are adopting software-defined sensor networks that virtualize signal capture through existing access point infrastructure. This convergence is decomposing capital expenditure barriers for mid-market operators while compressing installation timelines from months to weeks.
China's Personal Information Protection Law is mandating granular consent workflows and purpose-limitation documentation for domestic app operators. The regulation forces GPS and beacon-dependent services to rebuild data pipelines with explicit user authorization at each collection point. Domestic Chinese location intelligence providers are responding by developing consent-management middleware that chains authorization states across multiple touchpoints.
Retail procurement of foot-traffic analytics is consolidating around integrated platform contracts rather than point-solution subscriptions. Department store and quick-service restaurant chains are displacing single-purpose Wi-Fi analytics vendors with unified vendors offering predictive demand forecasting, demographic enrichment, and competitive benchmarking. This bundling is most visible in the United States, where enterprise buyers possess sufficient scale to negotiate outcome-based pricing tied to same-store sales correlation metrics.
Foot Traffic and Customer Location Intelligence Solution Market Segmentation
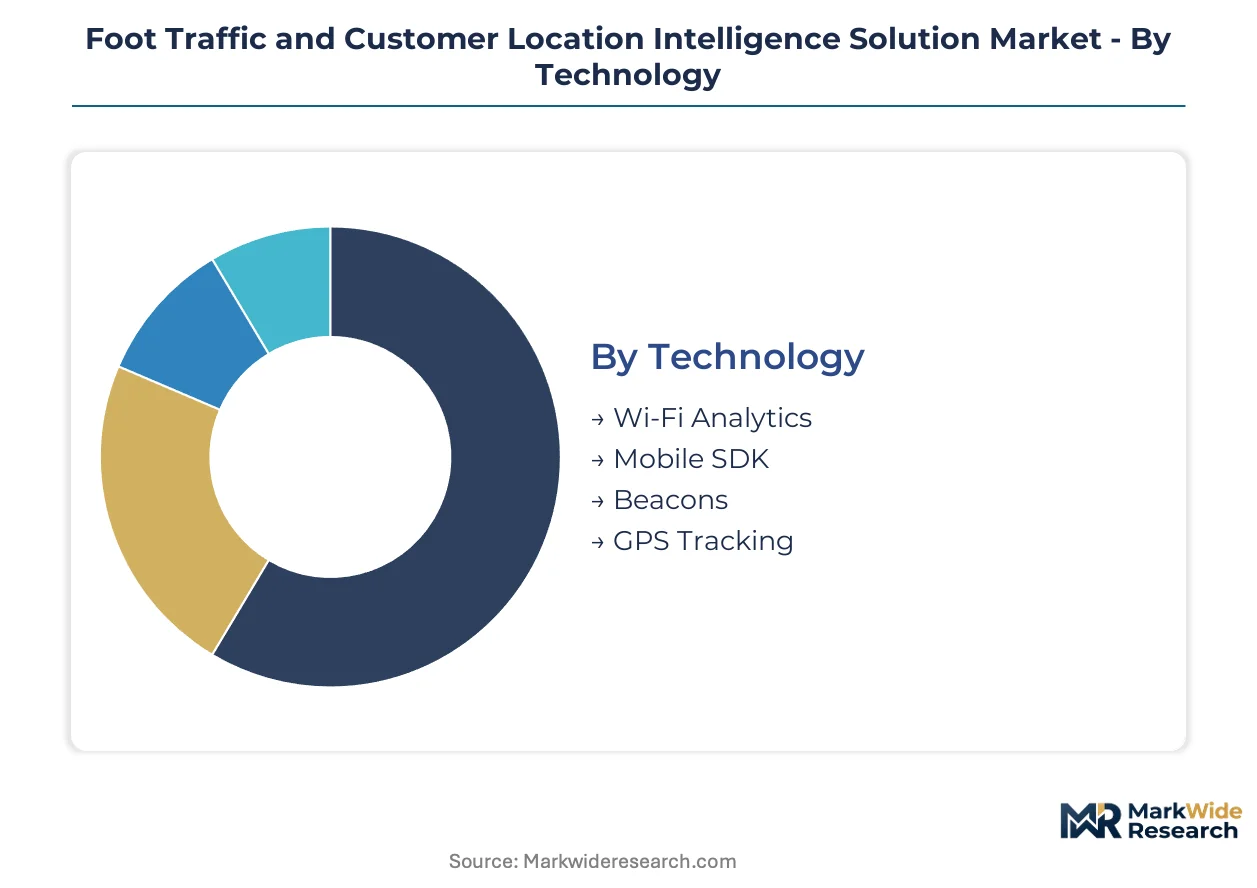
Technology selection determines data granularity, infrastructure cost, and regulatory exposure across deployment scenarios. Application focus shapes vendor R&D priorities and partnership ecosystems. End-user concentration in retail and transportation agencies concentrates purchasing power among a handful of large buyers.
Technology:
Wi-Fi Analytics and GPS Tracking dominate domestic infrastructure deployments, while Mobile SDK and Beacons concentrate in export-led software licensing models.
- Wi-Fi Analytics:Captures probe requests from smartphones and connected devices through existing access point infrastructure, enabling passive foot traffic measurement without dedicated hardware installation. Demand concentrates in United States retail chains and German transportation agencies seeking to retrofit legacy buildings with minimal capital expenditure.
- Mobile SDK:Embeds location permission workflows directly into iOS and Android applications, capturing GPS and beacon signals with explicit user consent. App publishers in China's domestic market integrate these kits into super-app ecosystems for loyalty program optimization, though iOS opt-in friction constrains sample completeness.
- Beacons:Bluetooth Low Energy transmitters enable proximity-based engagement with sub-meter accuracy for indoor positioning.
- GPS Tracking:Satellite-based positioning supports outdoor movement pattern analysis and fleet management integrations.
Wi-Fi Analytics commands the established base. The steepest expansion runs through Mobile SDK.
Application:
Cost tiering separates high-investment Smart Cities infrastructure from lower-friction Event Management deployments.
- Retail Analytics:Dwell-time measurement, visit frequency scoring, and competitive benchmarking enable store layout optimization and staffing allocation. United States department store chains and quick-service restaurant operators represent the primary demand concentration, with procurement consolidating around integrated platform contracts.
- Smart Cities:Municipal sensor networks for traffic optimization, public safety resource allocation, and transit network design require multi-year infrastructure commitments. Germany, China, and the United States lead deployment scale through dedicated smart city mandates and federal funding programs.
- Event Management:Crowd flow visualization and security resource positioning for temporary gatherings.
- Traffic Monitoring:Real-time congestion detection and signal timing optimization for transportation agencies.
Retail Analytics anchors current revenue. Smart Cities shows the steepest climb in contract value.
End User:
Customer type stratification separates enterprise-scale Retail Chains from project-based Event Organizers with diverging procurement cycles.
- Retail Chains:Multi-location operators require standardized analytics across hundreds or thousands of sites, driving demand for centralized dashboards and predictive demand forecasting modules. These buyers negotiate outcome-based pricing tied to same-store sales correlation metrics in the United States market.
- Transportation Agencies:Government entities in Germany, China, and the United States deploy location intelligence for traffic signal optimization and incident response resource positioning, with procurement constrained by public-sector budget cycles and vendor certification requirements.
- Event Organizers:Temporary deployment needs for crowd safety and vendor placement optimization.
- Hospitality Sector:Hotels and resorts measuring guest movement patterns for service positioning.
Retail Chains provide volume stability. Transportation Agencies deliver the longest contract tenures.
Solution:
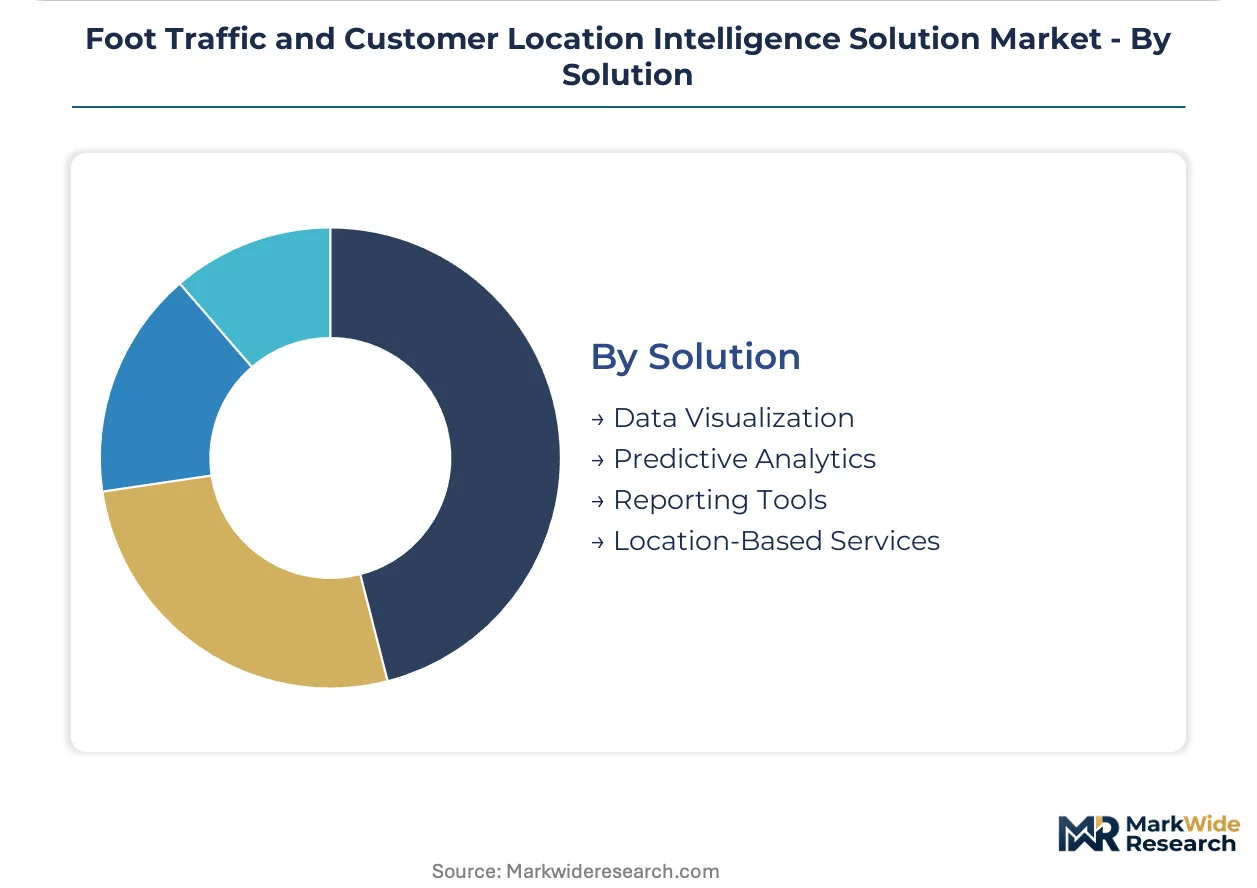
Margin tiering elevates Predictive Analytics above commoditized Reporting Tools through proprietary model differentiation.
- Predictive Analytics:Demand-forecasting modules integrating weather, event, and demographic variables command premium pricing from retail chains and hospitality operators seeking forward-looking occupancy and traffic projections. These solutions require specialized geospatial data science talent for model development and maintenance.
- Data Visualization:Pedestrian flow heatmaps, dwell-time dashboards, and comparative benchmarking interfaces represent the entry-tier offering, with differentiation hinging on rendering performance and API flexibility for enterprise system integration.
- Reporting Tools:Scheduled export capabilities and compliance documentation generators for audit trails.
- Location-Based Services:Real-time proximity triggers for marketing and operational workflows.
Data Visualization holds the installed base. Predictive Analytics captures the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where enterprise buyers negotiate outcome-based contracts, while Chinese vendors compete on volume-driven software licensing. Regulatory fragmentation across these three markets forces vendors to maintain parallel compliance architectures. Municipal smart city programs in each geography anchor infrastructure deployment timelines.
United States
Retail chains and quick-service restaurant operators drive demand for predictive analytics modules tied to same-store sales metrics. The FTC enforces Section 5 unfair-practice provisions against deceptive location-data collection, reshaping consent workflows for Wi-Fi probe request deployments. New York Metro and Greater Boston concentrate procurement activity among department store headquarters and transportation agencies.
Germany
Transportation agencies and municipal governments prioritize traffic optimization sensor networks with multi-year infrastructure commitments. The European Data Protection Board interprets GDPR Article 6 lawful-basis requirements for public space Wi-Fi tracking, clarifying compliance pathways for retail deployments. Bavaria and North Rhine-Westphalia lead smart city mandate implementation through federal funding programs.
China
Domestic app operators embed location permissions into super-app loyalty ecosystems, expanding passive data capture at scale. The Personal Information Protection Law mandates granular consent workflows and purpose-limitation documentation for GPS and beacon deployments. Yangtze River Delta and Pearl River Delta municipalities build out urban digitization infrastructure through state-directed investment.
India
Tier-2 and Tier-3 city digitization initiatives create first-mover positioning for infrastructure vendors seeking underpenetrated markets. The country's data protection framework imposes localization requirements on geospatial data processing, affecting cross-border analytics continuity. Maharashtra and Karnataka concentrate early smart city pilot deployments through central government funding allocation.
Foot Traffic and Customer Location Intelligence Solution Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with specialized geospatial data providers competing against integrated platform vendors on opposite ends of the margin spectrum. The vendor base separates into three strategic archetypes: proprietary dataset owners, automotive-grade positioning specialists, and retail-focused analytics platforms. Competitive moves concentrate on automated platform development to offset data science talent scarcity, and geographic expansion into underpenetrated smart city markets.
Within the proprietary dataset tier, SafeGraph and Foursquare occupy positions anchored by granular point-of-interest coverage and developer ecosystem loyalty respectively. HERE Technologies exemplifies the automotive-grade positioning archetype, extending its footprint from vehicle navigation systems into traffic monitoring deployments for transportation agencies. These three companies represent distinct competitive vectors—data asset depth, developer platform reach, and sensor fusion accuracy—that structure rivalry across application segments.
| Leading Market Players |
|---|
| SafeGraph |
| Crowd Connected |
| Foursquare |
| ESRI |
| Precisely |
| Placer Labs |
| Unacast |
| HERE Technologies |
| RetailNext |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day sensor procurement lead times for Bluetooth beacon and Wi-Fi access point hardware concentrate pricing power with East Asian contract manufacturers, compressing margin buffers for software-layer vendors while amplifying volume discounts for retail chains placing consolidated platform orders. This supply-chain rigidity forces mid-market operators toward software-defined deployments that virtualize signal capture through existing infrastructure, altering the cost structure across deployment tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order predictive analytics modules from standard data visualization dashboards. Subscription SaaS-tiered pricing dominates, with three-tier pricing structure across premium, standard, and economy levels differentiating by integration complexity and demographic enrichment depth. Cost compression in the visualization tier is intensifying because open-source rendering libraries commoditize basic heatmap functionality. Retail chains exhibit lowest price sensitivity, while Tier-2 municipal transportation agencies in India demonstrate highest elasticity.
Supply Chain Analysis
Strategic-stockpile preferences concentrate among German transportation agencies buffering against semiconductor lead-time volatility, while just-in-time procurement dominates US retail chains optimizing working capital. Hardware manufacturing centers on Taiwan, South Korea, and China for Bluetooth chipsets and Wi-Fi sensor components. Raw material dependencies span silicon wafers, rare earth magnets for beacon enclosures, and lithium-ion cells for portable deployments. Single-source vulnerability in advanced node semiconductor fabrication creates supply chain risk. Distribution runs through direct enterprise sales teams for predictive analytics, with value-added resellers handling mid-market visualization deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: GDPR Article 6 compliance frameworks and China's Personal Information Protection Law create certification barriers that entrench incumbent data processors with established consent infrastructure.
For Market Incumbents: Compound proprietary dataset depth through exclusive point-of-interest partnerships that lock out replication. Invest in automated bias auditing modules ahead of EU AI Act enforcement timelines. Vertical integration into edge computing hardware reduces cloud transmission costs and defends margin position against pure-software challengers.
For New Entrants and Emerging Players: Lead with consent-management middleware for China's domestic app operators rebuilding pipelines under Personal Information Protection Law mandates. India's Tier-2 smart city programs represent the most penetrable geography, with underdeveloped vendor certification requirements lowering entry friction. Partner with municipal system integrators rather than competing for direct procurement contracts.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive navigation divisions seeking to monetize traffic monitoring assets outside core vehicle infotainment revenue streams. Five-to-ten-year viability hinges on predictive analytics model accuracy retention as privacy regulations degrade longitudinal dataset completeness. Monitor iOS location permission opt-in rate trajectories as the critical inflection indicator for Mobile SDK addressable market sizing.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Consent Orchestration Platform | Reduces compliance engineering burden across FTC, GDPR, and PIPL jurisdictions simultaneously. |
| Edge Computing Hardware Integration | Lowers latency for real-time traffic monitoring while satisfying data sovereignty constraints. |
| Predictive Demand Forecasting Module Launch | Captures premium pricing from hospitality operators seeking weather-integrated occupancy projections. |
| Smart City Infrastructure Partnership | Secures multi-year municipal contracts with German transportation agencies prioritizing traffic optimization. |
| Mobile SDK Geographic Expansion | Penetrates India's super-app ecosystems before domestic location intelligence providers consolidate market position. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with retail chain analytics directors, municipal transportation agency procurement officers, location intelligence platform engineers, and mobile SDK integration specialists. Secondary validation drew from FTC enforcement action filings, European Data Protection Board guidance documents, China's Personal Information Protection Law implementation notices, SEC 10-K disclosures from listed geospatial technology providers, and smart city funding allocation databases. Bottom-up deployment estimates triangulated against top-down market sizing derived from sensor hardware shipment volumes and software licensing revenue patterns.
Across the analysis window, forecasts model technology segmentation by Wi-Fi Analytics, Mobile SDK, Beacons, and GPS Tracking; application segmentation by Retail Analytics, Smart Cities, Event Management, and Traffic Monitoring; and end-user segmentation by Retail Chains, Transportation Agencies, Event Organizers, and Hospitality Sector. CAGRs were derived from regression analysis against smart city infrastructure investment trajectories and retail digitization program adoption curves, with predictive analytics module pricing premiums and iOS opt-in rate assumptions as industry-specific forecast inputs.
Forecasts assume regulatory continuity in United States FTC Section 5 enforcement, European GDPR Article 6 interpretations, and China's Personal Information Protection Law implementation; material policy shifts would require re-modeling consent-friction coefficients and data retention limit scenarios. Revision becomes warranted when semiconductor fabrication capacity utilization or iOS privacy policy changes cross thresholds that alter hardware availability or addressable sample completeness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Australia Digital Twin Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Global Process Orchestration Market
Digital Solutions
Global Delivery Management Software Market
Digital Solutions
Bahrain ICT Market
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
Backup-As-A-Service (Baas) Market
Digital Solutions
Online Laundry Services Market
Digital Solutions
Digital Signage Services Market
Digital Solutions
Shipping Software Market
Digital Solutions
Service Orchestration Market
Digital Solutions
Webrtc Market