
 Digital Metronome Market | 2026-2036
Digital Metronome Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Metronome Market Insights
Buyer concentration among music education institutions is pivoting toward consolidated district-level procurement in North America and Europe, replacing individual instructor purchases. Korg leverages its synthesizer distribution network to bundle metronome sales through music retailer channels. Yamaha sustains institutional loyalty through integration with its silent piano systems and classroom management software. Soundbrenner differentiates via wearable haptic technology that extends beyond traditional audio click functions into body-rhythm training.
A digital metronome is an electronic tempo-keeping device that generates precise audible or visual beats per minute (BPM) within a range typically spanning 30 to 280 BPM, utilizing quartz-crystal or software-based timing engines for accuracy within ±0.1%. Its primary commercial purpose is to train rhythmic precision in musical practice, ensemble rehearsal, and recording studio environments where consistent tempo reference is essential. App-based metronomes now occupy the fastest-expanding margin pool as subscription models replace one-time hardware purchases among hobbyist users. Tabletop metronomes retain dominance in professional studio settings where physical knob interfaces and dedicated audio output remain non-negotiable workflow elements. Clip-on metronomes compete for portability share among traveling orchestral musicians who prioritize battery life and belt-clip durability over feature depth.
The FCC governs wireless transmission standards for Bluetooth-enabled metronome hardware sold in the United States, while the EU's RoHS and REACH frameworks restrict hazardous substances in circuit board manufacturing for European market access. Japan's METI enforces electrical appliance safety certifications that constrain import pathways for uncertified Asian manufacturers. Stakeholders must monitor evolving wireless protocol standards and regional substance-compliance thresholds to avoid product detention at customs checkpoints.
Market Dynamics
The migration from standalone hardware to app-integrated practice ecosystems is compressing unit economics while expanding addressable user bases through subscription monetization models.
Growth Catalysts
- Bluetooth Low Energy (BLE) protocol maturation:Wireless synchronization between metronomes and DAW software eliminates cable clutter in home studios, accelerating adoption among bedroom producers in Germany and the United States.
- Music education procurement centralization:Consolidated district-level purchasing in Texas and California replaces fragmented individual instructor orders, creating volume commitments that stabilize manufacturer revenue predictability.
- MIIT certification harmonization:China's streamlined wireless audio device approval process reduces time-to-market for compliant hardware, enabling faster product refresh cycles for export-focused Shenzhen manufacturers.
Market Restraints
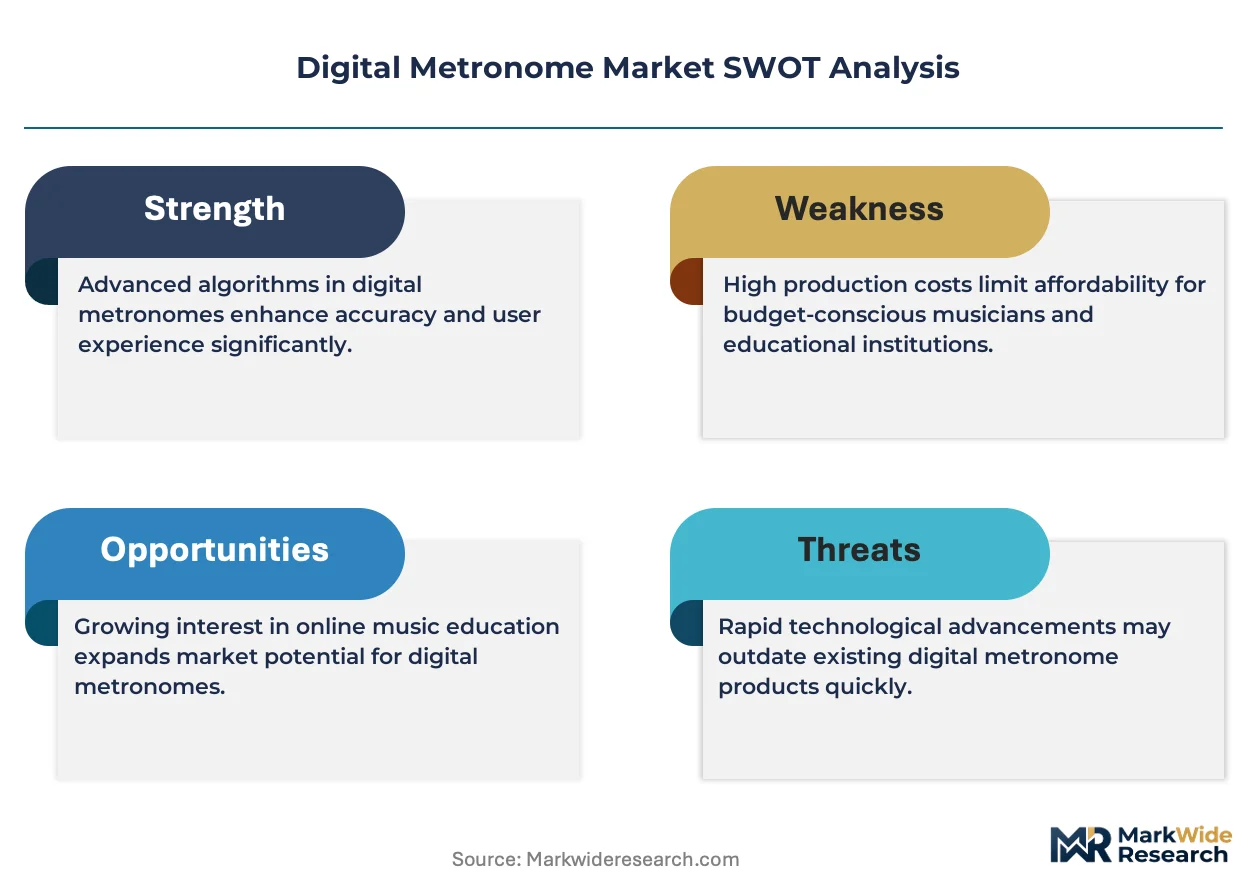
- Quartz crystal oscillator cost volatility:Precision timing component prices fluctuate with semiconductor foundry capacity allocation, squeezing margin on entry-level tabletop units.
- Single-source dependency for haptic actuators:Eccentric rotating mass motor supply concentrates among three East Asian component houses, exposing wearable metronome brands to allocation risk.
- Free smartphone app substitution:Basic tempo-keeping applications pre-installed on iOS and Android devices satisfy casual user needs without hardware expenditure.
Strategic Opportunities
- India's untapped institutional segment:Western classical music conservatories in Mumbai and Bangalore lack standardized practice-room equipment, presenting first-mover advantages for bundled hardware-software offerings.
- Biometric tempo adaptation:Heart rate variability sensors from fitness wearables are converging with metronome algorithms to create adaptive practice tools that respond to player stress indicators.
- South Korea's smart classroom mandates:Government digitization incentives for K-12 music education create procurement channels for networked metronome systems with teacher oversight dashboards.
Industry Challenges
- FCC Part 15 compliance timeline:Unintentional radiator certification for new Bluetooth chipset iterations delays product launches by four to six months, compressing selling seasons.
- Embedded firmware talent scarcity:Real-time audio processing expertise concentrates among senior developers in Tokyo and Seoul, inflating compensation for timing-critical software roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Metronome Market |
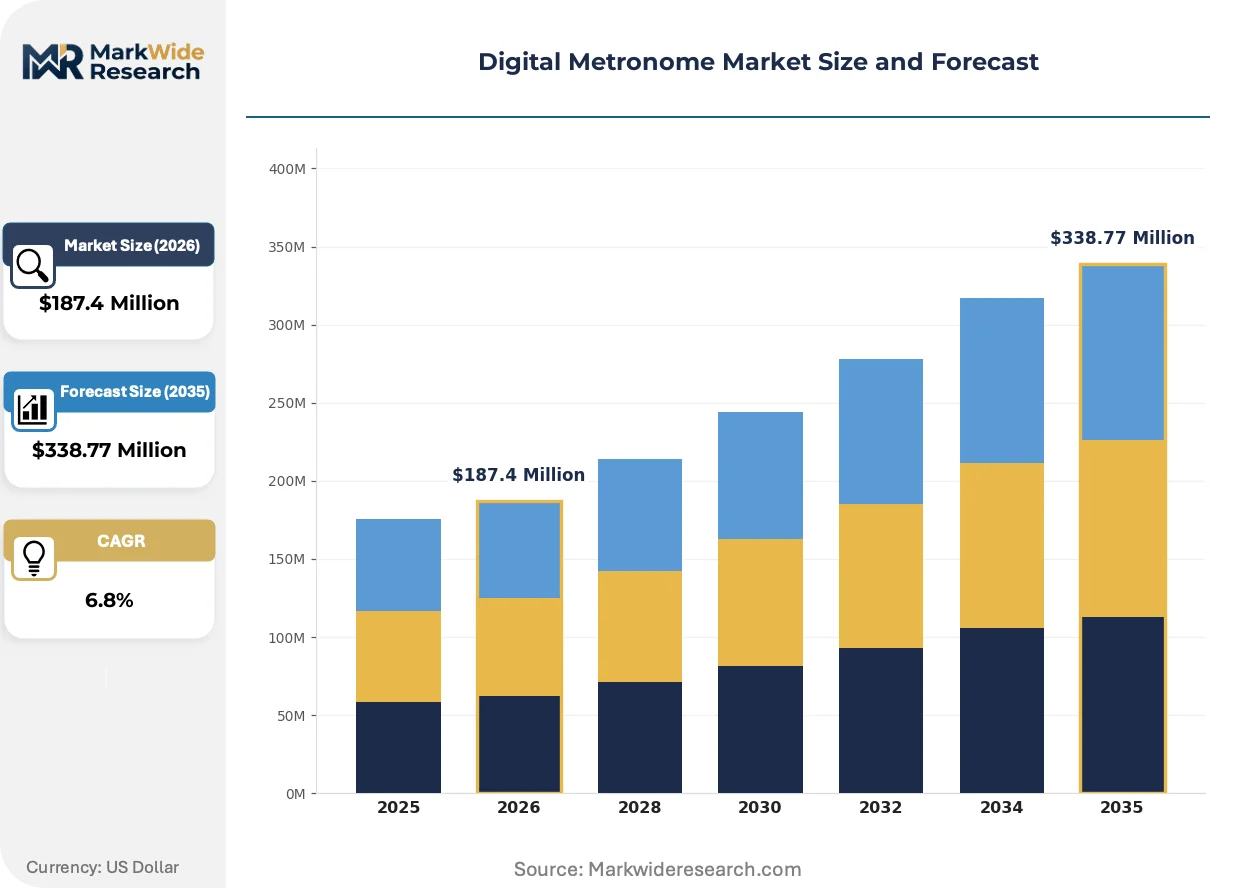
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Metronomes, Clip-On Metronomes, App-Based Metronomes, Digital Tuners End User: Musicians, Music Schools, Professional Studios, Hobbyists Feature: LED Display, Bluetooth Connectivity, Customizable Beats, Volume Control Deployment: Mobile Applications, Desktop Applications, Standalone Devices, Educational Platforms |
| Companies Covered | Korg, Yamaha, Boss, Soundbrenner, Roland, Wittner, Seiko, Cherub Technology, Peterson Electro-Musical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Metronome Market Trends and Innovations
Haptic feedback mechanisms are displacing audible click tracks across professional practice environments, while regulatory fragmentation around wireless protocols forces parallel certification strategies.
Polyrhythmic visualization software is integrating with traditional metronome hardware through companion tablet applications. Advanced music programs at Juilliard and Berklee now require students to practice against moving graphical representations of complex meter subdivisions. This convergence is integrating visual cognition training into previously audio-only tempo discipline, expanding the functional definition of metronome utility.
REACH substance restrictions on cadmium and lead in circuit board solder joints are forcing component substitutions across European-bound production lines. Manufacturers serving German and French markets now specify tin-silver-copper alloys that comply with ECHA hazard thresholds. Professional studio-grade tabletop units face the steepest reformulation costs due to their larger PCB surface areas and through-hole component densities.
District-level purchasing committees in Texas and California now bundle metronome procurement with broader instrument and classroom technology acquisitions. Individual instructor autonomy is contracting as standardized equipment lists replace discretionary spending authority. This concentration is most visible in public school systems where federal ESSER funding flows through centralized technology departments rather than departmental budgets.
Digital Metronome Market Segmentation
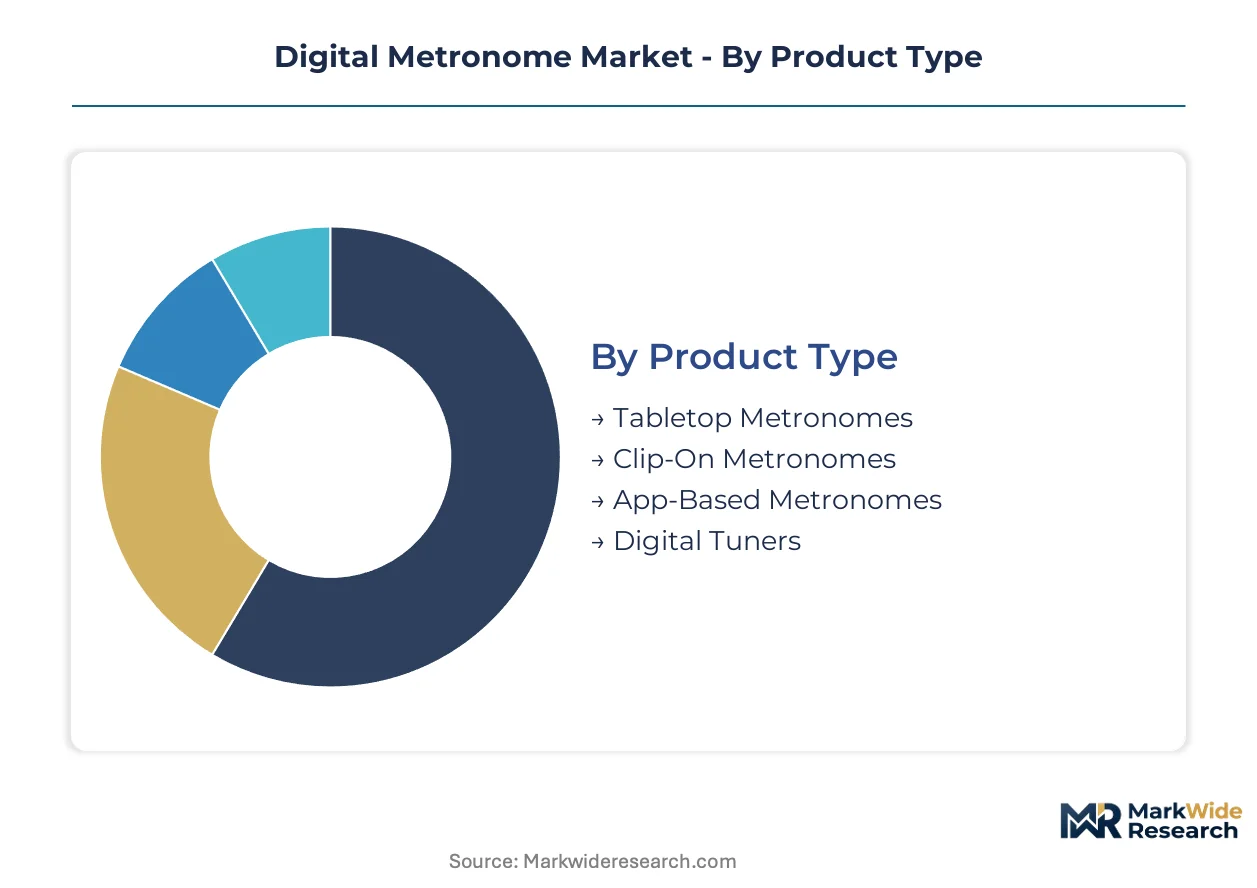
Digital metronome manufacturers configure production lines around distinct hardware-software boundaries, with component sourcing strategies varying sharply between quartz-dependent tabletop units and sensor-rich wearable variants. Segmentation clarity enables procurement teams to match institutional budgets against durability specifications and connectivity requirements.
Product Type:
Supply concentration for precision timing components clusters around Japanese and German quartz oscillator foundries, creating divergent cost structures across physical form factors.
- Tabletop Metronomes:These units incorporate discrete quartz-crystal timing engines housed in chassis with dedicated audio amplification circuits. Professional studios in Nashville and London specify these for their tactile knob interfaces and balanced XLR output options that integrate with console patch bays.
- Clip-On Metronomes:Belt-worn devices prioritize eccentric rotating mass motors and coin-cell battery architectures over acoustic drivers. Traveling orchestral musicians in Vienna and Chicago favor these for practice-room portability where headphone monitoring is impractical.
- App-Based Metronomes:Software implementations leverage device-native audio APIs and haptic feedback motors already present in smartphones. Subscription monetization models now dominate this segment as developers bundle polyrhythm visualization tools.
- Digital Tuners:Combination devices integrate pitch detection algorithms alongside tempo functions, requiring additional microphone or piezoelectric pickup hardware. These appeal to student violinists and guitarists seeking consolidated practice tools.
Tabletop metronomes absorb the bulk of installed capacity in professional recording environments; app-based variants are expanding most quickly through freemium-to-subscription conversion funnels.
End User:
Procurement authority is migrating from individual instructors toward centralized technology departments, reshaping volume discount structures and warranty negotiation leverage.
- Musicians:Individual performers select devices based on instrument-specific requirements—drummers prioritize accent pattern programming while pianists favor visual beat indicators. Direct-to-consumer channels capture this fragmented demand.
- Music Schools:Institutional buyers in Texas and California now issue standardized equipment lists for practice rooms, consolidating previously discretionary purchases. Bulk procurement contracts specify five-year replacement cycles and theft-deterrent mounting hardware.
- Professional Studios:Commercial recording facilities in Los Angeles and London demand rack-mountable units with MIDI clock synchronization and word-clock integration for DAW tempo alignment.
- Hobbyists:Casual practitioners exhibit highest price sensitivity and shortest replacement intervals, driving volume for entry-level clip-on units through mass-market music retailers.
Music schools concentrate the largest order volumes; hobbyist segments climb the fastest as beginner instrument sales rebound.
Feature:
Component bill-of-materials complexity escalates with wireless protocol integration, forcing manufacturers to maintain parallel SKUs for Bluetooth-enabled and basic configurations.
- LED Display:Seven-segment and dot-matrix implementations provide visual tempo confirmation for hearing-impaired users and silent practice scenarios. Battery drain considerations favor low-power OLED variants in premium units.
- Bluetooth Connectivity:BLE 5.0 modules enable synchronization with tablet-based sheet music applications and teacher oversight dashboards. South Korean smart classroom mandates are accelerating institutional adoption of networked practice tools.
- Customizable Beats:Polyrhythm programming capabilities accommodate complex meter subdivisions required by contemporary classical and jazz curricula. Juilliard and Berklee now specify these functions in student equipment requirements.
- Volume Control:Analog potentiometer or digital attenuation circuits adjust click intensity for ensemble rehearsal contexts where acoustic bleed must be minimized.
LED displays anchor the majority of unit shipments; Bluetooth connectivity gains share fastest as educational platforms mandate wireless integration.
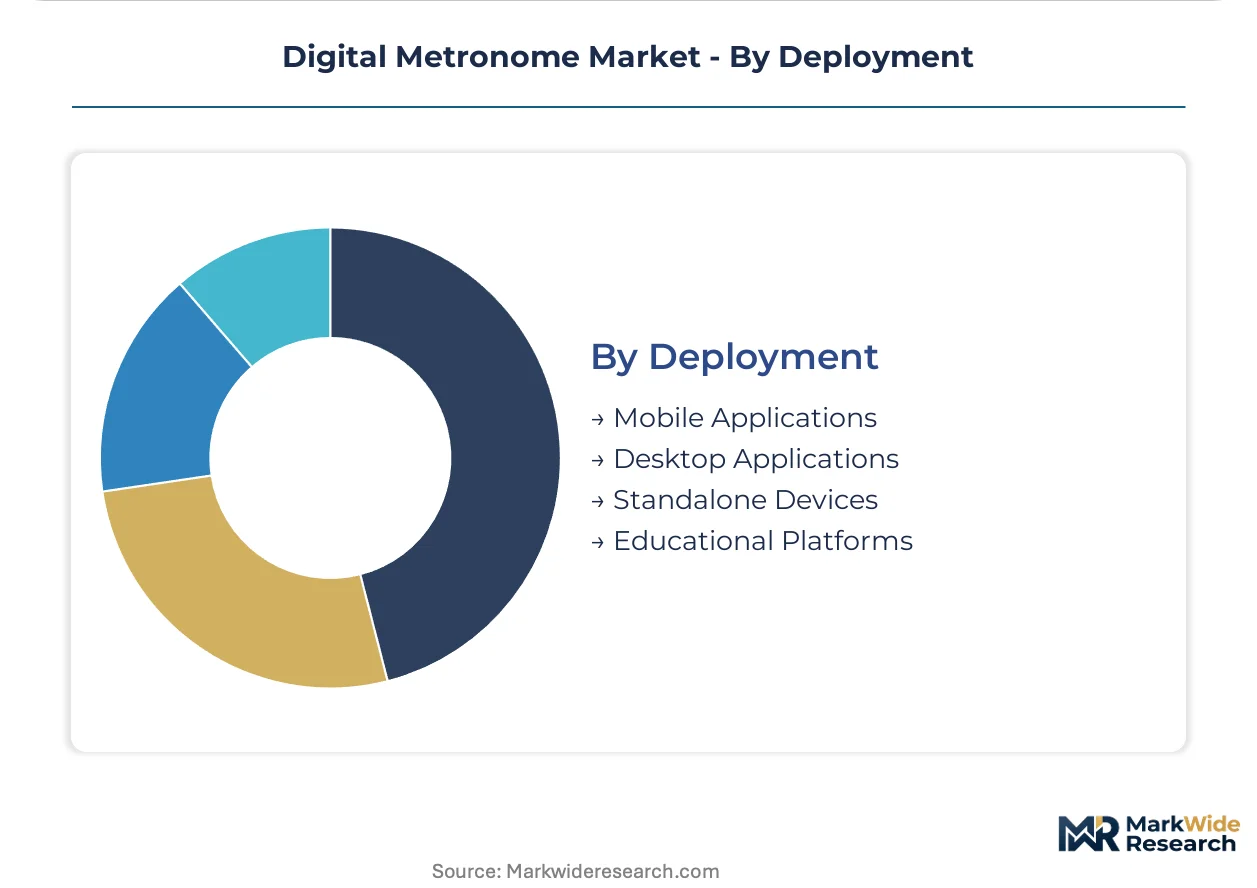
Deployment:
Software distribution economics favor cloud-based deployment models that decouple revenue from hardware manufacturing cycles.
- Mobile Applications:iOS and Android implementations dominate hobbyist segments through app store distribution and subscription billing infrastructure. Freemium tiers with basic tempo functions convert users to paid polyrhythm modules.
- Desktop Applications:macOS and Windows plugins integrate with DAW software via AU, VST, or AAX formats. Bedroom producers in Berlin and Austin favor these for tempo mapping during composition workflows.
- Standalone Devices:Purpose-built hardware without companion software dependencies persists in professional contexts where operating system updates risk workflow disruption.
- Educational Platforms:Institutional deployments bundle metronome functions within broader learning management systems, enabling practice-time analytics and instructor remote monitoring.
Standalone devices retain the largest installed base in professional settings; educational platforms are climbing fastest as district-level procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quartz crystal oscillator foundries in Japan and Germany anchor precision timing component supply for digital metronome manufacturing. These localities feed assembly operations across three continents while regional certification regimes reshape market access conditions.
United States
District-level procurement consolidation in Texas and California music education systems drives volume demand for networked practice tools. FCC Part 15 certification governs Bluetooth-enabled hardware distribution, creating four-to-six month approval timelines for new chipset iterations. Nashville recording studios specify tabletop units with MIDI clock synchronization for DAW integration.
Germany
Bedroom producers in Berlin favor desktop metronome plugins with AU and VST format compatibility for composition workflows. REACH substance restrictions on cadmium and lead in circuit board solder joints force tin-silver-copper alloy substitutions in European-bound production lines. Frankfurt-area retailers bundle metronome sales with silent piano systems through consolidated music equipment distribution.
China
Shenzhen manufacturers accelerate product refresh cycles following MIIT certification harmonization for wireless audio devices. Export-focused production clusters face compliance restructuring as certification requirements reshape hardware export pathways. Pearl River Delta assembly operations supply entry-level clip-on units to traveling orchestral musicians in Europe and North America.
Japan
METI electrical appliance safety certifications constrain import pathways for uncertified Asian manufacturers seeking market entry. Tokyo and Seoul concentrate embedded firmware talent for real-time audio processing roles, inflating compensation for timing-critical software positions. Kanto region synthesizer distribution networks bundle metronome sales through established music retailer channels.
South Korea
Government digitization incentives for K-12 music education create procurement channels for networked metronome systems with teacher oversight dashboards. Bluetooth-enabled practice tools dominate student segment preferences in Seoul and Busan. Smart classroom mandates accelerate institutional adoption of BLE 5.0 modules synchronized with tablet-based sheet music applications.
Digital Metronome Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue wearable haptic technology and app-integrated practice ecosystems. The vendor base spans diversified musical instrument conglomerates, precision timing specialists, and software-native developers. Three strategic archetypes dominate: synthesizer distributors leveraging retail channel bundling, silent piano system integrators capturing institutional loyalty, and wearable technology developers differentiating through body-rhythm training. Competitive moves concentrate on strategic partnerships with music education platforms and portfolio diversification into biometric tempo adaptation.
Within the diversified instrument conglomerate tier, Korg and Yamaha exemplify distinct positioning strategies. Korg occupies a position anchored in synthesizer distribution network leverage for retail channel penetration. Yamaha sits within the institutional loyalty segment through integration with silent piano systems and classroom management software. Soundbrenner represents the wearable technology archetype, differentiating via haptic feedback mechanisms that extend beyond traditional audio click functions.
| Leading Market Players |
|---|
| Korg |
| Yamaha |
| Boss |
| Soundbrenner |
| Roland |
| Wittner |
| Seiko |
| Cherub Technology |
| Peterson Electro-Musical Products |
| Others |
Pricing and Supply Chain Analysis
Quartz crystal oscillator foundries in Japan and Germany feed precision timing components through three pricing tiers, with raw material volatility in semiconductor-grade silicon compressing margins on entry-level tabletop units while professional studio-grade hardware retains premium positioning through XLR output bundling and extended warranty terms.
Pricing Analysis
Warranty bundling separates professional studio-grade tabletop units from economy clip-on variants, with Nashville and London recording facilities paying premiums for five-year replacement guarantees and theft-deterrent mounting hardware. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FCC Part 15 and METI compliance adding cost layers to Bluetooth-enabled configurations. Pricing pressure stems from free smartphone app substitution in hobbyist segments, where iOS and Android native tempo tools eliminate hardware expenditure for casual users. Music schools exhibit lowest price sensitivity due to federal ESSER funding flows, while individual musicians face acute budget constraints.
Supply Chain Analysis
Direct-to-retail channels handle fragmented individual musician demand, while consolidated district-level procurement in Texas and California flows through specialized music equipment distributors. Component sourcing concentrates in Japan, Germany, and China, with Shenzhen assembly operations feeding entry-level clip-on units and Kanto-region foundries supplying precision quartz oscillators. Raw material dependencies span semiconductor-grade silicon, tin-silver-copper solder alloys for REACH compliance, and eccentric rotating mass motors from East Asian component houses. Single-source vulnerability for haptic actuators exposes wearable metronome brands to allocation risk during foundry capacity crunches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quartz crystal oscillator foundry capacity constraints prop pricing power for certified precision timing component suppliers, with semiconductor-grade silicon allocation bottlenecks limiting entry-level unit production expansion.
For Market Incumbents: Hedge against app-based substitution by deepening integration with silent piano systems and classroom management software platforms. Secure captive supply of haptic actuators through long-term offtake agreements with East Asian component houses to mitigate allocation risk from eccentric rotating mass motor concentration. Prioritize FCC Part 15 pre-certification investments to compress four-to-six month approval timelines for Bluetooth chipset iterations. For New Entrants and Emerging Players: Capture white-space in India's untapped institutional segment, where Western classical music conservatories in Mumbai and Bangalore lack standardized practice-room equipment. Target biometric tempo adaptation convergence with heart rate variability sensors from fitness wearables, creating adaptive practice tools that respond to player stress indicators. Pursue bundled hardware-software offerings through direct institutional sales rather than retail channel competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision timing specialists with established METI and FCC certification portfolios in Japan and the United States. Long-term viability hinges on embedded firmware talent concentration in Tokyo and Seoul for real-time audio processing capabilities. Watch for MIIT certification harmonization completion as inflection indicator for Shenzhen manufacturer export acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Sensor Integration | Heart rate variability convergence creates adaptive tempo tools responding to player stress indicators. |
| Backward Integration into Haptic Actuators | Captive supply of eccentric rotating mass motors mitigates single-source allocation risk from East Asian component houses. |
| Educational Platform Partnership | South Korean smart classroom mandates create procurement channels for networked metronome systems with teacher oversight dashboards. |
| REACH Compliance Reformulation | Tin-silver-copper alloy substitution in European-bound production lines maintains market access under ECHA hazard thresholds. |
| Silent Piano System Bundling | Integration with Yamaha's established institutional loyalty programs captures consolidated district-level procurement in Texas and California. |
Research Methodology
Trade publications, customs databases, and semiconductor foundry capacity reports formed the secondary backbone, cross-referenced with primary interviews spanning metronome hardware engineers, music school procurement directors, music retailer category managers, and embedded firmware developers. Bottom-up and top-down triangulation validated shipment volumes and pricing tiers across tabletop, clip-on, wearable, and app-based product configurations.
Bottom-up modeling built from unit economics across product type, end user, feature set, and deployment mode, while top-down constraints anchored aggregate market size against musical instrument sales correlation and music education enrollment trends. CAGRs derived from segment-level growth rate blending across the projection horizon, with Bluetooth Low Energy protocol maturation and district-level procurement centralization as key demand drivers. Inputs incorporated FCC Part 15 certification timelines, MIIT harmonization progress, and REACH substance restriction phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to quartz crystal oscillator cost volatility and free smartphone app substitution rates. Periodic stress-testing of base assumptions is recommended, particularly around embedded firmware talent scarcity in Tokyo and Seoul and evolving wireless protocol standards requiring parallel certification strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Smart Offices Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
Parking Management Systems Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
United Kingdom ICT Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
GCC and Africa ICT Market
Digital Solutions
Global Structured Data Archiving and Application Retirement Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Computer Aided Design (CAD) Market