
 Search Engine Optimization Services Market | 2026-2036
Search Engine Optimization Services Market Size, Share, and Industry Trends Forecast 2026-2036
Search Engine Optimization Services Market Intelligence
ISO/IEC 27001 certification is unwinding the competitive landscape for SEO service providers, as enterprise clients mandate information security management proof before contract award. WebFX leverages its full-service digital marketing infrastructure to anchor mid-market accounts across multiple verticals. Titan Growth competes through proprietary technology platforms that automate technical audit workflows. Sure Oak specializes in link-building campaigns for SaaS companies, occupying a narrow but defensible niche.
Search engine optimization services encompass systematic methods to improve website visibility in organic search results through technical infrastructure refinement, content relevance enhancement, and authority signal cultivation. Core deliverables include crawl budget optimization, schema markup implementation, and backlink profile remediation designed to elevate domain authority scores and qualified traffic acquisition. Technical SEO and local SEO represent the fastest-expanding service type categories, driven by mobile-first indexing mandates and hyperlocal commerce digitization. The managed services delivery model dominates enterprise accounts, while DIY tools capture price-sensitive small business segments where margin pools remain thinner.
The Federal Trade Commission scrutinizes deceptive ranking claims in SEO marketing, while the EU AI Act imposes disclosure obligations on automated content generation tools used in optimization workflows. The California Consumer Privacy Act constrains how SEO practitioners deploy user behavioral data for personalization and retargeting strategies. Stakeholders must monitor evolving algorithm transparency requirements and privacy jurisprudence to calibrate service architectures and client contractual frameworks.
Market Dynamics
Google's mobile-first indexing mandate and the EU AI Act's transparency requirements are forcing SEO service providers to rebuild technical audit methodologies and client reporting frameworks from the ground up.
Growth Catalysts
- E-commerce Platform Saturation:Marketplace sellers in the United States and Germany now treat organic search visibility as a survival necessity, not a growth option. This shifts SEO from discretionary marketing spend to fixed operational cost.
- ISO/IEC 27001 Certification Mandates:Enterprise procurement teams in financial services and healthcare verticals require information security management proof before contract award, filtering out uncertified competitors.
- Hyperlocal Commerce Digitization:Small retailers across India and Brazil are adopting local SEO services to capture "near me" search intent as smartphone penetration deepens in tier-2 and tier-3 cities.
Market Restraints
- Technical Talent Scarcity:The pool of engineers capable of JavaScript rendering optimization and Core Web Vitals remediation remains concentrated in San Francisco, London, and Bangalore, creating wage inflation pressure.
- Algorithm Opacity:Google's proprietary ranking systems prevent SEO providers from offering guaranteed outcomes, forcing contingency-based pricing models that compress margins.
- Privacy Regulation Friction:The California Consumer Privacy Act constrains behavioral data deployment for personalization strategies, limiting retargeting effectiveness in the United States market.
Strategic Opportunities
- AI-Generated Content Disclosure:The EU AI Act creates compliance service demand as European enterprises require audit trails for automated content workflows used in optimization campaigns.
- SaaS Vertical Specialization:Link-building and technical infrastructure services for software-as-a-service companies remain underpenetrated relative to retail and media verticals.
- Voice Search Architecture:Natural language query optimization for smart speakers and automotive interfaces opens new service categories as conversational AI adoption accelerates in South Korea and Japan.
Industry Challenges
- Schema Markup Standardization Lag:Fragmented implementation guidelines across industry verticals force SEO providers to maintain multiple technical specification libraries, increasing operational complexity.
- Cross-Functional Integration:Technical SEO recommendations require coordination with engineering teams, content operations, and paid media functions that operate on conflicting timelines and incentive structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Search Engine Optimization Services Market |
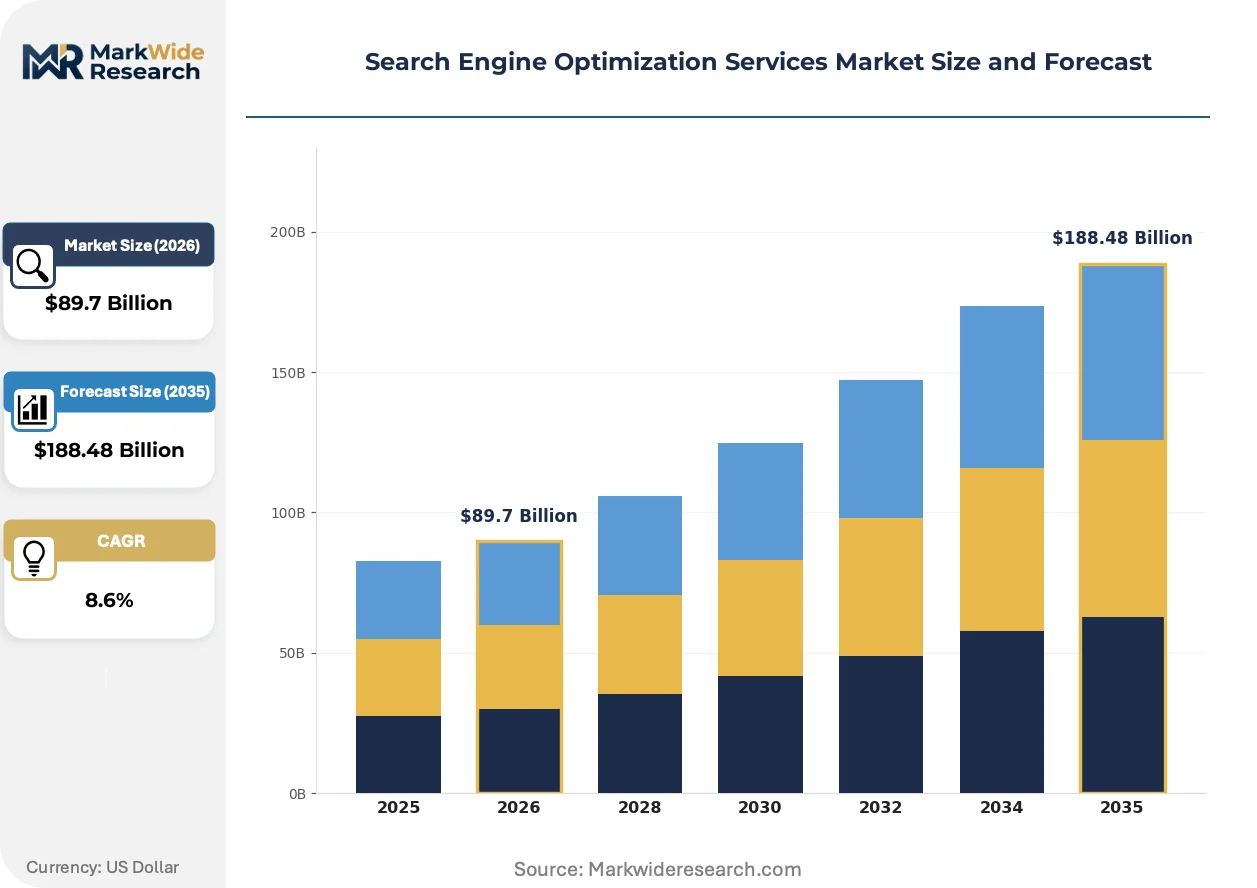
| Market Size in 2026 | $89.7 Billion |
| Market Size in 2035 | $188.48 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: On-page Optimization, Off-page Optimization, Technical SEO, Local SEO Delivery Model: Consulting, Managed Services, DIY Tools, Hybrid Solutions End User: Small Businesses, Enterprises, E-commerce, Digital Agencies Pricing Model: Fixed Price, Hourly Rate, Performance-based, Subscription |
| Companies Covered | Victorious, Straight North, Titan Growth, Sure Oak, WebFX, Intero Digital, Searchbloom, SmartSites, First Page Sage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Search Engine Optimization Services Market Strategic Shifts & Innovations
Machine learning inference engines and automated content generation tools are fragmenting traditional SEO workflows into specialized micro-services, compressing project timelines and reshaping how clients evaluate provider capabilities.
Generative AI content pipelines are decomposing conventional editorial workflows by automating keyword research, outline generation, and metadata production at scale. Mid-market e-commerce operators in Germany and the United States are adopting these tools to maintain publishing velocity without proportional headcount expansion. This technology is decomposing the traditional full-service agency model into modular, API-connected specialist layers.
The EU AI Act's transparency obligations are mandating disclosure of automated decision-making in content ranking and generation workflows. European SEO providers must now maintain audit trails for algorithmic recommendations delivered to clients. SaaS companies operating across multiple EU member states face the steepest compliance burden as they reconcile national implementations of the framework.
Enterprise buyers are consolidating vendor relationships and demanding outcome-based contracts tied to qualified traffic or revenue attribution rather than activity metrics. This displaces traditional retainer models in the United States financial services and healthcare verticals where procurement teams now require proof of incremental revenue contribution. The shift is most visible in New York and Chicago, where enterprise marketing operations have invested in attribution infrastructure.
Search Engine Optimization Services Market Segmentation
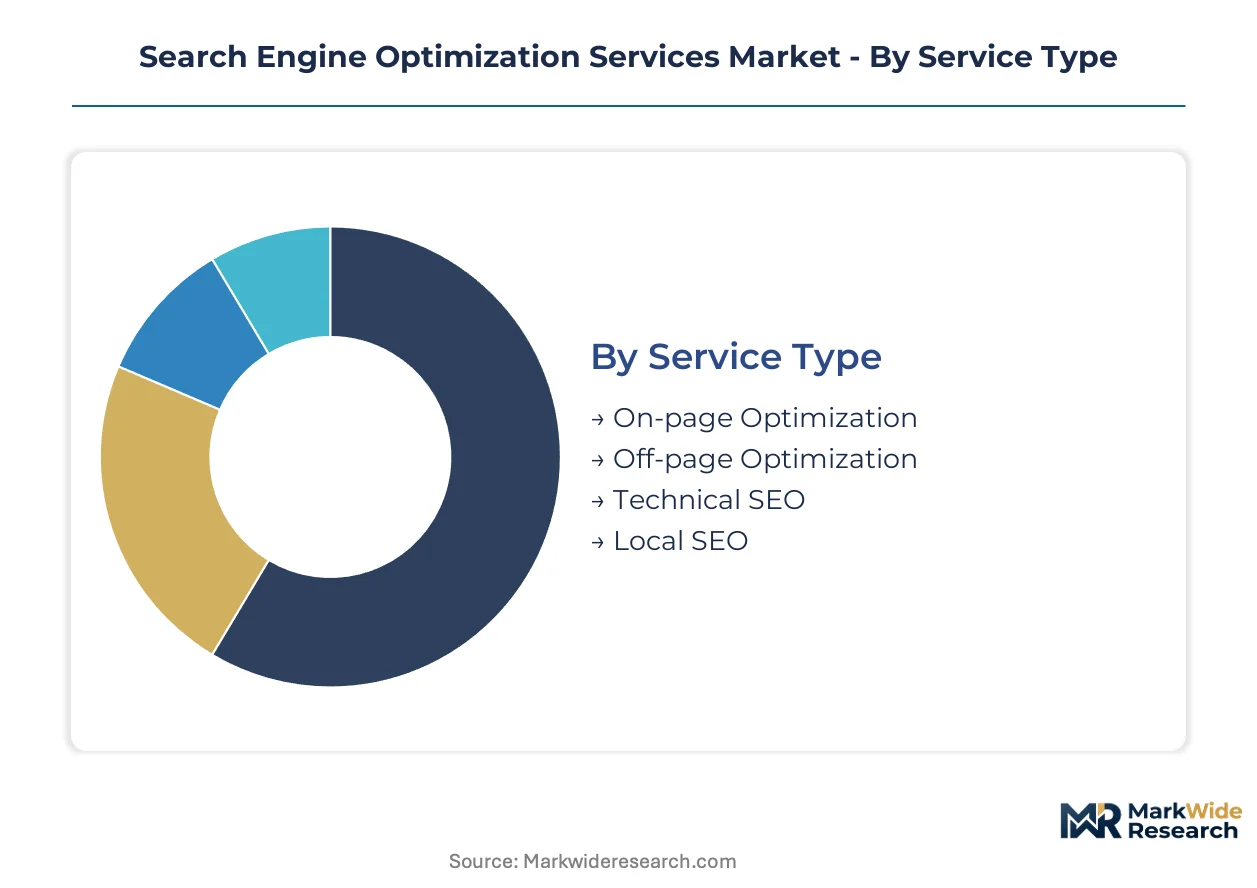
SEO service providers structure offerings around distinct technical capabilities, engagement models, and buyer economics. Segmentation reveals where margin pools concentrate and which delivery formats command premium pricing.
Service Type:
Margin pools concentrate in specialized technical disciplines that require scarce engineering talent and command retainer premiums.
- On-page Optimization:Content refinement, metadata enhancement, and internal linking architecture designed to improve relevance signals. United States e-commerce platforms drive concentrated demand as marketplace sellers compete for organic visibility.
- Off-page Optimization:Authority cultivation through backlink acquisition, digital PR, and brand mention campaigns. SaaS companies in Germany and the United States represent the fastest-closing demand gap as link equity becomes decisive for competitive keywords.
- Technical SEO:Crawl budget management, JavaScript rendering optimization, and Core Web Vitals remediation. Enterprise procurement teams mandate this for site migrations and platform replatforming initiatives.
- Local SEO:Google Business Profile optimization, citation management, and geo-targeted content strategies. Tier-2 cities in India and Brazil generate expanding demand as smartphone penetration deepens hyperlocal commerce.
The dominant share belongs to On-page Optimization, while Local SEO is closing the gap fastest.
Delivery Model:
Volume concentration shifts toward integrated engagements that embed providers within client operating rhythms.
- Consulting:Project-based audits, strategy development, and advisory retainers for in-house teams. Financial services enterprises in New York and Chicago favor this model for compliance-sensitive implementations.
- Managed Services:Continuous optimization, reporting, and technical maintenance delivered through dedicated account teams. This format captures the deepest enterprise spend pools and longest contract tenures.
- DIY Tools:Self-service platforms for keyword tracking, rank monitoring, and competitive analysis. Small business segments with thinner margins and limited procurement sophistication adopt these solutions.
- Hybrid Solutions:Blended engagements combining platform access with periodic expert intervention. Mid-market e-commerce operators in Germany and the United States gravitate toward this flexibility.
Managed Services commands the largest revenue base, though Hybrid Solutions are gaining traction among buyers seeking cost discipline without capability sacrifice.
End User:
Customer type determines pricing power, contract structure, and sales cycle complexity.
- Small Businesses:Local service providers, independent retailers, and professional practices with limited marketing budgets. Price sensitivity pushes this segment toward DIY tools and templated service packages.
- Enterprises:Fortune 500 corporations, healthcare systems, and financial institutions with dedicated procurement functions. ISO/IEC 27001 certification and outcome-based contracting requirements filter vendor pools aggressively.
- E-commerce:Marketplace sellers, direct-to-consumer brands, and multi-channel retailers. Organic search visibility functions as fixed operational cost rather than discretionary spend for this category.
- Digital Agencies:Creative shops, media buyers, and full-service firms white-labeling SEO capabilities. This segment values speed, scalability, and minimal client-facing friction.
Enterprises generate the highest contract values, while E-commerce is expanding most quickly as platform saturation intensifies.
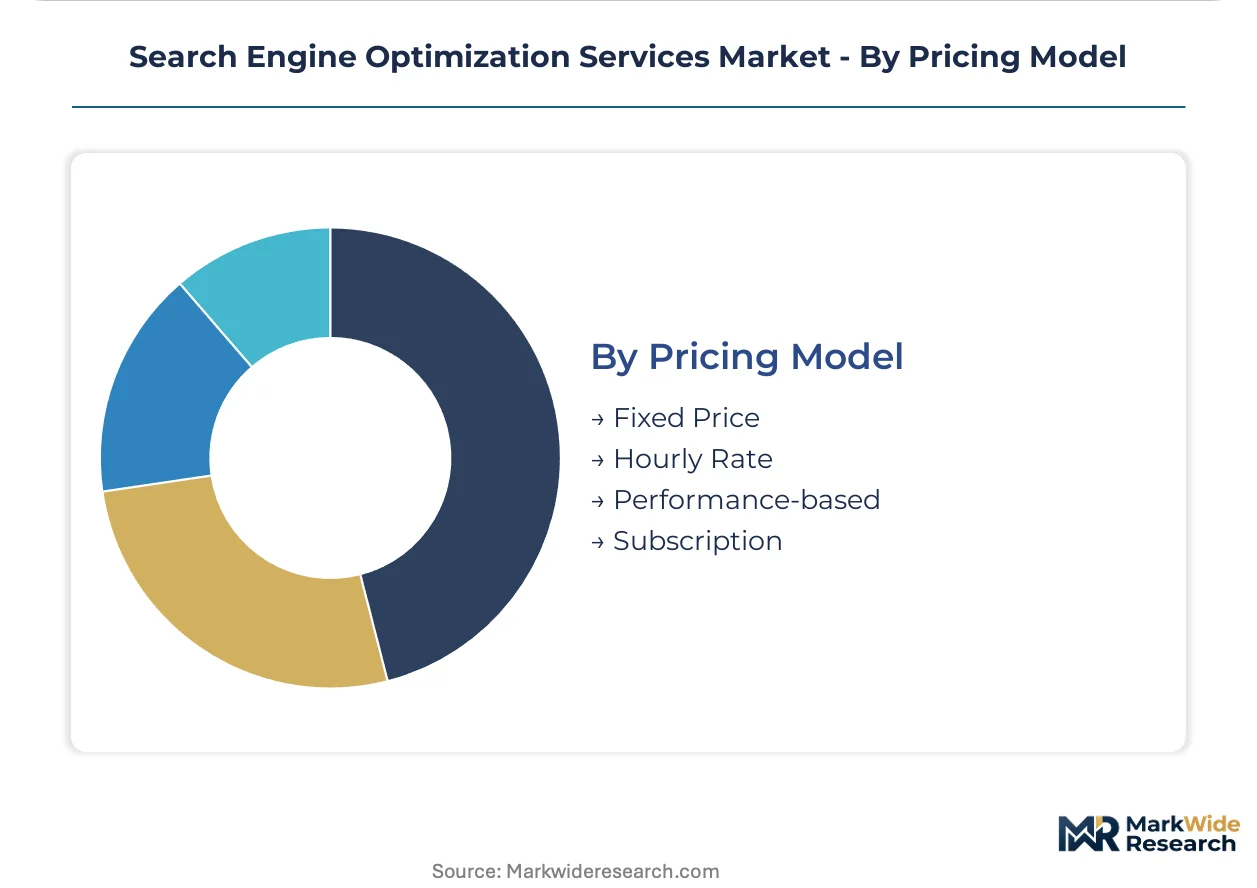
Pricing Model:
Payment structure reflects risk allocation between provider and client, with implications for margin stability.
- Fixed Price:Scoped engagements with defined deliverables and timelines. Small businesses and project-based consulting favor this predictability.
- Hourly Rate:Time-and-materials billing for ad hoc support and technical troubleshooting. Digital agencies and enterprise staff augmentation use this format.
- Performance-based:Compensation tied to rank improvements, traffic growth, or revenue attribution. Google's algorithm opacity constrains provider willingness to accept pure contingency terms.
- Subscription:Recurring monthly fees for ongoing optimization, reporting, and support. Managed services and hybrid solutions deploy this structure to smooth revenue recognition.
Subscription models anchor the largest revenue base, though Performance-based pricing is climbing fastest as procurement teams demand proof of incremental contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams concentrate in the United States, Germany, and United Kingdom, where technical talent pools and e-commerce platform density drive premium service demand. Mid-market adoption accelerates in India and Brazil as smartphone penetration deepens hyperlocal commerce digitization.
United States
Financial services and healthcare enterprises in New York and Chicago mandate ISO/IEC 27001 certification before contract award, filtering vendor pools aggressively. The FTC scrutinizes deceptive ranking claims in SEO marketing, forcing transparency in client reporting. San Francisco and Austin anchor the deepest technical talent concentrations for JavaScript rendering optimization and Core Web Vitals remediation.
Germany
E-commerce marketplace sellers treat organic visibility as operational necessity rather than discretionary spend, compressing sales cycles for technical SEO providers. The EU AI Act imposes disclosure obligations on automated content generation tools used in optimization workflows. Munich and Berlin host the densest clusters of SaaS companies purchasing link-building and authority cultivation services.
United Kingdom
Digital agencies in London white-label SEO capabilities to capture speed and scalability without building in-house technical teams. GDPR constraints limit behavioral data deployment for personalization strategies, reshaping retargeting service architectures. The capital's financial services procurement teams demand outcome-based contracts tied to qualified traffic attribution.
India
Tier-2 and tier-3 cities generate expanding demand for local SEO as smartphone penetration deepens hyperlocal commerce digitization among small retailers. The country's central bank monitors fintech marketing compliance, indirectly constraining how SEO practitioners deploy user data. Bangalore and Hyderabad concentrate engineering talent for technical audit platform development serving export markets.
Brazil
São Paulo-based e-commerce operators adopt managed services delivery models to navigate platform algorithm volatility without building internal technical teams. ANVISA regulates health product marketing claims, intersecting with SEO content compliance requirements. The city's advertising cluster drives regional pricing benchmarks for Latin American mid-market accounts.
Search Engine Optimization Services Market Key Industry Players
Player mix skews toward specialized boutiques and full-service digital marketing infrastructure providers rather than pure-play scale operators. Market structure fragments across technical capability tiers, with premium positions held by firms possessing proprietary audit platforms and ISO/IEC 27001 certification. Two strategic archetypes dominate: technology-enabled specialists automating technical workflows, and vertically integrated full-service agencies capturing cross-sell revenue. Competitive moves center on certification acquisition for enterprise access and outcome-based contract structuring to displace traditional retainers.
Within the technology-enabled tier, Titan Growth and Sure Oak exemplify divergent specialization strategies. Titan Growth anchors its position through proprietary platforms automating technical audit workflows, while Sure Oak occupies a narrow but defensible niche in link-building campaigns for SaaS companies. WebFX represents the full-service infrastructure archetype, leveraging integrated digital marketing capabilities to anchor mid-market accounts across multiple verticals. Victorious and Straight North sit within the outcome-based contracting vanguard, structuring engagements around rank improvements and traffic attribution rather than activity metrics.
| Leading Market Players |
|---|
| Victorious |
| Straight North |
| Titan Growth |
| Sure Oak |
| WebFX |
| Intero Digital |
| Searchbloom |
| SmartSites |
| First Page Sage |
| Others |
Cost & Logistics Intelligence
Thirty-day technical audit delivery cycles concentrate pricing power among certified providers in San Francisco and London, compressing margins for uncertified competitors who cannot meet enterprise procurement timelines. This lead-time band shapes how SEO service providers structure talent acquisition and platform automation investments.
Pricing Analysis
Cost-plus contracts indexed to engineering labor rates in Bangalore and San Francisco dominate enterprise engagements, with ISO/IEC 27001 certification commanding premium-mid-economy pricing differentiation. Subscription models anchor revenue stability for managed services, while performance-based structures face compression because Google's algorithm opacity prevents guaranteed outcome clauses. Small businesses exhibit highest price sensitivity, gravitating toward DIY tools, whereas Fortune 500 procurement teams prioritize certification over cost.
Supply Chain Analysis
Inventory of technical talent concentrates in the United States, India, and the United Kingdom, with seventy-five-day hiring cycles for Core Web Vitals specialists creating bottleneck conditions. The supply chain draws from software engineering pipelines, cloud infrastructure providers, and proprietary audit platform developers. Single-source vulnerability sits with concentrated JavaScript optimization expertise in Bangalore and San Francisco. Distribution runs through direct enterprise sales teams, digital agency partnerships, and self-service platform portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI content tools threaten to displace traditional editorial-heavy SEO workflows, forcing incumbents to defend through proprietary technology and outcome-based contracting that automation cannot easily replicate.
For Market Incumbents: Compound defensive positioning through ISO/IEC 27001 certification investments and proprietary technical audit platform development. Vertical integration into automated content generation workflows addresses the generative AI substitution threat. Outcome-based contract structuring with revenue attribution clauses displaces vulnerable retainer models.
For New Entrants and Emerging Players: SaaS vertical specialization in link-building and authority cultivation represents the most penetrable white-space, as incumbent coverage remains thin relative to retail and media. Local SEO services for tier-2 Indian and Brazilian cities offer geographic entry with lower competitive density. Go-to-market through white-label partnerships with digital agencies minimizes client acquisition friction.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because enterprise procurement teams are consolidating vendor relationships and mandating certification barriers that favor scaled providers. Acquisition targets should possess proprietary audit platforms and established ISO/IEC 27001 credentials. The signal to watch is FTC enforcement action against deceptive ranking claims, which would accelerate compliance-driven vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Platform Development | Automated technical audit workflows differentiate Titan Growth from labor-dependent competitors. |
| ISO/IEC 27001 Certification Investment | Enterprise procurement teams in New York financial services mandate this credential before contract award. |
| SaaS Vertical Specialization | Link-building campaigns for software companies occupy a narrow but defensible niche like Sure Oak's positioning. |
| Outcome-Based Contract Structuring | Revenue attribution clauses displace activity-based retainers in Chicago healthcare procurement. |
| Hybrid Solution Expansion | Blended platform-expert engagements capture mid-market e-commerce demand in Germany and the United States. |
Research Approach
A standing panel of SEO agency executives, enterprise marketing procurement officers, technical audit engineers, and SaaS growth leaders provided ongoing calibration across the analysis window. Primary interview data combined with secondary validation from SEC filings, Google algorithm update documentation, EU regulatory registers, and trade association membership records. Bottom-up service-provider revenue estimates triangulated against top-down enterprise marketing spend allocations.
Consistency checks validated volume and value outputs against external benchmarks across the modeling period. The analytical framework modeled segmentation dimensions including service type, delivery model, end-user category, and pricing structure. CAGRs derived from trend extrapolation of certified provider headcounts and enterprise contract values. Industry-specific inputs incorporated Google mobile-first indexing mandates and EU AI Act disclosure requirements.
Forecasts assume regulatory continuity in FTC enforcement patterns and EU AI Act implementation; material policy shifts would require re-modeling. Algorithm opacity and talent concentration risks could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital String Encoder Market
Digital Solutions
Hardware Engineering and Design Services Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Track and Trace Solutions Market
Digital Solutions
In-App Purchase Market
Digital Solutions
Hybrid Events Software Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Real Time Store Monitoring Platform Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Email Marketing Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
US Digital Twin Market
Digital Solutions
Product Engineering Services Market
Digital Solutions
IT Monitoring Tools Market