
 Global DDI Market | 2026-2036
Global DDI Market Size, Share, and Industry Trends Forecast 2026-2036
Global DDI Market Foresight
Modular bundling of DNS-DHCP-IPAM functions into unified platforms is broadening buyer choice across enterprise and service provider segments. Infoblox leverages its appliance heritage to dominate high-scale telecom deployments. EfficientIP anchors European demand with strong channel control across France and Germany. Cisco Systems extends its networking installed base into DDI adjacencies through embedded security integrations.
DDI denotes the integrated management triad of Domain Name System, Dynamic Host Configuration Protocol, and IP Address Management, typically delivered through software appliances or cloud-native controllers that automate network identity resolution, device provisioning, and IPv4/IPv6 address allocation across heterogeneous infrastructures. The primary commercial purpose centers on reducing operational overhead, eliminating address conflicts, and enforcing security policy at the network's foundational layer. Drug Discovery Solutions occupies the largest value pool among product types, reflecting biopharma R&D intensification and the complexity of modern target identification workflows. Cloud-Based deployment represents the fastest-expanding configuration, as regulated industries resolve compliance concerns and migrate core infrastructure off-premises.
FDA 21 CFR Part 11 and EMA GxP guidelines shape validation requirements for DDI platforms supporting clinical trial infrastructure, particularly around audit trails and electronic signature integrity. The EU AI Act and HIPAA security rules further constrain how patient-linked network data traverses automated discovery systems. Stakeholders must monitor evolving cross-border data localization mandates that could fragment cloud DDI architectures and force region-specific platform instances.
Market Dynamics
Cloud-native controller architectures are compressing deployment timelines for DDI infrastructure, forcing incumbent appliance vendors to rearchitect software stacks or surrender mid-market accounts to subscription-based competitors.
Growth Catalysts
- EMA GxP validation frameworks:European pharmaceutical regulators mandate audit-ready IP address tracking for clinical trial networks, creating procurement pull for compliant DDI platforms.
- IPv6 exhaustion protocols:Regional internet registries are activating final allocation phases, compelling enterprise network teams to automate dual-stack address management.
- Biopharma R&D intensification:Boston and Basel clusters are expanding discovery infrastructure, driving integrated DNS-DHCP-IPAM procurement for high-availability lab environments.
Market Restraints
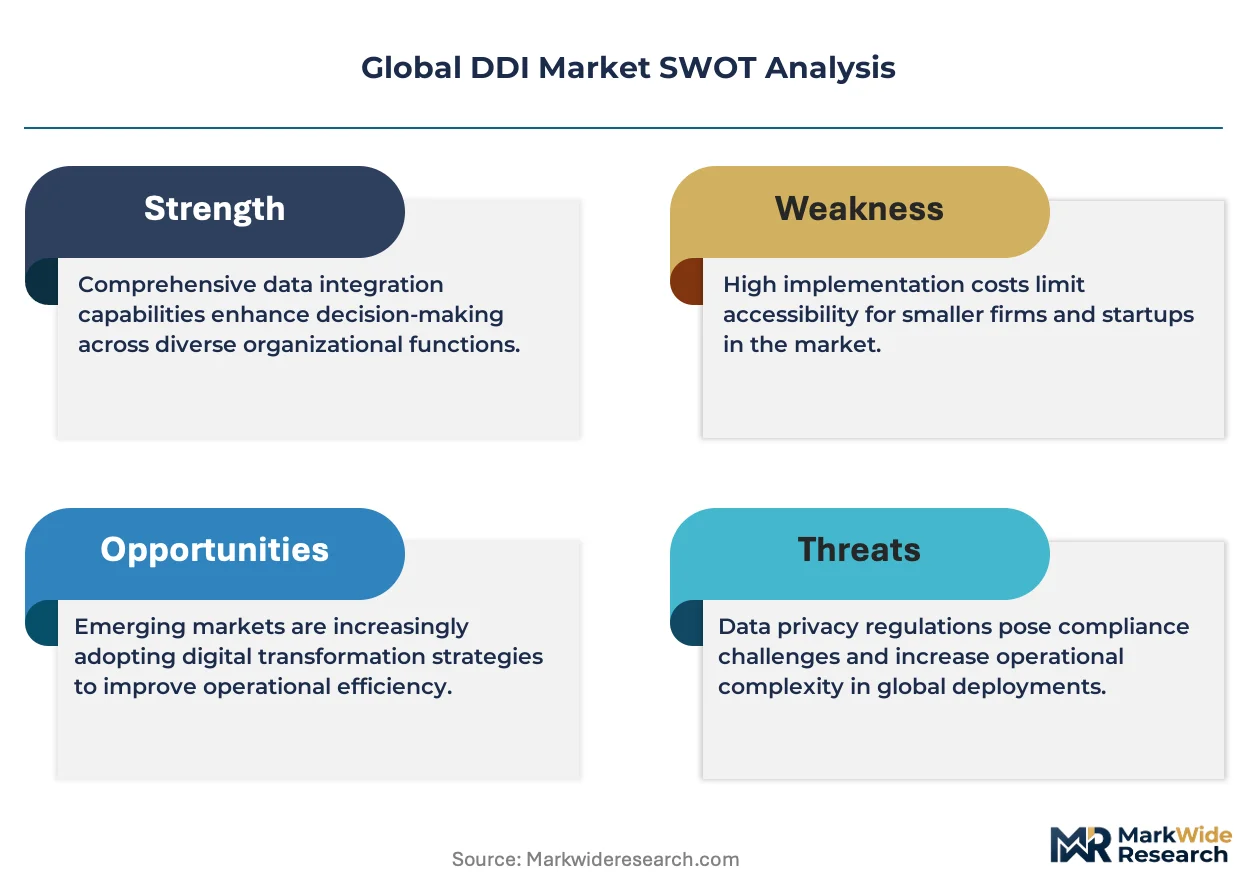
- Specialized engineering talent scarcity:Certified DDI architects command premium compensation, inflating implementation costs for complex multi-site deployments.
- Appliance hardware supply concentration:Custom network processor fabrication depends on Taiwan-based foundry capacity, exposing delivery timelines to geopolitical friction.
- Legacy BIND substitution resistance:Open-source DNS remains embedded in university and government networks, delaying commercial platform displacement.
Strategic Opportunities
- India BIS certification pathways:Domestic manufacturing incentives are attracting hyperscale data center construction, creating greenfield DDI deployment demand.
- Zero Trust architecture convergence:Network access control integration with identity-aware DNS is opening adjacent security spending categories for DDI vendors.
- EU AI Act data provenance rules:Automated IP-to-device mapping becomes audit-critical for AI training infrastructure, expanding regulated buyer pools.
Industry Challenges
- Multi-vendor orchestration complexity:Heterogeneous cloud-native and on-premises DNS stacks require custom API development, stretching implementation timelines.
- FDA 21 CFR Part 11 documentation burden:Electronic signature validation for DDI configuration changes demands specialized compliance engineering that vendors struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DDI Market |
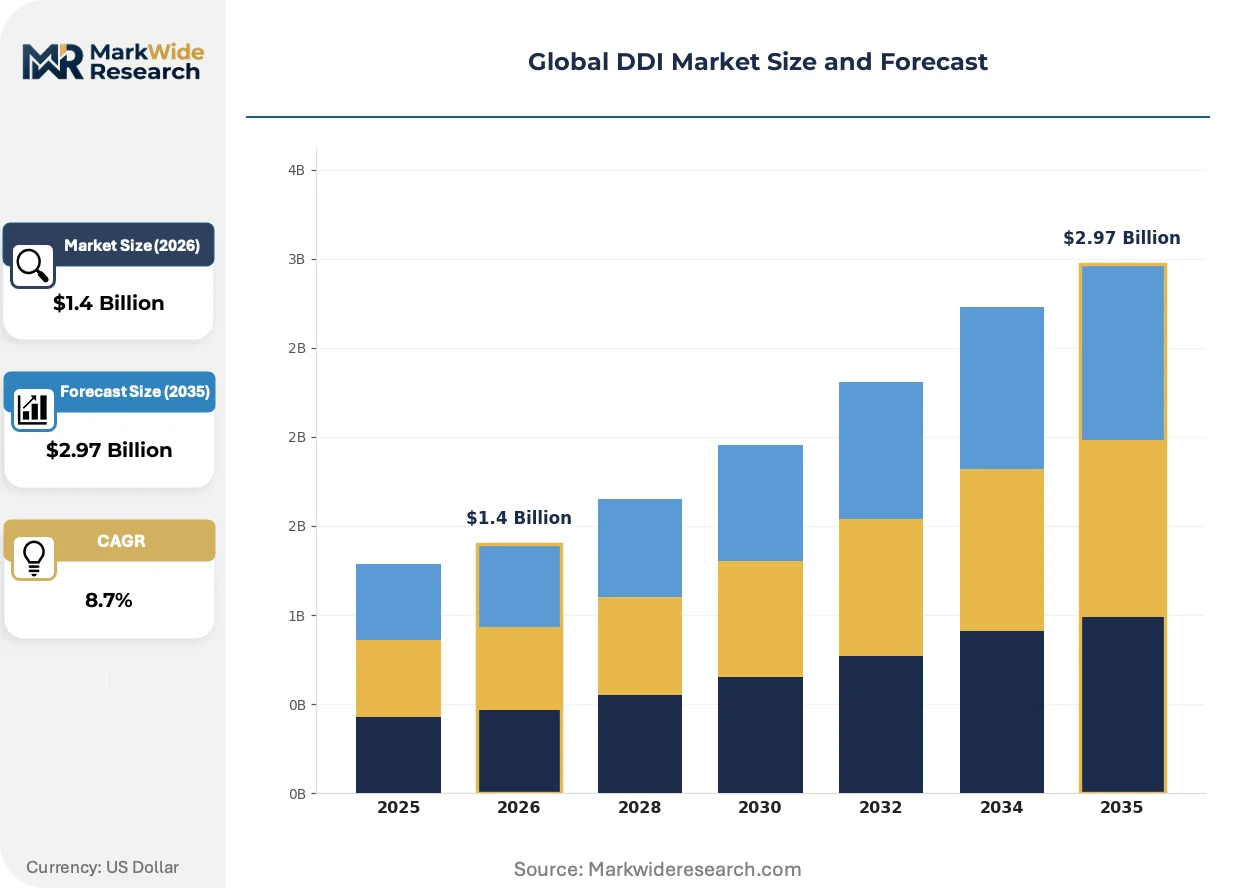
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug Discovery Solutions, Clinical Trial Management, Pharmacovigilance Systems, Regulatory Compliance Tools, Data Integration Platforms Application: Adverse Event Prediction, Drug Interaction Screening, Patient Safety Monitoring, Treatment Optimization, Clinical Decision Support End User: Pharmaceutical Companies, Contract Research Organizations, Hospitals, Academic Research Centers, Biotechnology Firms Deployment: On-Premises, Cloud-Based, Hybrid, Software as a Service, Platform as a Service |
| Companies Covered | Infoblox, BlueCat Networks, EfficientIP, Cisco Systems, MEN&MICE, SolarWinds, Nokia, ApplianSys, TCPWave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DDI Market Shifts & Advancements
Containerized network functions are dissolving the boundary between infrastructure and application layers, forcing DDI platforms to embed directly into Kubernetes control planes rather than operate as external services.
DNS-over-HTTPS (DoH) encryption is modularizing traffic inspection architectures. Financial services firms in London and Singapore are mandating DoH for branch office resilience, compressing demand for traditional recursive resolver appliances. This shift is forcing vendors to reprice software-only offerings against hardware-centric legacy contracts.
REACH chemical substance tracking extensions are expanding to cover data center coolant disclosures. German and Dutch facility operators must now document IP-connected environmental sensors in audit trails, tightening DDI integration requirements for building management systems. Pharmaceutical manufacturers with EU manufacturing footprints are prioritizing platforms with pre-validated REACH compliance modules.
Subscription consumption models are displacing perpetual license procurement in mid-enterprise accounts. Channel partners in France and Australia are unbundling implementation services from software fees, compressing vendor margins while accelerating customer acquisition. Healthcare systems with constrained capital budgets are driving this shift most aggressively.
Global DDI Market Segmentation
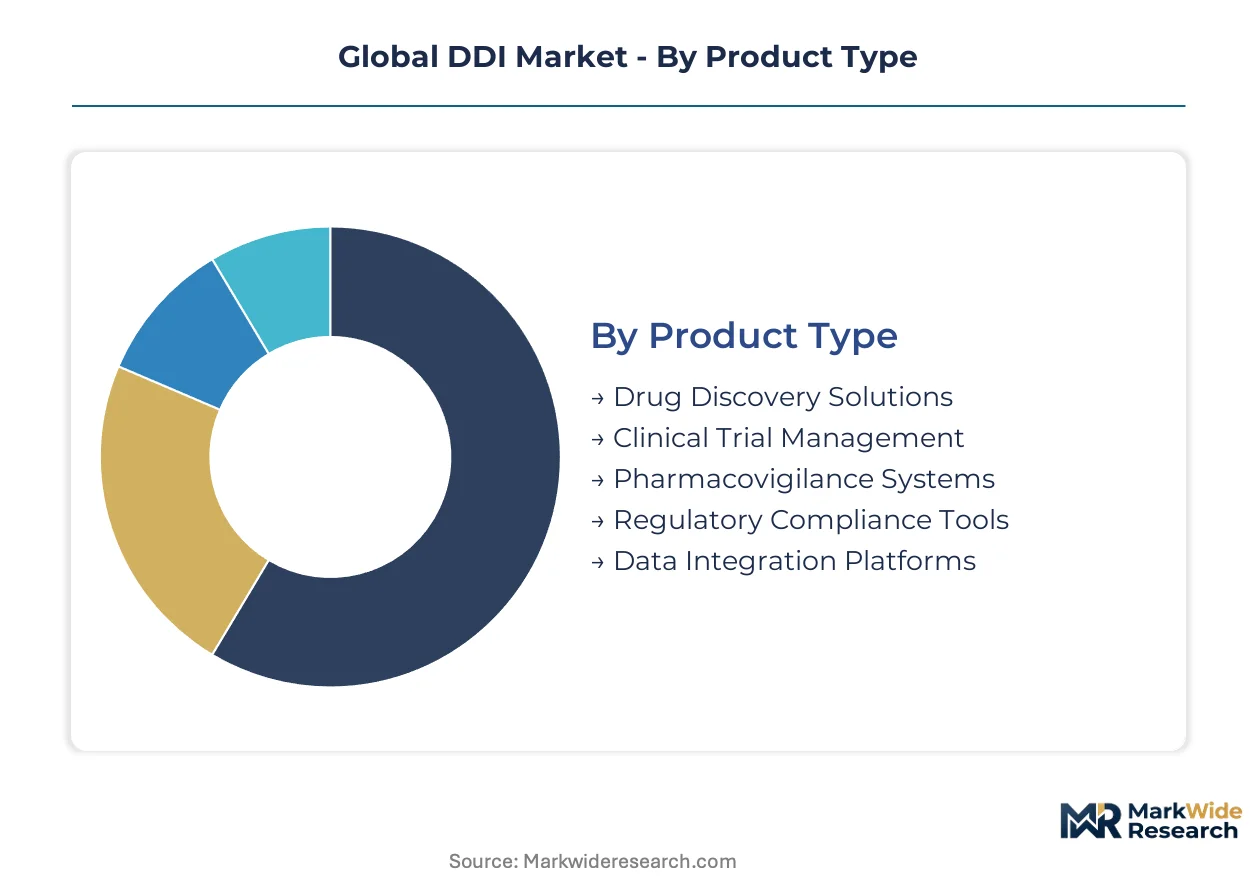
Segmentation in the DDI market reflects divergent buyer priorities across pharmaceutical R&D workflows, regulatory compliance mandates, and infrastructure modernization timelines. Procurement patterns split sharply between discovery-stage platforms requiring high computational throughput and clinical-stage systems demanding audit-grade data lineage.
Product Type:
Buyers prioritize platforms that compress time-to-insight for specific therapeutic programs, with procurement committees weighting integration depth against validation overhead.
- Drug Discovery Solutions:These platforms orchestrate target identification, lead optimization, and compound library management through AI-augmented molecular modeling. Boston and Basel biopharma clusters are expanding procurement for high-throughput screening infrastructure as antibody-drug conjugate pipelines multiply.
- Clinical Trial Management:Systems coordinating site selection, patient recruitment, and regulatory submission workflows. Demand concentrates among mid-cap sponsors in the United States seeking to replace fragmented point solutions with unified data repositories that satisfy FDA 21 CFR Part 11 requirements.
- Pharmacovigilance Systems:Automated adverse event signal detection and case processing for post-market surveillance obligations.
- Regulatory Compliance Tools:Pre-validated modules addressing EMA GxP and FDA documentation standards for electronic records.
- Data Integration Platforms:Middleware connecting laboratory information management systems with enterprise data lakes.
Drug Discovery Solutions leads on scale; Clinical Trial Management leads on momentum.
Application:
Functional use cases map directly to risk-adjusted reimbursement incentives and liability exposure in specific therapeutic areas.
- Adverse Event Prediction:Machine learning models trained on historical safety databases to forecast drug toxicity profiles before human exposure. Large pharma sponsors in Germany are prioritizing these capabilities for rare disease programs where patient pools offer limited real-world learning.
- Drug Interaction Screening:In silico and clinical pharmacology tools predicting metabolic pathway conflicts and contraindication risks. Contract research organizations across India are building specialized service offerings around polypharmacy analysis for geriatric indications.
- Patient Safety Monitoring:Real-time surveillance dashboards for hospitalized populations receiving investigational therapies.
- Treatment Optimization:Dosing algorithms integrating biomarker data with patient demographic factors.
- Clinical Decision Support:Point-of-care recommendations embedded in electronic health record workflows.
Drug Interaction Screening anchors current procurement volumes; Adverse Event Prediction is climbing the fastest as oncology pipeline complexity intensifies.
End User:
Organizational scale and regulatory sophistication determine platform configuration preferences, with capital availability shaping deployment model choices.
- Pharmaceutical Companies:Integrated platform deployments spanning discovery through commercialization, with procurement committees in San Francisco and Cambridge demanding API-first architectures that accommodate biologic modality diversification. These buyers are consolidating vendor relationships to reduce validation redundancy across therapeutic franchises.
- Contract Research Organizations:Multi-tenant platform configurations serving sponsor-specific data isolation requirements. Indian and Eastern European CROs are expanding capacity to capture outsourced pharmacovigilance and clinical data management mandates from Western sponsors.
- Hospitals:Point solutions for formulary management and antimicrobial stewardship programs.
- Academic Research Centers:Grant-funded pilot deployments with limited enterprise integration requirements.
- Biotechnology Firms:Modular procurement prioritizing speed-to-clinic over comprehensive functionality.
Pharmaceutical Companies dominate absolute spending; Contract Research Organizations are gaining share fastest as sponsor outsourcing accelerates.
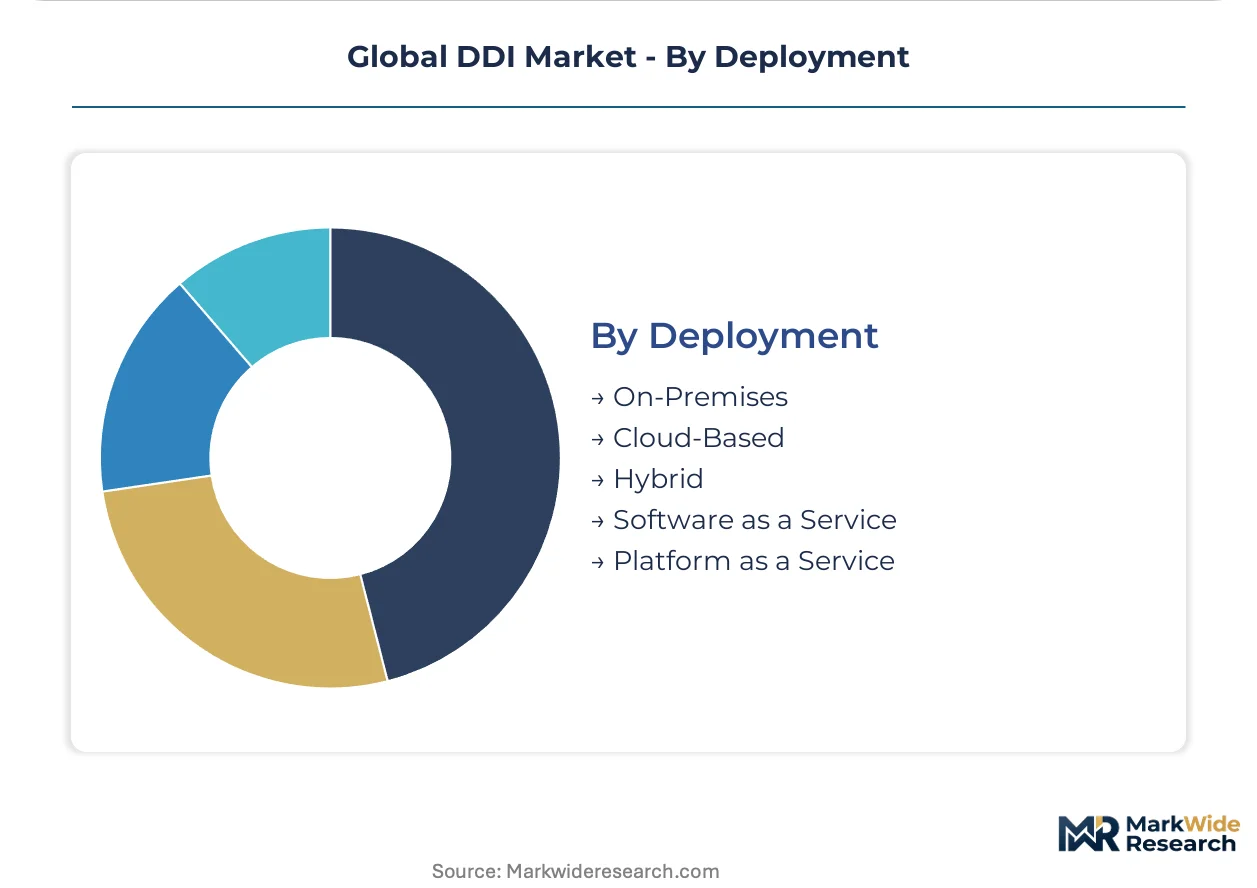
Deployment:
Infrastructure strategy reflects data sovereignty concerns, validation burden tolerance, and hybrid workforce requirements across distributed research teams.
- Cloud-Based:Fully managed SaaS configurations with automated compliance patching and elastic compute scaling. European buyers are migrating core infrastructure off-premises as EMA guidance clarifies audit trail expectations for hosted environments, though cross-border data localization mandates are forcing region-specific instance proliferation.
- Hybrid:Split architectures retaining sensitive discovery data on-premises while pushing scalable analytics to cloud substrates. United States mid-enterprise accounts are adopting this model to balance capital efficiency with intellectual property protection.
- On-Premises:Self-managed installations for classified government research or extreme latency-sensitive workloads.
- Software as a Service:Subscription consumption with standardized configuration templates.
- Platform as a Service:Developer-facing environments for custom workflow construction.
Hybrid deployments anchor near-term procurement volumes; Cloud-Based configurations are expanding most quickly as FDA and EMA validation frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DDI platforms emerged from enterprise networking roots in the United States during the 1990s, with early appliance deployments scaling through telecom infrastructure buildouts. The technology subsequently diffused through European regulated industries and Asia-Pacific data center construction waves.
United States
FDA 21 CFR Part 11 validation requirements and HIPAA security rules drive procurement for clinical trial infrastructure. Boston and San Francisco biopharma clusters are expanding integrated DNS-DHCP-IPAM deployments for high-availability lab environments. Cloud migration accelerates as sponsors consolidate fragmented point solutions.
Germany
EMA GxP frameworks and REACH chemical tracking extensions mandate audit-ready IP address documentation for manufacturing facilities. The Rhine-Ruhr industrial corridor is retrofitting building management systems with DDI-integrated environmental sensors. Automotive suppliers in Baden-Württemberg are adopting zero-trust network architectures.
United Kingdom
Financial services regulators in London are mandating DNS-over-HTTPS encryption for branch office resilience. The Cambridge life sciences cluster is procuring hybrid deployment models to balance intellectual property protection with capital efficiency. NHS trusts are piloting subscription-based consumption for formulary management.
India
BIS certification pathways and domestic manufacturing incentives are attracting hyperscale data center construction in Maharashtra and Karnataka. Contract research organizations in Hyderabad are building multi-tenant platform configurations for Western sponsor outsourcing. CDSCO guidance is clarifying validation expectations for hosted clinical environments.
Japan
METI industrial digitization programs and PMDA pharmaceutical regulations are converging on network identity management standards. The Kanto region's pharmaceutical manufacturers are prioritizing platforms with pre-validated compliance modules. Osaka-based CROs are expanding capacity for pharmacovigilance data management.
Global DDI Market Competitive Landscape
The competitive structure tilts toward incumbent appliance vendors defending high-scale telecom accounts against cloud-native challengers. Market concentration remains moderate with tiered specialization across enterprise, service provider, and regulated industry verticals. Three archetypes dominate: hardware-anchored incumbents with security integrations, pure-play DDI specialists with channel depth, and networking conglomerates leveraging installed base adjacencies. Consolidation pressure is intensifying through strategic partnerships and subscription model conversions.
Within the appliance heritage tier, Infoblox and EfficientIP exemplify divergent geographic anchoring strategies. Infoblox occupies a position aligned with North American telecom scale requirements, while EfficientIP anchors European demand through channel control across France and Germany. Cisco Systems sits within the networking extension archetype, translating enterprise switching and routing relationships into adjacent DDI procurement.
| Leading Market Players |
|---|
| Infoblox |
| BlueCat Networks |
| EfficientIP |
| Cisco Systems |
| MEN&MICE |
| SolarWinds |
| Nokia |
| ApplianSys |
| TCPWave |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up DDI specialists have consolidated fragmented regional players across France and Germany, concentrating pricing power with vendors who control channel relationships while compressing margins for systems integrators serving mid-market healthcare accounts.
Pricing Analysis
Subscription consumption models with tiered feature entitlements anchor vendor revenue streams, separating enterprise-grade GxP validation modules from standard DNS-DHCP automation. Price differentiation hinges on FDA 21 CFR Part 11 certification tier and multi-site deployment scale. Cost compression in mid-market SaaS tiers is intensifying because cloud-native challengers undercut appliance-based perpetual licenses. Hospital procurement committees exhibit highest price sensitivity; pharmaceutical sponsors in Boston and Basel demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based foundry capacity for custom network processors powering high-scale telecom appliances. Hardware fabrication concentrates in Taiwan, China, and South Korea, while software development clusters in the United States, Ireland, and India. Component dependencies include specialized ASICs, memory modules, and cryptographic acceleration chips. Tariff exposure on semiconductor imports threatens delivery timelines for on-premises appliance orders. Distribution runs through authorized channel partners in France, Germany, and Australia who unbundle implementation services from software fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global DDI Market reads as a late-cycle quality story where procurement committees now prioritize audit-grade validation over raw throughput, elevating vendors with pre-certified FDA and EMA compliance modules above commodity DNS providers.
For Market Incumbents: Acquire cloud-native controller technology stacks to offset appliance revenue erosion. Incumbents must rearchitect software delivery for Kubernetes-embedded deployments while defending high-scale telecom accounts against subscription-based challengers. Certification investment in REACH-compliant environmental sensor integration secures pharmaceutical manufacturing footprint in Germany and the Netherlands. For New Entrants and Emerging Players: Containerized network functions automation offers a technology-first wedge into mid-enterprise healthcare accounts constrained by capital budgets. White-space targets include Indian CRO multi-tenant configurations and NHS trust subscription pilots. The most penetrable segment spans hybrid deployment models for United States mid-cap biotech firms seeking intellectual property protection with capital efficiency. For Investors and Strategic Acquirers: Valuations sit cheapest among appliance-heritage vendors with stagnant R&D conversion and eroding mid-market share. Long-term viability over the next decade favors platforms with API-first architectures accommodating biologic modality diversification. The signal to watch is EMA guidance evolution on cross-border data localization mandates that could force region-specific cloud instance proliferation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Controller Development | Kubernetes-embedded DNS-DHCP-IPAM compresses deployment timelines for biopharma lab environments. |
| GxP Validation Module Pre-Certification | FDA 21 CFR Part 11-ready platforms command procurement preference among clinical trial sponsors. |
| Zero Trust Architecture Integration | Identity-aware DNS opens adjacent security spending categories with financial services regulators in London. |
| Multi-Tenant Platform Configuration | Indian CROs capture outsourced pharmacovigilance mandates from Western pharmaceutical sponsors. |
| REACH Compliance Module Development | German facility operators require IP-connected environmental sensor documentation for coolant tracking. |
Research Methodology
Direct dialogue with DDI platform engineers, pharmaceutical IT procurement leads, regulatory compliance officers, and channel distribution partners grounded qualitative insights. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA GxP framework updates, hyperscaler capex disclosures, and clinical trial infrastructure spending databases. Bottom-up deployment sizing across biopharma clusters and top-down vendor revenue triangulation anchored market estimates.
Segment-level projections across product type, deployment model, end-user scale, and regional regulatory cluster fed into analytical framework outputs over the projection horizon. CAGRs were derived from elasticity modeling against biopharma R&D intensity indices and cloud migration penetration curves. IPv6 exhaustion protocols and EMA audit trail requirement evolution served as primary forecast inputs.
The model holds under stable cross-border data flow regimes; deviation in EU AI Act enforcement stringency or Taiwan semiconductor export restrictions would shift cloud-native adoption trajectories. Forecasts reflect assumptions around validation framework harmonization between FDA and EMA. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global IT Asset Disposition (ITAD) Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Digital Commerce Platform Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Function As a Service (Faas) Market
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
IT Asset Management Market
Digital Solutions
OSS/BSS Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
Social Networking App Market
Digital Solutions
Email Deliverability Tools Market
Digital Solutions
Defense IT Spending Market
Digital Solutions
Global Autonomous Data Platform Market
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Incidence Management Software Market