
 E-Governance Market | 2026-2036
E-Governance Market Size, Share, and Industry Trends Forecast 2026-2036
E-Governance Market Analysis
Modular unbundling of legacy government IT contracts is rebalancing vendor selection criteria across procurement offices. IBM Corporation leverages its federal systems integration heritage to anchor large-scale infrastructure renewals. Microsoft Corporation competes through cloud-native productivity stacks tailored for inter-agency collaboration. Tata Consultancy Services dominates municipal digitization programs across South Asia with localized deployment expertise.
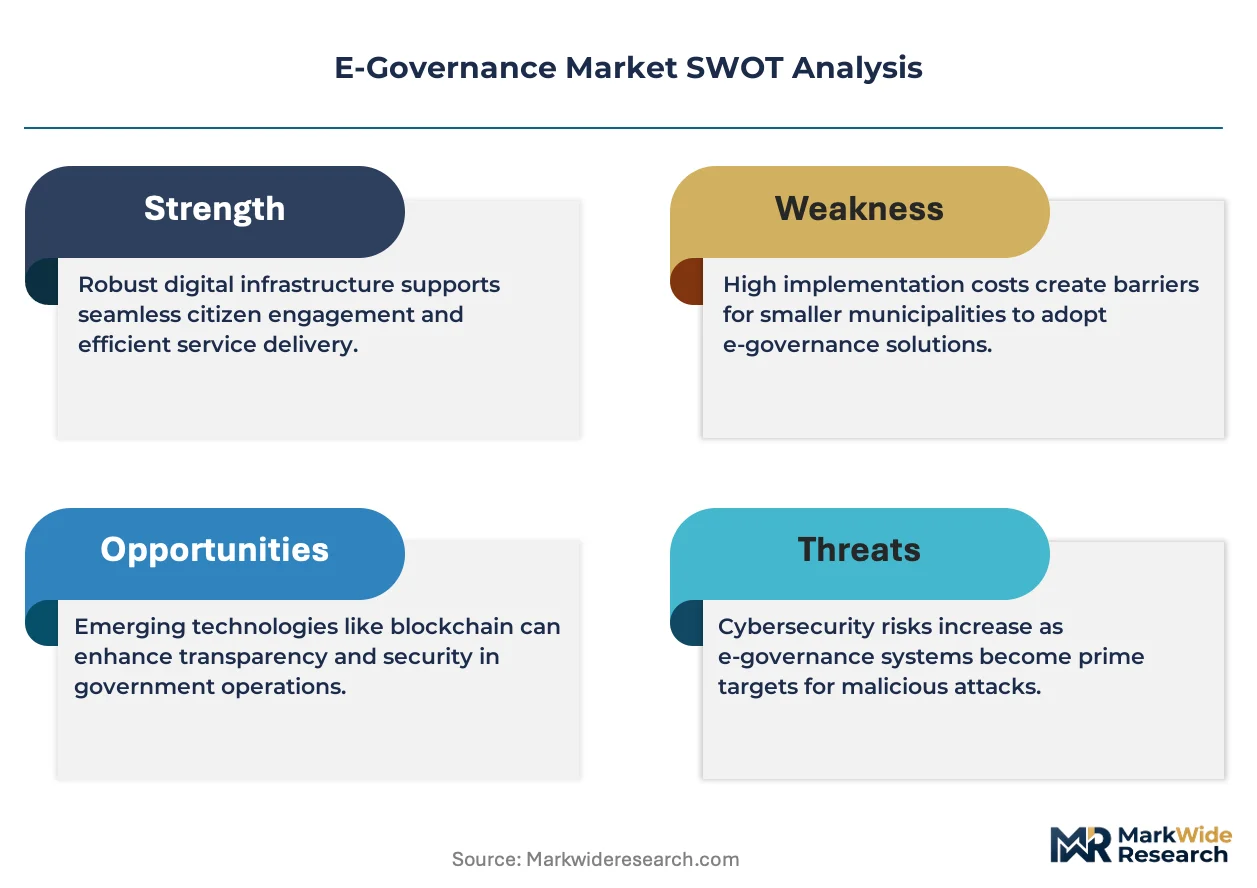
E-governance denotes the application of information and communication technologies to public administration operations, encompassing digital identity verification, secure data exchange protocols, and API-based intergovernmental connectivity. Its primary purpose centers on reducing bureaucratic friction while improving transparency in citizen-state interactions. Cloud-based deployment now leads investment flows as agencies prioritize elastic capacity for tax-filing and benefit-distribution surges. Artificial intelligence integration within e-administration represents the fastest-expanding technology segment, though on-premises installations retain stronghold status in defense and classified environments where data sovereignty mandates prevail.
The EU AI Act and GDPR impose algorithmic accountability requirements on automated decision systems deployed by European agencies, directly shaping vendor qualification criteria. India's BIS standards and Digital India compliance frameworks mandate interoperable data formats across state and federal portals, creating uniform technical baselines. China's GB standards and SAMR cybersecurity rules govern government cloud procurement, restricting foreign platform participation. Stakeholders must monitor evolving data-localization mandates and cross-border certification reciprocity agreements as determinants of market access eligibility.
Market Dynamics
Cloud-native service delivery is compressing procurement cycles for municipal IT infrastructure as agencies abandon monolithic legacy contracts in favor of modular, API-first architectures that enable elastic scaling during tax-filing and benefit-distribution surges.
Growth Catalysts
- Digital India compliance frameworks:India's BIS-mandated interoperable data standards across state and federal portals create uniform technical baselines that accelerate vendor onboarding and system integration timelines.
- Biometric integration:Municipal governments deploy fingerprint and iris verification for welfare distribution, cutting identity fraud while streamlining citizen access to subsidized services.
- EU AI Act algorithmic accountability:European procurement offices now require explainable AI documentation for automated decision systems, creating certified vendor tiers that reward early compliance investments.
Market Restraints
- Data sovereignty mandates:Defense and classified environments in China, Russia, and Gulf states require on-premises installations, blocking foreign cloud providers from security-sensitive segments.
- Cross-border certification gaps:Absent reciprocity agreements between India's STQC and Europe's ETSI, vendors face redundant testing costs that extend deployment timelines by 8-14 months.
- Legacy system debt:COBOL-based tax and pension systems in Japan, Germany, and US federal agencies resist API wrapping, forcing expensive parallel infrastructure builds during transition periods.
Strategic Opportunities
- Sub-Saharan municipal digitization:Rwanda's Irembo platform and Kenya's Huduma Centre network demonstrate replicable models for national portal consolidation across underpenetrated East African markets.
- Converged AI-blockchain audit trails:Immutable transaction logging for procurement and land registry systems addresses corruption risks while satisfying IFI transparency requirements for development financing.
- Mobile-first service design:India's UMANG super-app architecture—aggregating 1,600+ services—provides a template for bypassing desktop infrastructure gaps in low-PC-penetration economies.
Industry Challenges
- API governance expertise scarcity:Government IT departments lack personnel skilled in OAuth 2.0 security protocols and microservices orchestration, forcing reliance on costly systems integrators for architecture decisions.
- Interoperability testing bottlenecks:India's national e-governance division reports 40% of state portal integration projects stall during cross-platform data validation phases due to inconsistent XML schema implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Governance Market |
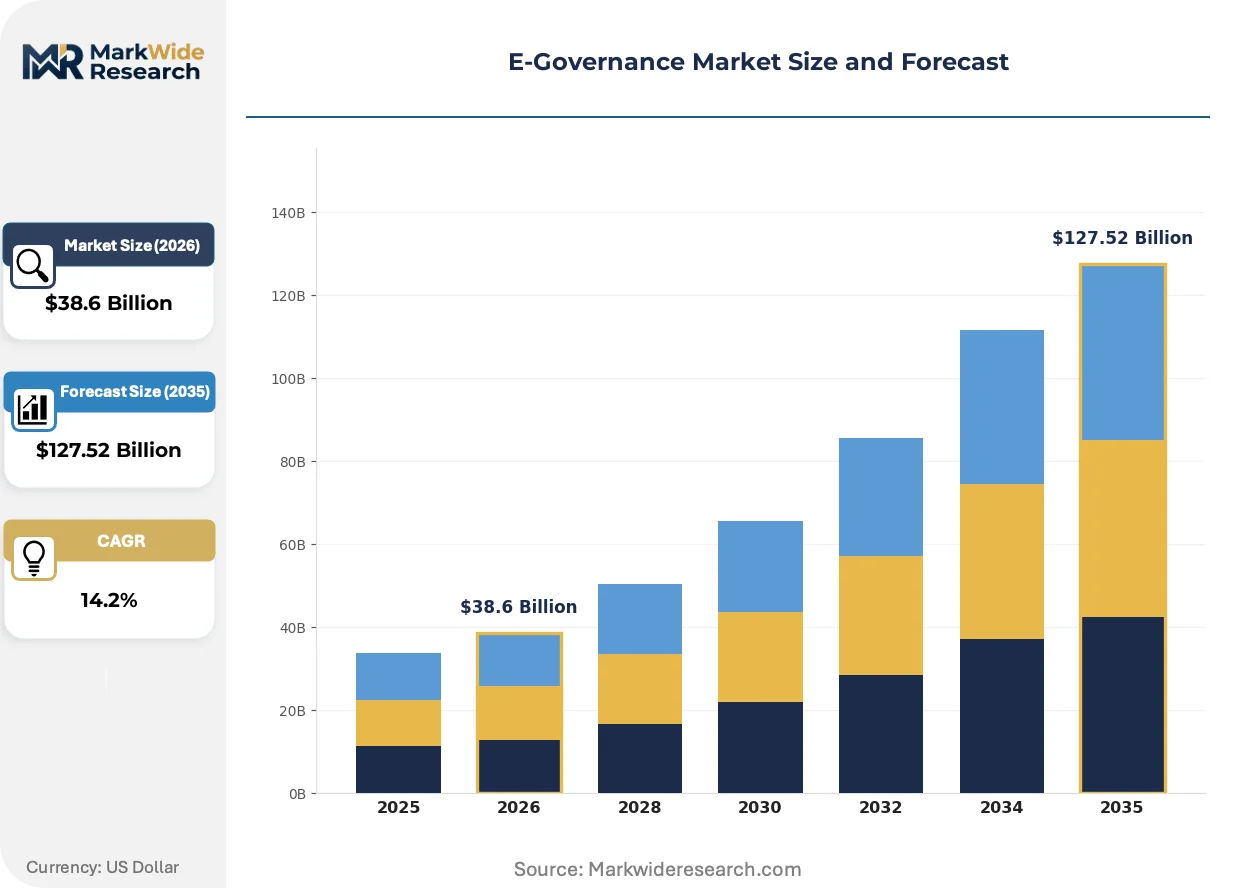
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: E-Administration, E-Procurement, E-Democracy, E-Health Deployment Model: Cloud-Based, On-Premises, Hybrid, Community Cloud End User: Government Agencies, Municipalities, Public Sector Units, Defense Technology: Blockchain, Artificial Intelligence, Internet of Things, Big Data |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Accenture plc, Capgemini SE, Atos SE, Tata Consultancy Services, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Governance Market Emerging Trajectories
Artificial intelligence integration is redefining citizen-state interaction models while distributed ledger technologies and zero-trust security architectures reshape backend infrastructure procurement criteria across OECD and emerging economies alike.
Blockchain-based land registries and procurement audit systems are decentralizing trust mechanisms in government record-keeping. Estonia's KSI blockchain anchors its e-Residency and healthcare data exchanges, while Colombia's pilot with Ripple for property titles demonstrates adoption momentum in Latin American anti-corruption initiatives. This architecture eliminates single-point-of-failure risks in centralized databases while creating immutable evidentiary chains for judicial disputes.
The EU AI Act's risk-based classification system for automated decision-making is forcing algorithmic impact assessments into standard RFP requirements. European agencies now demand documented training data provenance and human-in-the-loop override protocols for high-risk applications including visa processing and welfare eligibility. Vendors without pre-certified compliance modules face automatic disqualification from Framework Contracts.
Subscription-based SaaS procurement is displacing perpetual license models in municipal IT budgets. Danish and Dutch municipalities now aggregate demand through joint procurement vehicles, negotiating tiered pricing for identity-as-a-service and document management platforms. This concentration shifts vendor economics toward recurring revenue retention and reduces upfront capital barriers for smaller cities.
E-Governance Market Segmentation
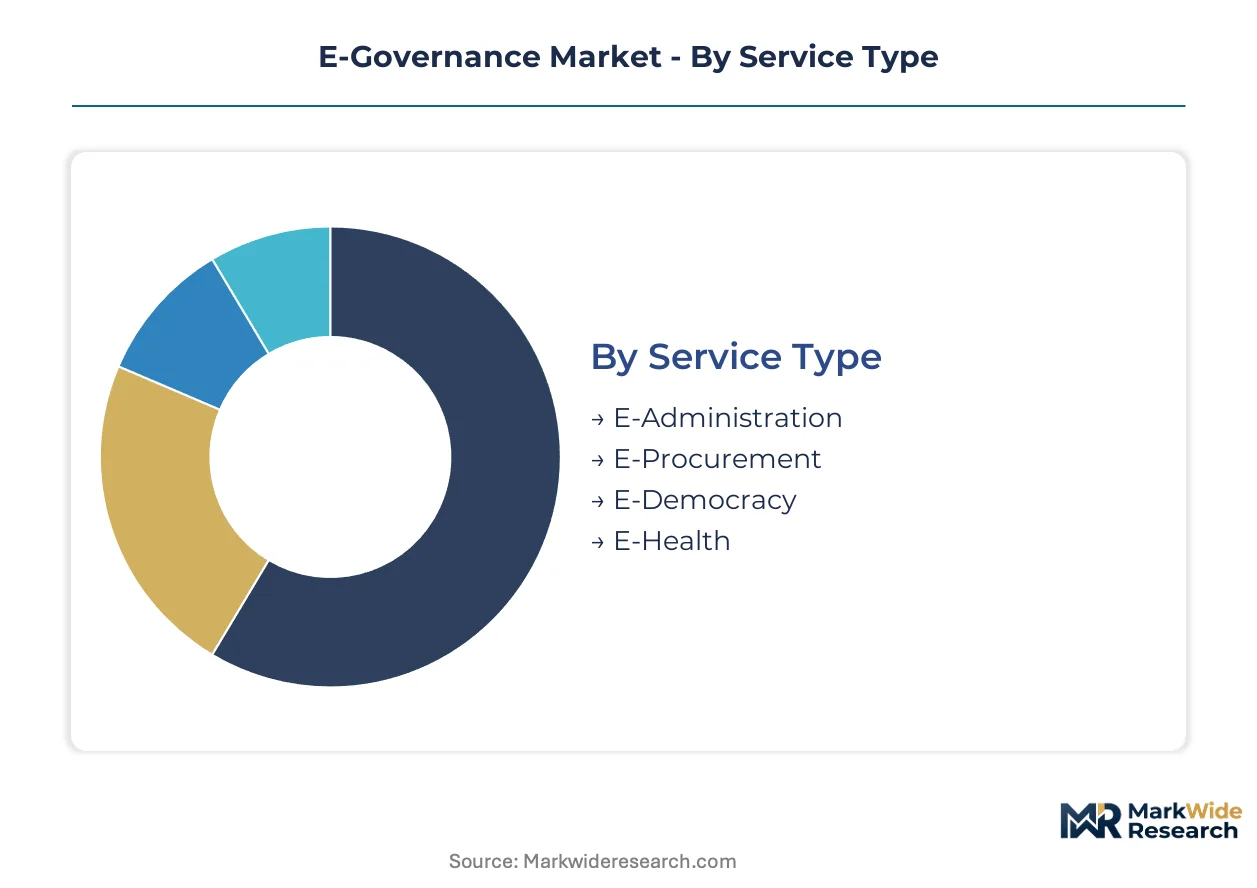
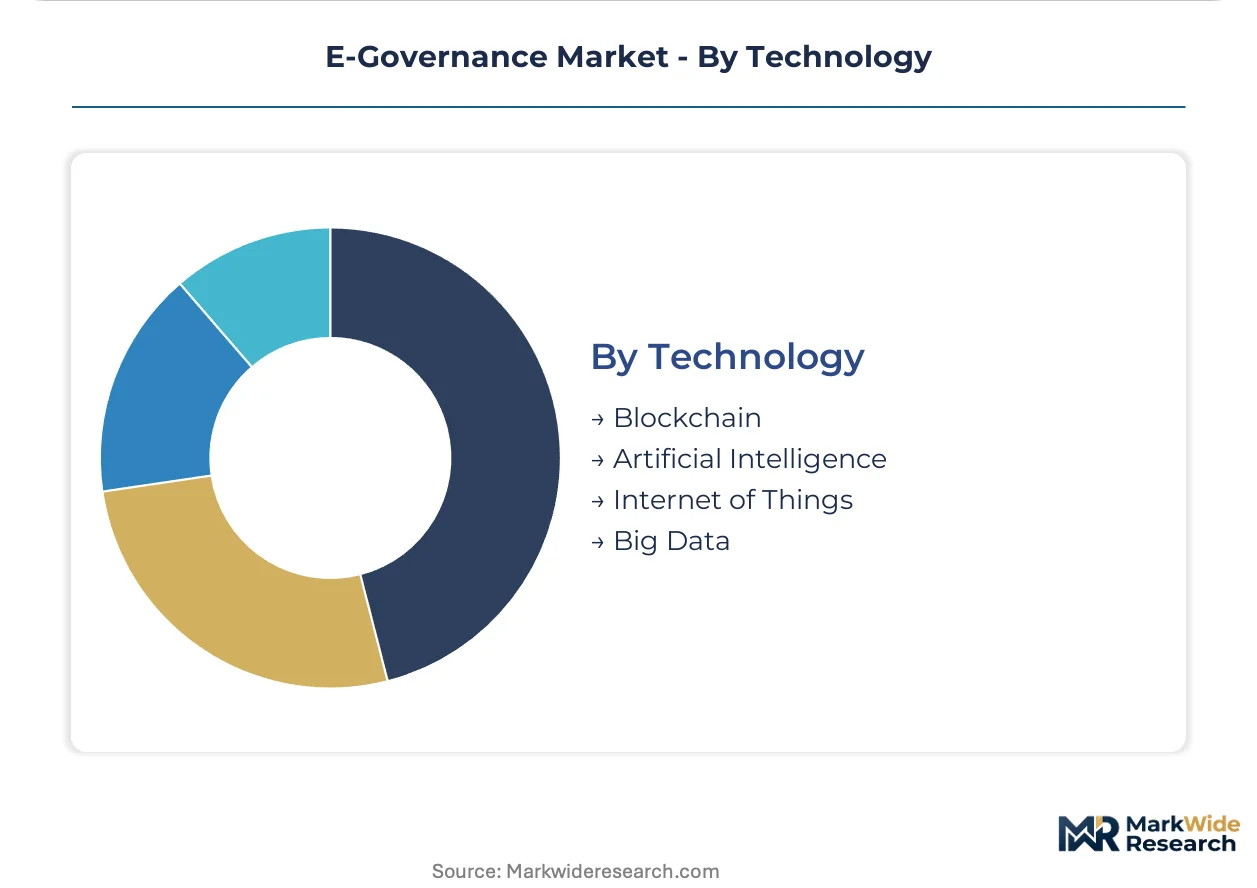
E-governance procurement diverges sharply across deployment models and service types, with cloud-native architectures displacing legacy infrastructure in civilian agencies while classified environments retain on-premises mandates. Technology integration patterns vary by administrative tier—municipalities prioritize mobile-first service delivery, defense agencies demand air-gapped systems, and federal ministries pursue cross-agency data interoperability.
Service Type:
Agency procurement budgets allocate differentially based on citizen transaction volume and regulatory compliance burden, with high-frequency services commanding premium automation investments.
- E-Administration:Core digital infrastructure for tax filing, permit processing, and civil registry management. India's Digital India initiative drives nationwide portal consolidation here, with biometric integration now mandatory for welfare distribution systems.
- E-Procurement:Automated tendering, vendor qualification, and contract lifecycle management. Brazil's ComprasNet and South Korea's KONEPS demonstrate how centralized platforms cut procurement cycle times by half while embedding anti-corruption audit trails.
- E-Democracy:Digital voting, public consultation portals, and petition systems. Estonia's i-Voting infrastructure and Taiwan's vTaiwan deliberation platform anchor demand in advanced digital societies.
- E-Health:Electronic medical records, telemedicine scheduling, and prescription tracking. Denmark's Sundhed.dk and Rwanda's TRACnet illustrate divergent maturity paths between OECD and emerging economies.
Volume sits with E-Administration; growth tilts toward E-Procurement as IFI transparency mandates spread across developing economies.
Deployment Model:
Data sovereignty requirements and workload elasticity needs split procurement decisions between scalable cloud architectures and controlled on-premises environments.
- Cloud-Based:Elastic compute and storage accessed via public internet with multi-tenant resource pooling. Danish municipalities aggregate demand through joint procurement vehicles, negotiating tiered pricing for identity-as-a-service platforms that scale during tax-filing surges.
- On-Premises:Dedicated hardware installations within government-owned facilities. China's SAMR cybersecurity rules and Russia's data-localization laws block foreign cloud providers from defense and classified segments, preserving incumbent systems integrators.
- Hybrid:Split workloads across private infrastructure and public cloud with orchestrated data flow. Germany's Gaia-X federated infrastructure exemplifies European attempts to retain data control while accessing cloud elasticity.
- Community Cloud:Shared infrastructure exclusive to government entities with common compliance frameworks. India's MeghRaj program provisions standardized cloud services across state and federal agencies under unified BIS standards.
Deployment gravity centers on Cloud-Based for civilian services; Hybrid architectures are expanding most quickly as agencies balance elasticity against sovereignty constraints.
End User:
Organizational tier determines security classification, integration complexity, and vendor qualification thresholds.
- Government Agencies:Federal ministries and departmental bodies managing nationwide policy implementation. India's national e-governance division mandates interoperable XML schemas across state portals, creating uniform integration baselines.
- Municipalities:City and county administrations delivering localized services. Kenya's Huduma Centre network consolidates previously fragmented municipal services into single-window access points.
- Public Sector Units:State-owned enterprises and statutory authorities with commercial operations. These entities blend government compliance requirements with competitive procurement pressures.
- Defense:Military and intelligence organizations with classified information mandates. Air-gapped networks and electromagnetic shielding requirements exclude standard commercial cloud offerings entirely.
Municipalities generate highest transaction volumes; Defense segments sustain premium pricing through specialized security specifications.
Technology:
Integration depth varies by administrative function—some technologies anchor backend infrastructure while others transform citizen-facing interfaces.
- Blockchain:Distributed ledger architectures for immutable record-keeping. Colombia's pilot with Ripple for property titles and Estonia's KSI blockchain for healthcare data demonstrate anti-corruption applications in land registry and identity verification.
- Artificial Intelligence:Machine learning for document processing, eligibility determination, and predictive service routing. The EU AI Act's risk-based classification now mandates explainable AI documentation and human-in-the-loop override protocols for visa processing and welfare eligibility systems.
- Internet of Things:Sensor networks for smart city infrastructure, environmental monitoring, and asset tracking. Singapore's sensor deployment for traffic optimization and waste management illustrates integrated urban governance applications.
- Big Data:Aggregate analytics across administrative datasets for policy modeling and fraud detection. India's Aadhaar-linked benefit distribution generates massive transaction streams requiring real-time anomaly detection.
Artificial Intelligence commands current investment priority; Blockchain audit trails are gaining share fastest as IFI financing attaches transparency conditions to development loans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption of e-governance platforms concentrates in administrative reform corridors, while production capabilities cluster around systems integration hubs with federal contracting heritage. India's Digital India initiative generates the largest procurement volumes, though European regulatory standard-setting shapes vendor qualification frameworks worldwide.
United States
Federal cloud-first mandates and municipal IT modernization programs drive procurement across civilian agencies. The Federal Risk and Authorization Management Program (FedRAMP) establishes baseline security certifications for cloud service providers. Washington DC's federal contracting corridor hosts systems integrators anchoring large-scale infrastructure renewals for tax and benefits administration.
India
Portal consolidation and biometric welfare distribution systems command the majority of public IT spending. BIS-mandated interoperable data standards across state and federal portals create uniform technical baselines for vendor onboarding. Karnataka's Bangalore cluster concentrates deployment expertise for municipal digitization programs across South Asia.
Germany
Gaia-X federated infrastructure initiatives balance data sovereignty requirements against cloud elasticity demands. The Online Access Act (Onlinezugangsgesetz) mandates digital service availability for all federal administrative procedures by law. Berlin-Brandenburg's government IT cluster hosts specialists in hybrid architecture integration for federal ministries.
China
Smart city deployments and government cloud procurement dominate investment flows under digital infrastructure plans. SAMR cybersecurity rules and GB standards restrict foreign platform participation in sensitive segments. Beijing's Zhongguancun software corridor anchors domestic systems integration for provincial administrative platforms.
Estonia
E-Residency infrastructure and blockchain-anchored healthcare data exchanges demonstrate mature digital state architecture. GDPR compliance frameworks shape data exchange protocols with EU peer agencies. Tallinn's digital governance cluster exports technical advisory services to emerging economies replicating its X-Road interoperability model.
E-Governance Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated structure where scale advantages in federal systems integration coexist with localized deployment expertise. The vendor landscape consolidates around three strategic archetypes: heritage federal contractors with classified infrastructure credentials, cloud-native platform providers with productivity stack ecosystems, and regional systems integrators with municipal implementation depth. Competitive positioning hinges on M&A activity targeting specialized compliance capabilities and strategic partnerships bridging technology platforms with local regulatory expertise.
Within the heritage federal contractor tier, IBM Corporation and Oracle Corporation exemplify established positioning through decades of classified infrastructure integration. Microsoft Corporation anchors the cloud-native platform vector with productivity and collaboration stacks tailored for inter-agency environments. Tata Consultancy Services occupies a distinct position among regional specialists, with deployment expertise concentrated in South Asian municipal digitization programs. These three archetypes represent the competitive spectrum rather than exhaustive market coverage, with each emphasizing different procurement qualification pathways.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Accenture plc |
| Capgemini SE |
| Atos SE |
| Tata Consultancy Services |
| NEC Corporation |
| Others |
Supply Flow & Price Mechanics
Vertical integration into cloud infrastructure provisioning anchors supply positioning and pricing power for heritage federal contractors serving classified environments, while modular API-first architectures enable SaaS-native vendors to compress procurement cycles and capture recurring revenue streams in municipal segments.
Pricing Analysis
Margin tightening in cloud-native service tiers reflects subscription-based SaaS displacement of perpetual license models across Danish and Dutch municipal joint procurement vehicles. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and integration complexity, with EU AI Act compliance documentation commanding substantial premiums. Cost compression accelerates in on-premises infrastructure as China's SAMR cybersecurity rules and Russia's data-localization laws restrict foreign participation, preserving incumbent pricing power. Municipalities exhibit highest price sensitivity due to capital budget constraints; defense agencies demonstrate lowest sensitivity given air-gapped security mandates.
Supply Chain Analysis
Freight costs for specialized hardware shipments to air-gapped defense installations amplify total cost of ownership for on-premises deployments across Germany, Japan, and Gulf states. Supply concentration centers on India for systems integration talent, Estonia for blockchain governance exports, and the United States for FedRAMP-certified cloud infrastructure. Component dependencies include cryptographic hardware security modules, biometric sensor arrays, and sovereign cloud compute instances. Single-source vulnerability persists in qualified security assessor networks for classified certification pathways. Distribution runs through federal contracting corridors in Washington DC, Bangalore's deployment expertise cluster, and Tallinn's digital governance advisory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic accountability requirements erect a compliance moat that rewards early-certified vendors with automatic Framework Contract qualification, while excluding unprepared competitors from European procurement pools.
For Market Incumbents: Lock in certification advantages by pre-positioning explainable AI documentation and human-in-the-loop override protocols ahead of expanding EU AI Act enforcement timelines. Deepen vertical integration into biometric hardware supply chains to secure welfare distribution contracts under India's BIS-mandated interoperability standards. Counter emerging cloud-native specialists through strategic partnerships with municipal joint procurement vehicles in Denmark and the Netherlands. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for specialized compliance consultancies to capture certification workflow automation demand from mid-tier systems integrators lacking in-house algorithmic impact assessment capabilities. Target Sub-Saharan municipal digitization programs in Rwanda and Kenya replicating Irembo and Huduma Centre architectures, where incumbent presence remains thin. Pursue mobile-first service design partnerships with India's UMANG super-app ecosystem to bypass desktop infrastructure gaps in low-PC-penetration economies. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by heritage federal contractors seeking cloud-native capability grafts, particularly for vendors holding pre-certified EU AI Act compliance modules. Long-term viability hinges on recurring revenue retention in municipal SaaS subscriptions rather than one-time perpetual license conversions. Watch for India's STQC-Europe ETSI reciprocity negotiations as an inflection signal that would eliminate redundant testing costs and accelerate vendor onboarding timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Pre-certification with explainable AI documentation secures automatic Framework Contract qualification across European procurement offices. |
| Biometric Hardware Integration | Fingerprint and iris verification capabilities capture welfare distribution contracts under India's Digital India compliance frameworks. |
| Mobile-First Service Architecture | UMANG super-app replication enables market entry in low-PC-penetration economies across Sub-Saharan Africa and South Asia. |
| Blockchain Audit Trail Deployment | Immutable transaction logging satisfies IFI transparency conditions attached to development financing for procurement and land registry systems. |
| Municipal Joint Procurement Participation | Aggregated demand vehicles in Denmark and the Netherlands reduce customer acquisition costs and establish recurring revenue baselines. |
Methodological Framework
Multi-period observation of cloud procurement volumes, biometric integration milestones, and EU AI Act implementation timelines anchored the trend analysis, supplemented by interviews with government CIOs, municipal IT procurement officers, systems integration architects, and compliance certification specialists. Secondary validation drew from FedRAMP authorization databases, India's STQC certification registries, ETSI technical specifications, and BIS interoperability standards documentation. Bottom-up project pipeline tracking across municipal digitization programs combined with top-down budget allocation analysis from national e-governance divisions to establish market sizing boundaries.
Segment-weighting across deployment models, service types, end-user tiers, and technology integration depths informed the analytical framework throughout the projection horizon. CAGRs derived from elasticity-adjusted adoption curves for cloud-native architectures, penetration rate modeling for biometric welfare systems, and regulatory compliance lag effects for EU AI Act implementation. Industry-specific inputs included Digital India portal consolidation timelines, Gaia-X federated infrastructure deployment schedules, and cross-border certification reciprocity negotiation status.
The model assumes a particular technology adoption path; alternative pathways for hybrid cloud sovereignty architectures or blockchain-anchored identity verification would alter the outlook substantially. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, interoperability standard adoption rates, and municipal budget cycle stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Smart Signaling Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
India Smart City Market
Smart City Technology
Global Smart City Market
Smart City Technology
Smart City Framework Market
Smart City Technology
Global Smart Ticketing Market
Smart City Technology
Smart Mailbox Market
Smart City Technology
Smart Space Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Global Smart Pole Market