
 Government Cloud Market | 2026-2036
Government Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Government Cloud Market Intelligence
The substitution of on-premise government data centers with commercial cloud infrastructure is recalibrating the total cost of ownership and service delivery models for public sector IT. Amazon Web Services leverages its first-mover advantage and extensive service portfolio in this space. Microsoft sustains a strong position through its deep relationships with government agencies and hybrid cloud offerings. Oracle competes by focusing on secure database and enterprise application migration for mission-critical workloads.
Government cloud refers to a computing model where cloud infrastructure and services are architected specifically for public sector use. It involves isolated environments and stringent security controls, often requiring compliance with frameworks like FedRAMP in the US or G-Cloud in the UK. Infrastructure as a Service (IaaS) remains the foundational solution offering, while Hybrid Cloud deployments are gaining traction for data sovereignty. Federal Agencies constitute the dominant end-user category due to large-scale modernization projects.
Regulatory frameworks like the US FedRAMP, the UK's G-Cloud framework, and Australia's IRAP are critical for market access. These standards dictate data sovereignty, security protocols, and vendor certification, directly influencing procurement decisions by government bodies. Vendors and agencies must continually assess the trade-offs between adopting multi-cloud strategies for innovation and the security complexities they introduce.
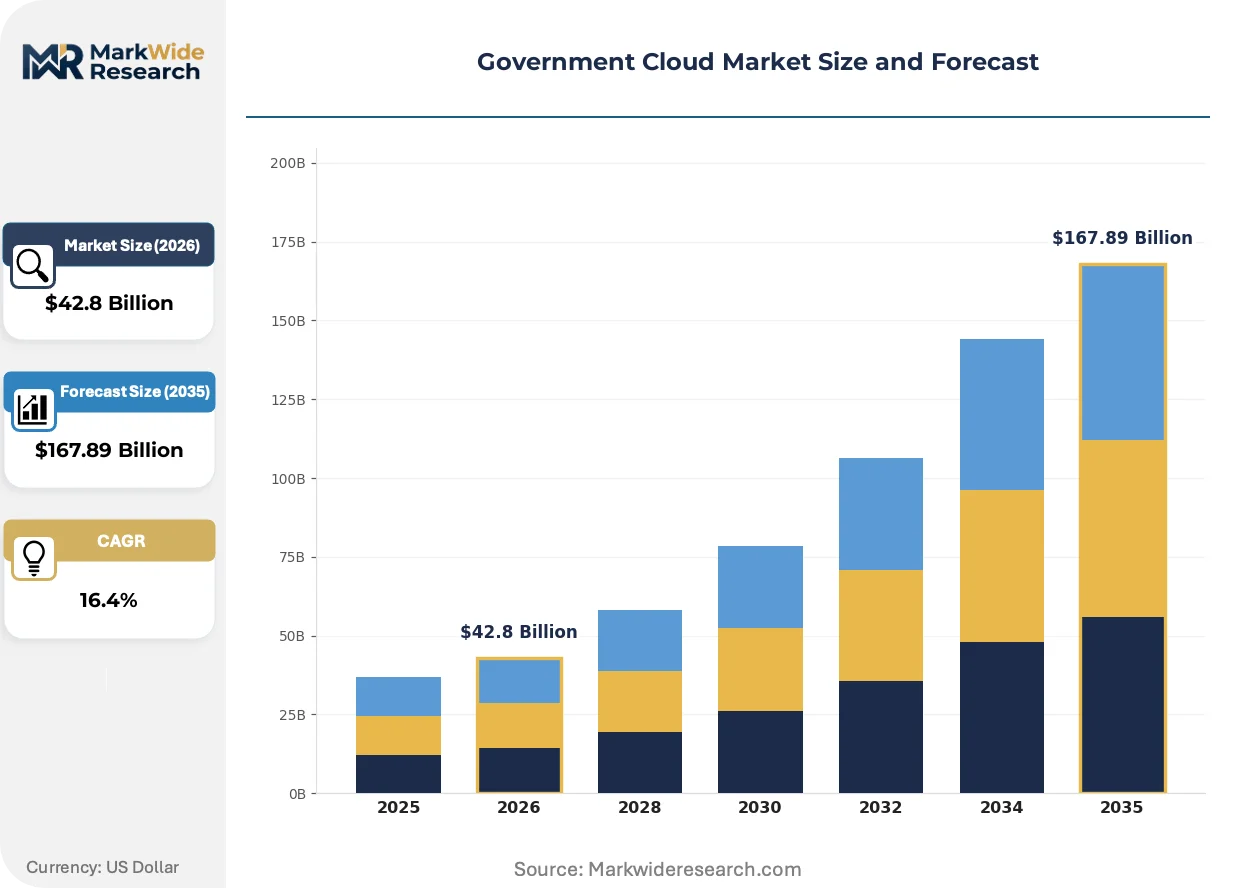
Market Dynamics
The central dynamic is the tension between national security imperatives demanding data sovereignty and the cost efficiencies of commercial hyperscale infrastructure. This conflict dictates public sector architecture and procurement choices.
Growth Catalysts
- Digital Modernization Mandates:Government initiatives to replace aging IT infrastructure with scalable cloud solutions drive foundational demand within large federal agencies.
- Defense Sector Adoption:The integration of cloud for command and control systems within defense organizations accelerates procurement for tactical data processing.
- Security Standardization:Frameworks like the US FedRAMP create a clear pathway for vendors, reducing ambiguity and speeding procurement for compliant cloud services.
Market Restraints
- Data Sovereignty Laws:National regulations mandating data remain within a country's borders create technical hurdles for deploying unified government cloud platforms.
- High Certification Costs:The lengthy, expensive process to achieve compliance with standards like FedRAMP High acts as a barrier for smaller cloud providers.
- Legacy System Complexity:The difficulty and cost of migrating mission-critical applications from decades-old government mainframes restrains the pace of adoption.
Strategic Opportunities
- Sovereign AI Clouds:Developing cloud environments for agencies to train AI models on sensitive data within national borders is a key growth area.
- State and Local Government Penetration:The market for state and municipal government cloud services in the United States remains underserved compared to federal agencies.
- Edge Computing for Defense:Integrating cloud with edge devices offers opportunities for tactical defense applications, enabling processing in disconnected environments.
Industry Challenges
- Cleared Talent Shortage:A scarcity of cloud architects and cybersecurity experts holding the necessary government security clearances constrains project execution and increases labor costs.
- Complex Systems Integration:The difficulty of interfacing modern cloud services with bespoke legacy government systems without operational disruption remains a primary implementation hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Government Cloud Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $167.89 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Private Cloud, Community Cloud, Hybrid Cloud, Multi-Cloud, Dedicated Cloud Solution Offering: Infrastructure as a Service, Platform as a Service, Software as a Service, Disaster Recovery, Data Analytics Application: Public Safety, Education Administration, Taxation Systems, Defense Operations, Social Services End User: Federal Agencies, Local Authorities, Public Sector Enterprises, Regulatory Bodies, Law Enforcement |
| Companies Covered | Amazon Web Services, Microsoft, Google, IBM, Oracle, Cisco Systems, Dell Technologies, CGI, VMware, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Government Cloud Market Strategic Shifts & Innovations
Evolution toward specialized, mission-specific cloud environments defines the market's trajectory. This includes the development of sovereign capabilities and purpose-built platforms for intelligence, defense, and civilian agency workloads, moving beyond general-purpose infrastructure.
Confidential computing, which utilizes secure hardware enclaves, is a key technological development. It processes sensitive data in an encrypted state, shielding it even from the cloud provider's access. Intelligence agencies and defense departments are adopting this for collaborative analysis, and this technology is electrifying the market for multi-party data sharing on highly sensitive workloads.
The EU's push for digital sovereignty, exemplified by initiatives like GAIA-X, is a significant regulatory force. It compels US-based hyperscalers to engineer specific data residency solutions and form partnerships with local European providers. Consequently, government bodies in Europe are prioritizing vendors that guarantee data is processed and stored exclusively within the EU, altering procurement criteria.
A move from single-vendor contracts to multi-cloud strategies alters agency buying patterns. This disrupts monolithic, long-term contracts favoring incumbents and replaces them with a flexible, best-of-breed approach. This shift is most visible within US and Australian federal departments seeking to avoid vendor lock-in and access specialized services.
Government Cloud Market Segmentation
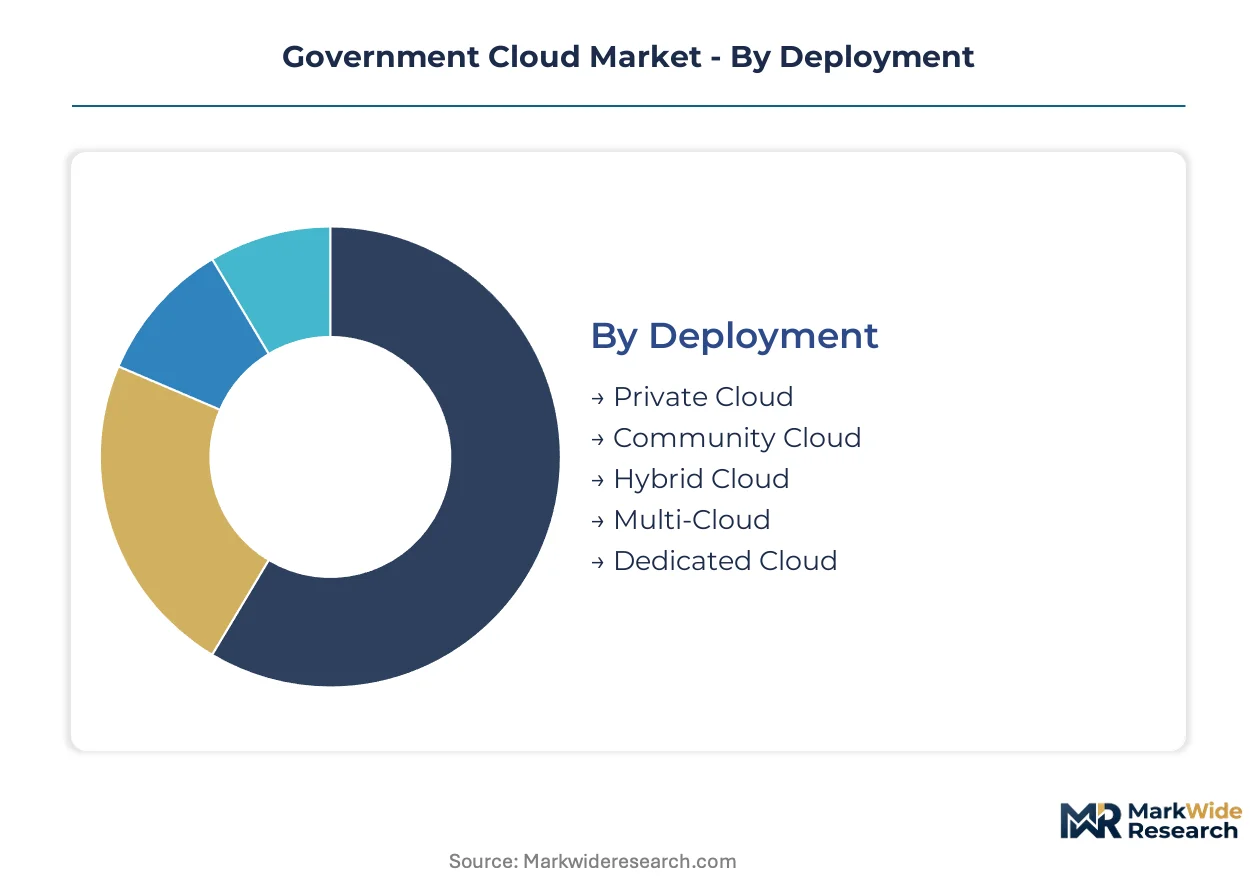
The government cloud market segmentation reflects the diverse operational needs and stringent security requirements across public sector entities. Understanding these distinct segments is crucial for solution providers to tailor offerings that meet specific compliance mandates and functional demands.
Deployment:
Deploying government cloud solutions often involves significant upfront capital investment, particularly for dedicated infrastructure.
- Hybrid Cloud:This deployment model integrates on-premises infrastructure with public cloud services, creating a unified IT environment. Demand concentrates in European governments and US federal agencies seeking data sovereignty alongside scalability, enabling seamless integration of legacy systems with modern cloud capabilities.
- Dedicated Cloud:A single-tenant cloud environment with isolated physical infrastructure, offering maximum security and performance. National security agencies and critical infrastructure operators in countries like the United States and Australia prioritize this model for highly sensitive workloads and classified data.
- Private Cloud:Cloud infrastructure provisioned for exclusive use by a single organization, managed either internally or by a third party.
- Community Cloud:Shared cloud infrastructure provisioned for a specific community of consumers from organizations with common concerns, such as intelligence agencies or research institutions.
- Multi-Cloud:The use of multiple cloud computing services from different providers within a single architecture, mitigating vendor lock-in and leveraging best-of-breed services.
Dedicated Cloud absorbs the bulk of installed capacity; Hybrid Cloud is expanding most quickly.
Solution Offering:
The varied application requirements within government drive the differentiation across solution offerings.
- Infrastructure as a Service:IaaS provides virtualized computing resources over the internet, including virtual machines, storage, and networking. US federal agencies and UK government departments utilize IaaS as a foundational layer for modernizing aging IT infrastructure and hosting new applications.
- Data Analytics:Solutions that enable processing, analyzing, and visualizing large datasets to extract insights and support decision-making. Intelligence communities and defense organizations globally adopt these tools for threat assessment, operational planning, and policy development.
- Platform as a Service:PaaS delivers a complete development and deployment environment in the cloud, abstracting underlying infrastructure management.
- Software as a Service:SaaS provides ready-to-use applications hosted by a third-party vendor and accessible over the internet, commonly used for administrative tasks.
- Disaster Recovery:Cloud-based services designed to ensure business continuity and data resilience by replicating data and systems to offsite locations.
Infrastructure as a Service forms the foundational layer for most government cloud deployments; Data Analytics solutions are becoming strategically critical for informed decision-making.
Application:
Specific government functions dictate the unique cloud application requirements across the public sector.
- Defense Operations:Cloud solutions supporting military command and control, intelligence gathering, surveillance, and reconnaissance (ISR) systems. The US Department of Defense and NATO member countries are heavily investing in this segment for tactical edge computing and secure data processing.
- Public Safety:Cloud services for emergency response, law enforcement data management, and citizen safety initiatives. Local authorities in Germany and municipal police departments in the United States deploy these systems for real-time incident management and crime prevention.
- Education Administration:Cloud platforms for managing student information, learning management systems, and administrative functions within public education institutions.
- Taxation Systems:Cloud-based solutions for tax collection, financial reporting, and compliance management within national revenue agencies.
- Social Services:Cloud applications supporting citizen welfare programs, public health data management, and community support initiatives.
Defense Operations represent the most complex cloud application environments; Public Safety applications drive significant transactional volume.
End User:
Varying levels of regulatory oversight and data sensitivity characterize different government end-user segments.
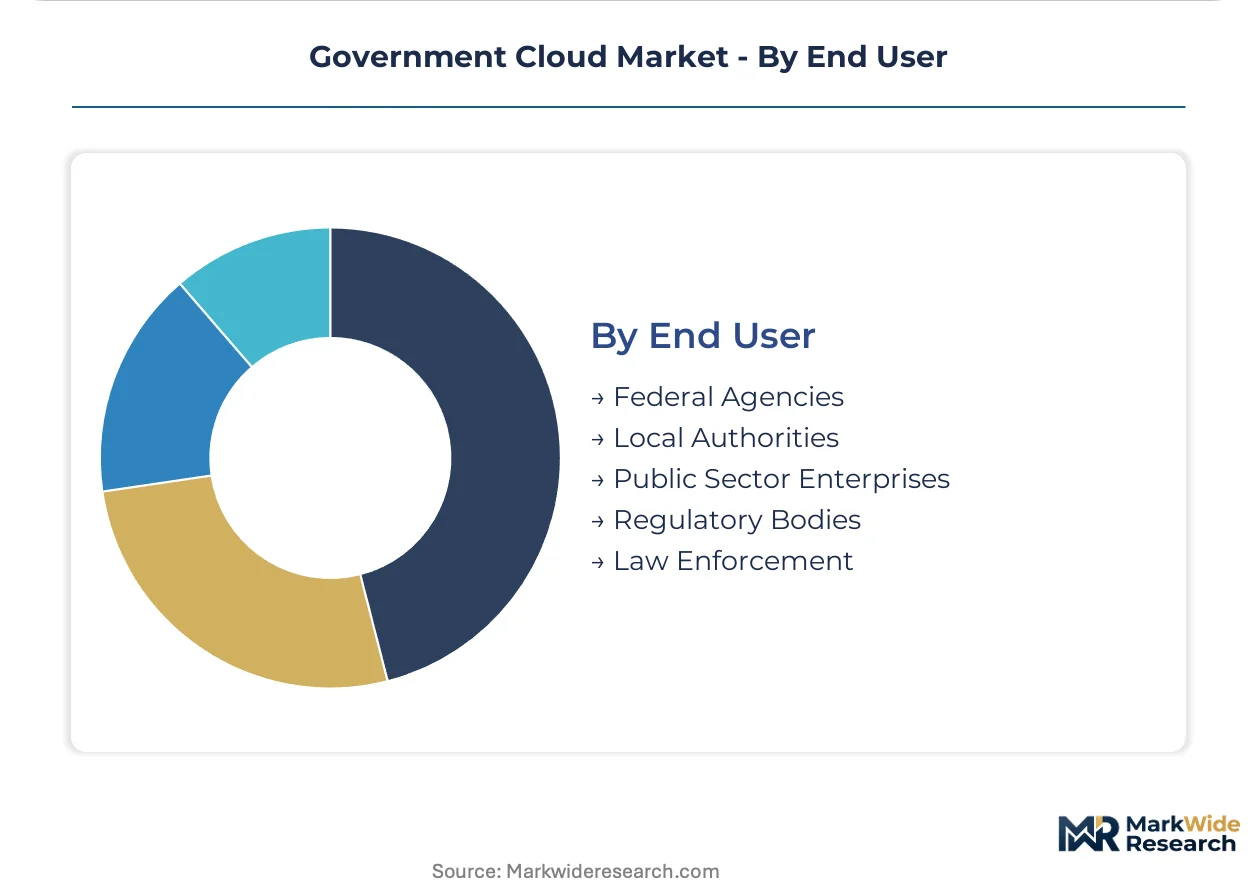
- Federal Agencies:National-level government departments responsible for large-scale IT modernization projects and critical national infrastructure. The US federal government, particularly agencies like the Department of Homeland Security, leads this segment in cloud adoption and spending.
- Local Authorities:Municipal, county, and state-level government entities providing direct citizen services and managing regional infrastructure. State governments in Australia and European municipalities are increasingly migrating citizen-facing applications to the cloud for efficiency and accessibility.
- Public Sector Enterprises:Government-owned corporations or organizations operating in commercial sectors, such as utilities or transportation.
- Regulatory Bodies:Agencies responsible for enforcing laws, setting standards, and overseeing specific industries, requiring secure data management for compliance.
- Law Enforcement:Police departments, investigative agencies, and correctional facilities utilizing cloud for evidence management, analytics, and operational support.
Federal Agencies exhibit the most mature cloud adoption profiles; Local Authorities are rapidly increasing their cloud spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates significant demand for government cloud services. This demand is driven by extensive federal agency modernization projects. Public sector entities globally are recalibrating IT strategies to leverage cloud infrastructure.
United States
Federal agencies drive substantial demand for government cloud services, fueled by large-scale IT modernization initiatives and defense operations. The US FedRAMP authorization process standardizes security requirements, accelerating compliant cloud procurement. Washington D.C. agencies lead cloud adoption for critical national infrastructure and mission-critical workloads.
United Kingdom
British government departments pursue digital transformation initiatives, enhancing public sector service delivery through cloud platforms. The UK's G-Cloud framework streamlines procurement for cloud services, ensuring compliance and efficiency. London government departments increasingly utilize cloud for citizen-facing applications and data management.
Germany
German public sector entities prioritize data sovereignty and local authority modernization, particularly for public safety applications. European initiatives like GAIA-X strongly influence data residency requirements for cloud vendors. Municipalities across Bavaria and North Rhine-Westphalia deploy cloud for real-time incident management and administrative tasks.
Australia
Australian federal agencies prioritize modernization projects, increasingly adopting multi-cloud strategies to avoid vendor lock-in and enhance resilience. Australia's IRAP framework dictates stringent security protocols for government cloud deployments. Canberra federal agencies utilize cloud services for secure data processing and collaborative analysis.
France
French ministries and local authorities emphasize digital sovereignty and public sector efficiency, requiring secure data processing within national borders. French government bodies prioritize vendors guaranteeing data storage and processing exclusively within the EU. Paris-based ministries leverage cloud platforms for administrative functions and citizen welfare programs.
Government Cloud Market Key Industry Players
Strategic partnerships dominate the current landscape, as hyperscale providers collaborate with specialized security vendors and regional integrators. The market exhibits consolidation among major cloud providers, yet fragmentation persists among niche solution providers offering specialized government-specific services. Hyperscale providers, specialized security vendors, and system integrators constitute the primary strategic archetypes. Key competitive moves include strategic partnerships, portfolio diversification, and geographic expansion into new public sector markets.
Within the hyperscale provider tier, Amazon Web Services and Microsoft exemplify companies leveraging extensive service portfolios and established government relationships. Oracle occupies a position focused on secure database and enterprise application migration for mission-critical workloads. These entities anchor the market by providing foundational infrastructure and a broad range of cloud services to government agencies globally.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Oracle |
| Cisco Systems |
| Dell Technologies |
| CGI |
| VMware |
Cost & Logistics Intelligence
Specialized talent costs for cloud architects and cybersecurity experts significantly influence the overall service pricing for government cloud solutions, particularly for highly secure, dedicated environments. This cost component flows directly into the premium charged for compliant, mission-critical deployments.
Pricing Analysis
Volume-based contracts often yield lower per-unit margins for cloud providers compared to highly customized, secure deployments. Pricing stratifies across certification levels, with FedRAMP High authorization commanding a premium due to stringent security requirements and specialized infrastructure. Customization level and the integration complexity with legacy systems also drive price differentiation. Pricing softness reflects increasing multi-cloud adoption, as agencies seek best-of-breed services from multiple vendors. Federal agencies involved in defense operations exhibit lower price sensitivity compared to local authorities managing administrative tasks.
Supply Chain Analysis
Regional data centers and localized infrastructure deployment are central to the government cloud supply chain, ensuring data residency and low latency. Geographic supply concentration includes the United States, United Kingdom, and Germany, driven by early adoption and robust regulatory frameworks. The supply chain relies on semiconductor chips, specialized networking hardware, and high-capacity data storage components. Geopolitical tensions affecting semiconductor chip supply represent a structural risk. Downstream distribution primarily involves direct contracts with government agencies, often facilitated by system integrators for complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The government cloud market operates under a supply constraint, primarily driven by the scarcity of FedRAMP High authorized data center capacity. This bottleneck props up premium pricing for highly secure, compliant infrastructure.
For Market Incumbents: Cement existing relationships with federal agencies by investing in continuous FedRAMP authorization updates and deepening integration with legacy government systems. This defends against the threat posed by emerging niche providers specializing in sovereign AI clouds. Leveraging strategic acquisitions of specialized security firms can further enhance their service portfolio and market position.
For New Entrants and Emerging Players: Enter via niche application segments within state and local government agencies, leveraging specialized expertise in specific public sector functions. Underserved state and local government markets, particularly for public safety applications, present significant white-space opportunities. Focusing on rapid, tailored deployments for specific departmental needs offers a compelling go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized security software providers in the United States, particularly those with existing FedRAMP accreditations. Long-term viability across a five-to-ten-year window favors platforms capable of handling classified data within sovereign boundaries. Mid-sized cloud providers with niche expertise in confidential computing or sovereign AI represent attractive acquisition targets. Increasing government R&D spending on quantum-resistant cryptography serves as a key inflection signal to watch.
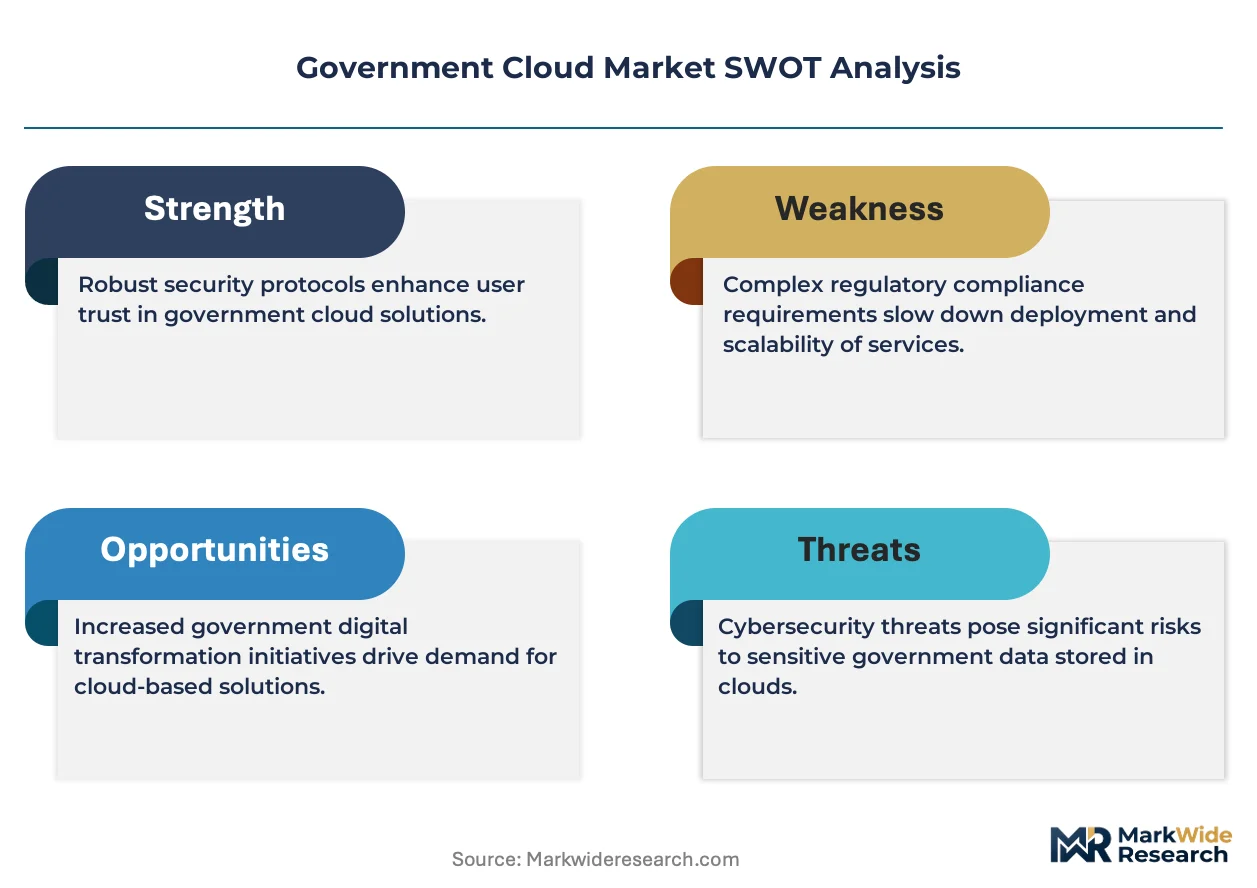
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in FedRAMP High Data Centers | Increases availability of secure infrastructure for critical US federal agency workloads. |
| Strategic Partnerships with Local European Providers | Ensures compliance with GAIA-X and addresses EU data sovereignty requirements. |
| Portfolio Diversification into Sovereign AI Cloud | Captures demand from intelligence agencies for secure, national AI model training. |
| Accelerated FedRAMP High and IRAP Certifications | Expands market access for new services within US and Australian government bodies. |
| Geographic Expansion into State and Local Government | Taps into an underserved market segment with significant digital modernization potential. |
Research Approach
Multi-period observation of government IT spending patterns and cloud adoption rates anchored the trend analysis, supplemented by interviews with key industry stakeholders. Primary research involved discussions with federal CIOs, defense procurement officers, cloud solution architects, and cybersecurity compliance specialists. This was triangulated with secondary validation from US FedRAMP marketplace data, UK G-Cloud framework reports, Australian IRAP documentation, and public sector IT budget disclosures, ensuring both bottom-up and top-down insights.
An input-output matrix structured the quantitative forecasting, mapping demand drivers to supply-side capabilities across the analysis window. The market was segmented by deployment model, solution offering, application, end-user category, and regional regulatory frameworks. Compound Annual Growth Rates were derived through regression analysis, considering historical growth trajectories and projected market shifts. Key industry-specific forecast inputs included government digital modernization mandates and evolving data sovereignty requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid geopolitical shifts or significant regulatory changes. All forecasts reflect documented assumptions regarding technological advancements and procurement cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Cloud Enablement Market
Cloud Computing
UK Cloud Computing Market
Cloud Computing
North America Professional Cloud Services Market
Cloud Computing
SME Cloud Market
Cloud Computing
Global Server Virtualization Market
Cloud Computing
Multi-Cloud Networking Market
Cloud Computing
Hybrid Cloud Services Market
Cloud Computing
North America Cloud Microservices Platform Market
Cloud Computing
Philippines ICT Market
Cloud Computing
AI and Blockchain Cloud Services Market
Cloud Computing
Community Cloud Market
Cloud Computing
Cloud Data Quality Monitoring Market
Cloud Computing
Cloud ELN Service Market
Cloud Computing
Indonesia Cloud Market
Cloud Computing
Cloud Computing Stack Layers Market
Cloud Computing
Global Cloud Computing in Healthcare Market