
 Asia-Pacific Flanges Market | 2026-2036
Asia-Pacific Flanges Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Flanges Market Insights
Stainless steel is pivoting toward duplex and super-duplex grades in offshore and sour-service applications, replacing conventional carbon steel flanges in corrosion-critical environments. Nippon Steel Corporation leverages its integrated steelmaking and forging capabilities to supply high-nickel alloy flanges for Japanese LNG infrastructure. Saini Flange Pvt anchors its position through specialized forging operations serving India's domestic refinery expansion. Georg Fischer competes with advanced plastic-composite flange systems for chemical resistance in semiconductor fab water systems.
Asia-Pacific flanges are mechanical connectors, typically forged or cast, that bolt pipe sections, valves, and equipment together at standardized pressure-temperature ratings such as ASME B16.5 Class 150 through 900. Their primary purpose is to enable disassembly for maintenance while containing pressurized fluids across oil and gas, power, and process industries. Weld neck configurations command premium positioning due to superior fatigue resistance in cyclic thermal service, while slip-on variants occupy volume-driven water supply and general piping segments. Stainless steel and alloy steel grades are capturing margin pools as petrochemical operators specify higher corrosion allowances for extended asset life.
China's SAMR enforces GB standards for pressure equipment materials, while India's BIS mandates IS certification for flanges used in boiler and pressure vessel construction. Japan's METI coordinates JIS standards alignment with international pressure equipment codes, creating a layered compliance environment for cross-border suppliers. Australia's TGA and South Korea's MFDS indirectly shape demand through their pharmaceutical and food-grade piping specifications. Stakeholders must monitor how evolving carbon-border mechanisms and domestic content requirements across these jurisdictions will redirect sourcing decisions and qualification timelines.
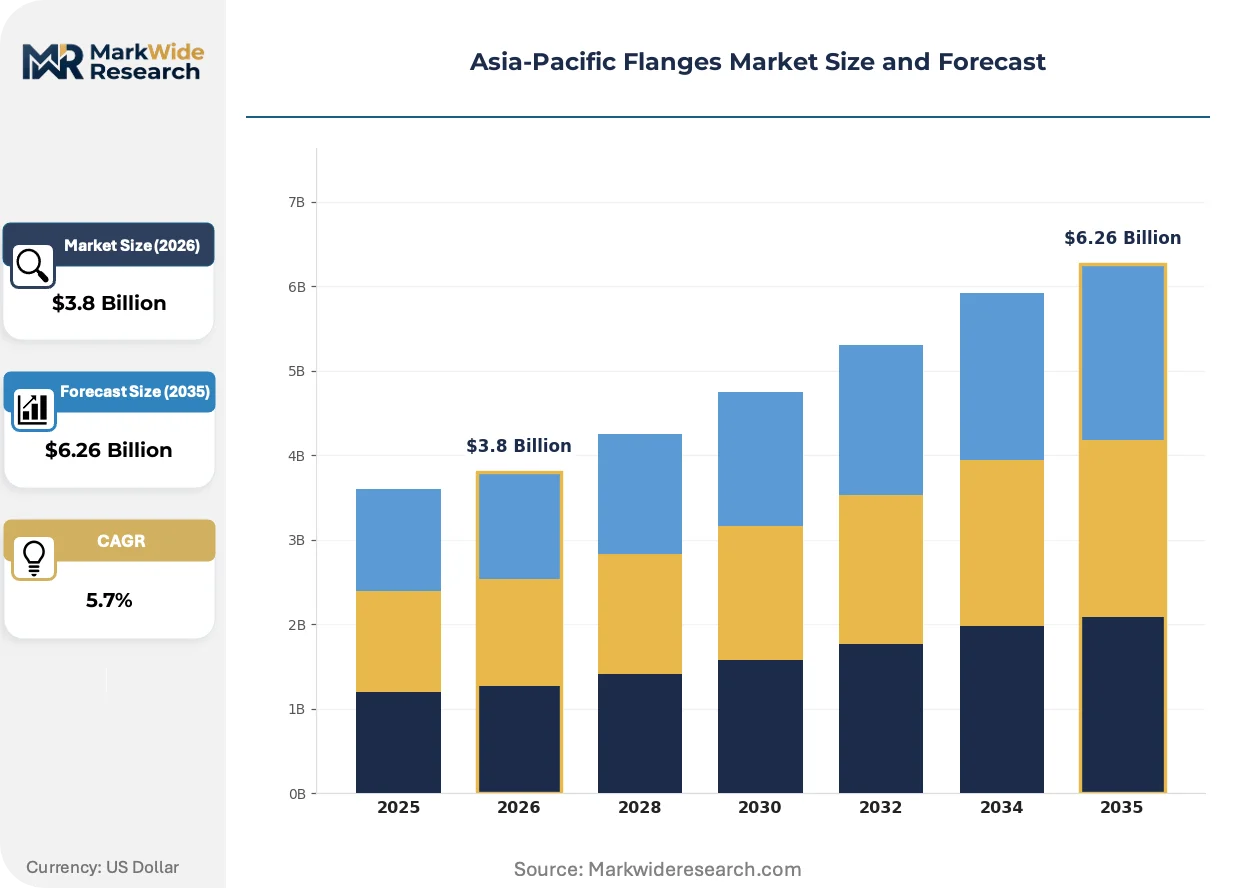
Market Dynamics
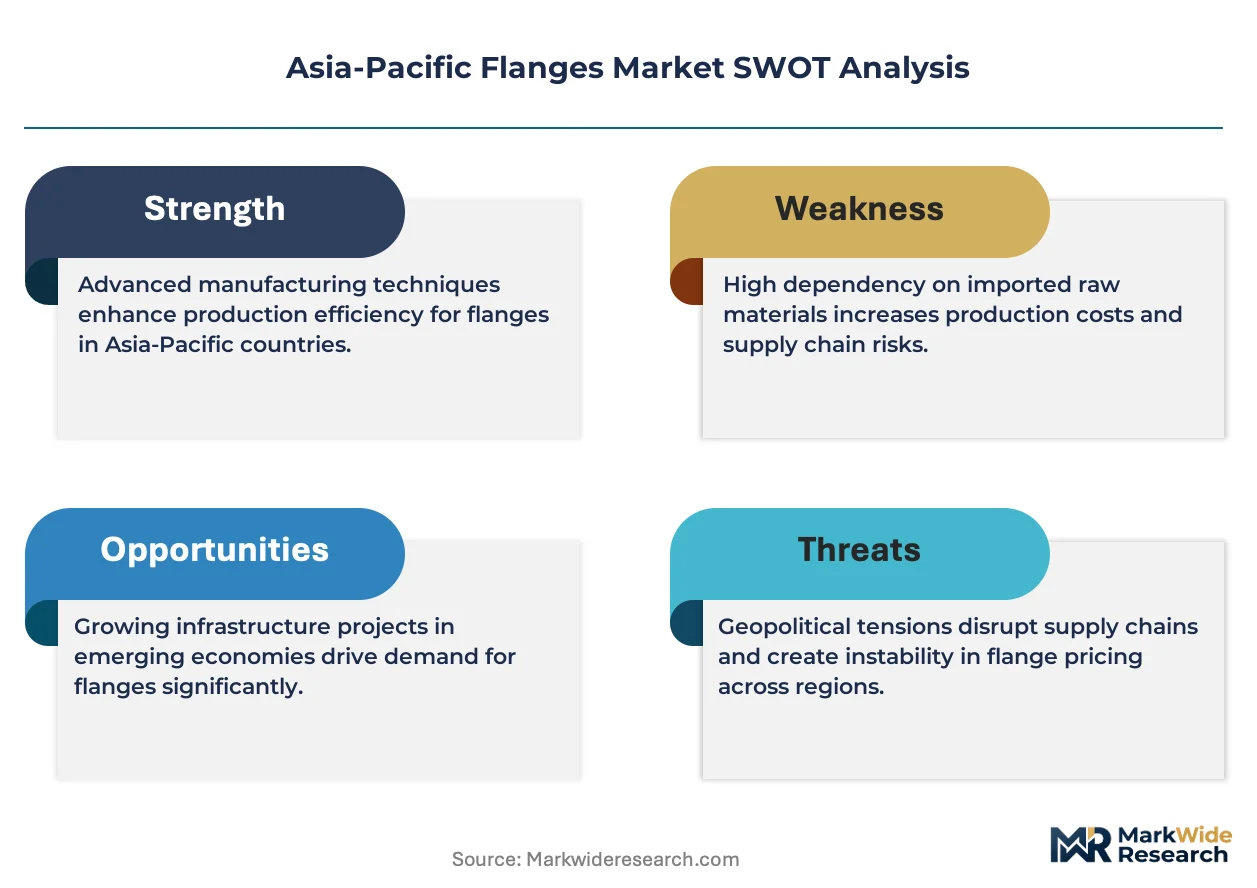
Material specification upgrades across Asia-Pacific process industries are compressing procurement cycles for corrosion-resistant alloys while extending supplier qualification timelines. China's GB standards and India's BIS certification regimes now mandate full material traceability for critical service flanges, forcing foundries to restructure quality systems.
Growth Catalysts
- Refinery and LNG terminal buildouts:India's western coastal corridor is accelerating flange procurement for high-pressure processing lines as petrochemical complexes expand capacity.
- GB standards enforcement:China's SAMR tightening of pressure equipment material rules is displacing non-compliant suppliers and consolidating procurement toward certified domestic and regional vendors.
- Duplex grade substitution:Offshore and sour-service applications are specifying super-duplex stainless steel flanges to replace carbon steel in chloride-rich environments.
Market Restraints
- Nickel alloy input volatility:High-nickel content grades face cost pressure from concentrated raw material sourcing through a limited supplier base.
- Regional forging capacity concentration:Heavy-wall and large-diameter flange production clusters in select East Asian manufacturing hubs, creating geographic supply risk.
- Plastic-composite substitution:Semiconductor fab water systems are specifying advanced polymer flanges for chemical resistance, compressing metal flange addressable market in this vertical.
Strategic Opportunities
- Southeast Asia petrochemical expansion:Vietnam and Indonesia process industry investments are creating demand for ASME Class 600 and 900 rated weld neck configurations.
- JIS-ISO alignment:Japan's METI coordination of domestic standards with international pressure equipment codes is reducing cross-border qualification friction for compliant suppliers.
- Digital traceability integration:Blockchain-enabled material certification is converging with IoT sensor monitoring to enable predictive maintenance contracts for flange assets.
Industry Challenges
- Non-destructive testing technician scarcity:Ultrasonic and radiographic inspection certification programs are not producing qualified personnel at the pace required by expanding fabrication demand.
- Dual certification timeline compression:Suppliers seeking both BIS and GB approvals face sequential rather than parallel review processes, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Flanges Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Stainless Steel, Carbon Steel, Alloy Steel, Plastic Connection Type: Weld Neck, Slip-On, Blind, Socket Weld Pressure Class: 150#, 300#, 600#, 900# Industry Application: Oil & Gas, Water Supply, Chemical Processing, Power Generation |
| Companies Covered | AFG Holdings, Saini Flange Pvt, Nippon Steel Corporation, Flanschenwerk Bebitz GmbH, Hitachi, Georg Fischer, ASC Engineered Solutions, Mueller Water Products, Parker Hannifin, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Flanges Market Trends and Innovations
Automation of forging and finishing operations is compressing lead times while elevating dimensional consistency for high-pressure rated products. Regulatory divergence across Asia-Pacific jurisdictions is fragmenting compliance requirements. Buyer concentration among EPC contractors is reshaping procurement power dynamics.
Closed-die precision forging combined with robotic grinding and CNC machining is automating the production of complex flange geometries previously requiring manual finishing. Japanese and Korean shipyards are specifying these automated-process flanges for LNG carrier cargo systems. The technology is automating quality documentation generation, reducing certification labor and accelerating customer audit acceptance.
India's BIS has mandated IS certification for all flanges used in boiler and pressure vessel construction under amended pressure equipment rules. This regulatory tightening is disqualifying uncertified imports and redirecting procurement toward domestic foundries with established BIS laboratory relationships. The western refinery corridor is responding fastest, with Reliance Industries and Indian Oil Corporation revising approved vendor lists to exclude non-compliant sources.
Engineering-procurement-construction contractors are consolidating annual flange volumes into framework agreements with tier-one suppliers, displacing spot purchasing through distributor networks. This buyer concentration is compressing margins for mid-scale forging houses while rewarding integrated steelmakers with captive melt shops. The pattern is most visible in Australia's resources sector, where BHP and Rio Tinto have standardized procurement through regional supply hubs in Perth and Brisbane.
Asia-Pacific Flanges Market Segmentation
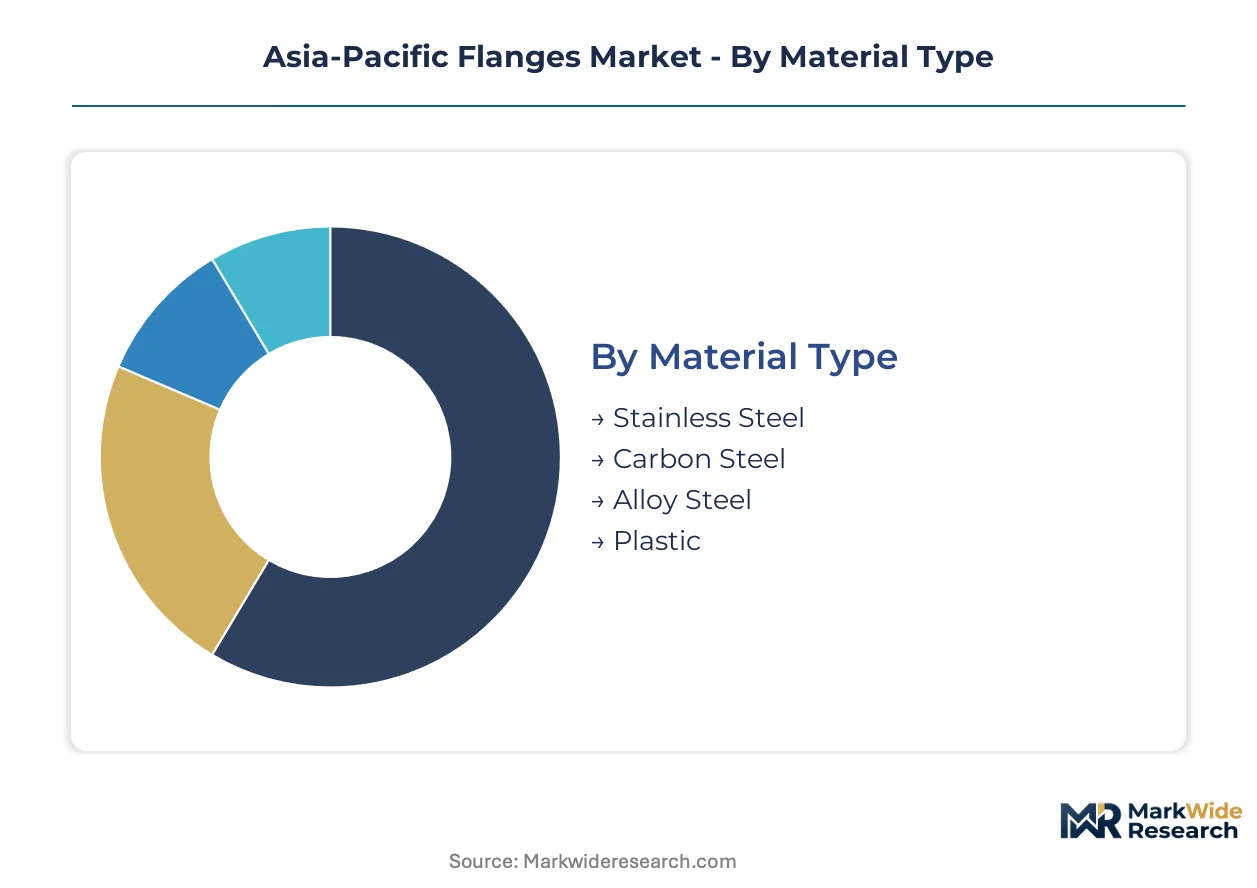
Material substitution cycles and pressure rating upgrades are fragmenting procurement specifications across Asia-Pacific process industries. Segment boundaries blur when duplex grades replace carbon steel in corrosive service or when plastic composites displace metals in semiconductor water systems.
Material Type:
Upgrade cycles for corrosion resistance are compressing replacement intervals while elevating alloy specifications in critical service applications.
- Stainless Steel:Austenitic grades dominate general process piping, while duplex and super-duplex variants are capturing share in offshore platforms and sour-gas processing. India's western coastal refineries are specifying higher nickel content for extended asset life in chloride-rich environments.
- Carbon Steel:Standard grades retain volume leadership in water distribution and low-pressure utility piping. China's municipal infrastructure buildouts are absorbing coated carbon steel flanges for cost-sensitive buried service applications.
- Alloy Steel:Chrome-molybdenum grades serve elevated temperature boiler and power generation applications. Japanese thermal power operators specify P91 and P92 grades for ultra-supercritical steam conditions.
- Plastic:PVDF and PTFE composite flanges are displacing metals in semiconductor fab ultrapure water systems. Singapore and South Korea fab expansions are driving procurement for chemical-resistant polymer connectors.
Carbon steel sits at the top of the volume ranking, with duplex stainless steel climbing the fastest.
Connection Type:
Application severity dictates configuration selection, with fatigue-critical service commanding premium weld neck specifications over commodity slip-on alternatives.
- Weld Neck:Superior fatigue resistance and structural integrity under cyclic thermal loading. LNG carrier cargo systems and high-pressure hydrocarbon processing lines in Australia and Indonesia mandate this configuration.
- Slip-On:Lower installed cost and simpler alignment requirements suit non-critical water and steam applications. India's municipal water authorities specify slip-on variants for distribution network expansion.
- Blind:Positive isolation for pressure testing and maintenance shutdowns. Refinery turnaround schedules in Thailand and Vietnam are driving spot procurement for temporary isolation.
- Socket Weld:Compact dimensions for high-pressure small-bore piping in instrument and control lines. South Korean shipyards specify socket weld flanges for LNG carrier fuel gas systems.
Slip-on configurations dominate unit volumes, though weld neck specifications are gaining share fastest in energy infrastructure.
Pressure Class:
Project scale and hazard classification are elevating minimum pressure ratings across petrochemical and LNG terminal developments.
- 150#:Low-pressure water, HVAC, and general industrial service. China's commercial building sector absorbs substantial volumes for heating and cooling distribution.
- 300#:Moderate pressure process piping in chemical and food processing. Australian mining operations specify 300# ratings for slurry and tailings handling.
- 600#:High-pressure hydrocarbon processing and power generation steam lines. Indonesia's expanding refinery capacity is concentrating demand for this rating class.
- 900#:Severe service in LNG liquefaction and subsea production. Malaysia's offshore gas developments require 900# weld neck configurations for high-pressure wellhead connections.
The 150# rating maintains volume leadership, while 600# specifications are expanding most quickly in Southeast Asian petrochemical investment.
Industry Application:
End-use concentration varies by national industrial structure, with energy and water infrastructure commanding distinct specification profiles.
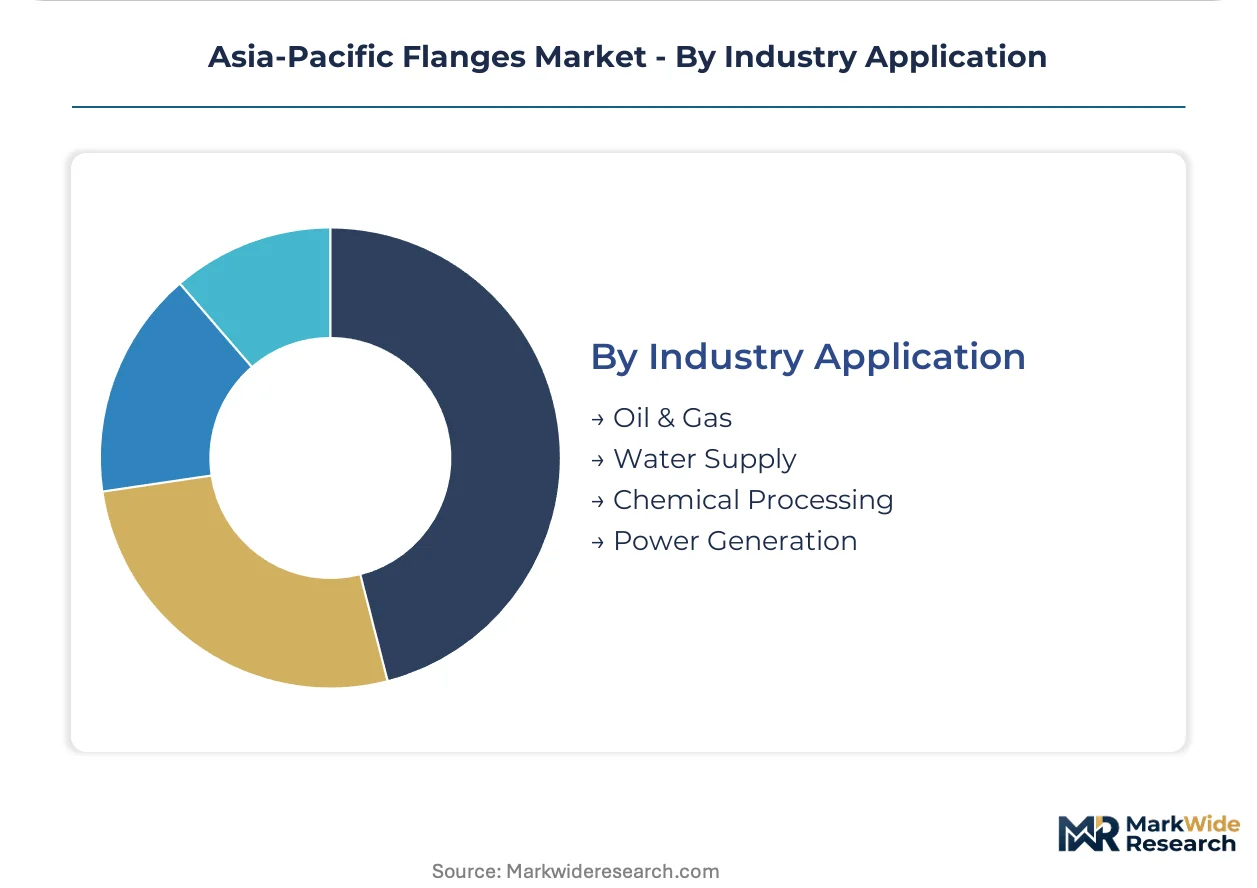
- Oil & Gas:Exploration, production, refining, and LNG value chain applications. Australia's offshore gas developments and India's refinery expansions are concentrating procurement for sour service and cryogenic specifications.
- Water Supply:Municipal distribution, treatment, and desalination infrastructure. China's South-North Water Transfer project and Philippine urban water utilities are driving carbon steel and ductile iron flange demand.
- Chemical Processing:Fertilizer, petrochemical, and specialty chemical production. Vietnam's emerging integrated refining and petrochemical complexes are specifying corrosion-resistant alloys for acid service.
- Power Generation:Thermal, nuclear, and renewable energy plant construction. Japan's thermal power fleet refurbishment and India's ultra-mega power projects are elevating high-temperature alloy specifications.
Oil and gas sits at the top of the value ranking, with chemical processing climbing fastest on Southeast Asian capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's western coastal corridor anchors flange procurement intensity across the Asia-Pacific region, where refinery and LNG terminal investments concentrate demand for high-pressure rated configurations.
India
Reliance Industries and Indian Oil Corporation are accelerating flange procurement for refinery expansion along the Gujarat-Maharashtra industrial belt. India's BIS mandates IS certification for pressure vessel construction, disqualifying uncertified imports and redirecting sourcing toward domestic foundries with established laboratory relationships. The Jamnagar refining complex is revising approved vendor lists to exclude non-compliant sources.
China
Municipal infrastructure buildouts are absorbing coated carbon steel flanges for cost-sensitive buried water distribution applications. China's SAMR enforces GB standards for pressure equipment materials, displacing non-compliant suppliers and consolidating procurement toward certified domestic and regional vendors. The Yangtze River Delta manufacturing clusters are restructuring quality systems to meet full material traceability mandates.
Japan
LNG infrastructure investments are driving specification of high-nickel alloy flanges for cryogenic cargo systems and regasification terminals. Japan's METI coordinates JIS standards alignment with international pressure equipment codes, reducing cross-border qualification friction for compliant suppliers. Kanto-based shipyards are specifying automated-process flanges for LNG carrier construction.
Australia
Offshore gas developments in the Browse and Scarborough fields are concentrating procurement for 900# weld neck configurations in high-pressure wellhead connections. Australia's TGA shapes demand through pharmaceutical-grade piping specifications, though resources sector procurement dominates volume. BHP and Rio Tinto have standardized flange purchasing through regional supply hubs in Perth and Brisbane.
South Korea
Semiconductor fab expansions are driving procurement of chemical-resistant polymer flanges for ultrapure water systems. South Korea's MFDS indirectly shapes demand through food-grade piping specifications, while shipyards specify socket weld flanges for LNG carrier fuel gas systems. The Busan-Ulsan industrial corridor is integrating automated forging quality documentation into customer audit protocols.
Asia-Pacific Flanges Market Competitive Landscape
Global majors compete with regional champions across certification and material specification dimensions, creating a tiered structure where integrated steelmakers with captive melt shops hold procurement advantages. The vendor base separates into three strategic archetypes: diversified industrial conglomerates with forging divisions, specialized flange fabricators serving domestic energy infrastructure, and advanced materials suppliers targeting corrosion-critical applications. Competitive moves center on dual certification acquisition for BIS and GB compliance, alongside framework agreement consolidation with engineering-procurement-construction contractors.
Among Asia-Pacific-based fabricators, Saini Flange Pvt anchors the specialized domestic supplier tier through forging operations serving India's refinery expansion, while Nippon Steel Corporation represents the integrated steelmaker archetype with capabilities spanning high-nickel alloy production. Georg Fischer occupies a position in advanced materials systems, exemplifying the diversification path beyond traditional metal flanges into polymer-composite solutions for chemical resistance applications.
| Leading Market Players |
|---|
| AFG Holdings |
| Saini Flange Pvt |
| Nippon Steel Corporation |
| Flanschenwerk Bebitz GmbH |
| Hitachi |
| Georg Fischer |
| ASC Engineered Solutions |
| Mueller Water Products |
| Parker Hannifin |
| Others |
Pricing and Supply Chain Analysis
Captive melt shop integration anchors pricing power for Asia-Pacific flange suppliers, as foundries with in-house nickel alloy production bypass volatile spot markets for critical raw materials. China's SAMR traceability mandates and India's BIS certification requirements are compressing margins for non-integrated competitors while rewarding vertically structured producers with cost visibility and procurement leverage.
Pricing Analysis
Input-cost pass-through from nickel alloy volatility is intensifying price differentiation between captive-melt integrated suppliers and merchant-market dependent fabricators. Three-tier pricing structure across premium ASME-certified, standard BIS-compliant, and economy-grade uncoated carbon steel levels segments buyer willingness-to-pay. Pricing pressure stems from EPC contractor consolidation into framework agreements, compressing spot-market premiums. Municipal water authorities exhibit highest price sensitivity for slip-on carbon steel volumes, while LNG terminal operators absorb premium weld neck specifications with limited negotiation leverage.
Supply Chain Analysis
Workforce-availability constraints in China's Yangtze River Delta, India's Gujarat-Maharashtra belt, and Japan's Kanto region are extending lead times for certified forging technicians. Raw material sourcing draws from Indonesian nickel laterite, Australian coking coal, and South Korean ferrochrome feedstocks. Single-source vulnerability concentrates in high-nickel alloy semifinished products from limited East Asian melt shops. Distribution runs through EPC contractor regional hubs in Perth, Brisbane, and Singapore, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific flange markets offer margin expansion through alloy grade substitution toward duplex and super-duplex specifications, as corrosion-critical applications absorb premium pricing for extended asset life. Automation of forging documentation and certification labor is compressing cost-to-serve for integrated producers.
For Market Incumbents: Deepen backward integration into nickel alloy melt capacity to secure input cost visibility against LME volatility. Expand BIS and GB dual-certification laboratory relationships in India's western refinery corridor to disqualify import competition. Defend framework agreement positioning with Reliance Industries and Indian Oil Corporation through predictive maintenance service bundling. For New Entrants and Emerging Players: Capture Southeast Asian petrochemical greenfield demand in Vietnam and Indonesia, where ASME Class 600 and 900 weld neck specifications face limited certified domestic supply. Target semiconductor fab water system polymer flange applications in Singapore and South Korea, where Georg Fischer's metal-composite positioning leaves white space for specialized entrants. Pursue JIS-ISO alignment certification to reduce cross-border qualification friction with Japanese LNG infrastructure buyers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale forging houses with established BIS laboratory relationships because India's western coastal refinery expansion is disqualifying uncertified imports and consolidating procurement toward compliant domestic sources. Five-to-ten year viability hinges on automation capex for quality documentation generation. Target acquisition archetype: specialized flange fabricators with captive heat treatment and NDT capabilities in Gujarat or Maharashtra. Watch nickel alloy input cost spreads as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Melting | Captive supply of high-nickel semifinished products secures margin visibility against LME volatility. |
| Dual Certification Investment (BIS and GB) | Simultaneous compliance with India's pressure vessel rules and China's SAMR standards opens cross-border procurement. |
| Automation of Forging Documentation | Robotic grinding and CNC machining accelerate customer audit acceptance for Japanese LNG carrier specifications. |
| Framework Agreement Consolidation | Long-term offtake contracts with BHP and Rio Tinto displace spot purchasing through Perth and Brisbane hubs. |
| Predictive Maintenance Service Bundling | Blockchain-enabled material certification with IoT sensor monitoring creates recurring revenue attachment to flange assets. |
Research Methodology
Coverage spans India, China, Japan, Australia, and South Korea, with primary inputs from each market's forging clusters and end-use procurement centers. Primary interviews with EPC contractor procurement directors, refinery maintenance managers, shipyard specification engineers, and foundry quality directors combined with secondary validation from customs trade data, BIS certification registries, JIS standards documentation, and SAMR pressure equipment filings. Bottom-up unit demand modeling triangulated against top-down alloy consumption estimates.
Rate-of-change decomposition separates volume growth from alloy grade mix shift and price-level effects across the projection horizon. Segmentation dimensions include material type, connection configuration, pressure class rating, and industry application. CAGRs derived from project pipeline analysis for refinery, LNG terminal, and power generation investments, cross-referenced with flange content-per-unit estimates for high-pressure processing lines. Nickel alloy price assumptions and certification timeline compression effects inform margin trajectory modeling.
Regulatory enforcement variance, nickel alloy input cost volatility, and EPC contractor procurement consolidation are the dominant revision risks to forecast assumptions. Material deviation in SAMR traceability mandate timing, BIS laboratory capacity constraints, or framework agreement pricing terms warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Decorative Tiles Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
China Marble Market
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
Architectural Membrane Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Indonesia Cement Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
Modular Commercial Building System Market
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
Elastomeric Expansion Joint Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Concrete Repair Product Market
Building & Construction Materials
Composite Slate Roofing Market