
 Tile Grout Market | 2026-2036
Tile Grout Market Size, Share, and Industry Trends Forecast 2026-2036
Tile Grout Market Analysis
Aftermarket service revenue from grout restoration and resealing is rewriting margin capture across the value chain. Sika AG leverages its construction chemicals footprint to anchor specification-grade epoxy systems in commercial projects. MAPEI S.p.A. competes through vertical integration into raw material sourcing for cement-based blends. Laticrete International Inc. specializes in high-performance polymer-modified formulations for demanding wet-area applications.
Tile grout comprises a filler material—typically Portland cement, sand, and water for standard formulations, or resin binders exceeding 95% solids for epoxy variants—engineered to fill joints between ceramic, porcelain, or natural stone tiles while providing structural stability and moisture resistance. Its primary commercial purpose centers on preventing substrate water intrusion and accommodating thermal expansion in installed tile assemblies. Epoxy grout commands premium positioning in industrial and swimming pool applications where chemical resistance and zero absorption are mandatory. Cement-based products sustain volume leadership across residential channels due to installer familiarity and lower material cost. Polymer-modified segments are gaining fastest in commercial specifications where modified flexibility standards reduce callback risk.
FDA oversight of antimicrobial additive claims, EPA VOC emission limits under architectural coatings rules, and ISO 13007 classification of ceramic tile grouts collectively shape product formulation and market access requirements. REACH substance restrictions in Europe further constrain certain biocide chemistries, pushing manufacturers toward inorganic antimicrobial alternatives. Stakeholders must monitor evolving state-level VOC thresholds in California and New York alongside tightening performance classifications in multi-jurisdictional specification standards.
Market Dynamics
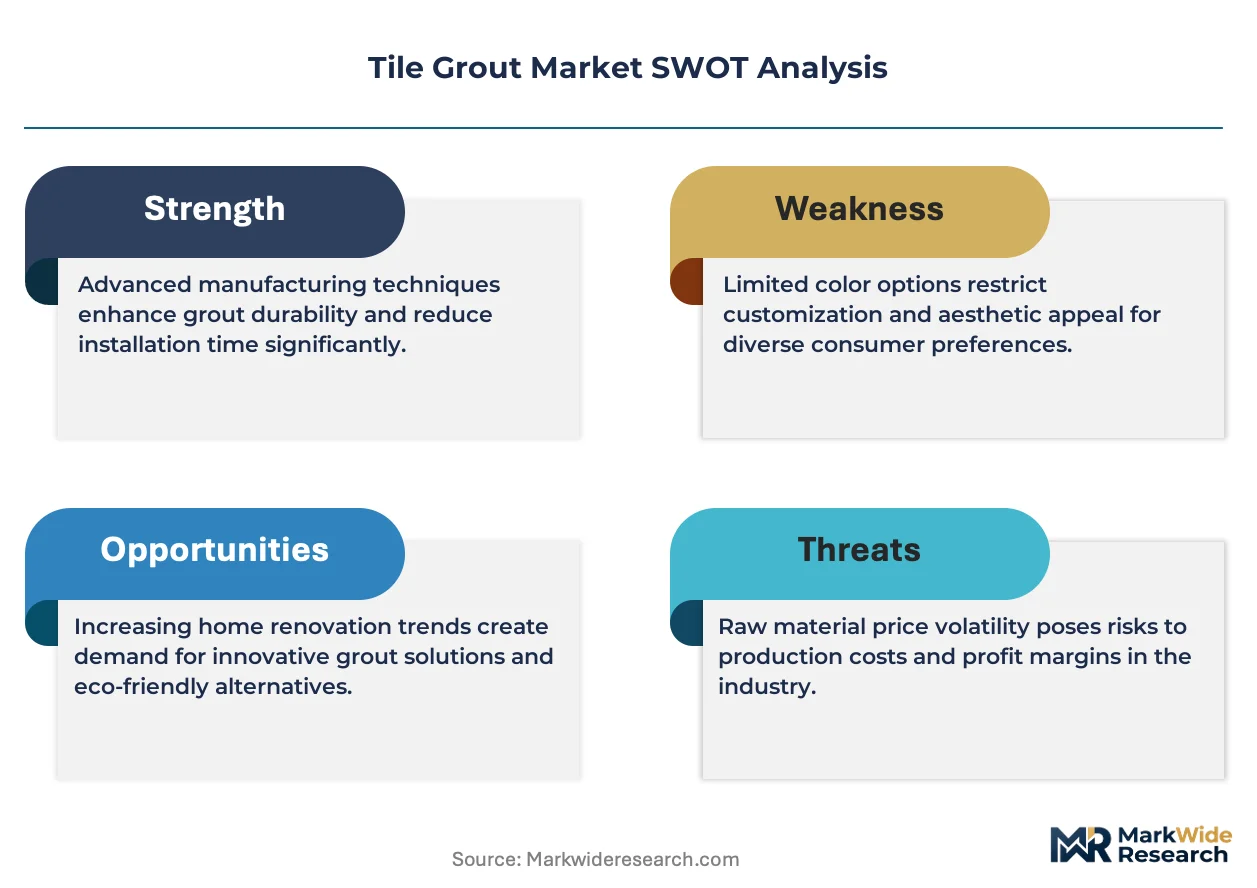
Polymer-modified grout formulations are capturing specification share from conventional cement-based products as building codes tighten flexibility and crack-resistance requirements across residential and commercial construction channels.
Growth Catalysts
- LEED Certification Mandates:North American commercial developers specify low-VOC, antimicrobial grout systems to secure green building points and meet tenant sustainability requirements.
- Epoxy Resin Technology:Industrial facilities and aquatic centers adopt 95%+ solids epoxy grout for zero-absorption performance in chemical-exposure environments.
- China Coastal Manufacturing:Guangdong and Zhejiang provinces drive volume through accelerated tile installation rates in high-rise residential and hospitality construction.
Market Restraints
- Portland Cement Price Volatility:Energy-intensive clinker production exposes formulators to input cost swings that compress margin on economy-grade cementitious products.
- Biocide Supply Concentration:REACH substance restrictions in Europe constrain certain organic antimicrobial chemistries, forcing reliance on a narrow supplier base for inorganic alternatives.
- Installer Skill Limitations:Epoxy grout application demands precise timing and surface preparation that exceeds the capability of generalist tilers, restricting premium product penetration.
Strategic Opportunities
- Grout Restoration Services:Aftermarket resealing and color-matching maintenance contracts capture recurring revenue from aging commercial and institutional tile installations.
- Antimicrobial Additive Convergence:Silver-ion and copper-based inorganic biocides integrate with polymer-modified matrices to satisfy FDA and EPA dual-claim requirements.
- Digital Specification Platforms:Architects and contractors source certified products through BIM-integrated procurement channels that filter by performance classification and compliance documentation.
Industry Challenges
- ISO 13007 Certification Timelines:Multi-jurisdictional testing protocols delay product launches as manufacturers sequence classification submissions across regional accreditation bodies.
- Skilled Applicator Shortages:Specialized epoxy and urethane grout installation training programs lag demand growth, constraining premium segment volume expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tile Grout Market |
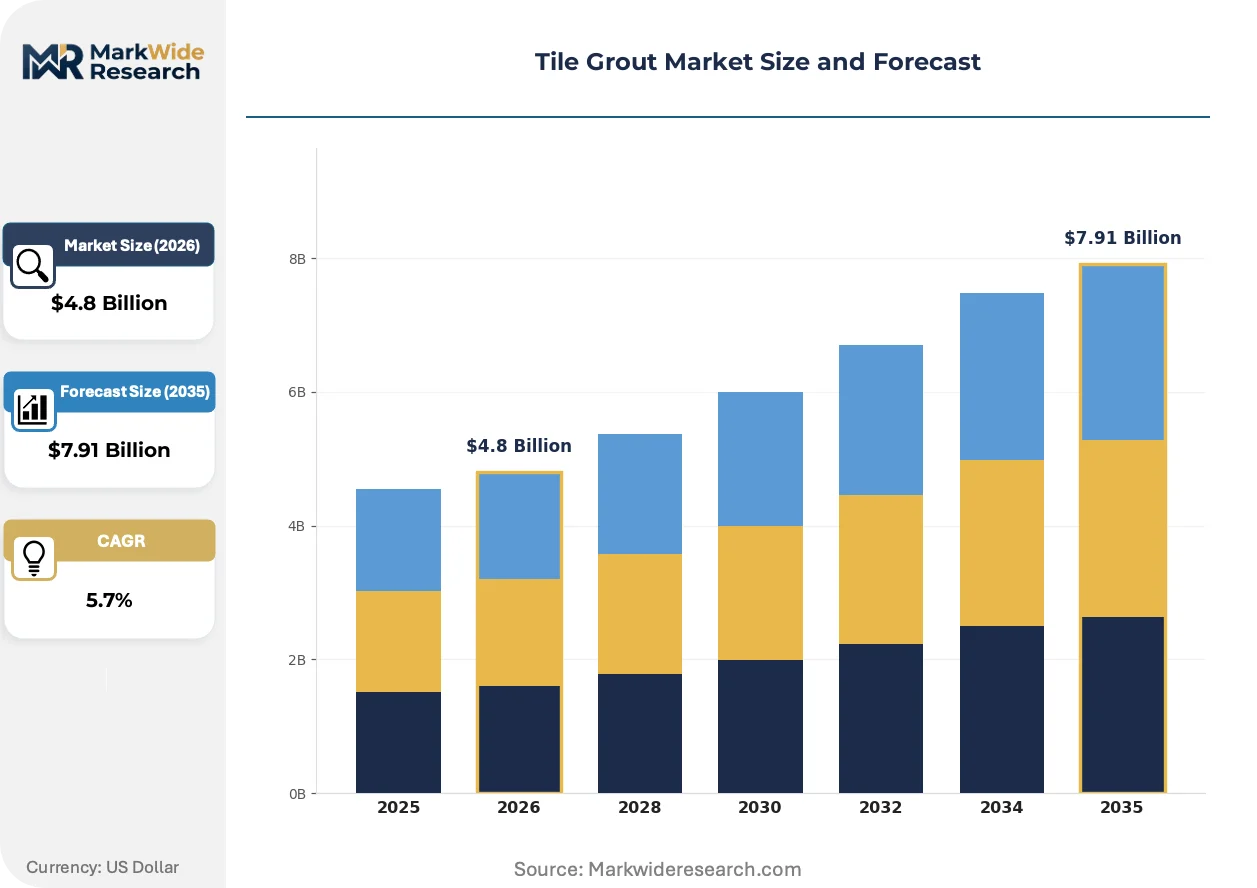
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement-based, Epoxy, Furan, Polymer Modified Application: Residential, Commercial, Industrial, Swimming Pools End User: Contractors, Retailers, DIY Enthusiasts, Architects Distribution Channel: Online, Specialty Stores, Home Improvement Centers, Wholesale |
| Companies Covered | Henkel AG & Co. KGaA, Ardex Group, Sika AG, RPM International, Laticrete International Inc., Saint-Gobain Group, BASF, Arkema Group, MAPEI S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tile Grout Market Emerging Trajectories
Formulation chemistry, regulatory compliance architecture, and procurement digitization are converging to compress product lifecycles and elevate performance thresholds across the tile grout value chain.
Pre-mixed, ready-to-use polymer grout is collapsing the traditional site-mixing workflow that has dominated residential installation for decades. Large-format tile contractors in the United States and Germany specify factory-blended consistency to eliminate batch-to-batch variability and reduce callback rates. This shift compresses demand for bagged cementitious powder at the premium residential tier while expanding margin capture through value-added formulation services.
REACH substance restrictions are eliminating specific isothiazolinone biocides from European grout formulations, forcing manufacturers to reformulate with inorganic antimicrobial alternatives. ECHA's evolving candidate list creates continuous compliance overhead as new substances face authorization requirements. Formulators with captive inorganic additive capabilities secure specification advantages in healthcare and food-processing verticals where antimicrobial claims face heightened scrutiny.
Building information modeling platforms are embedding grout performance data into architectural specification workflows, displacing traditional distributor-driven product selection. Contractors in China's tier-one cities filter procurement options by ISO 13007 classification, VOC emission thresholds, and LEED contribution points before issuing purchase orders. This digitization concentrates specification influence among manufacturers with comprehensive certification documentation and compresses spot-market purchasing for undifferentiated commodity grades.
Tile Grout Market Segmentation
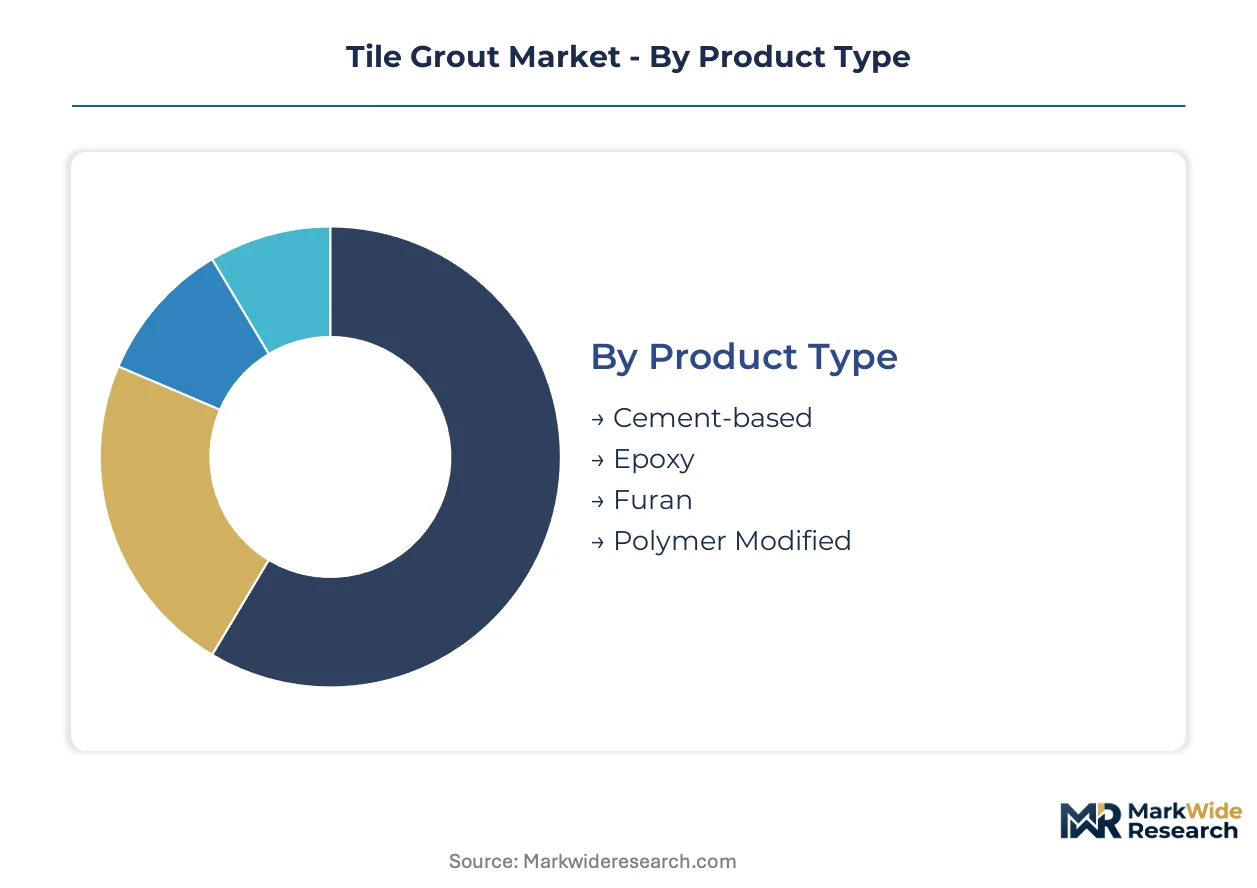
Tile grout segmentation tracks how formulation chemistry, installation setting, and procurement channel each reshape margin structures and specification influence. Understanding these divides reveals where technology premiums command pricing power versus where commodity competition erodes returns.
Product Type:
Cost tier separates the four product categories, with material composition and labor skill requirements driving sharp price stratification from economy-grade cement to premium epoxy systems.
- Cement-based:Portland cement, sand, and water formulations dominate residential renovation volume due to installer familiarity and material accessibility. Demand concentrates in single-family housing across the United States and Germany where cost-sensitive homeowners prioritize budget over performance specifications. Portland cement price volatility compresses margin on economy-grade products.
- Epoxy:Resin binders exceeding 95% solids deliver zero-absorption performance mandatory for industrial facilities and aquatic centers. Specification share is climbing fastest in chemical-exposure environments where ISO 13007 classifications require crack resistance and thermal stability. Epoxy application demands precise timing that exceeds generalist tiler capability.
- Furan:Carbon-filled thermoset resins engineered for extreme chemical resistance in industrial process environments. Demand localizes to pharmaceutical manufacturing and heavy chemical processing installations.
- Polymer Modified:Latex or acrylic additives blended into cementitious matrices enhance flexibility and bond strength. Adoption accelerates in commercial wet-area specifications where modified standards reduce callback liability.
Cement-based grout commands the established base. The steepest expansion runs through polymer-modified formulations.
Application:
Volume scale and specification intensity diverge sharply across these four settings, with commercial and industrial projects driving premium product penetration while residential channels sustain commodity throughput.
- Residential:Single-family and multi-family housing installations generate the highest unit volume through renovation and new construction activity. Demand clusters in China's coastal provinces and U.S. Sun Belt metros where tile installation rates outpace other regions. Homeowner preference for pre-mixed polymer products is collapsing traditional site-mixing workflows.
- Commercial:Office, retail, and hospitality specifications prioritize LEED certification compliance and antimicrobial performance. North American developers specify low-VOC systems to secure green building points and meet tenant sustainability requirements.
- Industrial:Manufacturing and processing facilities mandate chemical-resistant epoxy or furan systems. FDA oversight of antimicrobial claims shapes product selection in food-processing verticals.
- Swimming Pools:Aquatic centers and residential pools require zero-absorption grout to prevent water intrusion and chlorine degradation. Specification concentrates in institutional recreation facilities.
Residential channels absorb the highest unit volume. Industrial applications generate the steepest value-per-square-meter returns.
End User:
Customer type determines whether procurement flows through specification influence, retail availability, or direct contractor supply agreements.
- Contractors:Professional installers specify products based on ISO 13007 classification and callback risk profiles. Large-format tile specialists in Germany and the United States increasingly demand factory-blended consistency.
- Retailers:Distributors and home improvement chains stock bagged cementitious powders for walk-in DIY demand. Inventory decisions track regional construction activity and seasonal renovation cycles.
- DIY Enthusiasts:Homeowner self-installers favor pre-mixed, ready-to-use formulations that eliminate batch mixing errors. Digital platforms and home improvement centers capture this segment.
- Architects:Specification professionals filter procurement through BIM-integrated channels that prioritize certification documentation and LEED contribution points. Building information modeling platforms embed grout performance data into design workflows.
Contractors anchor volume procurement. Architects concentrate specification influence for premium-tier products.
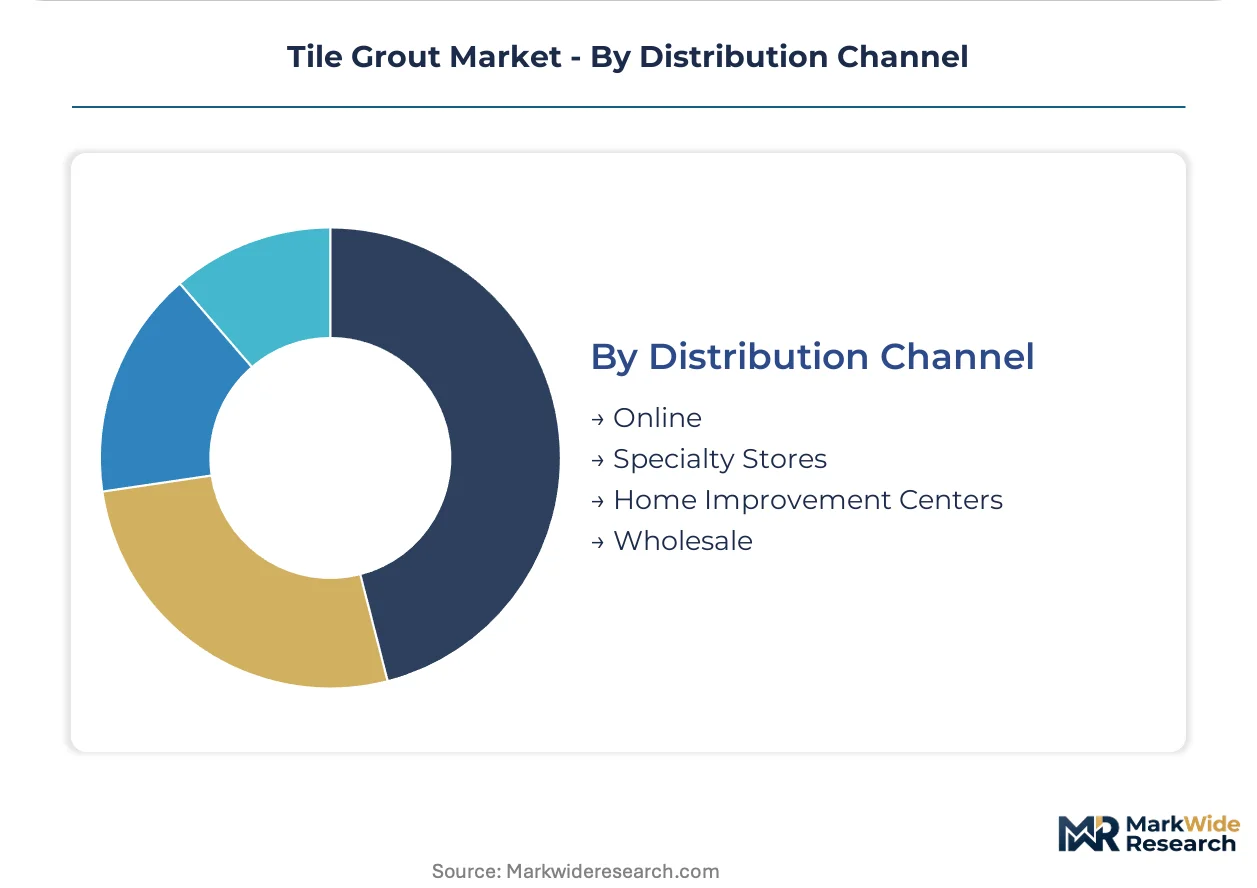
Distribution Channel:
Supply chain configuration separates digital-first procurement from traditional physical retail, with certification documentation requirements favoring platforms with comprehensive compliance libraries.
- Online:E-commerce and digital specification platforms enable filtering by VOC thresholds, antimicrobial claims, and performance classification. Procurement digitization concentrates influence among manufacturers with complete certification documentation.
- Specialty Stores:Tile and flooring distributors serve professional contractors with technical support and color-matching services. These outlets capture specification-grade epoxy and polymer-modified volume.
- Home Improvement Centers:Big-box retailers stock economy-grade cementitious products for residential DIY and small contractor demand. Seasonal inventory cycles track renovation activity patterns.
- Wholesale:Direct supply agreements with large construction firms and national contractor networks. Volume pricing and just-in-time delivery secure commercial project specifications.
Home improvement centers move the highest unit volume. Online channels are climbing fastest for specification-grade procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity among residential renovators in Germany and the United States contrasts sharply with specification-driven procurement in China's coastal manufacturing zones, where performance premiums dominate commercial project economics.
United States
Single-family housing renovation across Sun Belt metros sustains cement-based grout volume, while LEED-certified commercial developers in California and New York specify low-VOC polymer systems. EPA architectural coatings rules enforce tightening VOC emission thresholds. Installation rates concentrate in Dallas-Fort Worth and Phoenix where large-format tile adoption accelerates factory-blended procurement.
Germany
Technical tilers in Bavaria and North Rhine-Westphalia demand pre-mixed polymer formulations to eliminate batch variability on precision residential projects. REACH compliance through ECHA constrains isothiazolinone biocide use, forcing reformulation toward inorganic antimicrobials. Stuttgart and Munich anchor specification-grade epoxy penetration in commercial wet-area applications.
China
Guangdong and Zhejiang provinces drive absolute volume through accelerated high-rise residential and hospitality construction. NMPA oversight of antimicrobial additive claims shapes product registration requirements. Shenzhen and Hangzhou manufacturing clusters concentrate tile installation activity where polymer-modified specifications outpace conventional cement adoption.
India
Urban residential construction in Maharashtra and Gujarat generates cementitious grout demand from cost-sensitive contractor networks. BIS certification requirements for construction chemicals elevate product entry barriers. Mumbai and Ahmedabad construction corridors absorb volume from mid-rise residential developments where site-mixing persists.
United Arab Emirates
Hospitality and commercial megaprojects in Dubai specify premium epoxy systems for zero-absorption performance in aquatic and spa environments. MOHAP registration requirements govern antimicrobial product claims in healthcare verticals. Dubai Design District and Abu Dhabi Central Business District concentrate specification activity where LEED-equivalent standards drive procurement decisions.
Tile Grout Market Vendor Landscape
Construction-chemical conglomerates and specialty adhesive formulators split the market along specification-grade versus economy-grade fault lines. The vendor base concentrates among European and North American entities with captive raw material positions, alongside Asian manufacturers leveraging coastal manufacturing density. Three archetypes dominate: diversified construction-chemical majors, vertically integrated tile-system specialists, and regional powder-blend suppliers. Capacity expansion in polymer-modified formulations and backward integration into resin production represent the primary competitive vectors.
Within the diversified construction-chemical tier, Sika AG and BASF occupy positions anchored by broad construction chemicals portfolios. MAPEI S.p.A. exemplifies the vertically integrated specialist archetype with in-house control over cementitious raw material sourcing. Laticrete International Inc. represents the specification-focused formulator segment targeting high-performance wet-area applications. These three entities collectively illustrate how geographic origin and corporate structure shape strategic positioning across premium and mid-market tiers.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Ardex Group |
| Sika AG |
| RPM International |
| Laticrete International Inc. |
| Saint-Gobain Group |
| BASF |
| Arkema Group |
| MAPEI S.p.A. |
| Others |
Supply Flow & Price Mechanics
Portland cement price volatility determines both tiered pricing spreads across economy-to-premium formulations and the geographic clustering of manufacturing capacity around clinker production sites. Energy-intensive clinker kilns in China and Germany anchor supply positioning while exposing formulators to input cost swings that compress margins on commodity-grade cementitious products.
Pricing Analysis
Grout restoration and resealing service contracts drive lifetime value capture beyond initial material sales. Three-tier pricing structure across premium, standard, and economy levels separates epoxy systems from polymer-modified formulations from conventional cement-based powders. Cost compression in economy-grade segments is intensifying because Portland cement energy inputs fluctuate with natural gas pricing. Residential DIY buyers exhibit highest price sensitivity while commercial developers specifying LEED-certified projects accept premium positioning.
Supply Chain Analysis
Tariff exposure between the United States and China dominates raw material sourcing decisions for antimicrobial additive suppliers. Manufacturing gravity centers on Guangdong and Zhejiang provinces in China, alongside North Rhine-Westphalia in Germany and Texas in the United States. Formulation chemistry draws from epoxy resin feedstocks, Portland cement clinker, and inorganic biocide additives. Single-source vulnerability concentrates in isothiazolinone biocide alternatives following REACH restrictions. Distribution runs through specialty tile distributors for specification-grade products and home improvement centers for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential renovation cycles in the United States, Germany, and China position this market for cyclical recovery as housing turnover and mortgage rate resets unlock deferred maintenance spending.
For Market Incumbents: Harden specification influence by embedding grout performance data into BIM platforms that architects filter by ISO 13007 classification and LEED contribution points. Deepen backward integration into inorganic antimicrobial additive production to secure healthcare and food-processing verticals against REACH-driven supply disruption. Channel control through exclusive distributor relationships defends margin position against private-label encroachment in economy tiers. For New Entrants and Emerging Players: Build out grout restoration and color-matching service capabilities to capture recurring aftermarket revenue from aging commercial installations in Germany and the United States. The most penetrable white space sits in pre-mixed polymer formulations for large-format tile contractors seeking batch consistency guarantees. Digital specification platforms offer direct go-to-market access that bypasses established distributor gatekeepers. For Investors and Strategic Acquirers: REACH substance authorization timelines reshapes the acquisition landscape by elevating formulators with captive inorganic biocide capabilities above competitors facing reformulation overhead. Long-term viability favors vertically integrated specialists with upstream cementitious raw material control and downstream specification channel access. The signal to watch is ECHA candidate list expansion pace as a proxy for compliance cost acceleration across European market exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive epoxy feedstock supply secures margin against petrochemical volatility in industrial-grade formulations. |
| BIM Platform Certification Embedding | Architect specification workflows filter procurement by ISO 13007 class and VOC thresholds before distributor engagement. |
| Grout Restoration Service Buildout | Aftermarket resealing contracts generate recurring revenue from aging hospitality and healthcare installations. |
| Inorganic Antimicrobial Additive Capacity | Silver-ion and copper-based biocide production satisfies FDA and EPA dual-claim requirements in food-processing verticals. |
| Pre-Mixed Polymer Formulation Expansion | Factory-blended consistency eliminates batch variability callbacks from large-format tile contractors in Germany and the United States. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and construction chemical industry association reports. Interviews with technical tilers, commercial contractors, distributor procurement managers, and specification architects informed demand-side dynamics. Secondary validation drew from ECHA substance restriction notices, EPA architectural coatings rules, ISO 13007 classification documentation, and SEC construction chemical segment disclosures. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry tiers.
Forecast inputs include residential renovation permit data, commercial construction square footage pipelines, and tile installation rate indices across coastal Chinese provinces and Sun Belt United States metros. Segmentation dimensions span product type, application setting, end-user archetype, and procurement channel. CAGRs derive from regression analysis against construction activity leading indicators and specification standard adoption curves. Portland cement price indices and REACH authorization timelines feed sensitivity testing.
Stress conditions across clinker energy costs, biocide supply availability, and installer skill shortage severity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and specification platform adoption velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Glass Curtain Wall Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Global Concrete Surface Retarders Market
Building & Construction Materials
Sheet Metal Market
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
Household Mosaic Tiles Market