
 Europe Faucet Market | 2026-2036
Europe Faucet Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Faucet Market Foresight
Subscription-based filter replacement and connected water-usage monitoring is consolidating around fixture ecosystems that extend beyond the point of sale. Grohe leverages its digital platform architecture to anchor recurring revenue streams across installed bases. Hansgrohe competes through R&D intensity in thermostatic cartridge engineering. Ideal Standard dominates commercial specification channels across the United Kingdom and Nordic markets.
A faucet is a valved plumbing fixture that controls water discharge through a sealed cartridge mechanism, typically rated for pressure tolerance between 0.5 and 10 bar and manufactured via hot-forging of brass billets followed by CNC machining and surface plating. Its primary purpose is to regulate flow volume, temperature mixing, and water conservation in residential, commercial, and institutional buildings. Single-handle configurations lead volume in residential renovation owing to ergonomic preference and simpler installation, while pull-down variants capture expanding share in kitchen applications where task flexibility matters. Brass material grades command the dominant margin pool due to durability certification requirements and finish longevity, though stainless steel gains specification in healthcare and food-service settings where corrosion resistance is non-negotiable.
CE marking under the EU Construction Products Regulation and national plumbing codes enforced by Germany's DVGW and France's ACS certification shape product compliance burdens and time-to-market for new entrants. The EU Ecodesign Directive and impending tighter limits on maximum flow rates are forcing cartridge redesigns and aerator investments across manufacturing footprints. Stakeholders must monitor how the EU Green Deal's building renovation wave redirects procurement specifications toward water-efficiency labeling and embedded-carbon disclosure requirements.
Market Dynamics
The EU Green Deal's building renovation wave is compressing product lifecycles and redirecting procurement specifications toward water-efficiency labeling and embedded-carbon disclosure requirements across Western European markets.
Growth Catalysts
- EU Ecodesign Directive:Tighter maximum flow rate limits are forcing cartridge redesigns and aerator investments, expanding the addressable base for premium water-efficient fixtures in residential renovation channels.
- Brass billet supply concentration:Hot-forging capacity clustering in Germany and Italy is shortening lead times for CE-marked products serving the DACH renovation market.
- Smart cartridge integration:Thermostatic and digital mixing technologies are capturing specification share in multi-unit residential developments across France and the Nordic region.
Market Restraints
- Low-lead brass formulation mandates:ECHA restrictions on lead content in drinking water contact materials are elevating raw material costs and compressing margin pools for mid-tier manufacturers.
- Surface plating supply bottlenecks:Chromium finishing capacity concentration in Southern Europe is creating vulnerability to energy price volatility and environmental compliance delays.
- Technical limitation in sensor reliability:Capacitive and infrared activation systems face durability challenges in hard-water environments common across Central European municipal supplies.
Strategic Opportunities
- Poland and Romania residential construction:Underpenetrated premium fixture penetration in these markets offers whitespace for water-efficient specification products meeting EU Green Deal renovation targets.
- Healthcare and food-service stainless steel:Corrosion-resistant specification demand is expanding beyond traditional brass-dominated channels into institutional procurement frameworks.
- Subscription filter replacement:Connected water-usage monitoring platforms are creating recurring revenue streams that extend manufacturer relationships beyond initial point-of-sale transactions.
Industry Challenges
- DVGW and ACS certification timelines:Germany's technical and scientific association and France's sanitary conformity certification impose multi-month approval delays that compress product launch windows.
- Thermostatic cartridge engineering talent:Precision machining and ceramic disc engineering expertise scarcity constrains R&D throughput for temperature-control innovation.
- Legacy plumbing infrastructure compatibility:Pressure tolerance mismatches between modern 0.5-10 bar rated cartridges and aging municipal distribution systems in Southern European building stock create installation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Faucet Market |
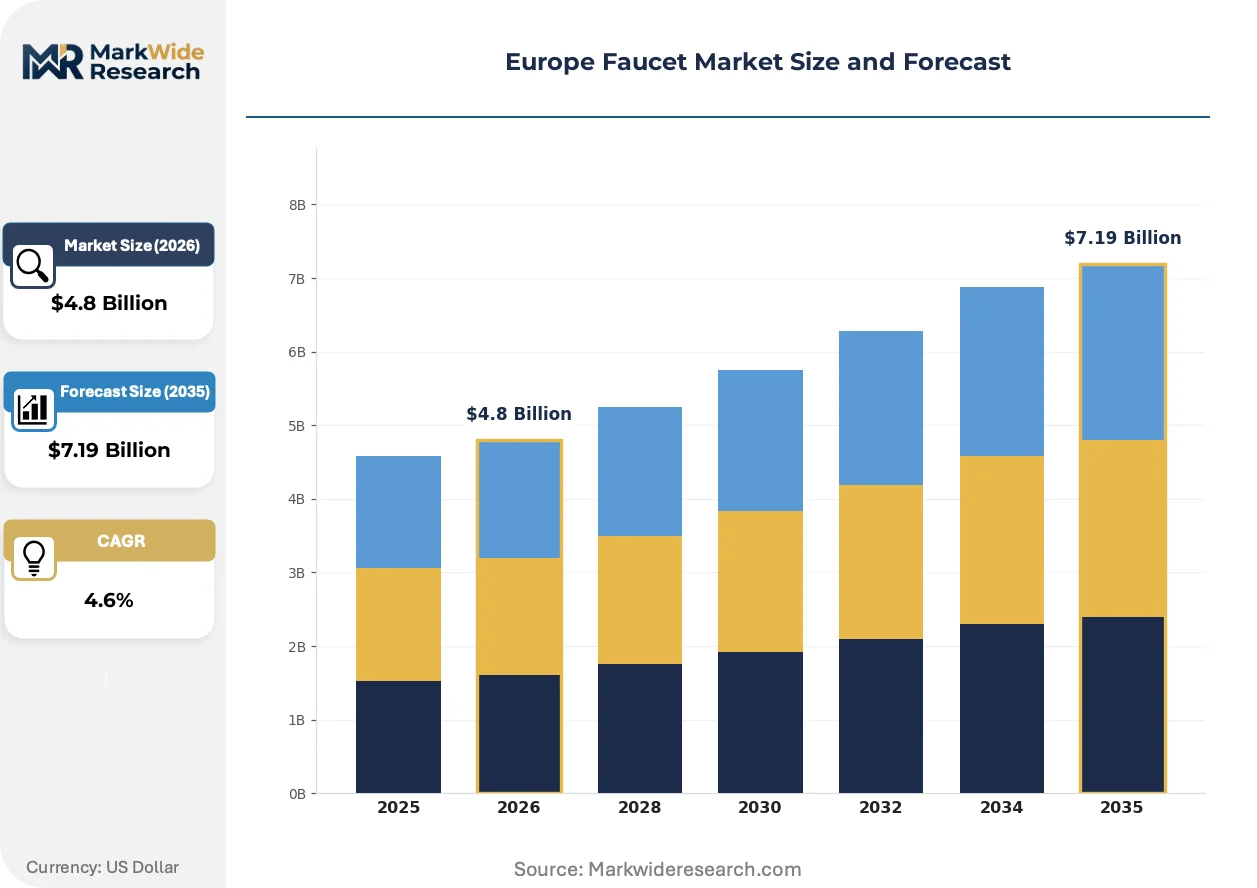
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Handle, Double-Handle, Pull-Down, Wall-Mounted Material: Brass, Stainless Steel, Plastic, Bronze Design Style: Modern, Traditional, Vintage, Contemporary Application: Residential, Commercial, Hospitality, Industrial |
| Companies Covered | Ideal Standard, Franke, Grohe, Dornbracht, Blanco, Hansgrohe, Villeroy & Boch, Damixa, Roca, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Faucet Market Shifts & Advancements
Digital platform architectures and connected fixture ecosystems are reshaping how manufacturers capture value beyond hardware sales, while regulatory pressure on water efficiency accelerates material and cartridge engineering transitions.
Touchless sensor activation is electrifying kitchen and commercial restroom specification channels. Infrared and capacitive proximity detection systems eliminate physical contact points in food-service and healthcare settings. Facility managers across German hospital networks and French hospitality chains are specifying these systems at accelerating rates. The technology is electrifying competitive positioning by enabling outcome-based service contracts that bundle hardware with predictive maintenance and usage analytics.
REACH and the EU Ecodesign Directive are tightening the regulatory screw on material composition and flow performance. Lead-content restrictions and impending maximum flow rate reductions are forcing reformulation of brass billets and complete aerator redesigns across manufacturing footprints. German and Italian producers with in-house metallurgy capabilities are responding fastest, while importers face extended retesting and recertification cycles that compress their effective selling seasons.
Specification buyers are consolidating vendor relationships around full-bathroom ecosystem providers rather than discrete fixture procurement. Architects and commercial developers in the United Kingdom and Benelux markets are awarding single-source contracts covering faucets, showers, and connected water management systems. This behavior is compressing the specification channel for standalone faucet specialists and elevating platform-integrated manufacturers who can deliver unified digital interfaces across fixture categories.
Europe Faucet Market Segmentation
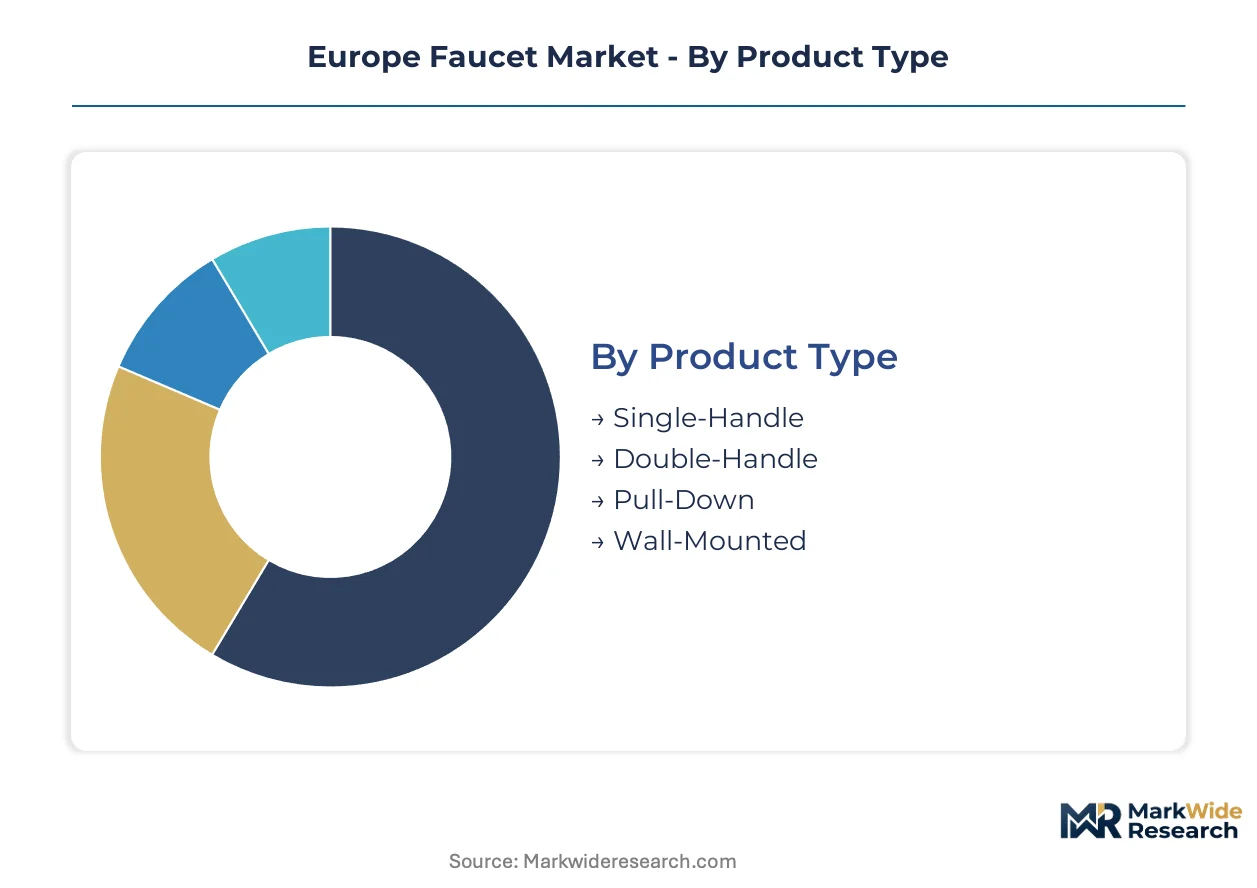
Fixture specification in Europe diverges sharply across renovation versus new-build channels, with material certification and water-efficiency ratings functioning as primary screening criteria for procurement teams. Understanding how product type, material composition, and end-use application intersect reveals where margin pools concentrate and where compliance burdens create competitive moats.
Product Type:
Installation complexity and ergonomic preference drive contractor and homeowner selection, with single-handle configurations dominating residential renovation due to simpler retrofit requirements.
- Single-Handle:Ceramic disc cartridges enable one-handed temperature and flow control through lateral and vertical lever movement. German and French residential renovation channels specify these for aging-in-place adaptations and kitchen efficiency upgrades where space constraints limit handle clearance.
- Pull-Down:Retractable hose systems with magnetic or weight-return docking deliver task-flexible spray patterns for food preparation and sink basin coverage. Nordic and Benelux kitchen specification is tilting toward these variants as open-plan living integrates cooking and entertaining zones.
- Double-Handle:Separate hot and cold controls suit heritage building restorations across Italy and Spain where preservation codes mandate period-appropriate aesthetics.
- Wall-Mounted:Concealed valve bodies enable minimalist counter designs in premium residential and boutique hospitality settings across Switzerland and Austria.
Volume sits with Single-Handle; growth tilts toward Pull-Down.
Material:
Regulatory pressure on lead content and corrosion resistance is restructuring raw material procurement, with certification-grade brass commanding specification premiums in drinking water contact applications.
- Brass:Hot-forged copper-zinc alloys with lead content below ECHA thresholds dominate CE-marked production. Italian and German manufacturers with in-house metallurgy capabilities capture margin premiums through DVGW and ACS certification bundling.
- Stainless Steel:AISI 304 and 316 grades deliver corrosion immunity in healthcare sterilization sinks and commercial kitchen prep stations. French hospital networks and German food-processing facilities specify these for regulatory compliance with surface hygiene protocols.
- Plastic:Glass-reinforced polymer bodies serve cost-sensitive temporary installations and utility sinks where pressure ratings and finish longevity are secondary considerations.
- Bronze:Copper-tin formulations with antimicrobial surface properties find niche specification in wellness and spa applications across Alpine resort developments.
Volume concentrates in Brass; Stainless Steel is climbing the fastest.
Design Style:
Architectural specification trends are fragmenting aesthetic procurement, with project type and building era dictating style alignment rather than universal preference hierarchies.
- Modern:Geometric forms with matte black or brushed nickel finishes align with contemporary residential developments across Dutch and Danish urban cores.
- Traditional:Cross-handle and porcelain-accented designs serve period property renovations in British and Belgian conservation districts.
- Vintage:Bridge-spout and claw-foot adjacent styling supports hospitality theming in Portuguese and Greek boutique hotel conversions.
- Contemporary:Softened edges and mixed-metal finishes bridge transitional interiors in Polish and Czech residential construction upgrading from post-socialist building stock.
Modern styling captures specification volume; Contemporary is gaining share fastest in emerging European markets.
Application:
End-use procurement frameworks diverge in decision-maker identity, technical specification depth, and service contract expectations.
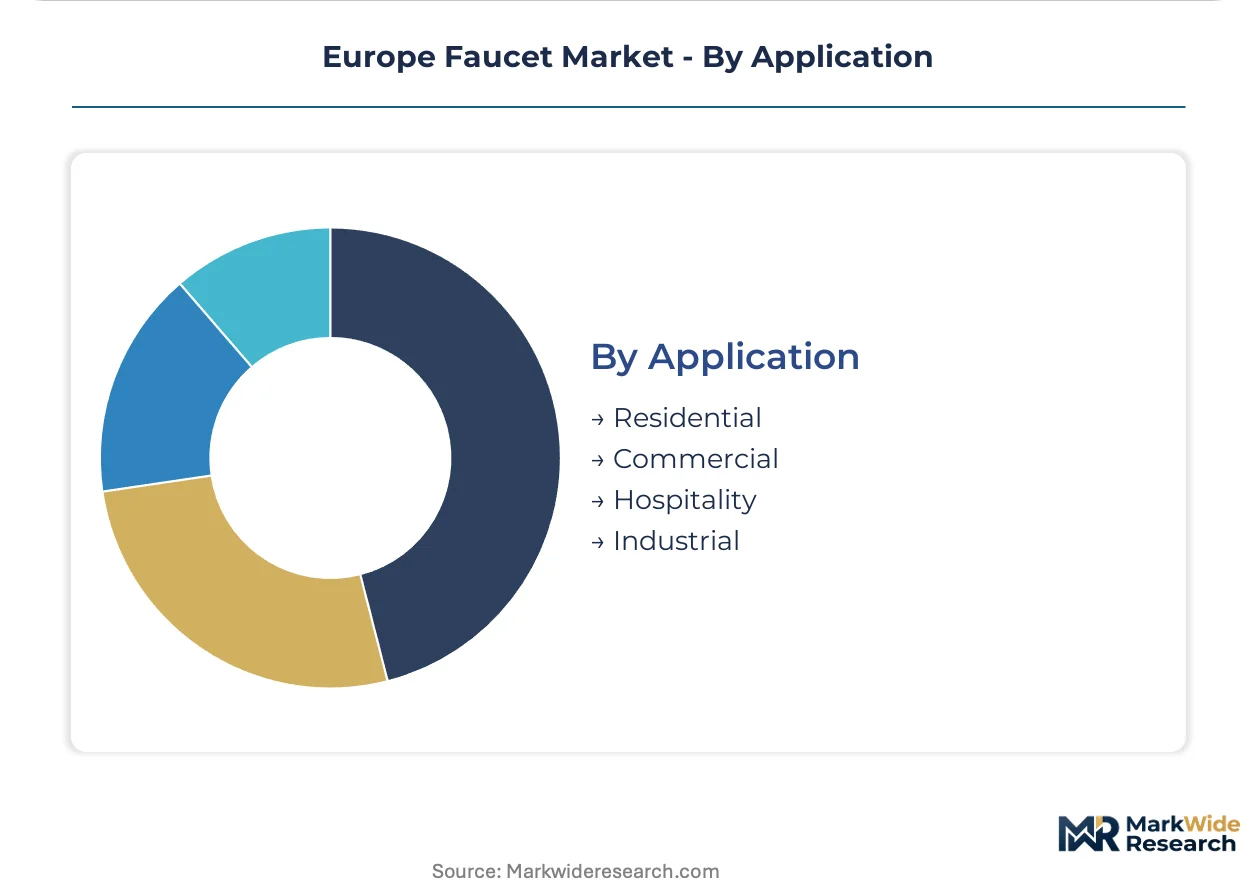
- Residential:Individual homeowners and renovation contractors prioritize installation simplicity and finish coordination with sanitary ware. German and French replacement cycles accelerate under EU Green Deal renovation financing.
- Commercial:Facility managers and procurement consortiums demand durability certification, spare parts availability, and multi-site service agreements. British office and retail fit-out channels concentrate specification volume.
- Hospitality:Brand standards teams at hotel groups and restaurant chains mandate design consistency across properties with connected water management integration for usage monitoring.
- Industrial:Process water and washdown applications in manufacturing and logistics facilities specify heavy-duty brass or stainless steel bodies with high-flow capacity and vandal-resistant construction.
Residential channels absorb volume; Hospitality delivers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors European faucet manufacturing, with hot-forging capacity clustering around Dortmund and Essen serving DACH renovation demand. This concentration shortens lead times for CE-marked products while compressing margin pools for distant competitors.
Germany
Residential renovation cycles accelerate under EU Green Deal financing instruments targeting building stock modernization. DVGW certification mandates impose multi-month approval timelines that favor established domestic producers with in-house testing infrastructure. The Stuttgart-Baden-Württemberg precision engineering cluster concentrates thermostatic cartridge R&D and ceramic disc machining expertise.
France
ACS sanitary conformity requirements redirect procurement toward water-efficient fixtures in multi-unit residential developments across Île-de-France. Ecodesign Directive flow-rate limits force aerator redesigns among importers facing extended recertification cycles. Lyon-based hospitality specification channels drive touchless sensor adoption in hotel and restaurant fit-outs.
Italy
Heritage building restoration codes in Tuscany and Veneto sustain demand for period-appropriate double-handle configurations. Brass billet hot-forging capacity concentrates in Lombardy, enabling rapid turnaround on custom finishes for premium residential channels. ECHA lead-content restrictions elevate raw material costs for mid-tier manufacturers without metallurgy capabilities.
United Kingdom
Commercial office and retail fit-out channels concentrate specification volume in London and Southeast England. Ideal Standard dominates these procurement frameworks through bundled bathroom ecosystem contracts. Building Regulations Part G water efficiency requirements tighten maximum flow specifications for new construction and major renovations.
Poland
Post-socialist building stock modernization creates whitespace for premium water-efficient fixtures meeting EU renovation targets. Warsaw and Kraków residential construction channels show underpenetrated smart cartridge penetration relative to Western European benchmarks. Domestic distributors are consolidating vendor relationships around full-ecosystem providers with connected water management platforms.
Europe Faucet Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where in-house metallurgy and forging capabilities separate premium specification winners from import-dependent challengers. The vendor base fragments across three strategic archetypes: integrated brass processors with captive hot-forging capacity, ecosystem platform providers bundling digital services, and stainless steel specialists targeting institutional corrosion-resistance requirements. M&A activity concentrates on connected water management platform acquisitions, while capacity expansion focuses on low-lead brass formulation retooling ahead of ECHA enforcement timelines.
Within the integrated brass processor tier, Grohe and Hansgrohe exemplify divergent competitive positioning through platform architecture versus R&D intensity. Grohe anchors recurring revenue streams through subscription-based filter replacement and digital ecosystem integration. Hansgrohe occupies a position defined by thermostatic cartridge engineering depth. Ideal Standard represents the ecosystem bundling archetype through commercial specification channel dominance across United Kingdom and Nordic markets.
| Leading Market Players |
|---|
| Ideal Standard |
| Franke |
| Grohe |
| Dornbracht |
| Blanco |
| Hansgrohe |
| Villeroy & Boch |
| Damixa |
| Roca |
| Others |
Supply & Pricing Matrix
Copper-zinc alloy billet indices cascade through European faucet manufacturing, compressing margin pools at mid-tier producers lacking in-house hot-forging capacity while amplifying pricing power for integrated brass processors serving DVGW and ACS certification channels.
Pricing Analysis
Margin tightening in mid-tier segments reflects ECHA lead-content reformulation costs and chromium plating supply bottlenecks. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification bundling and metallurgy capabilities. Price differentiation hinges on DVGW/ACS pre-approval status and captive forging capacity. Residential renovation contractors show highest price sensitivity; hospitality brand standards teams exhibit lowest.
Supply Chain Analysis
Single-source vulnerability sits with chromium finishing capacity clustering in Southern Europe. Hot-forging capacity concentrates in Germany, Italy, and Poland. Raw material dependencies span low-lead brass billets, ceramic disc cartridges, and nickel-chromium plating chemistry. Supply chain risk centers on energy price volatility affecting electroplating operations. Distribution runs through plumbing merchant networks and direct commercial specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brass billet hot-forging capacity scarcity props pricing power for integrated manufacturers, constraining volume expansion for import-dependent competitors across the EU Green Deal renovation wave.
For Market Incumbents: Extend platform ecosystem integration into subscription filter replacement and connected water-usage monitoring. Lock in specification channel control through bundled bathroom ecosystem contracts. Defend against stainless steel specialists encroaching on healthcare procurement by accelerating low-lead brass certification investments. For New Entrants and Emerging Players: Direct-to-contractor digital channels offer lowest-friction entry into Polish and Romanian residential construction whitespace. Target underpenetrated smart cartridge specification in Warsaw and Kraków multi-unit developments. Lead with water-efficiency labeling compliance as the procurement door-opener. For Investors and Strategic Acquirers: The window for entry favors connected water management platform acquisitions with recurring revenue architecture. Long-term viability rests on installed base monetization rather than transactional hardware margins. Watch ECHA enforcement timelines for low-lead brass as the margin compression inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Lead Brass Formulation Retooling | ECHA compliance deadlines force metallurgy capability investments ahead of enforcement windows. |
| Connected Platform Integration | Grohe's digital architecture demonstrates recurring revenue capture beyond point-of-sale transactions. |
| Healthcare Stainless Steel Expansion | French hospital networks specify corrosion-resistant fixtures for sterilization sink applications. |
| DACH Specification Channel Control | Ideal Standard's UK-Nordic ecosystem bundling locks out standalone faucet competitors. |
| Poland-Romania Distribution Buildout | Post-socialist building stock modernization creates whitespace for EU Green Deal-compliant entrants. |
Research Methodology
Trade publications, EU regulatory filings, and brass billet price benchmarks formed the secondary backbone. Primary interviews with plumbing merchant procurement directors, DVGW certification engineers, hospitality brand standards managers, and ceramic disc cartridge R&D heads validated demand assumptions. Bottom-up and top-down triangulation cross-checked volume estimates against customs data and renovation financing disbursement records.
Bottom-up modeling aggregated segment-level unit economics across product type, material grade, and end-use application dimensions. Top-down validation anchored total addressable market sizing against EU Green Deal building renovation targets and national plumbing code adoption rates. CAGRs derived from installed base replacement cycles and specification trend trajectories. Forecast inputs incorporated Ecodesign Directive flow-rate limit phase-ins and ECHA lead-content enforcement schedules.
The model holds under steady EU renovation financing commitment; deviation in energy price volatility or chromium plating capacity closures would shift margin distribution. Forecasts reflect assumptions about certification timeline stability and brass billet supply concentration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
Asia-Pacific Cross-Laminated Timber Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Artificial Wood Beams Market