
 US Residential Remodeling Market | 2026-2036
US Residential Remodeling Market Size, Share, and Industry Trends Forecast 2026-2036
US Residential Remodeling Market Insights
The widening spread between luxury whole-home gut renovations and cosmetic refresh projects is repositioning how contractors structure their service portfolios. Power Home Remodeling leverages direct-to-consumer marketing and in-house installation crews to dominate the replacement window and siding segments. D.R. Horton anchors its remodeling adjacent services through scale advantages tied to its new construction footprint. Lennar Corp. differentiates by bundling smart-home infrastructure into renovation packages that appeal to tech-forward homeowners.
US residential remodeling encompasses the structural alteration, modernization, and functional upgrade of existing single-family and multifamily dwellings, typically involving building permit filings, licensed trade coordination, and compliance with local energy codes. Kitchen renovation and bathroom remodeling command the largest share of homeowner spending, with basement finishing representing the fastest-growing category as remote-work permanence drives demand for dedicated home office square footage. Material selection stratifies across project tiers, with engineered wood and composite products capturing share from traditional lumber in mid-market renovations while natural stone and custom metalwork concentrate in luxury engagements.
EPA lead-safe certification requirements, OSHA fall-protection standards for residential construction, and local energy-efficiency codes collectively shape contractor compliance costs and homeowner project timelines. The Department of Energy's building performance benchmarks increasingly influence retrofit specifications, particularly for HVAC and insulation upgrades. Stakeholders must monitor how municipal zoning liberalization for accessory dwelling units reshapes room addition demand and contractor capacity allocation across metropolitan markets.
Market Dynamics
The aging housing stock across Sun Belt metros is compressing renovation cycles as millennial first-time buyers prioritize immediate functional upgrades over deferred maintenance, forcing contractors to restructure project pipelines around rapid-turnaround kitchen and bathroom packages.
Growth Catalysts
- EPA Lead Renovation, Repair and Painting Rule:Mandatory contractor certification has professionalized the trades, raising barrier to entry and protecting incumbent certified operators from price-based competition.
- Remote-work permanence:Dedicated home office construction is driving basement finishing demand, converting underutilized square footage into taxable living space.
- Engineered wood products:Moisture-resistant composites are expanding addressable project scope into previously unsuitable climate zones and applications.
Market Restraints
- Lumber input volatility:Framing and finish carpentry margins remain exposed to commodity price swings with limited pass-through mechanisms in fixed-bid contracts.
- Licensed trade concentration:Master electrician and plumber availability constraints in high-growth metros extend project timelines and inflate labor premiums.
- OSHA fall-protection standards:Residential roof work compliance adds equipment and training overhead that smaller contractors struggle to absorb.
Strategic Opportunities
- Accessory dwelling unit liberalization:Municipal zoning reforms in California and Texas are creating room addition demand that general contractors can capture through design-build integration.
- Smart-home infrastructure bundling:HVAC and electrical contractors can expand project scope by pre-wiring automation systems during major renovations.
- Infrared thermography:Building envelope diagnostic services are opening new revenue streams alongside traditional insulation retrofit sales.
Industry Challenges
- EPA certification timeline:Lead-safe renovator training requirements create onboarding friction for workforce expansion during demand spikes.
- Project management software integration:Legacy contractors face workflow disruption migrating from paper-based scheduling to cloud-based coordination platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Residential Remodeling Market |
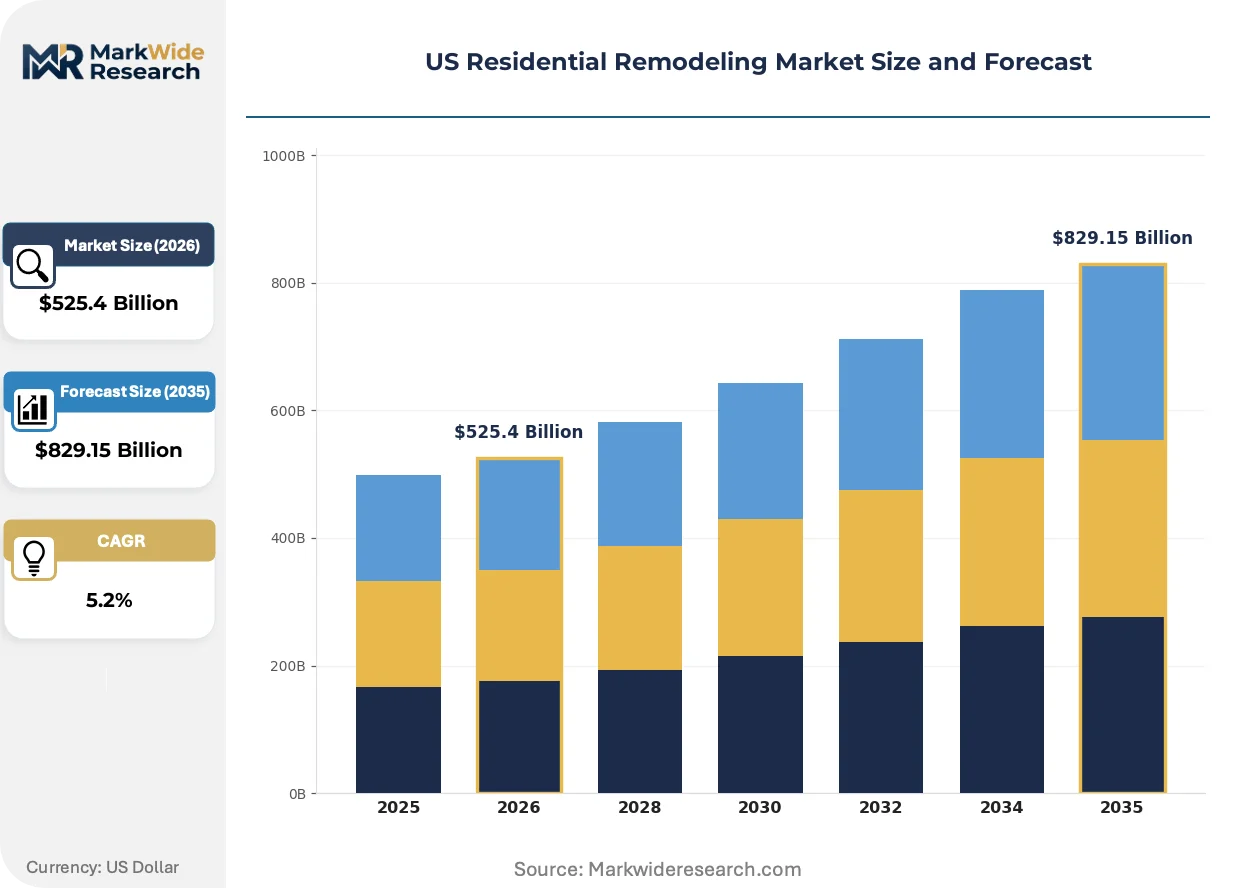
| Market Size in 2026 | $525.4 Billion |
| Market Size in 2035 | $829.15 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Kitchen Renovation, Bathroom Remodeling, Basement Finishing, Room Additions Material Type: Wood, Metal, Glass, Concrete Project Size: Small, Medium, Large, Luxury Client Type: Homeowners, Real Estate Developers, Contractors, Investors |
| Companies Covered | PulteGroup, Taylor Morrison, Power Home Remodeling, Meritage Homes Corp., KB Home, D.R. Horton, NVR, Iconiq Construction, Lennar Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Residential Remodeling Market Trends and Innovations
Material science advances and digital measurement tools are compressing pre-construction phases while expanding customization options, shifting competitive advantage toward firms that control both design iteration speed and installation quality.
Cross-laminated timber is overtaking dimensional lumber in whole-home structural renovations. Engineered mass timber enables longer spans and open-concept reconfigurations that traditional framing cannot achieve. High-end residential architects in Pacific Northwest markets are specifying CLT for second-story additions, compressing on-site construction schedules by reducing crane time and cutting waste disposal costs.
The Department of Energy's building performance benchmarks are tightening HVAC replacement specifications. Regional utility rebate programs now require minimum SEER ratings that obsolete entry-level equipment inventory. Contractors in Northeast and Midwest markets are responding by upselling heat pump conversions that qualify for IRA tax credits, repositioning their service mix toward electrification retrofits.
Homeowners are consolidating vendor relationships through design-build contracts rather than bidding separate architectural and construction phases. This procurement compression favors contractors with in-house drafting capacity and 3D visualization tools. The shift is most pronounced in Texas and Florida metros where rapid permitting timelines reward integrated project delivery that eliminates handoff delays between designer and builder.
US Residential Remodeling Market Segmentation
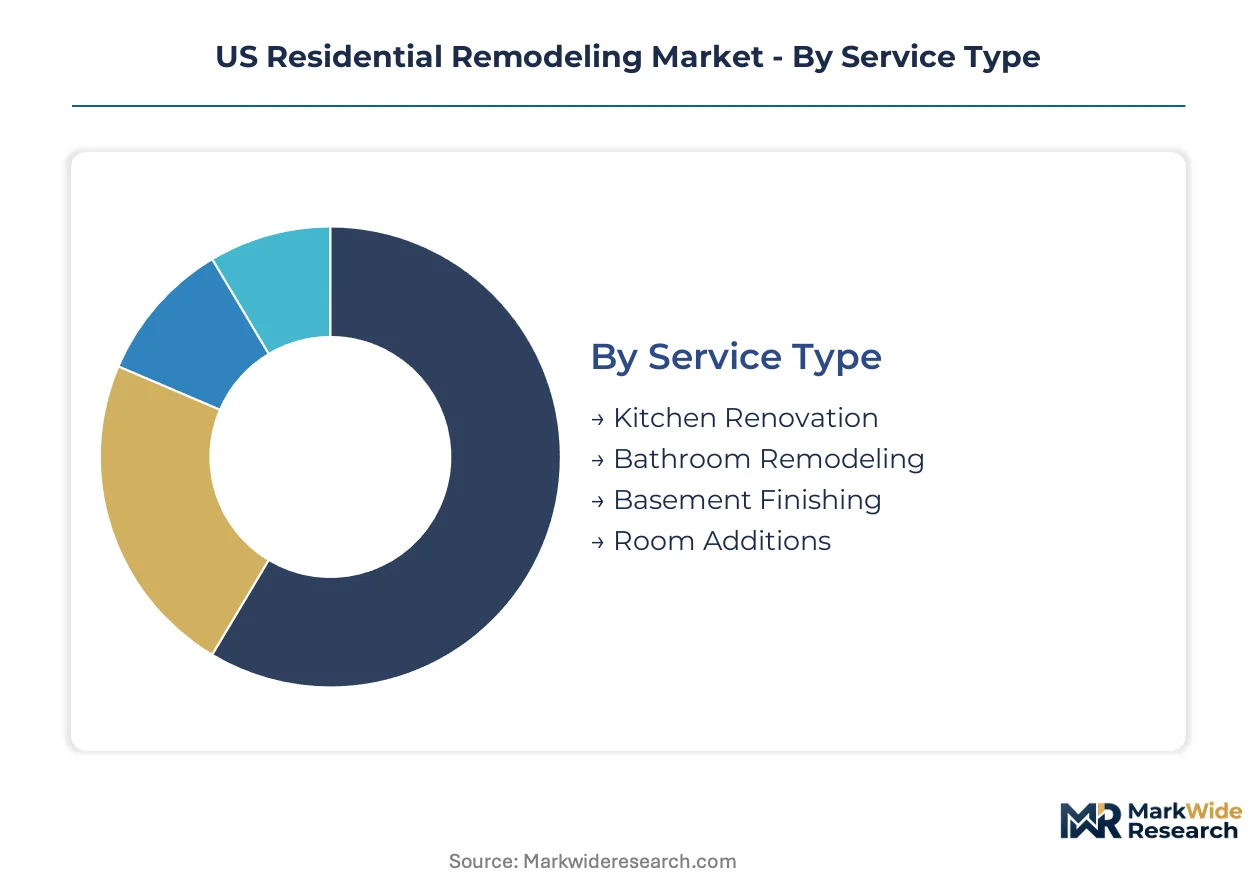
Segmentation in US residential remodeling reveals how project scope, material selection, and client economics fragment contractor specialization. Understanding these divisions explains why national players cluster in high-volume replacement categories while regional specialists dominate custom architectural work.
Service Type:
Customization intensity varies sharply across this category, from standardized product installations to architect-driven spatial reconfigurations.
- Kitchen Renovation:Cabinet refacing and appliance replacement dominate volume, with quartz countertops and semi-custom cabinetry capturing middle-market spend. Phoenix and Dallas metros show compressed project cycles as millennial buyers prioritize immediate move-in readiness over deferred upgrades.
- Bathroom Remodeling:Wet-area renovations involving waterproofing, tile, and fixture replacement require licensed plumbing coordination. Sun Belt demand concentrates in Tampa and Austin where aging stock turnover accelerates renovation frequency among first-time buyers.
- Basement Finishing:Moisture remediation and egress window installation precede finished square footage conversion. Remote-work permanence drives fastest category expansion.
- Room Additions:Foundation work and structural integration with existing framing demand permit complexity that favors established contractors. California ADU liberalization is reshaping demand geography.
Leading the category by volume: Kitchen Renovation. Expanding most quickly: Basement Finishing.
Material Type:
Cost tier stratification determines specification authority, with architects controlling premium selections and contractors driving commodity substitutions.
- Wood:Engineered lumber and cross-laminated timber displace dimensional framing in structural applications. Moisture-resistant composites expand project scope into previously unsuitable climate zones.
- Metal:Steel framing and aluminum window systems dominate commercial-adjacent residential work. Thermal break technology advances are repositioning metal in energy-code-compliant envelopes.
- Glass:Low-E coatings and triple-pane assemblies meet DOE building performance benchmarks. Northeast utility rebate programs require specifications that obsolete entry-level glazing inventory.
- Concrete:Polished slabs and stamped hardscaping concentrate in luxury outdoor living projects. Foundation repair and decorative flatwork sustain regional contractor specialization.
Capturing highest volume: Wood. Steepest expansion trajectory: Glass.
Project Size:
Customer type and financing method correlate tightly with project scale, dictating contractor organizational structure and sales cycle length.
- Small:Single-trade repairs and cosmetic refreshes under $25,000 complete within days. Handyman networks and specialty contractors compete on speed and scheduling flexibility.
- Medium:Kitchen and bathroom packages between $25,000 and $100,000 require multi-trade coordination. Design-build firms compress procurement through in-house drafting capacity.
- Large:Whole-home renovations and substantial additions exceed $100,000 and extend six to eighteen months. General contractors with dedicated project managers control this tier.
- Luxury:Architect-led gut renovations with custom millwork and imported materials command premium pricing. Limited contractor capacity constrains market depth.
Dominating by transaction count: Medium. Gaining share fastest: Large.
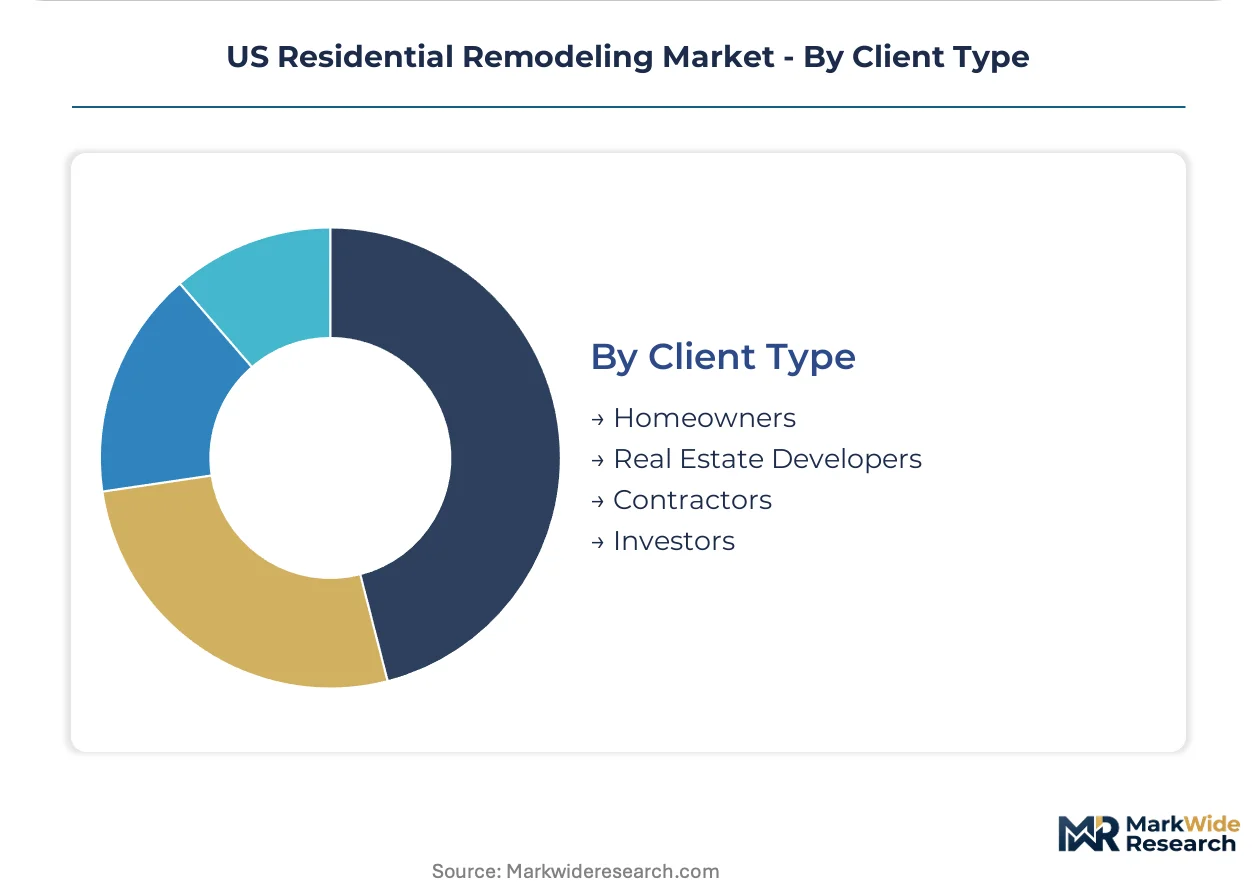
Client Type:
Procurement sophistication and repeat-purchase potential separate institutional clients from one-time residential buyers.
- Homeowners:Emotional purchase drivers and financing constraints shape project scope. Direct-to-consumer marketing channels capture replacement window and siding demand.
- Real Estate Developers:Pre-sale renovation and model home upgrades support absorption velocity. Scale advantages anchor remodeling-adjacent services through new construction footprints.
- Contractors:Subcontractor relationships and referral networks sustain project pipelines. EPA lead-safe certification requirements professionalize trade entry.
- Investors:Rental property turnover and value-add repositioning prioritize rapid turnaround. Phoenix and Dallas metros show concentrated investor activity in cosmetic refresh segments.
Generating highest project volume: Homeowners. Expanding fastest: Investors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phoenix anchors remodeling demand acceleration as millennial first-time buyers compress upgrade cycles across Sun Belt metros. EPA lead-safe certification requirements shape contractor capacity allocation differently across state regulatory environments.
California
Accessory dwelling unit liberalization drives room addition demand in Los Angeles and San Diego metros. CalGreen building codes tighten energy-efficiency specifications for HVAC and insulation retrofits. Bay Area contractors capture premium pricing for design-build integration amid rapid permitting timelines.
Texas
Dallas-Fort Worth housing stock turnover accelerates kitchen and bathroom renovation frequency among investor buyers. Municipal zoning reforms in Austin and Houston reshape ADU construction pipelines. San Antonio contractors expand basement finishing scope as remote-work permanence converts underutilized square footage.
Florida
Tampa and Orlando metros concentrate aging stock renovation demand from first-time millennial purchasers. Miami-Dade hurricane code upgrades drive window and door replacement cycles. Jacksonville contractors navigate OSHA fall-protection compliance costs for residential roof work in high-growth subdivisions.
Arizona
Phoenix leads national basement finishing expansion as dedicated home office construction penetrates suburban markets. State energy codes align with DOE building performance benchmarks for insulation retrofit specifications. Scottsdale luxury segments command custom millwork and imported material premiums.
US Residential Remodeling Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and project complexity dimensions. The market structures around three distinct tiers: national scale operators with direct-to-consumer marketing infrastructure, regional design-build firms with in-house drafting capacity, and local specialty contractors competing on scheduling flexibility. Strategic archetypes include integrated homebuilders leveraging new construction footprints for remodeling-adjacent services, pure-play replacement specialists controlling installation quality through captive crews, and technology-forward operators bundling smart-home infrastructure. Dominant competitive moves encompass vertical integration into trade labor pools and geographic clustering within high-permit-velocity metros.
Within the national scale tier, Power Home Remodeling and D.R. Horton exemplify divergent paths toward market presence. Power Home Remodeling occupies a position as a direct-to-consumer replacement specialist with in-house installation crew control. D.R. Horton anchors remodeling-adjacent services through scale advantages tied to its new construction footprint. Lennar Corp. sits within the technology-forward archetype, representing smart-home infrastructure bundling strategies that appeal to tech-forward homeowners.
| Leading Market Players |
|---|
| PulteGroup |
| Taylor Morrison |
| Power Home Remodeling |
| Meritage Homes Corp. |
| KB Home |
| D.R. Horton |
| NVR |
| Iconiq Construction |
| Lennar Corp. |
| Others |
Pricing and Supply Chain Analysis
Lumber input volatility cascades through fixed-bid residential remodeling contracts, compressing margins for framing and finish carpentry while rewarding contractors with captive mill relationships or engineered wood product sourcing agreements that stabilize material cost pass-through across project tiers.
Pricing Analysis
Project completion guarantees anchor value-based pricing in whole-home renovations, where contractors price to outcome rather than input cost. Three-tier pricing structure across premium, standard, and economy levels separates architect-led gut renovations from design-build kitchen packages and cosmetic refresh handyman services. Cost compression in the mid-market tier intensifies because engineered wood substitution erodes traditional lumber premium pricing. Investor buyers in Phoenix and Dallas metros exhibit highest price sensitivity, while Scottsdale luxury segments show least elasticity for custom millwork specifications.
Supply Chain Analysis
EPA lead-safe certification requirements gate contractor participation in pre-1978 housing stock, professionalizing trade entry and protecting incumbent certified operators. Engineered lumber and cross-laminated timber draw from Pacific Northwest manufacturing clusters, while moisture-resistant composite products source from Southeast chemical processing hubs. Single-source vulnerability concentrates in cross-laminated timber supply where domestic mass timber mills remain limited. Distribution runs through regional building material distributors with local contractor account management, supplemented by direct-to-pro channels for high-volume replacement window and siding specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US residential remodeling market functions as a cost-of-compliance story where EPA Lead Renovation, Repair and Painting Rule certification requirements erect barrier-to-entry moats that protect incumbent certified operators from price-based competition by unqualified entrants.
For Market Incumbents: Acquire licensed master electrician and plumber capacity in high-growth Sun Belt metros where trade availability constraints extend project timelines. Backward integration into in-house installation crews defends margin position against pure-play replacement specialists, while EPA certification investment deepens competitive moats as demand spikes create workforce expansion friction. For New Entrants and Emerging Players: Digital measurement tools and 3D visualization software offer technology-first wedge into design-build procurement compression in Texas and Florida metros where rapid permitting timelines reward integrated project delivery. Basement finishing segments present most penetrable white-space as remote-work permanence drives fastest category expansion, with infrared thermography diagnostic services enabling differentiated entry alongside traditional insulation retrofit sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional design-build firms with in-house drafting capacity in California ADU liberalization markets where municipal zoning reforms reshape room addition demand geography. Long-term viability centers on contractors controlling both design iteration speed and installation quality across the analysis window. Watch municipal zoning liberalization velocity in accessory dwelling unit permitting as inflection indicator for room addition contractor capacity allocation.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Certification Investment | Lead-safe renovator training protects incumbent positioning against unqualified price competition in pre-1978 housing stock. |
| Design-Build Integration | In-house drafting capacity compresses procurement timelines in Texas and Florida rapid-permit metros. |
| Smart-Home Infrastructure Bundling | HVAC and electrical contractors expand project scope by pre-wiring automation systems during major renovations. |
| Engineered Wood Product Sourcing | Moisture-resistant composites stabilize material cost exposure while expanding addressable climate zone scope. |
| Trade Labor Pool Acquisition | Captive master electrician and plumber capacity defends project timeline commitments in high-growth Sun Belt metros. |
Research Methodology
Multi-period observation of housing stock turnover rates, permit filing velocities, and contractor certification counts anchored the trend analysis, supplemented by interviews with general contractors, licensed trade specialists, municipal building officials, and building material distribution managers. Secondary validation drew from EPA enforcement data, Department of Energy building performance benchmark disclosures, state energy code adoption tracking, and local zoning liberalization records. Bottom-up project pipeline modeling triangulated against top-down housing stock age demographics and millennial first-time buyer migration patterns.
Input-output matrices mapped project volume flows across service type, material selection, and client archetype dimensions, with value outputs derived from contractor bid data and homeowner expenditure surveys across the projection horizon. Segmentation modeling incorporated project scope intensity, financing method, and regional regulatory cluster variations. CAGRs were derived from trend extrapolation of permit velocity and housing stock turnover acceleration, with cross-validation against material supplier shipment data and trade association membership growth.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lumber commodity price volatility extremes or abrupt shifts in municipal ADU zoning permissiveness. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Global Manufactured Homes Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Japan Residential Construction Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
North America Prefabricated Housing Market
Residential Construction
Siding Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Residential Construction Market
Residential Construction
Austria Prefabricated Houses Market
Residential Construction
Qatar Residential Construction Market
Residential Construction
Germany Prefabricated Houses Market
Residential Construction
Germany Residential Construction Market
Residential Construction
Europe Residential Construction Market
Residential Construction
Latin America Residential Construction Market