
 Scandinavia Prefabricated Housing Market | 2026-2036
Scandinavia Prefabricated Housing Market Size, Share, and Industry Trends Forecast 2026-2036
Scandinavia Prefabricated Housing Market Analytics
Buyer concentration among Sweden's municipal housing companies is decoupling from traditional general contractor relationships as Stockholm, Gothenburg, and Malmö public housing bodies consolidate procurement into multi-year framework agreements. Lindbacks leverages its factory in Härnösand to anchor supply to these bulk buyers with standardized timber-frame modules. Gotenehus AB competes through design flexibility, while Peab AB sustains project development capabilities that bridge factory output and municipal land allocations.
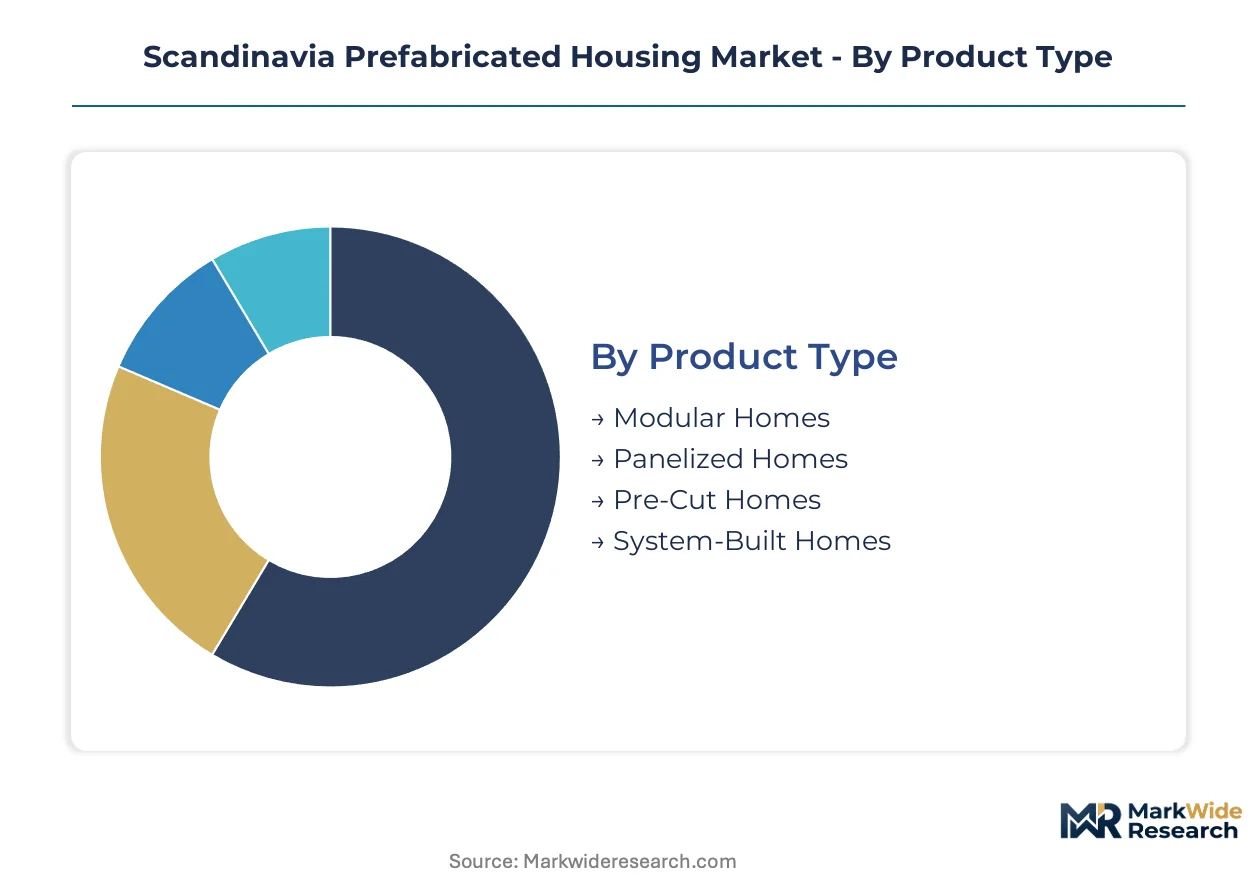
Prefabricated housing denotes dwellings manufactured in controlled factory conditions using precision-cut components or volumetric modules, typically achieving tolerances of 1-2 millimeters before transport to site for assembly. Panelized homes dominate current output across Scandinavia due to transport efficiency and compatibility with local building trades, while modular homes represent the fastest-growing category as urban infill projects demand minimal site disruption. Timber frame construction method leads volume given Nordic forest resources and Boverket's embodied carbon thresholds, though hybrid systems are gaining share where acoustic performance requirements exceed pure wood solutions.
Sweden's Boverket, Norway's Direktoratet for Byggkvalitet, and Finland's Ministry of the Environment collectively enforce building performance standards that privilege factory quality control over variable site conditions. REACH chemical restrictions and the EU Green Deal's building renovation wave shape material specifications and end-of-life obligations for manufacturers. Stakeholders must monitor whether Norwegian kommuner extend Stockholm-style framework contracting, as this procurement shift would redistribute margin pools toward scale producers capable of multi-year capacity commitments.
Market Dynamics
Sweden's Boverket climate declaration mandate is compressing project timelines and forcing developers toward factory-controlled timber-frame construction with verified embodied carbon data.
Growth Catalysts
- Boverket Climate Declarations:Sweden's building code amendments now require carbon accounting for all new construction, privileging prefabricated timber systems with documented supply chain footprints over site-cast alternatives.
- Stockholm-Uppsala Land Scarcity:The corridor's acute shortage of developable plots favors modular units that minimize site disruption and accelerate permitting cycles compared to conventional builds.
- Municipal Framework Contracting:Sweden's public housing bodies are consolidating procurement into multi-year agreements that reward scale producers with predictable volume commitments.
Market Restraints
- Transport Geometry Constraints:Volumetric modules face hard dimensional limits on Nordic road networks, capping unit sizes and forcing panelized solutions for larger footprints.
- Skilled Installation Bottlenecks:Norway and Denmark lack sufficient crane operators and module-sealing specialists to match Sweden's factory output expansion.
- REACH Chemical Compliance:ECHA restrictions on flame retardants and adhesives complicate material sourcing for hybrid timber-steel systems targeting acoustic performance thresholds.
Strategic Opportunities
- Norwegian Kommune Procurement:Municipalities outside Oslo remain fragmented purchasers; framework contracting adoption would unlock bulk demand comparable to Sweden's consolidated buyers.
- EU Green Deal Renovation Wave:Retrofit-focused volumetric modules for building envelope upgrades represent untapped application space distinct from new-build social housing.
- Digital Twin Integration:Convergence of BIM workflows with factory automation enables real-time carbon tracking from design through assembly, differentiating bids for climate-conscious developers.
Industry Challenges
- Timber Engineering Talent Gap:Nordic universities produce insufficient structural engineers specializing in mass timber connections and fire-rated assemblies to match factory expansion plans.
- Multi-Party Warranty Complexity:Factory warranties, transport liability, and site installation guarantees create jurisdictional disputes when defects emerge post-occupancy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scandinavia Prefabricated Housing Market |
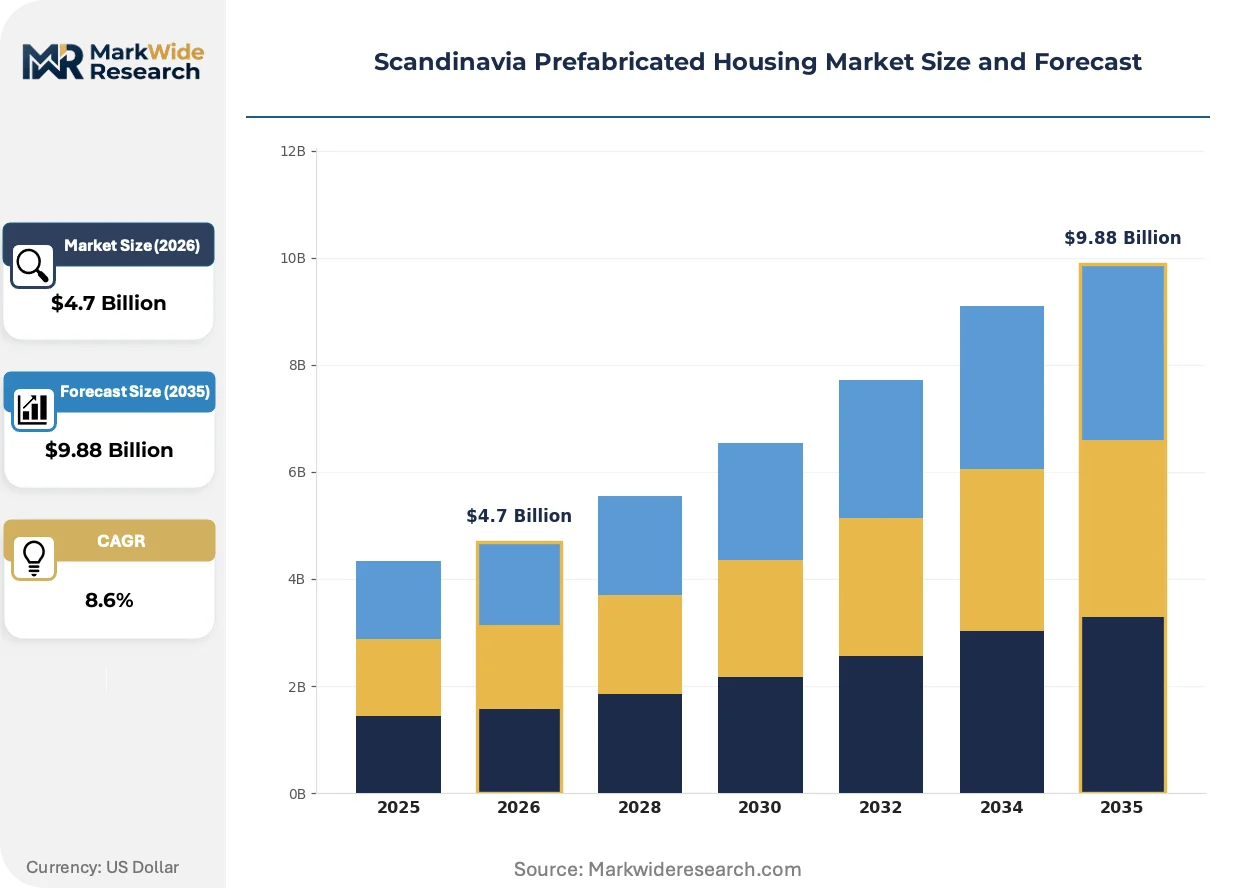
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Pre-Cut Homes, System-Built Homes End User: Residential Developers, Construction Companies, Individual Buyers, Government Projects Construction Method: Light Gauge Steel, Timber Frame, Concrete Panel, Hybrid Systems Design Style: Modern, Traditional, Industrial, Eco-friendly |
| Companies Covered | Lindbacks, Gotenehus AB, Peab AB, Anebyhusgruppen AB, Alvsbyhus AB, Derome AB, Trivselhus AB, Eksjohus AB, Martinson Group AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scandinavia Prefabricated Housing Market Evolving Landscape
Factory automation and regulatory carbon accounting are converging to reshape how Scandinavian housing is specified, priced, and delivered across the project lifecycle.
Cross-laminated timber (CLT) is consolidating its position as the dominant structural material for mid-rise residential modules in Sweden. Stockholm's municipal housing companies now specify CLT cores for projects above four stories, compressing the competitive window for steel-frame alternatives. The technology is consolidating supplier margins toward integrated producers with captive sawmill capacity.
Sweden's Boverket climate declaration framework is tightening enforcement thresholds for embodied carbon in new construction. Developers must now submit verified Environmental Product Declarations for structural materials, favoring prefabricated systems with factory-audited supply chains over site-cast concrete with variable batch impacts. Panelized timber producers with ISO-compliant carbon accounting are capturing disproportionate share of public tenders.
Municipal buyers are consolidating procurement authority into centralized technical teams that specify performance outcomes rather than prescriptive methods. Sweden's regional housing bodies now contract for energy-neutral units rather than component lists, compressing the role of traditional general contractors. This pattern is most visible in Gothenburg and Malmö, where framework agreements span 500-plus units with standardized interfaces for MEP systems.
Scandinavia Prefabricated Housing Market Segmentation
Segmentation in the Scandinavia prefabricated housing market reveals how procurement patterns, material specifications, and buyer types concentrate margin pools differently across factory-built housing categories. Understanding these splits exposes where Boverket climate mandates and municipal framework contracting reshape competitive positioning.
Product Type:
Volume production currently concentrates in panelized systems, while modular solutions command premium positioning for urban infill projects demanding minimal site disruption.
- Modular Homes:Volumetric units manufactured as complete three-dimensional boxes with pre-installed MEP systems achieve tolerances of 1-2 millimeters in factory conditions. Stockholm-Uppsala corridor developers specify these for infill sites where crane time and site closure windows are severely constrained by dense urban adjacencies. Transport geometry limits on Nordic road networks cap unit dimensions, forcing design compromises for larger footprints.
- Panelized Homes:Flat-pack wall, floor, and roof components dominate current Scandinavian output due to transport efficiency and compatibility with local building trades. Sweden's municipal housing companies favor standardized panel interfaces that enable rapid on-site assembly by regional contractor networks without specialized module-sealing expertise. This category absorbs the bulk of Boverket climate declaration compliance through factory-audited timber supply chains.
- Pre-Cut Homes:Precision-cut framing packages shipped as kit-of-parts serve individual buyers and small-scale developers with design flexibility requirements. Norway's fragmented kommune procurement outside Oslo favors these for dispersed rural projects where transport costs for finished modules prove prohibitive.
- System-Built Homes:Integrated building systems combining structural frames with pre-engineered MEP and facade elements target performance-specification tenders. Denmark's renovation-focused housing programs experiment with these for building envelope upgrades distinct from new-build applications.
Today's leader: Panelized Homes. Tomorrow's challenger: Modular Homes.
End User:
Procurement authority is consolidating toward institutional buyers with multi-year volume commitments, compressing the role of fragmented individual purchasers.
- Residential Developers:Private developers in Sweden's Stockholm-Uppsala corridor now specify prefabricated timber systems to compress permitting cycles and meet Boverket climate declaration thresholds. These buyers prioritize factory-audited Environmental Product Declarations over component flexibility.
- Construction Companies:Traditional general contractors face margin compression as municipal housing bodies consolidate procurement into centralized technical teams. Gothenburg and Malmö framework agreements spanning 500-plus units now bypass contractor intermediaries for direct factory relationships.
- Individual Buyers:Single-family custom home purchasers concentrate in Norway's rural kommuner and Denmark's coastal regions where design flexibility outweighs unit cost considerations. These buyers lack negotiating leverage for carbon accounting documentation required by institutional tenders.
- Government Projects:Sweden's municipal housing companies anchor regional demand through multi-year framework agreements rewarding scale producers with predictable volume. Boverket building code amendments mandate climate declarations that privilege factory-controlled supply chains over site-cast alternatives for public tenders.
Institutional buyers are capturing procurement share fastest.
Construction Method:
Material selection tracks directly against Boverket embodied carbon thresholds and acoustic performance requirements across residential building types.
- Timber Frame:Nordic forest resources and Boverket climate mandates position mass timber as the dominant structural method for mid-rise residential modules. CLT cores now exceed four stories in Stockholm municipal specifications, consolidating supplier margins toward integrated producers with captive sawmill capacity.
- Hybrid Systems:Timber-steel combinations gain share where acoustic performance thresholds exceed pure wood solutions, particularly for party walls in dense urban infill. REACH chemical restrictions on flame retardants and adhesives complicate material sourcing for these applications.
- Light Gauge Steel:Cold-formed steel framing serves renovation modules and non-residential applications where timber moisture sensitivity poses risks. These systems struggle to compete on embodied carbon metrics against mass timber alternatives in climate-declaration tenders.
- Concrete Panel:Precast concrete systems retain niche positioning for foundation and basement elements where timber durability concerns persist. Boverket climate declarations increasingly disadvantage these systems due to variable batch carbon impacts versus factory-audited timber supply chains.
Timber Frame commands current volume. Hybrid Systems are climbing the fastest.
Design Style:
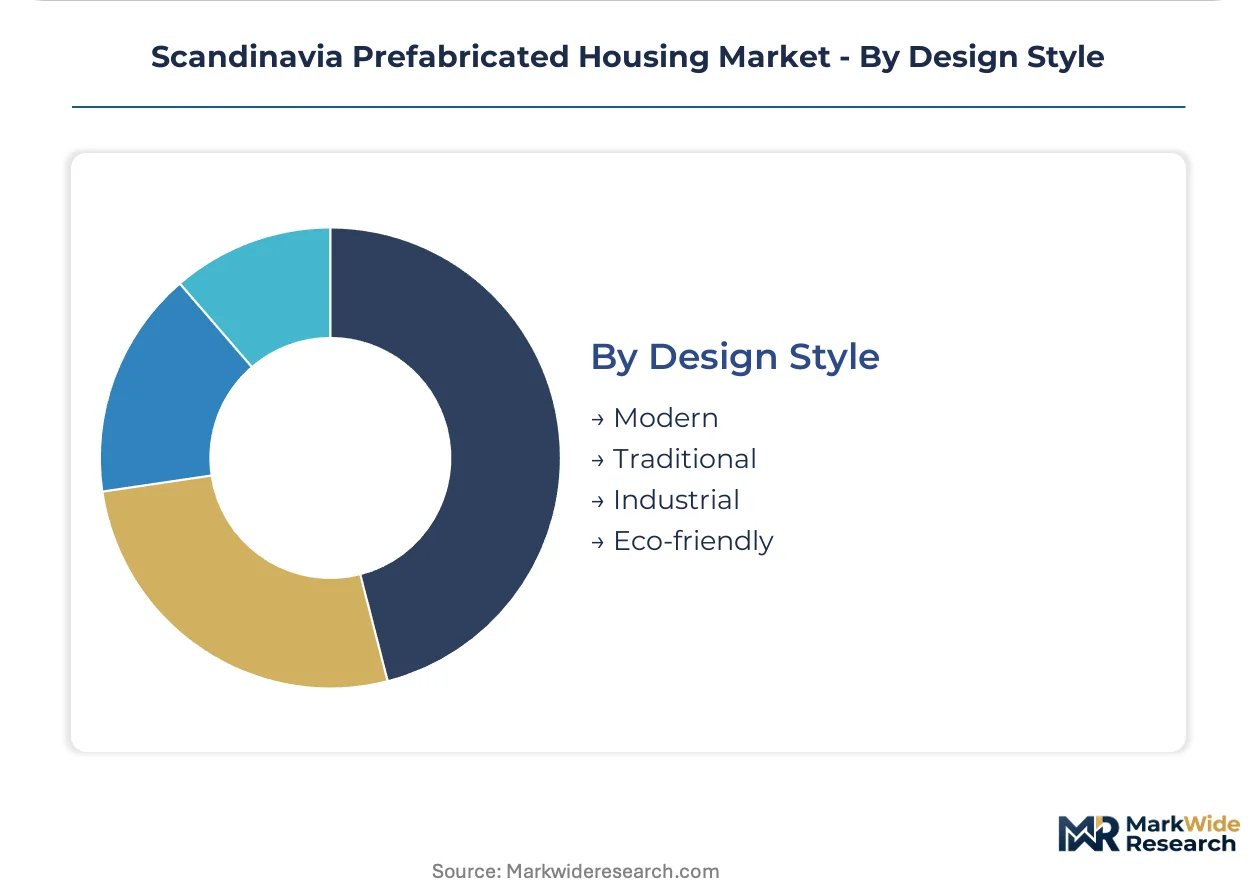
Aesthetic specification splits between municipal standardization pressures and premium differentiation for private developers.
- Eco-friendly:Passive house performance specifications and biogenic material palettes dominate municipal framework agreements in Sweden. These designs integrate with Boverket climate declaration requirements through documented supply chain footprints and energy-neutral operational targets.
- Modern:Clean-lined minimalism with large glazing ratios serves urban infill projects in Stockholm and Copenhagen where land values justify premium construction costs. Factory precision enables the tight tolerances required for high-performance envelope detailing.
- Traditional:Pitched roofs and vernacular cladding respond to heritage context requirements in Norway's coastal kommuner and Denmark's historic districts. Panelized systems accommodate these aesthetics without sacrificing factory production efficiencies.
- Industrial:Exposed structural elements and utilitarian finishes target adaptive reuse and commercial-to-residential conversion projects. These designs leverage modular construction's minimal site disruption for sensitive urban locations.
Eco-friendly leads municipal procurement. Modern captures private developer premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's timber engineering workforce anchors prefabricated housing expertise across the Nordic region, with factory automation specialists and mass timber structural engineers concentrated in Stockholm-Uppsala and Härnösand industrial clusters.
Sweden
Boverket climate declarations and municipal framework contracting drive demand for factory-audited timber systems. The building code mandates verified Environmental Product Declarations for structural materials. Stockholm-Uppsala corridor developers specify CLT cores above four stories, consolidating supply toward integrated producers with captive sawmill capacity.
Norway
Kommune procurement fragmentation outside Oslo limits bulk purchasing power for social housing programs. The Direktoratet for Byggkvalitet enforces performance standards that privilege factory quality control over variable site conditions. Bergen and Trondheim municipalities experiment with panelized systems for coastal infill projects constrained by transport geometry limits.
Denmark
Renovation-focused housing programs create demand for building envelope upgrade modules distinct from new-build applications. REACH chemical restrictions shape material specifications for hybrid timber-steel systems. Copenhagen's dense urban core favors modular units minimizing site disruption during adaptive reuse conversions.
Finland
The Ministry of the Environment coordinates building performance standards with Sweden and Norway through Nordic regulatory harmonization. Timber frame construction dominates volume given extensive forest resources and embodied carbon thresholds. Tampere and Turku industrial clusters supply precision-cut components for cross-border municipal tenders.
Scandinavia Prefabricated Housing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, with municipal framework agreements rewarding scale producers while design-flexibility segments sustain mid-cap differentiation. Market structure tilts toward consolidation as Stockholm, Gothenburg, and Malmö housing bodies aggregate demand into multi-year commitments. Three archetypes dominate: integrated timber producers with captive sawmill capacity, design-flexible panelized specialists, and project developers bridging factory output with municipal land allocations. Competitive moves center on backward integration into timber supply and digital twin integration for real-time carbon tracking.
Among Sweden-based fabricators, Lindbacks, Gotenehus AB, and Peab AB occupy distinct positioning within the procurement hierarchy. Lindbacks represents the scale-driven archetype through its Härnösand factory anchoring supply to municipal bulk buyers. Gotenehus AB exemplifies the design-flexibility specialist competing for tenders requiring aesthetic customization. Peab AB sits within the project developer tier, sustaining capabilities that bridge factory production with public land allocation processes.
| Leading Market Players |
|---|
| Lindbacks |
| Gotenehus AB |
| Peab AB |
| Anebyhusgruppen AB |
| Alvsbyhus AB |
| Derome AB |
| Trivselhus AB |
| Eksjohus AB |
| Martinson Group AB |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap timber processors anchor supply discipline across Sweden's factory network, translating Boverket carbon accounting mandates into pricing power over municipal buyers locked into multi-year framework agreements. Their captive sawmill capacity insulates margin pools from raw material volatility while compressing bids from non-integrated panelized specialists competing for Stockholm-Uppsala corridor tenders.
Pricing Analysis
Project-based bundled contracts dominate municipal procurement, wrapping factory production, transport logistics, and on-site crane installation into single-price commitments. Price differentiation rests on ISO-compliant carbon accounting documentation and captive timber supply rather than design flexibility. Cost compression in standard panelized tiers is intensifying because Sweden's public housing bodies consolidate volume into fewer suppliers. Individual buyers in Norway's rural kommuner exhibit highest price sensitivity, lacking negotiating leverage for climate declaration compliance that institutional tenders require.
Supply Chain Analysis
Single-source vulnerability sits with Sweden's concentrated CLT core production, where Stockholm-Uppsala and Härnösand industrial clusters feed cross-border demand from Norway and Finland. Raw material flows draw from Nordic spruce and pine forests, engineered timber adhesives, and specialized crane logistics operators. Supply chain risk centers on REACH chemical restrictions complicating adhesive sourcing for hybrid timber-steel systems. Distribution runs through direct factory-to-site relationships for municipal bulk buyers, bypassing traditional general contractor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Boverket's climate declaration mandate continuously tightens embodied carbon thresholds, forcing recurring technology upgrades and consolidating procurement toward factory-audited suppliers.
For Market Incumbents: Lock in municipal framework agreement renewals by anchoring multi-year capacity commitments to Stockholm, Gothenburg, and Malmö housing bodies. Defend against emerging pure-play modular specialists by deepening backward integration into mass timber engineering talent pools and digital twin carbon tracking capabilities that municipal technical teams now specify as tender requirements.
For New Entrants and Emerging Players: The premium-to-economy price gap in Norway's fragmented kommune procurement outside Oslo offers white-space entry below Sweden's consolidated municipal tiers. Target Denmark's renovation-focused envelope upgrade modules where EU Green Deal funding creates demand distinct from new-build social housing. Lead with design-flexible panelized systems that accommodate heritage aesthetics without sacrificing factory production efficiencies.
For Investors and Strategic Acquirers: Valuations sit cheapest among design-flexible mid-caps lacking captive sawmill capacity but holding established contractor relationships in Norway and Denmark. Long-term viability over the next decade hinges on regulatory harmonization extending Stockholm-style framework contracting across Nordic borders. Watch whether Norwegian Direktoratet for Byggkvalitet mandates climate declarations matching Sweden's Boverket thresholds as the signal for demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Sawmill Capacity | Secures timber supply chains against Boverket carbon accounting requirements while compressing input costs for municipal bulk tenders. |
| Digital Twin Integration with BIM Workflows | Enables real-time embodied carbon tracking from design through assembly, differentiating bids for climate-conscious Stockholm housing bodies. |
| Framework Agreement Expansion into Norway | Captures kommune procurement consolidation if Direktoratet for Byggkvalitet harmonizes climate declaration mandates with Sweden. |
| Renovation Module Product Line Development | Addresses Denmark's EU Green Deal building envelope upgrade programs distinct from saturated new-build social housing segments. |
| Mass Timber Engineering Talent Acquisition | Resolves structural bottlenecks as Nordic universities produce insufficient fire-rated assembly specialists for factory expansion plans. |
Research Methodology
Bottom-up municipal procurement modeling reconciled against top-down factory capacity tracking forms the analytical core of this study. Primary interviews with municipal housing procurement officers, mass timber structural engineers, factory automation specialists, and crane logistics operators combined with secondary validation from Boverket regulatory filings, Direktoratet for Byggkvalitet performance standards, EU Green Deal implementation documents, and Nordic timber trade association output data. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of panelized and modular output volumes across Sweden, Norway, Denmark, and Finland established baseline growth patterns. The projection framework segments by product type, construction method, end-user procurement tier, and design performance specification, with CAGRs derived from regression analysis against municipal housing backlog data and regulatory implementation timelines. Forecast inputs include Boverket climate declaration enforcement thresholds, REACH chemical restriction amendments, and timber engineering workforce pipeline projections.
Caveats apply where regulatory harmonization delays, REACH chemical ban expansions, or transport geometry constraint relaxations could materially shift the outlook. Forecasts reflect documented assumptions about municipal framework contracting adoption rates and embodied carbon threshold tightening schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Asia-Pacific Prefabricated Housing Market
Residential Construction
Outdoor Living Structure Market
Residential Construction
North America Bath Remodeling Market
Residential Construction
Siding Market
Residential Construction
US Residential Construction Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
Japan Residential Construction Market
Residential Construction
North America Residential Construction Market
Residential Construction
Residential Construction Market
Residential Construction
Canada Manufactured Homes Market
Residential Construction
Europe Manufactured Homes Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Saudi Arabia Residential Construction Market
Residential Construction
Saudi Arabia Manufactured Homes Market
Residential Construction
Residential Roofing Market
Residential Construction
Prefabricated Homes Market