
 Pharmaceutical Solid Dosage Contract Manufacturing Market | 2026-2036
Pharmaceutical Solid Dosage Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Solid Dosage Contract Manufacturing Market Outlook
The capital-intensity divergence between high-volume continuous manufacturing lines and batch-oriented facilities is redrawing competitive tiers in pharmaceutical solid dosage contract manufacturing. Catalent, Inc. leverages integrated development-to-commercialization campuses across multiple continents to anchor large-molecule and small-molecule portfolios alike. Lonza Group AG sustains specialized positions in potent compound handling and high-containment operations. Jubilant Pharmova Limited competes on cost-optimized scale from Indian facilities serving regulated markets.
Pharmaceutical solid dosage contract manufacturing encompasses the outsourced production of tablets, capsules, powders, and granules through unit operations including granulation, compression, coating, and packaging, typically performed under current Good Manufacturing Practice conditions with batch records subject to regulatory audit. The primary commercial purpose is to enable sponsor companies to access validated manufacturing capacity without capital deployment in fixed assets. Tablets dominate current volume flows due to established tooling libraries and universal patient acceptability, while controlled-release and sustained-release delivery modes command premium pricing structures reflecting specialized polymer matrix technologies and bioequivalence study investments. Immediate-release formats remain the volume baseline for generic manufacturer clients prioritizing speed-to-market and manufacturing economy.
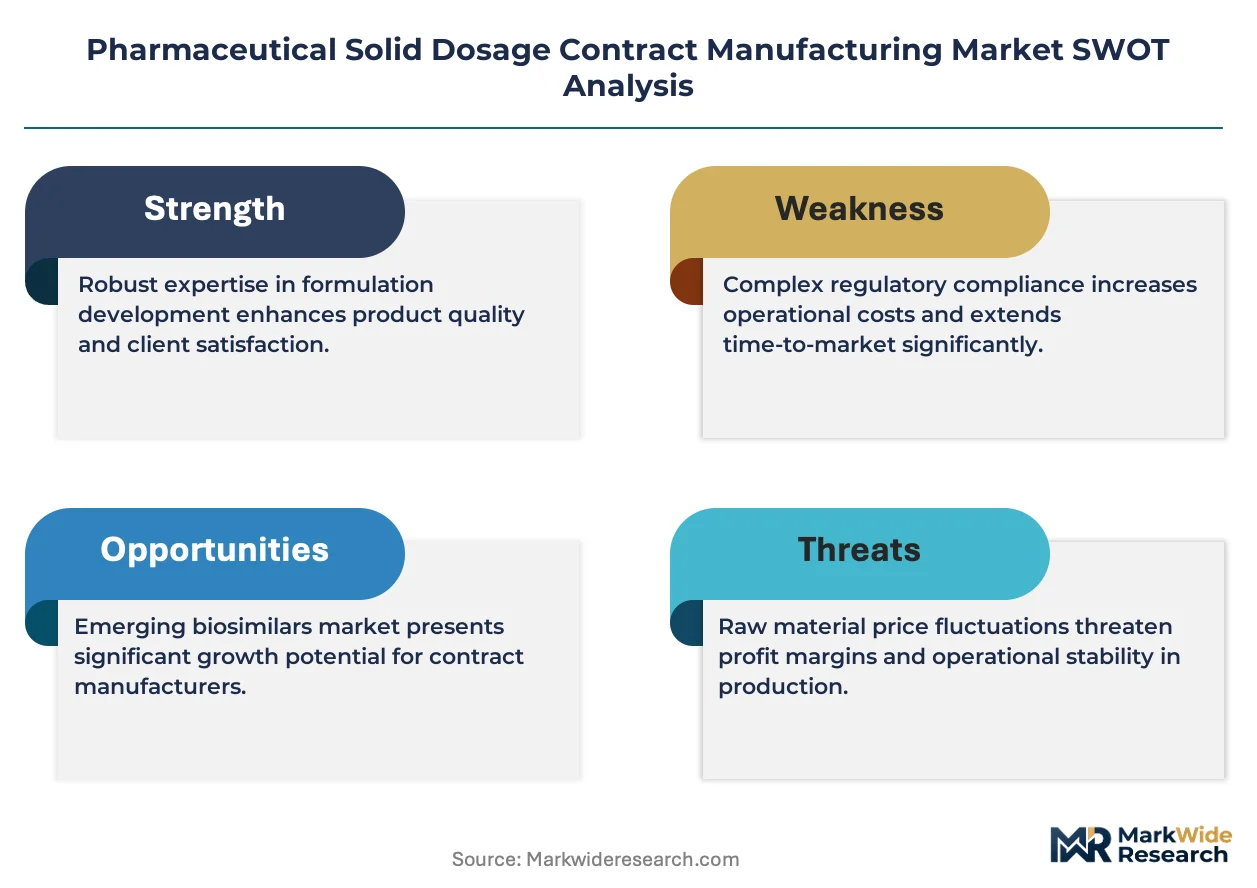
FDA current Good Manufacturing Practice enforcement, EMA Annex 1 sterile and non-sterile guidance revisions, and ICH Q13 continuous manufacturing guidelines collectively elevate compliance costs and favor contract manufacturers with dedicated regulatory affairs infrastructure. CDSCO and other national regulators in major supply jurisdictions are aligning inspection protocols with PIC/S standards, tightening market access for facilities lacking international certification. Stakeholders must monitor which contract manufacturers are converting batch records to real-time release testing architectures, as this capability divergence will separate preferred supplier tiers from commodity capacity providers.
Market Dynamics
Continuous manufacturing adoption is compressing batch cycle times and forcing legacy facilities toward capital-intensive retrofits or obsolescence, redrawing competitive tiers between integrated CDMO campuses and standalone commodity providers.
Growth Catalysts
- ICH Q13 Continuous Manufacturing Guidelines:FDA and EMA alignment on real-time release testing is accelerating sponsor migration from batch validation, favoring contract manufacturers with integrated process analytical technology suites.
- Generic Manufacturer Outsourcing Surge:Cost pressures on off-patent portfolios are driving volume concentration toward CDSCO-compliant Indian facilities with PIC/S certification and established ANDA submission support.
- Serialization Mandate Deadlines:DSCSA enforcement in the US and FMD compliance in Europe are disqualifying in-house operations lacking track-and-trace infrastructure, pushing sponsors toward equipped contract partners.
Market Restraints
- API Supply Concentration:Dependence on Chinese and Indian active pharmaceutical ingredient producers creates exposure to export restriction risks and geopolitical friction in critical starting material flows.
- Containment Capital Requirements:Potent compound handling necessitates isolator technology and dedicated HVAC systems, erecting seven-figure entry barriers for mid-scale entrants in high-potency segments.
- Batch Record Conversion Costs:Legacy documentation systems require multimillion-dollar electronic batch record implementations to satisfy FDA data integrity expectations, straining smaller contract manufacturers.
Strategic Opportunities
- Orphan Drug Manufacturing:Small-batch flexibility for rare disease indications remains underserved, with sponsors seeking CDMOs capable of validated campaigns below commercial scale thresholds.
- Bi-layer Tablet Convergence:Integration of immediate-release and extended-release strata in single-unit dosing is opening formulation partnerships between polymer specialists and high-speed compression houses.
- PLI Scheme Incentives:India's production-linked incentive framework for pharmaceuticals is attracting greenfield investments in continuous manufacturing lines with dedicated regulatory affairs infrastructure.
Industry Challenges
- Process Analytical Technology Talent Scarcity:Recruitment of chemometricians and real-time analytics specialists lags facility expansion, constraining rollout of predictive quality systems.
- Legacy Equipment Integration:Retrofitting continuous direct compression lines into existing batch-oriented plants requires extended validation timelines and creates hybrid workflow inefficiencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Solid Dosage Contract Manufacturing Market |
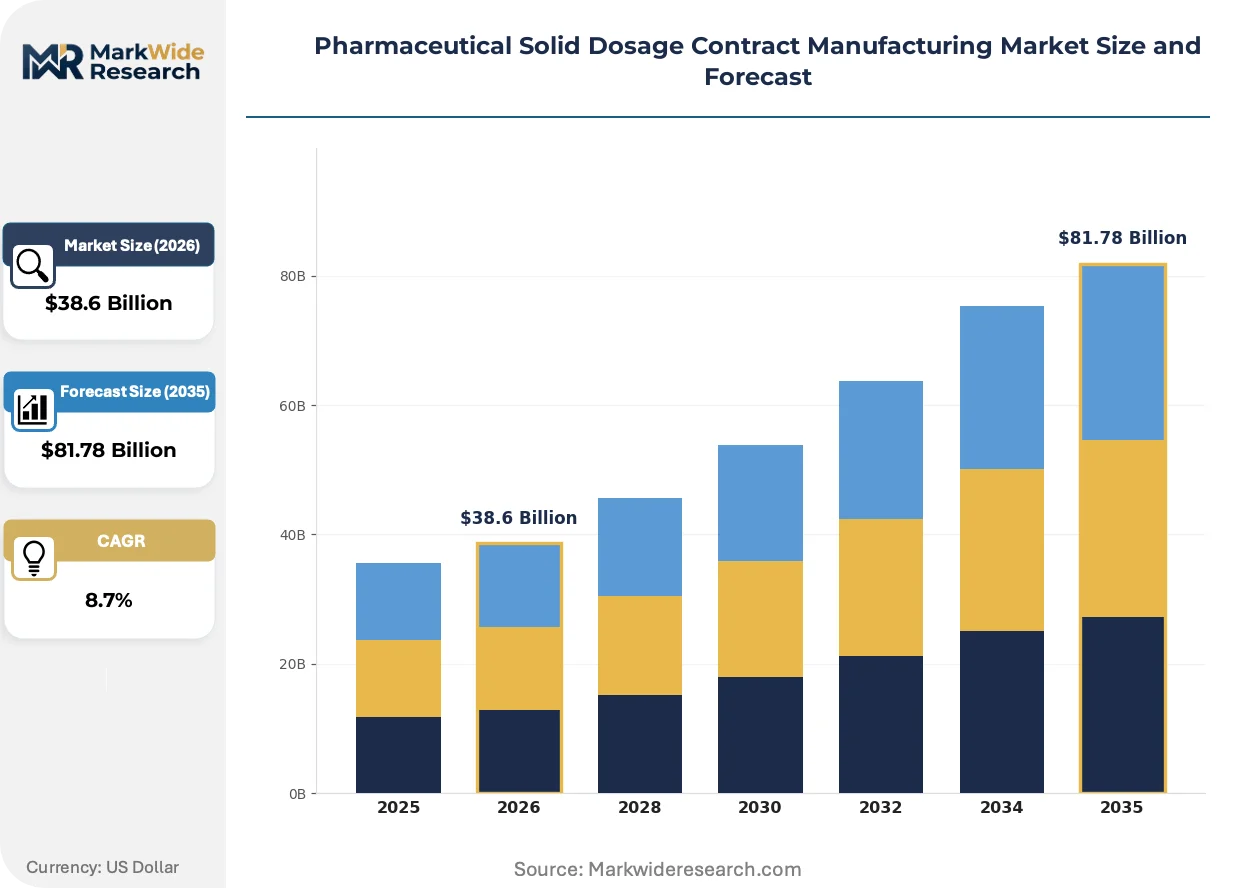
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powders, Granules Delivery Mode: Immediate Release, Controlled Release, Sustained Release, Delayed Release End User: Pharmaceutical Companies, Biopharmaceuticals, Contract Research Organizations, Generic Manufacturers Technology: Extrusion, Compression, Coating, Blister Packaging |
| Companies Covered | Catalent, Inc., Lonza Group AG, Aenova Group, Jubilant Pharmova Limited, Patheon Pharma Services, Corden Pharma International, Boehringer Ingelheim International GmbH, Piramal Pharma Solutions, Recipharm AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Solid Dosage Contract Manufacturing Market Strategic Shifts
Digital twin deployment and modular manufacturing architectures are compressing tech transfer timelines while enabling distributed production models that challenge traditional centralized CDMO economics.
Single-use containment systems for potent compound handling are miniaturizing high-potency manufacturing footprints. Oncology-focused sponsors are adopting these isolator technologies at accelerated pace to de-risk cross-contamination exposure. The resulting facility downsizing is enabling geographic proximity between manufacturing and clinical trial sites, compressing supply chain nodes.
EMA Annex 1 revisions on contamination control strategy are mandating formal risk assessments for non-sterile solid dosage operations. Contract manufacturers must document barrier integrity and personnel flow controls to retain GMP certification. European facilities with existing containment infrastructure are absorbing compliance costs more readily than batch-oriented competitors in emerging supply jurisdictions.
Biopharma procurement teams are consolidating vendor panels around integrated development-through-commercialization partners. Small-molecule sponsors are displacing transactional spot-contracting with multi-year capacity reservation agreements. This concentration is most visible among mid-cap generic manufacturers seeking regulatory submission support bundled with manufacturing capacity.
Pharmaceutical Solid Dosage Contract Manufacturing Market Segmentation
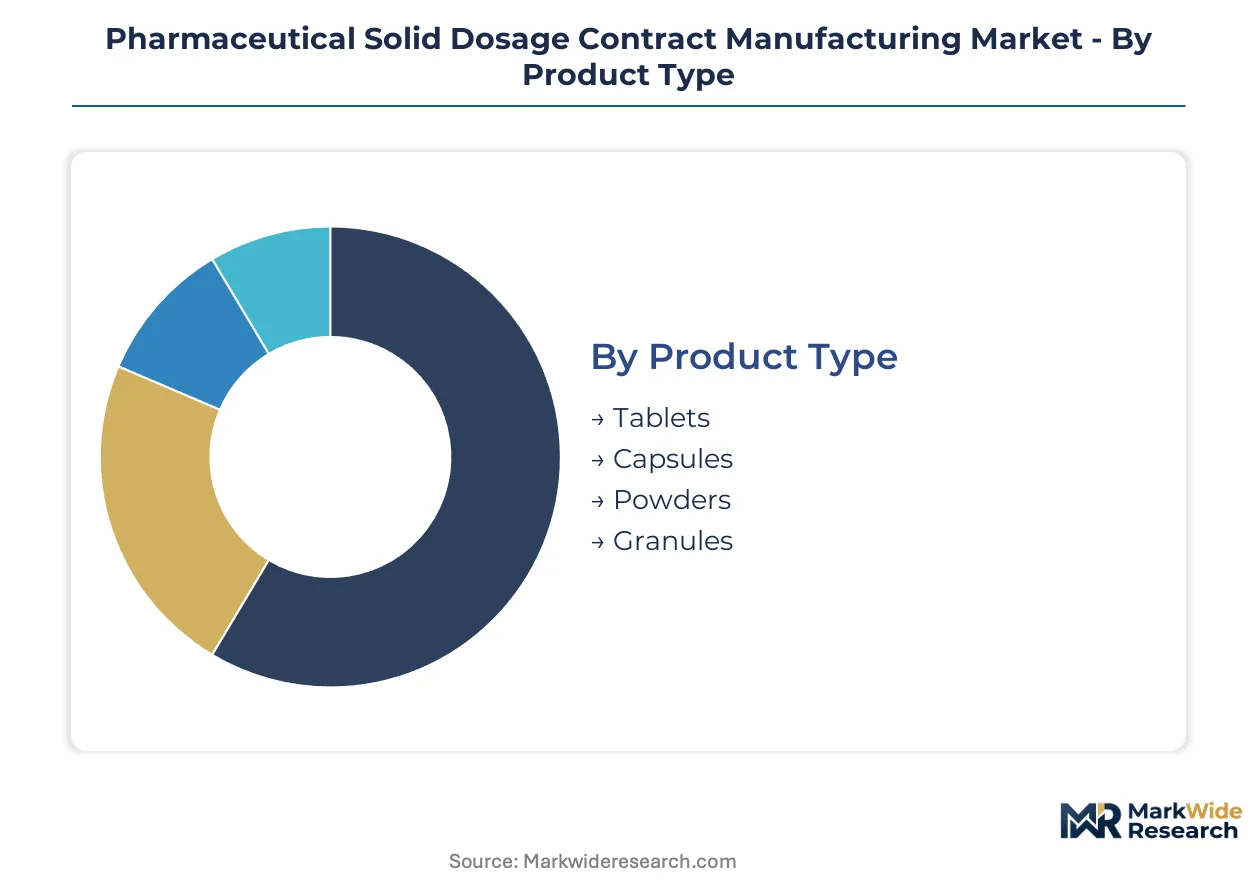
Segmentation in pharmaceutical solid dosage contract manufacturing reveals distinct capability requirements and margin profiles across product formats, release technologies, and customer types. Contract manufacturers must align capital deployment with the specific validation and regulatory demands of each segment to capture sustainable revenue.
Product Type:
Substitution pressure runs strongest against powders and granules as sponsors consolidate toward unit-dose formats with superior patient compliance and packaging efficiency.
- Tablets:Compressed solid units formed through granulation, compression, and coating sequences. Demand concentrates among generic manufacturers in India seeking high-speed rotary press capacity for ANDA submissions to FDA. Tooling standardization and established bioequivalence pathways anchor tablet dominance in outsourced volume.
- Capsules:Gelatin or HPMC shells enclosing powder or pellet fills, enabling combination therapies and taste masking. Biopharmaceutical sponsors in the United States favor capsules for Phase III scale-up due to faster formulation development cycles versus tablet optimization.
- Powders:Uncompressed bulk formulations for reconstitution or sachet filling. Pediatric and geriatric indications in Japan sustain niche demand despite unit-dose preference trends.
- Granules:Intermediate agglomerated forms for subsequent compression or direct sachet packaging. CDSCO-registered Indian facilities supply granule intermediates to European sponsors seeking to bypass wet granulation capacity constraints.
Tablets anchor the volume base while capsules gain share at the steepest rate.
Delivery Mode:
Cost tier stratification separates commodity immediate-release formats from premium-priced modified-release technologies requiring specialized polymer expertise and extended stability studies.
- Immediate Release:Rapid dissolution formulations with minimal excipient complexity. Generic manufacturers in India drive volume concentration for US market entry under abbreviated new drug application pathways.
- Controlled Release:Zero-order or first-order kinetic profiles achieved through matrix or reservoir systems. European sponsors seeking EMA compliance pay premium pricing for validated osmotic pump and multi-layer tablet platforms.
- Sustained Release:Extended plasma concentration maintenance via hydrophilic matrix or coated pellet technologies. Oncology-focused biopharmaceuticals in the United States favor sustained release for reduced dosing frequency in chronic administration.
- Delayed Release:Enteric or colonic targeting through pH-dependent polymer coatings. Specialized CDMOs in Switzerland command capacity premiums for Eudragit-based formulations requiring precise dissolution trigger calibration.
Immediate release dominates current volume flows while controlled release expands most quickly as sponsors pursue lifecycle management extensions.
End User:
Customer type determines contract structure complexity, with biopharmaceuticals demanding integrated development services and generic manufacturers prioritizing capacity reservation economics.
- Pharmaceutical Companies:Large-cap innovators outsourcing commercial manufacturing post-patent expiry or for capacity overflow. US-based sponsors favor multi-year agreements with CDMOs holding FDA warning letter clearance histories.
- Biopharmaceuticals:Emerging and established biotech firms lacking in-house solid dosage infrastructure. Cell therapy and gene therapy sponsors in Boston and San Diego clusters are expanding into oral solid partnerships for combination product strategies.
- Contract Research Organizations:Clinical trial material suppliers requiring GMP manufacturing for Phase I through Phase III. Indian CROs with CDSCO licensing serve domestic sponsors and multinational trials.
- Generic Manufacturers:Cost-optimized producers competing on ANDA first-to-file timing. PIC/S-certified Indian facilities capture disproportionate generic outsourcing as FDA inspection frequency intensifies.
Generic manufacturers anchor the volume base while biopharmaceuticals gain share at the steepest rate.
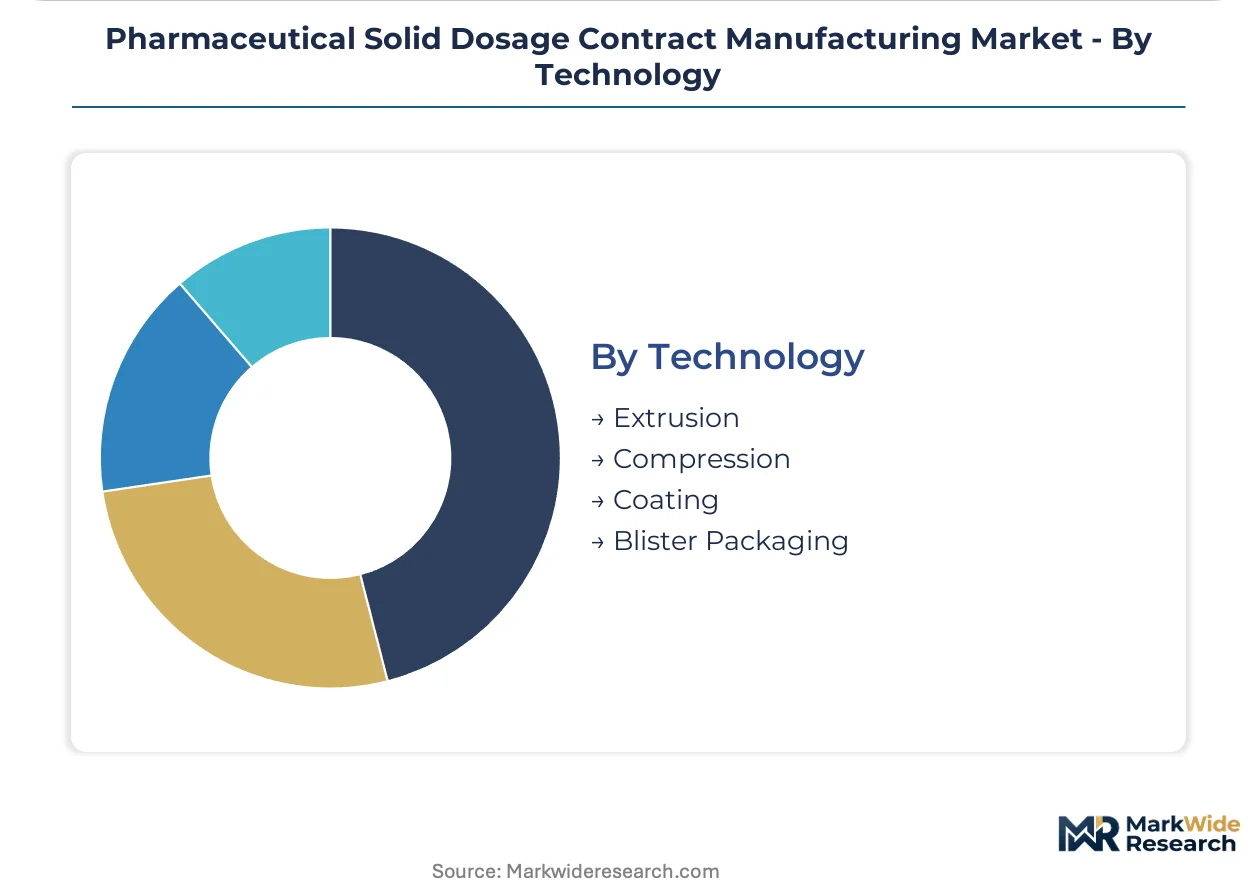
Technology:
Technology selection correlates directly with facility capital intensity and regulatory inspection focus, compressing margins for standalone packaging houses while rewarding integrated process control.
- Extrusion:Hot-melt or twin-screw processing for amorphous solid dispersions and fixed-dose combinations. Solubility-enhancement applications in the United States drive adoption as BCS Class II and IV compounds dominate development pipelines.
- Compression:Direct compression or roller compaction tableting with real-time weight and hardness monitoring. High-speed double-rotary presses in Indian facilities serve global generic volume requirements.
- Coating:Film, enteric, or functional coating for moisture protection, taste masking, or modified release. European EMA inspections focus heavily on coating pan airflow validation and spray gun uniformity.
- Blister Packaging:Thermoformed or cold-formed unit-dose packaging with integrated serialization. DSCSA compliance mandates in the United States are disqualifying standalone packaging providers lacking track-and-trace infrastructure.
Compression anchors the volume base while extrusion gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes pharmaceutical solid dosage contract manufacturing through integrated development partnerships, while India and China absorb capacity through pure-play manufacturing economics with regulatory submission support bundled separately.
United States
FDA serialization mandates and DSCSA enforcement deadlines are disqualifying in-house operations lacking track-and-trace infrastructure, accelerating sponsor migration toward equipped contract partners. The Boston and San Diego biotech clusters are expanding oral solid partnerships for combination product strategies. Catalent maintains integrated development-to-commercialization campuses serving large-molecule and small-molecule portfolios alike.
India
Generic manufacturers are driving volume concentration toward CDSCO-compliant facilities with PIC/S certification and established ANDA submission support. The country's production-linked incentive framework for pharmaceuticals is attracting greenfield investments in continuous manufacturing lines. Maharashtra and Gujarat host the primary supply hubs serving North American and European pharmaceutical sponsors.
Germany
EMA Annex 1 revisions on contamination control strategy are mandating formal risk assessments for non-sterile solid dosage operations. Facilities with existing containment infrastructure are absorbing compliance costs more readily than batch-oriented competitors. The Rhine-Main region concentrates specialized CDMOs commanding capacity premiums for Eudragit-based formulations.
Switzerland
Swissmedic oversight and proximity to European biopharmaceutical sponsors sustain demand for high-containment operations and potent compound handling. Lonza Group AG anchors specialized positions in these segments from Basel-area facilities. The country's regulatory alignment with EMA standards enables seamless Eudragit-based formulation partnerships.
China
NMPA alignment with ICH guidelines is tightening inspection protocols and favoring contract manufacturers with dedicated regulatory affairs infrastructure. Yangtze River Delta facilities are converting batch records to real-time release testing architectures. Shanghai-based campuses serve domestic sponsors and multinational trials requiring GMP manufacturing.
Pharmaceutical Solid Dosage Contract Manufacturing Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the former commanding multi-year capacity reservation agreements and the latter competing on spot-contracting economics. The market structure compresses margins for standalone packaging houses while rewarding integrated process control. Three archetypes dominate: integrated development-through-commercialization partners, high-containment specialists for potent compounds, and cost-optimized scale operators from Indian facilities. Competitive moves concentrate on M&A for regulatory submission capabilities and geographic expansion into CDSCO-compliant jurisdictions.
Among integrated CDMOs, Catalent, Inc. and Lonza Group AG exemplify the development-to-commercialization campus model across multiple continents. Jubilant Pharmova Limited occupies a position within the cost-optimized tier, representing Indian facilities that compete on scale while serving regulated markets. These three anchors illustrate the capability divergence separating preferred supplier tiers from commodity capacity providers.
| Leading Market Players |
|---|
| Catalent, Inc. |
| Lonza Group AG |
| Aenova Group |
| Jubilant Pharmova Limited |
| Patheon Pharma Services |
| Corden Pharma International |
| Boehringer Ingelheim International GmbH |
| Piramal Pharma Solutions |
| Recipharm AB |
| Others |
Value Chain & Pricing Dynamics
FDA current Good Manufacturing Practice enforcement and EMA Annex 1 contamination control mandates simultaneously gate supply qualification and stratify pricing power across contract manufacturing tiers. CDMOs with PIC/S certification and dedicated regulatory affairs infrastructure command capacity premiums while uncertified facilities face exclusion from regulated market procurement panels.
Pricing Analysis
Long-term capacity reservation agreements dominate sponsor-CDMO relationships, displacing transactional spot-contracting as biopharmaceutical procurement teams consolidate vendor panels. Three-tier pricing structure across integrated development partners, high-containment specialists, and commodity scale operators reflects certification grade and real-time release testing capability. Cost compression in immediate-release generic tablet manufacturing intensifies as Indian facilities expand rotary press capacity. Generic manufacturers exhibit highest price sensitivity, while oncology-focused biopharmaceuticals prioritize containment infrastructure over unit economics.
Supply Chain Analysis
API supply concentration across China and India creates single-source vulnerability for critical starting materials in solid dosage manufacturing. Active pharmaceutical ingredient flows from Zhejiang Province and Gujarat State feed granulation and compression operations across North American and European CDMO networks. Export restriction risks on key intermediates threaten batch continuity for sponsors lacking dual-qualified suppliers. Distribution runs through sponsor-managed logistics networks with temperature-validated cold chain segments for moisture-sensitive formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates niche opportunities as continuous manufacturing adoption splits contract manufacturers into integrated campus operators and legacy batch facilities. Orphan drug manufacturing demand and bi-layer tablet formulation partnerships reward specialized capabilities over scale.
For Market Incumbents: Fortify regulatory submission capabilities through dedicated ANDA support teams in CDSCO-compliant jurisdictions. Backward integration into polymer matrix technologies for modified-release platforms defends margin position against emerging extrusion specialists. Capacity expansion in Maharashtra and Gujarat captures generic manufacturer outsourcing surge while PIC/S certification investment maintains European market access.
For New Entrants and Emerging Players: Small-batch flexibility for rare disease indications represents the most penetrable service-layer gap where large-scale CDMOs under-serve. Single-use containment systems for potent compound handling enable geographic proximity strategies near Boston and San Diego biotech clusters. Partnership-based go-to-market models with CROs bundle clinical trial material manufacturing with Phase III scale-up services.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale CDMOs possessing FDA warning letter clearance histories but lacking continuous manufacturing infrastructure. Five-to-ten year viability hinges on conversion to real-time release testing architectures and ICH Q13 compliance. The inflection signal to watch is sponsor migration patterns from batch validation to integrated process analytical technology suites.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Line Investment | FDA and EMA alignment on ICH Q13 favors CDMOs with real-time release testing capabilities. |
| High-Containment Facility Certification | Isolator technology investments capture oncology sponsor demand for potent compound handling. |
| Regulatory Affairs Infrastructure Buildout | Dedicated ANDA submission teams in Indian facilities attract generic manufacturer outsourcing. |
| Bi-Layer Tablet Platform Development | Integration of immediate-release and extended-release strata opens lifecycle management partnerships. |
| Serialization System Deployment | DSCSA and FMD compliance mandates disqualify unequipped competitors from sponsor vendor panels. |
Study Parameters
Operator-level perspectives from regulatory affairs directors, CDMO procurement managers, generic manufacturer supply chain leads, and biopharmaceutical formulation scientists anchored the qualitative base. Primary interview insights combined with secondary validation from FDA Form 483 observations, EMA inspection reports, CDSCO facility registrations, and ANDA submission databases. Bottom-up capacity modeling and top-down sponsor spending analysis triangulated market sizing across the projection horizon.
Sensitivity analysis tested forecast robustness against API supply disruption scenarios and regulatory inspection frequency variations. Segmentation modeling spanned product type, delivery mode, end user category, and technology platform across the analysis window. CAGRs derived from sponsor pipeline data, capacity expansion announcements, and generic filing trends. Continuous manufacturing adoption curves and serialization compliance deadlines served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO enforcement regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as ICH Q13 implementation timelines and geopolitical friction in API trade flows evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Opioids Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Global Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Constipation Laxative Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Global Bone Morphogenetic Protein Market
Pharmaceuticals
Compound Potassium Hydrogen Phosphate Injection Market
Pharmaceuticals
Veterinary Insulin Drugs Market
Pharmaceuticals
Global Benzodiazepines Market
Pharmaceuticals
Inhalable Drug Market
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Asia-Pacific Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Global Acne Medication Market
Pharmaceuticals
Denmark Pharmaceutical Market