
 Piriformis Syndrome Treatment Market | 2026-2036
Piriformis Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Piriformis Syndrome Treatment Market Outlook
A capital-intensity divergence between large pharmaceutical manufacturers and specialized physical therapy device makers is redrawing competitive boundaries in piriformis syndrome care. Bayer AG leverages its established analgesic portfolio to sustain volume leadership across prescription NSAID segments. Omron Healthcare competes through portable TENS and electrotherapy units designed for home-based symptom management.
Piriformis syndrome treatment addresses compression or irritation of the piriformis muscle against the sciatic nerve, typically requiring multimodal intervention combining pharmacological pain control with targeted musculoskeletal rehabilitation. The condition's diagnosis relies on physical examination maneuvers such as the FAIR test combined with imaging exclusion of lumbar disc pathology. Medication and physical therapy segments dominate current revenue, while interventional techniques including botulinum toxin injections and ultrasound-guided hydrodissection represent the fastest-growing margin pool. Outpatient clinics anchor delivery volume, though home care settings are gaining traction as wearable therapeutic devices improve patient compliance.
The FDA oversees neuromodulation device approvals and opioid-containing analgesic labeling, directly shaping product development timelines and commercialization pathways for US market participants. The EMA's MDR framework in Europe imposes additional clinical evidence requirements on implantable pain therapy systems, creating divergent regulatory burdens across Atlantic markets. Stakeholders must monitor reimbursement policy shifts for non-surgical chronic pain interventions as payors recalibrate coverage criteria for conservative versus interventional approaches.
Market Dynamics
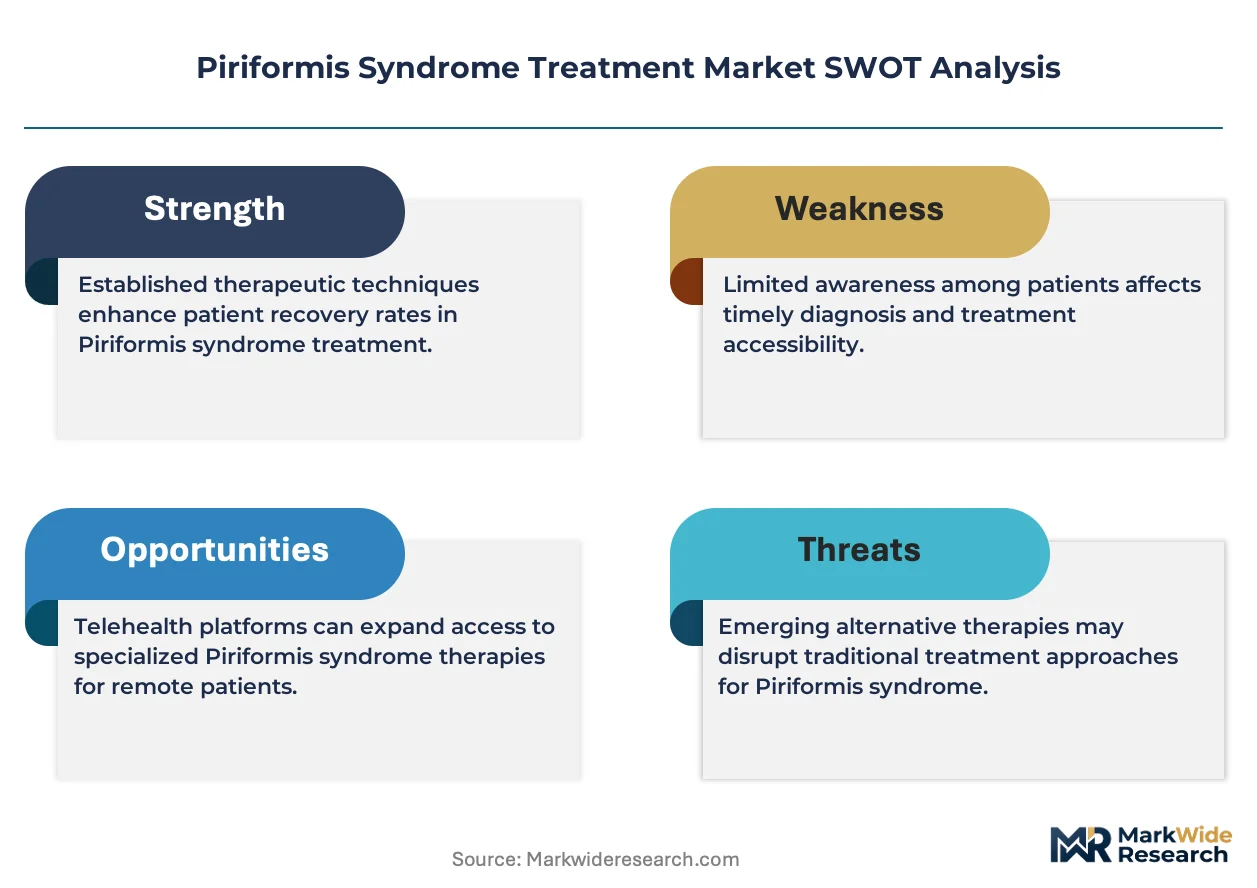
The piriformis syndrome treatment market is reconfiguring around the FDA's evolving stance on implantable neuromodulation devices for chronic pain, which is compressing development timelines for manufacturers while expanding eligible patient populations for interventional therapies.
Growth Catalysts
- Sports Medicine Clinic Expansion:Specialized orthopedic rehabilitation networks across the United States are standardizing multimodal physical therapy protocols that combine manual manipulation with electrotherapy, creating dedicated referral pathways for piriformis syndrome patients.
- MDR Framework Maturation:The European Medicines Agency's Medical Device Regulation is clarifying clinical evidence requirements for implantable pain therapy systems, reducing regulatory uncertainty for manufacturers pursuing CE marking.
- Wearable Therapeutic Convergence:Portable TENS and neuromuscular electrical stimulation devices are integrating with smartphone-based biofeedback applications, enabling home-based symptom management that reduces clinic dependency.
Market Restraints
- Diagnostic Imaging Cost Burden:MRI and ultrasound requirements to exclude lumbar disc pathology impose substantial out-of-pocket costs on patients, particularly in high-deductible insurance plans.
- Botulinum Toxin Supply Concentration:Manufacturing of therapeutic neurotoxins concentrates among a limited pool of biologics producers, creating vulnerability to production disruptions and price volatility.
- Opioid Prescribing Restrictions:State-level prescription drug monitoring programs and CDC guidelines are constraining access to traditional analgesic pathways for chronic musculoskeletal pain.
Strategic Opportunities
- Home Care Channel Penetration:Reimbursement frameworks for remote therapeutic monitoring are expanding coverage for wearable electrotherapy devices prescribed through telehealth consultations.
- Ultrasound-Guided Hydrodissection:Minimally invasive interventional techniques that separate the piriformis muscle from the sciatic nerve using fluid injection are gaining traction among pain management specialists.
- Conservative Care Mandates:Private payors and Medicare Advantage plans are implementing prior authorization requirements that favor physical therapy over surgical intervention for sciatica-like presentations.
Industry Challenges
- Interventional Pain Specialist Shortage:Fellowship-trained physicians capable of performing ultrasound-guided injections and neuromodulation implantation are concentrated in urban academic medical centers.
- Device-Pharma Integration Complexity:Manufacturers combining pharmacological and electrotherapy offerings face divergent regulatory pathways requiring separate quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piriformis Syndrome Treatment Market |
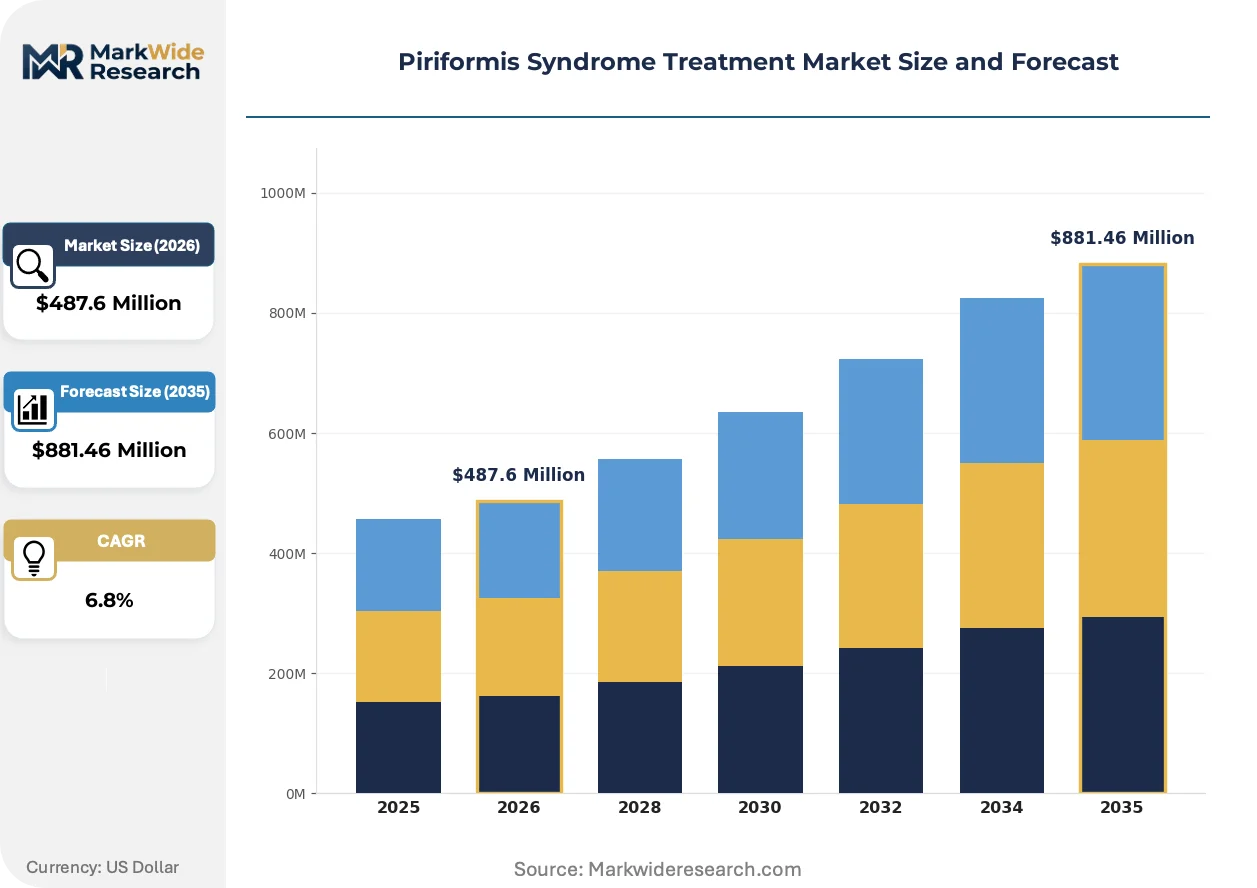
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Physical Therapy, Medication, Surgery, Alternative Therapies Patient Demographics: Athletes, Middle-aged Adults, Seniors, Office Workers Care Setting: Outpatient Clinics, Rehabilitation Centers, Home Care, Hospitals Therapy Approach: Conservative Management, Interventional Techniques, Surgical Intervention, Combined Therapy |
| Companies Covered | Bayer AG, Novartis AG, AstraZeneca, Sanofi, Teva Pharmaceuticals, Endo Pharmaceuticals, Omron Healthcare, DePuy Synthes, Miracle Stretch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piriformis Syndrome Treatment Market Strategic Shifts
Neuromodulation hardware miniaturization and algorithm-driven personalization are converging to reshape how chronic piriformis syndrome is managed outside traditional clinical settings, with implications for device economics and patient adherence.
High-frequency spinal cord stimulation systems are supplanting conventional low-frequency tonic stimulation for chronic neuropathic pain presentations. Pain management physicians in academic medical centers are adopting these platforms at accelerating rates. The technology is compressing market share for legacy implantable pulse generators while expanding addressable populations to include patients with complex regional pain syndrome comorbidities.
EMA's Medical Device Regulation is tightening post-market surveillance requirements for implantable neuromodulation systems. Manufacturers must now submit periodic safety update reports and maintain European-based authorized representatives. The MDR framework is most affecting small-to-mid cap device developers without established European regulatory infrastructure, forcing partnerships or market exits.
Patients are initiating care pathways through direct-to-consumer telehealth platforms rather than primary care referrals. Virtual musculoskeletal specialists are conducting FAIR test demonstrations via video consultation and prescribing home-based electrotherapy trials. This channel shift is most visible in United States markets with high smartphone penetration and permissive interstate telehealth licensing.
Piriformis Syndrome Treatment Market Segmentation
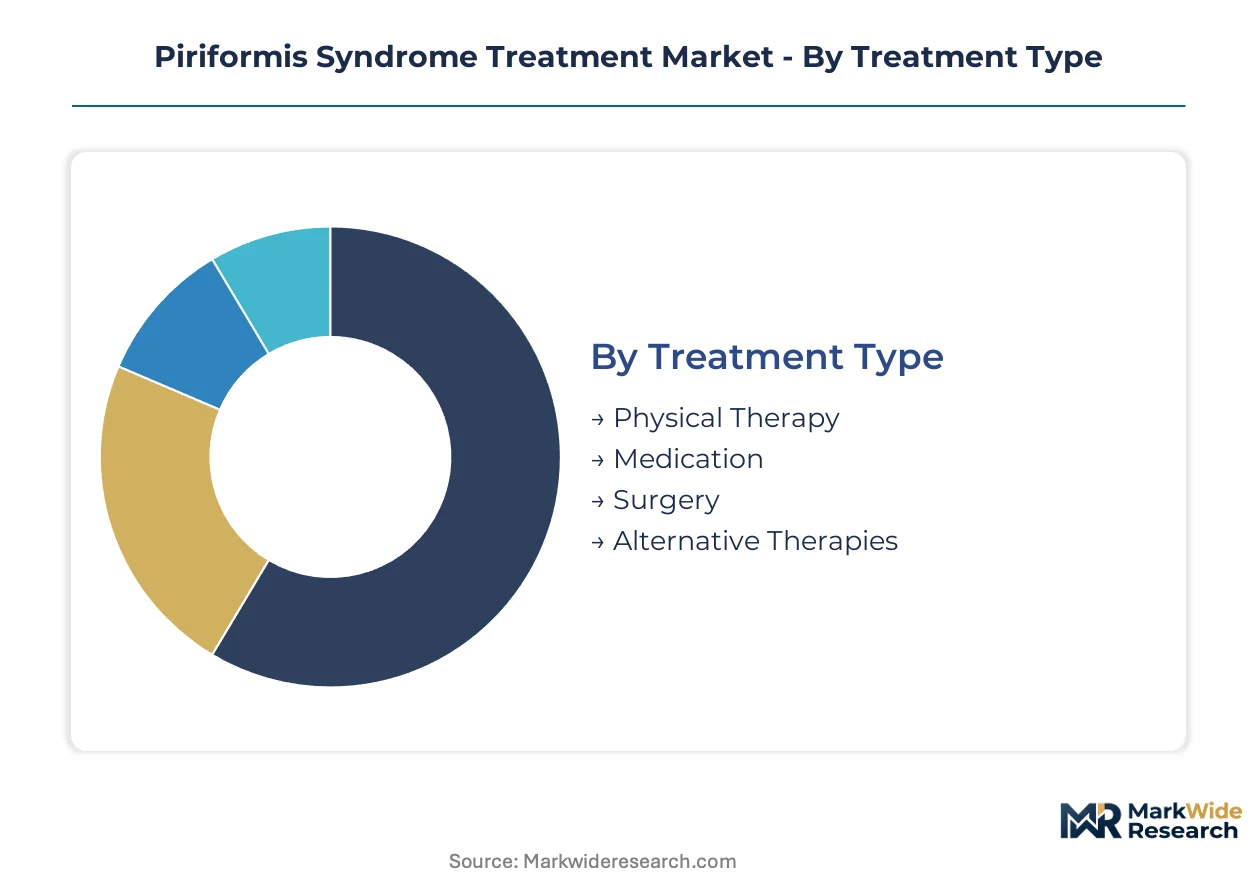
Piriformis syndrome treatment spans divergent clinical pathways where reimbursement policy and patient acuity determine segment profitability. Understanding how margin pools distribute across modalities reveals where manufacturers and providers are repositioning resources.
Treatment Type:
Margin concentration favors interventional and pharmacological approaches over labor-intensive physical therapy, though volume leadership remains with conservative modalities.
- Medication:NSAIDs, muscle relaxants, and neuropathic pain agents constitute the prescription volume anchor. United States demand concentrates in Medicare Part D formularies where prior authorization requirements favor generic analgesics over branded alternatives, compressing manufacturer margins while sustaining pharmacy benefit manager rebates.
- Physical Therapy:Manual manipulation protocols, stretching regimens, and electrotherapy modalities require high clinician time investment per episode. Sports medicine clinics in California and Texas are standardizing multimodal protocols that bundle TENS units with supervised exercise, creating subscription-like revenue streams that offset fee-for-service compression.
- Surgery:Piriformis release and sciatic nerve decompression procedures carry the highest per-case reimbursement but represent under 5% of diagnosed cases due to conservative care mandates.
- Alternative Therapies:Acupuncture, dry needling, and chiropractic adjustment serve patients seeking opioid alternatives outside conventional medical channels.
The dominant share belongs to Medication, while Physical Therapy is closing the gap fastest through bundled care models and wearable device integration.
Patient Demographics:
Volume distribution tracks occupational risk exposure and age-related musculoskeletal degeneration patterns across working-age populations.
- Athletes:Runners, cyclists, and hockey players present with acute piriformis irritation from repetitive hip rotation. NCAA sports medicine programs and professional team physicians drive protocol standardization, with demand clustering in Florida, Arizona, and Colorado training facilities where year-round athletic activity concentrates.
- Office Workers:Prolonged sitting and poor ergonomic positioning generate chronic piriformis compression. Corporate wellness contracts in Seattle, Austin, and Raleigh-Durham are embedding musculoskeletal screening into benefits packages, expanding addressable populations beyond traditional clinical referrals.
- Middle-aged Adults:Degenerative changes combined with sustained physical activity create overlapping diagnostic presentations with lumbar spine pathology.
- Seniors:Fall risk and polypharmacy concerns push treatment toward conservative modalities, though Medicare Advantage plans are expanding home-based physical therapy authorization.
Athletes command premium pricing for expedited return-to-play protocols, yet Office Workers represent the steepest expansion trajectory as employer-sponsored musculoskeletal benefits proliferate.
Care Setting:
Reimbursement arbitrage between facility-based and home-based delivery is reallocating capital toward remote monitoring infrastructure.
- Outpatient Clinics:Independent pain management practices and orthopedic urgent care centers anchor diagnostic volume. Cleveland Clinic, Mayo Clinic, and specialized spine centers in Philadelphia have developed dedicated piriformis syndrome pathways that combine ultrasound-guided injection with same-day physical therapy evaluation.
- Home Care:Wearable TENS devices, smartphone-guided exercise applications, and telehealth follow-up are displacing clinic-dependent episodes. FDA-cleared prescription electrotherapy units with remote compliance monitoring qualify for remote therapeutic monitoring codes, enabling physician practices to bill for asynchronous patient management.
- Rehabilitation Centers:Post-acute facilities focus on complex cases with comorbid lumbar pathology requiring coordinated multidisciplinary care.
- Hospitals:Inpatient admission is rare, limited to post-surgical recovery or severe neurological compromise requiring neurosurgical consultation.
Outpatient Clinics retain the dominant patient share, though Home Care is gaining ground fastest as FDA-cleared wearable devices expand reimbursable remote monitoring.
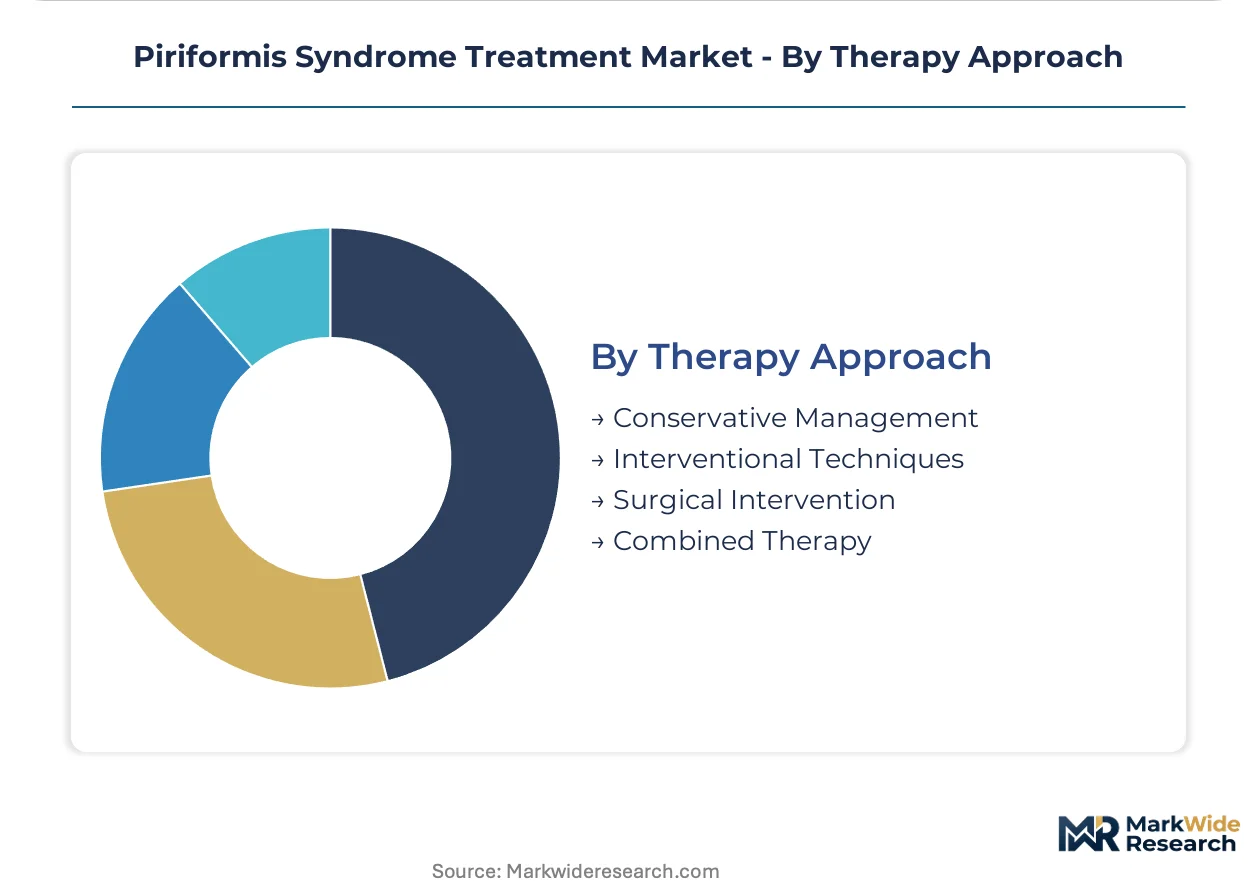
Therapy Approach:
Clinical decision pathways increasingly stratify patients by response to conservative measures before authorizing interventional or surgical escalation.
- Conservative Management:Activity modification, physical therapy, and oral pharmacotherapy constitute the mandatory first-line approach under most commercial and Medicare Advantage protocols. UnitedHealthcare, Aetna, and Cigna have implemented 6-12 week conservative care requirements before approving advanced imaging or interventional procedures, embedding this segment into utilization management infrastructure.
- Interventional Techniques:Ultrasound-guided corticosteroid injection, botulinum toxin chemodenervation, and hydrodissection procedures serve patients failing conservative measures. Fellowship-trained pain physicians at academic medical centers in Boston, Baltimore, and Houston are adopting hydrodissection protocols that separate piriformis from sciatic nerve using dextrose or saline injection, creating procedure-specific reimbursement codes.
- Combined Therapy:Simultaneous pharmacological, physical, and interventional intervention for complex presentations.
- Surgical Intervention:Reserved for refractory cases with confirmed anatomical entrapment and failed 6+ month conservative trials.
Conservative Management holds the dominant position by payer mandate, while Interventional Techniques are climbing fastest as ultrasound-guided procedures demonstrate durable outcomes in academic center cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States favoring interventional pain procedures while European markets emphasize conservative rehabilitation protocols and Japan prioritizes device-based home care solutions.
United States
Specialized orthopedic rehabilitation networks in Florida, Arizona, and Colorado drive protocol standardization for athletes and office workers alike. The FDA maintains active evaluation pathways for novel neuromodulation devices targeting chronic pain indications. Cleveland Clinic and Mayo Clinic anchor dedicated piriformis syndrome treatment pathways that combine ultrasound-guided injection with same-day physical therapy evaluation.
Germany
Industrial occupational health programs and aging workforce demographics sustain demand for conservative musculoskeletal interventions. The EMA's MDR framework imposes stringent clinical evidence requirements on implantable pain therapy systems seeking CE marking. Pain management specialists in Bavaria and North Rhine-Westphalia are adopting ultrasound-guided hydrodissection techniques for refractory cases.
Japan
Metropolitan aging populations and high smartphone penetration accelerate adoption of wearable therapeutic devices for home-based symptom management. METI oversees medical device quality standards while PMDA evaluates novel electrotherapy platforms. Tokyo and Osaka medical centers are integrating portable TENS units with smartphone-based biofeedback applications.
United Kingdom
NHS cost-containment pressures and conservative care mandates favor physical therapy over surgical intervention for sciatica-like presentations. The MHRA aligns with EMA MDR requirements for implantable neuromodulation systems post-Brexit. London and Manchester sports medicine clinics are standardizing multimodal protocols that bundle electrotherapy with supervised exercise programs.
India
Rising corporate wellness adoption and expanding private hospital networks create addressable populations beyond traditional clinical referrals. CDSCO regulates pharmaceutical analgesics and medical devices under consolidated frameworks. Maharashtra and Karnataka are witnessing proliferation of specialized pain management centers offering botulinum toxin interventions.
Piriformis Syndrome Treatment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical conglomerates controlling analgesic volume and dedicated device manufacturers capturing margin in electrotherapy segments. The competitive terrain separates into three archetypes: diversified pharmaceutical conglomerates with established pain portfolios, specialized electrotherapy device makers, and interventional pain technology developers. M&A activity concentrates on neuromodulation platform acquisitions, while portfolio diversification moves emphasize combining pharmacological and device-based offerings under single commercial umbrellas.
Among diversified pharmaceutical conglomerates, Bayer AG and Novartis AG exemplify the integrated leader archetype, leveraging established analgesic portfolios to sustain volume leadership across prescription NSAID and neuropathic pain agent segments. Omron Healthcare occupies a distinct position within the specialized device tier, competing through portable TENS and electrotherapy units designed for home-based symptom management. These three companies collectively represent the competitive spectrum spanning pharmaceutical, device, and convergent therapeutic approaches.
| Leading Market Players |
|---|
| Bayer AG |
| Novartis AG |
| AstraZeneca |
| Sanofi |
| Teva Pharmaceuticals |
| Endo Pharmaceuticals |
| Omron Healthcare |
| DePuy Synthes |
| Miracle Stretch |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation agreements with botulinum toxin manufacturers lock in supply access and price visibility for pain management practices facing volatile biologics procurement. These contracts tether clinic margins to fermentation batch yields while insulating against spot-market volatility in neurotoxin supply.
Pricing Analysis
After-sales service contracts for wearable electrotherapy devices drive lifetime value through subscription-based firmware updates and remote monitoring tiers. Pricing stratifies across premium prescription-grade units with FDA-cleared remote therapeutic monitoring codes, standard direct-to-consumer TENS devices, and economy-tier unregulated mass-market alternatives. Cost compression in the economy tier stems from Asian manufacturing scale and commoditized electrode technology. Corporate wellness buyers exhibit lowest price sensitivity due to bundled benefits accounting, while uninsured direct-pay patients in high-deductible plans face acute affordability constraints.
Supply Chain Analysis
Port congestion along the Shanghai-Los Angeles trade lane elevates inbound logistics costs for electrode components and microprocessor assemblies sourced from East Asian contract manufacturers. Manufacturing concentrates in China, South Korea, and Malaysia for portable electrotherapy hardware, while pharmaceutical APIs for muscle relaxants and neuropathic agents draw from Indian and Swiss chemical synthesis facilities. Single-source vulnerability concentrates in therapeutic neurotoxin fermentation capacity, where manufacturing expertise clusters among a handful of European biologics specialists. Distribution runs through specialized medical device distributors and direct-to-consumer e-commerce channels with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as telehealth licensing proliferation and wearable device reimbursement create niches outside established orthopedic networks. Demand-side shift toward home-based symptom management splinters traditional clinic-centric care pathways.
For Market Incumbents: Secure formulary positioning for combination pharmacotherapy-device bundles before Medicare Advantage plans finalize conservative care mandates. Incumbents must deepen backward integration into electrode manufacturing to offset Asian supply chain exposure and defend margin position against low-cost electrotherapy imports. FDA 510(k) pathway expertise remains the critical lever for maintaining regulatory moats. For New Entrants and Emerging Players: Anchor in employer-sponsored musculoskeletal benefits programs where prior authorization requirements favor novel conservative modalities over surgical alternatives. The most penetrable white space sits in smartphone-integrated biofeedback platforms for office worker populations in Austin, Seattle, and Raleigh-Durham corporate campuses. A direct-to-telehealth go-to-market angle bypasses entrenched orthopedic referral networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electrotherapy device manufacturers with remote monitoring subscription attach rates. Long-term viability hinges on reimbursement durability for remote therapeutic monitoring codes across the analysis window. Acquisition targets should demonstrate established hospital system partnerships and FDA-cleared prescription device portfolios. The signal to watch is CMS National Coverage Determination revisions for non-surgical chronic pain interventions.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy Development | Securing remote therapeutic monitoring codes from CMS unlocks physician billing for asynchronous patient management. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic pathways demonstrate how academic anchor institutions standardize multimodal protocols. |
| Software Companion Development | Smartphone biofeedback integration differentiates prescription electrotherapy from commoditized direct-to-consumer alternatives. |
| CE Marking Pathway | EMA MDR compliance for implantable neuromodulation systems opens European addressable populations beyond US concentration. |
| FDA Submission | 510(k) clearance for high-frequency spinal cord stimulation platforms expands eligible patient populations for interventional pain specialists. |
Study Parameters
The analysis maps medication, physical therapy, interventional techniques, and surgical intervention segments, each validated through pain management physicians, biomedical engineers, hospital purchasing committees, and GPO contracts managers. Primary interview findings triangulate against FDA 510(k) filings, CMS Medicare data, EMA MDR submissions, and hospital procurement databases. Secondary validation draws from clinical trial registries and payer formulary documentation. Bottom-up patient volume estimates reconcile with top-down market value assessments across modeling approaches.
Consistency checks validate volume and value outputs against external benchmarks including academic medical center procedure databases and commercial claims analytics. The forecast framework segments by treatment type, patient demographic, care setting, and therapy approach across the projection horizon. CAGRs derive from modeled patient incidence, procedure penetration rates, and average revenue per episode assumptions. Ultrasound-guided hydrodissection adoption curves and wearable device compliance rates constitute key industry-specific forecast inputs.
Material uncertainties — regulatory rejection of novel neuromodulation indications, botulinum toxin supply disruptions, and telehealth licensing reversals — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and conservative care mandate durability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Progressive Multifocal Leukoencephalopathy Treatment Market
Specialty Medicine
Anal Cancer Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Parathyroid Disorders Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Hepatic Encephalopathy Treatment Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Pleurodynia Treatment Market
Specialty Medicine
Global Targeted Cancer Therapy Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Amino Acid Metabolism Disorders Treatment Market