
 Arterial Blood Collection Market | 2026-2036
Arterial Blood Collection Market Size, Share, and Industry Trends Forecast 2026-2036
Arterial Blood Collection Market Outlook
Chinese polymer suppliers is decoupling from Western resin pricing, forcing arterial blood collection device makers to redraw raw material sourcing maps. Becton Dickinson and Company leverages captive needle manufacturing to sustain margin stability across its syringe and catheter lines. Thermo Fisher Scientific anchors its position through R&D intensity in automated collection systems. Greiner Bio-One competes on specialized blood collection tubes engineered for precise gas analysis.
Arterial blood collection encompasses the sterile extraction of oxygenated blood from radial, brachial, or femoral arteries using puncture devices or indwelling catheters, with samples typically analyzed for pH, partial pressure of oxygen, and partial pressure of carbon dioxide within minutes to guide ventilator management and acid-base correction. Blood collection tubes designed for gas analysis command premium positioning due to heparin coating requirements and minimal dead-space engineering that prevents clot formation and sample degradation. Hospitals remain the dominant end user, though point-of-care devices are gaining procedural share as bedside testing protocols shorten turnaround times for critical care decisions. Safety mechanisms represent the fastest-growing technology segment as needlestick injury prevention becomes a non-negotiable procurement criterion.
FDA 510(k) clearance pathways and OSHA Bloodborne Pathogens standards jointly determine market access for new arterial collection devices in the United States, while ISO 13485 certification governs quality management for suppliers seeking multi-country distribution. The EU MDR transition is extending conformity assessment timelines for manufacturers targeting European hospitals, compressing near-term launch windows. Stakeholders must monitor how automated collection systems reshape staffing models in intensive care units and whether reimbursement shifts favor capital equipment over disposable volumes.
Market Dynamics
FDA's sharpened focus on sharps injury prevention is forcing arterial blood collection device manufacturers to redesign safety mechanisms before 510(k) clearance, while Chinese polymer suppliers decouple from Western resin pricing and force raw material sourcing redraws.
Growth Catalysts
- OSHA Bloodborne Pathogens compliance mandates:Hospital procurement committees now require retractable safety needles as standard, eliminating non-compliant suppliers from vendor lists.
- Critical care unit expansion:Hospital-based ICUs are multiplying arterial line placements for continuous blood gas monitoring in ventilated patients.
- Point-of-care testing protocols:Bedside analyzers are shortening turnaround times for acid-base decisions, pulling collection devices closer to patient rooms.
Market Restraints
- Specialized polymer input volatility:Medical-grade polypropylene and polycarbonate prices fluctuate with Chinese export quota adjustments.
- Heparin coating supply concentration:Anticoagulant coating chemistry relies on a narrow supplier base in Asian manufacturing clusters.
- EU MDR conformity compression:Extended assessment timelines for Class IIa devices delay European hospital launches by 12-18 months.
Strategic Opportunities
- Automated collection system penetration:R&D investment in robotics-assisted arterial sampling targets staffing shortages in US intensive care units.
- Home-based respiratory monitoring:Portable arterialized capillary devices open ambulatory chronic obstructive pulmonary disease management.
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract catheter and safety needle assembly operations.
Industry Challenges
- ISO 13485 certification bottlenecks:Quality management system audits face auditor availability constraints, slowing multi-country distribution readiness.
- Legacy EMR integration friction:Automated collection systems require HL7 FHIR compatibility investments that strain mid-tier hospital IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arterial Blood Collection Market |
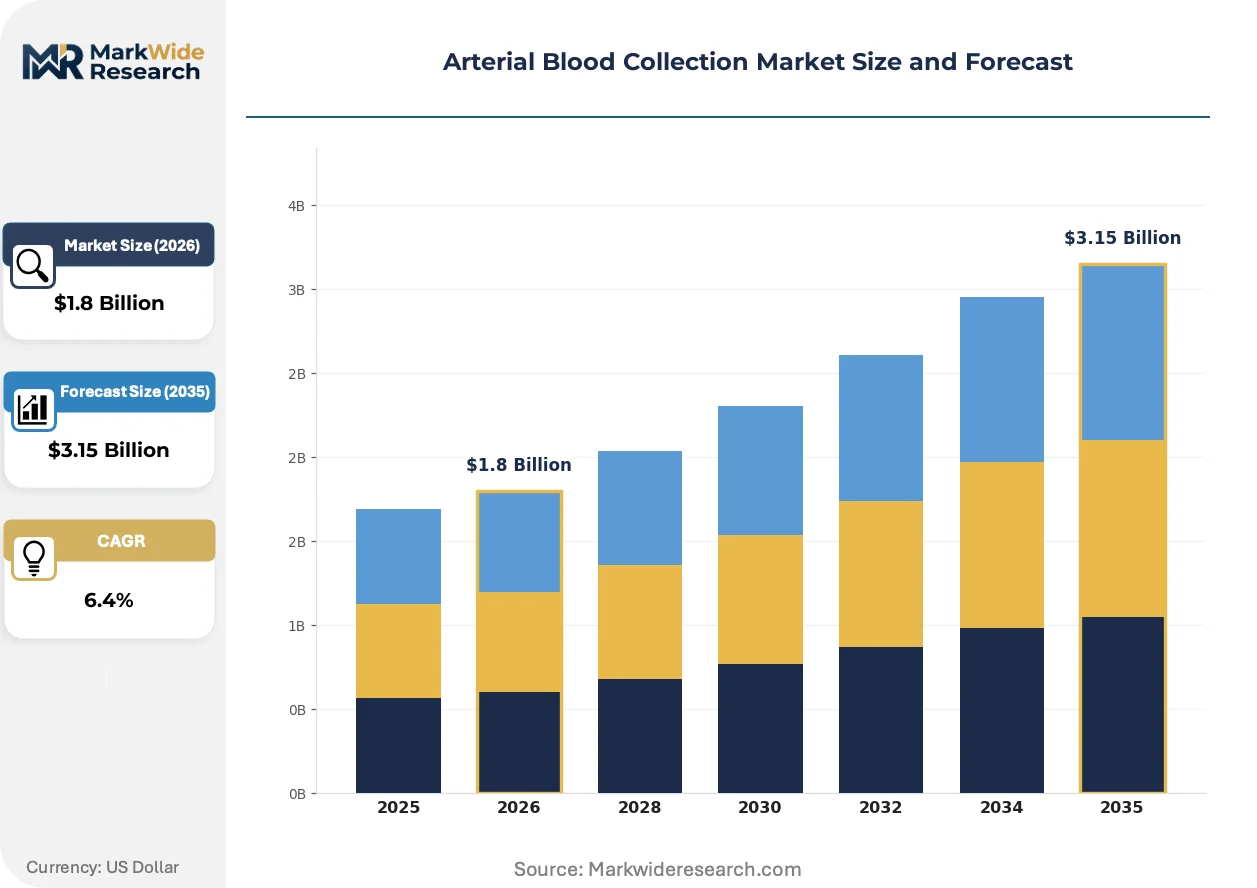
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syringes, Needle Sets, Catheters, Blood Collection Tubes End User: Hospitals, Diagnostic Laboratories, Blood Banks, Research Institutes Application: Diagnostic Testing, Blood Gas Analysis, Transfusion Services, Clinical Trials Technology: Manual Collection, Automated Systems, Point-of-Care Devices, Safety Mechanisms |
| Companies Covered | Becton Dickinson and Company, Thermo Fisher Scientific, Terumo Corporation, Cardinal Health, Greiner Bio-One, Medtronic plc, Sekisui Medical, Sarstedt AG & Co, Narang Medical Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arterial Blood Collection Market Strategic Shifts
Arterial blood collection is pivoting from manual puncture toward integrated safety-engineered systems that compress procedural variation and reduce occupational exposure liability.
Passive safety needle technology is electrifying device design by eliminating activation steps that clinicians sometimes skip under time pressure. Emergency departments and rapid-response teams are adopting these mechanisms fastest. The technology is electrifying competitive differentiation as safety performance becomes a non-negotiable procurement criterion.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for manufacturers targeting European hospitals. Notified body capacity constraints compress near-term launch windows. Class IIa arterial collection devices face the steepest documentation burden, pushing some suppliers toward US-first regulatory strategies.
Buyer committees are consolidating vendor relationships around full-line suppliers who bundle arterial syringes, safety needles, and gas-analysis tubes under single-source contracts. Group purchasing organizations are displacing individual hospital negotiations in the United States. This concentration is most visible in multi-hospital health systems seeking procurement efficiency.
Arterial Blood Collection Market Segmentation
Arterial blood collection devices fragment across four dimensions that determine procurement logic: capital equipment versus disposables, acute care versus ambulatory settings, laboratory versus bedside workflows, and manual versus automated handling protocols. Each segmentation axis carries distinct margin profiles and regulatory pathways that reshape vendor positioning.
Product Type:
Capital intensity concentrates in catheter manufacturing, where extrusion tolerances and heparin coating chemistry demand specialized polymer processing infrastructure.
- Syringes:Polypropylene barrel construction with Luer-lock compatibility dominates ICU procurement. US hospital systems specify retractable safety mechanisms as mandatory, eliminating non-compliant suppliers from multi-year vendor contracts.
- Needle Sets:Stainless steel cannula production integrates passive safety activation to prevent needlestick injuries. Emergency departments and rapid-response teams drive fastest uptake of single-handed deployment designs.
- Catheters:Radiopaque polyurethane construction with integrated pressure transducer ports commands premium positioning in continuous monitoring applications.
- Blood Collection Tubes:Minimal dead-space engineering with lithium heparin coating prevents clot formation during gas analysis transport.
Most installed capacity flows through Syringes. Expansion is steepest in Catheters as continuous arterial line placements multiply in ventilated patient populations.
End User:
Customer concentration patterns separate high-volume acute care purchasers from specialized reference laboratories with distinct technical specifications.
- Hospitals:Critical care units and emergency departments generate procedural volume through arterial line maintenance and acute respiratory failure management. Group purchasing organizations consolidate vendor relationships around full-line suppliers bundling syringes, needles, and gas-analysis tubes.
- Diagnostic Laboratories:Centralized processing facilities demand standardized tube specifications for automated analyzer compatibility. ISO 15189 accreditation requirements drive quality system investments.
- Blood Banks:Arterial sampling for donor screening represents niche volume with specialized anticoagulant protocol requirements.
- Research Institutes:Clinical trial applications require lot traceability and documentation exceeding standard clinical procurement.
Procurement volume concentrates in Hospitals. Research Institutes show steepest expansion as interventional cardiology trials multiply arterial access requirements.
Application:
Workflow differentiation separates time-critical bedside decisions from batch-processed laboratory confirmations.
- Diagnostic Testing:Broad-spectrum metabolic panels and coagulation studies utilize arterial access when venous sampling proves inadequate. Hospital laboratories process these through automated analyzer lines with standardized tube specifications.
- Blood Gas Analysis:pH, PaO2, and PaCO2 measurements guide ventilator adjustments within minutes of collection. Point-of-care devices are displacing central laboratory processing in ICU settings.
- Transfusion Services:Arterial sampling supports massive transfusion protocol monitoring in trauma resuscitation.
- Clinical Trials:Protocol-mandated arterial access for pharmacokinetic sampling drives specialized collection device procurement.
Procedural volume flows through Diagnostic Testing. Blood Gas Analysis expands most quickly as bedside analyzer deployment accelerates turnaround time competition.
Technology:
Automation intensity separates labor-dependent manual protocols from capital-intensive robotic systems with divergent staffing implications.
- Manual Collection:Operator-dependent radial artery puncture remains standard in emergency and critical care settings. OSHA Bloodborne Pathogens compliance now mandates retractable safety needles as baseline procurement.
- Automated Systems:Robotics-assisted arterial sampling targets staffing shortages in US intensive care units. HL7 FHIR compatibility requirements strain mid-tier hospital IT integration budgets.
- Point-of-Care Devices:Portable analyzers compress turnaround times for acid-base decisions. Capillary arterialized devices enable ambulatory chronic obstructive pulmonary disease management.
- Safety Mechanisms:Passive activation technology eliminates skipped steps under time pressure. FDA 510(k) clearance pathways sharpen design requirements for sharps injury prevention.
Installed base concentrates in Manual Collection. Safety Mechanisms gain share fastest as needlestick liability reshapes procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains larger procedure volumes than Germany, yet both markets face tightening safety regulations that reshape procurement criteria for arterial collection devices.
United States
Critical care units in Texas and Florida are multiplying arterial line placements for ventilated patients. OSHA Bloodborne Pathogens standards now mandate retractable safety needles as baseline hospital procurement. Boston's medical device cluster concentrates R&D investment in passive safety activation systems.
Germany
Baden-Württemberg's hospital networks standardize gas-analysis tube specifications for automated laboratory compatibility. EU MDR Article 10 technical documentation requirements extend conformity assessment timelines for Class IIa devices. Bavaria's catheter manufacturers face compressed launch windows as notified body capacity constraints intensify.
China
Shanghai and Beijing hospitals are expanding point-of-care analyzer deployment for bedside blood gas decisions. NMPA medical device registration pathways are tightening quality system requirements for imported collection devices. Jiangsu province's polymer processing clusters are decoupling from Western resin pricing benchmarks.
India
Maharashtra's tertiary care centers are adopting safety-engineered needles to reduce needlestick injury liability. CDSCO medical device rules and PLI scheme incentives jointly attract catheter assembly operations to domestic manufacturing zones. Gujarat's emerging device parks host initial safety needle production lines.
Japan
Tokyo's academic medical centers pioneer robotics-assisted arterial sampling to address intensive care staffing shortages. PMDA quality management system inspections enforce ISO 13485 certification rigor for market access. Osaka's precision manufacturing base supplies radiopaque catheter components across Asia-Pacific.
Arterial Blood Collection Market Competitive Environment
United States producers anchor one tier; Japanese and German specialists hold differentiated positions in safety-engineered and precision-manufactured segments. The vendor base separates into three strategic archetypes: integrated medical device conglomerates with captive needle manufacturing, specialized blood collection system developers, and regional catheter fabricators with polymer processing expertise. Competitive moves concentrate on portfolio diversification into automated collection systems and backward integration into medical-grade polymer compounding.
Among integrated conglomerates, Becton Dickinson and Company exemplifies the captive manufacturing archetype through in-house needle production. Thermo Fisher Scientific occupies a position emphasizing R&D intensity in automated systems. Greiner Bio-One represents specialized engineering focused on precision tube specifications for gas analysis applications.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Thermo Fisher Scientific |
| Terumo Corporation |
| Cardinal Health |
| Greiner Bio-One |
| Medtronic plc |
| Sekisui Medical |
| Sarstedt AG & Co |
| Narang Medical Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive needle manufacturing by integrated conglomerates anchors both supply security and premium pricing power in arterial blood collection, insulating syringe and catheter lines from raw material volatility that pressures standalone device assemblers. This backward integration into stainless steel cannula production concentrates margin control among US and Japanese producers while forcing mid-tier competitors toward contract manufacturing arrangements with thinner pricing leverage.
Pricing Analysis
Capacity additions in China's Jiangsu polymer processing clusters are reshaping price floors for medical-grade polypropylene barrels, compressing margins for syringe manufacturers dependent on Western resin benchmarks. Three-tier pricing structure across premium safety-engineered, standard OSHA-compliant, and economy non-retractable levels separates Becton Dickinson's passive activation systems from private-label alternatives. Cost compression in standard syringe tiers intensifies because Chinese suppliers decoupled from Western pricing. Group purchasing organizations demonstrate highest price sensitivity, while academic medical centers prioritize safety performance over unit economics.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai to Los Angeles strains just-in-time inventory models for heparin-coated collection tubes, forcing hospitals toward quarterly blanket orders with built-in price adjustment clauses. Raw material dependencies draw from German polycarbonate for transparent barrel construction, Japanese stainless steel for cannula stock, and Chinese lithium heparin for anticoagulant coatings. Single-source vulnerability concentrates in Asian coating chemistry suppliers, where export quota adjustments disrupt anticoagulant availability. Distribution runs through Cardinal Health and McKesson medical-surgical divisions to hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arterial blood collection market reads as a late-cycle quality story where ICU expansion and OSHA compliance mandates shift procurement toward premium safety-engineered devices with validated needlestick prevention. This demand migration favors suppliers with captive manufacturing and regulatory clearance depth over price-competitive assemblers.
For Market Incumbents: Anticipate margin compression in standard syringe tiers by accelerating FDA 510(k) submissions for passive safety mechanisms that command premium positioning. Consolidate catheter manufacturing through acquisition of specialized polymer extrusion facilities to secure heparin coating supply chains against Asian export restrictions. For New Entrants and Emerging Players: Capture the India domestic manufacturing opportunity created by PLI scheme incentives and CDSCO regulatory streamlining for safety needle assembly. Target Maharashtra and Gujarat tertiary care centers with localized production cost advantages against imported devices, leveraging distributor partnerships with regional hospital networks. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap safety needle specialists because EU MDR conformity assessment bottlenecks extend European launch timelines and strand smaller manufacturers without notified body relationships. Monitor FDA 510(k) clearance velocity as the inflection signal for automated collection system viability, where robotics-assisted arterial sampling addresses documented ICU staffing shortages.| Strategic Initiative | Industry Significance |
|---|---|
| Passive Safety Needle Development | FDA 510(k) clearance for activation-free designs eliminates clinician error under emergency pressure. |
| Backward Integration into Polymer Compounding | Captive medical-grade polypropylene production insulates margins from Chinese export quota volatility. |
| Point-of-Care Analyzer Partnership | Bedside blood gas device bundling pulls arterial collection devices closer to patient rooms. |
| EU MDR Notified Body Relationship | Secured conformity assessment capacity decompresses Class IIa device launch timelines for European hospitals. |
| HL7 FHIR Compatibility Investment | Automated collection system integration with Epic and Cerner EMR platforms unlocks health system procurement. |
Study Parameters
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market's hospital procurement landscape. The research combined structured interviews with critical care physicians, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at device manufacturers with secondary validation through FDA 510(k) databases, OSHA injury reporting systems, EU MDR notified body registers, and hospital procurement contract filings. Bottom-up procedure volume estimates triangulated against top-down device shipment data from customs records and distributor disclosures.
Rate-of-change decomposition across the analysis window separated volume growth from price-mix effects in arterial blood gas analysis applications. The analytical framework modeled segmentation dimensions including product type, end user facility tier, manual versus automated handling protocol, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for safety mechanism adoption, adjusted for EU MDR transition delays and India's PLI scheme capacity buildout assumptions.
Underlying measurement precision varies by segment; blood gas analysis applications carry tighter precision than research institute volumes where clinical trial sponsorship fluctuates unpredictably. Forecasts reflect assumptions about OSHA enforcement continuity, Chinese polymer export policy stability, and ICU staffing shortage severity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Europe Surgical Glue Market
Medical Supplies
Surgical and Examination Gloves Market
Medical Supplies
Safety Box for Syringe Market
Medical Supplies
Face Mask Market
Medical Supplies
Breast Shells Market
Medical Supplies
Global Biohazard Bag Market
Medical Supplies
Platelet and Plasma Market
Medical Supplies
Venipuncture Needles and Syringes Market
Medical Supplies
Healthcare Cleanroom Consumables Market
Medical Supplies
Global Urinary Drainage Bags Market
Medical Supplies
Enteral Syringes Market
Medical Supplies
Intranasal Splints Market
Medical Supplies
Global Hypodermic Needles Market
Medical Supplies
Sterile Container Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Hydrocolloid Sponges Market