
 Middle Ear Infection Treatment Market | 2026-2036
Middle Ear Infection Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle Ear Infection Treatment Market Insights
The EU Green Deal is restructuring procurement criteria for antimicrobial agents across European hospital networks, favoring suppliers with verified sustainable manufacturing audits. Pfizer Inc. leverages its vertically integrated active pharmaceutical ingredient network to secure preferential tender access in Germany and France. Johnson & Johnson sustains competitive positioning through its broad-spectrum analgesic portfolio calibrated for pediatric pain management protocols. GlaxoSmithKline plc anchors European market presence via specialized otic suspension formulations that meet EMA's tightened environmental risk assessment standards.
Middle ear infection treatment encompasses pharmacological and procedural interventions targeting acute otitis media, otitis media with effusion, and chronic suppurative conditions, with antibiotic suspensions typically formulated at specific mg-per-kg body weight concentrations for tympanic membrane penetration. The primary purpose centers on eradicating bacterial pathogens, reducing tympanic cavity inflammation, and preventing conductive hearing loss sequelae in pediatric populations. Antibiotics dominate current prescribing volumes, though analgesics capture disproportionate margin pools due to over-the-counter accessibility and recurrent purchase patterns across household medicine cabinets. The delivery mode landscape tilts toward oral suspensions in pediatric settings, while topical otic drops gain traction in outpatient clinics seeking to minimize systemic exposure and antibiotic stewardship penalties.
FDA pediatric exclusivity provisions and EMA's pediatric investigation plans jointly shape clinical trial investment priorities, compelling sponsors to generate age-stratified efficacy data before market authorization. REACH chemical safety protocols and EPA pharmaceutical effluent guidelines further constrain formulation chemistry choices, particularly for corticosteroid combinations with environmental persistence profiles. Stakeholders must monitor evolving reimbursement thresholds for watchful waiting versus immediate antibiotic intervention, as health technology assessments in major markets recalibrate cost-effectiveness benchmarks for recurrent infection protocols.
Market Dynamics
Pediatric ambulatory surgical centers are consolidating tympanostomy procedure volumes into high-throughput networks, compressing procurement cycles for antibiotic suspensions and analgesic formulations while elevating formulary standardization requirements.
Growth Catalysts
- FDA Pediatric Exclusivity Program:The incentive structure accelerates age-appropriate formulation development by granting extended market protection to sponsors generating stratified pediatric efficacy data.
- Rapid Diagnostic Protocols:Acute otitis media point-of-care testing in outpatient clinics is reducing watchful waiting delays and accelerating appropriate antibiotic initiation.
- EU Green Deal Procurement Criteria:Sustainable manufacturing audits are becoming mandatory filters for antimicrobial supplier qualification across German and French hospital networks.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient production for macrolide antibiotics clusters in specific Asian manufacturing zones, exposing formulators to single-source disruption risk.
- REACH Environmental Persistence Standards:Corticosteroid combination therapies face reformulation mandates due to tightened aquatic toxicity thresholds under ECHA protocols.
- Systemic Antibiotic Substitution:Topical otic drops are capturing pediatric cases previously managed with oral suspensions, compressing volume for traditional oral antibiotic manufacturers.
Strategic Opportunities
- EMA Pediatric Investigation Plans:Early engagement with the mandated development framework secures priority review pathways for novel otic suspension delivery mechanisms.
- Ambulatory Surgical Center Networks:Direct distribution partnerships with high-volume tympanostomy providers bypass traditional wholesale markup structures.
- Biodegradable Polymer Delivery:Convergence of sustained-release implant technology with antibiotic loading is expanding into chronic suppurative otitis media protocols.
Industry Challenges
- Pediatric Formulation Toxicology Expertise:Scarce regulatory toxicologists specializing in neonatal pharmacokinetics are extending clinical trial timelines for age-de-escalation studies.
- Legacy Manufacturing Equipment Retrofit:EPA pharmaceutical effluent guidelines are forcing capital-intensive wastewater treatment upgrades at oral suspension production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle Ear Infection Treatment Market |
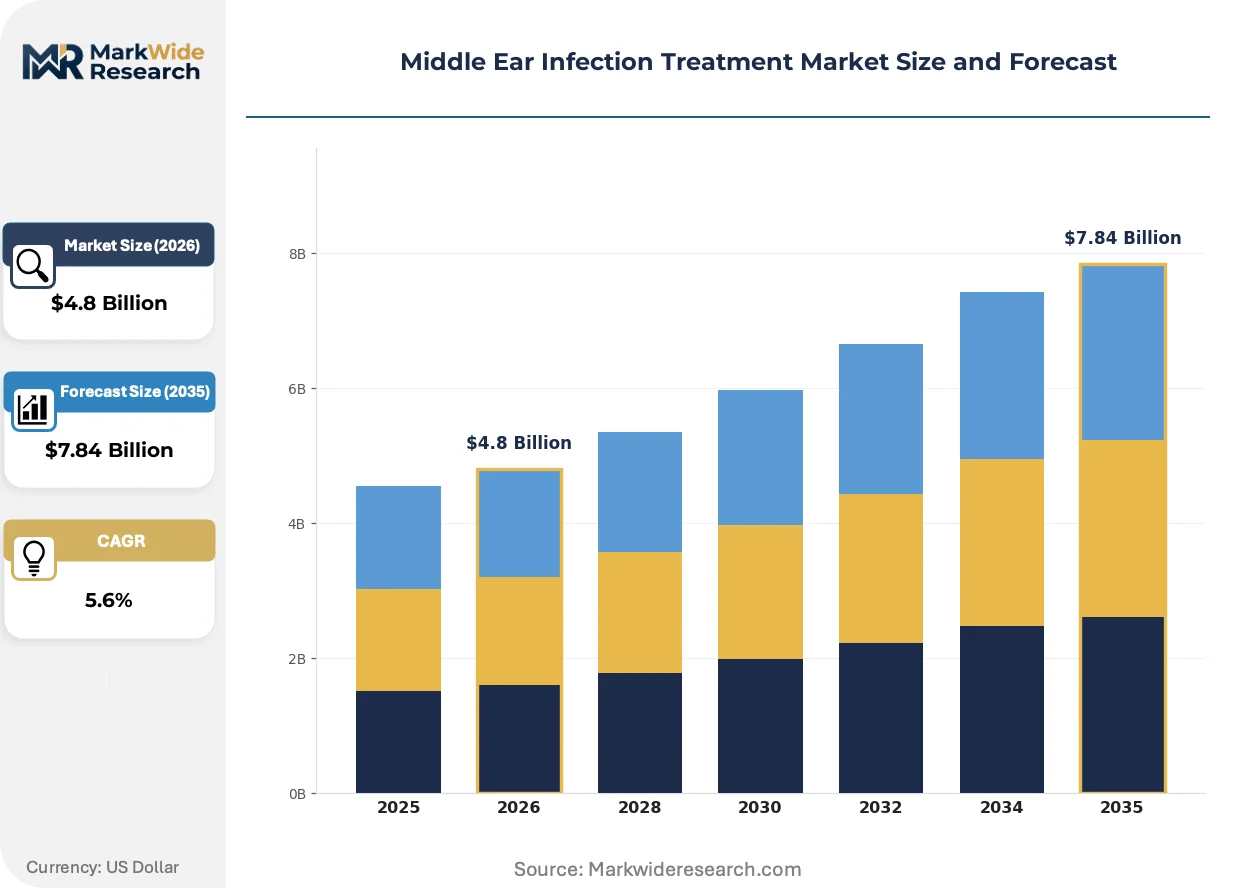
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antibiotics, Antihistamines, Corticosteroids Delivery Mode: Oral, Topical, Injectable, Intranasal End User: Pediatric, Adult, Hospital, Outpatient Clinic Treatment Stage: Acute, Chronic, Recurrent, Preventive |
| Companies Covered | Pfizer Inc., Johnson & Johnson, GlaxoSmithKline plc, Novartis AG, Sanofi S.A., Medtronic plc, Olympus Corporation, Cipla Limited, American Diagnostic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle Ear Infection Treatment Market Trends and Innovations
Tympanic membrane penetration enhancement technologies and stewardship-driven delivery mode shifts are restructuring competitive advantage around bioavailability metrics and environmental compliance credentials rather than brand recognition alone.
Modified-release antibiotic microspheres engineered for sustained tympanic cavity concentration are expanding into recurrent acute otitis media protocols previously managed with repeated oral courses. Pediatric otolaryngology practices in the United States are adopting these implants at accelerating pace for patients with three or more annual infections. The technology is expanding into chronic suppurative cases by eliminating daily adherence barriers in pediatric populations.
REACH chemical safety protocols now mandate environmental risk assessment documentation for all new otic suspension filings before EMA marketing authorization, extending pre-submission preparation timelines by eight to fourteen months. Formulators are responding by eliminating paraben preservatives and redesigning aqueous vehicle compositions to meet aquatic toxicity thresholds. German hospital procurement coalitions have integrated these compliance verifications into tender scoring rubrics, disadvantaging suppliers without verified sustainable manufacturing audits.
Household medicine cabinet stocking patterns for pediatric analgesics are shifting from reactive acute purchase to preventive seasonal inventory building, particularly in United States markets with high-deductible health plans. Retail pharmacy chains are responding with bundled cold-and-flu season merchandising that positions analgesic suspensions adjacent to diagnostic otoscopes. This behavioral shift concentrates margin capture in third-party logistics providers capable of demand-forecasting at the postal code level.
Middle Ear Infection Treatment Market Segmentation
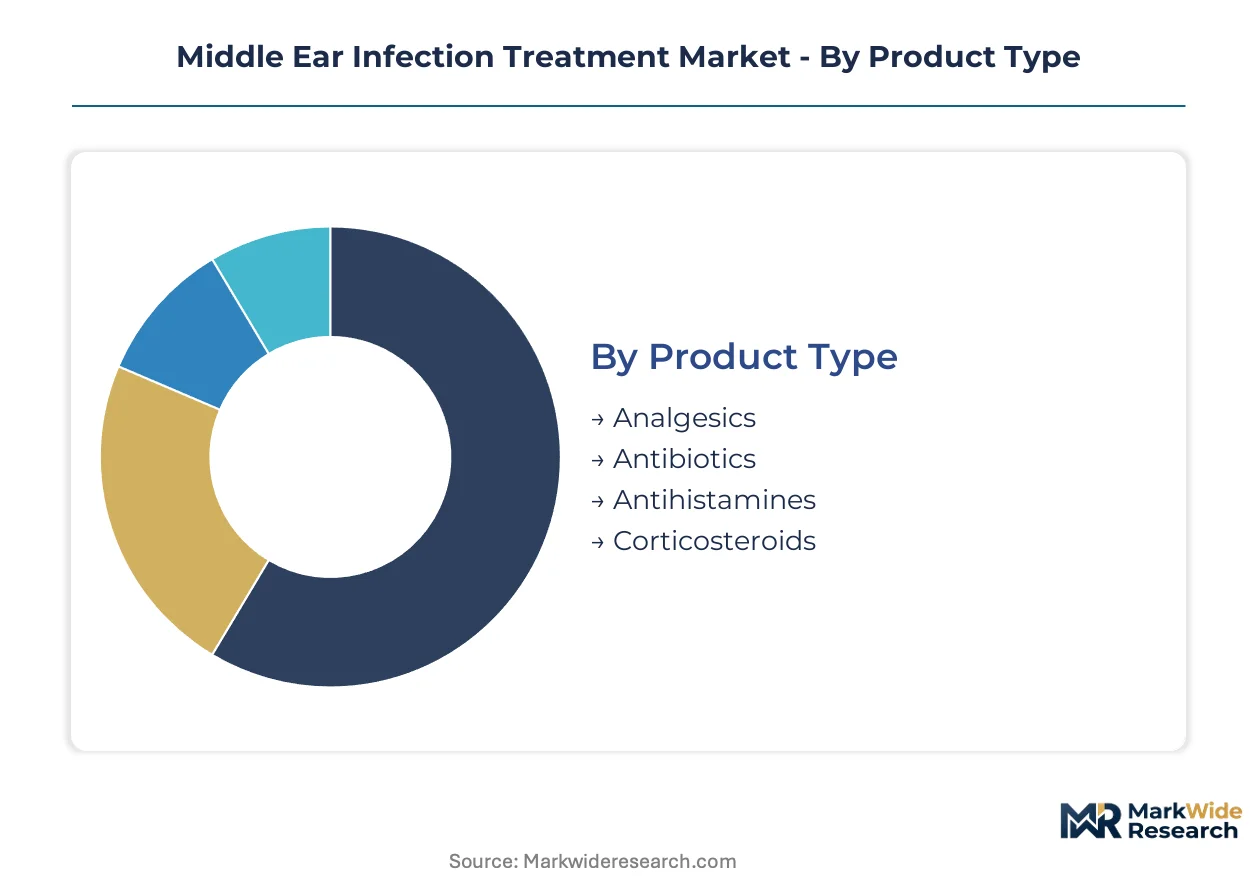
Segmentation in the Middle Ear Infection Treatment Market reveals distinct regulatory pathways and reimbursement thresholds that reshape competitive positioning across product categories. Each dimension carries specific certification burdens from FDA pediatric exclusivity requirements to EMA environmental risk assessments that determine market access feasibility.
Product Type:
Certification burdens vary sharply across pharmacological classes, with antibiotics requiring pediatric investigation plans under FDA and EMA frameworks while analgesics face lighter over-the-counter thresholds.
- Analgesics:Formulations combine acetaminophen or ibuprofen suspensions calibrated to mg-per-kg pediatric dosing protocols. Demand concentrates in United States retail pharmacy chains where seasonal household stocking patterns drive repeat purchase cycles under high-deductible health plans.
- Antibiotics:Macrolide and amoxicillin-clavulanate suspensions dominate prescribing volumes, with FDA pediatric exclusivity incentives accelerating age-appropriate formulation development. Supply concentrates in vertically integrated API networks that secure preferential tender access across German and French hospital procurement coalitions.
- Antihistamines:Adjunctive decongestant formulations targeting eustachian tube dysfunction in allergic pediatric populations face lighter regulatory pathways but narrower reimbursement coverage.
- Corticosteroids:Combination therapies with antibiotic bases face reformulation mandates under REACH aquatic toxicity thresholds, extending EMA pre-submission timelines by eight to fourteen months.
Leading the category by volume: Antibiotics. Growing fastest: Analgesics.
Delivery Mode:
Cost tier differentiation separates premium implantable sustained-release systems from commodity oral suspensions, with reimbursement codes determining viable price floors across ambulatory settings.
- Oral:Suspensions formulated at specific mg-per-kg concentrations remain the pediatric standard, though stewardship penalties are compressing volume for traditional manufacturers.
- Topical:Otic drops gain traction in outpatient clinics seeking to minimize systemic exposure and antibiotic stewardship penalties, capturing cases previously managed with oral suspensions.
- Injectable:Reserved for severe acute cases or surgical prophylaxis in hospital settings, with limited pediatric penetration due to needle aversion protocols.
- Intranasal:Emerging delivery for antihistamine-decongestant combinations targeting eustachian tube patency, constrained by limited tympanic membrane penetration data.
Volume leadership: Oral. Steepest expansion trajectory: Topical.
End User:
Customer type segmentation aligns procurement authority with treatment setting, distinguishing retail pharmacy purchasing patterns from institutional formulary control.
- Pediatric:Dominant demand segment requiring age-de-escalation toxicology studies that extend clinical trial timelines due to scarce neonatal pharmacokinetics expertise.
- Adult:Smaller volume pool with higher comorbidity complexity and broader antibiotic resistance profiles requiring broader-spectrum coverage.
- Hospital:Inpatient formulary standardization drives consolidation toward high-throughput antibiotic suspension procurement cycles.
- Outpatient Clinic:Rapid diagnostic protocol adoption accelerates appropriate antibiotic initiation while elevating topical otic drop preference.
Volume concentration: Pediatric. Fastest share gain: Outpatient Clinic.
Treatment Stage:
Application urgency determines reimbursement thresholds, with acute intervention commanding immediate payment codes while preventive protocols face health technology assessment scrutiny.
- Acute:Immediate antibiotic or analgesic intervention for tympanic membrane inflammation and pain management, capturing the majority of prescribing decisions.
- Chronic:Sustained-release antibiotic microspheres and biodegradable polymer implants eliminate daily adherence barriers in persistent suppurative cases.
- Recurrent:Modified-release implants expand into patients with three or more annual infections, displacing repeated oral antibiotic courses.
- Preventive:Tympanostomy tube placement and prophylactic antibiotic protocols face tightening cost-effectiveness benchmarks in major market health technology assessments.
Revenue concentration: Acute. Climbing fastest: Recurrent.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing clusters in Asia supply formulation facilities in North America and Europe, creating a production-consumption divide that shapes procurement vulnerability and regulatory compliance costs across consuming markets.
United States
Ambulatory surgical centers in Texas and Florida are consolidating tympanostomy volumes into high-throughput networks that compress antibiotic suspension procurement cycles. FDA pediatric exclusivity provisions accelerate age-appropriate formulation development through extended market protection incentives. Pediatric otolaryngology practices in the Boston and Philadelphia metro corridors are adopting modified-release antibiotic microspheres for recurrent infection protocols.
Germany
Hospital procurement coalitions in Bavaria and North Rhine-Westphalia have integrated REACH environmental compliance verifications into tender scoring rubrics for antimicrobial suppliers. The EU Green Deal mandates sustainable manufacturing audits as mandatory filters across German hospital networks. Formulation facilities in the Frankfurt-Rhine-Main cluster are retrofitting wastewater treatment systems to meet tightened pharmaceutical effluent guidelines.
France
Pediatric outpatient clinics in the Île-de-France region are deploying rapid diagnostic protocols that reduce watchful waiting delays for acute otitis media cases. ANSM oversight of pediatric investigation plans shapes clinical trial investment priorities for otic suspension developers. Lyon-based manufacturing sites are reformulating corticosteroid combinations to eliminate paraben preservatives under ECHA aquatic toxicity thresholds.
United Kingdom
Retail pharmacy chains in Greater London and the Southeast are bundling analgesic suspensions with diagnostic otoscopes for seasonal household inventory building. NHS cost-effectiveness benchmarks for recurrent infection protocols are tightening reimbursement thresholds for watchful waiting versus immediate antibiotic intervention. Manchester and Birmingham distribution hubs are optimizing demand-forecasting at postal code level for pediatric analgesic replenishment cycles.
India
CDSCO regulatory pathways for fixed-dose antibiotic combinations are attracting formulation investment toward pediatric suspension development. Domestic manufacturers in Gujarat and Maharashtra are expanding capacity for macrolide active pharmaceutical ingredients to reduce import dependency. Hyderabad-based clinical research organizations are building neonatal pharmacokinetics expertise to support age-de-escalation studies for global sponsors.
Middle Ear Infection Treatment Market Competitive Landscape
The competitive structure tilts toward vertically integrated pharmaceutical conglomerates with captive API networks and specialized otic formulation capabilities. Three archetypes dominate: broad-spectrum antibiotic developers with pediatric exclusivity portfolios, analgesic specialists capturing OTC margin pools through household stocking patterns, and surgical device-procedure integrators bundling tympanostomy tube placement with prophylactic pharmaceutical protocols. Dominant competitive moves include direct distribution partnerships with ambulatory surgical center networks and reformulation investments to meet REACH environmental persistence standards.
Among North American and European pharmaceutical conglomerates, Pfizer Inc., Johnson & Johnson, and GlaxoSmithKline plc exemplify the vertically integrated archetype with established positions across antibiotic and analgesic categories. These entities occupy positions shaped by regulatory engagement with FDA pediatric exclusivity frameworks and EMA pediatric investigation plans. Novartis AG and Sanofi S.A. represent the European-domiciled tier with comparable integration depth. Medtronic plc and Olympus Corporation sit within the procedural intervention segment where device-pharmaceutical bundling is restructuring ambulatory center procurement. Cipla Limited anchors the emerging market formulation specialist archetype with cost-optimized suspension manufacturing capabilities.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| GlaxoSmithKline plc |
| Novartis AG |
| Sanofi S.A. |
| Medtronic plc |
| Olympus Corporation |
| Cipla Limited |
| American Diagnostic Corporation |
| Others |
Pricing and Supply Chain Analysis
Modified-release antibiotic microsphere manufacturing is consolidating production economics around specialized biopolymer synthesis capabilities while simultaneously concentrating API sourcing leverage in Asian manufacturing zones. This dual compression of cost structures and supply nodes is restructuring how formulators negotiate procurement terms and defend margin positions across pediatric and chronic treatment segments.
Pricing Analysis
Margin tightening in oral antibiotic suspensions reflects REACH-driven reformulation costs and stewardship penalty exposure in European hospital networks. Pricing stratifies across premium implantable microspheres, standard oral suspensions, and economy generic analgesics, with certification tier and volume scale as primary differentiation levers. Cost-down pressure on standard oral antibiotics accelerates because topical otic drops capture pediatric cases previously managed with systemic therapy. Outpatient clinic networks exhibit highest price sensitivity due to bundled reimbursement constraints, while ambulatory surgical centers accept premium positioning for implantable sustained-release systems.
Supply Chain Analysis
Single-source vulnerability sits with macrolide API production concentrated in India and China, where fermentation capacity and purification infrastructure anchor global antibiotic suspension supply. Formulation feedstocks draw from amoxicillin-clavulanate precursors, acetaminophen bulk compounds, and biodegradable polymer carriers for implantable delivery systems. Tariff exposure on active pharmaceutical ingredient imports from specific Asian manufacturing zones poses structural disruption risk for European and North American formulators lacking captive API networks. Distribution runs through wholesale pharmaceutical distributors serving hospital procurement coalitions and direct-to-clinic channels for high-volume tympanostomy providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into active pharmaceutical ingredient production and forward integration into ambulatory surgical center distribution networks constitute the decisive competitive race in this market. Players securing both levers will capture pricing power and procurement access that fragmented competitors cannot replicate.
For Market Incumbents: To counter topical otic substitution eroding oral antibiotic volumes, incumbents must deepen captive API production of macrolide and amoxicillin-clavulanate precursors in India while securing exclusive distribution partnerships with high-throughput pediatric ambulatory surgical center networks in Texas and Florida. EMA pediatric investigation plan engagement secures priority review pathways that delay generic entrants. For New Entrants and Emerging Players: FDA pediatric exclusivity provisions in the United States open a window for novel otic suspension delivery mechanisms targeting recurrent infection protocols with three or more annual episodes. White-space concentrates in biodegradable polymer implant manufacturing for chronic suppurative cases and seasonal analgesic bundling with diagnostic otoscopes for household medicine cabinet penetration. Go-to-market traction requires postal-code-level demand forecasting partnerships with retail pharmacy chains. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized otic formulation developers with EMA environmental risk assessment pre-submission documentation and validated sustainable manufacturing audits for EU Green Deal procurement compliance. Long-term viability hinges on regulatory moat sustainability and API supply security rather than brand equity alone. The signal to watch is German hospital procurement coalition tender scoring rubric evolution toward mandatory environmental compliance verification.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pediatric Investigation Plan Engagement | Priority review pathways for novel otic suspensions accelerate market authorization timelines against generic competition. |
| REACH Environmental Compliance Certification | Sustainable manufacturing audits unlock German and French hospital procurement coalition tender access under EU Green Deal mandates. |
| Ambulatory Surgical Center Direct Distribution | Bypassing wholesale markup structures captures margin in high-volume tympanostomy networks consolidating in Texas and Florida. |
| Biodegradable Polymer Implant Development | Sustained-release antibiotic microspheres eliminate daily adherence barriers in pediatric recurrent infection protocols. |
| API Manufacturing Backward Integration | Captive macrolide production in India and China insulates formulators from single-source disruption and tariff exposure. |
Research Methodology
FDA pediatric exclusivity filings, EMA marketing authorization submissions, and hospital procurement database records formed the secondary backbone, cross-referenced with primary interviews with pediatric otolaryngologists, hospital formulary directors, antibiotic stewardship committee leads, and ambulatory surgical center procurement managers. Bottom-up triangulation of prescribing volume data with top-down pharmaceutical manufacturer revenue disclosures validated segment-level estimates across oral suspension, topical otic drop, and implantable delivery categories.
Bottom-up modeling anchored forecasts in patient incidence projections, treatment protocol evolution, and reimbursement code penetration across acute, recurrent, and chronic treatment stages. Segmentation dimensions included product pharmacological class, delivery mode mechanism, end-user setting, and patient age stratum. CAGRs were derived from regression analysis of historical volume trends adjusted for regulatory pathway acceleration effects and stewardship policy adoption curves. Key inputs incorporated rapid diagnostic protocol deployment rates in outpatient clinics and REACH reformulation timeline impacts on EMA submission schedules.
The model assumes a particular technology adoption path for modified-release antibiotic microspheres; alternative pathways for sustained-release implant penetration would alter the outlook if topical otic drops achieve superior bioavailability profiles or if watchful waiting protocols expand under tightened cost-effectiveness benchmarks. Forecasts reflect assumptions about pediatric exclusivity incentive continuity, API supply chain stability, and environmental regulatory stringency trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Stereotactic Body Radiation Therapy Market
Medical Treatment
Malaria Treatment Market
Medical Treatment
Goodpasture Syndrome Treatment Market
Medical Treatment
Frozen Skin Graft Market
Medical Treatment
Anorectal Malformation Treatment Market
Medical Treatment
Thymus Cancer Treatment Market
Medical Treatment
Babesiosis Treatment Market
Medical Treatment
Angioedema Treatment Market
Medical Treatment
Ligament Repair and Reconstruction Market
Medical Treatment
China Nose Reconstruction Market
Medical Treatment
Achalasia Treatment Market
Medical Treatment
Global Systemic Lupus Erythematosus Treatment Market
Medical Treatment
Amyloidosis Treatment Market
Medical Treatment
Histoplasmosis Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Single Dose Radiotherapy Services Market