
 Hyperphosphatemia Market | 2026-2036
Hyperphosphatemia Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperphosphatemia Market Outlook
A widening R&D scale gap between large-cap pharmaceutical firms and emerging biotechs is rotating competitive capital toward novel non-calcium binder platforms. Sanofi leverages its nephrology commercial infrastructure to sustain hospital formulary access across European dialysis networks. Takeda Pharmaceutical Company Limited anchors its position through integrated development of iron-based binder candidates. Ardelyx differentiates via its NHE3 inhibitor approach, competing outside traditional chelation chemistry entirely.
Hyperphosphatemia denotes pathologically elevated serum phosphate levels, typically exceeding 4.5 mg/dL in adults, arising from impaired renal excretion in chronic kidney disease or dysregulated parathyroid hormone signaling. Phosphate binders function by forming insoluble complexes with dietary phosphate in the gastrointestinal tract, preventing systemic absorption and reducing cardiovascular calcification risk. Non-calcium binders command premium positioning due to reduced hypercalcemia liability in long-term dialysis populations, while calcium-based binders retain volume leadership in emerging markets where cost sensitivity dominates procurement decisions. Dialysis centers represent the fastest-growing end-user channel as integrated care models consolidate medication administration within treatment facilities.
FDA orphan drug designations and EMA pediatric investigation requirements shape clinical trial investment thresholds for novel phosphate-lowering agents, with Japan's PMDA offering Sakigake fast-track pathways for innovation in renal therapeutics. The EU MDR and FDA 21 CFR Part 312 govern investigational new drug applications and post-market surveillance obligations for binder formulations. Stakeholders must monitor evolving reimbursement benchmarks for non-calcium alternatives against generic calcium carbonate erosion, while tracking real-world evidence requirements that payers increasingly demand for premium therapy positioning.
Market Dynamics
The dialysis center consolidation wave is restructuring phosphate binder procurement, as integrated care networks centralize purchasing decisions and squeeze traditional hospital pharmacy margins.
Growth Catalysts
- Orphan drug incentives:The FDA's orphan drug designation program accelerates clinical trial timelines for pediatric hyperphosphatemia indications, drawing venture capital into rare-disease formulations.
- Dialysis center expansion:Freestanding dialysis facilities in the United States and Japan are absorbing medication administration into treatment protocols, creating captive demand for oral phosphate binders.
- Iron-based chemistry:Next-generation ferric citrate formulations address both phosphate control and iron deficiency anemia, reducing pill burden for end-stage renal disease patients.
Market Restraints
- Generic calcium carbonate erosion:Patent-expired calcium-based binders flood emerging markets at sub-dollar daily therapy costs, compressing pricing headroom for novel non-calcium alternatives.
- API supply concentration:Active pharmaceutical ingredient manufacturing for sevelamer hydrochloride clusters in coastal China, exposing formulators to shipping disruption and environmental compliance volatility.
- Reimbursement gatekeeping:Medicare's bundled payment model for dialysis services limits separate billing for premium phosphate binders, forcing manufacturers to absorb cost differentials.
Strategic Opportunities
- PMDA Sakigake pathway:Japan's fast-track approval system for breakthrough renal therapeutics offers reduced review timelines for first-in-class NHE3 inhibitors targeting phosphate absorption.
- Peritoneal dialysis home therapy:The shift toward home-based renal replacement creates demand for patient-administered phosphate binders with simplified dosing regimens and reduced monitoring requirements.
- Real-world evidence mandates:EU MDR post-market surveillance requirements favor sponsors with existing cardiovascular outcomes databases, rewarding early investments in observational registries.
Industry Challenges
- Biomarker validation bottlenecks:The absence of standardized serum phosphate variability endpoints complicates Phase III trial design and prolongs FDA pre-submission negotiations.
- Legacy EHR integration:Dialysis center medication reconciliation systems require custom API development to capture phosphate binder adherence data for pay-for-performance contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperphosphatemia Market |
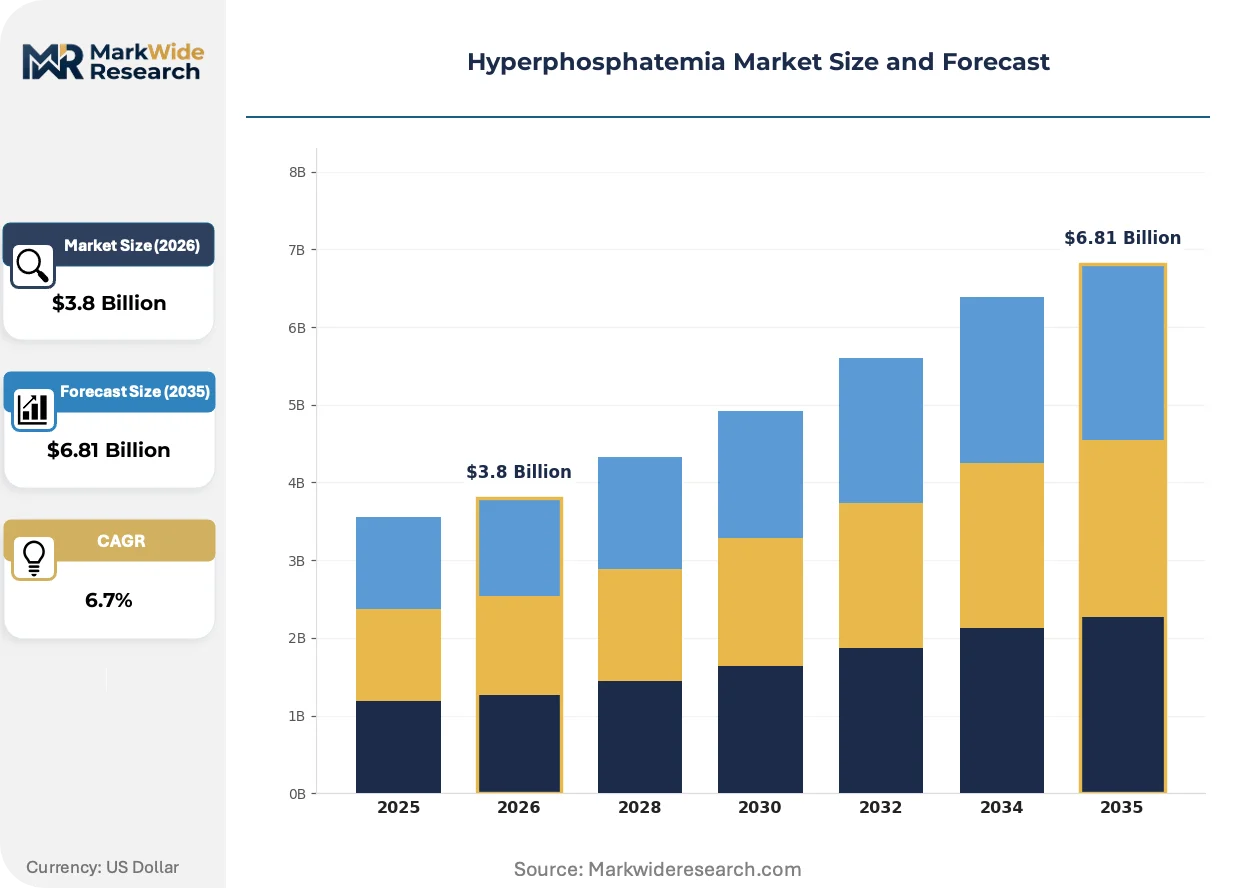
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphate Binders, Calcium-Based Binders, Non-Calcium Binders, Others End User: Hospitals, Homecare, Dialysis Centers, Specialty Clinics Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Wholesalers Treatment Approach: Dietary Management, Pharmacotherapy, Combination Therapy, Others |
| Companies Covered | Sanofi, Takeda Pharmaceutical Company Limited, Astellas Pharma Inc., Akebia Therapeutics, Inc., Ardelyx, CSL Vifor, Unicycive Therapeutics, Lupin, OPKO Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperphosphatemia Market Strategic Shifts
Novel absorption mechanisms are disrupting the chelation chemistry paradigm that has dominated hyperphosphatemia therapy for three decades, creating openings for mechanism-differentiated entrants.
Tenapanor, an NHE3 inhibitor, is decomposing the traditional phosphate binder category by blocking intestinal phosphate transport rather than binding dietary phosphate. Dialysis networks in the United States are piloting this mechanism in calciphylaxis-prone patient subpopulations. The technology is decomposing established market share patterns by offering cardiovascular outcomes differentiation that calcium and non-calcium binders cannot replicate.
EMA pediatric investigation plans now mandate age-appropriate formulation development for all novel phosphate-lowering agents seeking EU marketing authorization. This regulatory expansion forces sponsors to invest in palatable pediatric dosage forms years before adult indication approval. European dialysis centers face delayed access to adult therapies when sponsors deprioritize pediatric timelines, creating competitive openings for firms with parallel development tracks.
Integrated pharmacy services within dialysis facilities are displacing traditional retail dispensing for phosphate binders. Large dialysis organizations in the United States now source directly from wholesalers, bypassing retail pharmacy markups and capturing drug margin internally. This channel consolidation is most advanced in Florida and Texas, where vertically integrated dialysis chains control medication administration from chairside to claims submission.
Hyperphosphatemia Market Segmentation
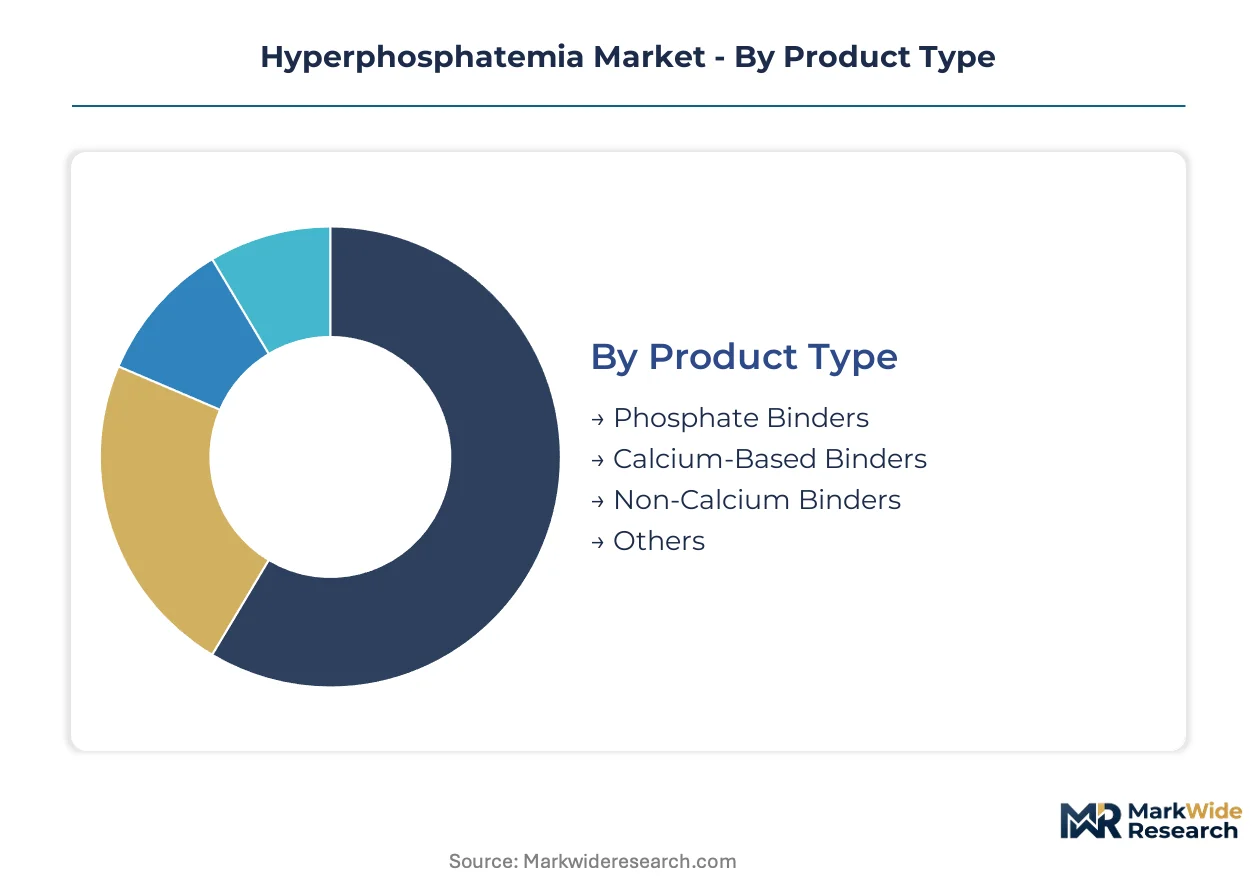
Segmentation in the hyperphosphatemia market reveals distinct competitive dynamics across product chemistry, care setting, and procurement channels. Each dimension carries specific substitution threats and margin structures that reshape manufacturer positioning.
Product Type:
Substitution pressure from generic alternatives weighs most heavily on calcium-based formulations, while non-calcium platforms defend through clinical differentiation.
- Phosphate Binders:Broad category encompassing all chelating agents that form insoluble phosphate complexes in the gastrointestinal tract. Demand concentrates in dialysis centers across the United States where Medicare reimbursement protocols favor established therapeutic categories.
- Calcium-Based Binders:Formulations using calcium carbonate or calcium acetate to sequester dietary phosphate. These products face severe pricing compression in India and Brazil where national health systems prioritize lowest-cost procurement.
- Non-Calcium Binders:Sevelamer hydrochloride and lanthanum carbonate formulations eliminate hypercalcemia risk in long-term dialysis populations. Japan's PMDA fast-track pathways accelerate approval for novel non-calcium entrants with cardiovascular outcomes data.
- Others:Emerging iron-based and magnesium-containing alternatives. Experimental uptake in German nephrology departments tests tolerability against established standards.
Calcium-Based Binders retain volume leadership; Non-Calcium Binders hold the steepest expansion curve.
End User:
Care setting migration is redistributing purchasing authority from hospital administrators to integrated dialysis operators.
- Hospitals:Acute care facilities manage hyperphosphatemia in pre-dialysis chronic kidney disease patients. Procurement decisions in France and Italy remain fragmented across departmental formularies.
- Homecare:Peritoneal dialysis patients self-administer phosphate binders outside clinical supervision. Simplified dosing regimens from Canadian manufacturers address adherence challenges in remote patient populations.
- Dialysis Centers:Freestanding facilities consolidate medication administration into treatment protocols. United States integrated care networks in Florida and Texas now source binders directly from wholesalers, bypassing retail pharmacy channels entirely.
- Specialty Clinics:Nephrology-focused outpatient settings manage pre-end-stage patients. Reimbursement variability across German states creates procurement inconsistency.
Dialysis Centers command the fastest volume gains; Hospitals maintain the largest absolute patient base.
Distribution Channel:
Channel consolidation is eliminating intermediate margin layers as large dialysis organizations internalize drug procurement.
- Hospital Pharmacies:Institutional dispensaries serving inpatient and adjacent outpatient populations. Japanese hospital pharmacies retain phosphate binder dispensing despite dialysis center expansion.
- Retail Pharmacies:Community-based dispensing for homecare patients and supplement purchasers. United States retail chains face margin erosion as Medicare bundled payments redirect volume to dialysis-integrated channels.
- Online Pharmacies:Digital platforms offering direct-to-patient delivery for maintenance prescriptions. Regulatory scrutiny from the FDA and state boards constrains controlled substance adjacent sales.
- Wholesalers:Bulk distributors supplying integrated dialysis networks and hospital systems. Cardinal Health and McKesson in the United States negotiate direct contracts with large dialysis organizations, compressing traditional retail markups.
Wholesalers capture the largest transaction volume; Online Pharmacies expand most quickly among homecare segments.
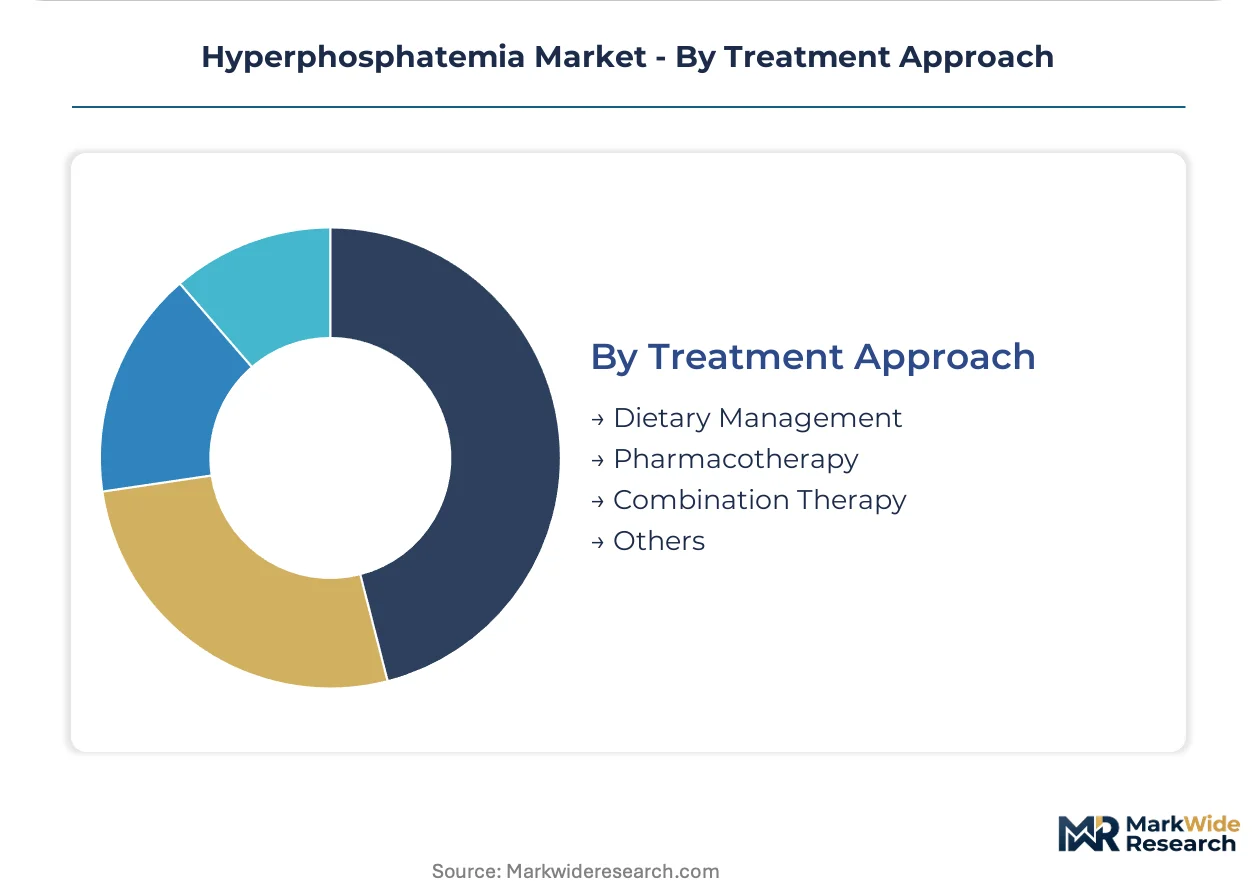
Treatment Approach:
Combination protocols are displacing monotherapy as nephrologists target multiple pathophysiological pathways simultaneously.
- Dietary Management:Phosphate restriction counseling and nutritional intervention. Patient compliance limitations in the United Kingdom drive adjunctive pharmacotherapy prescriptions.
- Pharmacotherapy:Standalone phosphate binder administration. Calcium-based formulations dominate in Mexico and Southeast Asia where cost sensitivity overrides cardiovascular risk considerations.
- Combination Therapy:Concurrent use of phosphate binders with vitamin D analogs or calcimimetics. French and Spanish nephrology guidelines increasingly mandate combination approaches for calciphylaxis-prone patients.
- Others:Experimental NHE3 inhibition and intestinal phosphate transport blockade. Tenapanor pilot programs in United States dialysis networks test mechanism-differentiated positioning.
Pharmacotherapy retains the largest patient population; Combination Therapy gains share fastest among academic medical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Brazil exhibit extreme price sensitivity toward calcium-based phosphate binders, while Japanese and United States dialysis networks absorb substantial premiums for non-calcium alternatives with cardiovascular outcomes differentiation.
United States
Medicare's bundled payment model for dialysis services concentrates phosphate binder procurement within integrated care networks in Florida and Texas. The FDA's orphan drug designation program accelerates pediatric hyperphosphatemia trials, drawing venture capital into rare-disease formulations. Large dialysis organizations in the Southeast now source directly from Cardinal Health and McKesson, bypassing retail pharmacy markups entirely.
Japan
An aging dialysis population exceeding 340,000 patients sustains demand for iron-based and non-calcium binder therapies. The PMDA's Sakigake fast-track pathway reduces review timelines for breakthrough renal therapeutics, rewarding sponsors with cardiovascular outcomes databases. Tokyo and Osaka dialysis centers pilot NHE3 inhibitor protocols in calciphylaxis-prone patient subpopulations.
Germany
EMA pediatric investigation plans mandate age-appropriate formulation development for all novel phosphate-lowering agents seeking EU marketing authorization. The EU MDR governs post-market surveillance obligations for binder formulations, favoring sponsors with existing observational registries. Bavarian and North Rhine-Westphalia nephrology departments test experimental magnesium-containing alternatives against established standards.
India
National health system procurement prioritizes lowest-cost calcium carbonate formulations, compressing pricing headroom for novel entrants. The CDSCO regulates investigational new drug applications for phosphate-lowering agents under accelerated approval pathways for unmet medical needs. Mumbai and Hyderabad manufacturing clusters supply generic active pharmaceutical ingredients to Southeast Asian and African markets.
Brazil
ANVISA registration requirements for phosphate binders align with WHO prequalification standards, facilitating parallel submission strategies. Cost sensitivity in the public health system sustains volume leadership for calcium-based formulations despite cardiovascular risk profiles. São Paulo dialysis networks consolidate purchasing decisions as integrated care models expand through the Southeast region.
Hyperphosphatemia Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in the hyperphosphatemia market. Large-cap pharmaceutical firms with nephrology commercial infrastructure dominate hospital formulary access and integrated dialysis network contracts, while emerging biotechs concentrate R&D capital on novel non-calcium binder platforms and NHE3 inhibition mechanisms. The competitive structure stratifies across three archetypes: diversified pharma incumbents, mechanism-differentiated biotech specialists, and generic API manufacturers. Dominant competitive moves include strategic partnerships for dialysis center channel access and portfolio diversification into iron-based combination therapies.
Within the diversified pharma tier, Sanofi leverages established European dialysis network relationships, while Takeda Pharmaceutical Company Limited anchors its position through integrated development programs. Ardelyx occupies a distinct mechanism-differentiated position competing outside traditional chelation chemistry entirely. These three companies exemplify the strategic archetypes reshaping competitive capital allocation toward novel absorption mechanisms and real-world evidence generation for premium therapy positioning.
| Leading Market Players |
|---|
| Sanofi |
| Takeda Pharmaceutical Company Limited |
| Astellas Pharma Inc. |
| Akebia Therapeutics, Inc. |
| Ardelyx |
| CSL Vifor |
| Unicycive Therapeutics |
| Lupin |
| OPKO Health |
| Others |
Value Chain & Pricing Dynamics
API manufacturing scale economies in coastal China concentrate active pharmaceutical ingredient production for sevelamer hydrochloride, creating cost floors that generic calcium carbonate producers in India and Brazil struggle to match. This scale asymmetry forces novel non-calcium binder developers to absorb margin compression or pursue premium cardiovascular outcomes differentiation.
Pricing Analysis
After-sales revenue from iron deficiency anemia co-treatment drives lifetime value for ferric citrate formulations. Three-tier pricing structure across premium non-calcium binders, standard calcium-based alternatives, and economy generic carbonate segments dominates procurement. Pricing pressure stems from Medicare bundled payment limits on separate phosphate binder billing in United States dialysis networks. Emerging market public health systems exhibit extreme price sensitivity, while Japanese integrated care networks absorb substantial premiums for cardiovascular-differentiated therapies.
Supply Chain Analysis
Just-in-time inventory strategies dominate phosphate binder distribution to United States dialysis centers, while strategic stockpiling persists in Japan and Germany for NHE3 inhibitor pilot programs. Active pharmaceutical ingredient manufacturing concentrates in coastal China, Mumbai, and Hyderabad clusters. Key inputs include sevelamer hydrochloride resin, lanthanum carbonate rare earths, and ferric citrate iron sources. Single-source vulnerability for sevelamer API exposes formulators to shipping disruption. Distribution runs through Cardinal Health and McKesson direct contracts with large dialysis organizations, bypassing retail pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as dialysis center consolidation waves create procurement authority concentration, repeating patterns last observed during the 2010-2015 integrated care expansion.
For Market Incumbents: Consolidate hospital formulary access through nephrology commercial infrastructure investments in European dialysis networks. Lock in direct wholesaler contracts with Florida and Texas integrated care organizations before channel margin compression accelerates. Counter generic calcium carbonate erosion by accelerating real-world evidence generation for cardiovascular outcomes differentiation.
For New Entrants and Emerging Players: Differentiate on mechanism by pursuing PMDA Sakigake fast-track pathways for NHE3 inhibitors in calciphylaxis-prone patient subpopulations. Target peritoneal dialysis home therapy segments where simplified dosing regimens address adherence gaps that incumbent chelation chemistry cannot fill. Enter through specialty clinic channels in German states with reimbursement variability that rewards innovative positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mechanism-differentiated biotech specialists with parallel pediatric-adult development tracks over diversified pharma incumbents facing generic erosion. Long-term viability across the next decade hinges on cardiovascular outcomes database depth and regulatory exclusivity runway. Watch for inflection when Medicare reimbursement benchmarks shift toward non-calcium alternatives in bundled payment recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Pediatric Investigation Plan Parallel Track | Accelerates EU marketing authorization by satisfying pediatric formulation mandates ahead of adult indication approval. |
| Real-World Evidence Registry Investment | Builds cardiovascular outcomes databases that EU MDR post-market surveillance requirements increasingly favor for premium positioning. |
| Direct Wholesaler Contracting | Captures margin from retail pharmacy bypass as Florida and Texas dialysis chains consolidate procurement authority. |
| Iron-Based Combination Therapy Pipeline | Addresses dual phosphate control and anemia management to reduce pill burden in end-stage renal disease populations. |
| PMDA Sakigake Fast-Track Submission | Reduces review timelines for breakthrough NHE3 inhibitors targeting intestinal phosphate transport blockade. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient-volume modeling triangulated against top-down pharmaceutical revenue estimates.
Across the analysis window, forecasts applied segmentation by product chemistry, care setting, distribution channel, and regional regulatory cluster. CAGRs derived from epidemiological projections of chronic kidney disease prevalence combined with therapy penetration assumptions. Forecast inputs included dialysis center expansion rates, generic erosion curves, and orphan drug designation timelines.
Material uncertainties — regulatory reimbursement recalibration, API supply disruption, and biomarker validation delays — sit outside the modeled envelope. Forecasts reflect assumptions about Medicare bundled payment stability and PMDA fast-track pathway continuity. Revision becomes warranted when cardiovascular outcomes data from observational registries crosses thresholds for payer access differentiation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Human Immunodeficiency Virus Therapeutics Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Amoxicillin Drugs Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market