
 Hepatitis - B Therapeutics Market | 2026-2036
Hepatitis - B Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatitis - B Therapeutics Market Outlook
Next-generation capsid assembly modulators and RNA-targeting agents are redrawing competitive boundaries in hepatitis B therapeutics. Gilead Sciences sustains one of the deepest late-stage pipelines in core protein allosteric modulators. Bristol-Myers Squibb anchors its position through long-standing entecavir franchises and immunotherapy adjacencies. Vir Biotechnology differentiates via monoclonal antibody approaches aimed at functional cure endpoints.
Hepatitis B therapeutics encompass antiviral agents, immunomodulatory biologics, and prophylactic vaccines designed to suppress viral replication, reduce liver inflammation, or eliminate covalently closed circular DNA from hepatocytes; tenofovir disoproxil fumarate remains the benchmark nucleoside analogue with high genetic barrier to resistance. Nucleoside analogue regimens still dominate prescription volume but face margin compression as patents mature. Oral administration routes capture the majority of chronic patient days due to convenience and adherence advantages. Immune modulator development represents the fastest-expanding segment as investigators pursue finite-duration functional cures.
FDA breakthrough therapy designations and EMA PRIME eligibility criteria shape which hepatitis B programs secure priority review resources and reimbursement traction. WHO prequalification standards influence procurement decisions across low-income country immunization programs. Stakeholders must weigh the timing of interferon-sparing combination protocols against the risk that curative claims outpace durable virologic endpoint validation.
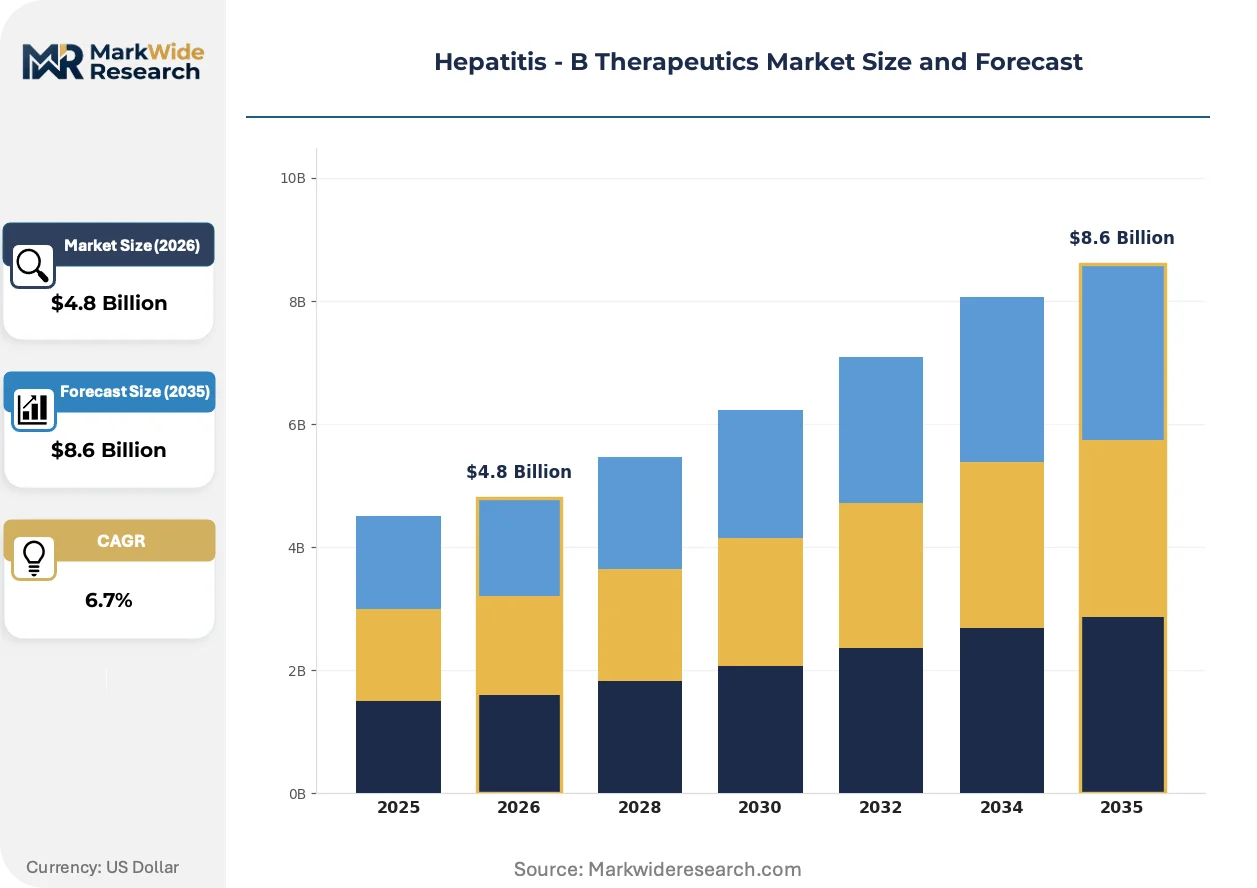
Market Dynamics
The transition from indefinite nucleoside analogue suppression toward finite-duration functional cure regimens is restructuring clinical trial investment and reimbursement benchmarks across hepatitis B therapeutics.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Priority review pathways compress development timelines for core protein allosteric modulators. Sponsors gain accelerated market access negotiations.
- Hospital-based antiviral adoption:Integrated care protocols in tertiary liver centers consolidate prescription authority. Specialist-driven treatment intensification expands addressable patient pools.
- RNA-targeting platform maturation:siRNA and antisense mechanisms enable cccDNA transcriptional silencing. Preclinical-to-clinical translation rates for these modalities outpace historical benchmarks.
Market Restraints
- Active pharmaceutical ingredient concentration:Tenofovir and entecavir raw material supply clusters in specific Asian manufacturing zones. Single-source dependencies create vulnerability to export restriction cascades.
- Functional cure endpoint validation:Persistent cccDNA reservoirs defy standardized quantification. Regulatory acceptance of surrogate markers remains inconsistent across FDA and EMA.
- Interferon-sparing combination costs:Triple and quadruple therapy architectures multiply per-patient manufacturing burden. Payer resistance intensifies in price-controlled European markets.
Strategic Opportunities
- China's unmet chronic patient base:Provincial reimbursement expansion for innovative antivirals outpaces prior access limitations. Local partnership requirements favor technology licensors over direct entrants.
- Monoclonal antibody combination protocols:Viral entry blockers paired with immune modulators open finite-treatment paradigms. Development partnerships between biologics specialists and nucleoside incumbents accelerate.
- WHO prequalification procurement:Low-income country immunization programs create volume anchors for prophylactic vaccine tenders. Manufacturing scale commitments secure long-term offtake visibility.
Industry Challenges
- cccDNA quantification assay standardization:Hepatocyte biopsy sampling variability corrupts functional cure trial readouts. Cross-laboratory harmonization efforts lag therapeutic candidate advancement.
- Immune-tolerant patient stratification:ALT-normal, high-viral-load subpopulations demonstrate divergent treatment response. Trial enrichment criteria require iterative biomarker refinement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatitis - B Therapeutics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nucleoside Analogues, Interferons, Immune Modulators, Vaccine End User: Hospitals, Clinics, Diagnostic Labs, Homecare Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular Therapeutic Area: Infectious Diseases, Gastroenterology, Hepatology, Others |
| Companies Covered | Gilead Sciences, Inc., Bristol-Myers Squibb Company, GSK plc, Merck & Co., Inc., AbbVie Inc., Assembly Biosciences, Inc., Arbutus Biopharma, Vir Biotechnology, Aligos Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatitis - B Therapeutics Market Strategic Shifts
Competitive boundaries in hepatitis B therapeutics are being redrawn by convergence of nucleic acid therapeutics with immunomodulatory biologics, forcing incumbents to reconfigure pipeline priorities and partnership strategies.
Capsid assembly modulation is bifurcating the nucleoside analogue maintenance paradigm. Second-generation core protein allosteric modulators with improved pharmacokinetic profiles are capturing investigator-initiated trial share from first-in-class predecessors. The technology is bifurcating prescriber expectations between viral suppression and true virologic clearance endpoints.
EMA PRIME eligibility criteria are reshaping European development timelines. Priority medicines designation grants enhanced regulatory dialogue and accelerated assessment for curative hepatitis B regimens. German and French national health technology assessment bodies are adjusting evidentiary thresholds to accommodate novel surrogate endpoints.
Specialist procurement consolidation is compressing formulary decision cycles. Hospital pharmacy and therapeutics committees in the United States are centralizing antiviral selection authority. Integrated delivery networks in Texas and California are piloting risk-sharing arrangements tied to sustained virologic response rates.
Hepatitis - B Therapeutics Market Segmentation
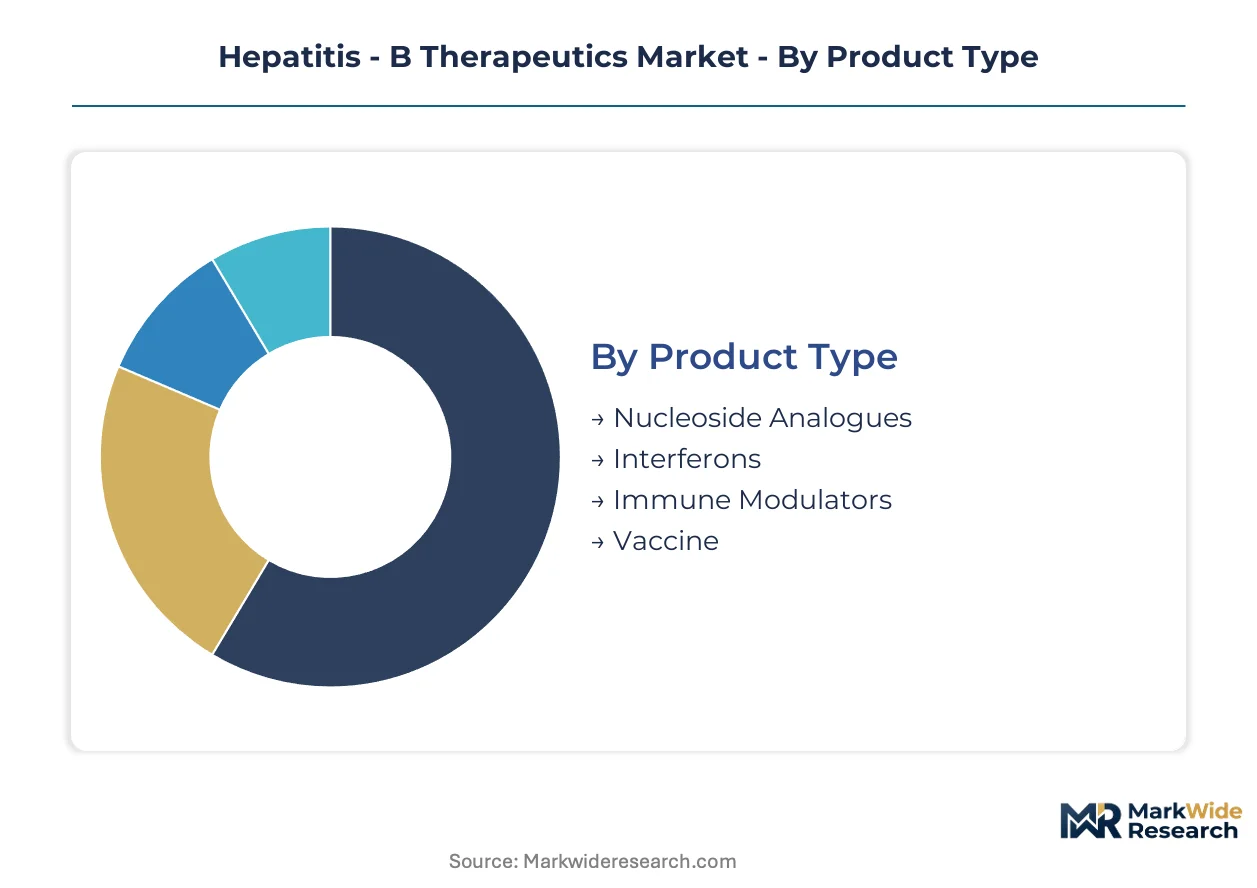
Segmentation in hepatitis B therapeutics reveals divergent regulatory pathways and reimbursement structures across product modalities. Understanding these divisions enables stakeholders to align development priorities with payer expectations and clinical trial design requirements.
Product Type:
FDA breakthrough therapy designation and EMA PRIME eligibility criteria create tiered approval timelines across therapeutic modalities, with nucleic acid platforms commanding accelerated review resources.
- Nucleoside Analogues:Tenofovir disoproxil fumarate and entecavir form the backbone of chronic suppression protocols. Hospital-based antiviral adoption in the United States, China, and Germany concentrates prescription volume for these agents as patents mature.
- Interferons:Pegylated interferon-alpha regimens deliver finite-duration treatment options with durable off-therapy response in selected populations. Specialist-driven treatment intensification in tertiary liver centers sustains demand despite tolerability limitations and administration burden.
- Immune Modulators:Toll-like receptor agonists and checkpoint inhibitors target cccDNA transcriptional silencing through host immune restoration.
- Vaccine:Prophylactic formulations prevent transmission through pre-exposure immunization; WHO prequalification standards govern procurement for low-income country programs.
Nucleoside analogues handle the majority of throughput; immune modulators are climbing the fastest on share as functional cure endpoints reshape investment priorities.
End User:
Patient acuity and reimbursement complexity concentrate purchasing authority across institutional settings, with integrated care protocols consolidating decision-making in high-volume centers.
- Hospitals:Tertiary liver centers manage decompensated cirrhosis and hepatocellular carcinoma complications requiring intensive monitoring. Texas and California integrated delivery networks pilot risk-sharing arrangements tied to sustained virologic response rates.
- Clinics:Community-based hepatology practices handle stable chronic patients on nucleoside analogue maintenance. Outpatient prescription volume in Germany and France reflects national health technology assessment adjustments for novel surrogate endpoints.
- Diagnostic Labs:cccDNA quantification and HBsAg seroclearance testing support functional cure trial enrollment.
- Homecare:Oral antiviral self-administration enables long-term adherence outside institutional settings.
Hospitals capture the highest per-patient revenue intensity; homecare is expanding most quickly as oral regimens displace parenteral alternatives.
Administration Route:
Formulation development investments track patient convenience demands and adherence economics, with oral platforms commanding manufacturing scale commitments.
- Oral:Once-daily nucleoside analogues dominate chronic patient days through convenience and sustained viral suppression. Entecavir and tenofovir formulations anchor prescription volume across United States, China, and Germany.
- Intravenous:Hospital-based administration for acute hepatitis B flares and investigational immune modulator protocols. Tertiary centers in California and Texas consolidate infusion capacity for combination trials.
- Subcutaneous:Pegylated interferon delivery enables outpatient self-administration with weekly dosing intervals.
- Intramuscular:Vaccine administration routes align with immunization program logistics in low-income settings.
Oral administration handles the majority of patient-days; subcutaneous delivery is gaining share fastest as interferon-sparing combinations reduce injection burden.
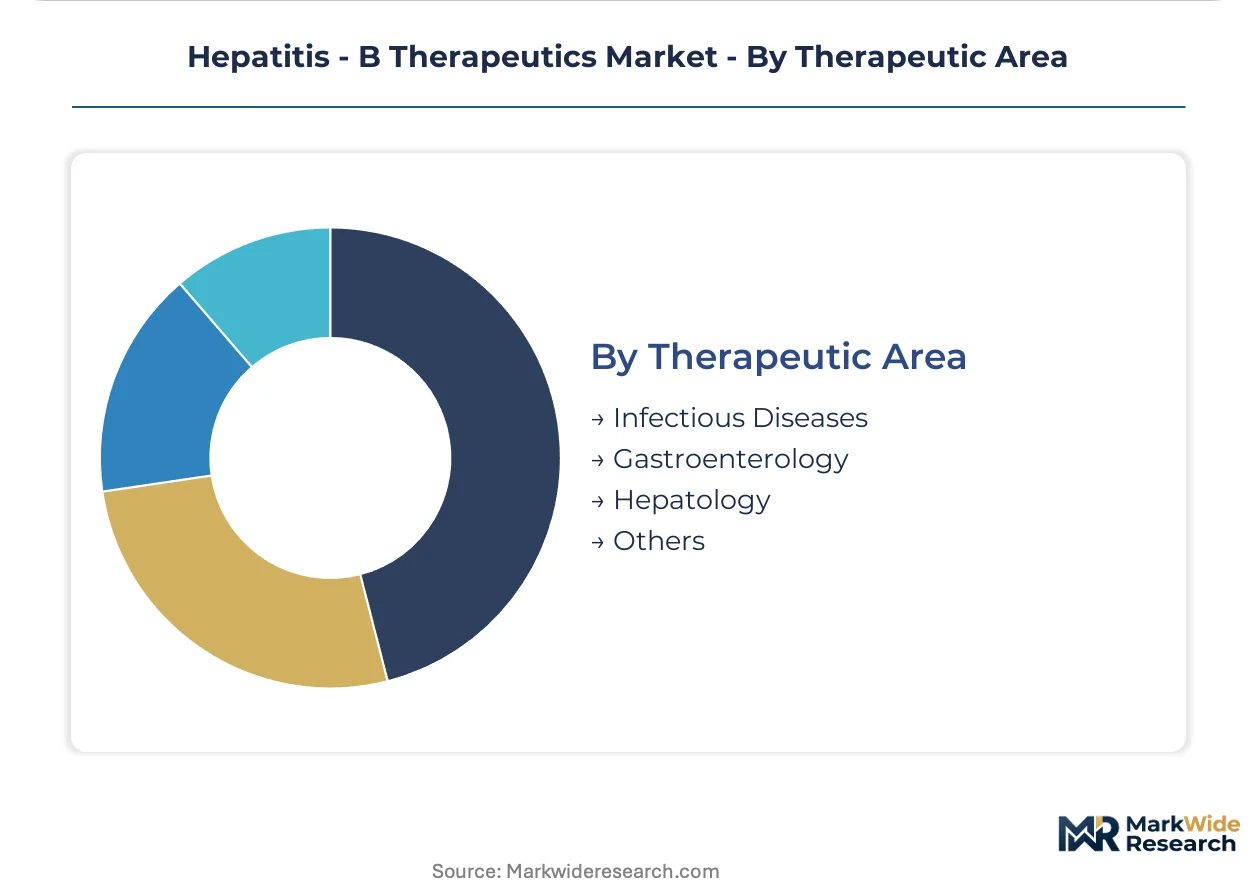
Therapeutic Area:
Specialty board certification and fellowship training pathways determine prescriber authority distribution across clinical domains.
- Infectious Diseases:Antiviral stewardship programs in United States academic medical centers govern nucleoside analogue selection. HIV-hepatitis B co-infection management concentrates expertise in tertiary referral networks.
- Hepatology:Dedicated liver centers in Germany and France drive functional cure trial enrollment and immune modulator adoption. Transplant hepatologists manage end-stage disease with curative regimen urgency.
- Gastroenterology:General GI practices handle initial diagnosis and nucleoside analogue initiation in community settings.
- Others:Oncology and internal medicine sub-specialists contribute to hepatocellular carcinoma surveillance and co-morbidity management.
Hepatology captures the highest-value patient management; infectious diseases is expanding most quickly as antiviral stewardship extends into hepatitis B protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports active pharmaceutical ingredients for tenofovir and entecavir to formulation facilities in India and the United States, establishing the dominant trade corridor for hepatitis B therapeutics manufacturing.
United States
Hospital-based antiviral adoption concentrates prescription authority in tertiary liver centers across Texas and California. FDA breakthrough therapy designations accelerate review timelines for core protein allosteric modulators. Integrated delivery networks in Houston and Los Angeles pilot risk-sharing arrangements tied to sustained virologic response rates.
China
Provincial reimbursement expansion for innovative antivirals unlocks access to the world's largest chronic patient base. NMPA regulatory reforms compress development timelines for domestic biotech candidates. Manufacturing clusters in Jiangsu and Zhejiang provinces supply raw materials for global nucleoside analogue production.
Germany
Specialist-driven treatment intensification in hepatology centers drives functional cure trial enrollment. EMA PRIME eligibility grants enhanced regulatory dialogue for curative regimens. The Rhine-Ruhr and Munich metropolitan areas concentrate hospital pharmacy and therapeutics committee authority for antiviral selection.
India
Domestic formulation capabilities transform imported APIs into finished tenofovir products for domestic and export markets. CDSCO accelerated approval pathways align with WHO prequalification standards for low-income country procurement. Hyderabad and Ahmedabad house contract manufacturing organizations serving immunization program tenders.
Japan
Pegylated interferon-alpha regimens retain demand in hepatology practices pursuing finite-duration treatment options. PMDA consultation programs guide sponsors through novel surrogate endpoint validation for functional cure claims. The Kanto region around Tokyo concentrates transplant hepatologist expertise managing end-stage disease.
Hepatitis - B Therapeutics Market Competitive Environment
Listed leaders compete with private specialists across late-stage pipeline depth and immunomodulatory platform diversification. The market structure tiers between nucleoside incumbents with mature franchises and biotech challengers pursuing finite-duration functional cures. Three archetypes dominate: large-cap diversified pharmaceutials with antiviral heritage, mid-cap nucleic acid therapeutics specialists, and immunotherapy-focused biologics developers. Competitive moves concentrate on strategic partnerships between nucleoside incumbents and immune modulator developers, alongside technology licensing deals for RNA-targeting platforms.
Among the large-cap pharmaceutical tier, Gilead Sciences and Bristol-Myers Squibb occupy positions reflecting antiviral franchise depth and immunotherapy adjacency respectively. Vir Biotechnology represents the biologics specialist archetype pursuing monoclonal antibody approaches. These three exemplify the competitive tension between maintenance suppression regimens and finite-duration functional cure development pathways reshaping investment priorities across hepatitis B therapeutics.
| Leading Market Players |
|---|
| Gilead Sciences, Inc. |
| Bristol-Myers Squibb Company |
| GSK plc |
| Merck & Co., Inc. |
| AbbVie Inc. |
| Assembly Biosciences, Inc. |
| Arbutus Biopharma |
| Vir Biotechnology |
| Aligos Therapeutics |
| Others |
Value Chain & Pricing Dynamics
RNA-targeting platform maturation displaces nucleoside analogue procurement patterns while simultaneously concentrating API manufacturing in Jiangsu and Zhejiang provinces and compressing margin structures for first-generation antiviral portfolios.
Pricing Analysis
Second-generation core protein allosteric modulators command premium positioning against maturing tenofovir and entecavir franchises nearing patent expiry. Pricing stratifies across premium, standard, and economy tiers based on FDA breakthrough therapy designation status and hospital formulary tier placement. Cost compression in the nucleoside analogue segment is intensifying because provincial reimbursement expansion in China favors domestic manufacturers. Community hepatology practices exhibit highest price sensitivity; tertiary liver centers demonstrate lowest sensitivity due to risk-sharing arrangement structures.
Supply Chain Analysis
China produces tenofovir and entecavir active pharmaceutical ingredients for formulation facilities in India and the United States. Manufacturing draws from concentrated raw material feedstocks including adenine and phosphonate intermediates sourced from Zhejiang chemical clusters. Single-source dependencies in Asian export zones create vulnerability to regulatory restriction cascades. Distribution runs through hospital pharmacy and therapeutics committees consolidating procurement authority in Texas and California integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional cure endpoint validation functions as a platform-economics inflection where interoperability between nucleoside suppression and immune modulation protocols determines reimbursement traction and partnership value.
For Market Incumbents: Fortify entecavir franchise positions through backward integration into API manufacturing and exclusive supply arrangements with Jiangsu-based chemical producers. RNA-targeting specialists threaten nucleoside maintenance paradigms through finite-duration regimen claims. Priority investment in cccDNA quantification assay standardization secures trial enrollment control and regulatory dialogue leverage. For New Entrants and Emerging Players: Lead with monoclonal antibody combination protocols targeting immune-tolerant patient stratification gaps in German and French hepatology centers. China's provincial reimbursement expansion offers the most penetrable geography for technology licensors meeting NMPA local partnership requirements. Hospital-based pilot programs with risk-sharing structures provide optimal go-to-market validation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed RNA-targeting platform companies possessing EMA PRIME eligibility but requiring manufacturing scale commitments. Long-term viability hinges on functional cure endpoint regulatory acceptance across FDA and EMA jurisdictions. Acquisition target archetype: mid-cap biologics developers with validated siRNA mechanisms and incomplete China access partnerships. The signal to watch is harmonization progress on cccDNA quantification standards across reference laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Core protein allosteric modulator programs with FDA breakthrough therapy designation compress development timelines. |
| Manufacturing Scale-Up | Jiangsu and Zhejiang API capacity expansion secures raw material supply for global nucleoside analogue production. |
| Licensing Agreement | Technology licensors gain China market access through NMPA partnership requirements favoring local collaboration. |
| Regulatory Approval Pathway | EMA PRIME eligibility grants enhanced dialogue for curative hepatitis B regimen assessments in Germany. |
| Pipeline Diversification | Immune modulator development represents fastest-expanding segment as functional cure endpoints reshape priorities. |
Study Parameters
The analysis maps nucleoside analogue, interferon, immune modulator, and vaccine segments, each validated through hepatology specialists, hospital pharmacy directors, regulatory affairs leads, and payer access specialists. Primary interview insights triangulate against FDA filings, EMA submission databases, ClinicalTrials.gov records, and WHO prequalification standards. Bottom-up prescription volume modeling and top-down epidemiological prevalence estimates reconcile through iterative validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions include product modality, administration route, end-user institution type, therapeutic specialty, and regional regulatory cluster. CAGRs derive from patient population forecasting, treatment penetration assumptions, and pricing trajectory modeling. Forecast inputs incorporate hospital antiviral adoption rates and provincial reimbursement expansion timelines.
Forecasts assume regulatory continuity in FDA breakthrough therapy and EMA PRIME frameworks; material policy shifts would require re-modeling. cccDNA quantification assay standardization delays or functional cure endpoint rejection scenarios could revise trajectory assumptions. Recalibration cycles align with material shifts in reimbursement policy, regulatory guidance, and clinical trial readout schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Fast Melt Tablets Market
Pharmaceuticals
Global Paracetamol Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Over-The-Counter (OTC) Analgesics Market
Pharmaceuticals
Unit-Dose Respiratory Medications Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Anti-Parasitic Drugs Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Stomach Cancer Drugs Market
Pharmaceuticals
Global Two Piece Empty Hard Capsule Market
Pharmaceuticals
Cough and Cold Preparations Market