
 Dementia and Alzheimers Disease Treatment Market | 2026-2036
Dementia and Alzheimers Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Dementia and Alzheimers Disease Treatment Market Insights
Small-molecule chemistry is consolidating around amyloid-targeting biologics as the dominant therapeutic modality in Alzheimer's treatment. Biogen Inc. leverages its pioneering monoclonal antibody platform to anchor premium positioning in the early-stage treatment segment. Eli Lilly and Company sustains one of the deepest clinical pipelines across multiple tau and amyloid mechanisms. Roche Holding AG differentiates through diagnostic-therapeutic integration, pairing cerebrospinal fluid biomarker assays with therapeutic development.
Dementia and Alzheimers Disease Treatment encompasses pharmacological interventions designed to modify disease progression, manage cognitive symptoms, and address behavioral manifestations through mechanisms including cholinesterase inhibition, NMDA receptor modulation, and immunotherapy-mediated amyloid clearance; formulations range from oral tablets to intravenous infusions requiring cold-chain distribution. Monoclonal antibodies command the highest development investment and pricing power due to manufacturing complexity and clinical differentiation. Hospital care applications absorb the majority of infused therapy administration, while home care channels expand for oral maintenance regimens. The treatment stage dimension reveals early-stage interventions as the focal point for pipeline investment, with moderate-stage representing the largest currently addressable patient pool.
The FDA's accelerated approval framework and EMA's conditional marketing authorization pathway create divergent market access timelines across jurisdictions, with post-approval confirmatory trial obligations shaping commercial risk profiles. The EU AI Act and GDPR impose algorithmic transparency requirements on digital diagnostic tools increasingly paired with therapeutic protocols. Japan's PMDA Sakigake designation accelerates domestic review for novel mechanisms, influencing multinational launch sequencing. Stakeholders must monitor biomarker-based patient selection criteria as they redefine addressable populations and reimbursement negotiations across regulatory environments.
Market Dynamics
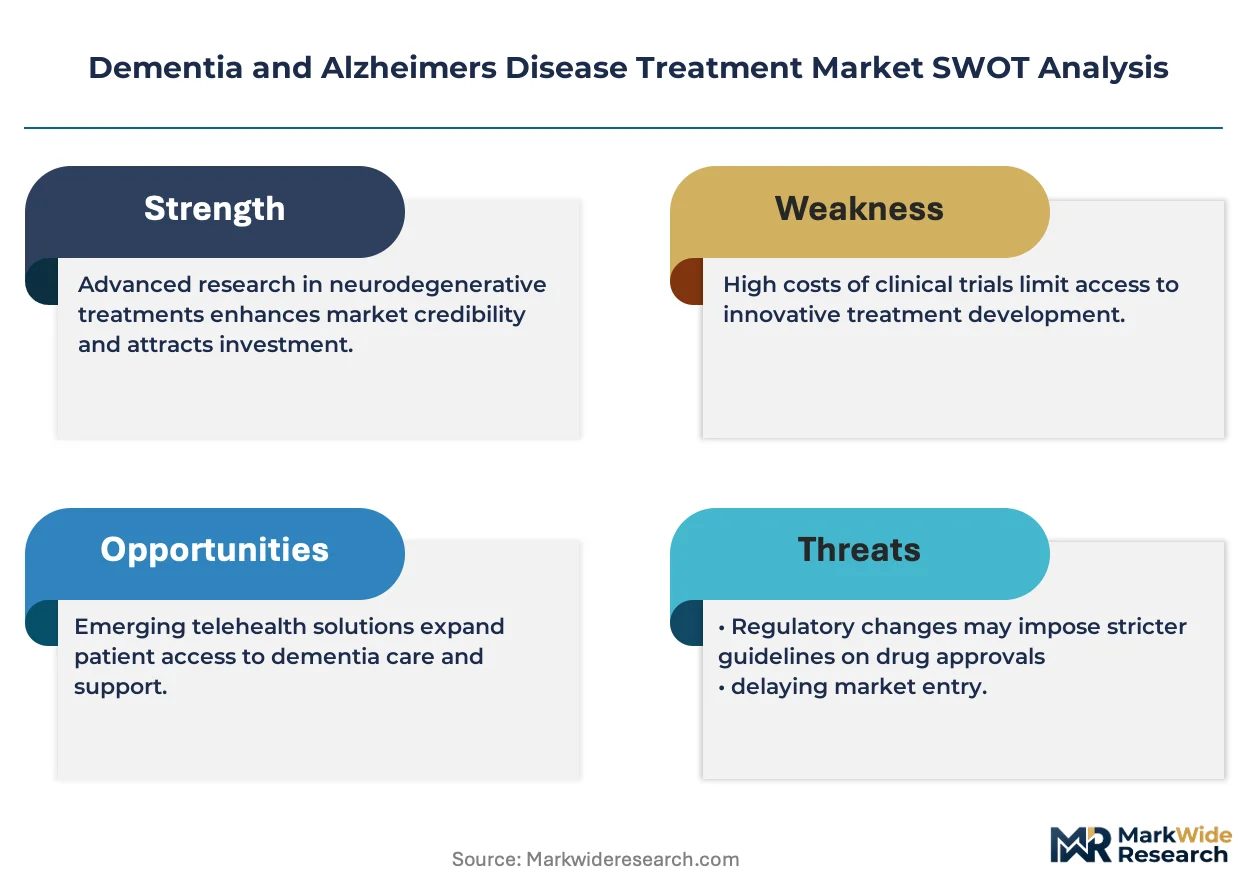
The FDA's accelerated approval pathway for Alzheimer's therapies is compressing development timelines while elevating confirmatory trial obligations, fundamentally altering how manufacturers sequence commercial launches and allocate R&D capital across early versus moderate-stage patient populations.
Growth Catalysts
- Biomarker-Guided Patient Selection:Cerebrospinal fluid assays and PET imaging are expanding addressable populations for disease-modifying therapies by enabling pre-symptomatic identification. Hospital systems in the United States are investing in integrated diagnostic-therapeutic protocols.
- Medicare Reimbursement Innovation:The Centers for Medicare & Medicaid Services has established coverage with evidence development frameworks for infused monoclonal antibodies, reducing access friction for novel biologics in approved indications.
- Amyloid Immunotherapy Manufacturing Scale-Up:Contract development and manufacturing organizations are expanding cold-chain biologics capacity to support commercial demand for intravenous infusion therapies requiring precise temperature control.
Market Restraints
- Plasma Collection Bottlenecks:Immunoglobulin and albumin feedstock constraints are elevating input costs for antibody-based therapeutics dependent on fractionated plasma derivatives.
- Confirmatory Trial Failure Risk:Post-acceleration confirmatory studies carry substantial termination probability, exposing manufacturers to revenue clawback provisions and market withdrawal scenarios under FDA accelerated approval conditions.
- Specialized Infusion Infrastructure Scarcity:Neurology-focused infusion centers concentrate in urban academic medical centers, creating geographic access disparities for rural and suburban patient populations requiring regular intravenous administration.
Strategic Opportunities
- Subcutaneous Formulation Development:Self-administered injection alternatives to intravenous infusion would unlock home care channel expansion and reduce healthcare system capacity constraints.
- Japan's PMDA Sakigake Pathway:Early engagement with Japan's priority review system enables accelerated domestic approval for novel mechanisms, supporting earlier revenue generation in the world's most aged population.
- Digital Biomarker Integration:Smartphone-based cognitive assessment tools paired with wearable sensors are enabling remote patient monitoring and decentralized trial execution for recruitment and retention advantages.
Industry Challenges
- Specialized Neurology Nursing Shortages:Infusion administration, adverse event monitoring, and patient counseling for amyloid-targeting therapies require trained neurodegenerative disease specialists in limited supply.
- Biomarker Assay Standardization Delays:Variability between cerebrospinal fluid collection protocols, analytical platforms, and cutoff thresholds complicates patient selection consistency across clinical and commercial settings.
- Brain Penetration Efficacy Uncertainty:Blood-brain barrier transit rates for systemically administered antibodies remain variable, creating dosing and scheduling optimization challenges that extend development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dementia and Alzheimers Disease Treatment Market |
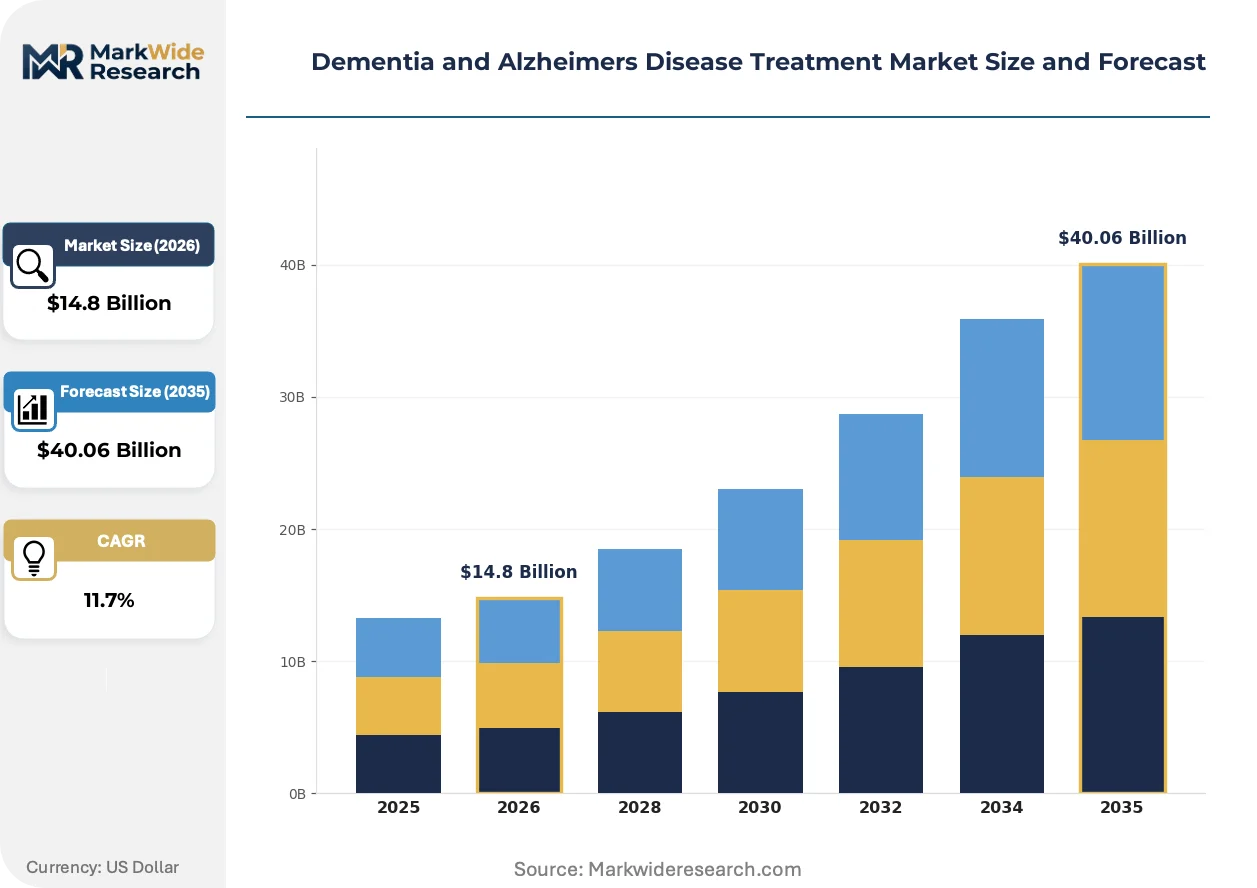
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $40.06 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cholinesterase Inhibitors, NMDA Receptor Antagonists, Combination Therapy, Monoclonal Antibodies Application: Clinical Trials, Home Care, Hospital Care, Palliative Care End User: Patients, Caregivers, Healthcare Providers, Pharmaceuticals Treatment Stage: Diagnosis, Early Stage, Moderate Stage, Late Stage |
| Companies Covered | Biogen Inc., Eli Lilly and Company, Roche Holding AG, Novartis AG, Eisai Co., Ltd., Johnson & Johnson, Pfizer Inc., Merck & Co., Inc., AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dementia and Alzheimers Disease Treatment Market Trends and Innovations
Biotechnology platforms are converging with digital infrastructure to reshape how Alzheimer's therapies are developed, administered, and reimbursed, with particular momentum around decentralized care models and algorithmic patient identification.
Subcutaneous monoclonal antibody delivery systems are decentralizing administration from hospital infusion suites to specialty pharmacy and home care settings. Neurology practices in Germany and the Netherlands are piloting nurse-supervised home injection programs for maintenance dosing. This shift is compressing healthcare system capacity constraints while elevating cold-chain logistics requirements for last-mile distribution.
The EU AI Act's risk classification framework for medical decision-support algorithms is reshaping how diagnostic software integrates with therapeutic protocols. Digital tools that recommend patient eligibility for amyloid-targeting therapies now face conformity assessment obligations and transparency requirements. Developers in France and Sweden are restructuring algorithmic architectures to meet explainability standards before commercial deployment.
Integrated delivery networks in the United States are consolidating procurement for disease-modifying therapies under centralized pharmacy and therapeutics committees. Hospital systems are replacing physician-led prescribing autonomy with protocol-driven authorization workflows tied to biomarker confirmation and MRI safety screening. This concentration is most visible in Medicare Advantage–dominated markets where risk-bearing entities control specialty drug spend directly.
Dementia and Alzheimers Disease Treatment Market Segmentation
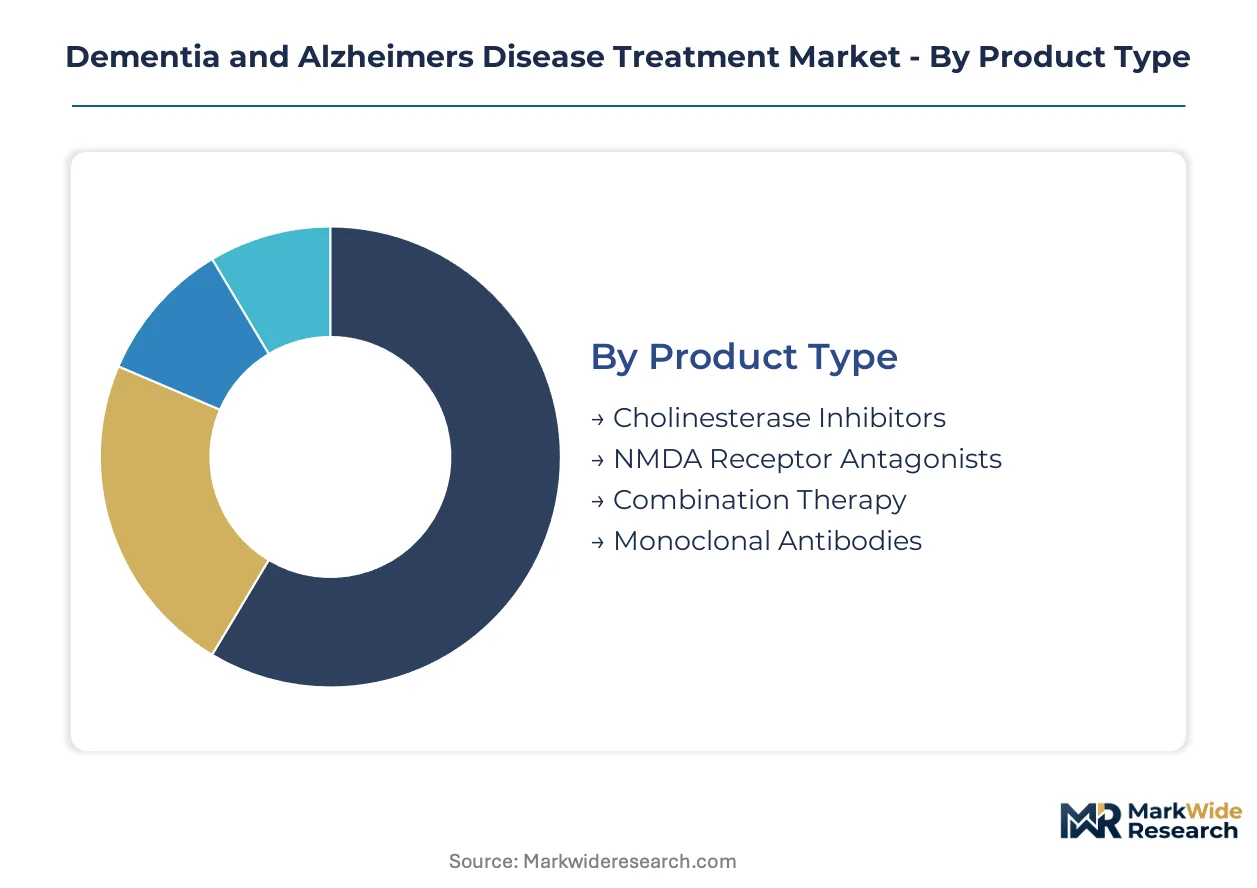
Segmentation in the Alzheimer's treatment market reveals how therapeutic modality, care setting, and disease stage interact to determine pricing power, reimbursement pathways, and competitive intensity. Manufacturers must align formulation development with the infrastructure constraints of each channel.
Product Type:
Prescriber familiarity and payer coverage thresholds drive selection between established small-molecule regimens and emerging biologics.
- Monoclonal Antibodies:Intravenous immunotherapies targeting amyloid-beta require cold-chain distribution and infusion center capacity. Hospital systems in the United States are prioritizing these therapies for early-stage patients with confirmed biomarker positivity, though Medicare coverage with evidence development frameworks create access friction.
- Cholinesterase Inhibitors:Oral small-molecules including donepezil and rivastigmine remain the standard first-line intervention for cognitive symptom management. Generic substitution has compressed pricing, though prescriber comfort sustains volume leadership in primary care settings across Germany and Japan.
- NMDA Receptor Antagonists:Memantine-based therapies address moderate-to-severe disease stages through glutamate modulation, typically prescribed as adjunct therapy to cholinesterase inhibitors in European markets.
- Combination Therapy:Stacked regimens pairing symptomatic agents with disease-modifying approaches are emerging in academic medical centers with integrated pharmacy and therapeutics oversight.
Monoclonal antibodies lead on momentum; cholinesterase inhibitors lead on scale.
Application:
Care setting determines reimbursement mechanics, patient monitoring intensity, and the feasibility of infused versus oral administration.
- Hospital Care:Academic medical centers and neurology-focused infusion suites administer intravenous monoclonal antibodies with mandatory MRI safety monitoring. The FDA's accelerated approval pathway has concentrated early biologic adoption in hospital outpatient departments with biomarker confirmation capabilities.
- Home Care:Oral maintenance regimens and emerging subcutaneous injection programs shift administration from institutional to residential settings. Nurse-supervised home injection pilots in the Netherlands are reducing healthcare system capacity constraints for maintenance dosing.
- Clinical Trials:Research sites execute decentralized protocols using digital biomarker tools for remote cognitive assessment and wearable sensor integration.
- Palliative Care:Late-stage symptom management emphasizes behavioral stabilization and caregiver support over disease modification, with hospice-integrated programs in the United Kingdom prioritizing non-pharmacological interventions.
Hospital care dominates current biologic revenue; home care is climbing the fastest as formulation innovation enables channel shift.
End User:
Decision-making authority fragments across patients, caregivers, and institutional purchasers with divergent risk tolerances and information access.
- Healthcare Providers:Neurologists and geriatricians control prescribing for disease-modifying therapies, though integrated delivery networks are replacing individual physician autonomy with protocol-driven authorization workflows tied to biomarker confirmation.
- Caregivers:Family members influence adherence to oral regimens and transportation logistics for infusion appointments, with caregiver burden assessments increasingly incorporated into treatment selection in Japanese clinical practice.
- Patients:Early-stage individuals with preserved decisional capacity participate in shared decision-making for amyloid-targeting therapies with uncertain clinical benefit profiles.
- Pharmaceuticals:Drug manufacturers and contract research organizations constitute the demand base for diagnostic assays, biomarker platforms, and trial execution services.
Healthcare providers lead on prescription volume; caregivers lead on adherence influence.
Treatment Stage:
Pipeline investment concentrates where regulatory pathways are clearest and commercial risk is most manageable.
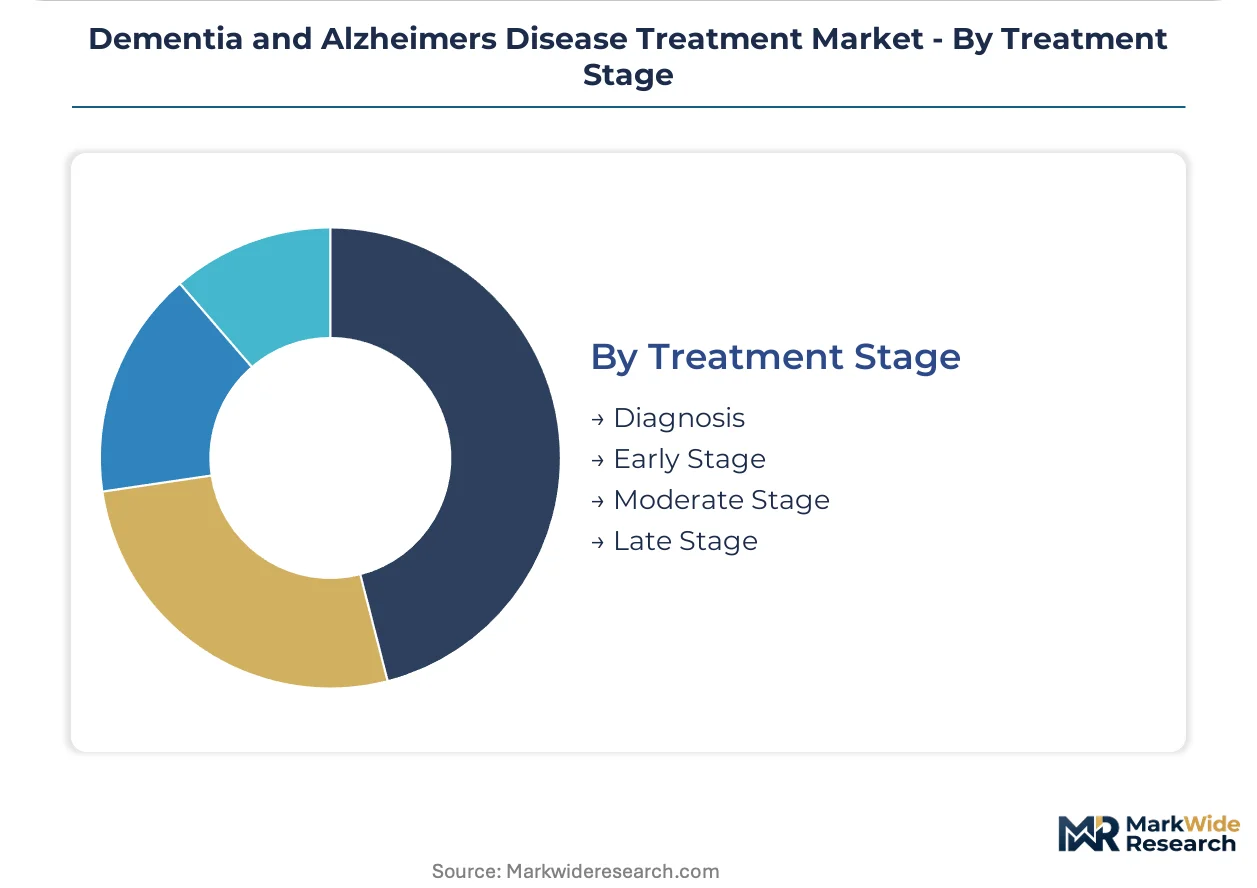
- Early Stage:Pre-symptomatic and mild cognitive impairment populations represent the target for amyloid-clearing monoclonal antibodies with accelerated FDA approval. Biomarker-guided patient selection through cerebrospinal fluid assays and PET imaging is expanding addressable populations in United States academic centers.
- Moderate Stage:The largest currently treatable patient pool receives symptomatic agents and emerging combination regimens, with Medicare Advantage risk-bearing entities controlling specialty drug spend in concentrated markets.
- Diagnosis:Cognitive screening and biomarker confirmation services create demand for diagnostic-therapeutic integration, with Roche pairing cerebrospinal fluid assays with therapeutic development.
- Late Stage:Severe dementia management emphasizes behavioral symptoms and supportive care, with limited disease-modifying intervention feasibility due to blood-brain barrier penetration challenges and neuronal loss.
Moderate stage leads on current patient volume; early stage leads on pipeline investment intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology corridor anchors pharmaceutical innovation for neurodegenerative therapeutics, with academic medical centers driving biomarker-guided patient selection protocols and early-stage clinical trial density.
United States
Medicare reimbursement structures favor innovative biologic treatments through coverage with evidence development frameworks. The FDA's accelerated approval pathway compresses commercial launch timelines while elevating confirmatory trial obligations. Hospital systems in Massachusetts and California are consolidating procurement under centralized pharmacy and therapeutics committees.
Germany
Neurology practices pilot nurse-supervised home injection programs for maintenance dosing of subcutaneous formulations. The EU AI Act imposes algorithmic transparency requirements on digital diagnostic tools paired with therapeutic protocols. Academic centers in Munich and Heidelberg lead biomarker assay standardization efforts for cerebrospinal fluid collection protocols.
Japan
The world's most aged population generates concentrated demand for disease-modifying interventions in pre-symptomatic populations. PMDA's Sakigake designation accelerates domestic review for novel mechanisms, influencing multinational launch sequencing. Tokyo and Osaka metropolitan areas concentrate infusion center infrastructure and specialized neurology nursing capacity.
Switzerland
Diagnostic-therapeutic integration strategies pair biomarker platforms with therapeutic development across Basel and Zurich clusters. Swissmedic maintains alignment with EMA conditional marketing authorization pathways while preserving national pricing autonomy. Roche's cerebrospinal fluid assay capabilities anchor the country's positioning in patient selection technology.
United Kingdom
NICE technology appraisals determine National Health Service access for amyloid-targeting monoclonal antibodies with contested cost-effectiveness profiles. Integrated care systems in London and Manchester are restructuring neurology referral pathways to accommodate biomarker confirmation requirements. Hospice-integrated programs prioritize non-pharmacological interventions for late-stage behavioral symptom management.
Dementia and Alzheimers Disease Treatment Market Competitive Landscape
Global majors compete with regional champions across therapeutic modality and diagnostic integration capabilities. The market structure concentrates around biotechnology specialists with monoclonal antibody platforms and diversified pharmaceutical conglomerates with parallel diagnostic assets. Three archetypes dominate: amyloid-targeting biologic developers, tau-pathway diversification strategists, and diagnostic-therapeutic integrators. Competitive moves center on subcutaneous formulation development and biomarker assay partnerships.
Within the biologic development tier, Biogen Inc., Eli Lilly and Company, and Roche Holding AG occupy distinct positioning vectors. Biogen represents the pioneering monoclonal antibody platform archetype with established early-stage treatment segment presence. Eli Lilly exemplifies pipeline depth across multiple tau and amyloid mechanisms. Roche anchors diagnostic-therapeutic integration, pairing cerebrospinal fluid biomarker assays with therapeutic development. These three entities collectively illustrate how manufacturing complexity and clinical differentiation command premium positioning in hospital care settings.
| Leading Market Players |
|---|
| Biogen Inc. |
| Eli Lilly and Company |
| Roche Holding AG |
| Novartis AG |
| Eisai Co., Ltd. |
| Johnson & Johnson |
| Pfizer Inc. |
| Merck & Co., Inc. |
| AbbVie Inc. |
| Others |
Pricing and Supply Chain Analysis
Venture-backed biologics specialists rolled up through 2021-2023 financing rounds now anchor supply-side concentration for amyloid-targeting monoclonal antibodies, translating cold-chain manufacturing scarcity into premium pricing discipline across hospital outpatient departments and academic infusion centers.
Pricing Analysis
Plasma fractionation cost pass-through from immunoglobulin feedstock constraints elevates input expenses for antibody-based therapeutics, compressing margins on established biologics while preserving premium positioning for novel mechanisms. Pricing stratifies across premium intravenous infusions, standard subcutaneous maintenance, and economy-tier oral generics based on biomarker confirmation requirements and administration complexity. Pricing pressure stems from Medicare coverage with evidence development clawback provisions. Medicare Advantage risk-bearing entities exhibit highest price sensitivity; early-stage academic medical centers demonstrate lowest.
Supply Chain Analysis
FDA current Good Manufacturing Practice certification and EMA Annex 1 sterile manufacturing standards gate contract development and manufacturing organization selection for cold-chain biologics, concentrating fill-finish capacity in Switzerland, Ireland, and Singapore. Manufacturing draws from fractionated plasma derivatives, single-use bioreactor systems, and temperature-controlled packaging materials. Single-source vulnerability permeates specialized neurology nursing and infusion center infrastructure. Distribution runs through hospital outpatient pharmacies and specialty pharmacy networks with last-mile cold-chain integrity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Dementia and Alzheimers Disease Treatment Market reads as a late-cycle quality story where demand migrates toward biomarker-confirmed, disease-modifying interventions with demonstrated amyloid clearance, displacing symptomatic-only regimens in prescriber preference hierarchies.
For Market Incumbents: Extend diagnostic-therapeutic integration capabilities through cerebrospinal fluid assay partnerships and MRI safety screening infrastructure to defend against emerging subcutaneous formulation entrants. Prioritize backward integration into biomarker platform control and capacity expansion in Japan's PMDA Sakigake pathway to secure priority review positioning. For New Entrants and Emerging Players: The EU AI Act's algorithmic transparency requirements in France and Sweden open a window for compliant digital diagnostic tools paired with therapeutic protocols. Target home care channel penetration for maintenance dosing through nurse-supervised injection programs, leveraging decentralized trial execution capabilities as go-to-market differentiation. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap diagnostic-therapeutic integrators lacking commercial-stage biologic assets but possessing biomarker assay platforms. Long-term viability hinges on confirmatory trial outcome resolution and subcutaneous formulation pipeline depth. Monitor FDA accelerated approval confirmatory study readouts as inflection signal for revenue clawback risk exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Enables home care channel expansion and reduces hospital infusion center capacity constraints. |
| Biomarker Assay Partnership | Roche's cerebrospinal fluid platform integration secures patient selection control for therapeutic protocols. |
| PMDA Sakigake Engagement | Accelerates domestic Japanese approval for novel mechanisms in the world's most aged population. |
| Digital Diagnostic Compliance | EU AI Act conformity assessment enables algorithmic patient eligibility tools in European markets. |
| Specialized Nursing Capacity Build | Addresses infusion administration and adverse event monitoring bottlenecks in amyloid-targeting therapy delivery. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored the analytical framework.
Bottom-up volume estimates by treatment stage, therapeutic modality, and administration route were cross-referenced against top-down pharmaceutical revenue disclosures across the projection horizon. Segmentation dimensions encompassed product type, care setting, end user archetype, and disease progression stage. CAGRs derived from patent expiry curves, biosimilar entry timelines, and regulatory approval velocity assumptions.
Revisions become necessary when confirmatory trial failures trigger accelerated approval withdrawal, biomarker assay standardization delays reshape addressable populations, or plasma collection disruptions intensify manufacturing input constraints. A model refresh is warranted upon material change in Medicare coverage with evidence development framework terms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Radiation Therapy Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
Laser Therapy Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Mesotherapy Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Stereotactic Radiation Therapy Market
Medical Treatment
Burns Treatment Market
Medical Treatment
Lymphedema Treatment Market
Medical Treatment
Anti-Rickettsial Treatment Market
Medical Treatment
Global Von Willebrand Disease Treatment Market
Medical Treatment
Myotonic Dystrophy Treatment Market
Medical Treatment
Bromhidrosis Disease Treatment Market
Medical Treatment
Mercury Poisoning Treatment Market
Medical Treatment
Motion Sickness Treatment Market