
 Hydrazine Market | 2026-2036
Hydrazine Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrazine Market Intelligence
Technical-grade supply contracts with embedded water treatment monitoring services is hardening as the dominant commercial format across industrial accounts. Arkema S.A. leverages its European manufacturing base to sustain long-term aerospace propulsion contracts. LANXESS AG anchors its position through backward integration into precursor chemicals, while Nippon Carbide Industries Co., Inc. differentiates via specialized hydrate grades for pharmaceutical synthesis.
Hydrazine refers to a colorless, flammable liquid with the chemical formula N₂H₄, produced primarily through the Raschig process or urea-based methods, serving as a powerful reducing agent and propellant across multiple industrial systems. Hydrazine hydrate dominates commercial volumes due to its safer handling profile and broad applicability in boiler water treatment and agrochemical intermediates, though anhydrous hydrazine commands premium positioning in aerospace propulsion where purity thresholds exceed standard industrial grades. The pharmaceutical application segment exhibits the steepest structural ascent as CDMOs expand active pharmaceutical ingredient manufacturing capacity, while agricultural chemicals maintains mature, volume-driven demand patterns tied to global crop protection cycles.
EPA regulations under the Clean Air Act and OSHA permissible exposure limits constrain domestic production economics and handling protocols in the United States, whereas REACH registration requirements and ECHA classification protocols govern European market access and product stewardship obligations. China's MEE enforces wastewater discharge standards that directly impact hydrazine manufacturing facility permitting and operating costs. Stakeholders must monitor evolving peroxide-based deoxygenation substitutes and regional carbon-intensity regulations that could reshape process technology investment priorities.
Market Dynamics
Water treatment utilities in China, India, and Japan are accelerating hydrazine hydrate procurement as boiler deoxygenation standards tighten under national environmental frameworks. This demand concentration is compressing supply lead times and reshaping contract structures toward embedded technical service bundles.
Growth Catalysts
- Boiler Water Treatment Expansion:Asia-Pacific power generation infrastructure buildout under China's dual carbon goals and India's National Electricity Plan is expanding hydrazine hydrate offtake for thermal plant water chemistry management.
- REACH Registration Compliance:European ECHA classification protocols for high-volume industrial chemicals are consolidating compliant supplier pools, advantaging established registrants with complete toxicological dossiers.
- CDMO Capacity Buildout:Contract development and manufacturing organizations in pharmaceutical synthesis are expanding hydrazine derivative demand for active pharmaceutical ingredient intermediates.
Market Restraints
- Chlorine Input Cost Volatility:Raschig process economics hinge on sodium hypochlorite and ammonia pricing, with energy-intensive chlor-alkali production exposing margins to electricity tariff fluctuations.
- Peroxide Substitution Threat:Carbohydrazide and catalyzed sodium sulfite chemistries are displacing hydrazine in low-pressure boiler systems where oxygen scavenging performance requirements are less stringent.
- OSHA Exposure Thresholds:United States permissible exposure limits for hydrazine vapor constrain handling automation investments and elevate workplace monitoring compliance burdens.
Strategic Opportunities
- Pharmaceutical Grade Specialization:Hydrazine hydrate meeting USP and EP monograph specifications commands substantial premia over technical grades, with synthesis route traceability becoming a procurement discriminator.
- Carbon-Intensity Regulation Alignment:China's MEE wastewater discharge standards and provincial carbon trading schemes are creating first-mover advantages for producers with closed-loop manufacturing and captive energy recovery.
- Aerospace Propulsion Contracts:Anhydrous hydrazine purity specifications exceeding 99.5% for satellite and launch vehicle applications sustain long-term offtake agreements with national space programs.
Industry Challenges
- Process Safety Engineering Talent Scarcity:Specialized expertise in exothermic hydrazine synthesis hazard analysis and relief system design is concentrated among retiring cohorts at legacy production facilities.
- ISO Tank Certification Timelines:Multimodal transport authorization for hydrazine hydrate bulk shipments requires extended UN portable tank testing and national dangerous goods authority approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrazine Market |
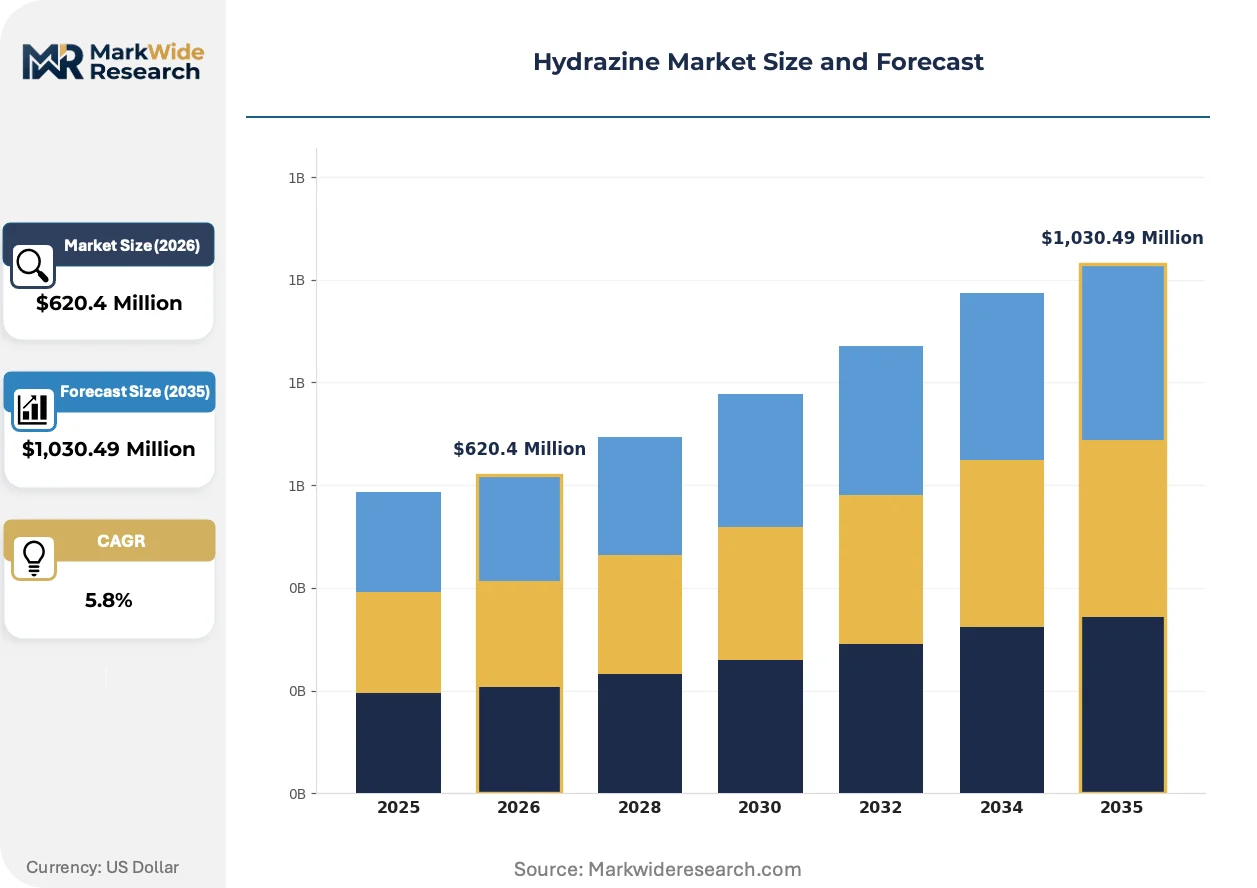
| Market Size in 2026 | $620.4 Million |
| Market Size in 2035 | $1,030.49 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrazine Hydrate, Anhydrous Hydrazine, Hydrazine Sulfate, Technical Grade Hydrazine Application: Aerospace Propulsion, Agriculture Chemicals, Pharmaceuticals, Water Treatment End User: Aerospace Industry, Chemical Manufacturing, Pharmaceutical Companies, Agricultural Sector Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Arkema S.A., LANXESS AG, Nippon Carbide Industries Co., Inc., Otsuka Chemical Co., Ltd., Yibin Tianyuan Group, Hunan Zhuzhou Chemical Industry Group Co., Ltd., Lonza Group AG, Japan Finechem Company, Inc., Weifang Yaxing Chemical Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrazine Market Strategic Shifts & Innovations
Process intensification and regulatory chemistry are compressing traditional hydrazine manufacturing economics while opening specialty grade niches. Technology convergence between water treatment monitoring and chemical supply is restructuring commercial relationships.
Continuous flow reactor technology is unifying hydrazine synthesis steps that historically required batch-wise separation and intermediate storage. European specialty chemical producers are retrofitting Raschig process trains with microreactor modules to reduce hold-up volumes and thermal runaway risk. This architecture is enabling just-in-time production footprints adjacent to major water treatment utility clusters.
China's MEE is enforcing real-time wastewater discharge monitoring through networked sensor mandates at chemical manufacturing facilities. Hydrazine producers face elevated capital requirements for effluent treatment system upgrades and continuous emissions verification infrastructure. Facilities in Jiangsu and Zhejiang provinces are responding by consolidating production at integrated sites with captive tertiary treatment capacity.
Technical service bundling is displacing commodity-only supply contracts in industrial water treatment accounts. Buyers in Japanese thermal power and Korean semiconductor fabrication facilities now expect dissolved oxygen monitoring, dosage optimization algorithms, and regulatory reporting assistance as standard contract inclusions. This shift compresses margins on hydrate volumes while extending customer lock-in duration.
Hydrazine Market Segmentation
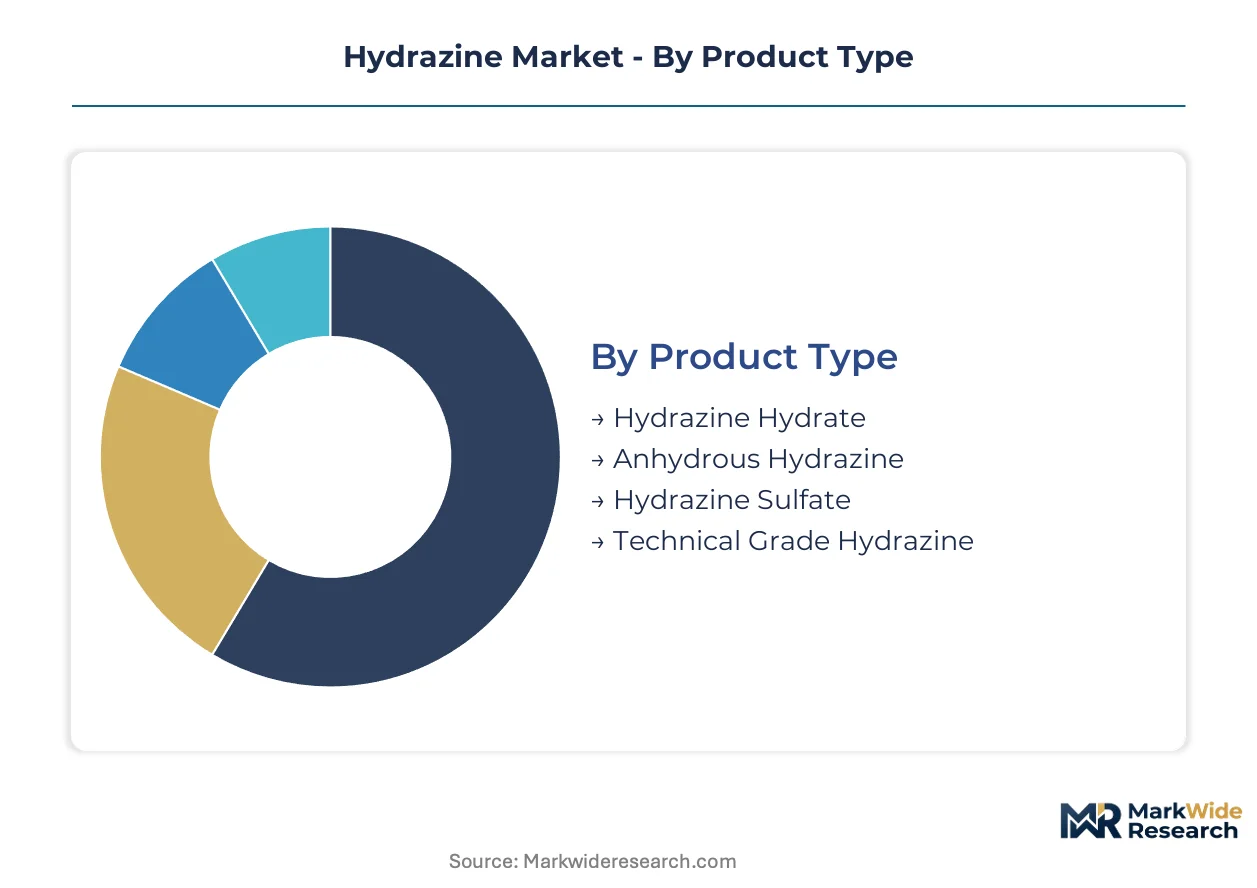
Hydrazine market segmentation reveals divergent buyer priorities across purity grades, application risk profiles, and procurement sophistication levels. Each category shapes contract structures, pricing mechanisms, and supplier qualification requirements in distinct ways.
Product Type:
Buyers differentiate primarily by handling safety thresholds and purity specifications rather than price sensitivity alone.
- Hydrazine Hydrate:An aqueous solution typically containing 35-80% hydrazine by weight, offering reduced flammability and toxicity exposure compared to anhydrous forms. Water treatment utilities in China and India specify hydrate grades for boiler deoxygenation under tightening MEE and Central Electricity Authority discharge protocols.
- Anhydrous Hydrazine:The pure N₂H₄ compound exceeding 99.5% concentration, demanding specialized storage and handling infrastructure. Aerospace propulsion programs in the United States and Europe mandate anhydrous specifications for satellite maneuvering thrusters and launch vehicle attitude control systems.
- Hydrazine Sulfate:A crystalline salt derivative with enhanced stability profile, primarily serving pharmaceutical synthesis intermediates where controlled release characteristics matter.
- Technical Grade Hydrazine:Industrial purity specifications suitable for agrochemical intermediate production and polymerization catalyst applications.
Hydrazine hydrate leads volumes today; anhydrous hydrazine is gaining share fastest in specialty aerospace contracts.
Application:
End-use concentration varies sharply by regulatory intensity and performance requirements.
- Water Treatment:Oxygen scavenging in high-pressure boiler systems remains the volume anchor, with Japanese and Korean power generators embedding technical service bundles into procurement contracts.
- Aerospace Propulsion:Satellite station-keeping and launch vehicle applications sustain premium pricing through national space program offtake agreements with purity thresholds exceeding standard industrial grades.
- Agriculture Chemicals:Mature demand tied to global crop protection cycles, with hydrazine serving as a building block for herbicide and fungicide active ingredients.
- Pharmaceuticals:Contract development and manufacturing organizations are expanding capacity for active pharmaceutical ingredient intermediates, with synthesis route traceability becoming a procurement discriminator under FDA and EMA quality frameworks.
Water treatment dominates current offtake; pharmaceutical applications are expanding most quickly.
End User:
Procurement sophistication separates institutional buyers from fragmented agricultural accounts.
- Chemical Manufacturing:Integrated producers with captive hydrazine derivative capacity, operating under OSHA process safety management and Seveso III obligations in the United States and Europe.
- Aerospace Industry:Prime contractors and national space agencies with long-term supply agreements, technical qualification protocols, and traceability requirements spanning raw material to finished propellant.
- Pharmaceutical Companies:Brand manufacturers and CDMOs subject to FDA current good manufacturing practice and EMA good manufacturing practice inspections for hydrazine-derived API intermediates.
- Agricultural Sector:Formulators and distributors with seasonal demand patterns, price-sensitive procurement, and less stringent documentation requirements.
Chemical manufacturing anchors volume; pharmaceutical companies are climbing the fastest on quality-premium contracts.
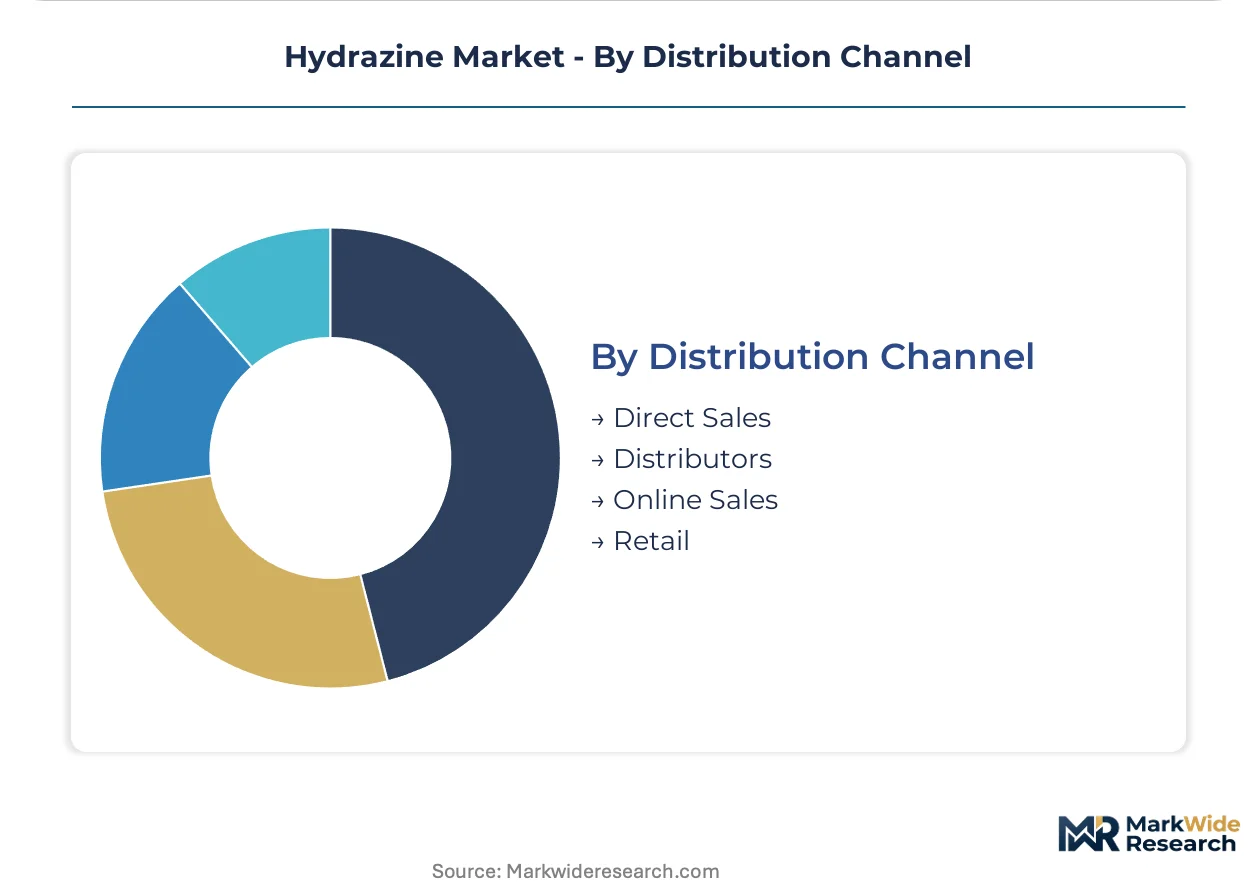
Distribution Channel:
Channel selection correlates with shipment scale, hazard classification, and buyer technical capability.
- Direct Sales:Bulk hydrate deliveries to water treatment utilities and aerospace contractors, often with embedded monitoring services and long-term offtake structures.
- Distributors:Regional chemical distributors handling smaller volume orders, drum packaging, and mixed-product shipments to agricultural and pharmaceutical accounts.
- Online Sales:Limited to research quantities and specialty grades, constrained by dangerous goods shipping regulations and carrier restrictions on hydrazine transport.
- Retail:Minimal penetration, restricted to consumer-adjacent applications with severely diluted formulations.
Direct sales leads volumes today; distributor channels are gaining share fastest in emerging market pharmaceutical sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production economics diverge sharply across jurisdictions as MEE discharge mandates in China, OSHA exposure thresholds in the United States, and REACH registration burdens in Europe create compliance-cost arbitrage that favors integrated manufacturing clusters with captive treatment infrastructure.
China
Thermal power expansion under the National Electricity Plan and dual carbon transition timelines is compressing hydrazine hydrate procurement cycles for boiler water treatment. MEE real-time wastewater monitoring mandates at chemical facilities in Jiangsu and Zhejiang are consolidating output at integrated sites with tertiary treatment capacity. Production gravity is shifting toward Zhejiang's chemical parks where captive energy recovery systems offset carbon-trading compliance costs.
India
Central Electricity Authority deoxygenation standards for thermal plants are accelerating technical-grade hydrazine offtake as utilities modernize water chemistry protocols. The PLI scheme for specialty chemicals is attracting capital toward pharmaceutical-grade hydrate capacity near Hyderabad and Ahmedabad. Gujarat's Dahej and Mundra industrial corridors are emerging as procurement hubs for agrochemical intermediate manufacturers.
United States
Aerospace propulsion contracts for satellite maneuvering systems sustain anhydrous hydrazine demand through NASA and defense program offtake agreements. EPA Clean Air Act constraints and OSHA permissible exposure limits are elevating handling automation investments at legacy production facilities. Gulf Coast chemical manufacturing clusters in Texas and Louisiana leverage existing chlor-alkali infrastructure for Raschig process feedstock access.
Germany
REACH registration compliance and ECHA classification protocols for high-volume industrial chemicals are consolidating compliant supplier pools among established registrants. The country's pharmaceutical CDMO sector is expanding hydrazine derivative demand for active pharmaceutical ingredient intermediates under EMA good manufacturing practice frameworks. BASF Ludwigshafen and Bayer Leverkusen anchor demand concentration in the Rhine-Ruhr chemical corridor.
Japan
METI energy efficiency mandates for thermal power generators are embedding technical service bundles into hydrazine hydrate procurement contracts. Semiconductor fabrication facilities in Kyushu and Kansai are specifying dissolved oxygen monitoring and dosage optimization as standard contract inclusions. Nippon Carbide Industries and Japan Finechem occupy positions in the domestic specialty-grade supply structure.
Hydrazine Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with aerospace propulsion and pharmaceutical synthesis favoring qualified incumbents while water treatment utilities prize technical service bundling over brand equity. The vendor base organizes into three strategic archetypes: European-headquartered registrants with complete REACH toxicological dossiers, Asia-Pacific integrated producers with backward control into precursor chemicals, and Japanese specialists in hydrate grades for pharmaceutical synthesis. Dominant competitive moves include capacity consolidation at MEE-compliant Chinese sites and pharmaceutical-grade specialization to capture USP and EP monograph premia.
Within the European registrant tier, Arkema S.A. and LANXESS AG exemplify positioning built on regulatory compliance infrastructure and long-term aerospace contract structures. Among Asia-Pacific integrated producers, Yibin Tianyuan Group and Hunan Zhuzhou Chemical Industry Group Co., Ltd. represent scale-driven manufacturing archetypes with proximity to domestic water treatment utility demand. Japanese specialists Nippon Carbide Industries Co., Inc. and Japan Finechem Company, Inc. occupy positions in the pharmaceutical-grade hydrate segment where synthesis route traceability commands procurement discrimination.
| Leading Market Players |
|---|
| Arkema S.A. |
| LANXESS AG |
| Nippon Carbide Industries Co., Inc. |
| Otsuka Chemical Co., Ltd. |
| Yibin Tianyuan Group |
| Hunan Zhuzhou Chemical Industry Group Co., Ltd. |
| Lonza Group AG |
| Japan Finechem Company, Inc. |
| Weifang Yaxing Chemical Co Ltd |
| Others |
Cost & Logistics Intelligence
Technical service bundling in Japanese and Korean water treatment procurement is forcing hydrate suppliers to absorb monitoring infrastructure costs into contract pricing, compressing commodity margins while extending customer lock-in duration. This shift rewards producers with captive technical service capabilities and penalizes pure commodity traders.
Pricing Analysis
Distributor markups on drum-packaged hydrate for agricultural and pharmaceutical accounts typically run higher than direct-to-utility bulk contracts, which embed dosage optimization and regulatory reporting assistance. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and economy hydrate levels reflects certification burden and synthesis route traceability requirements. Pricing pressure stems from peroxide-based oxygen scavengers gaining share in low-pressure boiler systems where performance thresholds permit substitution. Agricultural formulators exhibit highest price sensitivity due to seasonal demand patterns and limited specification differentiation, while aerospace contractors prioritize purity assurance over unit economics.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale hydrate demand from Chinese and Indian thermal power operators, while regional distributors manage fragmented agricultural and pharmaceutical accounts. Manufacturing concentrates in China, Germany, and the United States, with Zhejiang chemical parks and Gulf Coast chlor-alkali clusters anchoring regional supply. Raschig process economics rest on sodium hypochlorite, ammonia, and electricity inputs, exposing margins to energy tariff volatility. Single-source vulnerability concentrates in anhydrous hydrazine purification capacity qualified for aerospace propulsion contracts. Distribution runs through ISO-certified tank operators for bulk hydrate, with extended UN portable tank certification timelines constraining multimodal flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with China's MEE real-time wastewater monitoring mandates and REACH registration consolidation in Europe continuously raising compliance barriers that favor incumbent scale.
For Market Incumbents: Anchor market position through backward integration into chlor-alkali feedstocks and captive tertiary treatment capacity at MEE-compliant Chinese sites. Peroxide substitution in low-pressure boiler systems threatens volume erosion in technical-grade hydrate, demanding defensive specialization toward pharmaceutical-grade USP and EP monograph production. Certification investment in ISO tank fleets and aerospace propulsion qualification protocols extends customer switching costs. For New Entrants and Emerging Players: Continuous flow reactor technology offers a technology-first wedge to reduce thermal runaway risk and enable just-in-time production footprints adjacent to major utility clusters. White-space targets concentrate in pharmaceutical-grade hydrate for CDMOs near Hyderabad and Ahmedabad, plus technical service bundles for Korean semiconductor fabrication facilities. Go-to-market positioning should emphasize synthesis route traceability under FDA and EMA frameworks as a procurement discriminator. For Investors and Strategic Acquirers: Asymmetric upside sits with European-headquartered registrants possessing complete REACH toxicological dossiers and established aerospace contract structures. Long-term viability hinges on carbon-intensity regulation alignment as China's provincial trading schemes mature. Acquisition target archetype: integrated producers with captive energy recovery and MEE-compliant wastewater infrastructure. The signal to watch is carbohydrazide displacement rates in low-pressure boiler retrofits as a demand destruction indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Chlor-alkali capacity capture insulates Raschig process margins from electricity tariff volatility. |
| Pharmaceutical Grade Specialization | USP and EP monograph qualification commands substantial premia over technical hydrate grades. |
| Technical Service Bundling | Dissolved oxygen monitoring and dosage optimization algorithms extend customer lock-in duration. |
| Carbon-Intensity Alignment | Closed-loop manufacturing with captive energy recovery creates first-mover advantage under MEE standards. |
| Aerospace Propulsion Qualification | Anhydrous hydrazine purity exceeding 99.5% sustains long-term offtake with national space programs. |
Research Approach
Coverage spans China, India, the United States, Germany, and Japan, with primary inputs from each jurisdiction's chemical manufacturing and utility procurement stakeholders. The research combines interviews with plant managers at hydrazine production facilities, procurement leads at thermal power utilities and aerospace contractors, distribution channel partners handling drum-packaged hydrate, and technical R&D directors at CDMOs, validated against secondary sources including customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and MEE wastewater discharge compliance records. Bottom-up capacity and demand estimates triangulate against top-down market sizing from trade flow analysis.
Segmentation granularity extends to purity grade tier, end-use application, packaging format, and regional production hub, with aerospace propulsion purity specifications and pharmaceutical synthesis route traceability modeled as distinct demand drivers. CAGRs derive from capacity expansion announcements, utility procurement cycle analysis, and CDMO capacity buildout tracking across the projection horizon. Forecast inputs include chlor-alkali electricity intensity, MEE compliance cost trajectories, and REACH registration maintenance burdens.
The model holds under continued MEE enforcement intensity and REACH dossier completeness requirements; deviation in peroxide substitution rates or carbon trading scheme coverage would shift volume and value trajectories. Forecasts reflect assumptions about regulatory stability, process safety engineering talent availability, and ISO tank certification throughput capacity. Periodic stress-testing of base assumptions against carbohydrazide displacement signals and aerospace program budget allocations is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Scouring Agents Market
Chemicals
Dimethylaminopropylamine (DMAPA) Market
Chemicals
Power Plant Chemicals Market
Chemicals
North America Oxo-Alcohol Market
Chemicals
p-Coumaric Acid Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Potassium Alum Market
Chemicals
Maleic Acid Market
Chemicals
Anhydrides Market
Chemicals
Aromatic Polyamine Market
Chemicals
3-Dimethylacrylic Acid Methyl Ester Market
Chemicals
Calcium Hydroxide Market
Chemicals
Laboratory Chemicals Market
Chemicals
Diphosphate Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market