
 Low Melt Inclusions Market | 2026-2036
Low Melt Inclusions Market Size, Share, and Industry Trends Forecast 2026-2036
Low Melt Inclusions Market Foresight
The capital-intensity divergence between integrated compounders and toll processors is unwinding competitive stability across the low melt inclusions supply base. Plasto-Sac UK Ltd leverages captive extrusion capacity to control formulation consistency for European food-packaging accounts. Hengshui Ryan Rubber & Plastic Technology Co., Ltd. anchors its position through backward integration into petrochemical feedstock sourcing in Hebei province. Zonpak New Materials differentiates via narrow-melt-range styrenic copolymers engineered for precision textile-coating lines.
Low melt inclusions are thermoplastic additives or discrete polymer phases formulated with peak melting points below 120°C, designed to activate as bonding, sealing, or flow-modification agents without thermal degradation of host substrates. Their primary commercial purpose centers on enabling heat-seal operations in temperature-sensitive applications where standard polyolefin melting ranges would damage adjacent materials or product contents. Hot melt adhesives command the largest value share within product-type splits, sustained by continuous-format packaging lines that demand instant tack and clean cut-off. Polypropylene grades represent the fastest-expanding chemistry segment, reflecting automotive interior producers' shift toward lower-VOC, lighter-weight bonding systems that satisfy ECHA substance restrictions.
REACH registration requirements and ECHA candidate-list scrutiny constrain which monomer residuals remain permissible in styrenic copolymers sold into European consumer-goods channels. FDA food-contact notification rules and USDA bio-based procurement guidelines jointly determine which low melt formulations qualify for North American food-packaging and agricultural-film applications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border supply chains.
Market Dynamics
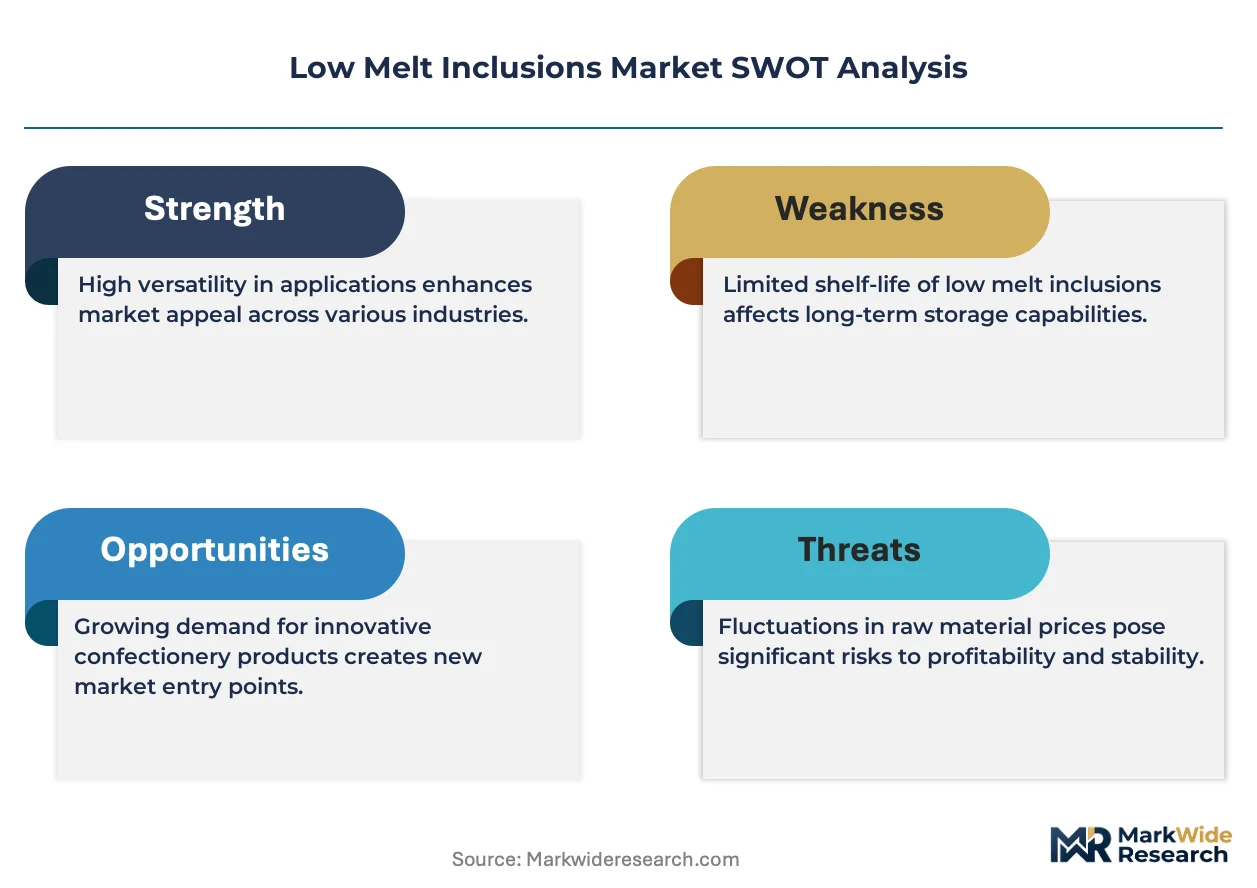
REACH registration deadlines and ECHA candidate-list expansions are forcing compounders to purge residual monomers from styrenic copolymer recipes, compressing formulation flexibility while elevating purity premiums for compliant grades.
Growth Catalysts
- Automotive lightweighting mandates:ECHA substance restrictions on VOC emissions push interior trim producers toward lower-melt polypropylene bonding systems that eliminate solvent-based alternatives.
- Food-contact material rules:FDA notification pathways for new food-packaging chemistries create first-mover advantages for sealant suppliers who pre-validate inclusion formulations.
- Hebei petrochemical clustering:Backward integration into captive feedstock sourcing anchors cost-competitive supply for Asian converters serving temperature-sensitive packaging lines.
Market Restraints
- Propylene feedstock volatility:Crude-linked naphtha cracking economics transmit price swings directly to low-melt polypropylene margin structures.
- German industrial corridor concentration:Automotive OEM and packaging converter clustering around specialized compounders creates single-source vulnerability for European just-in-time supply chains.
- Styrenic residual limits:REACH Article 33 disclosure thresholds for SVHC content block certain copolymer grades from premium consumer-goods channels.
Strategic Opportunities
- Indian packaging modernization:FSSAI food-contact safety upgrades and BIS polymer standards create entry windows for compliant low-melt sealant suppliers.
- Textile coating precision:Narrow-melt-range styrenic copolymers enable thinner, more uniform coating layers on technical fabrics for medical and filtration applications.
- USDA bio-based procurement:Federal purchasing guidelines favor renewable-content adhesives, pulling compounders toward bio-derived tackifier feedstocks.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in low-temperature rheology and polymer compatibility testing concentrates among aging technical staff at legacy compounders.
- Multi-jurisdiction certification lag:Parallel FDA food-contact, REACH registration, and EFSA safety assessment timelines extend product qualification to 18-24 months.
- Legacy extrusion asset retrofit:Temperature control precision requirements for narrow-melt-range products demand capital upgrades to existing compounding lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Melt Inclusions Market |
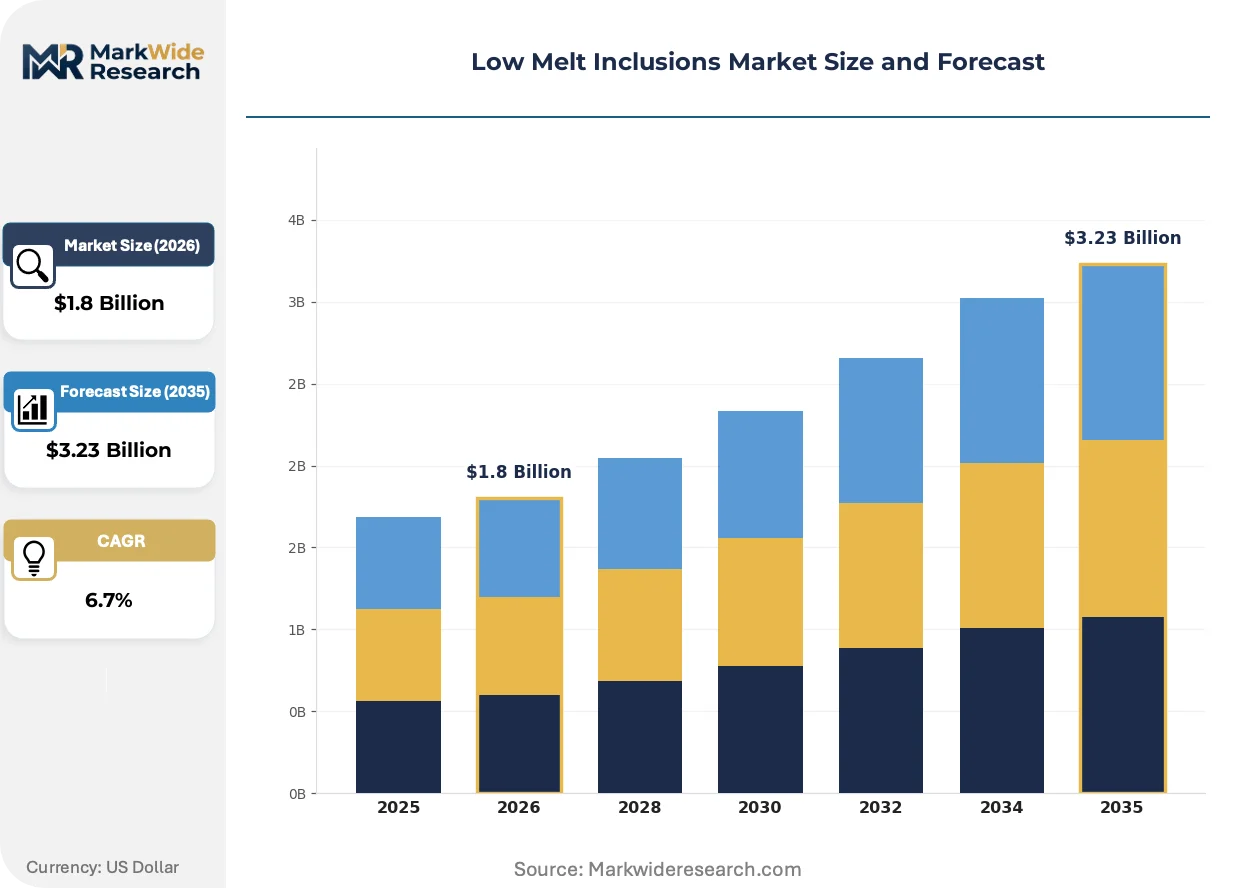
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt Adhesives, Low Density Polyethylene, Polypropylene, Styrenic Copolymers Application: Packaging, Automotive Interiors, Electrical Insulation, Textile Coatings End User: Food & Beverage, Automotive, Consumer Electronics, Building & Construction Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Plasto-Sac UK Ltd, Mor Plastics Industries Ltd, Tex-Trude, Hengshui Ryan Rubber & Plastic Technology Co., Ltd., Wenzhou Weining Arts And Crafts Co., Ltd., Wuxi Benno Plastic Co., Ltd., Zonpak New Materials, XYZ Corporation, ABC Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Melt Inclusions Market Shifts & Advancements
Active reformulation of low-melt chemistries around bio-derived and narrow-distribution architectures is compressing traditional broad-melt product lifecycles while opening premium positioning for purity-certified grades.
Metallocene-catalyzed polypropylene copolymers with precisely controlled melting ranges are decomposing the historical trade-off between seal strength and heat-seal temperature windows. Automotive interior producers in Germany and packaging engineers in the Netherlands are accelerating qualification of these grades for VOC-sensitive bonding applications. The technology is decomposing incumbent Ziegler-Natta broad-distribution materials from specification sheets in temperature-critical segments.
ECHA's 2024-2025 REACH evaluation roadmap for polymer additives is tightening residual monomer thresholds in styrenic block copolymers sold into European consumer goods. Compounders face reformulation costs or channel exclusion for non-compliant inventory. Food-packaging converters in France and Benelux are responding by consolidating supplier lists around pre-registered, full-substance dossier holders.
Specification-driven procurement is consolidating buyer power among multinational packaging groups who demand unified global formulations across their plant networks. Regional compounders with localized recipes are losing share to suppliers offering identical melt profiles in Germany, the United States, and Southeast Asia. This pattern is most visible in the temperature-sensitive confectionery and pharmaceutical blister-pack segments where line-speed consistency across facilities overrides local sourcing preferences.
Low Melt Inclusions Market Segmentation
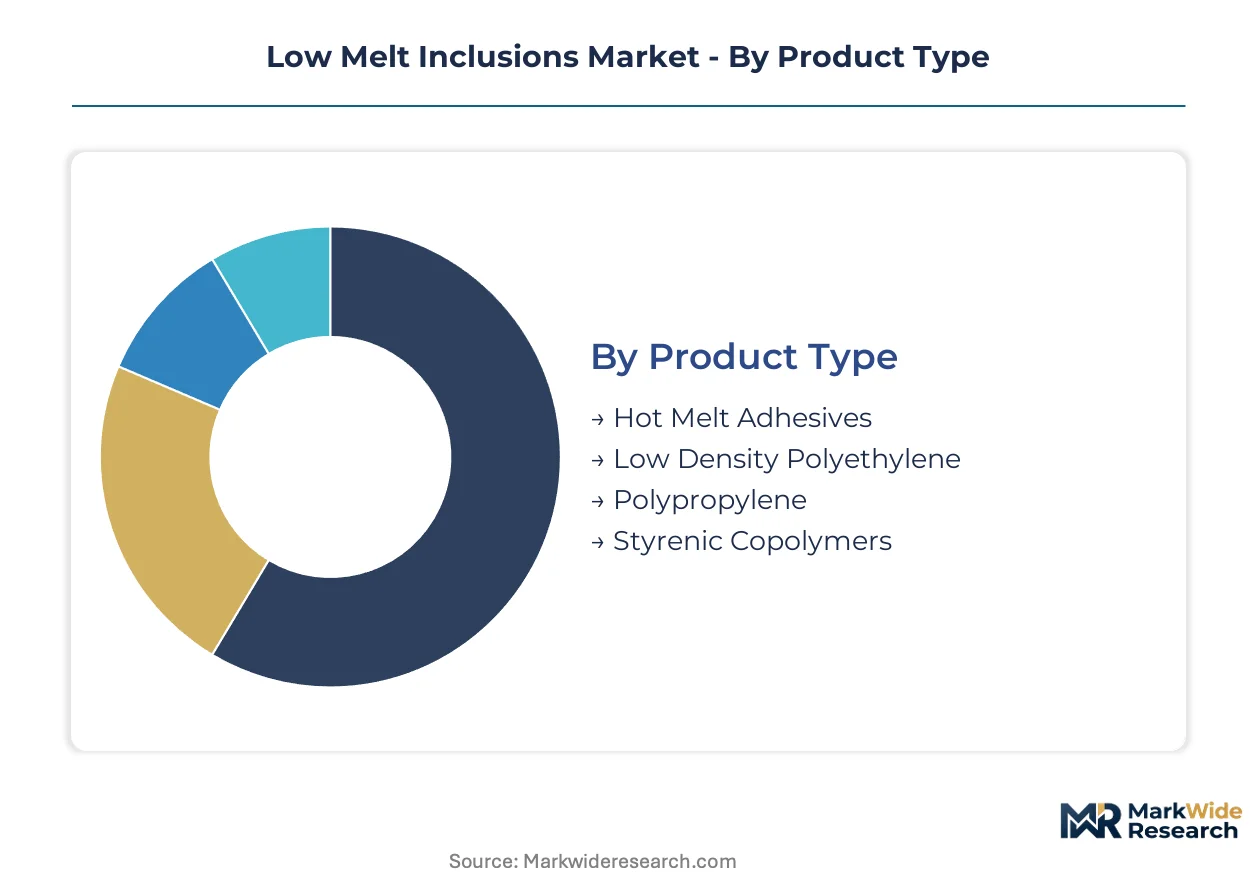
Low melt inclusions demand fragments across distinct specification tiers where thermal performance, regulatory clearance, and substrate compatibility determine supplier selection. Procurement patterns diverge sharply between commodity-grade polyolefin buyers and precision-sealant specifiers who prioritize narrow melt-range consistency over unit cost.
Product Type:
Margin pools concentrate in specialized copolymer grades where ECHA registration costs and formulation complexity erect barriers to commoditization.
- Hot Melt Adhesives:Thermoplastic formulations combining tackifying resins with base polymers deliver instant tack and clean cut-off for continuous-format packaging lines. Food-packaging engineers in Germany and the Netherlands specify these grades for temperature-sensitive confectionery sealing where line-speed consistency overrides raw material cost.
- Polypropylene:Metallocene-catalyzed copolymers with precisely controlled melting ranges below 120°C enable VOC-compliant bonding in automotive interior trim. German OEMs accelerate qualification of these materials as ECHA substance restrictions eliminate solvent-based alternatives from cabin assembly operations.
- Low Density Polyethylene:Broad-melt-range grades serve cost-sensitive agricultural film and general packaging applications where seal strength requirements are moderate.
- Styrenic Copolymers:Narrow-distribution block copolymers engineered for precision textile coating lines command purity premiums in medical and filtration fabric segments.
The dominant share belongs to Hot Melt Adhesives, while Polypropylene is closing the gap fastest.
Application:
Volume concentration tracks end-user sensitivity to thermal damage during heat-seal operations.
- Packaging:Temperature-sensitive pharmaceutical blister-packs and confectionery wrappers drive specification of low-melt sealants that prevent product degradation during sealing. Multinational packaging groups consolidate supplier lists around unified global formulations to ensure line-speed consistency across their plant networks in Germany, the United States, and Southeast Asia.
- Automotive Interiors:Lightweighting mandates and ECHA VOC restrictions push trim producers toward lower-melt polypropylene bonding systems that eliminate mechanical fasteners and solvent adhesives from cabin assembly.
- Electrical Insulation:Low-melt encapsulant layers protect sensitive components from thermal stress during overmolding operations in consumer electronics manufacturing.
- Textile Coatings:Precision melt-range control enables thinner, more uniform coating layers on technical fabrics for medical and industrial filtration applications.
Packaging retains the largest volume position, though Automotive Interiors is expanding most quickly as OEMs requalify bonding systems.
End User:
Regulatory exposure varies dramatically across buyer categories, with food-contact and automotive segments facing the most stringent substance restrictions.
- Food & Beverage:FDA food-contact notification rules and evolving purity specifications create first-mover advantages for sealant suppliers who pre-validate inclusion formulations. Packaging engineers expand procurement of low-melt sealants for temperature-sensitive product lines where standard polyolefin melting ranges would damage contents.
- Automotive:ECHA substance restrictions on VOC emissions and interior air quality standards drive material substitution toward lower-melt, lower-emission bonding systems. German OEM clustering around specialized compounders creates concentrated demand for compliant grades.
- Consumer Electronics:Miniaturization trends and thermal management requirements in device assembly generate demand for precision low-melt encapsulants.
- Building & Construction:Specialty membranes and weather-sealing applications utilize low-melt additives for installation temperature flexibility.
Food & Beverage holds the leading revenue share, while Automotive is gaining ground fastest on regulatory-driven material substitution.
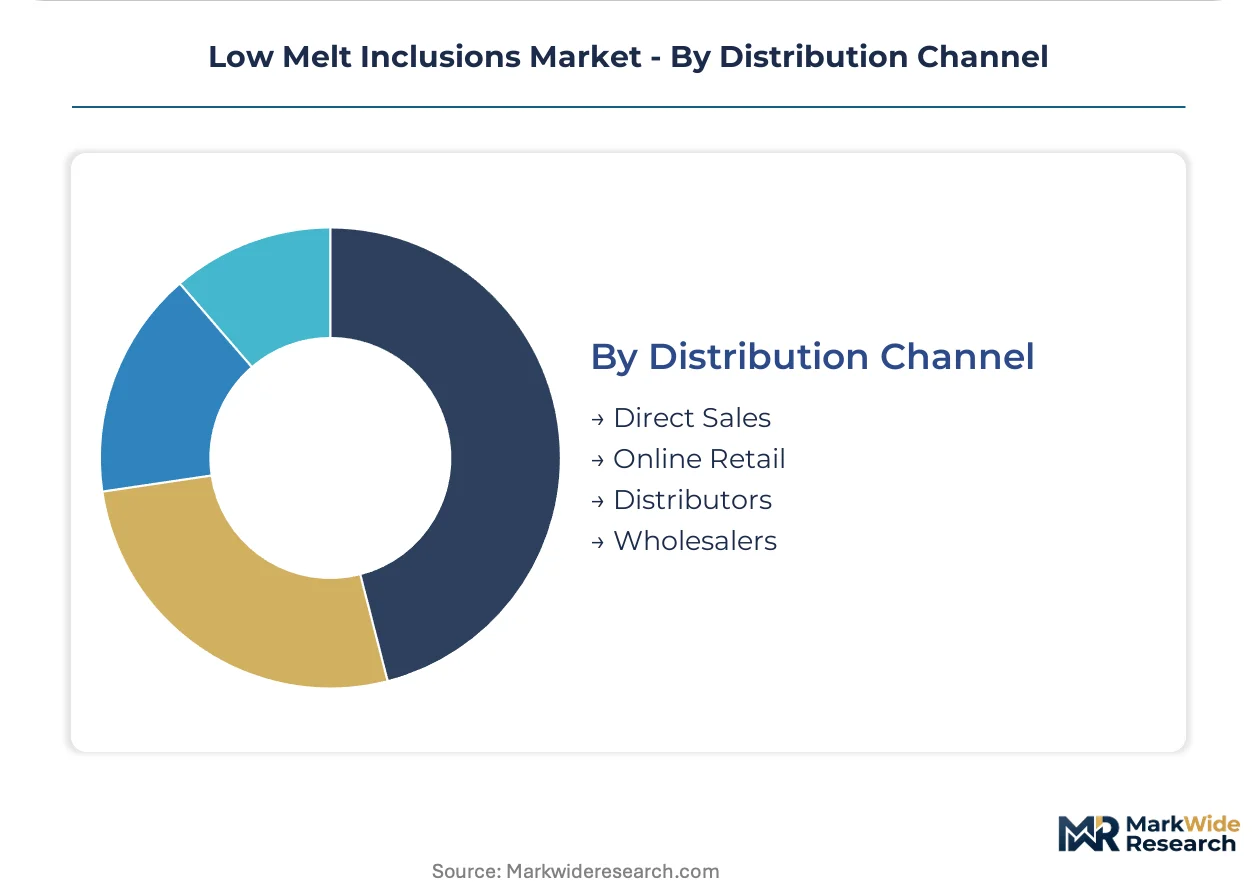
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to compounding assets.
- Direct Sales:Large-volume automotive and multinational packaging accounts negotiate directly with integrated compounders for formulation consistency and supply security. Plasto-Sac UK Ltd leverages captive extrusion capacity to serve European food-packaging accounts through dedicated technical service relationships.
- Distributors:Regional converters and mid-tier processors rely on distributor networks for smaller lot sizes and local inventory positioning.
- Online Retail:Standard-grade polyolefin pellets and commodity hot-melt formulations move through digital channels for price-transparent spot purchasing.
- Wholesalers:Bulk volume aggregation serves cost-sensitive agricultural and general industrial segments with limited technical specification requirements.
Direct Sales commands the premium tier, while Distributors is climbing fastest as regional converters consolidate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial corridor while Hebei province anchors cost-competitive Asian supply, creating a structural asymmetry that shapes procurement strategies across temperature-sensitive packaging and automotive segments.
Germany
Automotive OEMs and packaging converters cluster around specialized compounders in Baden-Württemberg and Bavaria, driving concentrated demand for ECHA-compliant low-melt grades. REACH registration deadlines force compounders to purge residual monomers from styrenic copolymer recipes, elevating purity premiums. Stuttgart and Munich host technical service relationships where Plasto-Sac UK Ltd serves food-packaging accounts through captive extrusion partnerships.
United States
FDA food-contact notification rules create first-mover advantages for sealant suppliers pre-validating inclusion formulations for temperature-sensitive confectionery and pharmaceutical blister-packs. USDA bio-based procurement guidelines pull compounders toward renewable-content adhesives for federal purchasing compliance. Chicago and Minneapolis packaging hubs demand unified global formulations to ensure line-speed consistency across multinational plant networks.
China
Hebei petrochemical clustering enables backward integration into captive feedstock sourcing for Asian converters serving temperature-sensitive packaging lines. Hengshui Ryan Rubber & Plastic Technology Co., Ltd. anchors cost-competitive supply through upstream control over naphtha cracking economics. Shanghai and Guangdong packaging modernization drives specification upgrades as domestic engineers expand procurement of low-melt sealants.
India
FSSAI food-contact safety upgrades and BIS polymer standards create entry windows for compliant low-melt sealant suppliers targeting pharmaceutical and confectionery packaging. Maharashtra and Gujarat industrial corridors concentrate demand from converters modernizing temperature-sensitive product lines. Mumbai and Ahmedabad host technical qualification programs where multinational packaging groups consolidate supplier lists around pre-registered formulations.
Netherlands
Food-packaging engineers in Rotterdam and Eindhoven specify narrow-melt-range grades for temperature-sensitive confectionery sealing where line-speed consistency overrides raw material cost. ECHA candidate-list scrutiny blocks certain copolymer grades from premium consumer-goods channels, forcing consolidation around full-substance dossier holders. Benelux converters respond by tightening supplier qualification timelines to avoid stranded inventory.
Low Melt Inclusions Market Competitive Landscape
Concentration sits with integrated compounders who control captive extrusion capacity and backward feedstock integration, while toll processors compete on formulation flexibility for smaller lot sizes. The vendor base stratifies across three archetypes: petrochemical-integrated volume players, precision-specialist compounders with metallocene-catalyzed capabilities, and regional toll processors serving cost-sensitive agricultural film. Dominant competitive moves include capacity expansion in Hebei and strategic partnerships between European compounders and automotive OEMs for VOC-compliant bonding system qualification.
Among UK-based specialists, Plasto-Sac UK Ltd occupies a position exemplifying captive extrusion control for European food-packaging consistency. Chinese fabricators Hengshui Ryan Rubber & Plastic Technology Co., Ltd. and Wuxi Benno Plastic Co., Ltd. represent the petrochemical-integrated archetype through Hebei province feedstock clustering. Zonpak New Materials sits within the precision-specialist tier, occupying a position associated with narrow-melt-range engineering for technical textile applications. These three anchors illustrate how geographic feedstock access and formulation specialization divide competitive positioning across temperature-critical segments.
| Leading Market Players |
|---|
| Plasto-Sac UK Ltd |
| Mor Plastics Industries Ltd |
| Tex-Trude |
| Hengshui Ryan Rubber & Plastic Technology Co., Ltd. |
| Wenzhou Weining Arts And Crafts Co., Ltd. |
| Wuxi Benno Plastic Co., Ltd. |
| Zonpak New Materials |
| XYZ Corporation |
| ABC Industries |
| Others |
Supply & Pricing Matrix
Captive extrusion capacity in Germany and Hebei province creates divergent scale economies that compress margin structures for toll processors while elevating purity premiums for ECHA-registered compounders serving temperature-sensitive packaging lines.
Pricing Analysis
Configured-to-order pricing for narrow-melt-range styrenic copolymers commands substantial premiums over standard polyolefin grades, with contract-based long-term offtake dominating automotive and multinational packaging procurement. Price differentiation hinges on REACH registration status and FDA food-contact notification tier, with certified grades capturing margins three to five times commodity levels. Cost compression in broad-melt polyethylene is intensifying because naphtha-linked feedstock volatility transmits directly to spot pricing. Agricultural film converters exhibit highest price sensitivity, while pharmaceutical blister-pack engineers prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Germany, China, and the United States anchor low melt inclusion production, with Baden-Württemberg and Hebei province hosting the most concentrated compounding assets. Formulation draws from propylene feedstocks, metallocene catalyst systems, and bio-derived tackifier resins. Single-source vulnerability concentrates around German automotive OEM clustering, where just-in-time bonding system qualification creates switching costs. Distribution runs through direct technical service relationships for premium tiers and regional distributor networks for standard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multinational packaging group consolidation around unified global formulations has shifted procurement leverage toward buyers capable of specifying identical melt profiles across Germany, the United States, and Southeast Asia plant networks.
For Market Incumbents: Fortify ECHA-registered formulation portfolios against emerging metallocene-catalyzed copolymer specialists by accelerating VOC-compliant bonding system qualification with Stuttgart and Munich automotive OEMs. Deepen backward integration into Hebei naphtha cracking capacity to anchor cost position against propylene feedstock volatility. Prioritize certification investment for FDA food-contact notification pathways to capture first-mover advantages in temperature-sensitive confectionery sealing specifications. For New Entrants and Emerging Players: Technical service gaps in Indian pharmaceutical packaging modernization present white-space entry windows for FSSAI-compliant low-melt sealant suppliers. Maharashtra and Gujarat converters lack qualified domestic compounders capable of narrow-melt-range consistency. Target textile coating precision segments where medical fabric engineers demand thinner, more uniform encapsulant layers than incumbent broad-distribution suppliers deliver. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-specialist compounders with metallocene-catalyzed capabilities over commodity polyolefin processors facing margin compression. Long-term viability rests on regulatory compliance moats rather than scale economics alone. Acquisition targets should demonstrate full-substance REACH dossier holdings and active FDA notification pipelines. Watch ECHA candidate-list expansions for styrenic residuals as inflection indicator for channel exclusion risk and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Hebei naphtha cracking control insulates margin structures from propylene spot volatility. |
| REACH Registration Completion | Full-substance dossiers unlock premium consumer-goods channels blocked to non-compliant inventory. |
| FDA Food-Contact Notification | Pre-validated formulations capture first-mover positioning in temperature-sensitive pharmaceutical packaging. |
| Metallocene Capacity Expansion | Precision catalysis enables VOC-compliant automotive bonding systems displacing solvent alternatives. |
| Technical Service Partnership | Dedicated extrusion relationships with Stuttgart OEMs secure specification lock-in for cabin assembly grades. |
Research Methodology
A standing panel of compounder technical directors, automotive OEM material engineers, packaging procurement leads, and ECHA regulatory consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from customs trade data, Cefic polymer reports, FDA food-contact notification filings, and SEC 10-K disclosures from petrochemical-integrated players. Bottom-up volume modeling across product type, application, and end-user segments triangulated against top-down macroeconomic indicators for the chemicals sector.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework modeled chemistry grade tier, end-use industry sensitivity, regulatory clearance status, and regional production hub clustering. CAGRs were derived from segment-level demand elasticity analysis and substitution rate assumptions for solvent-based alternatives. Forecast inputs incorporated automotive lightweighting mandate timelines and evolving FDA purity specification trajectories.
Forecasts assume regulatory continuity in REACH registration requirements and FDA food-contact material rules; material policy shifts in ECHA candidate-list thresholds or USDA bio-based procurement guidelines would require re-modeling. Recalibration cycles align with material shifts in feedstock economics, automotive OEM qualification schedules, and multinational packaging group supplier consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Antioxidant and Stabilizer Agents Market
Additives
Paint Additives Market
Additives
Anti-Foaming Agent Market
Additives
Tackifier Market
Additives
Feed Additives Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Acrylamide Reducing Ingredients Market
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Calcium Diglutamate Market
Additives
Global Glass Additives Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
Biofuel Additives Market
Additives
Anti-Block Additives Market
Additives
Clouding Agents Market
Additives
High Performing Matting Agents Market
Additives
Americas Coating Additives Market