
 Oxygen Scavengers Market | 2026-2036
Oxygen Scavengers Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Scavengers Market Analysis
China's chemical manufacturing corridor is reshaping regional supply dynamics for iron-based oxygen scavenger precursors. BASF SE leverages its integrated antioxidant and additive portfolio to serve multinational food packagers with consistent specification-grade output. Mitsubishi Gas Chemical Company anchors Asia-Pacific demand through proprietary ascorbate-based sachet technologies deployed across Japanese and South Korean retail chains. Kemira Oyj competes in water treatment-linked oxygen scavenger segments where boiler and pipeline corrosion control overlaps with industrial packaging applications.
Oxygen scavengers are chemical additives or physical inserts that bind dissolved or headspace oxygen through redox reactions, enzymatic catalysis, or transition metal oxidation, typically reducing residual oxygen below 0.1% in sealed environments to prevent oxidative degradation of sensitive products. Iron-based formulations dominate commercial volumes due to low cost and high oxygen-binding capacity, though enzymatic variants are gaining traction in refrigerated fresh-protein packaging where metal detection systems create compliance constraints. Among end users, food packaging absorbs the largest share of scavenger deployment as brand owners replace nitrogen flushing with active packaging to reduce material waste and extend distribution reach. Pharmaceutical applications command premium positioning due to USP and EP stability-testing requirements that mandate validated oxygen control for moisture-sensitive APIs and biologics.
The U.S. FDA regulates oxygen scavengers as food contact substances under 21 CFR, requiring migration studies and toxicology clearances that shape formulation choices and barrier-layer architectures. REACH and the EU Packaging and Packaging Waste Regulation restrict certain transition metal compounds and mandate recyclability assessments, pushing Clariant and Arkema Group toward mono-material-compatible scavenger designs. China's GB standards and SAMR food contact notifications add a third compliance layer for suppliers operating across manufacturing geographies. Stakeholders must monitor regulatory divergence between migration-limit regimes and recyclability certifications to avoid reformulation costs and market access delays.
Market Dynamics
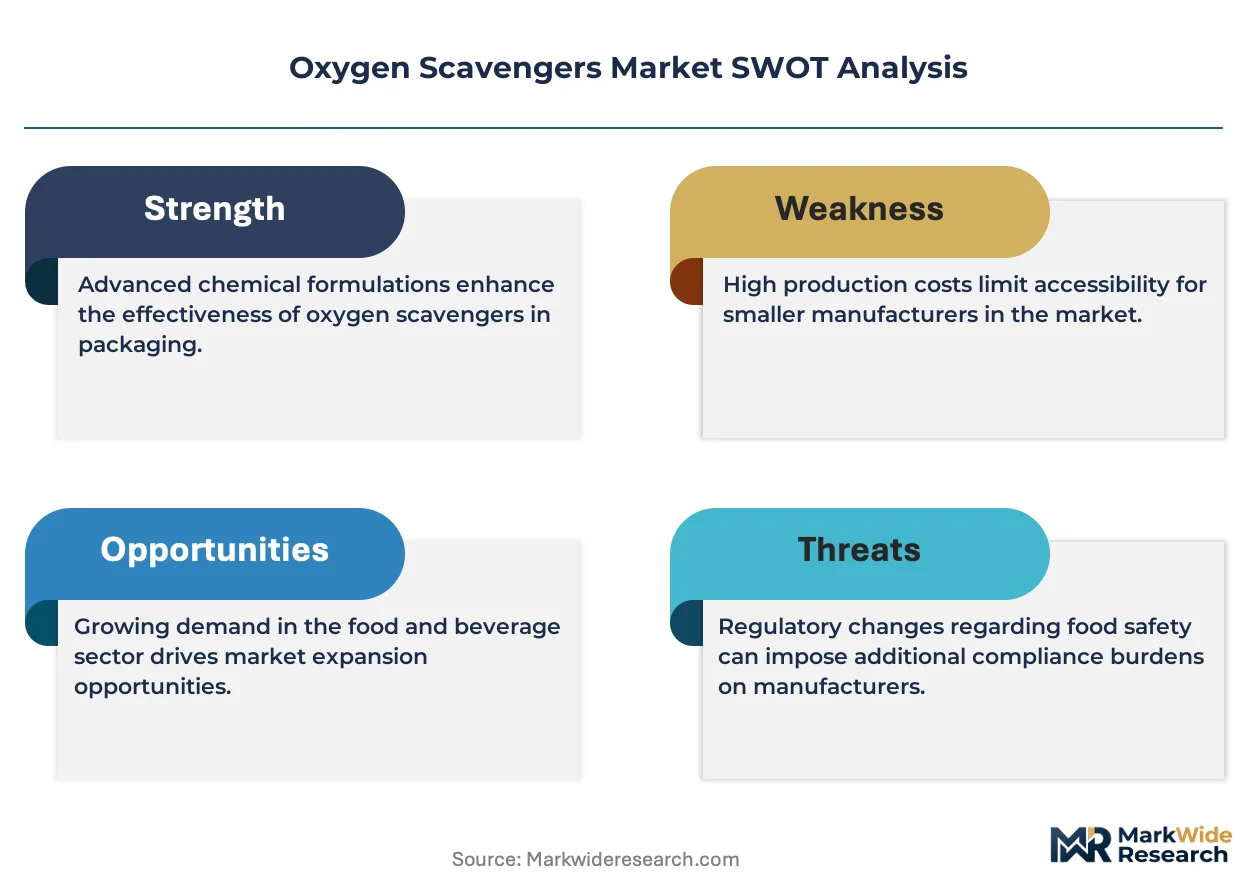
Iron-based oxygen scavenger formulations face mounting substitution pressure from enzymatic and ascorbate alternatives as food packagers redesign around metal detection compliance and mono-material recyclability mandates.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates are accelerating converter migration toward mono-material films with integrated oxygen-absorbing layers, expanding addressable substrate volumes.
- Fresh-protein retail chains:Japanese and South Korean supermarket operators are deploying enzymatic scavenger sachets in refrigerated meat and seafood cases to replace nitrogen flushing infrastructure.
- API stability requirements:USP and EP oxygen-control validation protocols for moisture-sensitive biologics are mandating validated scavenger systems in pharmaceutical primary packaging.
Market Restraints
- Iron powder supply concentration:Precursor production clusters in China's chemical manufacturing corridor create geographic vulnerability for iron-based scavenger formulators.
- REACH substance restrictions:ECHA scrutiny of certain transition metal compounds limits formulation flexibility and extends toxicology clearance timelines for European market entry.
- Enzyme cost structure:Glucose oxidase and catalase procurement costs remain 3-4x above iron powder equivalents, compressing margins in price-sensitive snack and bakery segments.
Strategic Opportunities
- India processed-food expansion:FSSAI-packaging compliance upgrades and cold chain investments in Maharashtra and Gujarat are opening deployment channels for sachet and film-integrated scavengers.
- Cell-cultured protein packaging:Oxygen sensitivity of novel protein matrices is creating specification demand for ultra-low residual oxygen scavenger systems without metallic contamination risk.
- Water treatment crossover:Boiler and pipeline corrosion-control oxygen scavenger chemistries are finding secondary pharmaceutical and electronics packaging applications through Kemira Oyj's industrial portfolio leverage.
Industry Challenges
- Migration study capacity:FDA 21 CFR food contact substance clearance requirements face bottlenecks at contracted toxicology labs, extending time-to-market for new scavenger formulations.
- Legacy equipment retrofit:Converting lines designed for passive barrier films require mechanical and thermal modification to handle active scavenger layer coextrusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Scavengers Market |
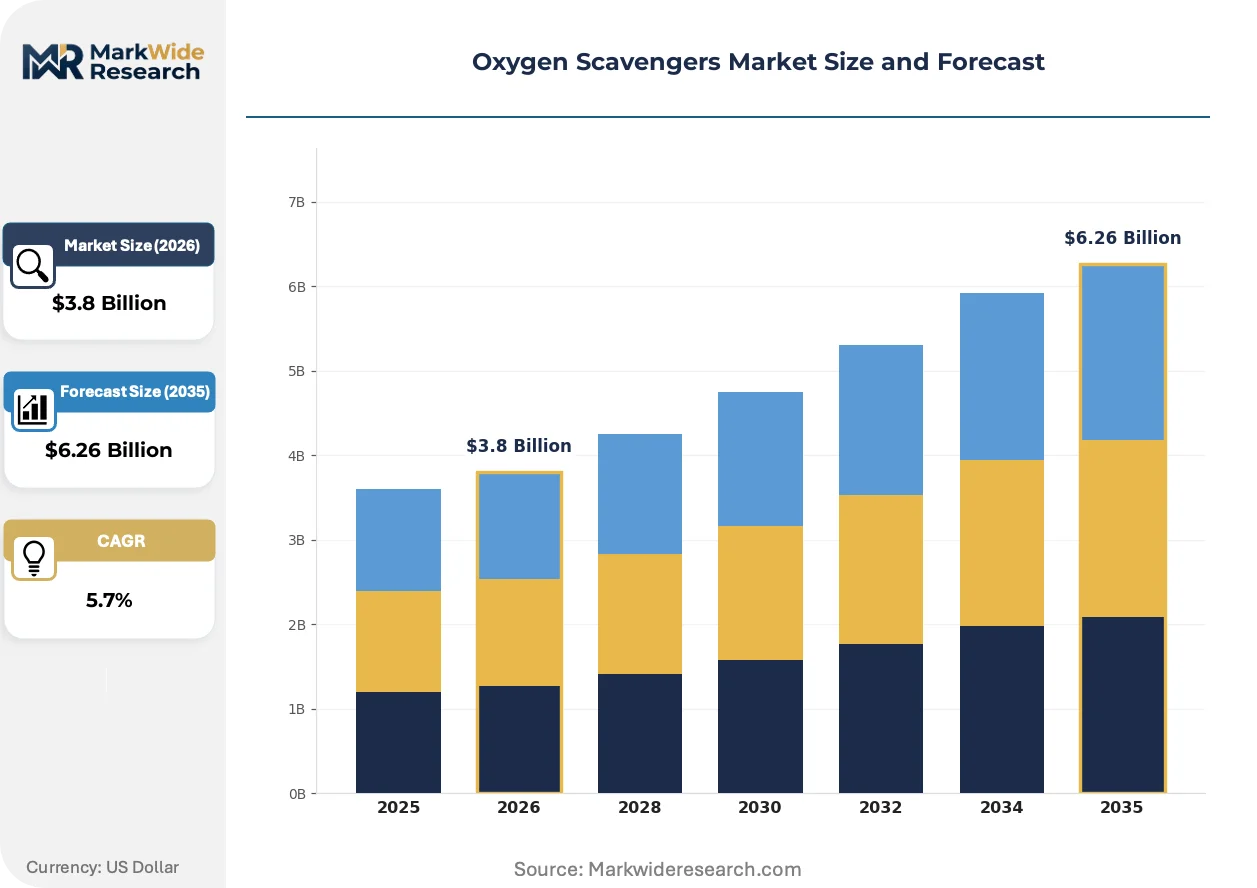
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Iron-Based, Enzymatic, Ascorbate-Based, Transition Metal Compounds End User: Food Packaging, Pharmaceuticals, Electronics, Chemicals Deployment: Flexible Packaging, Rigid Packaging, Bulk Packaging, Sachets Application: Aerospace, Automotive, Marine, Renewable Energy |
| Companies Covered | BASF SE, Mitsubishi Gas Chemical Company, Inc., Ecolab Inc., Clariant, Arkema Group, Avient Corporation, Solenis, Kemira Oyj, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Scavengers Market Emerging Trajectories
Active packaging integration is compressing the distinction between barrier materials and functional additives, with scavenger functionality migrating from external sachets into film substrates and closure liners.
Smart oxygen-indicator films incorporating colorimetric leuco-methylene blue and anthraquinone derivatives are digitizing quality assurance workflows across pharmaceutical distribution chains. Cold chain operators in Germany and Switzerland are piloting these visual-status systems to replace handheld headspace analyzers. The technology is digitizing compliance documentation and reducing manual inspection labor in high-value biologics logistics.
REACH restrictions on cobalt catalyst residues are forcing reformulation of certain oxidation-based scavenger systems toward manganese and copper alternatives. ECHA's 2023 substance evaluation roadmap has triggered preemptive formulation pivots by compounders serving EU medical device and food contact markets. Scandinavian packaging converters are accelerating qualification of non-cobalt scavenger masterbatches to maintain single-market certification efficiency.
Brand-owner technical buying committees are consolidating supplier relationships from multi-source commodity purchasing toward single-source active packaging partnerships with integrated scavenger-barrier-coating capabilities. This concentration is displacing spot-market iron powder trading in favor of multi-year specification-grade supply agreements. The shift is most visible in United States snack food and ready-meal segments where Walmart and Target supplier qualification timelines favor vertically integrated material systems.
Oxygen Scavengers Market Segmentation
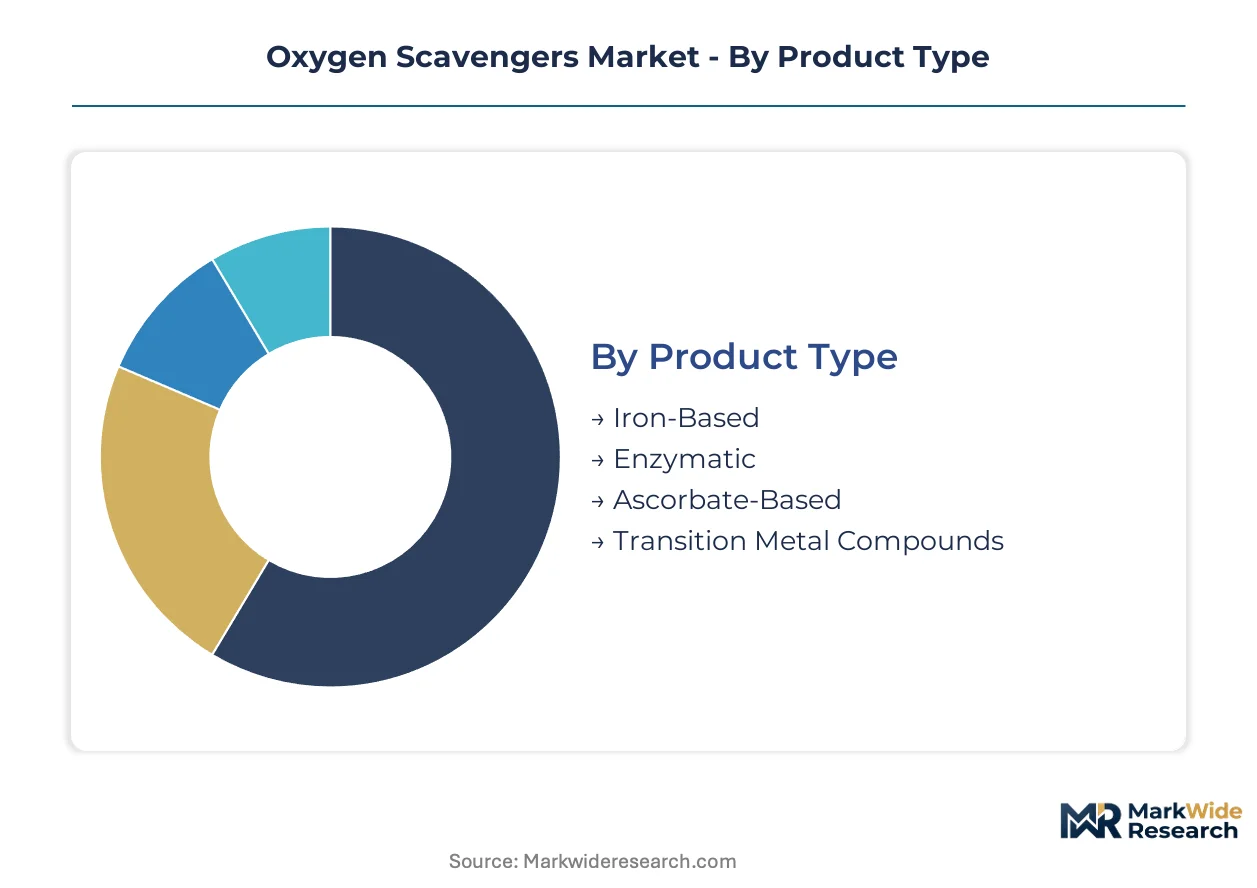
Oxygen scavenger deployment varies sharply by substrate compatibility, regulatory clearance pathways, and oxygen-binding kinetics required for specific product categories. Formulation choices cascade through film specifications, sachet geometries, and end-use validation protocols that shape supplier-customer relationships across food, pharmaceutical, and industrial segments.
Product Type:
Iron-based formulations anchor commercial volumes due to cost efficiency, though enzymatic and metal-free alternatives are capturing specification-driven niches where detection systems and recyclability mandates create compliance constraints.
- Iron-Based:Powdered metallic iron oxidizes in the presence of moisture to bind oxygen through Fe²⁺/Fe³⁺ redox chemistry, achieving residual levels below 0.1% in sealed environments. Food packaging converters in the United States and Germany specify these formulations for shelf-stable snacks and ready meals where metal detection systems tolerate ferrous content.
- Enzymatic:Glucose oxidase and catalase enzyme systems catalyze oxygen consumption without metallic residues, satisfying Japanese and South Korean retail chain requirements for fresh-protein cases with inline metal detection. The 3-4x cost premium over iron powder limits penetration in price-sensitive bakery and snack categories.
- Ascorbate-Based:Ascorbic acid derivatives serve pharmaceutical primary packaging where USP stability protocols require validated oxygen control without transition metal contamination risks.
- Transition Metal Compounds:Manganese and copper alternatives are displacing cobalt-containing systems under REACH substance restrictions, though ECHA toxicology clearances extend European market entry timelines.
The dominant share belongs to Iron-Based formulations, while Enzymatic alternatives are closing the gap fastest in refrigerated protein packaging segments.
End User:
Customer requirements diverge across stability validation tiers, with pharmaceutical applications commanding premium positioning due to regulatory testing burdens while food packaging drives volume scale.
- Food Packaging:Brand owners deploy scavengers to replace nitrogen flushing infrastructure, reducing material waste and extending distribution reach for processed foods. Walmart and Target supplier qualification timelines in the United States favor vertically integrated scavenger-barrier systems.
- Pharmaceuticals:USP and EP oxygen-control validation mandates moisture-sensitive API and biologics manufacturers toward specification-grade scavenger systems with documented migration profiles. FDA 21 CFR food contact substance clearances create toxicology lab bottlenecks that extend time-to-market.
- Electronics:Semiconductor and display manufacturers specify ultra-low residual oxygen environments to prevent oxidative degradation of sensitive components during shipping and storage.
- Chemicals:Industrial oxygen scavenger chemistries from water treatment applications find secondary packaging uses for moisture-sensitive chemical intermediates.
Food Packaging commands the largest deployment volumes, though Pharmaceuticals generate the steepest margin expansion trajectory due to validation and certification requirements.
Deployment:
Physical form factors determine integration complexity with existing converting infrastructure, with film-integrated layers requiring capital retrofit against sachet formats that deploy on legacy lines.
- Flexible Packaging:Mono-material films with coextruded scavenger layers are gaining share under EU Packaging and Packaging Waste Regulation recyclability mandates, though converting lines require thermal and mechanical modification.
- Rigid Packaging:Closure liners and container walls incorporate scavenger masterbatches for pharmaceutical bottles and nutritional supplement jars.
- Bulk Packaging:Industrial-scale scavenger systems protect chemical and agricultural commodity shipments during extended ocean freight.
- Sachets:External pouch formats remain prevalent in Japanese and South Korean retail chains for refrigerated meat and seafood cases, avoiding equipment retrofit costs.
Flexible Packaging holds the dominant position, while Sachet formats retain resilient demand in markets with legacy converting infrastructure.
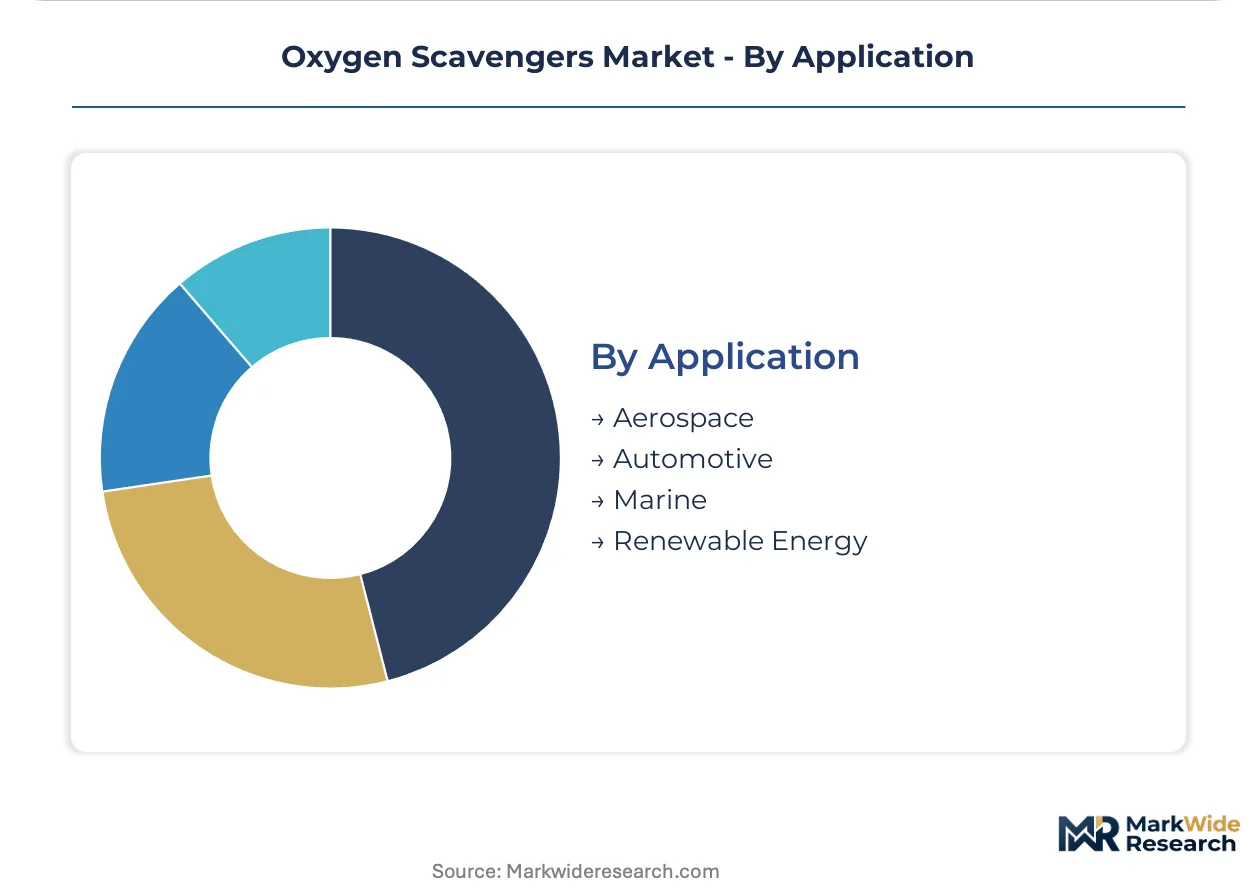
Application:
Industrial oxygen scavenger demand concentrates in corrosion control and preservation applications where equipment protection overlaps with packaged goods stability requirements.
- Aerospace:Fuel system and hydraulic fluid preservation specifications drive scavenger deployment for long-term component storage.
- Automotive:Brake fluid and coolant packaging incorporates oxygen-binding additives to prevent oxidative degradation during distribution.
- Marine:Ballast water treatment and pipeline corrosion control create secondary demand channels for industrial oxygen scavenger chemistries.
- Renewable Energy:Battery electrolyte and hydrogen storage systems require ultra-low oxygen environments to prevent contamination and degradation.
Automotive applications anchor industrial segment volumes, while Renewable Energy is gaining share fastest alongside battery and hydrogen infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulations in the United States establish the baseline compliance framework that shapes formulation choices across North American food and pharmaceutical packaging operations.
United States
Processed-food manufacturers in the Midwest and Southeast are expanding iron-based scavenger procurement to replace nitrogen flushing infrastructure. FDA 21 CFR food contact substance clearances create toxicology lab bottlenecks that extend time-to-market for new formulations. Walmart and Target supplier qualification timelines in Arkansas and Minnesota favor vertically integrated scavenger-barrier systems.
China
Chemical manufacturing corridors in Shandong and Jiangsu provinces concentrate precursor production for iron powder formulations. SAMR food contact notifications and GB standards add compliance layers for multinational suppliers operating across manufacturing geographies. Yangtze River Delta packaging clusters are retrofitting converting lines to handle mono-material films with integrated scavenger layers.
Germany
Pharmaceutical packagers in Baden-Württemberg and Bavaria command premium positioning for USP-validated oxygen control systems. REACH substance restrictions and ECHA scrutiny of transition metal compounds limit formulation flexibility and extend clearance timelines. Stuttgart and Munich industrial clusters are accelerating qualification of non-cobalt scavenger masterbatches.
Japan
Retail chains in the Kanto and Kansai regions deploy enzymatic scavenger sachets in refrigerated meat and seafood cases. METI standards and PMDA pharmaceutical packaging requirements shape specification-grade procurement. Tokyo and Osaka supermarket operators are replacing nitrogen flushing infrastructure with active packaging to reduce material waste.
South Korea
Fresh-protein distributors in Seoul and Busan are adopting enzymatic scavenger formats to satisfy inline metal detection requirements. MFDS pharmaceutical stability protocols mandate validated oxygen control for moisture-sensitive biologics. Gyeonggi-do packaging converters are expanding coextrusion capacity for film-integrated scavenger layers.
Oxygen Scavengers Market Vendor Landscape
Integrated chemical conglomerates and specialty additive suppliers split the market into distinct capability tiers. The vendor base concentrates around three strategic archetypes: diversified multinational chemical producers with antioxidant portfolios, regional gas and chemical specialists with proprietary sachet technologies, and water treatment chemical suppliers leveraging industrial corrosion-control expertise. Competitive moves center on backward integration into precursor manufacturing and multi-year specification-grade supply agreements that displace spot-market commodity trading.
Within the integrated chemical tier, BASF SE and Mitsubishi Gas Chemical Company occupy positions defined by specification-grade output consistency and proprietary formulation libraries. Kemira Oyj exemplifies the industrial-crossover archetype, applying boiler and pipeline corrosion-control chemistries to pharmaceutical and electronics packaging applications. Arkema Group and Clariant sit within the specialty materials tier, focusing on mono-material-compatible scavenger designs that satisfy EU recyclability mandates.
| Leading Market Players |
|---|
| BASF SE |
| Mitsubishi Gas Chemical Company, Inc. |
| Ecolab Inc. |
| Clariant |
| Arkema Group |
| Avient Corporation |
| Solenis |
| Kemira Oyj |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
China's chemical manufacturing corridor concentrates iron powder precursor output, anchoring cost structures for iron-based scavenger formulators while enzymatic alternatives command premium positioning in metal-detection-sensitive segments. Margin pools sit downstream with specification-grade compounders serving pharmaceutical and fresh-protein packaging verticals.
Pricing Analysis
Geographic price spreads widen between iron-based formulations sourced from Shandong and Jiangsu provinces versus enzymatic systems produced in Japanese and South Korean enzyme fermentation facilities. Three-tier pricing structure across premium, standard, and economy levels separates USP-validated pharmaceutical grades from food-contact commodity iron powders and industrial corrosion-control chemistries. Pricing pressure stems from enzyme cost premiums running multiple times above iron powder equivalents, compressing margins in snack and bakery categories. Food packaging converters exhibit highest price sensitivity, while pharmaceutical stability-validation requirements render API manufacturers least sensitive to unit cost.
Supply Chain Analysis
Extended payment terms from multinational food packagers are forcing working capital intensity onto mid-tier scavenger compounders, particularly those serving Walmart and Target supplier networks. Raw material flows draw from China's iron powder clusters, Japanese enzyme fermentation facilities, and German antioxidant precursor operations. Supply chain risk centers on single-source vulnerability for glucose oxidase and catalase enzymes, where fermentation capacity concentrates in limited geographic footprints. Distribution runs through specification-grade masterbatch compounders serving film converters, with direct sachet supply agreements penetrating Japanese and South Korean retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oxygen scavenger functionality is migrating from discrete sachets into film substrates and closure liners, creating platform-economics dynamics where integrated barrier-scavenger systems displace multi-source component procurement. Interoperability between active packaging layers and mono-material recyclability mandates is reshaping supplier-customer contracting structures.
For Market Incumbents: Build formulation libraries as moat by securing FDA 21 CFR food contact substance clearances ahead of toxicology lab capacity constraints. Backward integration into iron powder precursor manufacturing in Shandong and Jiangsu provinces reduces exposure to China's chemical manufacturing corridor concentration risk. Investment in non-cobalt scavenger masterbatches preserves EU market access under ECHA substance evaluation roadmaps. For New Entrants and Emerging Players: Pursue cell-cultured protein packaging as white-space target, where oxygen sensitivity of novel protein matrices creates specification demand without metallic contamination risk. India's FSSAI-packaging compliance upgrades in Maharashtra and Gujarat represent most penetrable geography for sachet and film-integrated scavenger deployment. Go-to-market angle should emphasize mono-material compatibility for EU Packaging and Packaging Waste Regulation recyclability mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic scavenger segments, where fermentation capacity expansion and regulatory clearance timelines extend cash conversion cycles. Long-term viability favors compounders with validated pharmaceutical stability protocols and backward-integrated precursor supply. Acquisition target archetype: specialty additive suppliers with FDA master files and specification-grade output consistency. Signal to watch is ECHA substance evaluation timeline acceleration for cobalt alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive iron powder supply from Shandong chemical corridors insulates against geographic concentration risk. |
| FDA Food Contact Substance Clearance Investment | Validated toxicology profiles accelerate time-to-market for new scavenger formulations in US food packaging. |
| Non-Cobalt Scavenger Masterbatch Qualification | REACH-compliant alternatives preserve single-market certification efficiency across EU medical device applications. |
| Long-term Specification-Grade Supply Agreements | Multi-year contracts with Walmart and Target supplier networks displace spot-market commodity trading. |
| Enzymatic Scavenger Capacity Expansion | Fermentation scale-up in Japanese and South Korean facilities serves fresh-protein retail chain demand. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR food contact substance filings, ECHA substance evaluation databases, and SAMR GB standard notifications. Primary interviews engaged procurement directors at multinational food packagers, technical R&D leads at scavenger compounders, regulatory affairs managers navigating REACH and FDA clearance pathways, and converting line engineers at flexible packaging operations. Secondary validation drew from customs trade data for iron powder and enzyme precursor flows, SEC filings of integrated chemical conglomerates, and industry association reports from chemical manufacturing corridors. Bottom-up demand modeling triangulated against top-down market sizing across formulation types and end-use segments.
Forecast inputs span iron-based and enzymatic formulation chemistries, food packaging versus pharmaceutical end-use validation tiers, sachet versus film-integrated deployment formats, and regional regulatory cluster divergence between FDA, REACH, and GB standard jurisdictions. Segmentation dimensions modeled include product type chemistry, end-user stability validation requirements, deployment physical form factors, and application-specific oxygen-binding kinetics. CAGRs were derived from regression analysis of historical procurement volumes against projected regulatory mandate implementation timelines and cold chain infrastructure investment patterns.
Sensitivities concentrate around ECHA substance evaluation acceleration, FDA toxicology lab capacity constraints, and iron powder supply disruption from China's chemical manufacturing corridor. Forecasts reflect assumptions regarding regulatory clearance timeline stability and enzyme fermentation capacity expansion trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Shortstop Inhibitor Market
Additives
United Kingdom Feed Additives Market
Additives
Friction Modifier Additives Market
Additives
Plastic Additives Market
Additives
Gluconic Acid and Derivatives Market
Additives
Citrate Ester Market
Additives
Pearlizers Market
Additives
Global Matting Agents Market
Additives
Japan Sodium Reduction Ingredient Market
Additives
Plasticizers Market
Additives
Performance Minerals Additives Market
Additives
Refinery Fuel Additives Market
Additives
Polysaccharides and Oligosaccharides Market
Additives
Global UV Absorbers Market
Additives
Tragacanth Market
Additives
Global Rheology Modification Coating Additives Market