
 Laboratory Chemicals Market | 2026-2036
Laboratory Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Chemicals Market Intelligence
High-purity water-based solvents is broadening the addressable market for traditional organic alternatives. Merck KGaA leverages its integrated supply chain from raw material sourcing to final packaging, securing cost advantages in analytical-grade production. Thermo Fisher Scientific sustains technology leadership through proprietary purification protocols that meet evolving pharmacopeial standards. Avantor anchors its position in North American biopharma accounts through dedicated cleanroom manufacturing capacity and channel control.
Laboratory chemicals are substances manufactured to controlled purity specifications, typically exceeding 95% assay with defined impurity profiles, and serve as inputs for analytical testing, synthesis, and quality verification across science-based industries. Solvents and reagents constitute the largest product volume pools, though buffers command premium pricing due to stringent biocompatibility requirements and custom formulation complexity. Analytical-grade chemicals dominate value capture because regulatory submission workflows mandate certified reference materials with full traceability documentation.
REACH in Europe, EPA standards in the United States, and ISO 17025 accreditation frameworks collectively shape product specifications, testing burdens, and cross-border market access for laboratory chemical suppliers. FDA current good manufacturing practice expectations for pharmaceutical applications extend upstream, forcing chemical producers to maintain audit-ready quality management systems. Stakeholders must monitor evolving substance restriction lists and pharmacopeial revision cycles to anticipate reformulation requirements and avoid supply discontinuities.
Market Dynamics
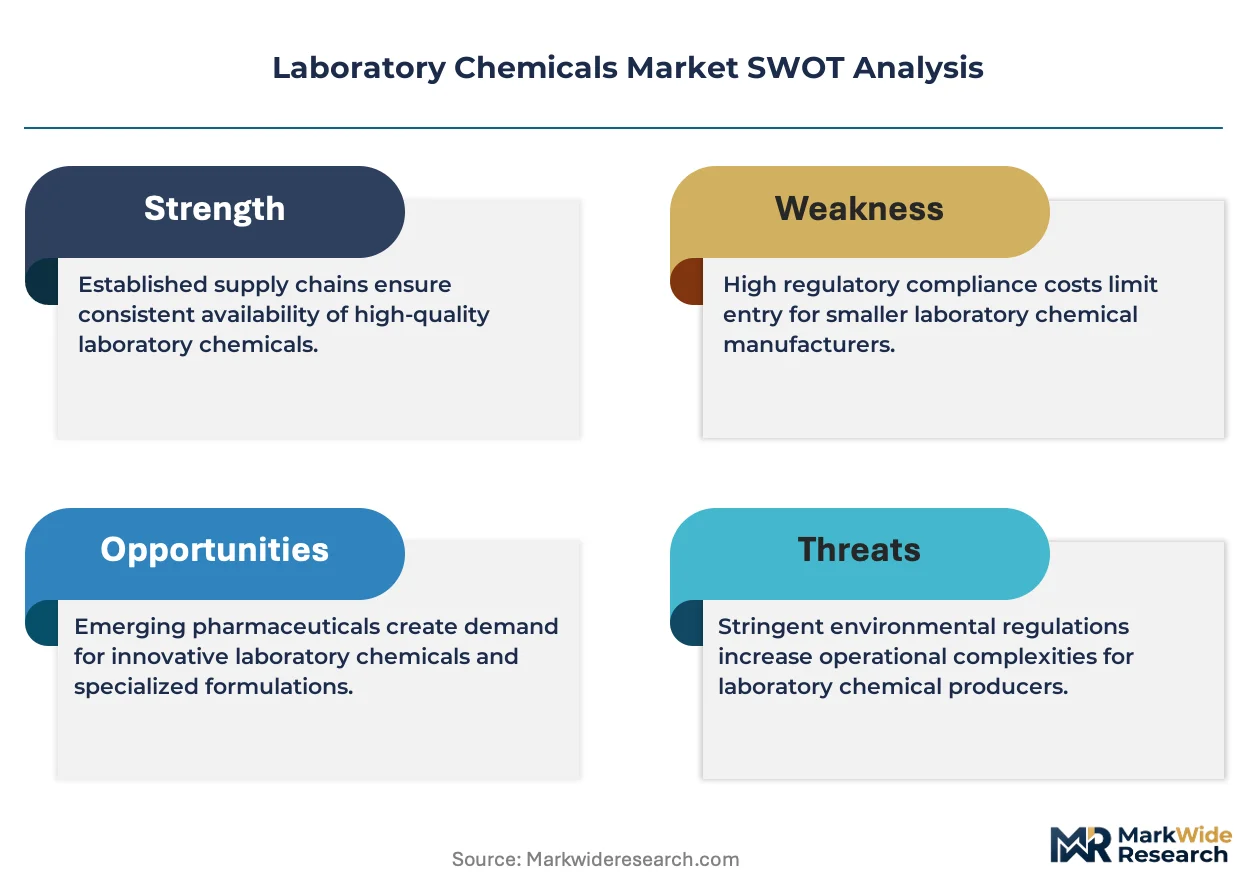
REACH compliance documentation requirements are compressing supplier margins while biologics manufacturers demand escalating purity tiers, creating a structural squeeze between regulatory burden and premium specification capture.
Growth Catalysts
- Biologics manufacturing expansion:Cell and gene therapy developers in Germany and Switzerland require ultra-low endotoxin reagents, pulling analytical-grade solvent volumes upward.
- EMA's tightened pharmacopeial alignment:The European Medicines Agency's impurity profiling mandates force reference material upgrades, extending certified product lifecycles.
- Academic cluster densification:Heidelberg and Cambridge life science corridors concentrate procurement volumes, enabling supplier scale efficiencies.
Market Restraints
- Acetonitrile feedstock volatility:HPLC-grade solvent producers face petrochemical derivative price swings that erode contracted margin structures.
- Single-source germanium dioxide dependence:Optical-grade reagent supply chains concentrate in Chinese smelter networks, creating geopolitical exposure.
- ISO 17025 accreditation backlog:Testing laboratory certification delays in Southern Europe extend product qualification timelines.
Strategic Opportunities
- India's CDMO buildout:Contract development and manufacturing organizations in Hyderabad and Bangalore seek local analytical-grade sourcing to replace imports.
- Water-based solvent substitution:Green chemistry mandates in the Netherlands and Denmark accelerate aqueous buffer adoption for chromatography workflows.
- Direct-to-lab e-procurement platforms:Biotech startups bypass traditional distributors, opening channel margin recapture for manufacturers with digital infrastructure.
Industry Challenges
- Analytical chemist talent scarcity:Specialized purification protocol expertise concentrates in Basel and Boston, constraining facility expansion in secondary markets.
- Multi-jurisdiction dossier harmonization:Reconciling USP, EP, and JP monograph divergences consumes regulatory affairs bandwidth.
- Legacy ERP integration with track-and-trace systems:Batch record digitization projects stall at mid-tier suppliers lacking IT modernization capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Chemicals Market |
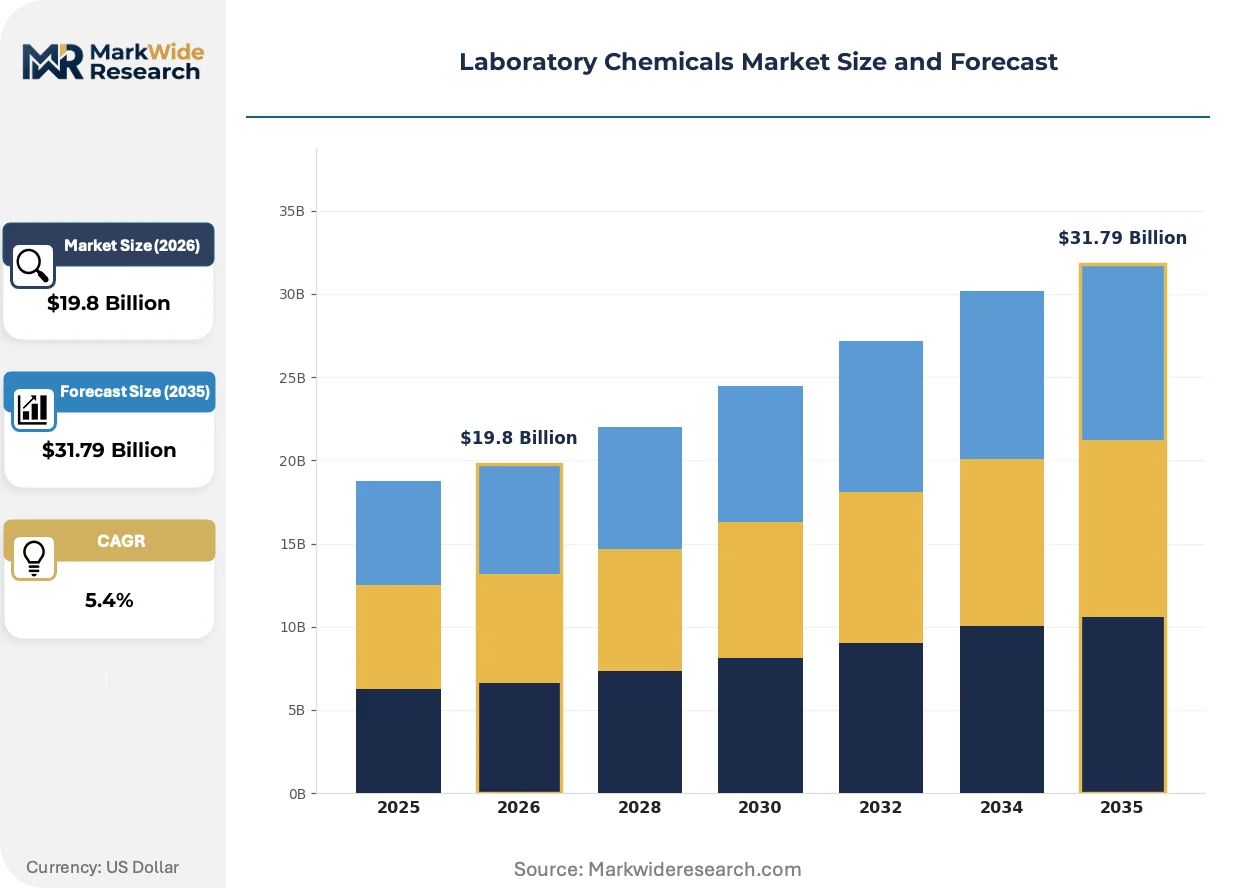
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $31.79 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Reagents, Buffers, Acids Grade: Analytical, Biochemical, Technical, Reagent End User: Research Laboratories, Pharmaceutical Companies, Academic Institutions, Industrial Facilities Application: Chemical Analysis, Biological Research, Quality Control, Production |
| Companies Covered | Agilent Technologies, Beckman Coulter, Merck KGaA, BD Biosciences, GE Healthcare, Avantor, PerkinElmer, Honeywell International, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Chemicals Market Strategic Shifts & Innovations
Continuous purification hardware and AI-driven impurity prediction are compressing traditional batch manufacturing economics while regulatory digitization mandates rewrite documentation workflows.
Single-use chromatography systems is modularizing downstream bioprocessing infrastructure. Biologics manufacturers in Denmark and Ireland adopt disposable flow paths to eliminate cross-contamination validation burdens. This shift is modularizing capital deployment, allowing production capacity to scale in 500-liter increments rather than fixed stainless-steel installations.
REACH's SCIP database requirements for substance of very high concern tracking extend upstream to laboratory chemical importers. European distributors now mandate full supply chain disclosure from Asian manufacturers. Analytical-grade solvent suppliers face the steepest compliance burden, as their fragmented raw material bases complicate article-level traceability.
Consolidated procurement consortia now dominate large pharmaceutical accounts. Three European pharma giants have centralized chemical buying through joint sourcing entities, displacing individual site-level purchasing autonomy. Germany-based manufacturing networks experience the most concentrated buyer power, pressuring regional distributor markups.
Laboratory Chemicals Market Segmentation
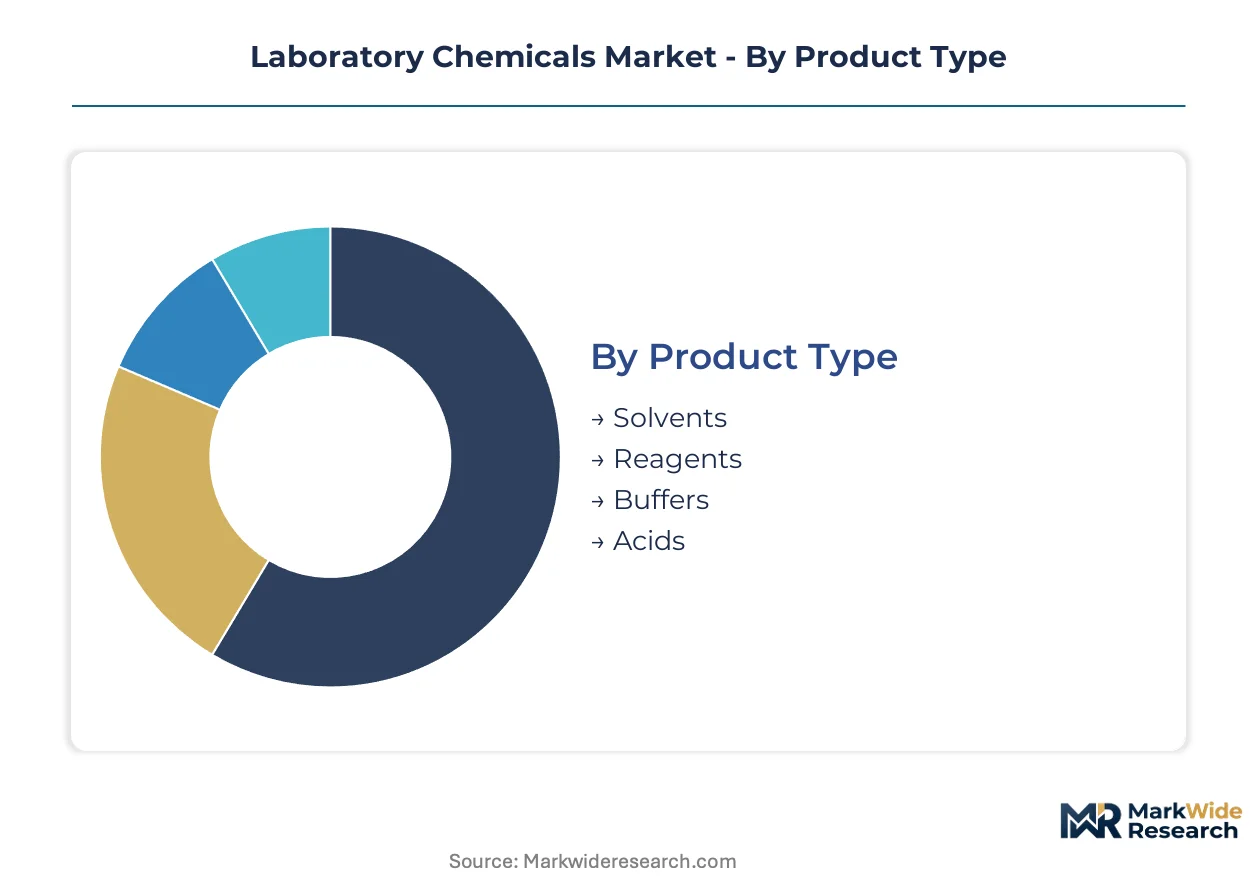
Laboratory chemicals exhibit divergent margin profiles across purity tiers and application contexts. Segmentation reveals where capital deployment concentrates and which specifications command pricing power in regulated environments.
Product Type:
Capital intensity peaks with solvent purification infrastructure, where multi-stage distillation and molecular sieve systems dominate upfront investment requirements.
- Solvents:Chromatography-grade acetonitrile and methanol require fractional distillation columns and inert atmosphere packaging lines. Demand clusters in German pharmaceutical quality control labs where HPLC workflows consume bulk volumes, though acetonitrile feedstock volatility compresses margin stability.
- Reagents:High-purity inorganic and organic synthesis inputs demand dedicated cleanroom filling suites and nitrogen-purged storage. Swiss biologics manufacturers in Basel drive specification escalation for ultra-low metal content grades.
- Buffers:Biocompatibility-certified aqueous formulations require endotoxin-controlled water systems and validated sterile filtration.
- Acids:Semiconductor-grade acids need sub-ppt trace metal specifications and fluoropolymer containment infrastructure.
Most installed capacity flows through Solvents. Expansion is steepest in Buffers.
Grade:
Margin stratification follows certification burden, with pharmacopeial-grade production absorbing the heaviest quality system overhead.
- Analytical:Certified reference materials with full traceability documentation and NIST-traceable calibration. EMA impurity profiling mandates in Heidelberg and Cambridge academic clusters sustain premium pricing.
- Biochemical:Cell-culture-tested specifications with endotoxin and bioburden certification. Danish gene therapy developers in Copenhagen drive fastest specification escalation.
- Technical:Industrial-scale synthesis inputs with basic purity guarantees and minimal documentation overhead.
- Reagent:General laboratory-grade chemicals for educational and routine analytical workflows.
Quality system costs concentrate in Analytical. Biochemical is gaining share fastest.
End User:
Procurement sophistication separates institutional buyers, with consolidated purchasing power reshaping supplier relationships.
- Research Laboratories:Fragmented demand across government and private R&D facilities with project-based ordering patterns.
- Pharmaceutical Companies:Audit-ready quality agreements and long-term supply contracts with mandatory backup sourcing. Three European pharma giants have centralized chemical buying through joint sourcing entities.
- Academic Institutions:Budget-constrained purchasing with heavy reliance on distributor consortia and grant-funded procurement cycles.
- Industrial Facilities:Process-scale solvent consumption with price-sensitive tender processes and bulk tanker delivery requirements.
Contract value concentrates with Pharmaceutical Companies. Digital procurement adoption is climbing fastest among Research Laboratories.
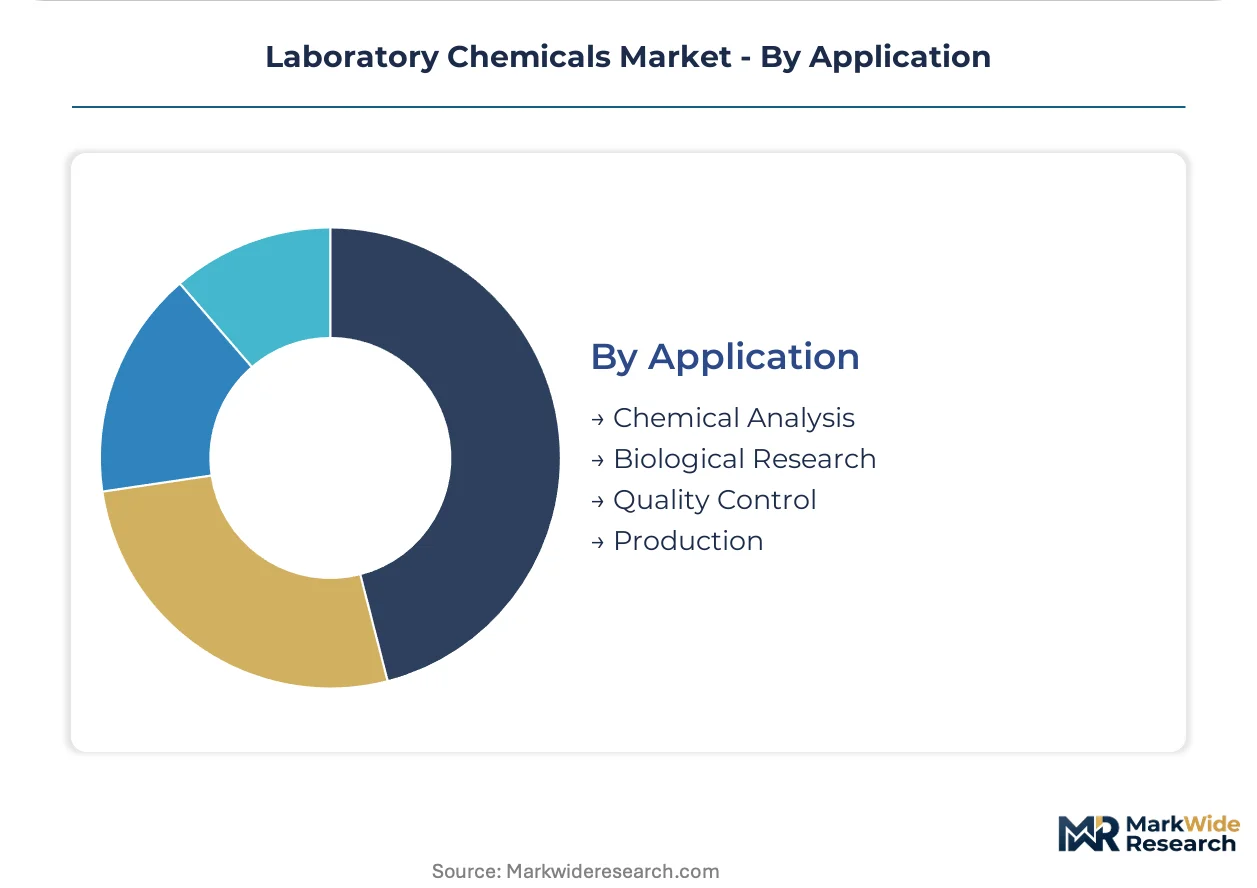
Application:
Regulatory submission workflows create sticky demand in verification applications where specification changes trigger costly revalidation.
- Chemical Analysis:Chromatography and spectroscopy consumables with method-defined purity requirements. REACH documentation burdens in Germany tighten supplier qualification.
- Biological Research:Cell-based assay reagents with sterility and cytotoxicity certification. CRISPR workflow expansion in Cambridge and Heidelberg drives specialized buffer demand.
- Quality Control:Release testing materials with pharmacopeial monograph compliance and stability data packages.
- Production:Process-scale chemical inputs with batch consistency requirements and raw material qualification dossiers.
Validation stickiness is strongest in Quality Control. Biological Research is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Main and Rhine-Neckar chemical corridors concentrate the highest analytical-grade solvent consumption in Europe, with Merck KGaA's Darmstadt headquarters anchoring regional supply chain integration.
United States
Biologics manufacturers in Greater Boston and the San Francisco Bay Area drive ultra-low endotoxin reagent procurement. FDA's current good manufacturing practice expectations extend upstream to chemical suppliers, forcing audit-ready quality management systems. Thermo Fisher Scientific's Waltham operations exemplify the premium-grade production capacity concentrated in Massachusetts.
Germany
Heidelberg and Cambridge academic clusters concentrate HPLC-grade solvent demand for chromatography workflows. REACH compliance documentation requirements from ECHA tighten purity certification burdens for imported materials. Merck KGaA leverages its Darmstadt-based integrated supply chain from raw material sourcing through final packaging.
Switzerland
Basel's pharmaceutical density generates specification escalation for ultra-low metal content reagents used in biologics manufacturing. Swissmedic's pharmacopeial alignment mandates force reference material upgrades with full traceability documentation. The city's gene therapy developers pull analytical-grade volumes upward through specialized buffer demand.
India
Hyderabad and Bangalore contract development and manufacturing organizations seek local analytical-grade sourcing to replace import dependence. CDSCO's tightening quality documentation requirements for pharmaceutical inputs accelerate supplier qualification timelines. The Telangana and Karnataka clusters represent the fastest-expanding procurement volumes outside established Western markets.
China
Shanghai and Suzhou biopharma manufacturing zones concentrate demand for biochemical-grade cell culture reagents. NMPA's impurity profiling mandates for pharmaceutical applications extend to upstream chemical suppliers. The Yangtze River Delta's optical-grade germanium dioxide processing creates single-source supply chain exposure for specialized reagent categories.
Laboratory Chemicals Market Key Industry Players
Global majors compete with regional champions across certification tiers and geographic proximity to end-use clusters. The vendor base stratifies into three tiers: integrated life science conglomerates with captive chemical production, specialized analytical-grade manufacturers with pharmacopeial accreditation depth, and regional distributors with logistics control over fragmented academic accounts. Dominant competitive moves include backward integration into high-purity raw material sourcing and strategic partnerships with biologics manufacturers for co-developed specification standards.
Among integrated life science conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify the premium-tier archetype through proprietary purification protocols and full supply chain control. Avantor occupies a distinct position in North American biopharma accounts through dedicated cleanroom manufacturing infrastructure. These three entities represent the consolidation vector in analytical-grade production, where regulatory submission workflows mandate certified reference materials with traceability documentation that smaller competitors struggle to replicate.
| Leading Market Players |
|---|
| Agilent Technologies |
| Beckman Coulter |
| Merck KGaA |
| BD Biosciences |
| GE Healthcare |
| Avantor |
| PerkinElmer |
| Honeywell International |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Consolidated procurement consortia among German pharmaceutical giants force suppliers to absorb REACH documentation costs while maintaining multi-tier certification capabilities, compressing margin structures and accelerating backward integration into captive raw material sourcing.
Pricing Analysis
Acetonitrile feedstock volatility passes through directly to HPLC-grade solvent contracts, with petrochemical derivative price swings eroding fixed-margin agreements. Pricing stratifies across pharmacopeial-grade, analytical-grade, and technical-grade tiers, with certification burden and NIST-traceable documentation driving 40-60 point spreads between adjacent tiers. Cost compression in technical-grade solvents intensifies as Indian CDMOs qualify local alternatives. Academic institutions exhibit highest price sensitivity; biologics manufacturers demonstrate lowest sensitivity due to revalidation costs.
Supply Chain Analysis
Dual-sourcing requirements from European pharma procurement consortia mandate qualified backup suppliers for all pharmacopeial-grade categories, fragmenting volume concentration. Geographic supply concentration centers on Germany, Switzerland, and China, with Darmstadt and Basel anchoring high-purity production while Chinese smelter networks control optical-grade germanium dioxide. Raw material dependencies include petrochemical derivatives, high-purity water systems, and nitrogen purge infrastructure. Single-source vulnerability in specialty inorganics creates geopolitical exposure. Distribution runs through authorized distributor networks with cleanroom logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laboratory chemicals market functions as a stable compounder, with biologics manufacturing expansion delivering steady specification escalation and recurring reagent demand across therapeutic modalities.
For Market Incumbents: Cement pharmacopeial accreditation depth by investing in simultaneous USP, EP, and JP monograph compliance capabilities, insulating against multi-jurisdiction dossier harmonization burdens. Capture channel margin through direct-to-lab e-procurement platforms that bypass traditional distributor markups, defending against digital-native entrants targeting biotech startup accounts.
For New Entrants and Emerging Players: AI-driven impurity prediction algorithms offer a technology-first wedge to compress batch manufacturing economics and undercut legacy purification protocols. Target India's Hyderabad and Bangalore CDMO clusters with local analytical-grade production, replacing import dependence while CDSCO qualification timelines accelerate. Pursue co-development partnerships with gene therapy developers for custom endotoxin specifications.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized analytical-grade manufacturers possessing ISO 17025 accreditation and cleanroom infrastructure in underserved regional hubs. Five-to-ten year viability rests on regulatory digitization readiness and SCIP database compliance capabilities. Monitor REACH substance restriction list revisions as inflection indicators for reformulation-driven replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Raw Materials | Merck KGaA's captive acetonitrile sourcing insulates margin from petrochemical volatility. |
| Cleanroom Manufacturing Capacity Expansion | Avantor's Waltham infrastructure captures North American biopharma audit-ready quality agreements. |
| Direct-to-Lab E-Procurement Platform Launch | Digital infrastructure recaptures distributor margins from biotech startup procurement. |
| Multi-Pharmacopeial Accreditation Investment | Simultaneous USP-EP-JP compliance reduces regulatory affairs bandwidth consumption. |
| Continuous Purification Technology Deployment | AI-driven impurity prediction compresses batch manufacturing economics versus legacy protocols. |
Research Approach
Coverage spans Germany, Switzerland, India, China, and the United States, with primary inputs from each market cluster combined with secondary validation. Primary interviews engaged plant managers at solvent purification facilities, procurement leads at Basel and Boston biologics manufacturers, distribution channel partners in European academic corridors, and technical R&D directors specializing in chromatography-grade production. Secondary sources included ECHA REACH registration databases, USP and EP monograph revision records, customs trade data for high-purity solvent imports, and SEC filings from integrated life science conglomerates. Bottom-up volume modeling triangulated against top-down market sizing from industry association data.
Granularity-level modeling operated at grade-tier, end-use industry, and regional production hub dimensions across the analysis window. Analytical framework projected solvent, reagent, buffer, and acid category volumes separately, with biologics manufacturing intensity and academic cluster densification as key demand drivers. CAGRs derived from regression analysis against pharmaceutical R&D expenditure and biologics approval trends, with REACH compliance cost pass-through and acetonitrile price volatility as adjustment factors.
The model holds under steady pharmacopeial alignment between EMA and FDA; deviation in monograph divergence timelines or sudden feedstock supply disruptions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Imaging Chemicals and Materials Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Isooctyl Alcohol Market
Chemicals
Fireworks Market
Chemicals
Scouring Agents Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Roofing Chemical Market
Chemicals
Dimethyl Phosphate Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Tributyl Phosphate Market
Chemicals
Power Plant Chemicals Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Global Glycol Ether Market