
 Power Plant Chemicals Market | 2026-2036
Power Plant Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Power Plant Chemicals Market Analysis
Aftermarket service revenue for chemical dosing optimization is rewriting how suppliers capture lifetime value from power generators. Nalco Water leverages its digital monitoring platforms to sustain long-term service contracts across coal and gas-fired fleets. Kemira anchors its position through specialized coagulant chemistry for flue gas desulfurization wastewater. Solenis competes on advanced deposit control polymers that extend boiler run lengths between chemical cleanings.
Power plant chemicals comprise formulated additives, treatment chemicals, and cleaning agents engineered to specific pH ranges, conductivity targets, and corrosion inhibition parameters for thermal and combined-cycle systems. These formulations prevent scale deposition, control microbiological fouling, and neutralize acidic combustion byproducts to protect capital equipment and maintain heat rate efficiency. Water treatment chemicals dominate volume demand as utilities confront stricter discharge limits, while fuel treatment additives represent the fastest-growing margin pool driven by biomass cofiring and opportunity fuel combustion. Chemical processing applications remain mature with stable replacement cycles, whereas cooling system biocide demand fluctuates with seasonal load patterns and regional water scarcity.
The EPA enforces effluent limitation guidelines that mandate zero liquid discharge or advanced wastewater treatment at coal-fired plants, directly expanding demand for precipitation and filtration chemistries. OSHA process safety management standards and ISO 14001 environmental management frameworks govern chemical handling protocols, influencing supplier qualification and plant-level procurement criteria. Stakeholders must monitor how carbon capture retrofits alter flue gas chemistry and create new treatment requirements for amine degradation products and corrosion byproducts.
Market Dynamics
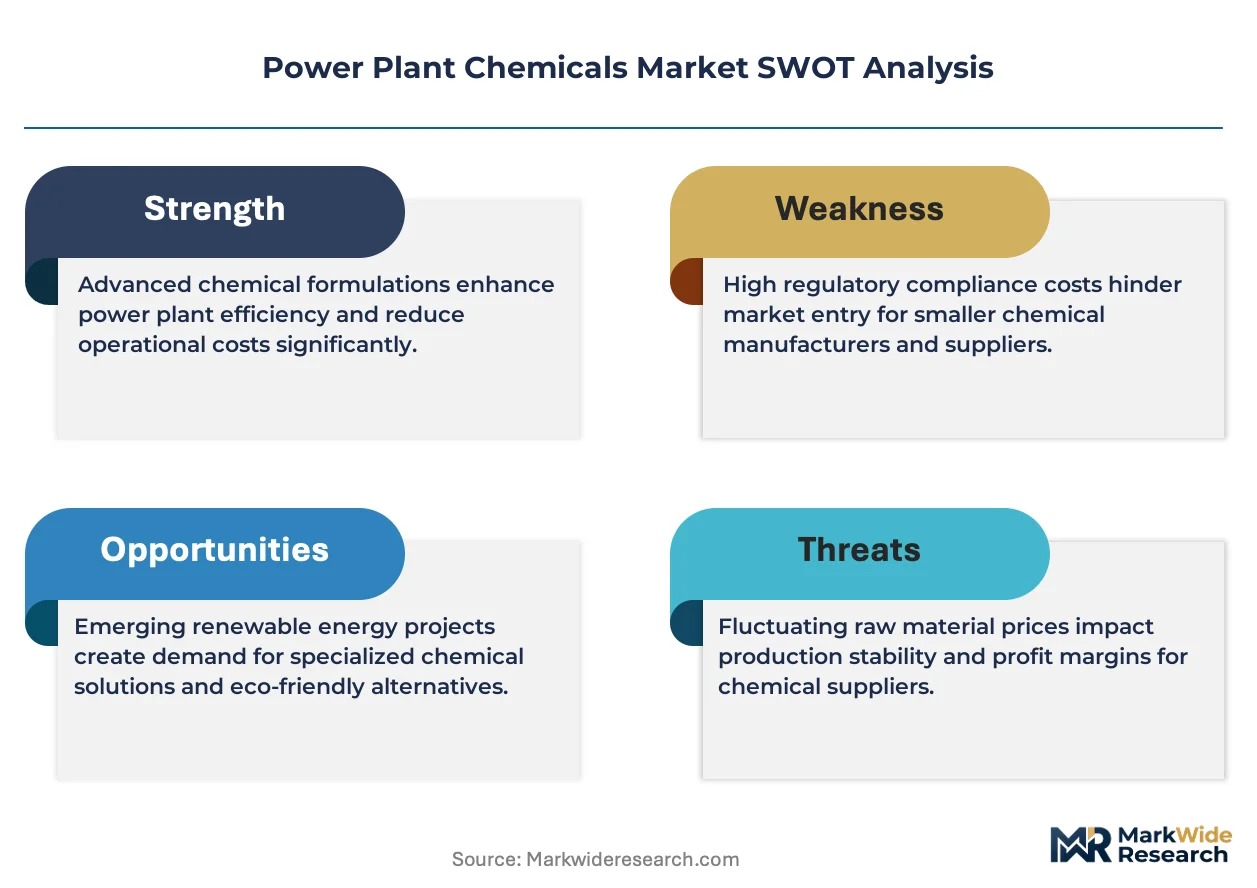
EPA effluent limitation guidelines are forcing coal-fired utilities to overhaul wastewater treatment infrastructure, redirecting capital toward precipitation chemistries and zero liquid discharge systems while compressing legacy chemical program budgets.
Growth Catalysts
- Zero liquid discharge mandates:EPA regulations at US coal plants are mandating advanced wastewater treatment, expanding demand for heavy metal precipitation and filtration chemistries.
- Biomass cofiring adoption:Thermal utilities in the Midwest and Southeast are blending agricultural residues with coal, requiring fuel treatment additives to manage corrosion and slagging.
- Flue gas desulfurization upgrades:Wet scrubber retrofits across the Gulf Coast corridor are consuming specialized coagulants for wastewater clarification and solids dewatering.
Market Restraints
- Feedstock cost volatility:Acrylic acid and phosphorus derivatives face price swings tied to crude oil and phosphate rock markets, compressing formulation margins.
- Supplier concentration risk:Specialty polymer production clusters in the US Gulf Coast and Rotterdam harbor expose buyers to hurricane and logistics disruptions.
- Amine degradation complexity:Carbon capture retrofits introduce new wastewater streams with heat-stable salts and corrosion byproducts lacking established treatment protocols.
Strategic Opportunities
- Combined-cycle hydrogen blending:Gas turbines adapting to hydrogen cofiring need modified fuel treatment chemistries and combustion deposit control.
- Digital chemical dosing platforms:IoT-enabled monitoring systems are opening recurring service revenue streams beyond commodity chemical sales.
- India's supercritical fleet expansion:NTPC and state utilities are commissioning high-efficiency coal units requiring ultra-pure water treatment specifications.
Industry Challenges
- Water chemist talent scarcity:Boiler water treatment expertise is retiring faster than vocational programs can replace, stretching plant technical staffs.
- Legacy DCS integration friction:New chemical monitoring systems require costly middleware to communicate with aging distributed control platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Plant Chemicals Market |
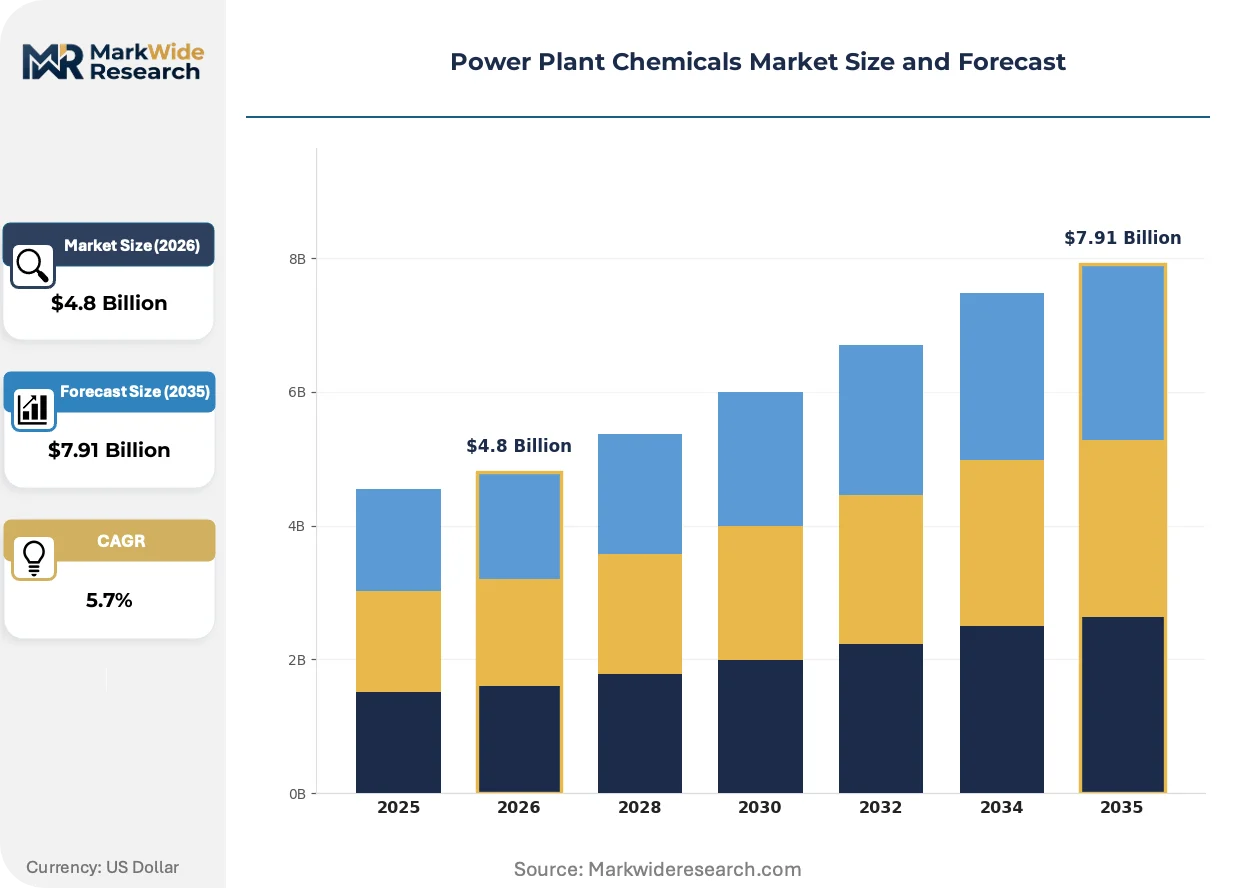
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Additives, Water Treatment, Fuel Treatment, Cleaning Agents Application: Steam Generation, Cooling Systems, Chemical Processing, Waste Management End User: Utility Companies, Independent Power Producers, Industrial Plants, Commercial Facilities Form: Liquid, Solid, Powder, Granular |
| Companies Covered | Nalco Water, Ecolab, Kemira, Veolia Water Technologies, SUEZ Water Technologies & Solutions, Curtis Bay Energy, AkzoNobel, BASF, Solenis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Plant Chemicals Market Emerging Trajectories
Treatment chemistries are pivoting toward closed-loop water systems and predictive dosing algorithms, displacing manual testing protocols and batch chemical additions across thermal generation fleets.
All-polymer internal treatment programs are migrating from traditional phosphate-pH control in high-pressure boilers. Combined-cycle operators in Texas and Florida are adopting these formulations to eliminate solids deposition and extend run lengths between acid cleanings. This shift is compressing demand for traditional phosphate-based products while elevating polymer suppliers with formulation expertise.
REACH authorization requirements for biocidal active substances are restricting quaternary ammonium compound availability in European cooling water applications. German and Polish power utilities are reformulating with alternative oxidizing biocides or non-chemical ultrasound systems. The transition is elevating compliance costs for chemical suppliers serving EU thermal fleets.
Long-term chemical service contracts are displacing spot procurement for boiler and cooling water programs. US independent power producers are bundling chemical supply with remote monitoring and performance guarantees. The model concentrates purchasing authority with corporate procurement teams rather than plant-level engineers.
Power Plant Chemicals Market Segmentation
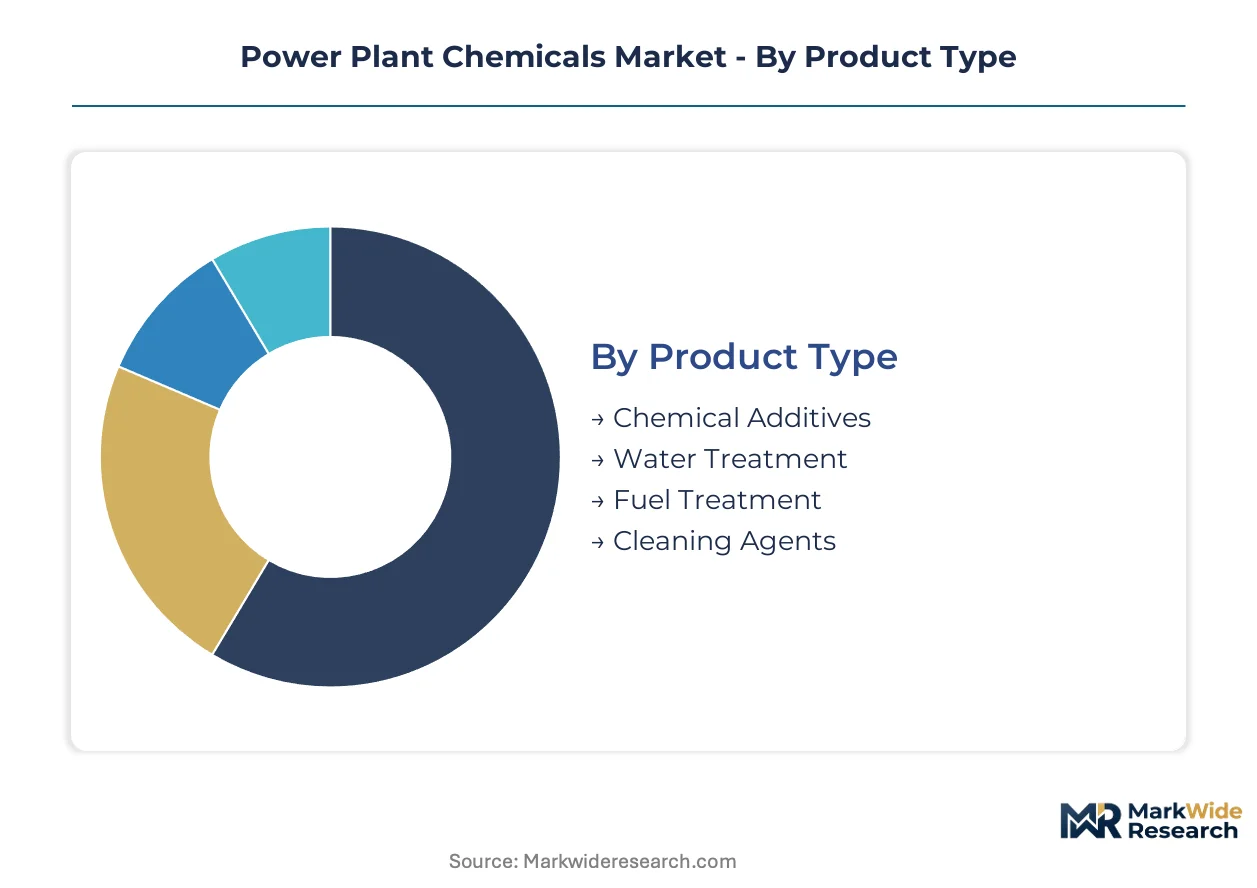
Power plant chemicals serve distinct operational functions across thermal generation infrastructure, with formulation chemistry and delivery form directly tied to equipment protection requirements and regulatory discharge limits. Segmentation reveals how supplier portfolios align with utility procurement patterns and retrofit-driven demand cycles.
Product Type:
Cost tier stratification separates commodity water treatment volumes from specialty fuel treatment margins and premium additive formulations.
- Chemical Additives:Formulated corrosion inhibitors and pH buffers protect boiler tubes and condensate systems from acidic attack and oxygen pitting. Demand concentrates across coal-fired fleets in the Ohio River Valley as plants extend outage intervals and defer capital replacement. EPA effluent guidelines are compressing phosphate-based program budgets while elevating polymer alternatives.
- Water Treatment:Coagulants, flocculants, and scale inhibitors manage feedwater purity and cooling tower blowdown. Gulf Coast combined-cycle operators are the primary consumption cluster, driven by zero liquid discharge mandates and brackish water sourcing. The category captures the highest procurement volumes but faces margin pressure from bulk commodity dynamics.
- Fuel Treatment:Combustion improvers and deposit modifiers address slagging and fouling in biomass cofiring and high-sulfur coal applications. Midwest utilities blending agricultural residues are expanding additive programs to manage corrosion byproducts and ash chemistry.
- Cleaning Agents:Acidic and alkaline formulations dissolve scale deposits during scheduled outages. Replacement cycles track boiler acid cleaning intervals, which are lengthening as polymer treatments reduce deposition rates.
Water treatment commands the established base. The steepest expansion runs through fuel treatment as cofiring adoption accelerates.
Application:
Volume concentration tracks the thermal duty cycle, with steam generation consuming continuous chemical injection and waste management absorbing episodic treatment spikes.
- Steam Generation:Boiler water conditioning requires continuous oxygen scavenger, pH adjuster, and phosphate or polymer dosing to prevent tube failures and maintain heat rate efficiency. Texas and Florida combined-cycle operators are migrating to all-polymer internal treatment programs that eliminate solids deposition. The application anchors supplier revenue through long-term service contracts with performance guarantees.
- Cooling Systems:Biocide programs control microbiological fouling in recirculating cooling towers and once-through systems. Seasonal load patterns and regional water scarcity drive demand volatility, with oxidizing biocides displacing quaternary ammonium compounds under tightening discharge limits.
- Chemical Processing:Amine treatment for carbon capture retrofits and flue gas conditioning chemicals represent emerging consumption nodes lacking established protocols for degradation product handling.
- Waste Management:Heavy metal precipitation and filtration chemistries treat flue gas desulfurization wastewater and bottom ash leachate. Wet scrubber retrofits across the Gulf Coast corridor are expanding coagulant demand for solids dewatering and clarification.
Steam generation absorbs the majority of recurring chemical spend. Waste management is climbing fastest as zero liquid discharge systems proliferate.
End User:
Customer type determines procurement authority concentration, with corporate-level contracting displacing plant-level purchasing among independent power producers.
- Utility Companies:Investor-owned and municipal utilities operate large coal and gas fleets with centralized chemical procurement and established supplier relationships. Gulf Coast and Midwest IOUs are bundling chemical supply with digital monitoring platforms to reduce technical staff burdens.
- Independent Power Producers:Merchant generators and renewable hybrids are adopting performance-based chemical service contracts that transfer operational risk to suppliers. Corporate procurement teams are consolidating purchasing authority away from plant engineers.
- Industrial Plants:Cogeneration facilities at refineries and chemical complexes maintain captive water treatment expertise and spot procurement flexibility.
- Commercial Facilities:District heating and smaller distributed generation represent fragmented demand with price-sensitive purchasing patterns.
Utility companies anchor the installed base. Independent power producers are expanding most quickly as merchant capacity and renewable hybrids multiply.
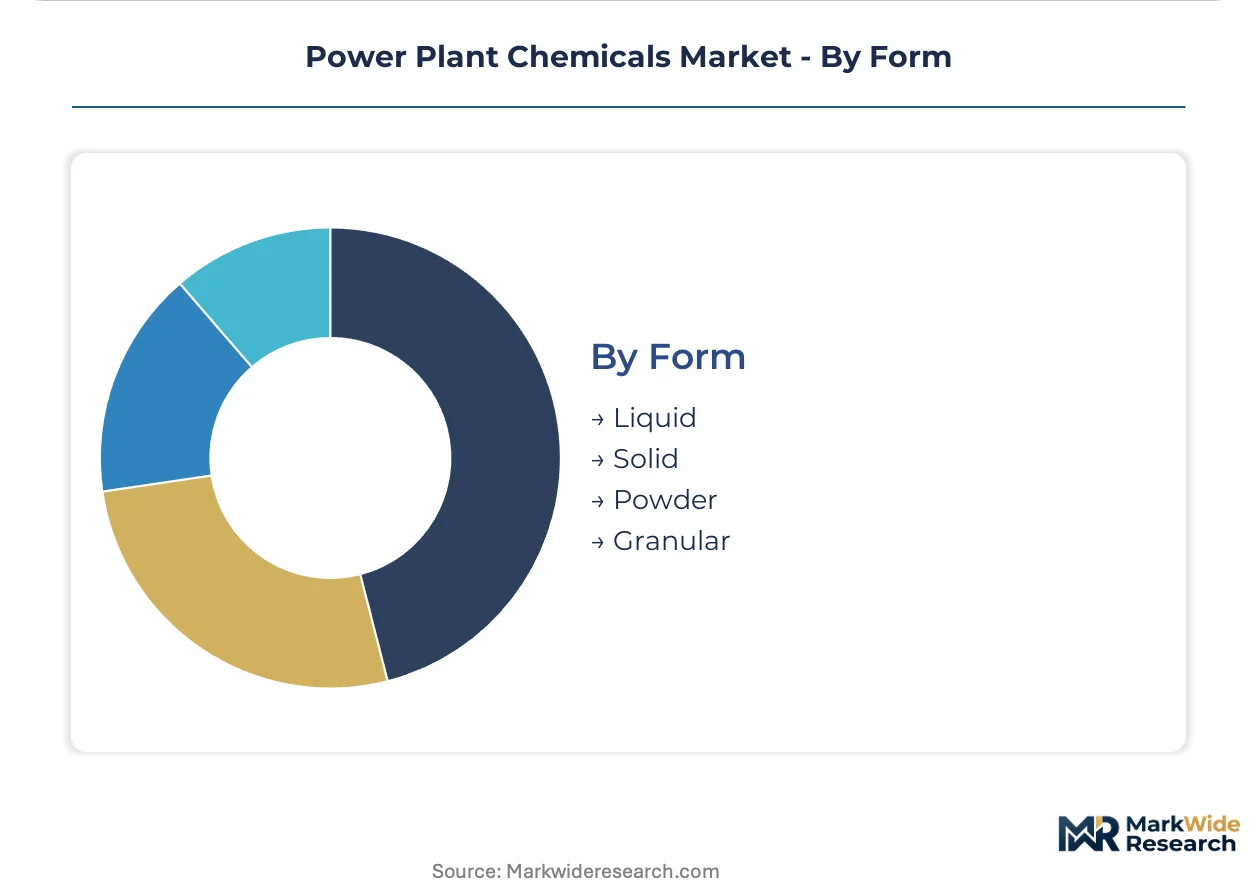
Form:
Supply chain configuration and dosing equipment compatibility shape form selection, with liquid formulations dominating continuous injection systems.
- Liquid:Ready-to-dose solutions integrate with automated feed systems and remote monitoring platforms. Gulf Coast chemical suppliers concentrate bulk liquid production near refining and petrochemical corridors.
- Solid:Tablet and block formulations serve cooling tower biocide applications and remote sites lacking bulk liquid handling infrastructure.
- Powder:Dry polymers and coagulants reduce transportation costs for high-volume water treatment programs, requiring on-site dissolution equipment.
- Granular:Controlled-release formulations extend dosing intervals in low-staffing environments and seasonal operations.
Liquid forms dominate operational consumption. Powder alternatives are gaining fastest where logistics costs and bulk storage constraints bite hardest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity on commodity water treatment chemicals, while Gulf Coast utilities in the United States absorb premium pricing for zero liquid discharge systems and digital service bundles without volume elasticity.
United States
EPA effluent limitation guidelines are forcing coal-fired utilities across the Ohio River Valley and Gulf Coast corridor to retrofit wastewater treatment infrastructure. The zero liquid discharge mandate at legacy coal plants is redirecting procurement budgets toward heavy metal precipitation chemistries and advanced filtration systems. Texas and Florida combined-cycle operators are migrating to all-polymer internal treatment programs that eliminate solids deposition.
Germany
REACH authorization requirements for biocidal active substances are restricting quaternary ammonium compound availability in cooling water applications. German power utilities are reformulating with alternative oxidizing biocides or non-chemical ultrasound systems to maintain regulatory compliance. The industrial cluster around the Rhine-Ruhr region anchors demand for specialized coagulant chemistry in flue gas desulfurization wastewater treatment.
China
Dual carbon goals and MEE discharge standards are accelerating treatment chemical adoption across thermal power fleets in the Yangtze River Delta and Pearl River Delta. State-owned utilities are commissioning ultra-supercritical coal units requiring ultra-pure water treatment specifications. The Shandong Peninsula concentration of coal-fired capacity is driving regional demand for oxygen scavengers and pH control additives.
India
NTPC and state utilities are expanding supercritical fleet capacity under Central Electricity Authority efficiency mandates, creating demand for high-purity boiler water treatment chemicals. The national pharmaceutical regulator's environmental compliance push is tightening discharge limits at captive power plants serving pharmaceutical clusters. Maharashtra and Gujarat industrial corridors are absorbing imported polymer formulations for cooling tower and boiler applications.
Japan
METI efficiency standards and aging thermal fleet maintenance cycles are sustaining replacement demand for boiler water treatment chemicals across the Kanto and Kansai regions. Japanese utilities are piloting amine-based carbon capture retrofits, introducing new wastewater streams with heat-stable salts requiring experimental treatment protocols. The Chubu industrial zone around Nagoya maintains concentrated demand for deposit control polymers in combined-cycle gas turbine systems.
Power Plant Chemicals Market Vendor Landscape
Integrated water treatment specialists and diversified chemical conglomerates split the market between service-intensive long-term contracts and volume-driven commodity supply. The vendor base concentrates around three strategic archetypes: digital platform operators bundling remote monitoring with chemical supply, regional coagulant and polymer formulators serving utility procurement clusters, and diversified industrial chemical houses leveraging backward integration into phosphorus and acrylic acid derivatives. Competitive positioning hardens through M&A capture of specialized formulation expertise and geographic expansion into India's supercritical fleet buildout.
Within the digital platform tier, Nalco Water and Ecolab exemplify the service-contract model that transfers operational risk from plant engineers to supplier technical staffs. Kemira and Solenis occupy positions as specialized formulators with deep expertise in deposit control polymers and flue gas desulfurization wastewater chemistry. These named entities represent how competitive advantage is concentrating in predictive dosing algorithms and performance-guaranteed chemical programs rather than commodity volume supply.
| Leading Market Players |
|---|
| Nalco Water |
| Ecolab |
| Kemira |
| Veolia Water Technologies |
| SUEZ Water Technologies & Solutions |
| Curtis Bay Energy |
| AkzoNobel |
| BASF |
| Solenis |
| Others |
Supply Flow & Price Mechanics
Houston Ship Channel freight rates directly feed into delivered chemical costs for Gulf Coast power generators, concentrating pricing power among suppliers with captive barge fleets while forcing inland utilities to absorb premium logistics differentials. This corridor cost structure reinforces three-tier pricing stratification across premium digital service bundles, standard formulated chemistries, and economy bulk commodity volumes.
Pricing Analysis
Aftermarket service revenue from digital dosing optimization drives lifetime value capture for incumbent suppliers. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and remote monitoring bundling. Cost compression in commodity water treatment volumes is intensifying because acrylic acid and phosphorus derivative feedstock volatility squeezes formulation margins. Independent power producers exhibit acute price sensitivity on spot chemical procurement, whereas investor-owned utilities absorb premium service bundles without volume elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for phosphorus derivative and specialty polymer sourcing. Production gravity centers on the US Gulf Coast, Rotterdam harbor, and Shandong Peninsula, with these regions anchoring global coagulant and scale inhibitor output. Raw material dependencies rest on phosphate rock, acrylic acid, and amine compounds. Single-source vulnerability concentrates in hurricane-exposed Gulf Coast chemical clusters. Distribution runs through bulk liquid terminals, regional blending facilities, and direct-to-plant tanker delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power plant chemicals market is entering a cyclical recovery phase as EPA effluent mandates force wastewater treatment retrofits across aging coal fleets, triggering replacement demand cycles for precipitation chemistries and zero liquid discharge systems.
For Market Incumbents: Build switching-cost moats through long-term performance-guaranteed service contracts that embed remote monitoring platforms and transfer operational risk from utility technical staffs. Deepen backward integration into phosphorus derivatives to defend margin position against feedstock volatility. Consolidate formulation expertise through targeted acquisition of regional polymer specialists serving India's supercritical fleet expansion. For New Entrants and Emerging Players: India's state utility procurement clusters represent underpenetrated white space where imported polymer formulations currently serve NTPC supercritical units requiring ultra-pure water specifications. Target fuel treatment additive programs for Midwest biomass cofiring applications as agricultural residue blending accelerates corrosion management demand. Enter through digital-native dosing platforms that bypass legacy DCS integration friction. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial chemical houses seeking to divest non-core water treatment divisions amid portfolio rationalization pressures. Long-term viability centers on service-contract recurring revenue models rather than commodity volume exposure. Watch carbon capture retrofit deployment rates as the inflection signal for amine degradation chemistry demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Derivatives | Captive supply of phosphate rock and phosphoric acid secures margin stability against commodity volatility. |
| Digital Chemical Dosing Platform Deployment | IoT-enabled monitoring systems at Texas combined-cycle plants open recurring service revenue streams beyond commodity sales. |
| Zero Liquid Discharge System Partnership | Collaboration with FGD wastewater treatment providers captures EPA-mandated retrofit spending across Ohio River Valley coal fleets. |
| India Supercritical Fleet Technical Specification | NTPC ultra-pure water chemistry requirements create formulation expertise barriers for imported polymer suppliers. |
| Fuel Treatment Additive Development for Biomass Cofiring | Midwest agricultural residue blending programs demand corrosion inhibitors managing slagging and ash chemistry. |
Methodological Framework
Desk research of EPA effluent limitation guidelines, ACC industry reports, and SEC 10-K chemical segment disclosures preceded structured interviews with utility procurement directors, power plant water chemists, EPC contractors, and specialty chemical formulators. Primary fieldwork across the Gulf Coast generation corridor and Midwest coal fleet operators combined with secondary validation from customs trade data and FERC filings. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and end user segments.
Assumptions held regulatory stringency and coal fleet retirement schedules within announced utility plans while varying natural gas price scenarios and carbon capture adoption rates across the projection horizon. The analytical framework modeled segmentation across water treatment grade tiers, fuel source categories, generation capacity classes, and regional regulatory clusters. CAGRs derived from historical replacement cycle patterns and retrofit-driven demand spikes. Forecast inputs incorporated polymer treatment adoption curves and zero liquid discharge mandate compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-owned chemical enterprises or accelerated coal plant closures would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Hydrophobing Agents Market
Chemicals
Allyl Alcohol Market
Chemicals
Muriatic Acid Market
Chemicals
Trifluoroacetic Acid (TFA) Market
Chemicals
Europe Hydrazine Market
Chemicals
Lauryl Dimethyl Amine Oxide Market
Chemicals
Desalination Chemicals Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Amyl Nitrite Market
Chemicals
Hypophosphorous Acid Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Pentanedione Market
Chemicals
Acid Anhydrides Market
Chemicals
Barbituric Acid Market
Chemicals
Global Benzalkonium Chloride Market