
 Phosphorus Pentasulfide (P2S5) Market | 2026-2036
Phosphorus Pentasulfide (P2S5) Market Size, Share, and Industry Trends Forecast 2026-2036
Phosphorus Pentasulfide (P2S5) Market Analysis
REACH registration requirements for hazardous intermediates is shifting the cost-of-entry calculus for European P2S5 suppliers, forcing smaller traders toward toll-manufacturing arrangements. Italmatch Chemicals S.p.A. leverages backward integration into yellow phosphorus to secure feedstock stability across its specialty phosphorus portfolio. ICL Group Ltd. anchors its position through captive phosphate rock access and multi-site manufacturing redundancy. Solvay S.A. differentiates via reagent-grade purification capabilities serving pharmaceutical and electronics customers.
Phosphorus pentasulfide is an inorganic compound with the empirical formula P4S10, commonly referenced as P2S5, appearing as yellow-green crystalline flakes with a melting point near 288°C; manufacturers produce it via direct reaction of red phosphorus with sulfur at controlled temperatures, yielding a reagent essential for thiophosphate and dithiophosphate synthesis across lubricant, agrochemical, and battery chemistry applications. Industrial grade material dominates volume flows into pesticide and rubber additive channels, while reagent grade commands premium pricing from lithium battery electrolyte salt producers. Pharmaceutical grade represents a nascent but high-margin pocket, constrained by batch consistency requirements and limited qualified suppliers.
EPA hazardous waste regulations and OSHA permissible exposure limits govern US handling and disposal protocols, while China's MEE enforces emissions caps on phosphorus chemical clusters in Yunnan and Guizhou provinces. The EU F-Gas Regulation and emerging battery passport standards indirectly shape P2S5 demand through lithium-ion supply chain traceability mandates. Stakeholders must monitor how sulfur and phosphorus feedstock cost volatility interacts with tightening occupational exposure thresholds across major manufacturing jurisdictions.
Market Dynamics
China's dominance in yellow phosphorus refining and cathode material manufacturing is reshaping P2S5 supply geography, concentrating electrolyte-grade production within domestic chemical clusters while forcing European and North American buyers to navigate REACH registration burdens and tariff exposure.
Growth Catalysts
- Lithium battery electrolyte salt expansion:Lithium hexafluorophosphate and lithium bis(fluorosulfonyl)imide production lines in China and South Korea are pulling high-purity P2S5 demand upward as gigafactory construction accelerates.
- REACH registration compliance:The European Chemicals Agency's substance evaluation protocols are consolidating supplier bases, advantaging registrants with full dossiers and pushing toll-manufacturing partnerships.
- Phosphorus chemical cluster development:Yunnan and Guizhou provinces in China are expanding captive sulfur-phosphorus integration, lowering feedstock logistics costs for domestic P2S5 manufacturers serving battery material supply chains.
Market Restraints
- Yellow phosphorus price volatility:Electricity-intensive thermal phosphorus production exposes P2S5 cost structures to power tariff fluctuations and seasonal supply constraints in southwestern China.
- Occupational exposure thresholds:OSHA permissible exposure limits and EU occupational exposure bands are tightening handling protocols, raising compliance costs for processors without closed-system reactor technology.
- Elemental sulfur supply concentration:Global sulfur markets concentrate around oil refining and natural gas processing byproduct flows, linking P2S5 input costs to hydrocarbon sector dynamics.
Strategic Opportunities
- Pharmaceutical-grade qualification:Batch-consistent P2S5 for active pharmaceutical ingredient synthesis remains undersupplied, with few qualified producers meeting ICH Q7 guidelines for thiophosphate intermediates.
- EU Battery Regulation traceability:The battery passport mandate creates premium positioning for European-based P2S5 suppliers with verified carbon footprint data and conflict-mineral-free phosphorus sourcing.
- Solid-state electrolyte precursor demand:Thio-LISICON and argyrodite sulfide solid electrolyte research programs are integrating P2S5-derived thiophosphate building blocks into next-generation cell architectures.
Industry Challenges
- Reactor corrosion management:Molten sulfur and phosphorus handling at elevated temperatures demands specialized alloy construction and preventive maintenance protocols that compress operating margins.
- Multi-jurisdictional registration timelines:Parallel EPA TSCA pre-manufacture notifications, REACH registrations, and China's MEE new chemical substance notifications extend market entry cycles for product variants.
- Analytical method standardization:Inconsistent impurity profiling specifications between industrial-grade and battery-grade customers complicates quality assurance and lot release procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phosphorus Pentasulfide (P2S5) Market |
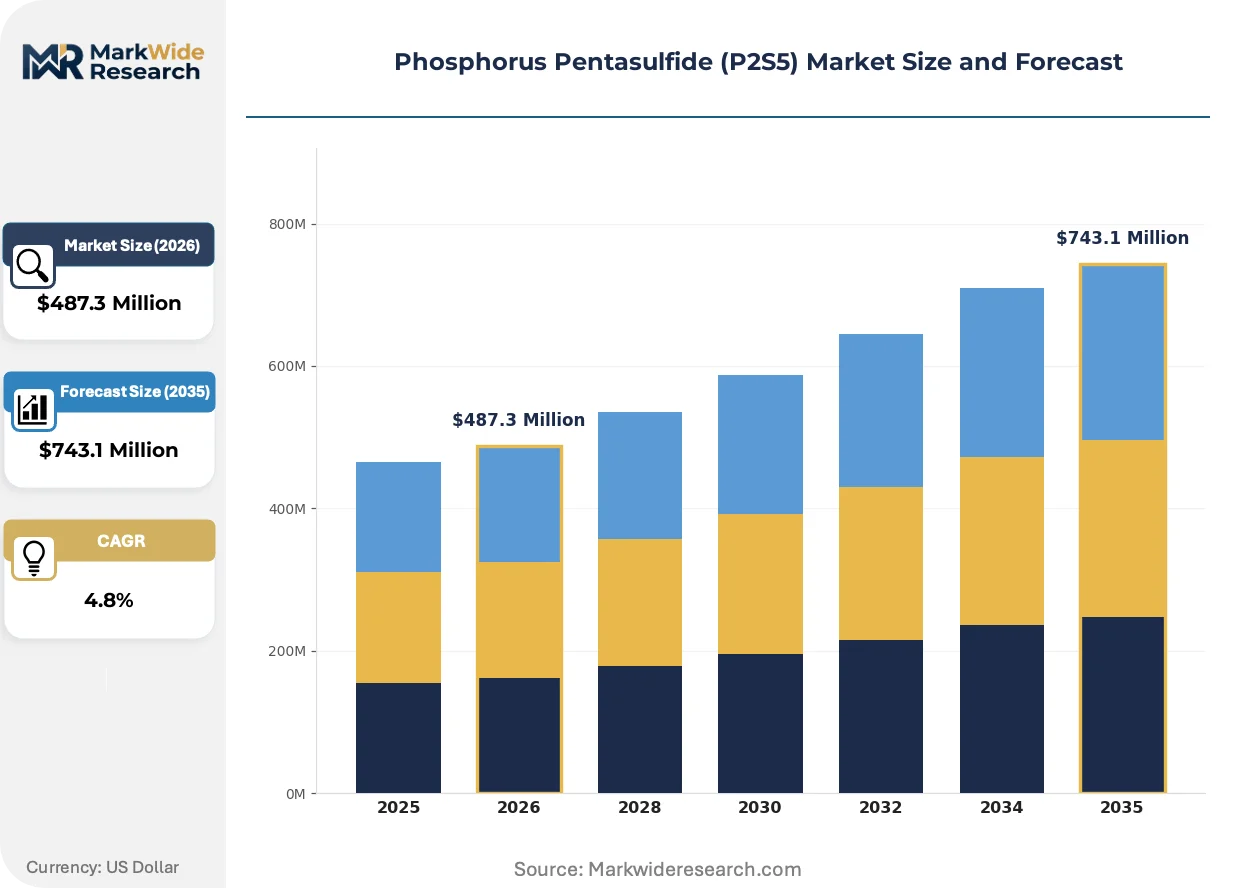
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Agricultural Grade, Pharmaceutical Grade Application: Lithium Batteries, Pesticide Production, Coating Applications, Rubber Additives End User: Agriculture, Electronics, Chemical Manufacturing, Pharmaceuticals Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Stores |
| Companies Covered | Italmatch Chemicals S.p.A., Perimeter Solutions, ICL Group Ltd., Nissan Chemical Corporation, Chemtrade, Solvay S.A., Fosfoquim S.A., The Shepherd Chemical Company, Lanxess AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phosphorus Pentasulfide (P2S5) Market Emerging Trajectories
Continuous reactor technology and closed-loop sulfur recovery systems are displacing batch processing in high-volume P2S5 manufacturing, while regulatory pressure on carbon intensity and supply chain traceability is reshaping procurement qualification criteria across battery material tiers.
Membrane-based purification technology is integrating into P2S5 finishing trains, enabling sub-ppm metal impurity removal required for lithium salt synthesis. Korean and Chinese electrolyte producers are adopting these units to meet cathode material specifications without reliance on solvent recrystallization. The technology is compressing the cost gap between industrial-grade and battery-grade product tiers.
The EU F-Gas Regulation and emerging battery passport standards are tightening substance traceability requirements for imported battery materials. European cathode manufacturers are now demanding REACH-registered P2S5 with documented carbon footprint calculations. This regulatory pressure is forcing non-EU suppliers to establish EU-based tolling partnerships or invest in registration dossiers.
Long-term offtake contracting is displacing spot market purchasing among large electrolyte salt producers. Tier-one battery manufacturers are securing multi-year P2S5 supply agreements directly with phosphorus chemical specialists, bypassing traditional distributor channels. This concentration is most visible in China, where CATL and BYD's supply chain affiliates are integrating backward into phosphorus refining.
Phosphorus Pentasulfide (P2S5) Market Segmentation
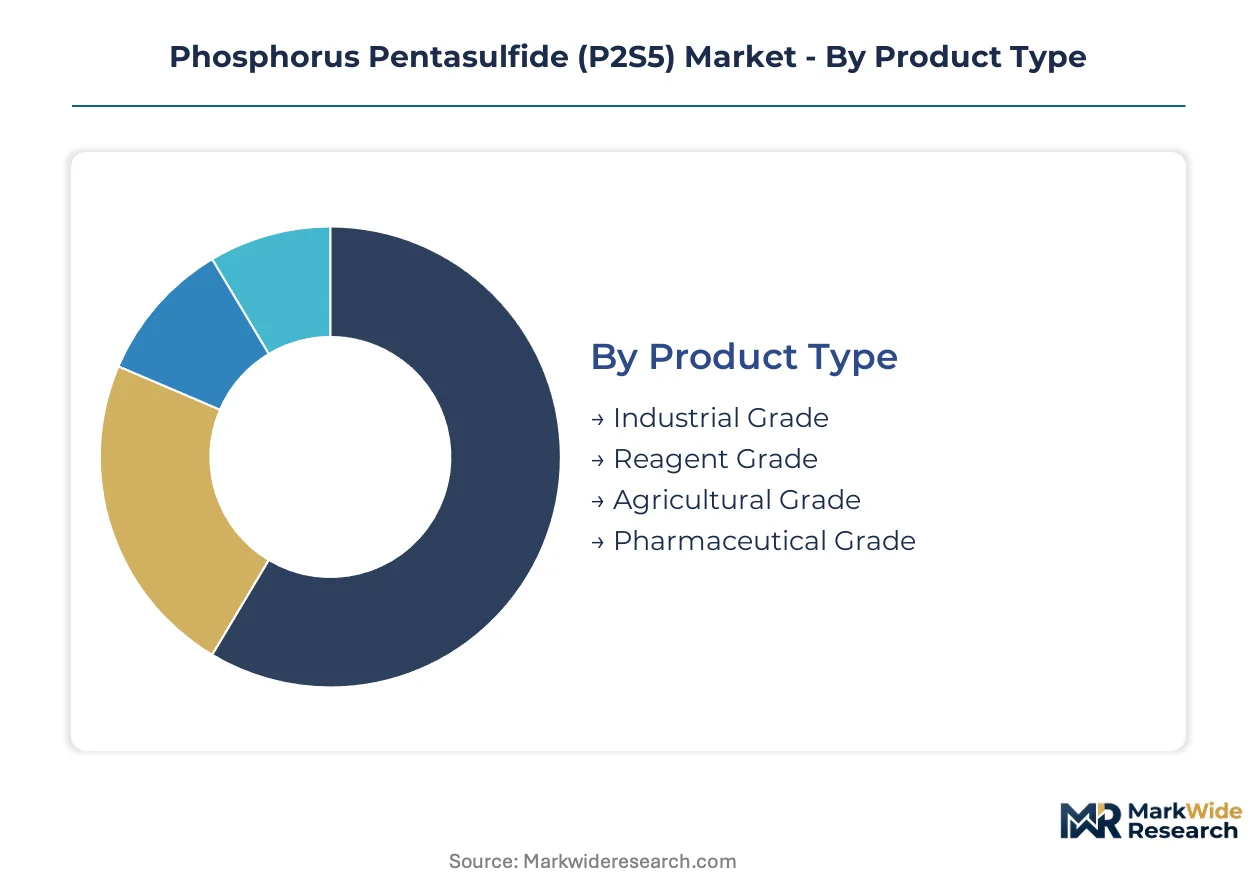
P2S5 buyers operate across fundamentally different specification regimes, from commodity pesticide formulations to sub-ppm purity lithium salt synthesis. Segmentation reveals how grade differentiation, application chemistry, and channel economics partition the market into non-substitutable demand pools with divergent margin structures.
Product Type:
Cost tier separates buyers more than application label, with purification intensity determining pricing power and supplier qualification barriers.
- Industrial Grade:Material with 95-98% purity and higher residual phosphorus content serves pesticide and rubber additive manufacturers through bulk rail and tanker deliveries. Volume concentrates in China's Yangtze River Delta chemical clusters, where integrated phosphorus refiners supply captive thiophosphate derivative plants with minimal logistics friction.
- Reagent Grade:Sub-ppm metal impurity specifications enable lithium hexafluorophosphate and lithium bis(fluorosulfonyl)imide synthesis for electrolyte salt producers. Korean and Chinese gigafactory supply chains are pulling this grade upward as cathode material specifications tighten, with membrane purification technology compressing historical premiums.
- Agricultural Grade:Intermediate purity tier optimized for organophosphate pesticide active ingredient synthesis, with moisture content controls stricter than industrial grade but metal tolerance looser than reagent specifications.
- Pharmaceutical Grade:Batch consistency under ICH Q7 guidelines for thiophosphate intermediates in active pharmaceutical ingredient routes; qualified supplier scarcity maintains structural premiums.
Volume sits with Industrial Grade; growth tilts toward Reagent Grade.
Application:
Application chemistry determines specification stringency, with electrochemical performance requirements creating the steepest purity gradients.
- Lithium Batteries:Electrolyte salt synthesis demands sub-ppm sodium, iron, and copper tolerances to prevent cathode degradation and cell gassing. Chinese producers are expanding dedicated reagent-grade lines to serve CATL and BYD supply chain affiliates.
- Pesticide Production:Thiophosphate and dithiophosphate intermediates for insecticide and fungicide manufacturing consume the largest absolute tonnage, with formulation flexibility permitting broader impurity windows.
- Coating Applications:Metal treatment and corrosion inhibitor formulations utilize P2S5-derived thiophosphate esters; specification requirements vary by substrate metal and end-use environment.
- Rubber Additives:Vulcanization accelerator precursors represent mature demand with stable volume but limited pricing power due to alternative sulfur donor chemistry availability.
Absolute tonnage flows through Pesticide Production; margin expansion concentrates in Lithium Batteries.
End User:
Customer technical capability and regulatory exposure shape procurement patterns more than sector scale alone.
- Agriculture:Formulation houses and generic pesticide manufacturers purchase industrial and agricultural grades through distributor networks with seasonal demand concentration around planting cycles.
- Electronics:Battery material and semiconductor chemical producers enforce the most rigorous supplier qualification protocols, with multi-year offtake agreements displacing spot purchasing among tier-one electrolyte salt manufacturers.
- Chemical Manufacturing:Intermediate producers serving multiple downstream channels operate flexible procurement strategies, shifting grade specifications based on derivative product mix.
- Pharmaceuticals:API manufacturers and contract development organizations represent the smallest volume pool but highest margin tier, with audit and documentation requirements limiting qualified supplier bases.
Procurement scale favors Agriculture; contract duration and technical service intensity peak with Electronics.
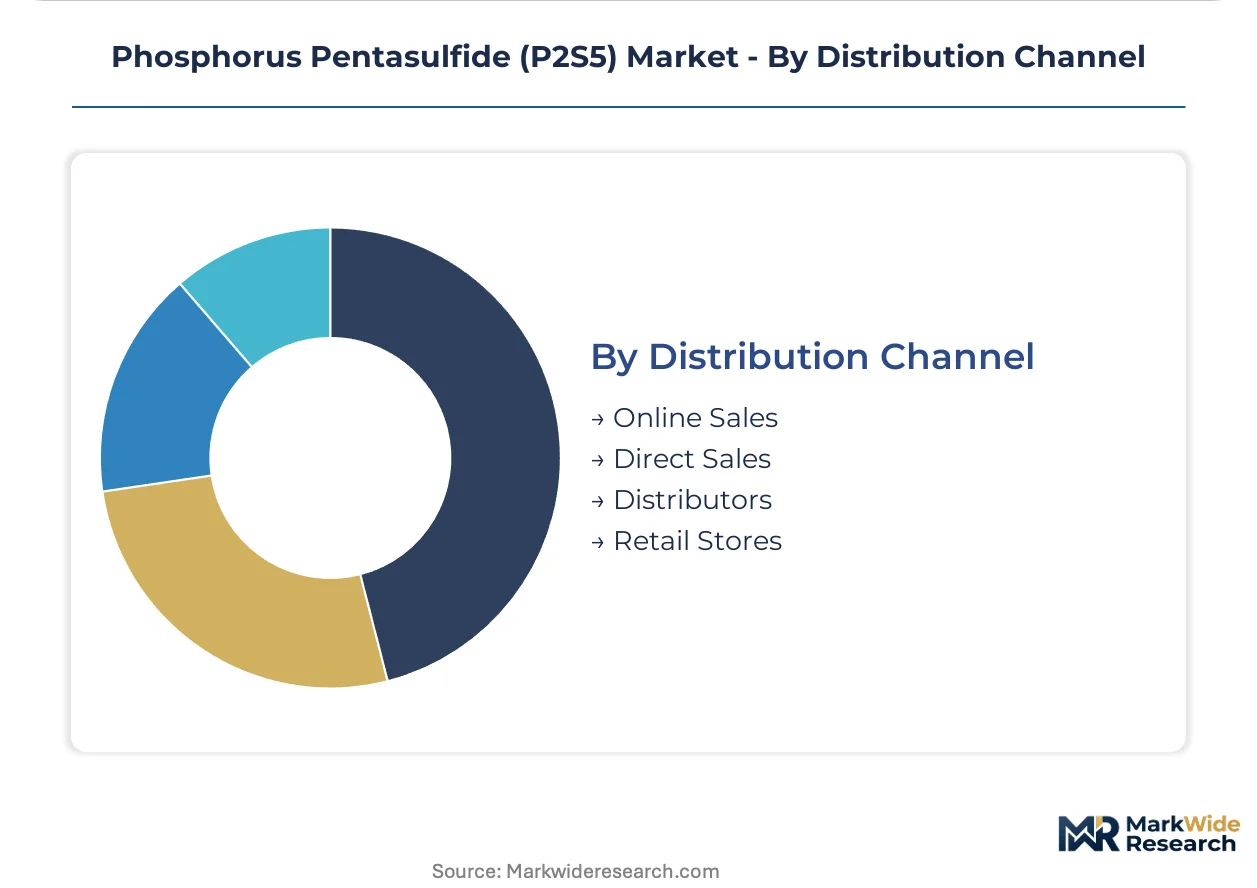
Distribution Channel:
Channel selection tracks customer scale and specification complexity, with direct relationships dominating high-purity segments.
- Direct Sales:Long-term supply agreements between phosphorus chemical specialists and large electrolyte salt or pesticide manufacturers, with technical service and joint specification development bundled.
- Distributors:Regional chemical distributors serve mid-tier pesticide formulators and coating manufacturers with inventory pooling and smaller lot sizing.
- Online Sales:E-procurement platforms capture spot demand for industrial-grade material from small-volume users and research institutions.
- Retail Stores:Minimal penetration; limited to agricultural supply cooperatives in developing markets with informal distribution infrastructure.
Contract value concentrates in Direct Sales; transaction frequency peaks through Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's phosphorus chemical industrial parks in Yunnan and Guizhou provinces anchor global P2S5 capacity, leveraging captive yellow phosphorus refining and integrated sulfur processing to serve battery material supply chains.
China
Lithium hexafluorophosphate and bis(fluorosulfonyl)imide producers in Jiangsu and Zhejiang provinces drive reagent-grade P2S5 consumption as CATL and BYD expand cathode material operations. MEE emissions caps on phosphorus clusters in Yunnan tighten production protocols. Kunming and Guiyang chemical parks concentrate electrolyte-grade manufacturing with backward integration into thermal phosphorus plants.
United States
EPA hazardous waste regulations and OSHA permissible exposure limits govern handling protocols for pesticide and lubricant additive manufacturers. Domestic demand flows through Gulf Coast chemical corridors serving agrochemical formulators. Texas and Louisiana industrial clusters process industrial-grade material for rubber additive and coating applications with established waste management infrastructure.
Germany
REACH registration requirements for hazardous intermediates consolidate supplier bases serving pharmaceutical and specialty chemical channels. ECHA substance evaluation protocols advantage dossier-complete registrants. Leverkusen and Ludwigshafen chemical complexes host toll-manufacturing arrangements for battery-grade material destined for European cathode producers.
South Korea
LG Chem and Samsung SDI electrolyte salt operations pull high-purity P2S5 through long-term offtake agreements with qualified suppliers. MFDS chemical substance notifications govern import and handling procedures. Ulsan and Yeosu petrochemical clusters integrate membrane purification technology for sub-ppm metal impurity removal serving gigafactory supply chains.
Japan
Thio-LISICON solid-state electrolyte research programs at METI-funded battery consortiums create precursor demand for specialized thiophosphate building blocks. JIS standards and PMDA pharmaceutical guidelines constrain qualified supplier bases. Osaka and Nagoya chemical corridors concentrate reagent-grade production for electronics and pharmaceutical applications.
Phosphorus Pentasulfide (P2S5) Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across differentiated grade tiers. The supplier base organizes around captive feedstock control, purification technology depth, and multi-jurisdictional registration capabilities. Three archetypes dominate: integrated phosphorus refiners with backward control over yellow phosphorus; specialty chemical houses with membrane purification and pharmaceutical qualification; and regional toll-manufacturers serving REACH-registered demand. Competitive moves center on long-term offtake contracting with battery material producers and toll-manufacturing partnerships to bypass registration burdens.
Among Italy-based chemical groups, Italmatch Chemicals S.p.A. exemplifies the integrated refiner archetype with captive yellow phosphorus access. ICL Group Ltd. and Solvay S.A. anchor the specialty chemical tier, representing diversified players with multi-site manufacturing and reagent-grade purification capabilities. These three occupy positions spanning industrial through pharmaceutical grade segments.
| Leading Market Players |
|---|
| Italmatch Chemicals S.p.A. |
| Perimeter Solutions |
| ICL Group Ltd. |
| Nissan Chemical Corporation |
| Chemtrade |
| Solvay S.A. |
| Fosfoquim S.A. |
| The Shepherd Chemical Company |
| Lanxess AG |
| Others |
Supply Flow & Price Mechanics
Captive sulfur-phosphorus integration across Yunnan and Guizhou chemical parks anchors both feedstock security and pricing power for Chinese electrolyte-grade producers, compressing margins for toll-dependent European competitors facing REACH registration cost burdens.
Pricing Analysis
Short-lead-time premiums for battery-grade material widen against discounted spot industrial-grade inventory as Korean and Chinese gigafactory supply chains lock in multi-year offtake contracts. Three-tier pricing structure across pharmaceutical, reagent, and industrial levels separates ICH Q7-qualified batches from membrane-purified electrolyte grades and commodity pesticide inputs. Cost compression in industrial-grade channels intensifies because membrane technology narrows purity premiums. Pesticide formulators exhibit highest price sensitivity; pharmaceutical API manufacturers show least.
Supply Chain Analysis
Skilled reactor operator availability in southwestern China and the U.S. Gulf Coast constrains capacity expansion timelines for continuous-process P2S5 lines. Manufacturing concentrates in China, South Korea, and Germany. Feedstock draws from yellow phosphorus refineries, elemental sulfur byproduct streams, and specialized alloy reactor components. Single-source vulnerability runs through Yunnan thermal phosphorus clusters exposed to power tariff volatility. Distribution runs through direct long-term agreements for battery-grade material and regional chemical distributors for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around REACH-registered suppliers with captive phosphorus access, as registration cost burdens force toll-dependent traders toward acquisition or exit.
For Market Incumbents: Extend membrane purification capabilities into pharmaceutical-grade qualification to capture ICH Q7 premiums before specialty chemical houses consolidate the tier. Lock multi-year offtake agreements with CATL and BYD supply chain affiliates to defend against Korean electrolyte producers integrating backward into phosphorus refining. Prioritize reactor corrosion management R&D to sustain operating margins against tightening OSHA and EU occupational exposure protocols.
For New Entrants and Emerging Players: Capture toll-manufacturing demand from European battery material producers seeking REACH-registered, carbon-footprint-documented supply without dossier investment. Target pharmaceutical-grade white space where qualified supplier scarcity sustains structural premiums. Enter through partnership with established phosphorus refiners lacking purification finishing capacity.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated phosphorus conglomerates seeking battery-grade purification technology and EU regulatory dossiers. Five-to-ten-year viability hinges on solid-state electrolyte precursor demand materializing from thio-LISICON and argyrodite research programs. Watch MFDS and ECHA substance evaluation timelines as inflection indicators for registration-driven consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Yellow Phosphorus | Italmatch's captive feedstock control insulates margins against electricity tariff volatility in Yunnan. |
| Membrane Purification Technology Deployment | Korean electrolyte producers leverage sub-ppm metal removal to meet CATL cathode specifications without solvent recrystallization. |
| REACH Registration Dossier Completion | ECHA substance evaluation protocols advantage dossier-complete registrants and force toll-manufacturing partnerships. |
| Long-term Supply Agreement Structuring | Tier-one battery manufacturers bypass distributor channels to secure multi-year P2S5 offtake directly with phosphorus specialists. |
| Pharmaceutical-grade ICH Q7 Qualification | Batch consistency for thiophosphate intermediates maintains structural premiums amid qualified supplier scarcity. |
Methodological Framework
Independent corroboration across regulatory filings, customs trade data, and phosphorus chemical industry associations underwrites the qualitative findings. Primary interviews with plant managers at Yunnan and Guizhou refineries, procurement leads at Korean electrolyte salt producers, distribution channel partners in European agrochemical corridors, and technical R&D directors at solid-state battery consortiums informed supply-side and demand-side dynamics. Secondary validation drew from ECHA REACH registration databases, MEE emissions disclosure filings, SEC 10-K extracts for listed phosphorus specialists, and ACC/Cefic specialty chemical reports. Bottom-up grade-tier volume estimates triangulated against top-down cathode material production forecasts.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by grade tier, end-use application chemistry, and regional production hub. Modeled dimensions include industrial-reagent-pharmaceutical grade stratification, lithium battery-pesticide-coating-rubber additive application mix, and China-South Korea-Europe-North America supply geography. CAGRs derive from electrolyte salt capacity expansion pipelines, cathode material specification evolution, and REACH registration timeline impacts. Forecast inputs incorporate yellow phosphorus power cost curves, membrane purification technology diffusion rates, and solid-state electrolyte precursor research funding flows.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Battery Regulation traceability mandate implementation, sulfur byproduct supply shifts from oil refining decarbonization, and Chinese MEE emissions cap enforcement intensity. Forecasts reflect documented assumptions on gigafactory construction schedules and cathode chemistry transitions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Chiral Chemicals Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Sulfur Chemicals Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Oxybenzone Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Chemical As a Service Market
Chemicals
Tanning Agents Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Cumene Market
Chemicals
Isoamyl Acetate Market
Chemicals
Global Butanediol Market
Chemicals
Diphenyl Sulfone Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
RO Membrane Chemicals Market