
 Scouring Agents Market | 2026-2036
Scouring Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Scouring Agents Market Outlook
Market Context
REACH compliance in Europe is decoupling legacy surfactant formulations from import eligibility, forcing Asian suppliers toward biodegradable chemistries. BASF SE leverages its specialty surfactant portfolio to sustain formulation leadership across European textile mills. Evonik Industries AG anchors its position through biosurfactant R&D intensity, while DyStar Singapore Pte Ltd. competes on regional channel control in Southeast Asian wet-processing hubs.
Technical Definition and Segments
Scouring agents are surface-active chemical formulations, typically anionic or non-ionic surfactants combined with chelating agents and alkalis, designed to remove natural waxes, pectins, and mineral impurities from raw textile fibers during pretreatment. Alkaline scouring dominates volume due to its cost efficiency on cotton and cotton-blend substrates, though enzymatic formulations represent the fastest-expanding margin pool as mills retrofit for reduced water and energy footprints. Liquid form factors lead industrial adoption for automated dosing systems, while powder scouring agents retain share in batch-processing operations across South Asian textile clusters.
Regulatory Frame and Outlook
EMA and ECHA frameworks in Europe govern biodegradability thresholds and aquatic toxicity limits for industrial surfactants, while India's BIS standards enforce quality specifications for textile-processing chemicals sold domestically. China's MEE regulations on wastewater COD discharge are restricting nonylphenol ethoxylate use in eastern province mills. Stakeholders must monitor regulatory divergence between EU biodegradability mandates and emerging economy enforcement gaps to calibrate regional product portfolios.
Market Dynamics
Enzymatic scouring technology is compressing process temperatures and water volumes, forcing chemical suppliers to reformulate around biosurfactant platforms as mills retrofit pretreatment lines for energy and effluent compliance.
Growth Catalysts
- REACH biodegradability mandates:European ECHA thresholds for aquatic toxicity are disqualifying legacy alkylphenol ethoxylates, pulling reformulation investment toward green surfactant chemistries.
- Bangladesh textile expansion:Wet-processing capacity additions in Dhaka and Chittagong are generating concentrated procurement of low-temperature scouring systems.
- Enzymatic pectinase platforms:Cellulase-compatible scouring enzymes are enabling combined desizing-scouring sequences that cut bath changes and steam loads.
Market Restraints
- Palm kernel oil feedstock volatility:Fatty alcohol precursors for non-ionic surfactants face price swings tied to Malaysian and Indonesian plantation output disruptions.
- Specialty enzyme supply concentration:Industrial pectinase and lipase production clusters in Denmark and the Netherlands create single-source vulnerability for Asian formulators.
- Performance gaps on synthetic blends:Enzymatic systems show reduced efficacy on polyester-cotton substrates versus alkaline scouring, limiting substitution on blended fabric runs.
Strategic Opportunities
- Vietnam wet-processing buildout:Ho Chi Minh City and Binh Duong province mills are greenfield-installing enzymatic pretreatment circuits without legacy alkaline infrastructure.
- China MEE wastewater incentives:Provincial COD discharge credits reward mills adopting biodegradable scouring agents, creating policy-tied demand pull.
- Digital dosing integration:Automated chemical injection systems in Turkish textile parks enable real-time enzymatic activity monitoring and recipe optimization.
Industry Challenges
- Enzyme stability in alkaline carryover:Pretreatment bath pH drift from residual caustic in continuous ranges denatures pectinase activity, requiring buffer chemistry investments.
- Multi-standard certification timelines:Mills supplying EU, US, and Japanese end-users must synchronize bluesign, ZDHC, and OEKO-TEX approvals, extending product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scouring Agents Market |
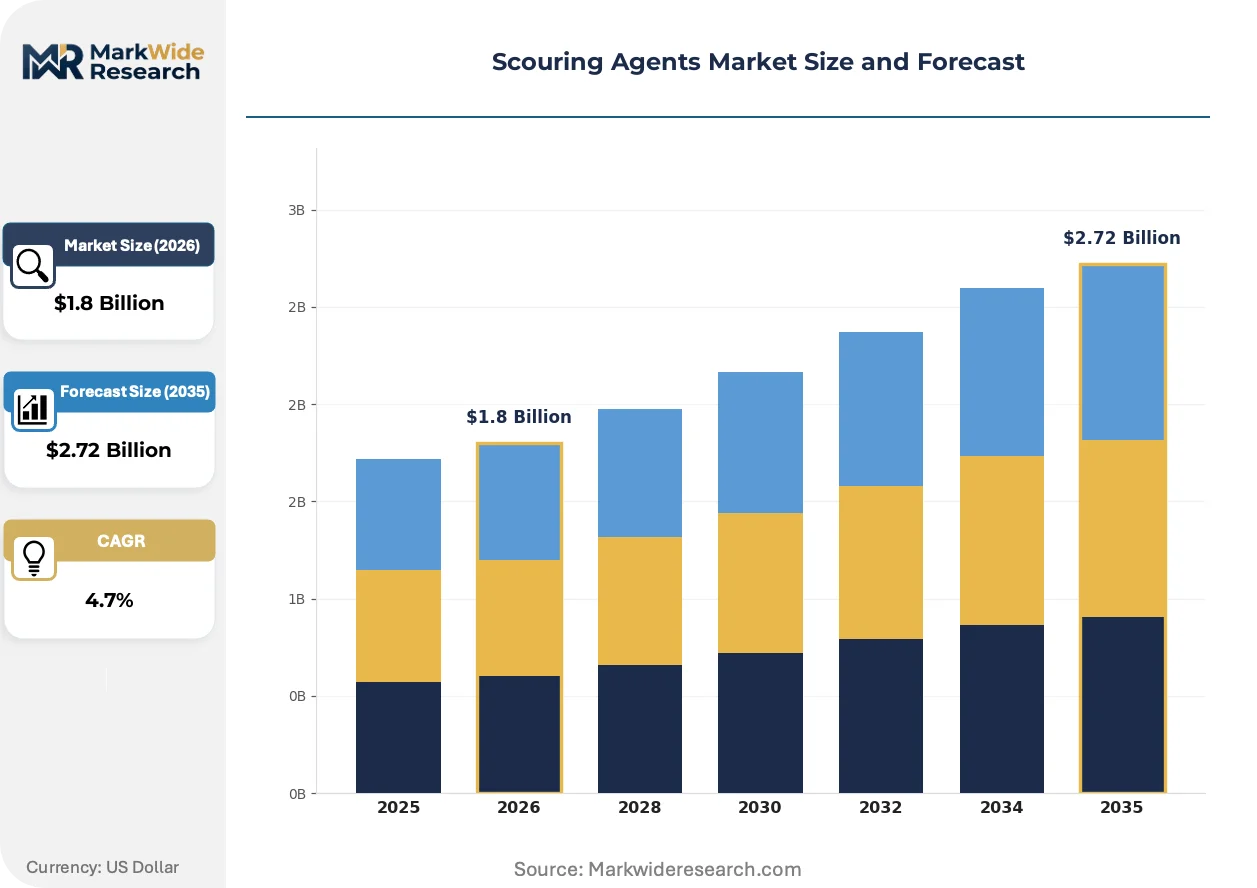
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline, Acidic, Neutral, Enzymatic End User: Textiles, Paper, Metal, Food Processing Application: Industrial Cleaning, Household Cleaning, Laundry, Oil Recovery Form: Liquid, Powder, Paste, Granules |
| Companies Covered | Viswaat Chemicals Limited, HT Fine Chemical Co., Ltd., Rung International, Indokemika Jayatama, Tata Chemicals, Sarex, DyStar Singapore Pte Ltd., BASF SE, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scouring Agents Market Strategic Shifts
Biocatalytic pretreatment platforms are converging with closed-loop water systems, compressing the traditional sequence of desizing, scouring, and bleaching into unified low-temperature processes that alter chemical procurement patterns.
Lipase-pectinase hybrid formulations are electrifying scouring performance on raw cotton by hydrolyzing natural waxes and pectins simultaneously at 50-60°C. Bangladeshi composite knit mills are retrofitting jet dyeing machines with enzymatic scouring modules to eliminate separate kier boiling. This convergence is electrifying demand for single-bath pretreatment chemicals that collapse process steps and reduce steam consumption by half.
China's MEE regulations on nonylphenol ethoxylate discharge are banning residual surfactant classes from Zhejiang and Jiangsu province effluent streams. Formulators are substituting alcohol ethoxylates and glucoside-based alternatives to maintain wetting performance. Guangdong province mills face the strictest COD limits, accelerating regional adoption of rapidly biodegradable scouring chemistries ahead of national enforcement timelines.
Textile chemical distributors in India are unbundling technical service from product supply, selling enzymatic scouring packages with on-site enzymatic activity assays and bath optimization consulting. Tiruppur and Surat cluster mills are contracting directly with enzyme producers for performance-based supply agreements tied to water and energy savings verification. This service integration is most advanced in South Indian processing hubs where effluent treatment costs dominate mill economics.
Scouring Agents Market Segmentation
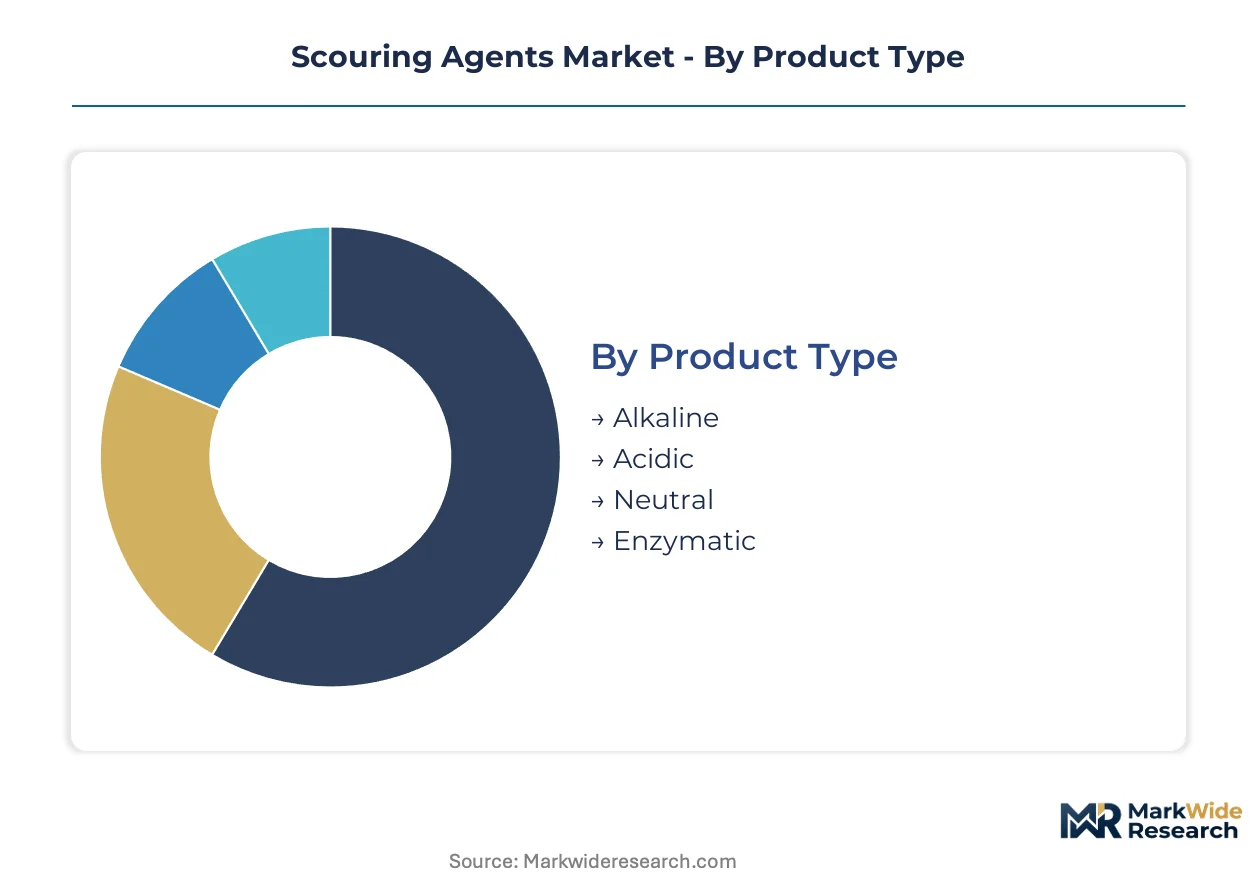
Segmentation in scouring agents reveals divergent margin structures between commodity alkaline formulations and premium enzymatic platforms. Procurement patterns split between cost-driven volume buyers in South Asian textile clusters and compliance-sensitive European mills seeking biodegradable chemistries.
Product Type:
Volume concentrates in alkaline systems while enzymatic platforms command expanding margin premiums across retrofitting textile mills.
- Alkaline:Sodium hydroxide-based formulations blended with surfactants and chelating agents dominate cotton pretreatment in Bangladesh and Vietnam due to raw material abundance and established kier infrastructure. Dhaka composite mills procure alkaline scouring in bulk for continuous woven processing despite rising effluent treatment costs.
- Enzymatic:Pectinase-lipase formulations operate at 50-60°C, cutting steam loads and water volumes. Tiruppur knit mills in India retrofit jet machines with enzymatic modules to eliminate separate boiling steps, driven by Tamil Nadu's strict COD discharge enforcement.
- Acidic:Sulfonic acid-based systems target mineral scale removal in metal finishing applications.
- Neutral:Mild surfactant blends serve delicate fiber processing where pH sensitivity constrains chemistry aggression.
Today's leader: Alkaline. Tomorrow's challenger: Enzymatic.
End User:
Application concentration varies sharply by substrate sensitivity and regulatory exposure across processing industries.
- Textiles:Cotton, wool, and synthetic fiber pretreatment consumes the majority of industrial scouring volume. Wet-processing capacity expansion in Vietnam's Binh Duong province and Bangladesh's Chittagong zone drives procurement of low-temperature enzymatic systems.
- Metal:Degreasing and surface preparation in automotive component manufacturing demands high-alkaline or solvent-based formulations.
- Paper:Pulp processing uses neutral surfactants for fiber cleaning without cellulose degradation.
- Food Processing:Equipment sanitation requires food-grade surfactant certifications under FSSAI in India and FDA in the United States.
Textiles anchor current procurement; metal processing offers adjacent expansion as automotive manufacturing reshoring accelerates.
Application:
Process integration trends favor multi-functional formulations that collapse discrete cleaning stages.
- Industrial Cleaning:Heavy-duty formulations remove petroleum-derived soils from manufacturing equipment. China's MEE wastewater incentives push Zhejiang province facilities toward biodegradable alternatives.
- Laundry:Consumer and commercial textile washing demands low-foam, cold-water surfactant systems.
- Household Cleaning:Hard surface and dishwashing applications favor concentrated liquid formats with fragrance compatibility.
- Oil Recovery:Surfactant flooding in enhanced petroleum extraction uses high-salinity tolerant formulations.
Industrial cleaning generates premium pricing power; laundry commands volume scale through distributor consolidation.
Form:
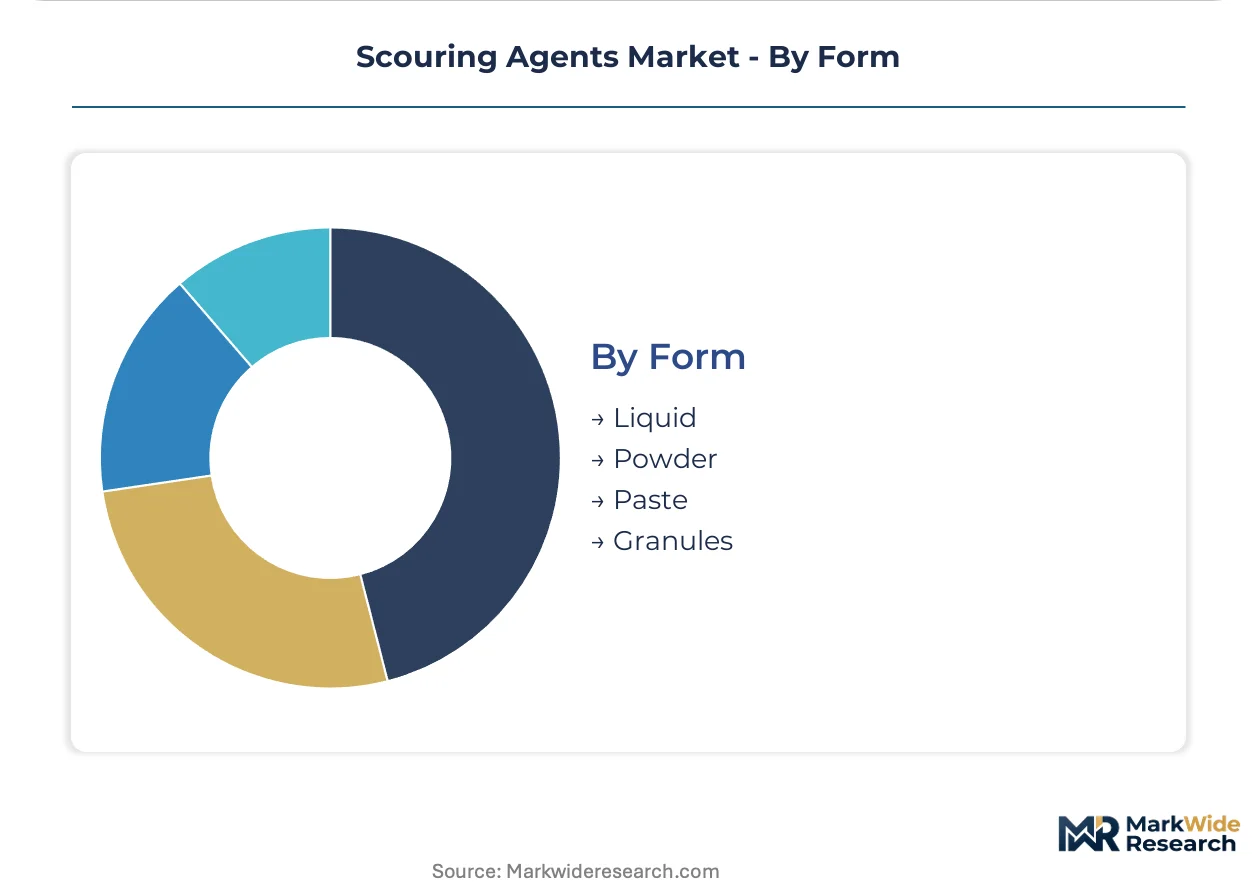
Physical state determines dosing automation compatibility and regional logistics economics.
- Liquid:Pumpable concentrates integrate with automated chemical injection systems in Turkish textile parks and European mills. Real-time enzymatic activity monitoring enables recipe optimization without manual handling.
- Powder:Dry blends retain cost advantage in batch-processing operations across Surat and Ludhiana textile clusters where capital investment in liquid dosing remains limited.
- Paste:High-viscosity formulations target manual application in small-scale metal workshops.
- Granules:Controlled-dissolution solids serve remote mining and oilfield operations with irregular supply chain access.
Liquid systems gain share fastest through automation adoption; powder persists where infrastructure investment lags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Textile chemical formulators cluster their technical service teams around wet-processing hubs in South Asia and Southeast Asia where mill density creates concentrated demand for enzymatic pretreatment solutions.
Bangladesh
Composite knit mills in Dhaka and Chittagong expand enzymatic scouring procurement as wet-processing capacity shifts from China. Bangladesh's Department of Environment enforces effluent discharge standards that favor biodegradable chemistries. Mills in Gazipur industrial zones retrofit jet dyeing machines with combined desizing-scouring modules to eliminate separate kier boiling.
Vietnam
Greenfield textile installations in Binh Duong and Ho Chi Minh City provinces specify enzymatic pretreatment circuits without legacy alkaline infrastructure. Vietnam's Ministry of Natural Resources and Environment tightens COD discharge limits for dyeing facilities. Foreign-owned mills in Dong Nai province contract directly with European enzyme suppliers for performance-based supply agreements.
India
Tiruppur and Surat cluster mills drive demand for liquid enzymatic concentrates compatible with automated dosing systems. Tamil Nadu Pollution Control Board enforces strict zero liquid discharge mandates on textile processors. Karnataka-based formulators unbundle technical service from product supply, selling scouring packages with on-site enzymatic activity assays.
China
Zhejiang and Jiangsu province mills face MEE regulations banning nonylphenol ethoxylate discharge from effluent streams. Guangdong facilities encounter the strictest COD limits, accelerating adoption of rapidly biodegradable alcohol ethoxylate alternatives. Shaoxing textile chemical distributors reformulate legacy surfactant portfolios to maintain wetting performance under tightened environmental enforcement.
Germany
Specialty chemical producers anchor biosurfactant R&D operations to serve REACH-compliant European textile mills. ECHA biodegradability thresholds disqualify alkylphenol ethoxylate formulations from import eligibility. North Rhine-Westphalia-based formulators leverage established channel relationships with premium apparel brands demanding ZDHC-certified pretreatment chemistries.
Scouring Agents Market Competitive Environment
Capital-heavy integrated chemical producers compete with asset-light specialty formulators for mill procurement contracts across Asian textile clusters. The supplier base fragments across regional channel controllers, global surfactant specialists, and enzyme technology licensors. Three archetypes dominate: multinational chemical conglomerates with broad surfactant portfolios, regional distributors with embedded technical service capabilities, and biotechnology-focused innovators with proprietary enzyme platforms. Competitive positioning hardens through backward integration into fatty alcohol feedstocks and forward integration into mill-side dosing automation.
Within the multinational tier, BASF SE and Evonik Industries AG exemplify divergent strategic postures toward biosurfactant development. DyStar Singapore Pte Ltd. occupies a position as regional channel anchor in Southeast Asian wet-processing hubs. Among India-centered suppliers, Tata Chemicals and Sarex represent scale-driven formulators with established mill relationships in Tiruppur and Surat clusters.
| Leading Market Players |
|---|
| Viswaat Chemicals Limited |
| HT Fine Chemical Co., Ltd. |
| Rung International |
| Indokemika Jayatama |
| Tata Chemicals |
| Sarex |
| DyStar Singapore Pte Ltd. |
| BASF SE |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Enzymatic scouring technology adoption simultaneously compresses production costs and concentrates supplier power among specialized biosurfactant formulators. This dual effect reshapes procurement economics as mills trade commodity alkaline chemistry for performance-contracted enzyme platforms.
Pricing Analysis
Three-tier pricing structure across premium enzymatic, standard alkaline, and economy bulk formulations dominates procurement contracts. Price differentiation rests on ZDHC certification tier and technical service bundling rather than base chemistry alone. Cost compression in standard alkaline tiers is intensifying because of palm kernel oil feedstock volatility and Bangladeshi mill consolidation. Composite knit manufacturers in Dhaka exhibit highest price sensitivity, while European premium apparel brands show lowest sensitivity due to compliance-driven specification lock-in.
Supply Chain Analysis
Regional distribution centers in Hamburg, Singapore, and Mumbai anchor hub-and-spoke patterns for liquid enzymatic concentrates. Manufacturing concentrates in Germany, China, and India, with biosurfactant R&D anchored in North Rhine-Westphalia and pectinase production clustered in Denmark. Raw material dependencies include fatty alcohol precursors from Malaysian plantations, glucose feedstocks for surfactant synthesis, and specialized enzyme cultures from Dutch fermentation facilities. Single-source vulnerability in industrial pectinase supply creates structural risk for Asian formulators. Distribution runs through technical service-embedded channel partners who co-locate with wet-processing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scouring agents market represents a late-cycle quality story as procurement shifts from cost-driven alkaline volume toward enzymatic platforms with verified water and energy savings. This transition favors suppliers with integrated biosurfactant capabilities and mill-side technical service infrastructure.
For Market Incumbents: To counter enzyme supply concentration risk, secure backward integration into fermentation capacity or captive pectinase sourcing through joint development with Danish biotech specialists. Simultaneously deepen channel control in Vietnam's Binh Duong province through co-located technical service teams that lock in greenfield mill specifications before alkaline infrastructure entrenches. For New Entrants and Emerging Players: Lipase-pectinase hybrid formulations offer a technology-first wedge into Tiruppur's retrofit market where Tamil Nadu Pollution Control Board enforcement creates urgent demand for COD-compliant chemistry. Target Surat's batch-processing cluster with powder-to-liquid conversion services that bypass capital constraints on automated dosing. Lead with performance-based contracting tied to verified water savings rather than per-kilogram product sales. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with embedded technical service capabilities but undifferentiated product portfolios. Long-term viability hinges on biosurfactant R&D intensity and ZDHC certification breadth as European compliance standards propagate to Asian supply chains. Watch for inflection when China's MEE extends nonylphenol ethoxylate bans beyond Zhejiang and Jiangsu to northern provinces, accelerating biodegradable chemistry substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Fermentation | Captive pectinase supply insulates formulators from Danish production bottlenecks and price volatility. |
| Green Manufacturing Transition | Alcohol ethoxylate substitution for nonylphenol ethoxylates ensures MEE compliance in Guangdong dyeing facilities. |
| Long-term Supply Agreement | Performance-based contracts with Tiruppur mills tie revenue to verified water and energy reduction metrics. |
| Joint Venture | European-Asian enzyme partnerships localize production and circumvent REACH-related import friction. |
| Capacity Expansion | Liquid concentrate production in Vietnam serves Binh Duong greenfield installations without legacy alkaline retrofit costs. |
Study Parameters
Direct dialogue with textile plant managers, chemical procurement leads at composite knit mills, distribution channel partners in Surat and Tiruppur clusters, and technical R&D directors at biosurfactant formulators grounded qualitative findings. Secondary validation drew from MEE wastewater discharge records, ECHA REACH substance registrations, ZDHC Manufacturing Restricted Substances List updates, and customs trade data for fatty alcohol imports. Bottom-up mill procurement surveys triangulated against top-down surfactant production capacity estimates.
Segment-level value outputs combined product type splits with end-use concentration across textile, metal, and paper processing applications. Modeled dimensions spanned alkaline versus enzymatic chemistry tiers, liquid versus powder form factors, and regional regulatory clusters distinguishing REACH-compliant from emerging economy enforcement gaps. CAGRs derived from elasticity-adjusted demand curves incorporating wet-processing capacity buildout in Bangladesh and Vietnam alongside enzyme substitution rates on cotton substrates.
The model holds under steady ECHA and MEE enforcement intensity; deviation in palm kernel oil supply disruptions or pandemic-scale logistics chokepoints would shift volume and value trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Tanning Agents Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
Carbon Tetrachloride Market
Chemicals
Ethanolamine Market
Chemicals
Valeronitrile Market
Chemicals
Europe Biguanide Market
Chemicals
Hydroxyethyl Methyl Cellulose Market
Chemicals
5 Dinitroaniline Market
Chemicals
P-Ethylphenol Market
Chemicals
China Inorganic Iodide Market
Chemicals
Iscotrizinol Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Sulfur Chemicals Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Malic Acid Market