
 North America Oxo-Alcohol Market | 2026-2036
North America Oxo-Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
North America Oxo-Alcohol Market Intelligence
Long-term supply contracts with embedded price-adjustment clauses are repositioning how oxo-alcohol value gets captured in North America. BASF SE leverages its integrated Ludwigshafen-derived process knowledge to sustain margin structures across US operations. Dow Chemical Company anchors its position through backward integration into Gulf Coast propylene supply, while ExxonMobil Chemical Company competes via refinery-integrated carbon monoxide feedstock access.
Oxo-alcohols are C4-C13 alcohols produced through hydroformylation of olefins with syngas, yielding products with precise carbon chain distributions critical for plasticizer and solvent applications. The hydroformylation reaction typically employs rhodium or cobalt catalysts at elevated pressure to achieve selectivity ratios above 10:1 for linear aldehyde formation. Butanol retains the largest volume share among product types, serving as the primary feedstock for butyl acrylate and glycol ether production. 2-Ethylhexanol commands premium positioning within the product mix due to its dominance in phthalate and non-phthalate plasticizer formulations for automotive and construction end users.
EPA regulations under the Clean Air Act shape volatile organic compound limits for coatings and adhesives applications, while OSHA enforces permissible exposure limits for worker handling of C4-C6 alcohol vapors in manufacturing settings. The US Chemical Safety Board investigation protocols influence process safety management standards at hydrogenation and distillation units. Stakeholders must monitor evolving state-level low-carbon fuel standards and potential federal carbon border adjustments that could alter feedstock cost structures for propylene-derived chemistries.
Market Dynamics
Long-term supply contracts with embedded price-adjustment clauses are repositioning how oxo-alcohol value gets captured across North America. Plasticizer manufacturers in the automotive sector are expanding purchases of 2-ethylhexanol as lightweighting requirements intensify.
Growth Catalysts
- EPA emissions rules:Tightening volatile organic compound limits for coatings and adhesives applications are pulling demand toward low-VOC solvent-grade oxo-alcohol formulations.
- Automotive lightweighting:Plasticizer manufacturers are expanding 2-ethylhexanol purchases to meet fuel efficiency mandates and reduce vehicle weight.
- Gulf Coast feedstock integration:Concentrated propylene supply access along the US Gulf Coast petrochemical corridor supports cost-competitive oxo-alcohol output.
Market Restraints
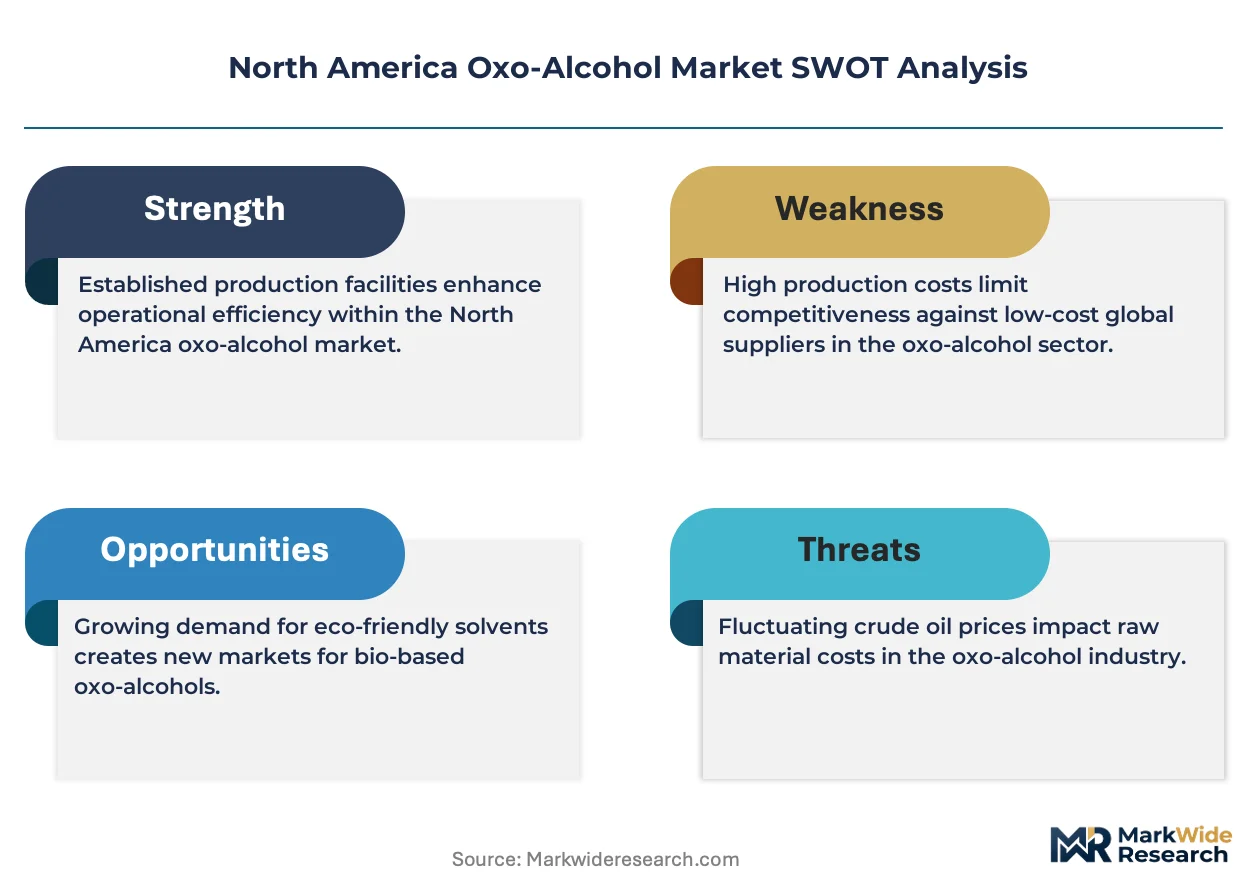
- Propylene feedstock volatility:Crude oil price swings and refinery operating rates directly compress margin structures for oxo-alcohol producers.
- OSHA workplace exposure limits:Tightening permissible exposure limits for C4-C6 alcohol vapors increase compliance costs and operational complexity.
- Bio-based plasticizer substitution:Epoxidized soybean oil and other renewable alternatives are capturing share in flexible PVC applications.
Strategic Opportunities
- Non-phthalate plasticizer expansion:Regulatory pressure on traditional phthalates creates white space for 2-ethylhexanol-based DOTP and DINCH formulations.
- Mexico manufacturing relocation:Automotive and construction supply chain migration to Mexico generates incremental oxo-alcohol demand for regional plasticizer production.
- Carbon border adjustment preparation:Early positioning for potential US federal carbon border mechanisms can secure preferential feedstock sourcing status.
Industry Challenges
- Process safety management complexity:US Chemical Safety Board investigation protocols demand rigorous hydrogenation and distillation unit upgrades.
- Specialized catalyst sourcing:Rhodium and cobalt catalyst supply concentration creates procurement vulnerability for hydroformylation operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Oxo-Alcohol Market |
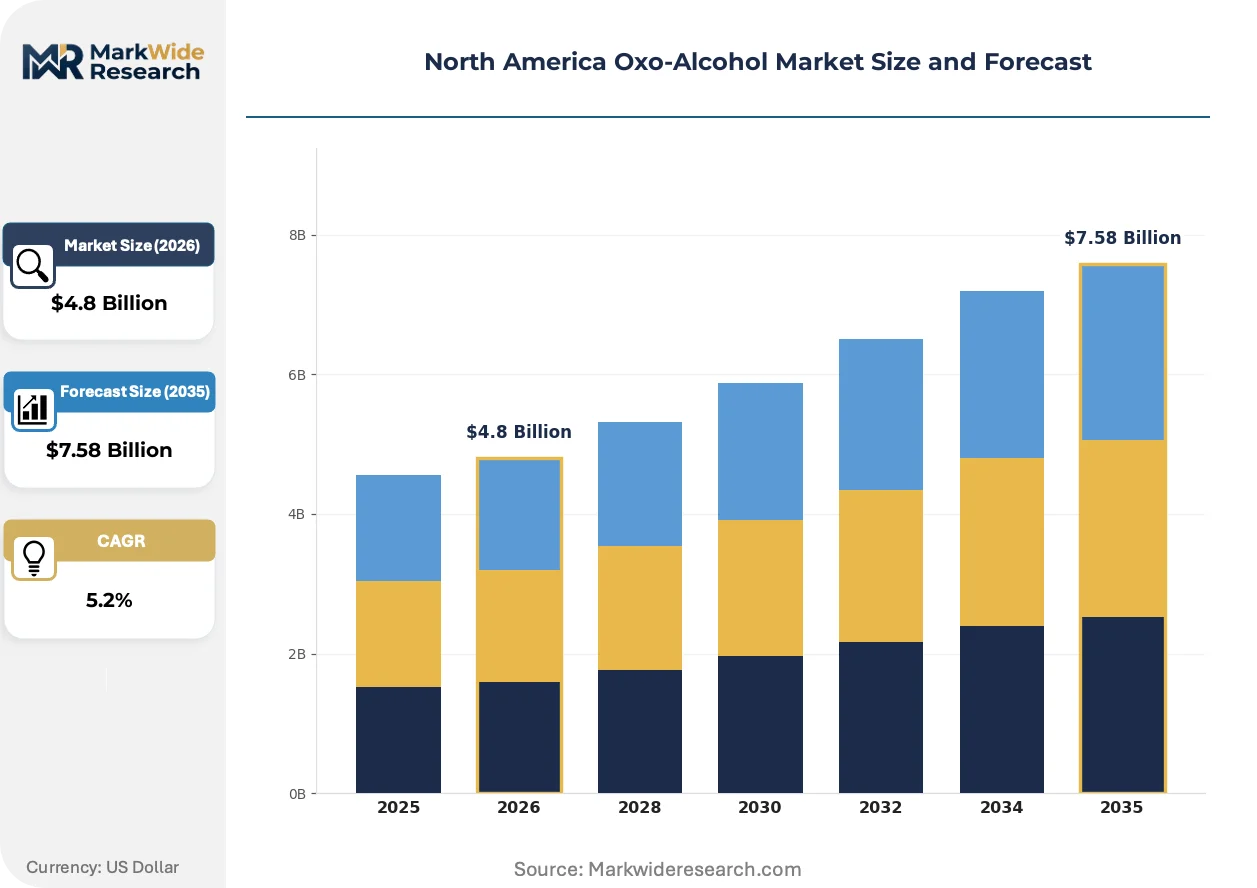
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butanol, 2-Ethylhexanol, Propanol, Glycol Ether Application: Plastics, Paints, Coatings, Adhesives End User: Automotive, Construction, Consumer Goods, Pharmaceuticals Technology: Hydrogenation, Oxidation, Distillation, Reaction |
| Companies Covered | Eastman Chemical Company, LG Chem, BASF SE, Arkema SA, INEOS, Dow Chemical Company, Evonik Industries, Huntsman Corporation, ExxonMobil Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Oxo-Alcohol Market Strategic Shifts & Innovations
Process intensification and catalyst efficiency improvements are actively reshaping competitive economics in oxo-alcohol production. Regulatory pressure on volatile organic compounds and plasticizer chemistries is accelerating formulation substitution cycles.
Rhodium-based low-pressure hydroformylation is overtaking traditional cobalt high-pressure processes in new capacity investments. Automotive plasticizer manufacturers are adopting rhodium-catalyzed 2-ethylhexanol for superior linear-to-branched selectivity ratios above 15:1. This technology compression is enabling single-train mega-plant economics that legacy cobalt installations cannot match.
EPA regulations under the Clean Air Act are tightening volatile organic compound limits for architectural coatings and industrial maintenance applications. Coatings formulators are responding by shifting from aromatic hydrocarbon solvents toward oxo-alcohol-based glycol ether alternatives. The architectural coatings segment across California and the Northeast is experiencing the fastest reformulation velocity due to state-level VOC regulations exceeding federal baselines.
Automotive OEMs are consolidating plasticizer procurement through direct long-term contracts with oxo-alcohol producers, bypassing traditional distributor channels. Tier-1 suppliers are losing intermediation value as OEMs seek supply security and formula co-development rights. This channel compression is most visible in Detroit-area automotive manufacturing clusters where Ford and General Motors have established direct supply relationships.
North America Oxo-Alcohol Market Segmentation
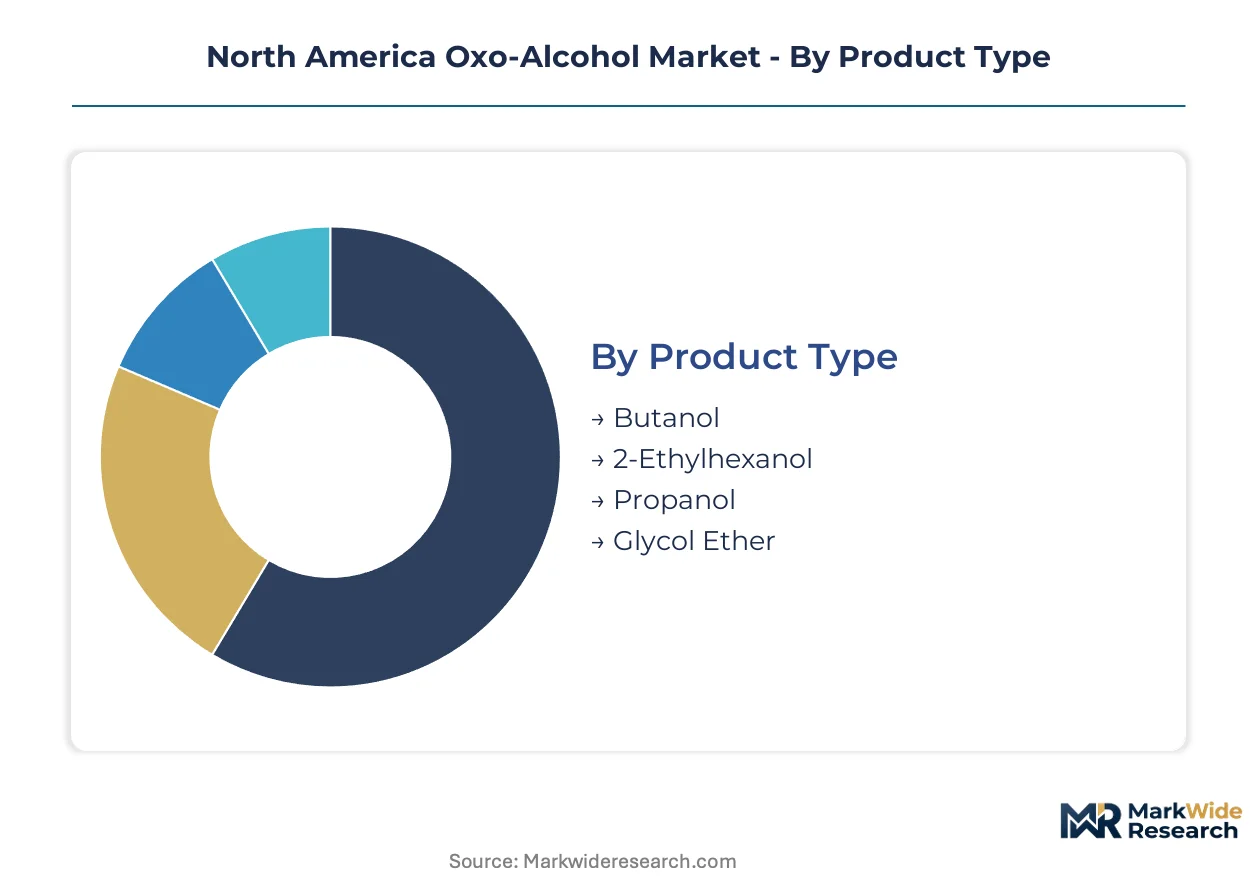
Oxo-alcohol producers configure product slate and process technology around distinct value capture opportunities across plasticizer, solvent, and chemical intermediate applications. Segmentation reveals where Gulf Coast feedstock integration translates into margin advantage versus specialty positioning.
Product Type:
Standardization dominates at commodity alcohol grades while specialty chain lengths command formulation premiums.
- Butanol:A four-carbon primary alcohol serving as the foundational feedstock for butyl acrylate esters and glycol ether synthesis. Demand concentrates in Texas and Louisiana coatings corridors where butyl acrylate producers anchor offtake agreements to Gulf Coast butanol supply.
- 2-Ethylhexanol:An eight-carbon branched alcohol produced through aldol condensation of butyraldehyde, commanding premium positioning in phthalate and non-phthalate plasticizer formulations. Automotive OEMs in Michigan and Ohio are expanding direct procurement of 2-ethylhexanol for flexible PVC interior applications as CAFE standards tighten.
- Propanol:A three-carbon alcohol employed in solvent and disinfectant formulations with narrower specification tolerances than butanol grades.
- Glycol Ether:Derivative alcohol-ether hybrids synthesized from oxo-alcohol precursors, serving waterborne coatings and semiconductor cleaning applications.
Leading the category by volume: Butanol. Growing fastest: 2-Ethylhexanol.
Application:
Application mix tracks directly with construction cycle timing and automotive production schedules.
- Plastics:The dominant consumption channel where oxo-alcohols convert to plasticizer esters for flexible PVC compounding. Construction spending in Florida and Texas is pulling 2-ethylhexanol into siding, flooring, and membrane applications faster than national averages.
- Paints:Architectural and industrial coatings employing butanol and glycol ethers as coalescing agents and viscosity modifiers. California South Coast Air Quality Management District regulations are accelerating reformulation toward low-VOC glycol ether systems.
- Coatings:Protective and functional surface treatments for automotive, marine, and industrial substrates.
- Adhesives:Pressure-sensitive and structural bonding formulations leveraging oxo-alcohol solvent properties.
Volume leadership sits with Plastics. Steepest expansion trajectory belongs to Paints under regulatory VOC compression.
End User:
End-user concentration reflects regional industrial base composition and import substitution patterns.
- Automotive:OEM and Tier-1 demand for interior and underhood flexible PVC components. Mexico manufacturing relocation is generating incremental oxo-alcohol demand for regional plasticizer production serving Detroit supply chains.
- Construction:Residential and commercial building materials including siding, roofing, flooring, and sealants. Sun Belt construction activity in Arizona and Nevada is outpacing national demand growth for plasticizer-intensive applications.
- Consumer Goods:Packaging, personal care, and household product formulations.
- Pharmaceuticals:High-purity solvent applications for active pharmaceutical ingredient synthesis.
Automotive anchors volume share. Construction exhibits the fastest climb amid housing supply expansion.
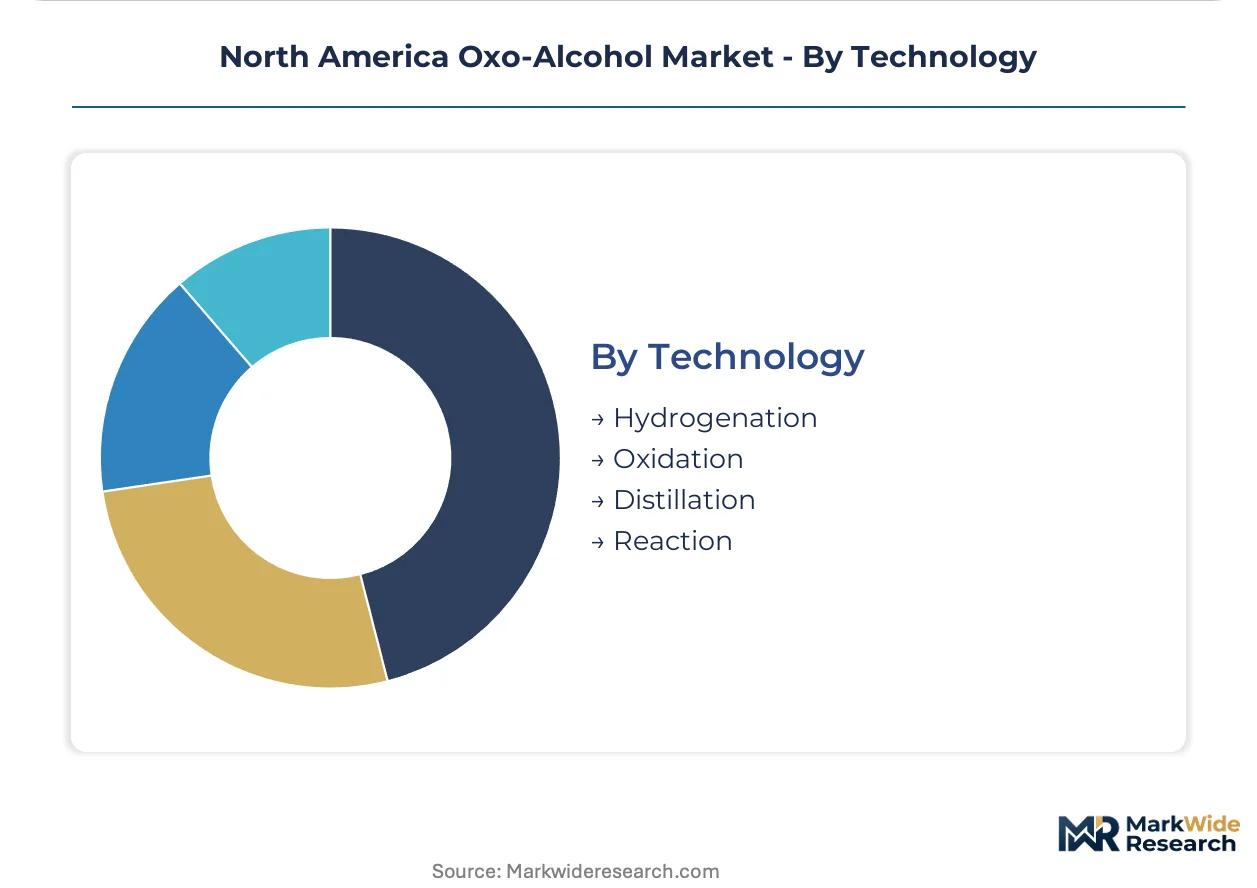
Technology:
Technology selection determines capital intensity, catalyst exposure, and product slate flexibility.
- Hydrogenation:Catalytic reduction of aldehyde intermediates to alcohol products, typically employing nickel or copper chromite catalysts at elevated pressure. US Gulf Coast producers are upgrading hydrogenation train efficiency to capture margin from propylene cost volatility.
- Oxidation:Alternative alcohol production pathways and aldehyde intermediate processing. Specialized oxidation units at Texas complex refineries are integrating with refinery offgas streams for carbon monoxide feedstock security.
- Distillation:Separation and purification stages achieving polymer-grade and solvent-grade specification tiers.
- Reaction:Aldol condensation and other carbon-carbon bond forming steps enabling chain length extension.
Hydrogenation operations lead by installed capacity. Oxidation integration is gaining share fastest among refinery-anchored producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates along the US Gulf Coast petrochemical corridor while consumption disperses across automotive clusters in the Midwest and construction markets in the Sun Belt. Canada maintains specialty chemical refining positions. Mexico captures manufacturing relocation demand.
United States
Automotive OEMs in Michigan and Ohio are expanding direct procurement of 2-ethylhexanol for flexible PVC interior applications as CAFE standards tighten. EPA regulations under the Clean Air Act are accelerating reformulation toward low-VOC glycol ether systems in architectural coatings. The Texas-Louisiana Gulf Coast anchors integrated propylene-to-oxo-alcohol production with backward integration into refinery carbon monoxide streams.
Canada
Specialty solvent demand from pharmaceutical and electronics manufacturing in Ontario and Quebec supports butanol and propanol offtake. Health Canada and PMRA oversight of chemical workplace exposure aligns with tightening North American standards. Alberta's petrochemical complex development is evaluating oxo-alcohol integration opportunities with regional propylene supply.
Mexico
Automotive and construction supply chain migration is generating incremental oxo-alcohol demand for regional plasticizer production serving Detroit supply chains. Mexican environmental regulations under SEMARNAT are converging with US EPA frameworks for VOC emissions in coatings. Nuevo León and the Bajío Region are attracting plasticizer compounding investments that pull oxo-alcohol imports from US Gulf Coast producers.
California
The South Coast Air Quality Management District enforces VOC limits exceeding federal EPA baselines, forcing the fastest coatings reformulation velocity in North America. Construction spending in Los Angeles and San Diego metro areas is pulling 2-ethylhexanol into siding, flooring, and membrane applications. Silicon Valley semiconductor cleaning applications sustain demand for high-purity glycol ether derivatives.
Texas
Integrated refinery-petrochemical complexes in Houston and Beaumont-Port Arthur leverage captive propylene and syngas feedstock access for cost-competitive oxo-alcohol output. OSHA enforcement of permissible exposure limits for C4-C6 alcohol vapors drives hydrogenation unit upgrades. The Texas-Louisiana border region concentrates North American hydroformylation capacity with rhodium-catalyzed process technology.
North America Oxo-Alcohol Market Key Industry Players
Capital-heavy producers with integrated Gulf Coast feedstock positions compete with asset-light formulators and distributors serving regional specialty applications. The market structure reflects a consolidated upstream oligopoly supplying a fragmented downstream conversion tier. Three archetypes dominate: integrated petrochemical majors with captive olefin supply, specialty chemical houses with formulation expertise, and regional distributors with logistics-advantaged positions. Capacity expansion and direct OEM procurement relationships represent the dominant competitive vectors reshaping value capture.
Among integrated petrochemical majors, BASF SE, Dow Chemical Company, and ExxonMobil Chemical Company exemplify the feedstock-integrated archetype. BASF SE represents European process technology transfer to North American operations. Dow Chemical Company anchors its position through Gulf Coast propylene supply integration. ExxonMobil Chemical Company occupies a position leveraging refinery-derived carbon monoxide feedstock access. These three companies sit within the tier that captures margin through backward integration rather than formulation differentiation.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| LG Chem |
| BASF SE |
| Arkema SA |
| INEOS |
| Dow Chemical Company |
| Evonik Industries |
| Huntsman Corporation |
| ExxonMobil Chemical Company |
| Others |
Cost & Logistics Intelligence
Commodity-standard-solvent grade divergence separates polymer-specification 2-ethylhexanol from technical-grade butanol in both contract structures and logistics configurations. Gulf Coast producers capture margin through captive propylene access while specialty distributors in Ontario and Quebec command premiums for pharmaceutical-grade propanol.
Pricing Analysis
Margin tightening in commodity butanol reflects propylene feedstock volatility and refinery operating rate swings. Long-term offtake agreements with quarterly price-adjustment clauses dominate volume transactions, separating spot-exposed distributors from integrated producers. Price differentiation hinges on chain-length specificity and OSHA compliance certification tier. Automotive OEM procurement teams exhibit lowest price sensitivity due to formula co-development requirements, while construction distributors face acute cost-down pressure.
Supply Chain Analysis
Return logistics for spent rhodium catalyst recovery flow through specialized refiners in Texas and Louisiana, closing the loop on hydroformylation operations. Production concentrates in the United States, Canada, and Mexico. Feedstock draws from Gulf Coast refinery propylene streams, Alberta natural gas liquids, and PEMEX petrochemical output. Single-source vulnerability sits with concentrated rhodium and cobalt catalyst supply. Distribution runs through tank-car rail networks and barge systems serving Midwest automotive clusters and California coatings corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock integration economics are forcing merchant producers without Gulf Coast propylene access toward exit or acquisition, consolidating value capture among backward-integrated majors.
For Market Incumbents: Deploy hydrogenation train efficiency upgrades to offset OSHA compliance cost inflation. Lock automotive OEMs into direct long-term supply agreements with embedded price-adjustment mechanisms. Capture margin from bio-based plasticizer substitution threats by accelerating non-phthalate DOTP and DINCH formulation partnerships. For New Entrants and Emerging Players: Enter via specialty solvent distribution in Ontario and Quebec pharmaceutical corridors where incumbent presence thins. Target Mexico's Nuevo León and Bajío Region plasticizer compounding investments pulling US Gulf Coast supply. Pursue toll-manufacturing arrangements with stranded propylene assets in Alberta. For Investors and Strategic Acquirers: Exit pathways concentrate in trade-sale to integrated petrochemical majors seeking Gulf Coast capacity expansion. Five-to-ten-year viability favors producers with captive carbon monoxide or propylene supply. Watch SEMARNAT environmental convergence with EPA frameworks as signal for Mexican demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Captive feedstock access insulates margin from crude oil volatility at Texas-Louisiana complexes. |
| Rhodium Catalyst Recovery Partnership | Closed-loop refining agreements reduce procurement exposure to South African supply concentration. |
| Non-Phthalate Plasticizer Capacity Expansion | DOTP and DINCH output captures regulatory pressure on traditional phthalate formulations. |
| Direct OEM Supply Agreement | Bypassing distributor channels secures volume commitments from Ford and General Motors procurement. |
| Low-VOC Glycol Ether Formulation Development | California SCAQMD compliance opens architectural coatings revenue in Los Angeles and San Diego metros. |
Research Approach
Document review covered SEC 10-K filings, American Chemistry Council production surveys, and EPA enforcement databases, complemented by interviews with plant managers at Gulf Coast hydroformylation facilities, procurement leads at Detroit-area automotive OEMs, and distribution channel partners serving California coatings formulators. Secondary validation drew from customs trade data, OSHA incident reports, and state-level air quality regulatory filings. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Historical capacity utilization patterns were cross-referenced against panel input from technical R&D directors and hydrogenation unit operators. Segmentation modeling spanned product type, application end-use, technology configuration, and regional production hub across the projection horizon. CAGRs were derived from demand elasticity analysis against construction spending and automotive production schedules. Forecast inputs incorporated propylene spread volatility and rhodium price trajectory assumptions.
Revisions become necessary when EPA VOC rulemakings accelerate, OSHA exposure limits tighten, or carbon border adjustment mechanisms materialize. Forecasts reflect documented assumptions on feedstock cost structures and catalyst availability. Practitioners should monitor SEMARNAT regulatory convergence and bio-based plasticizer penetration rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Aluminum Phosphide Market
Chemicals
Barbituric Acid Market
Chemicals
Para Cresol Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
Isoamyl Acetate Market
Chemicals
Diphosphate Market
Chemicals
Spirodiclofen Market
Chemicals
Cetyl Stearyl Alcohol Market
Chemicals
Global Electronic Grade Phosphoric Acid Market
Chemicals
Di Nitro Toluene Market
Chemicals
Myclobutanil Market
Chemicals
SLS and LABSA Market
Chemicals
Valeryl Chloride Market
Chemicals
Calcium Borate Market
Chemicals
Hexachloroethane Market