
 Hydrazine Hydrate Market | 2026-2036
Hydrazine Hydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrazine Hydrate Market Analysis
Pharmaceutical-grade hydrazine hydrate is reorganizing competitive dynamics as end users demand sub-ppm impurity profiles for satellite propulsion and active pharmaceutical ingredient synthesis. Arkema leverages backward integration into nitrile precursors to secure feedstock continuity across European polymerization markets. Lonza Group anchors its position through specialized batch production for life-science applications, while Yibin Tianyuan Group dominates bulk technical-grade supply to Asian agrochemical channels.
Hydrazine hydrate is an aqueous solution of hydrazine (N₂H₄·H₂O) typically manufactured through the Raschig process or urea-based oxidation, with concentrations ranging from 35% to 100% by weight; it functions primarily as a powerful reducing agent, blowing agent precursor, and high-energy propellant component. Industrial-grade formulations currently occupy the largest volume share, though pharmaceutical-grade segments command superior margin pools due to certification complexity and limited qualified supply. Aerospace applications lead value generation, while chemical synthesis channels sustain the broadest downstream diversification across specialty intermediates.
EPA regulations in the United States classify hydrazine as a hazardous air pollutant, mandating stringent workplace exposure limits and emission controls that elevate compliance costs for domestic manufacturers. REACH registration requirements in Europe and China's GB standards under SAMR oversight similarly constrain market entry for unqualified producers. Stakeholders must monitor evolving dual-use export controls and green chemistry mandates that could redirect investment toward closed-loop manufacturing and alternative synthesis pathways.
Market Dynamics
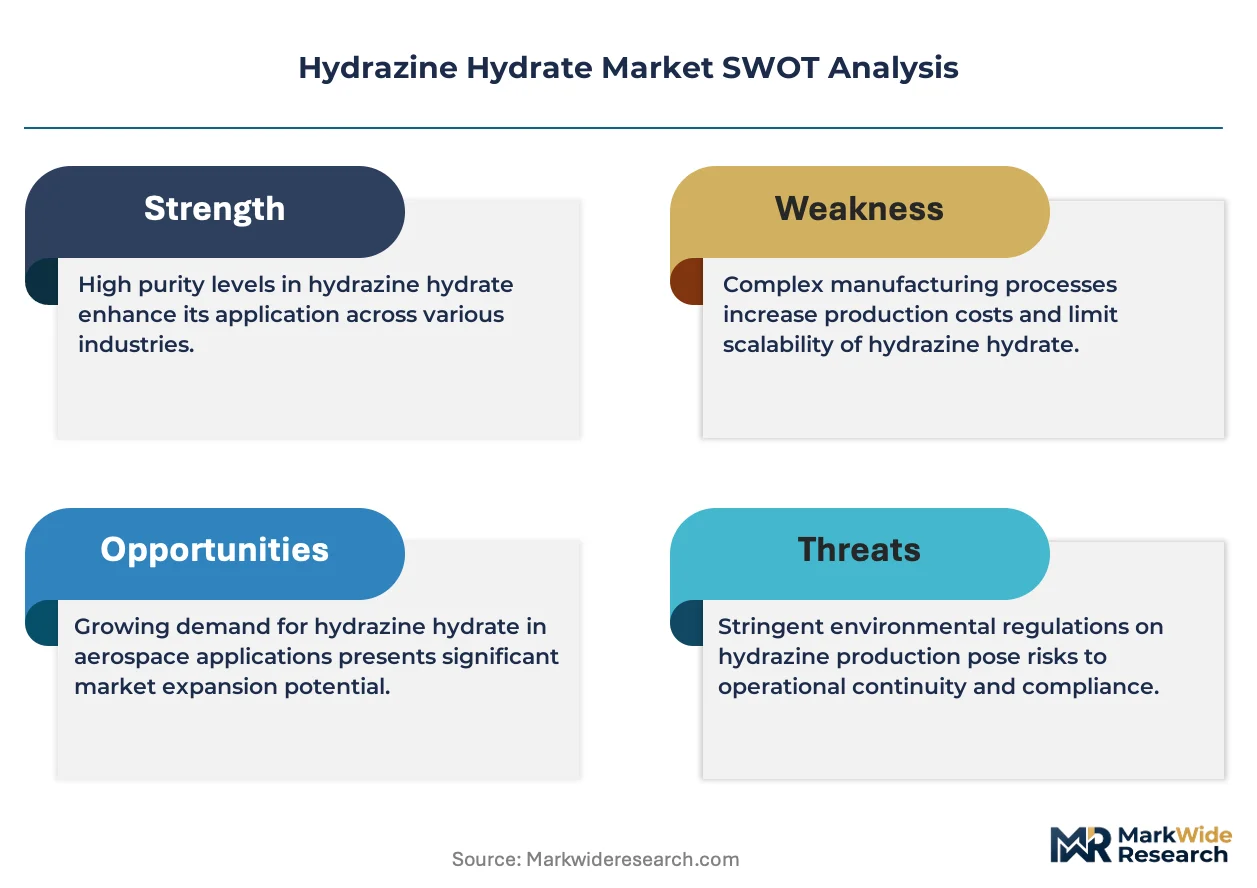
Pharmaceutical-grade purity specifications are compressing technical-grade margins as aerospace propellant formulators and API manufacturers demand sub-ppm impurity profiles certified under REACH and EPA frameworks.
Growth Catalysts
- REACH Purity Benchmarks:European polymerization initiator manufacturers are upgrading to pharmaceutical-grade hydrazine hydrate to secure export access, pulling capacity away from technical-grade markets.
- Aerospace Propulsion:Satellite constellation deployments are consuming high-concentration hydrazine hydrate for monopropellant thrusters, with procurement concentrated among German and Chinese launch vehicle integrators.
- India:The country's agrochemical intermediate sector is expanding Raschig-process capacity under BIS quality mandates to serve domestic crop protection formulation.
Market Restraints
- Feedstock Volatility:Ammonia and sodium hypochlorite price swings directly transmit to hydrazine hydrate production economics, squeezing batch producers without captive nitrile supply.
- Supply Concentration:Technical-grade volume clusters among Chinese state-affiliated chemical complexes, creating single-source vulnerability for Asian agrochemical channels.
- Substitution Pressure:Carbohydrazide and diethylhydroxylamine are displacing hydrazine hydrate in boiler water treatment applications at industrial facilities facing EPA workplace exposure audits.
Strategic Opportunities
- Saudi Arabia:The kingdom's specialty chemical import substitution initiative under Vision 2030 is creating demand for localized pharmaceutical-grade production to serve regional pharmaceutical manufacturing.
- Closed-Loop Synthesis:Urea-based oxidation processes with ammonia recovery systems are opening capital-efficient entry paths for producers targeting EU Green Deal compliance.
- Dual-Use Export Controls:Missile Technology Control Regime licensing requirements for high-concentration grades are creating margin pools for qualified suppliers serving NATO aerospace programs.
Industry Challenges
- Analytical Chemist Scarcity:ICP-MS and GC-MS operators capable of validating sub-ppm impurity profiles command premium wages, constraining batch release velocity at pharmaceutical-grade facilities.
- REACH Registration Timelines:Full substance dossier completion for hydrazine hydrate under ECHA extended deadlines requires 18-24 month toxicology studies, freezing new European market entry.
- Legacy Infrastructure Integration:Raschig-process plants retrofitted for pharmaceutical-grade output face contamination risks from historical technical-grade production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrazine Hydrate Market |
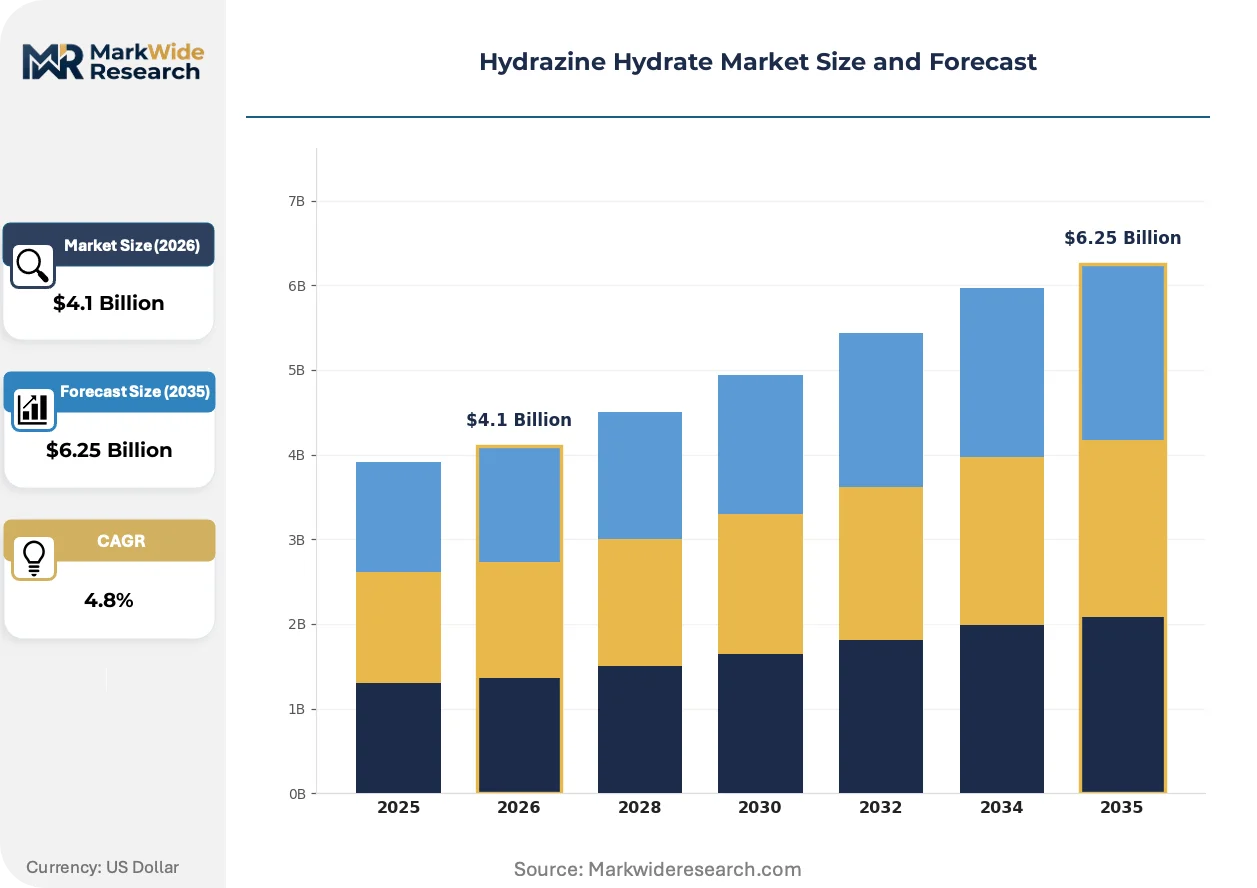
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.25 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Industrial Grade, Pharmaceutical Grade, Pure Grade Application: Aerospace, Agriculture, Chemical Synthesis, Pharmaceuticals End User: Aerospace Companies, Agricultural Firms, Chemical Manufacturers, Research Laboratories Delivery Mode: Liquid Supply, Solid Supply, Bulk Transport, Packaged Supply |
| Companies Covered | Arkema, LANXESS, Lonza Group, Otsuka Chemical, Nippon Carbide Industries, Huntsman Corporation, Olin Corporation, Yibin Tianyuan Group, Japan Finechem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrazine Hydrate Market Emerging Trajectories
Process intensification and analytical capability upgrades are splitting the competitive field between mass-market technical-grade suppliers and certified pharmaceutical-grade specialists serving regulated end-uses.
Membrane electrolysis for hydrazine synthesis is bifurcating the technology landscape away from conventional Raschig and urea oxidation routes. German specialty chemical producers are piloting solid-state electrolyzer stacks to eliminate sodium chloride byproduct streams. This approach is compressing waste treatment capital requirements while enabling modular capacity scaling for regional pharmaceutical clusters.
EPA's updated National Emission Standards for Hazardous Air Pollutants for hydrazine production sources are mandating continuous emissions monitoring systems at US manufacturing sites. The rule tightens fugitive emission thresholds and requires quarterly stack testing, elevating compliance overhead for domestic producers. Aerospace propellant blenders are responding by qualifying European and Asian pharmaceutical-grade imports to displace domestically sourced material.
Specification-driven supplier consolidation is concentrating procurement decisions among technical service teams rather than commodity purchasing departments. Boiler water treatment chemical distributors are ceding ground to direct mill relationships with certified producers offering on-site analytical support. This pattern is most pronounced in German and Japanese power generation sectors where plant insurance underwriters mandate certified supply chain documentation.
Hydrazine Hydrate Market Segmentation
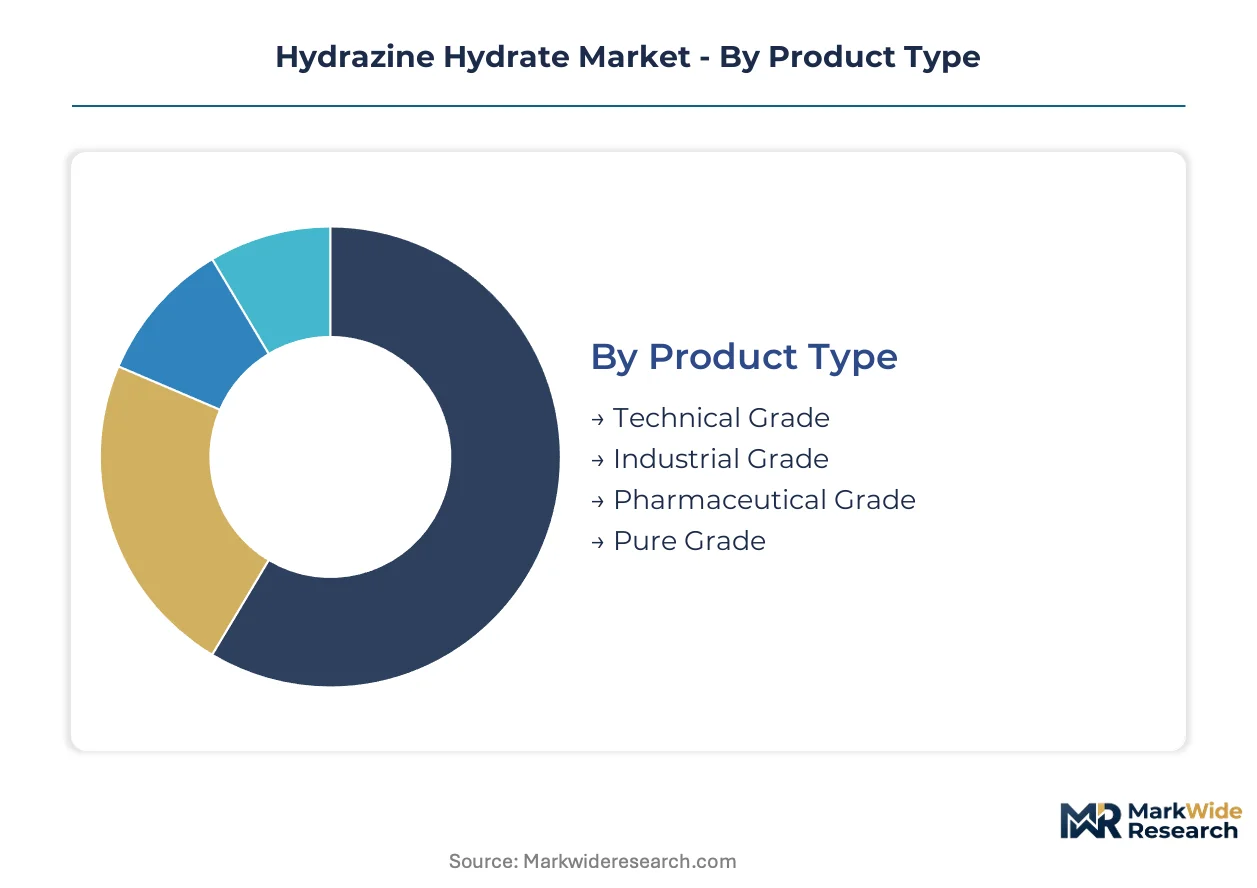
Hydrazine hydrate procurement patterns diverge sharply across purity grades and delivery modes, with aerospace propellant formulators and pharmaceutical manufacturers driving specification bifurcation. End-user certification requirements and regional regulatory frameworks reshape competitive positioning within each segment category.
Product Type:
Substitution pressure from carbohydrazide and diethylhydroxylamine hits technical-grade formulations hardest, while pharmaceutical-grade specifications create defensive moats against displacement.
- Technical Grade:Concentrations of 35-55% hydrazine hydrate serve boiler water treatment and agrochemical intermediate channels. Indian crop protection formulators under BIS mandates absorb the largest technical-grade volumes, though EPA workplace exposure audits accelerate substitution in US industrial facilities.
- Pharmaceutical Grade:Sub-ppm impurity profiles certified under REACH and EPA frameworks command premium positioning. Satellite constellation deployers in Germany and China concentrate procurement for monopropellant thrusters, with supply qualified under Missile Technology Control Regime licensing.
- Industrial Grade:Intermediate purity tiers bridge polymerization initiator and specialty intermediate applications. European manufacturers upgrade capacity to meet export access requirements.
- Pure Grade:Near-anhydrous formulations above 98% concentration serve niche research and calibration standards. Limited qualified supply constrains batch release velocity.
Technical Grade retains volume leadership; Pharmaceutical Grade holds the steepest expansion curve.
Application:
Cost tier stratification separates aerospace propulsion systems from commodity chemical synthesis channels, with certification overhead driving 3-4x pricing spreads between tiers.
- Aerospace:High-concentration hydrazine hydrate powers monopropellant thrusters for satellite attitude control and orbital insertion. German launch vehicle integrators anchor procurement alongside Chinese state aerospace programs.
- Pharmaceuticals:API synthesis and intermediate production demand validated impurity profiles under FDA and EMA oversight. Lonza Group anchors specialized batch production for life-science applications.
- Agriculture:Crop protection formulation consumes technical-grade volumes for pesticide and herbicide precursors. Indian Raschig-process expansion targets domestic substitution.
- Chemical Synthesis:Polymerization initiators, blowing agents, and specialty intermediates sustain broad downstream diversification. REACH registration timelines freeze new European market entry.
Aerospace captures value concentration; Pharmaceuticals climbs the fastest.
End User:
Customer type fragmentation concentrates procurement authority among technical service teams at aerospace companies, while agricultural firms delegate purchasing to commodity distributors.
- Aerospace Companies:Direct mill relationships with certified producers dominate procurement, with on-site analytical support mandated by plant insurance underwriters in German and Japanese power generation sectors.
- Chemical Manufacturers:Polymerization initiator producers upgrade to pharmaceutical-grade specifications to secure European export access under REACH purity benchmarks.
- Agricultural Firms:Domestic crop protection formulators in India expand Raschig-process capacity under BIS quality mandates.
- Research Laboratories:Niche calibration and analytical standard applications require limited pure-grade volumes with extended qualification timelines.
Aerospace Companies direct premium procurement; Chemical Manufacturers gain share fastest.
Delivery Mode:
Supply concentration geography dictates logistics configuration, with Chinese state-affiliated chemical complexes dominating bulk technical-grade flows while pharmaceutical-grade moves through specialized packaged channels.
- Bulk Transport:Rail and tanker movements of technical-grade material serve Indian agrochemical clusters and European polymerization hubs. Single-source vulnerability concentrates in Chinese state-affiliated production complexes.
- Packaged Supply:Drummed pharmaceutical-grade shipments with chain-of-custody documentation serve aerospace propellant blenders and API manufacturers. EPA NESHAP compliance costs elevate import preference for European and Asian certified material.
- Liquid Supply:Pipeline and dedicated tanker arrangements anchor integrated chemical manufacturing sites with captive consumption.
- Solid Supply:Hydrazine salt and derivative forms enable stabilized handling for remote research and specialty applications.
Bulk Transport retains volume leadership; Packaged Supply holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese state-affiliated chemical complexes dominate technical-grade hydrazine hydrate volume, while German and Indian specialty producers anchor pharmaceutical-grade certification capacity. Regulatory divergence across EPA, REACH, and BIS frameworks fragments procurement patterns. Aerospace propellant blenders in Germany and satellite manufacturers in China concentrate demand for high-concentration grades.
China
Satellite constellation deployments and monopropellant thruster programs drive pharmaceutical-grade consumption. GB standards under SAMR oversight tighten purity benchmarks for export-qualified material. Yibin Tianyuan Group and state-affiliated complexes in Sichuan-Chongqing anchor bulk technical-grade supply to Asian agrochemical channels.
Germany
Launch vehicle integrators and polymerization initiator manufacturers anchor European pharmaceutical-grade procurement. REACH registration requirements under ECHA extended deadlines constrain new market entry. Specialty chemical producers in North Rhine-Westphalia pilot membrane electrolysis to eliminate sodium chloride byproduct streams.
India
Domestic crop protection formulators expand Raschig-process capacity to serve pesticide and herbicide precursor demand. BIS quality mandates govern technical-grade specifications for agricultural intermediate channels. Maharashtra and Gujarat chemical clusters absorb the largest technical-grade volumes under import substitution programs.
United States
EPA National Emission Standards for Hazardous Air Pollutants elevate compliance costs for domestic Raschig-process manufacturers. Aerospace propellant blenders qualify European and Asian pharmaceutical-grade imports to displace domestically sourced material. Texas and Louisiana chemical corridors face continuous emissions monitoring system mandates.
Japan
Power generation sector procurement concentrates among certified producers offering on-site analytical support. METI oversight and JIS standards govern boiler water treatment chemical specifications. Kanto and Kansai industrial clusters demand chain-of-custody documentation for pharmaceutical-grade supply.
Hydrazine Hydrate Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the hydrazine hydrate competitive field. European and Japanese specialty chemical houses anchor pharmaceutical-grade certification capacity through analytical capability investments, while Chinese state-affiliated complexes dominate technical-grade volume through feedstock integration. Three archetypes define competitive positioning: backward-integrated nitrile producers, specialized batch manufacturers for life-science applications, and bulk technical-grade suppliers serving agrochemical channels. Capacity expansion and REACH registration completion represent the dominant competitive moves as qualification timelines freeze new European entry.
Among European specialty chemical houses, Arkema and Lonza Group exemplify divergent strategic positioning within pharmaceutical-grade tiers. Arkema leverages captive nitrile precursor supply to secure feedstock continuity across polymerization markets, while Lonza Group anchors specialized batch production architecture for API synthesis and intermediate applications. Japanese specialists Otsuka Chemical and Nippon Carbide Industries occupy positions between bulk commodity and certified pharmaceutical supply, reflecting intermediate purity tier concentration. Huntsman Corporation and Olin Corporation represent North American integrated chemical manufacturers navigating EPA compliance cost pressures through import qualification strategies. Yibin Tianyuan Group exemplifies Chinese state-affiliated technical-grade dominance through volume scale and domestic agrochemical channel capture.
| Leading Market Players |
|---|
| Arkema |
| LANXESS |
| Lonza Group |
| Otsuka Chemical |
| Nippon Carbide Industries |
| Huntsman Corporation |
| Olin Corporation |
| Yibin Tianyuan Group |
| Japan Finechem |
| Others |
Supply Flow & Price Mechanics
Chinese state-affiliated chemical complexes leverage 80-90 percent capacity utilization across Sichuan-Chongqing production hubs to compress unit economics for technical-grade material, simultaneously anchoring price floors for pharmaceutical-grade tiers through feedstock integration advantages that smaller batch producers cannot replicate.
Pricing Analysis
REACH registration requirements under ECHA extended deadlines dictate the pricing tier structure across European supply, creating three-tier pricing stratification across pharmaceutical-grade, industrial-grade, and technical-grade levels. Price differentiation rests on certification complexity and analytical validation overhead, with sub-ppm impurity profiling commanding 3-4x spreads over commodity technical-grade. Pricing pressure stems from carbohydrazide and diethylhydroxylamine substitution in boiler water treatment channels. Agricultural firms in India exhibit highest price sensitivity through commodity distributor procurement, while aerospace propellant blenders demonstrate lowest sensitivity due to MTCR licensing qualification requirements.
Supply Chain Analysis
Extended qualification timelines for pharmaceutical-grade certification stretch inventory cycles to 18-24 months for new market entrants. Geographic supply concentration centers on China, Germany, and India, with Chinese state-affiliated complexes dominating bulk technical-grade volume. Raw material dependencies draw from ammonia, sodium hypochlorite, and nitrile precursor streams. Single-source vulnerability concentrates in Sichuan-Chongqing production clusters serving Asian agrochemical channels. Distribution runs through direct mill relationships for aerospace and pharmaceutical end-users, while technical-grade flows through commodity chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward aerospace propellant blenders and pharmaceutical manufacturers as procurement authority consolidates among technical service teams with analytical validation capabilities, displacing traditional commodity purchasing departments.
For Market Incumbents: Shield pharmaceutical-grade margin pools by accelerating REACH dossier completion before extended deadlines freeze new European entry, while retrofitting Raschig-process infrastructure to eliminate cross-contamination risks from historical technical-grade runs. Prioritize captive nitrile supply integration to neutralize ammonia and sodium hypochlorite feedstock volatility that squeezes batch producers without upstream control. For New Entrants and Emerging Players: On-site analytical support gaps in Saudi Arabia's specialty chemical import substitution initiative open white-space for localized pharmaceutical-grade production serving regional pharmaceutical manufacturing under Vision 2030. Target membrane electrolysis pilot programs in North Rhine-Westphalia for technology licensing entry. Pursue joint venture structures with German specialty chemical houses to bypass 18-24 month toxicology study requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated nitrile producers with REACH-registered pharmaceutical-grade capacity over pure-play technical-grade volume players facing substitution headwinds. Long-term viability across the 5-10 year window hinges on analytical chemist workforce depth and closed-loop synthesis patent portfolios. Monitor EPA NESHAP compliance cost trajectories as inflection indicator for US domestic production economics versus import preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitrile Precursors | Arkema's captive supply strategy secures feedstock continuity against ammonia price volatility. |
| Membrane Electrolysis Capacity Buildout | German specialty chemical producers pilot solid-state stacks to eliminate sodium chloride byproduct streams. |
| REACH Registration Completion | Full substance dossier submission under ECHA deadlines freezes competitive entry for 18-24 months. |
| Long-term Supply Agreement with Aerospace Integrators | German and Chinese launch vehicle programs concentrate procurement for satellite constellation deployments. |
| Joint Venture for Saudi Pharmaceutical-Grade Production | Vision 2030 import substitution creates localized capacity to serve regional API manufacturing. |
Methodological Framework
A spread of perspectives from propellant formulators, API synthesis directors, polymerization initiator procurement leads, and boiler water treatment chemical distributors converged on the working assumptions. Primary fieldwork combined structured interviews with plant managers at Raschig-process facilities and technical service teams at aerospace companies. Secondary validation drew from ECHA registration databases, EPA NESHAP rulemaking dockets, BIS quality mandate publications, and customs trade flow records. Bottom-up capacity assessments and top-down end-use consumption estimates were triangulated against producer-reported volume disclosures.
Segmentation dimensions modeled span purity grade tier, end-use application, delivery mode configuration, and regional production hub classification across the analysis window. Aerospace propulsion demand curves, agrochemical intermediate consumption patterns, and pharmaceutical-grade qualification velocities informed growth trajectory assumptions. CAGRs were derived from supply-demand balance modeling rather than extrapolation of historical trends. Forecast inputs incorporated REACH registration timeline delays, EPA compliance cost pass-through coefficients, and membrane electrolysis technology adoption curves.
Forecasts assume regulatory continuity in REACH, EPA, and BIS frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Superplasticizer Market
Chemicals
CHPTAC Market
Chemicals
China Amines Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Global Benzalkonium Chloride Market
Chemicals
Non PVC Plasticizers Market
Chemicals
Triethanolamine Market
Chemicals
Calcium Hydride Market
Chemicals
Aromatic Polyamine Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Diphenylamine (DPA) Market
Chemicals
Oxybenzone Market
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
South Korea Methanol Market