
 Butylated Triphenyl Phosphate Market | 2026-2036
Butylated Triphenyl Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Butylated Triphenyl Phosphate Market Analysis
A capital-intensity divergence between integrated phosphorus producers and specialty chemical formulators is reorganizing competitive tiers in the butylated triphenyl phosphate value chain. Albemarle Corporation leverages captive bromine and phosphorus assets to sustain backward-integrated cost positions across flame retardant grades. LANXESS anchors its European manufacturing base with dedicated capacity serving automotive OEM specifications. Kindon Chemical Technology Co., Ltd. competes on volume scale from Zhejiang province, supplying regional electronics fabricators with liquid phosphate ester streams.
Butylated triphenyl phosphate denotes a triaryl phosphate ester modified with butyl substituents, typically produced through phosphorylation of butylated phenol precursors with phosphorus oxychloride, yielding a viscous liquid with phosphorus content around 8-9% and pour points below minus 15 degrees Celsius. The compound functions primarily as a halogen-free flame retardant plasticizer, imparting fire resistance and flexibility to polyvinyl chloride, cellulose acetate, and engineered thermoplastics in wire insulation, upholstery, and film applications. Flame retardant product types command the largest volume share, though plasticizer segments targeted at high-temperature automotive harnesses represent the fastest-expanding margin pool. Construction applications dominate absolute consumption, while electronics applications concentrate demand for low-volatility liquid grades meeting JIS and IEC connector specifications.
EPA oversight under the Toxic Substances Control Act and REACH registration requirements administered by ECHA impose substance-by-substance evaluation burdens on importers and manufacturers, elevating compliance costs for smaller traders while advantaging registrants with full dossier submissions. China's MEE enforces GB standards limiting volatile organic compound emissions from phosphate-containing coatings, redirecting formulation demand toward purified, low-odor butylated triphenyl phosphate grades. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and reposition supply contracts accordingly.
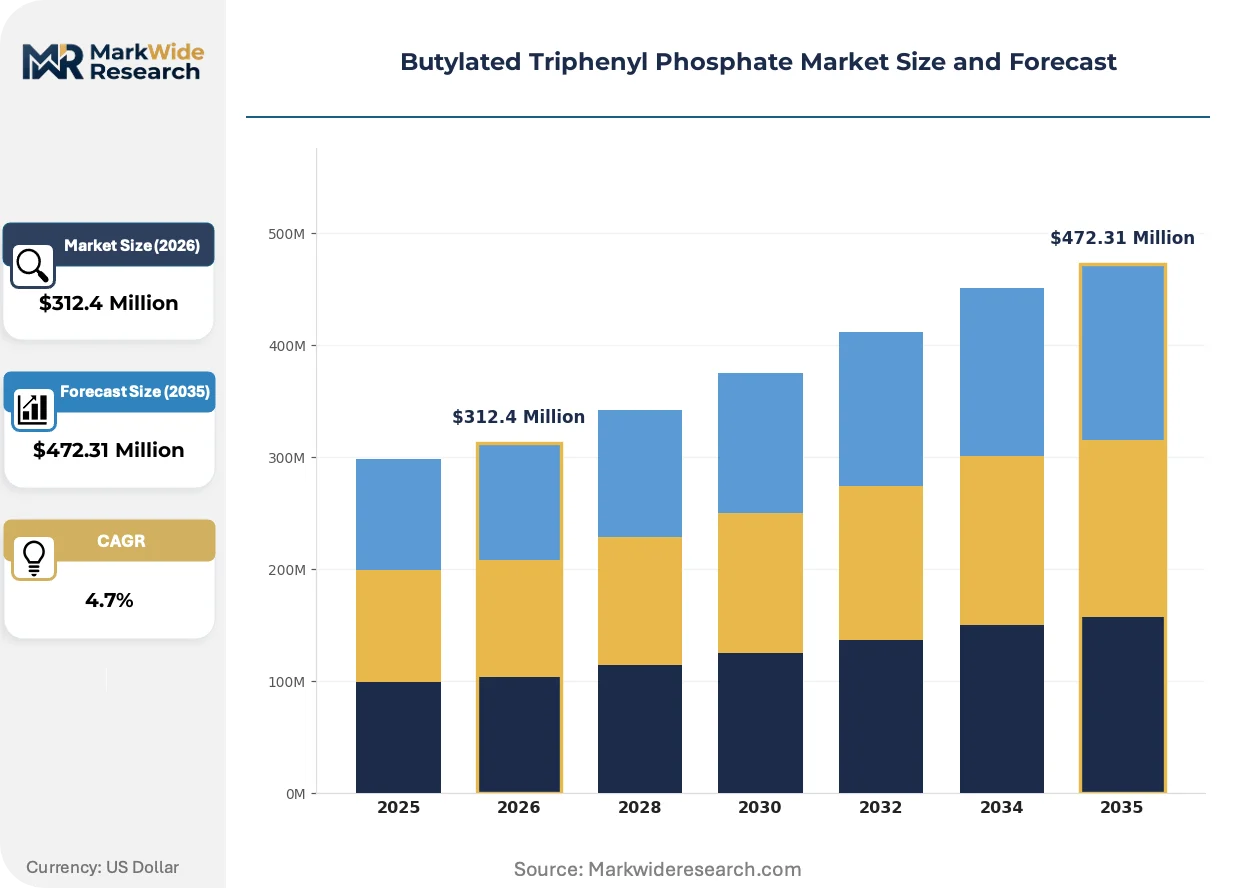
Market Dynamics
The butylated triphenyl phosphate market faces structural pressure from REACH-driven reformulation mandates in Europe and China's tightening GB standards on volatile organic compound emissions, forcing producers to purify liquid phosphate ester grades while maintaining cost parity with legacy formulations.
Growth Catalysts
- Automotive lightweighting mandates:OEM specifications for wire harness insulation in electric vehicles are pulling halogen-free flame retardant plasticizers into high-temperature applications previously served by brominated alternatives.
- REACH substance evaluation:ECHA's ongoing assessment of short-chain chlorinated paraffins is redirecting European demand toward triaryl phosphate esters in upholstery and construction films.
- Electronics cluster concentration:Zhejiang and Guangdong province manufacturing corridors are consuming disproportionate volumes of low-volatility liquid grades for connector housings meeting JIS specifications.
Market Restraints
- Phosphorus oxychloride cost volatility:Feedstock price swings tied to phosphate rock mining disruptions in Morocco and China compress margin predictability for non-integrated formulators.
- Substitution by intumescent coatings:Construction applications in commercial real estate are partially displacing additive flame retardants with reactive systems that eliminate plasticizer loadings entirely.
- REACH registration cost barriers:Full dossier submission requirements for butylated triphenyl phosphate consortia favor large-volume registrants and exclude smaller importers from European supply contracts.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for mobile phone and component production are building assembly capacity that will require imported technical phosphate esters for cable insulation.
- High-voltage EV cable specifications:Emerging 800-volt architectures demand thermal stability beyond conventional plasticizers, creating specification premiums for purified butylated grades.
- Green building certification alignment:LEED and BREEAM point systems rewarding low-emitting materials are steering specification authority toward architects specifying halogen-free flame retardant systems.
Industry Challenges
- Phosphorus process engineering talent scarcity:Specialized expertise in phosphorylation reactor design and byproduct control resides with aging workforces at legacy German and US production sites.
- Multi-jurisdiction compliance synchronization:Divergent EPA TSCA, REACH, and China MEE notification timelines force parallel track testing investments without guaranteed regulatory reciprocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Butylated Triphenyl Phosphate Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flame Retardants, Plasticizers, Coatings, Lubricants Application: Construction, Automotive, Electronics, Textiles Form: Liquid, Powder, Granule, Gel End User: Manufacturers, Distributors, Retailers, Contractors |
| Companies Covered | Radco Industries, Inc., Israel Chemicals Limited, LANXESS, Budenheim GmbH, Albemarle Corporation, ICL, Chemtura Corporation, Kindon Chemical Technology Co., Ltd., PCC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Butylated Triphenyl Phosphate Market Emerging Trajectories
Reformulation chemistry and regulatory chemistry are converging to reshape product specifications, with purity thresholds and emission profiles becoming as critical as flame retardant performance in customer selection criteria.
Low-odor purification technology is bifurcating the commodity and specialty segments of the butylated triphenyl phosphate market. Distillation and adsorption systems capable of reducing volatile residuals below 500 ppm are commanding specification premiums from automotive OEMs. Tier-1 wire harness suppliers in Germany and Japan are adopting these grades exclusively, while construction applications tolerate higher-volatility alternatives.
China's MEE enforcement of GB 30982-2014 limits on VOC emissions from interior coatings is tightening permissible thresholds for phosphate-containing formulations. Coating manufacturers in Shanghai and Jiangsu are reformulating toward purified liquid phosphate esters or abandoning the additive class entirely. The electronics sector, with its JIS C 3005 connector specifications, is absorbing the cost premium for compliant grades.
Specification authority is migrating from compounders to OEM material engineers armed with restricted substance databases. Automotive harness buyers at Volkswagen, Toyota, and BYD now mandate full material disclosure and third-party emission testing before contract award. Tier-2 suppliers without in-house toxicology resources are ceding formulation decisions to resin partners with dedicated regulatory affairs functions.
Butylated Triphenyl Phosphate Market Segmentation
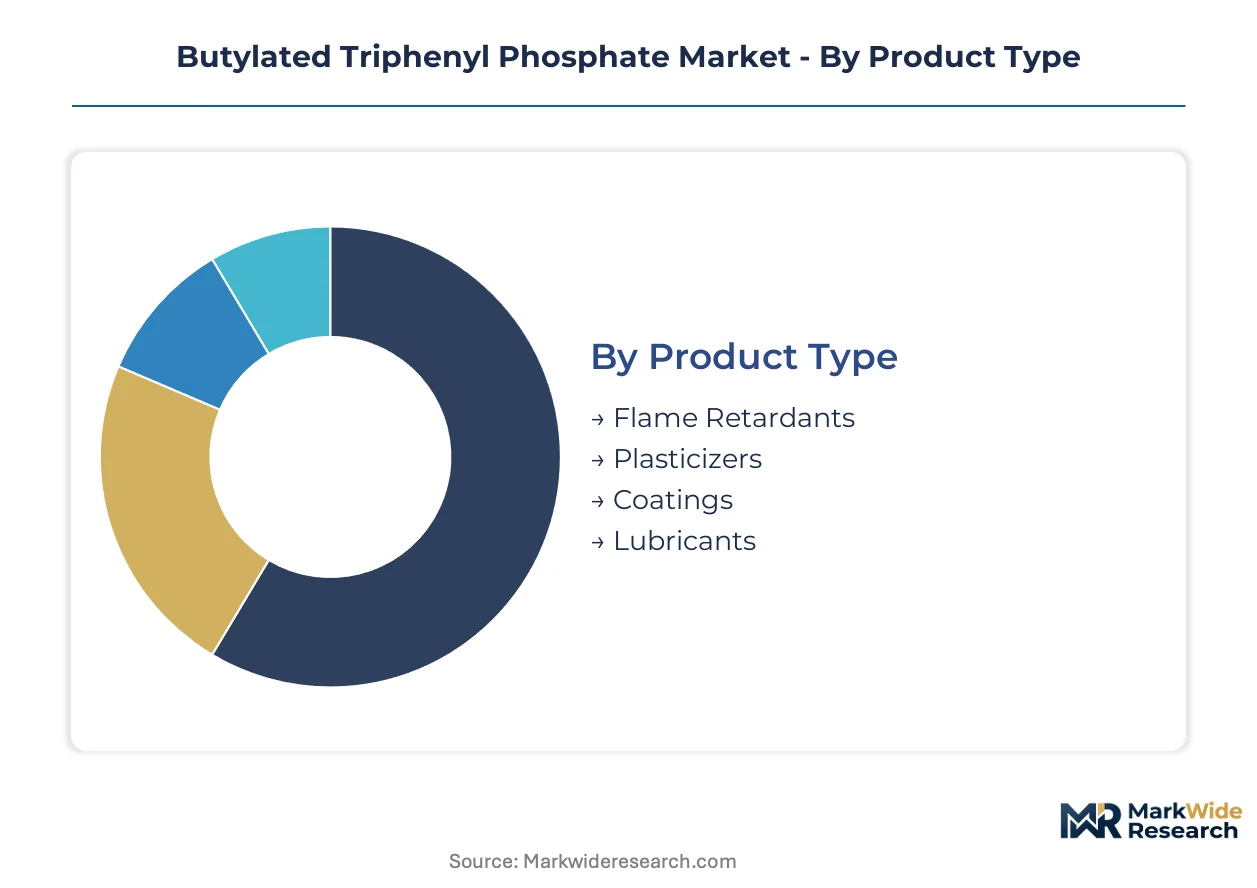
Margin capture in butylated triphenyl phosphate varies sharply by functional specification and purity tier. Segmentation reveals where reformulation investments concentrate and which customer specifications command sustainable premiums.
Product Type:
Flame retardant grades carry the widest specification spreads, with automotive OEMs paying premiums for low-odor purification while construction buyers prioritize volume cost.
- Flame Retardants:Halogen-free grades with phosphorus content of 8-9% serve wire insulation and upholstery applications. Demand concentrates in electric vehicle harness specifications from Volkswagen, Toyota, and BYD, where thermal stability requirements exclude legacy brominated alternatives.
- Plasticizers:High-temperature grades engineered for polyvinyl chloride and cellulose acetate flexibility command specification premiums in 800-volt EV cable architectures. Zhejiang and Guangdong electronics corridors absorb disproportionate volumes for connector housings meeting JIS C 3005 standards.
- Coatings:Low-VOC formulations align with China's GB 30982-2014 enforcement in Shanghai and Jiangsu provinces.
- Lubricants:Technical phosphate ester streams serve industrial fluid applications with narrower margin pools.
The dominant share belongs to Flame Retardants, while Plasticizers is closing the gap fastest.
Application:
Volume scale and regulatory intensity diverge across end-use sectors, with construction absorbing raw tonnage and electronics demanding certified purity.
- Construction:Commercial real estate films and interior coatings consume bulk volumes, though intumescent reactive systems are partially displacing additive flame retardants in LEED and BREEAM-certified projects.
- Automotive:OEM lightweighting mandates pull halogen-free plasticizers into high-temperature wire harness applications previously served by brominated compounds. Tier-1 suppliers in Germany and Japan now mandate full material disclosure and third-party emission testing.
- Electronics:Low-volatility liquid grades for connector housings concentrate demand in Zhejiang province manufacturing corridors.
- Textiles:Upholstery applications in European markets redirect toward triaryl phosphate esters as ECHA substance evaluation pressures short-chain chlorinated paraffin alternatives.
Construction retains volume leadership, though Automotive generates the steepest margin expansion.
Form:
Physical state determines logistics economics and compounding integration, with liquid grades dominating continuous process industries.
- Liquid:Viscous phosphate ester streams with pour points below minus 15 degrees Celsius integrate directly into wire coating and film extrusion lines. Low-volatility purification below 500 ppm residual content commands specification premiums from automotive OEMs.
- Powder:Solid grades serve batch compounding operations in construction and textile applications with lower purity thresholds.
- Granule:Free-flowing forms reduce dust exposure in manual handling environments.
- Gel:Thickened formulations target specialized coating applications with rheology requirements.
Liquid forms dominate value capture, while Powder maintains cost-sensitive volume positions.
End User:
Procurement authority concentrates with compounders possessing in-house toxicology and regulatory affairs capabilities.
- Manufacturers:Resin compounders and wire harness producers with dedicated regulatory functions control formulation decisions. Full REACH dossier submissions and EPA TSCA compliance capabilities exclude smaller traders from European and US supply contracts.
- Distributors:Regional chemical traders face margin compression from feedstock volatility in phosphorus oxychloride markets.
- Retailers:Limited direct engagement in technical phosphate ester channels.
- Contractors:Construction application buyers prioritize cost over certification in non-certified building projects.
Manufacturers command specification authority, while Distributors face structural pressure from integrated producer direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in butylated triphenyl phosphate tilt toward net-import dependence in manufacturing-intensive economies while integrated phosphorus producers in mining jurisdictions sustain export positions. Regulatory divergence across EPA, ECHA, and China MEE jurisdictions is fragmenting product specifications and redirecting supply contract geography.
China
Zhejiang and Guangdong electronics corridors absorb disproportionate volumes of low-volatility liquid grades for connector housings meeting JIS C 3005 specifications. China MEE enforcement of GB 30982-2014 limits on VOC emissions from interior coatings is tightening permissible thresholds for phosphate-containing formulations. Shanghai and Jiangsu coating manufacturers are reformulating toward purified liquid phosphate esters or abandoning the additive class entirely.
Germany
Automotive OEM specifications from Volkswagen and Tier-1 wire harness suppliers mandate full material disclosure and third-party emission testing before contract award. ECHA REACH substance evaluation of short-chain chlorinated paraffins redirects European upholstery and construction film demand toward triaryl phosphate esters. The North Rhine-Westphalia chemical belt hosts specialized phosphorylation reactor expertise concentrated with aging workforces at legacy production sites.
United States
EPA oversight under the Toxic Substances Control Act imposes substance-by-substance evaluation burdens on importers and manufacturers, elevating compliance costs for smaller traders. Electric vehicle harness specifications from domestic OEMs pull halogen-free flame retardant plasticizers into high-temperature applications previously served by brominated alternatives. The Gulf Coast petrochemical corridor maintains captive phosphorus oxychloride supply chains buffering feedstock volatility.
Japan
METI industrial standards and JIS C 3005 connector specifications concentrate demand for low-volatility liquid grades with residual content below 500 ppm. Toyota material engineers now mandate full material disclosure databases before Tier-2 supplier contract awards. The Kanto and Kansai manufacturing belts import technical phosphate ester streams for automotive and electronics compounding operations.
India
PLI scheme subsidies for mobile phone and component production are building assembly capacity that will require imported technical phosphate esters for cable insulation. BIS standards alignment with IEC specifications is creating certification pathways for flame retardant plasticizers in domestic electronics fabrication. Maharashtra and Karnataka electronics manufacturing clusters represent emerging demand nodes as contract manufacturers expand capacity.
Butylated Triphenyl Phosphate Market Vendor Landscape
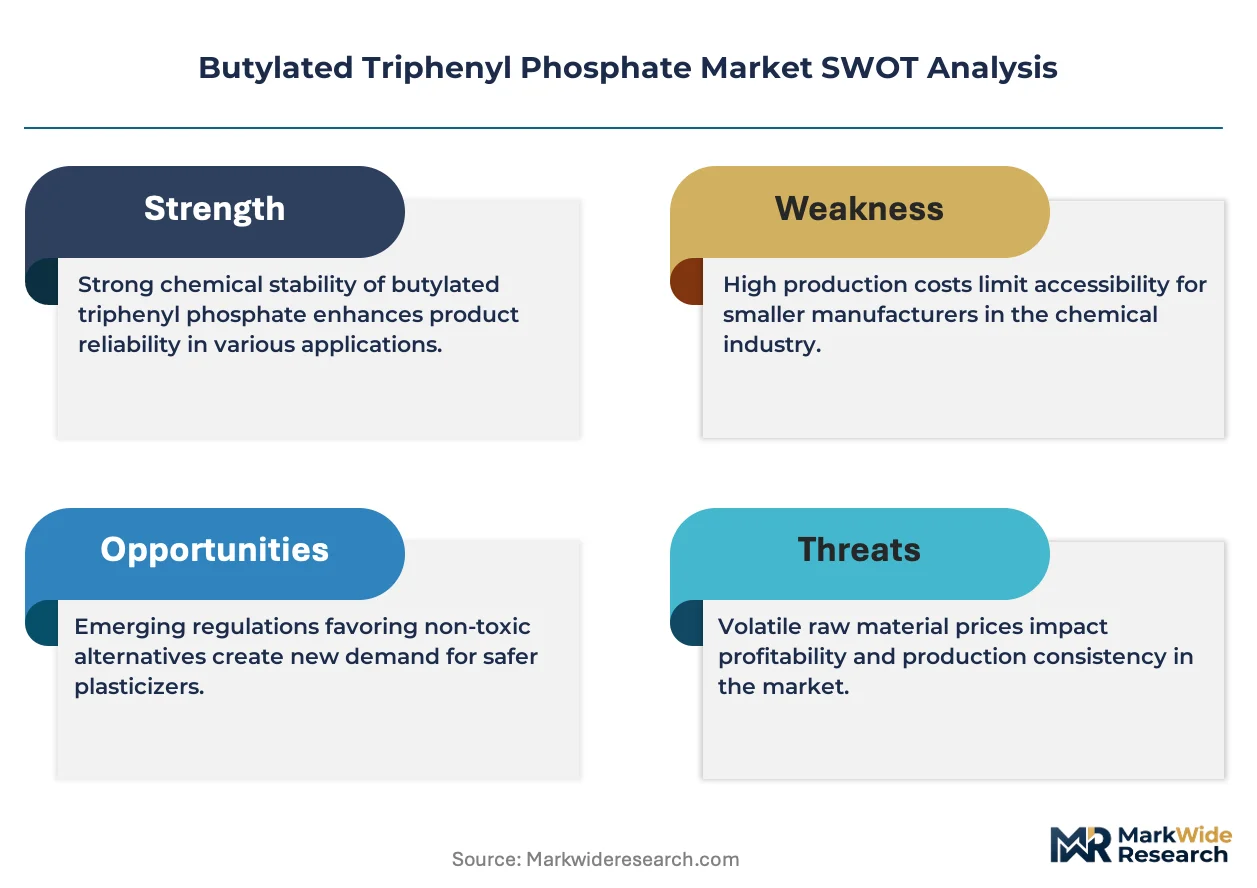
Concentration sits with integrated phosphorus producers possessing captive feedstock positions and specialty chemical formulators with dedicated regulatory affairs capabilities. The market structure bifurcates between backward-integrated majors sustaining cost parity across flame retardant grades and regional volume players serving specification-tolerant construction applications. Strategic archetypes include captive-resource majors, European automotive specification anchors, and China-based volume suppliers. Dominant competitive moves encompass purification technology investments for low-odor grades and direct OEM engagement bypassing distributor channels.
Among Germany-based chemical conglomerates, LANXESS anchors its European manufacturing base with dedicated capacity serving automotive OEM specifications. Albemarle Corporation represents the integrated-resource archetype, leveraging captive bromine and phosphorus assets to sustain backward-integrated cost positions across flame retardant grades. Kindon Chemical Technology Co., Ltd. occupies the volume-driven position, supplying regional electronics fabricators from Zhejiang province with liquid phosphate ester streams.
| Leading Market Players |
|---|
| Radco Industries, Inc. |
| Israel Chemicals Limited |
| LANXESS |
| Budenheim GmbH |
| Albemarle Corporation |
| ICL |
| Chemtura Corporation |
| Kindon Chemical Technology Co., Ltd. |
| PCC Group |
| Others |
Supply Flow & Price Mechanics
Substitution of brominated flame retardants by halogen-free phosphate esters in automotive wire harnesses is simultaneously redrawing supply geography toward Zhejiang province manufacturers and compressing pricing premiums for legacy grades. This input shift concentrates procurement power with Volkswagen, Toyota, and BYD material engineers who mandate full disclosure databases before contract award.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on volatility certification below 500 ppm residual content and REACH dossier completeness, with purified low-odor grades commanding substantial premiums from Tier-1 harness suppliers. Cost compression in standard grades is intensifying because phosphorus oxychloride feedstock volatility from Moroccan mining disruptions feeds through to non-integrated formulators. Construction compounders exhibit highest price sensitivity, while automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating landed costs for technical phosphate ester imports into Germany and Japan. Supply concentrates in China, Germany, and the United States, with captive phosphorus oxychloride production at Gulf Coast and North Rhine-Westphalia sites buffering raw material swings. The chain draws from phosphate rock mining in Morocco and China, phosphorylation reactor capacity in legacy German facilities, and butylated phenol precursors from petrochemical corridors. Single-source vulnerability sits with aging German process engineering expertise concentrated at legacy production sites. Distribution runs through direct OEM contracts that bypass regional chemical traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The butylated triphenyl phosphate market sits in early-cycle recovery as electric vehicle production ramps pull halogen-free plasticizers into high-temperature harness specifications previously served by brominated alternatives.
For Market Incumbents: Shield margin positions by deepening captive phosphorus oxychloride supply and accelerating low-odor purification capacity in Zhejiang province. Intumescent coating substitution in LEED-certified construction projects threatens volume in construction films, making automotive OEM specification lock-in the priority defensive lever. For New Entrants and Emerging Players: REACH registration fast-track through consortium participation opens European supply contracts currently blocked to smaller importers. White-space targets include India's PLI-subsidized electronics manufacturing clusters and 800-volt EV cable specifications demanding thermal stability beyond conventional plasticizers. A technical service partnership with resin compounders lacking in-house toxicology resources offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated phosphorus producers with REACH dossier completeness. Long-term viability rests on regulatory compliance capabilities rather than commodity scale, positioning German and US-based specialists with captive feedstock and full registration status as prime acquisition targets. Watch ECHA substance evaluation timelines for short-chain chlorinated paraffins as the inflection signal redirecting European upholstery demand toward triaryl phosphate esters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive phosphorus oxychloride supply buffers Moroccan phosphate rock volatility for integrated producers. |
| Low-Odor Purification Capacity | Distillation systems reducing residuals below 500 ppm unlock Volkswagen and Toyota harness specifications. |
| REACH Consortium Participation | Full dossier submission excludes smaller traders and secures European automotive supply contracts. |
| India Market Entry | PLI scheme subsidies for mobile phone assembly create imported phosphate ester demand in Maharashtra clusters. |
| High-Voltage Cable Certification | Thermal stability validation for 800-volt architectures commands specification premiums from EV OEMs. |
Methodological Framework
Desk research of customs trade data, SEC filings from Albemarle and LANXESS, and ECHA registration databases preceded structured interviews with phosphorylation plant managers, automotive wire harness procurement leads, and China-based electronics compounders. Primary fieldwork with distribution channel partners and technical R&D directors at flame retardant formulators was cross-validated against ACC and Cefic industry reports. Bottom-up volume estimates from application-level consumption were triangulated with top-down value projections.
Variance decomposition across product type, application, and regional production hub segments shaped the analytical framework over the projection horizon. Modeled dimensions included flame retardant versus plasticizer grades, construction versus automotive end-use splits, and liquid versus powder form factors. CAGRs were derived from segment-level growth rate synthesis, with electric vehicle harness content per vehicle and China's GB 30982-2014 enforcement intensity serving as key forecast inputs.
Underlying assumptions cover sustained electric vehicle production growth and REACH substance evaluation timelines, with deviation risk concentrated in phosphorus oxychloride feedstock disruptions and intumescent coating substitution rates in green building projects. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Italy Laboratory Chemicals Market
Chemicals
North America Isopropyl Alcohol Market
Chemicals
Trichlorosilane Market
Chemicals
Ferric Oxide Market
Chemicals
Betaine Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Hydrophobing Agents Market
Chemicals
Thiourea Market
Chemicals
Spirodiclofen Market
Chemicals
Maleic Acid Market
Chemicals
North America Methanol Market
Chemicals
Hypophosphorous Acid Market
Chemicals
United Kingdom Methanol Market
Chemicals
Methanol Market
Chemicals
India Ethoxylates Market