
 Diphosphate Market | 2026-2036
Diphosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Diphosphate Market Analysis
Aftermarket technical service revenue is reconfiguring margin capture across the diphosphate value chain. ICL Group Ltd. leverages its integrated phosphate rock assets to sustain cost leadership in flame-retardant and food-grade formulations. Prayon Group anchors European supply through its captive phosphate processing network in Belgium. Hubei Xingfa Chemical Group dominates Chinese export volumes with backward integration into phosphorus mining and thermal acid production.
Diphosphates are condensed phosphate salts composed of two orthophosphate units linked by a P-O-P bond, typically manufactured via thermal dehydration of monophosphates at controlled temperature profiles. These compounds function primarily as sequestrants, buffering agents, and leavening acids across industrial and food systems. Sodium diphosphate commands the largest product-type position due to its ubiquity in processed meat emulsions and detergent builders, while calcium diphosphate exhibits the fastest application growth in pharmaceutical tablet formulations and dental cements. Food additive demand within the application dimension concentrates margin pools around kosher and halal-certified grades, whereas fertilizer applications remain structurally mature with pricing tied to phosphate rock benchmarks.
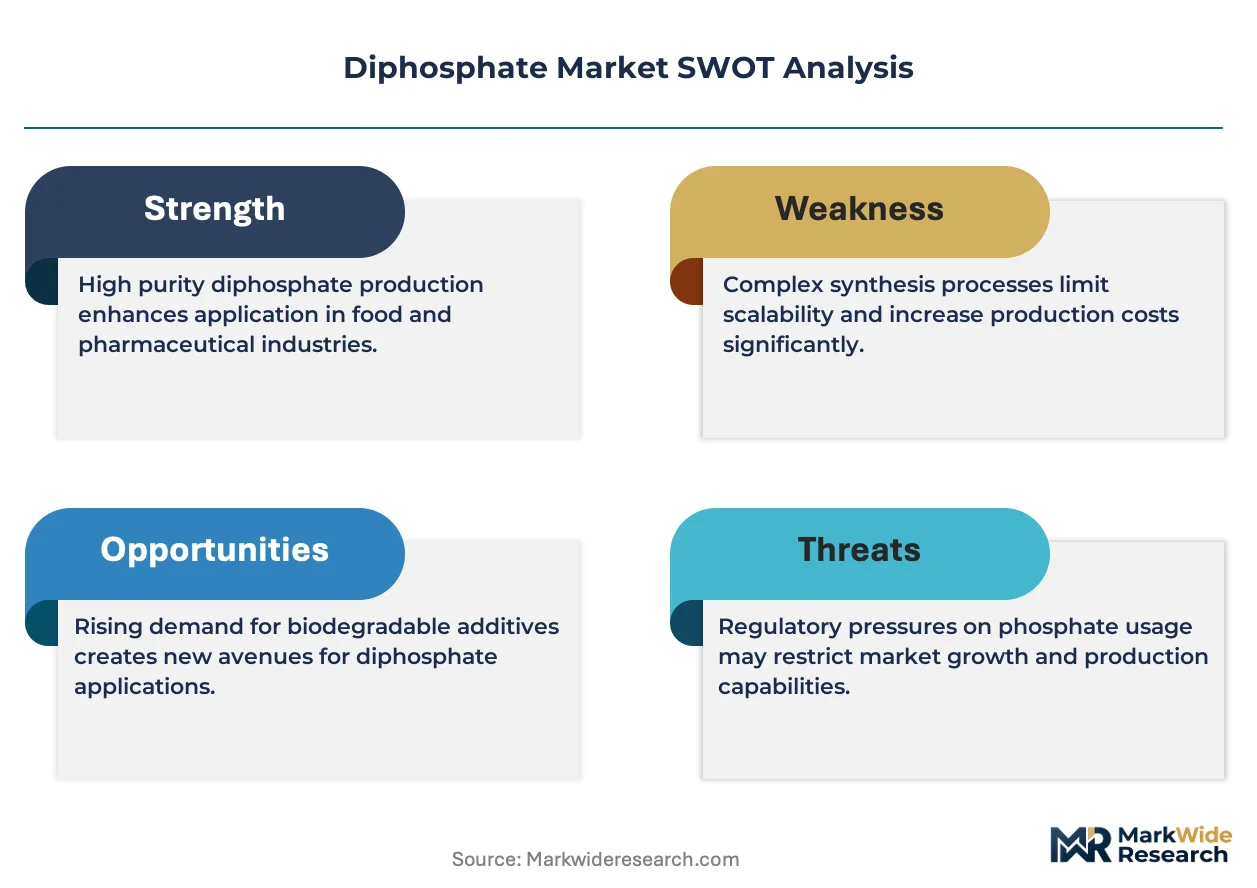
REACH registration requirements in Europe and FDA food additive regulations in the United States constrain market entry for uncertified producers while elevating compliance costs for existing suppliers. China's GB standards for food-grade phosphates and the EU F-Gas Regulation's indirect pressure on phosphate-based fire suppression alternatives are reshaping product development priorities. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation portfolios and avoid stranded certification investments.
Market Dynamics
REACH compliance tightening across Europe is compressing margins for uncertified diphosphate suppliers while concentrating volume among integrated producers with captive thermal acid capacity. The regulatory pressure is accelerating consolidation around kosher and halal-certified food-grade production lines.
Growth Catalysts
- Processed meat emulsion demand:Sodium diphosphate functions as the primary stabilizer in industrial meat processing, with capacity expansion visible across Brazilian and Chinese slaughterhouse operations.
- REACH registration thresholds:ECHA's purity mandates for food-contact applications are disqualifying marginal producers and expanding addressable market share for compliant manufacturers.
- Thermal dehydration process optimization:Advanced temperature-profile control systems are reducing energy intensity in diphosphate conversion, lowering unit economics for backward-integrated phosphate rock processors.
Market Restraints
- Phosphate rock price volatility:Input cost swings tied to Moroccan and Jordanian mining output compress margin predictability for non-integrated diphosphate manufacturers.
- Supply concentration in Chinese thermal acid:Hubei and Guizhou provinces dominate merchant acid supply, creating geographic single-point vulnerability for European and North American formulators.
- Substitution by organic acidulants:Citric acid and glucono-delta-lactone are displacing calcium diphosphate in certain pharmaceutical tablet formulations where clean-label positioning commands premium pricing.
Strategic Opportunities
- Pharmaceutical tablet excipient growth:Calcium diphosphate exhibits expanding utilization in direct-compression formulations where flowability and compressibility specifications are tightening.
- India food additive penetration:FSSAI modernization of phosphate additive standards is opening formal channels for certified imports into processed dairy and bakery segments.
- EU F-Gas Regulation tailwind:Phosphate-based fire suppression alternatives are gaining traction as fluorinated gas phase-out deadlines approach, redirecting R&D spend toward flame-retardant diphosphate grades.
Industry Challenges
- Halal certification timeline compression:Multi-jurisdictional religious authority approvals for food-grade diphosphates extend commercialization cycles by 12-18 months for new production facilities.
- Thermal acid furnace rebuild cycles:Refractory maintenance and electrode replacement in electric-furnace operations demand concentrated capital deployment every 5-7 years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diphosphate Market |
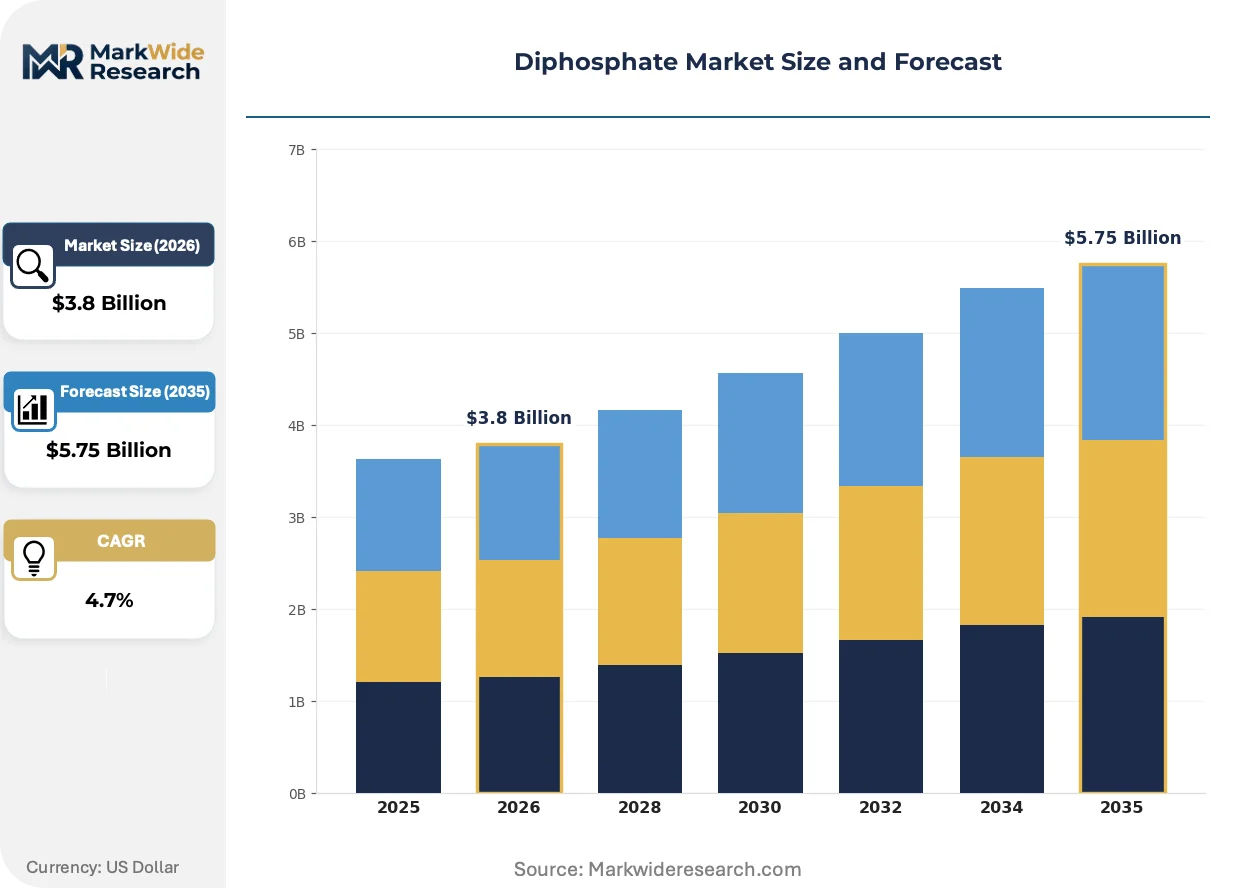
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Diphosphate, Potassium Diphosphate, Calcium Diphosphate, Ammonium Diphosphate Application: Food Additives, Fertilizers, Pharmaceuticals, Industrial Chemicals End User: Agriculture, Food & Beverage, Healthcare, Chemical Manufacturing Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Aditya Birla Chemicals, Nexeo Solutions, Hubei Xingfa Chemical Group, Mutchler Inc, Trivenichemical, Innophos Holdings Inc., ICL Group Ltd., Prayon Group, Generichem Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diphosphate Market Emerging Trajectories
Process control automation and regulatory data transparency are converging to reshape competitive positioning across food-grade and industrial diphosphate segments. Manufacturers are deploying sensor networks and batch-tracking systems to satisfy tightening chain-of-custody requirements.
Inline near-infrared spectroscopy is digitizing real-time purity verification during thermal dehydration. Major processed meat processors in Germany and the United States are mandating this capability from suppliers. The technology is compressing quality assurance cycles from hours to minutes while reducing off-spec batch volumes.
EU F-Gas Regulation phase-down schedules are redirecting formulation priorities toward phosphate-based intumescent systems. REACH registration dossiers for novel flame-retardant grades are expanding as ECHA evaluates persistence and bioaccumulation profiles. European construction chemical suppliers are responding by qualifying diphosphate alternatives in passive fire protection coatings.
Direct-procurement platforms are disintermediating traditional chemical distributors for standard-grade sodium diphosphate. Large meat processing conglomerates in Brazil and Spain are establishing vendor-managed inventory arrangements with thermal acid producers. This channel shift is most visible in Iberian and Mercosur markets where buyer concentration supports logistics optimization at plant-gate delivery terms.
Diphosphate Market Segmentation
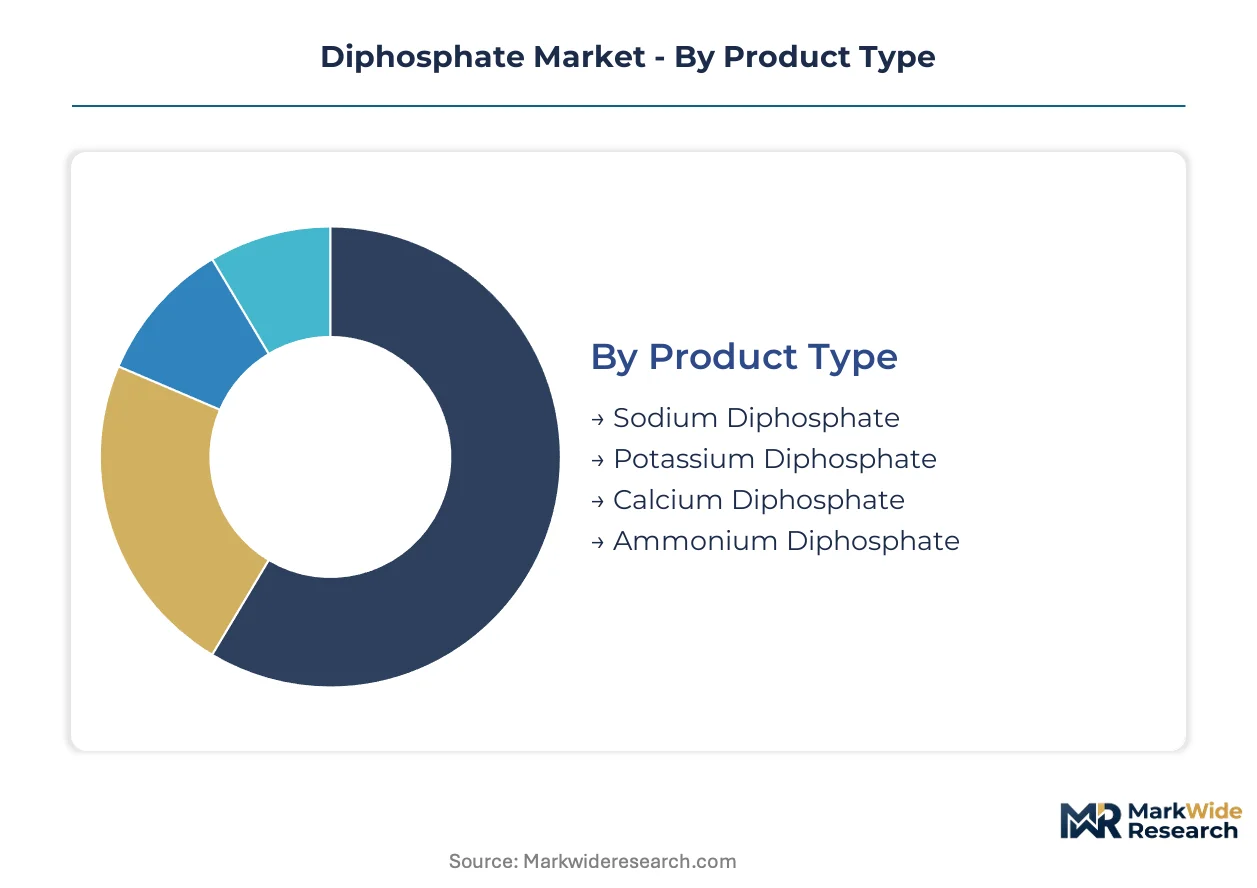
Diphosphate market segmentation reveals distinct velocity profiles across product chemistry and demand cycles. Food-grade specifications turn inventory fastest while fertilizer applications operate on seasonal procurement rhythms tied to planting calendars.
Product Type:
Sodium diphosphate rotates through supply chains most rapidly due to processed meat sector consumption patterns, whereas ammonium diphosphate exhibits extended holding periods tied to agricultural seasonality.
- Sodium Diphosphate:Manufactured via controlled thermal dehydration of monosodium phosphate to achieve specific P2O5 content between 63-65%. Brazilian and Chinese slaughterhouse operators dominate procurement volumes, with EFSA purity mandates compressing supplier qualification timelines for European meat processors.
- Calcium Diphosphate:Functions as a direct-compression tablet excipient with superior flowability indices compared to lactose alternatives. Pharmaceutical formulators in Germany and the United States are tightening compressibility specifications, driving specification-grade premiums for micronized particle distributions.
- Potassium Diphosphate:Low-sodium meat processing applications in Western Europe and hypertension-conscious consumer segments.
- Ammonium Diphosphate:Controlled-release fertilizer coatings and fire-retardant intumescent systems responding to EU F-Gas Regulation phase-down deadlines.
Sodium diphosphate anchors the volume base while calcium diphosphate gains share at the steepest rate.
Application:
Margin structures diverge sharply across this dimension, with pharmaceutical and food additive specifications commanding certification premiums against commoditized fertilizer grades.
- Food Additives:Sequestrant and buffering functions in processed meat emulsions, with kosher and halal certification gates extending commercialization cycles. German retail chains and U.S. meatpackers now mandate inline near-infrared spectroscopy verification from thermal acid suppliers.
- Pharmaceuticals:Tablet disintegrant and dental cement applications where USP-NF monograph compliance creates formulation lock-in. Direct-compression grade calcium diphosphate is displacing traditional excipients in immediate-release solid dosages manufactured for North American and European markets.
- Fertilizers:Phosphate rock benchmark pricing and Moroccan mining output volatility compress margin predictability for non-integrated compounders.
- Industrial Chemicals:Flame-retardant intumescent coatings and water treatment sequestrants with construction chemical qualification timelines.
Fertilizer applications generate the largest absolute tonnage while pharmaceutical specifications expand most quickly.
End User:
Procurement sophistication varies dramatically, with food and beverage conglomerates deploying vendor-managed inventory systems while agricultural buyers remain spot-market dependent.
- Food & Beverage:Processed meat, dairy, and bakery manufacturers in Spain and Brazil establishing direct-procurement platforms with Hubei and Guizhou thermal acid producers. FSSAI modernization in India is opening formal import channels for certified sodium diphosphate into dairy applications.
- Healthcare:Pharmaceutical tablet manufacturers and dental material suppliers with USP-NF and EP monograph compliance requirements. Calcium diphosphate specifications for direct compression are tightening flowability indices across German and U.S. formulators.
- Agriculture:Compound fertilizer blenders exposed to phosphate rock price swings from Moroccan and Jordanian mining operations.
- Chemical Manufacturing:Construction chemical and water treatment formulators qualifying phosphate-based fire suppression alternatives ahead of EU fluorinated gas phase-out deadlines.
Food and beverage operations drive the highest transaction frequency while healthcare applications demonstrate the steepest specification-grade expansion.
Distribution Channel:
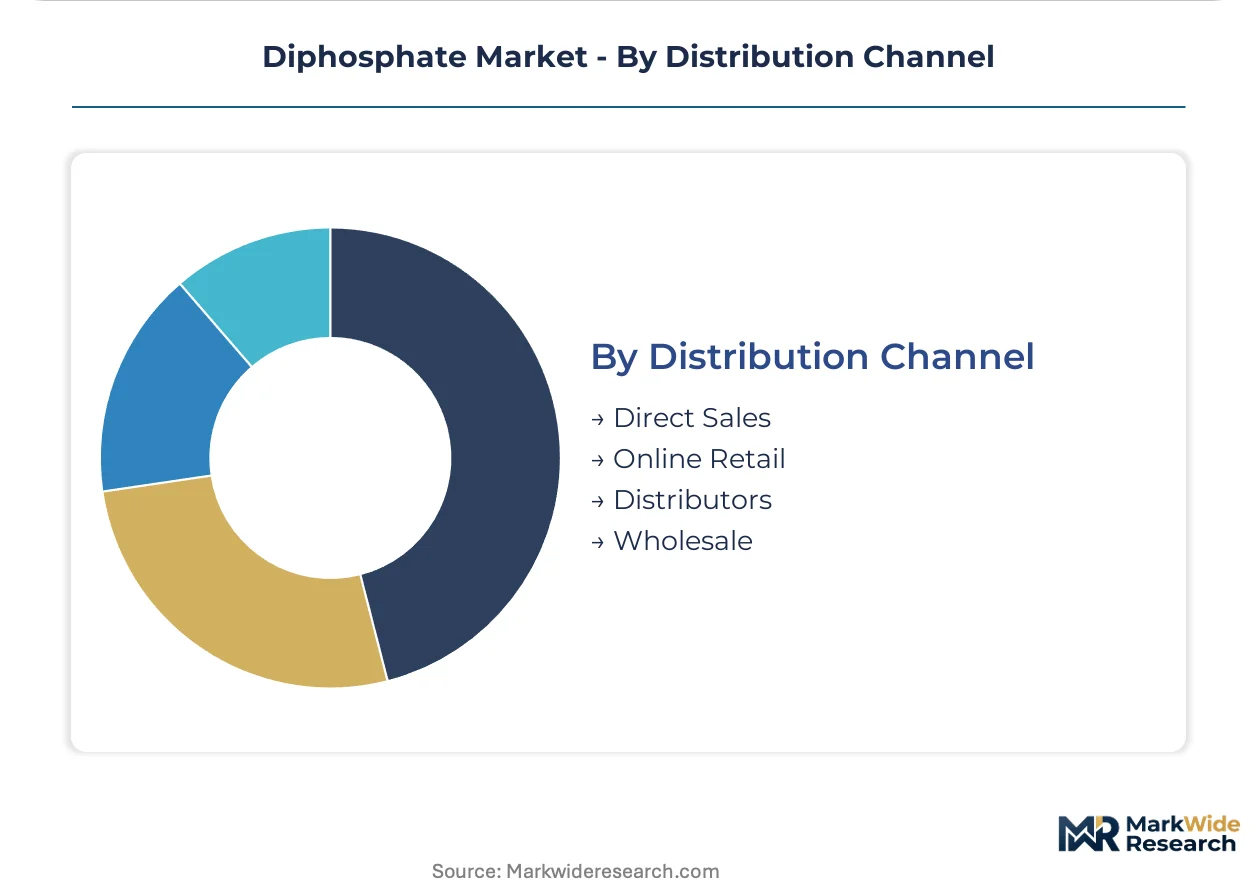
Channel economics reflect buyer concentration and logistics density, with direct sales penetrating where plant-gate delivery optimization is achievable.
- Direct Sales:Large meat processing conglomerates in Iberia and Mercosur markets negotiating vendor-managed inventory with thermal acid producers. Brazilian and Spanish buyers leverage volume concentration to secure plant-gate delivery terms bypassing traditional chemical distributors.
- Distributors:Regional chemical distributors serving mid-tier food processors and agricultural compounders with fragmented procurement volumes.
- Wholesale:Standard-grade sodium diphosphate for fertilizer blending operations with seasonal demand spikes.
- Online Retail:Laboratory-grade and small-volume pharmaceutical excipient procurement with specification documentation requirements.
Direct sales channels capture the largest volume flows while online retail demonstrates the most rapid expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Merchant thermal acid capacity clusters in Hubei and Guizhou provinces supply formulators across Brazil, Germany, and the United States. REACH registration thresholds and FDA food additive standards are compressing supplier qualification timelines in Europe and North America.
China
Hubei Xingfa Chemical Group anchors export volumes through backward integration into phosphorus mining and thermal acid production. GB standards for food-grade phosphates administered by SAMR are tightening purity specifications for domestic and export markets. The Yangtze River Delta chemical manufacturing corridor concentrates sodium diphosphate output serving Brazilian meat processors and European detergent compounders.
United States
Processed meat conglomerates in the Midwest and Southeast are mandating inline near-infrared spectroscopy verification from thermal acid suppliers. FDA food additive regulations constrain market entry for uncertified producers while elevating compliance costs for existing suppliers. Greater Chicago and Omaha slaughterhouse clusters drive procurement volumes for sodium diphosphate stabilizers in industrial meat emulsions.
Germany
EFSA purity mandates for food-contact applications are disqualifying marginal producers and expanding addressable market share for compliant manufacturers. The EU F-Gas Regulation is redirecting R&D spend toward flame-retardant diphosphate grades in construction chemical applications. The Rhine-Ruhr industrial corridor hosts formulation facilities qualifying phosphate-based fire suppression alternatives ahead of fluorinated gas phase-out deadlines.
Brazil
Slaughterhouse operators in São Paulo and Minas Gerais states are establishing direct-procurement platforms with Chinese thermal acid producers. ANVISA modernization of phosphate additive standards is opening formal channels for certified imports into processed meat segments. The Mercosur market supports vendor-managed inventory arrangements with plant-gate delivery terms bypassing traditional chemical distributors.
Belgium
Prayon Group anchors European supply through its captive phosphate processing network serving food-grade and industrial formulations. ECHA REACH registration requirements are accelerating consolidation around kosher and halal-certified production lines. The Port of Antwerp chemical cluster facilitates distribution to German meat processors and French pharmaceutical formulators.
Diphosphate Market Vendor Landscape
Integrated phosphate rock processors and merchant thermal acid specialists split the market along the backward-integration frontier. Three archetypes dominate: captive mining-to-acid operators, regional formulators with qualification expertise, and distributor-dependent traders serving spot agricultural demand. Consolidation is accelerating through REACH registration threshold pressure and direct-procurement platform expansion by large meat processors.
Within the integrated tier, ICL Group Ltd. and Prayon Group exemplify archetypes with captive phosphate rock assets and European regulatory qualification depth. Hubei Xingfa Chemical Group occupies a position representing Chinese backward integration into phosphorus mining and thermal acid production. These three anchors illustrate the geographic and structural segmentation between Middle Eastern-European supply networks and Chinese export dominance.
| Leading Market Players |
|---|
| Aditya Birla Chemicals |
| Nexeo Solutions |
| Hubei Xingfa Chemical Group |
| Mutchler Inc |
| Trivenichemical |
| Innophos Holdings Inc. |
| ICL Group Ltd. |
| Prayon Group |
| Generichem Corp |
| Others |
Supply Flow & Price Mechanics
Phosphate rock price volatility from Moroccan and Jordanian mining output compresses margin predictability for non-integrated manufacturers while simultaneously widening pricing tier spreads between captive thermal acid producers and merchant compounders. REACH registration thresholds in Europe and FDA food additive standards in the United States enforce certification premiums that reshape procurement patterns toward backward-integrated suppliers with verified purity documentation.
Pricing Analysis
REACH registration thresholds dictate the pricing tier structure across food-grade and industrial diphosphate segments. Three-tier pricing separates kosher-halal certified pharmaceutical grades from standard food-additive specifications and bulk fertilizer compounds. Certification premiums for EFSA-compliant and USP-NF monograph grades widen spreads against commoditized agricultural grades. Cost compression in standard sodium diphosphate intensifies because Brazilian and Spanish meat processors negotiate vendor-managed inventory arrangements directly with Hubei thermal acid producers. Agricultural compounders exhibit the highest price sensitivity due to phosphate rock benchmark exposure, while pharmaceutical formulators accept specification-grade premiums for micronized calcium diphosphate with tightened flowability indices.
Supply Chain Analysis
Extended payment terms from Brazilian slaughterhouse operators to Chinese thermal acid producers reveal supply-chain finance facilities that concentrate working capital pressure on merchant compounders. Geographic supply concentrates in Hubei and Guizhou provinces of China, Belgium's Port of Antwerp chemical cluster, and Israel's Negev phosphate mining district. Raw material dependencies center on phosphate rock from Moroccan and Jordanian mines, metallurgical-grade coke for electric furnace electrodes, and sulfuric acid for wet-process acid production. Single-source vulnerability runs through Chinese merchant thermal acid capacity serving European and North American formulators. Distribution runs through direct-procurement platforms for large meat processors and regional chemical distributors for fragmented agricultural buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-procurement platform expansion by Brazilian and Iberian meat processors signals a platform-economics inflection where vendor-managed inventory systems disintermediate traditional chemical distributors. Interoperability between inline near-infrared spectroscopy verification and batch-tracking databases is reshaping supplier qualification protocols.
For Market Incumbents: Harden kosher and halal certification depth to defend against emerging Chinese exporters with SAMR-compliant GB standards. Expand captive phosphate rock processing capacity in Belgium or Israel to offset Moroccan mining volatility. Prioritize thermal dehydration furnace automation to satisfy German meat processor mandates for real-time purity verification. For New Entrants and Emerging Players: Pursue pharmaceutical-grade calcium diphosphate production for direct-compression tablet applications where USP-NF compliance creates formulation lock-in. Target Indian dairy and bakery segments opened by FSSAI modernization of phosphate additive standards. Deploy specification-grade positioning with micronized particle distribution capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down deadlines reshape the acquisition landscape toward flame-retardant diphosphate specialists with REACH-registered intumescent coating qualifications. Long-term viability centers on integrated phosphate rock-to-acid operators with regulatory qualification depth across multiple jurisdictions. Monitor ECHA persistence and bioaccumulation evaluations for novel flame-retardant grades as the inflection indicator for R&D redirection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Captive Moroccan or Jordanian mining assets insulate ICL Group and Prayon from thermal acid price volatility. |
| Halal-Kosher Certification Investment | Multi-jurisdictional religious authority approvals extend commercialization moats for food-grade sodium diphosphate suppliers. |
| Inline Spectroscopy Deployment | Real-time NIR verification satisfies German retail chain mandates while compressing quality assurance cycles. |
| Flame-Retardant Grade R&D Expansion | Phosphate-based intumescent systems capture EU construction chemical demand ahead of fluorinated gas phase-outs. |
| Direct-Procurement Platform Partnership | Vendor-managed inventory arrangements with Brazilian meat processors bypass distributor margins and secure volume commitments. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with thermal acid plant managers, pharmaceutical procurement leads, meat processing technical directors, and construction chemical formulators; and secondary validation through customs trade databases, ECHA REACH registration dossiers, SEC 10-K filings from listed phosphate processors, and food additive regulatory filings with FDA and SAMR. Bottom-up volume modeling from identified production facilities triangulated against top-down demand estimates from end-use consumption patterns.
Forecast inputs considered thermal dehydration capacity expansion timelines, REACH registration compliance trajectories, and phosphate rock mining output fluctuations across the projection horizon. Segmentation dimensions modeled include product chemistry grade, application specification tier, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from slope analysis of historical volume trends adjusted for capacity commissioning schedules and regulatory inflection impacts. Industry-specific inputs incorporated electric furnace rebuild cycles and halal certification timeline compression effects.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by merchant compounders or accelerated ECHA evaluation timelines for novel flame-retardant grades would shift outcomes. Macroeconomic phosphate rock price spikes, regulatory divergence between FDA and EFSA purity mandates, or technological substitution by organic acidulants in pharmaceutical formulations would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Nonaisoprenol Market
Chemicals
Fine Chemicals Market
Chemicals
Integrated Chemistry Systems Market
Chemicals
Fluorene Market
Chemicals
Fatty Alcohol Market
Chemicals
Negative Photoresist Chemicals Market
Chemicals
Glyoxylic Acid Market
Chemicals
Methoprene Market
Chemicals
Europe Biguanide Market
Chemicals
Global Aldehyde Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Ferric Chloride Market
Chemicals
Copper Oxychloride Market
Chemicals
Ferric Oxide Market
Chemicals
Maleic Acid Market
Chemicals
Global Methyl Cellulose Market