
 Salt Hydrate Market | 2026-2036
Salt Hydrate Market Size, Share, and Industry Trends Forecast 2026-2036
Salt Hydrate Market Outlook
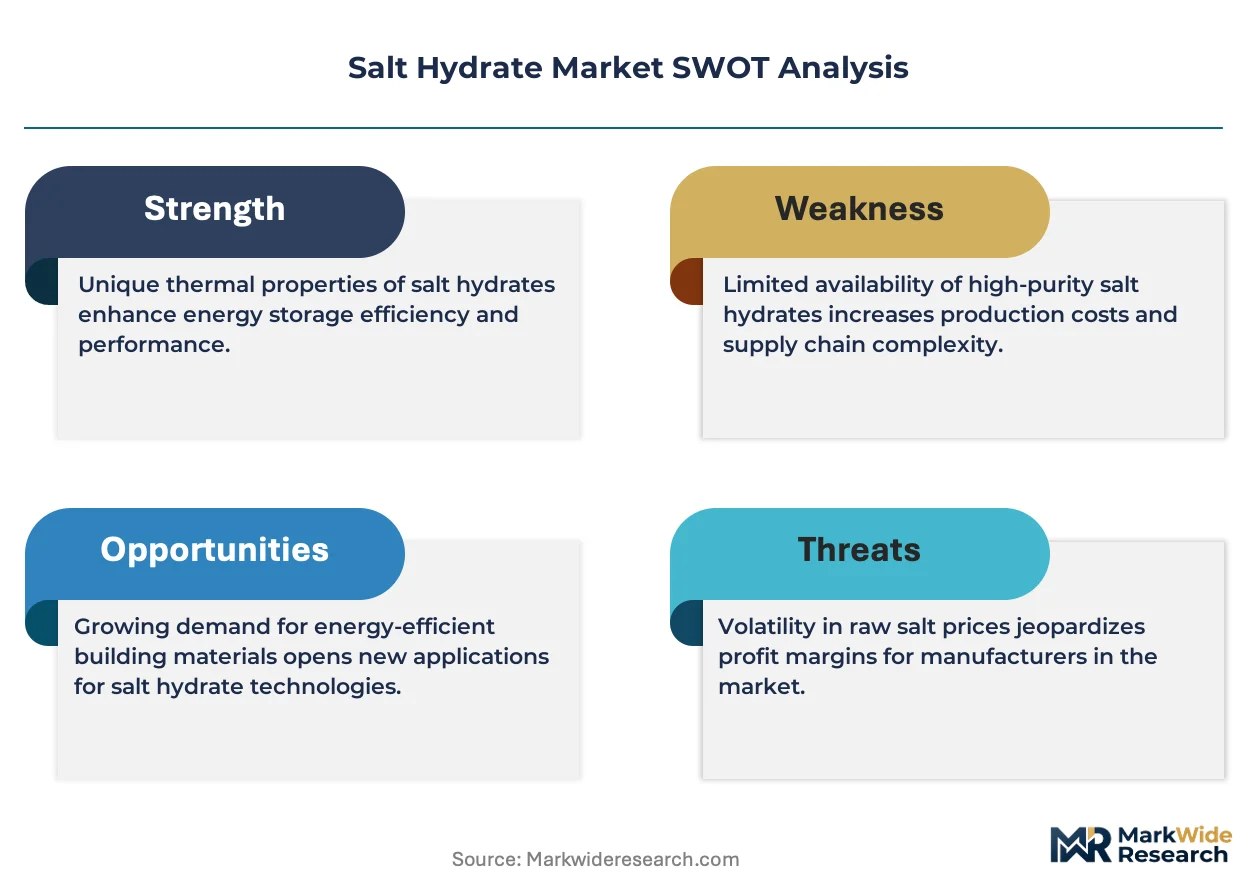
Asset-light leasing models for thermal energy storage systems is reconfiguring competitive entry barriers for smaller building operators. BASF SE leverages its integrated chemical production network to control feedstock costs for calcium chloride formulations. Rubitherm Technologies GmbH anchors its position through specialized R&D in encapsulated phase change materials. PCM Products Ltd competes on geographic reach across European industrial zones.
Salt hydrates are inorganic compounds that reversibly absorb and release latent heat at fixed temperatures through solid-liquid phase transitions, typically formulated with melting points between 15°C and 90°C for commercial thermal management applications. Energy storage applications lead volume demand as grid operators deploy salt hydrate tanks for load shifting and renewable integration. Temperature regulation in pharmaceutical cold chains represents the fastest-growing application segment, driven by stricter stability requirements for biologics distribution. HVAC systems remain a mature but steady outlet where salt hydrates displace conventional ice storage in commercial buildings seeking smaller footprint thermal banks.
The European Chemicals Agency enforces REACH compliance on salt hydrate formulations, restricting certain hydrate precursors and elevating purity standards for indoor applications. Germany's Federal Environment Agency implements building energy codes that explicitly credit phase change materials toward thermal inertia requirements. The U.S. EPA evaluates salt hydrate systems under its Significant New Alternatives Policy program for low-GWP thermal storage. Stakeholders must monitor how evolving refrigerant phase-down schedules in major economies redirect investment toward solid-state thermal storage chemistries.
Market Dynamics
Europe's F-Gas Regulation is compressing refrigerant availability and forcing HVAC manufacturers toward solid-state thermal storage chemistries, fundamentally restructuring competitive positioning across the salt hydrate value chain.
Growth Catalysts
- Biologics cold chain mandates:Stricter stability requirements for temperature-sensitive pharmaceuticals are accelerating phase change material adoption among distributors seeking passive thermal protection.
- Germany's building energy codes:Federal Environment Agency regulations explicitly credit phase change materials toward thermal inertia requirements, creating direct procurement pull from commercial construction.
- Calcium chloride feedstock integration:Integrated chemical production networks enable captive supply of hydrate precursors, compressing input cost volatility for system manufacturers.
Market Restraints
- REACH compliance costs:European Chemicals Agency restrictions on certain hydrate precursors elevate purity standards and testing burdens for indoor applications.
- Supercooling instability:Technical limitations in nucleation control reduce thermal reliability in sodium sulfate decahydrate formulations below commercial thresholds.
- Organic PCM substitution:Bio-based paraffin alternatives capture premium HVAC segments where footprint constraints matter less than temperature precision.
Strategic Opportunities
- India's pharmaceutical logistics expansion:Cold chain infrastructure gaps in biologics distribution create first-mover positioning for encapsulated salt hydrate systems.
- Grid-scale thermal storage:Utility load-shifting applications represent underpenetrated volume demand as renewable integration mandates intensify.
- Asset-light leasing models:Thermal energy storage-as-a-service contracts reconfigure capital barriers for smaller building operators seeking retrofit flexibility.
Industry Challenges
- Encapsulation engineering talent scarcity:Specialized R&D capabilities in micro-encapsulation chemistry concentrate among limited technical workforces in Germany and Japan.
- Multi-year certification timelines:EPA Significant New Alternatives Policy evaluation cycles delay commercial deployment for novel hydrate formulations in US HVAC applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salt Hydrate Market |
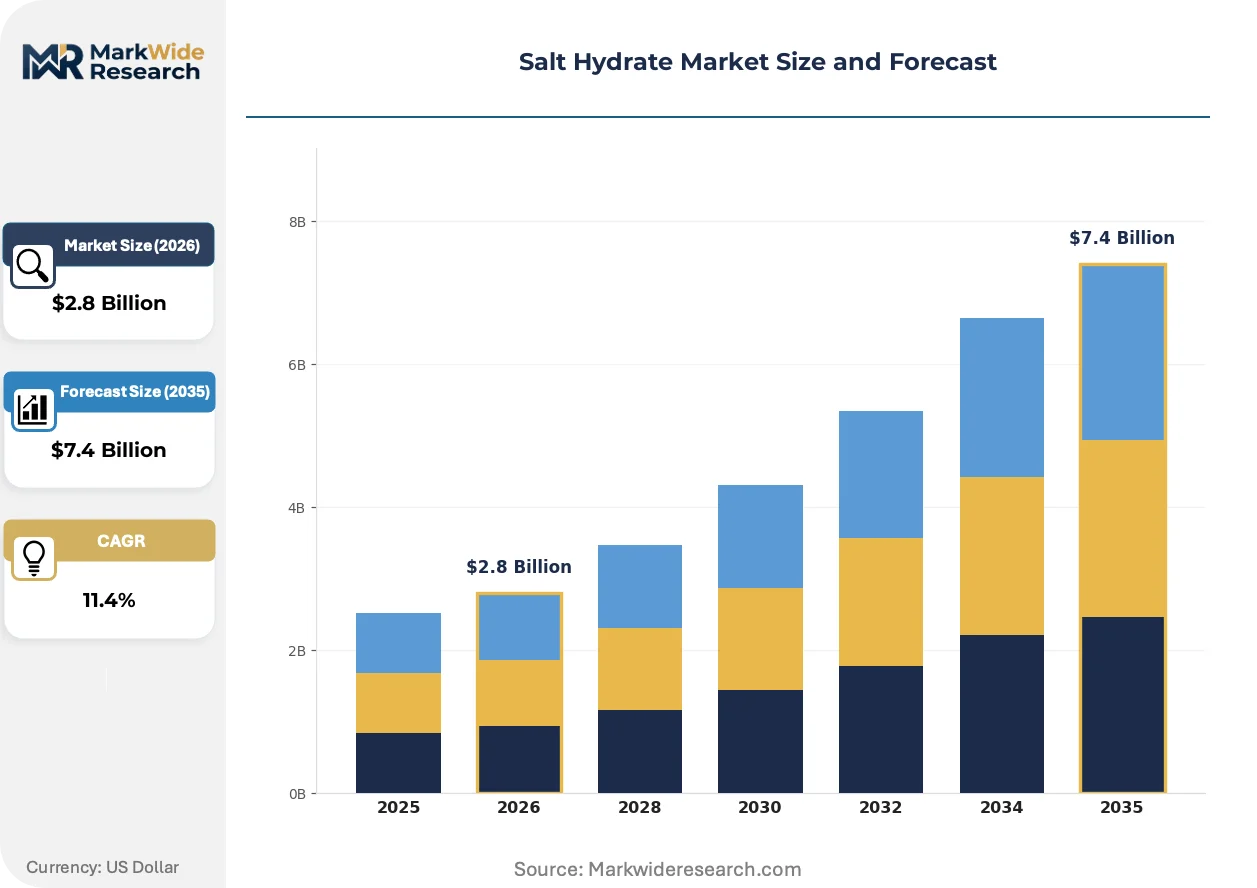
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Chloride, Sodium Sulfate, Magnesium Chloride, Lithium Bromide Application: Energy Storage, Temperature Regulation, Construction Materials, HVAC Systems Form: Granular, Powder, Liquid, Crystalline End User: Manufacturing, Chemical Processing, Renewable Energy, Construction |
| Companies Covered | Rubitherm Technologies GmbH, PCM Products Ltd, Phase Change Products Pty Ltd, Phase Change Energy Solutions Inc., Climator Sweden AB, Pluss Advanced Technologies Pvt. Ltd., RGEES LLC, Salca B.V., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salt Hydrate Market Strategic Shifts
Formulation chemistry and containment engineering are converging to expand operational temperature ranges while regulatory pressure on synthetic refrigerants accelerates solid-state thermal storage deployment across commercial building systems.
Encapsulated salt hydrate composites with engineered nucleation agents are collapsing the performance gap against organic phase change materials in HVAC thermal banking applications. Commercial real estate developers in Germany and the Netherlands are specifying these systems for peak load shaving. The technology is collapsing installed cost premiums versus conventional ice storage by eliminating chiller redundancy requirements.
Europe's F-Gas Regulation phase-down schedule is redirecting manufacturer R&D investment toward inorganic thermal storage chemistries with negligible global warming potential. HVAC OEMs face compressed refrigerant supply quotas through 2030. Commercial building retrofits in France and Italy are prioritizing salt hydrate tanks over mechanical compression systems to preempt compliance exposure.
Leasing structures for thermal energy storage assets are displacing capital purchase models among mid-size building operators seeking operational expenditure treatment. Energy service companies in Germany are bundling storage hardware with performance guarantees. This shift is most visible in chemical processing clusters around Ludwigshafen and Leverkusen where facility managers prioritize balance sheet flexibility over equipment ownership.
Salt Hydrate Market Segmentation
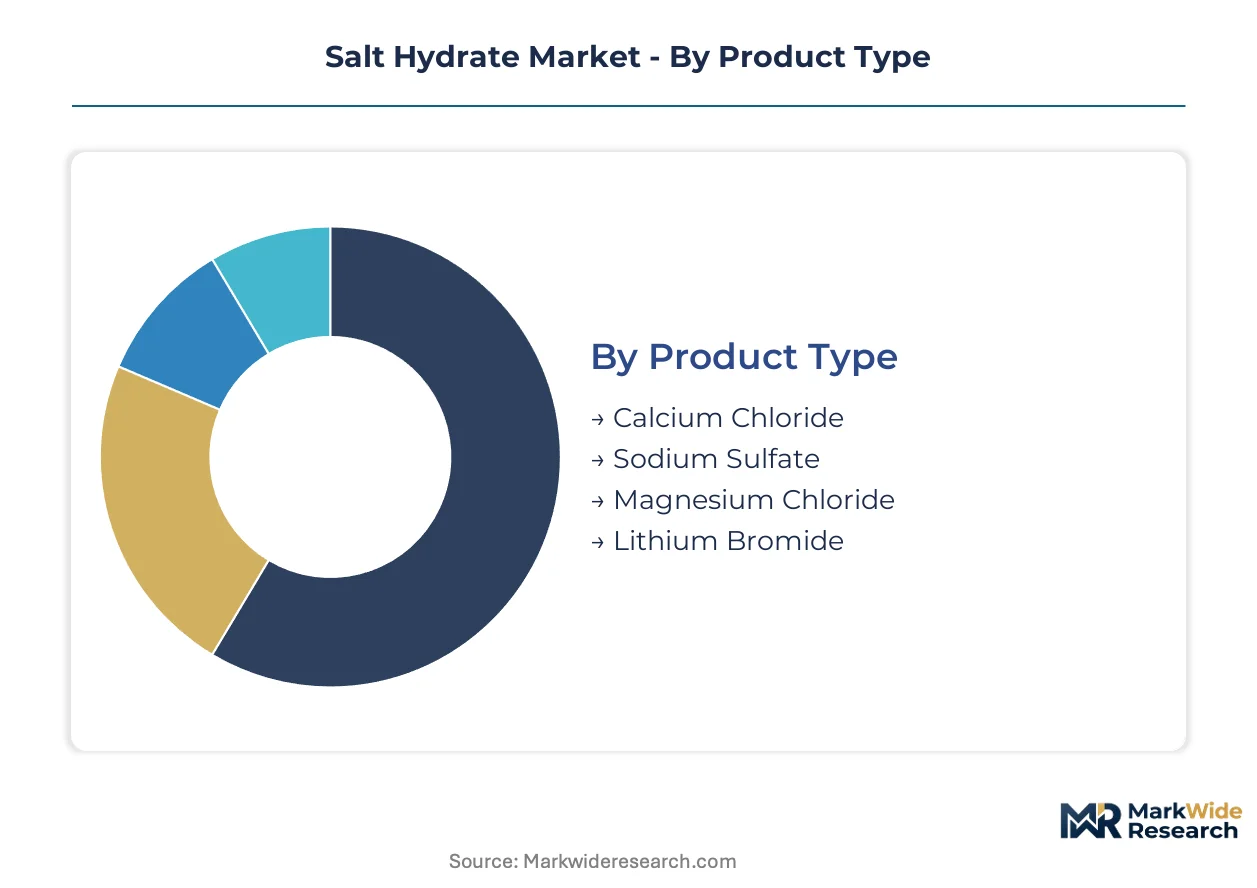
Salt hydrate formulations diverge sharply across thermal performance characteristics, end-use reliability requirements, and regulatory compliance burdens. Each segmentation axis reveals distinct competitive dynamics between incumbent mineral suppliers and specialized phase change material developers.
Product Type:
Mature commodity hydrates dominate volume while emerging formulations target precision thermal management applications.
- Calcium Chloride:Hydrated calcium chloride operates across the broadest commercial temperature range from -51°C to 30°C, making it the default choice for cold chain logistics and industrial dehumidification. Demand concentrates in Germany's chemical processing clusters where BASF SE and Lanxess AG deploy captive production for thermal storage systems.
- Sodium Sulfate:Glauber's salt formulations provide latent heat storage at 32°C with exceptional cost positioning, though supercooling instability limits deployment to controlled industrial environments. German building energy codes explicitly credit sodium sulfate decahydrate systems toward thermal inertia requirements in commercial construction.
- Magnesium Chloride:Hexahydrate variants serve niche desiccant and de-icing applications with hygroscopic properties that limit phase change cycling durability.
- Lithium Bromide:Premium absorption chiller applications absorb-refrigerant pairs in commercial HVAC, restricted by lithium supply cost volatility and REACH precursor scrutiny.
Calcium chloride retains volume leadership; lithium bromide holds the steepest expansion curve in premium thermal management.
Application:
Application segmentation tracks the migration from passive thermal mass toward active energy arbitrage and pharmaceutical protection systems.
- Energy Storage:Grid-scale salt hydrate tanks enable load shifting for renewable integration, with utility procurement concentrated in Germany and the Netherlands where building codes mandate thermal inertia. ECHA REACH compliance elevates purity standards for indoor installations.
- Temperature Regulation:Encapsulated phase change materials protect biologics distribution across Europe's pharmaceutical cold chains, driven by EMA stability requirements for temperature-sensitive therapeutics.
- Construction Materials:Plaster and concrete admixtures leverage salt hydrates for passive thermal mass in commercial buildings, facing substitution pressure from bio-based alternatives.
- HVAC Systems:Ice storage displacement continues in French and Italian commercial retrofits seeking F-Gas Regulation compliance through solid-state thermal banking.
Energy storage commands the largest installed base; temperature regulation is expanding most quickly in biologics distribution.
Form:
Physical form determines encapsulation engineering requirements and handling economics across industrial procurement workflows.
- Granular:Free-flowing granules suit bulk tank filling and industrial-scale thermal storage, with German chemical processors preferring this form for automated handling systems around Ludwigshafen.
- Powder:Fine particle sizes enable homogeneous dispersion in construction admixtures and composite materials, though dust exposure triggers stricter ECHA workplace exposure limits.
- Liquid:Pre-hydrated solutions eliminate dissolution energy penalties in absorption chiller applications, common in French district cooling networks.
- Crystalline:High-purity crystals serve laboratory and pharmaceutical-grade thermal management where nucleation control is critical.
Granular forms dominate industrial procurement; crystalline grades command premium positioning in pharmaceutical applications.
End User:
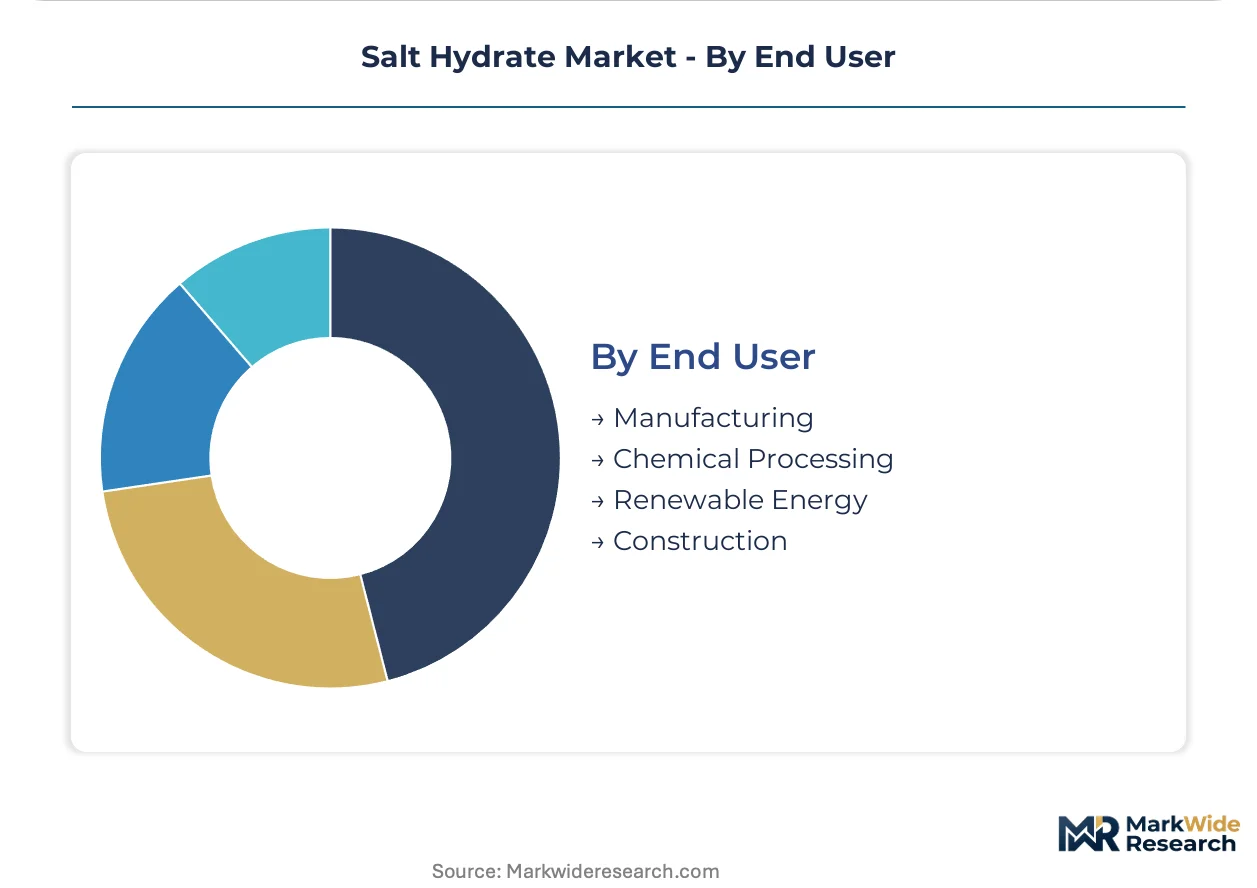
End user segmentation reflects divergent procurement sophistication between process industries and emerging renewable energy developers.
- Manufacturing:Automotive and electronics producers deploy salt hydrate thermal buffering for precision temperature control in cleanroom environments, with German OEMs specifying REACH-compliant formulations.
- Chemical Processing:Integrated producers like BASF SE consume captive hydrate supplies for exothermic reaction management and solvent recovery systems.
- Renewable Energy:Utility-scale solar and wind developers procure salt hydrate storage for grid stabilization, constrained by multi-year ECHA substance evaluation timelines for novel formulations.
- Construction:Commercial developers in the Netherlands specify phase change materials for peak load shaving, supported by national building codes that credit thermal inertia toward energy performance certificates.
Chemical processing absorbs the highest volume; renewable energy developers are gaining share fastest as grid integration mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in salt hydrates track chemical production networks and cold chain infrastructure investments. Germany and the United States run structural surpluses in formulated phase change materials. India and China remain net importers of encapsulated systems despite expanding domestic hydrate production.
Germany
Ludwigshafen and Leverkusen chemical clusters drive captive consumption of calcium chloride hydrates for thermal storage systems. The Federal Environment Agency credits phase change materials toward building energy code compliance, accelerating commercial construction procurement. BASF SE's integrated production network supplies hydrate precursors to regional HVAC manufacturers facing F-Gas Regulation quotas.
United States
Pharmaceutical distributors in the Northeast and California deploy salt hydrate systems for biologics cold chain protection. EPA Significant New Alternatives Policy evaluation cycles constrain novel formulation deployment in HVAC retrofits. Texas and Arizona utility operators pilot grid-scale thermal storage for renewable load shifting.
India
Cold chain infrastructure gaps in biologics distribution create demand for encapsulated salt hydrate shipping containers. CDSCO stability requirements for temperature-sensitive therapeutics mandate passive thermal protection. Maharashtra and Gujarat pharmaceutical hubs import formulated systems while domestic hydrate production concentrates in Gujarat chemical zones.
China
Dual carbon goals accelerate utility procurement of thermal storage for grid flexibility. Yangtze River Delta manufacturing clusters absorb hydrate volumes for precision temperature control in electronics cleanrooms. NMPA pharmaceutical regulations increasingly align with ICH stability standards, elevating cold chain equipment specifications.
Netherlands
Rotterdam port logistics operators specify salt hydrate thermal banking for pharmaceutical transshipment. National building codes credit phase change materials toward energy performance certificates, pulling commercial developer procurement. Randstad construction activity concentrates demand for plaster and concrete admixtures.
Salt Hydrate Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying formulated hydrates and encapsulation engineering. Market structure tilts toward consolidation among integrated chemical producers while specialized phase change material developers fragment across application niches. Two strategic archetypes dominate: captive chemical producers leveraging feedstock integration, and R&D-focused encapsulation specialists. Competitive moves concentrate on backward integration into hydrate precursor production and technology licensing partnerships for nucleation control.
Among German-based developers, Rubitherm Technologies GmbH exemplifies the encapsulation-specialist archetype through concentrated R&D capabilities. BASF SE anchors the integrated-producer tier with captive supply networks for calcium chloride formulations. PCM Products Ltd represents geographic-reach positioning across European industrial zones. These three occupy distinct competitive spaces rather than direct confrontation.
| Leading Market Players |
|---|
| Rubitherm Technologies GmbH |
| PCM Products Ltd |
| Phase Change Products Pty Ltd |
| Phase Change Energy Solutions Inc. |
| Climator Sweden AB |
| Pluss Advanced Technologies Pvt. Ltd. |
| RGEES LLC |
| Salca B.V. |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
German chemical clusters around Ludwigshafen and Leverkusen concentrate calcium chloride feedstock production, anchoring margin capture upstream while downstream system integrators compete on encapsulation engineering and thermal performance guarantees.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scaled tiering. Price differentiation separates REACH-certified pharmaceutical grades from standard industrial formulations, with certification level and customization depth as primary drivers. Cost compression in commodity hydrate tiers is intensifying as captive producers leverage integrated feedstock networks. Chemical processing end-users exhibit lowest price sensitivity due to thermal reliability requirements, while construction material distributors face acute margin pressure from bio-based PCM substitutes.
Supply Chain Analysis
Calcium chloride and sodium sulfate precursors draw from Germany, China, and the United States as dominant production geographies. Raw material sourcing rests on brine extraction operations, chlor-alkali co-production streams, and synthetic sulfate processing. Single-source vulnerability concentrates in specialized nucleation agent supply for supercooling control formulations. Distribution runs through integrated chemical distributors serving HVAC OEMs and pharmaceutical packaging specialists, with direct procurement relationships dominating bulk industrial offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Salt hydrate thermal storage is approaching a platform-economics inflection as leasing-as-a-service models decouple hardware ownership from thermal performance outcomes, creating interoperability standards between energy service companies and building management systems.
For Market Incumbents: Insulate core formulation margins by deepening captive supply of hydrate precursors through backward integration into brine extraction networks. Prioritize nucleation control R&D to close performance gaps against organic PCM substitutes in precision HVAC applications. Lock in long-term supply agreements with pharmaceutical distributors facing EMA stability mandate deadlines.
For New Entrants and Emerging Players: India's pharmaceutical logistics corridors present the most penetrable white-space for encapsulated salt hydrate shipping systems, with CDSCO cold chain regulations mandating passive thermal protection that domestic suppliers currently underserve. Target Maharashtra and Gujarat biologics hubs with asset-light leasing models that convert capital expenditure to operational expenditure treatment. Partner with regional 3PL operators for last-mile distribution infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed encapsulation specialists holding concentrated R&D talent in Germany and Japan. Long-term viability hinges on regulatory tailwinds from F-Gas phase-down schedules and building energy code thermal inertia credits. Monitor EPA SNAP evaluation timelines as inflection signals for US HVAC market entry viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Extraction | BASF SE's captive calcium chloride network compresses input cost volatility for thermal storage system manufacturing. |
| Encapsulation Technology Licensing | Rubitherm Technologies GmbH's nucleation control patents enable HVAC OEMs to displace conventional ice storage in F-Gas-regulated markets. |
| Asset-Light Leasing Model Expansion | German energy service companies bundle thermal storage hardware with performance guarantees across Ludwigshafen chemical processing clusters. |
| REACH Compliance Certification Investment | ECHA purity standards for indoor applications elevate barriers against uncertified hydrate imports from non-EU production zones. |
| Pharmaceutical Cold Chain Partnership | EMA biologics stability requirements pull encapsulated PCM adoption among distributors seeking passive thermal protection for temperature-sensitive therapeutics. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ECHA substance registration databases, customs trade flow records, and building energy code regulatory filings. Interviews with thermal storage system procurement managers at pharmaceutical distributors, HVAC OEM technical directors, and chemical plant operations heads informed demand-side validation. Bottom-up volume estimates triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs span hydrate formulation chemistry, encapsulation engineering maturity, and regulatory compliance trajectory. Segmentation dimensions modeled include product type tier, application end-use, physical form factor, and regional production cluster concentration. CAGRs derived from elasticity-adjusted demand projections incorporating F-Gas Regulation phase-down schedules and pharmaceutical cold chain infrastructure buildout rates. Renewable integration mandates and building energy code thermal inertia credits shaped scenario-weighted outcomes.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese hydrate producers or accelerated EPA SNAP approval timelines would shift outcomes. Cross-checking against IEA thermal storage deployment benchmarks and EMA pharmaceutical distribution audits is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Protein Purification Resin Market
Specialty Chemicals
Distarch Phosphate Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Cellulose Esters and Ethers Market
Specialty Chemicals
Glucono Delta Lactone Market
Specialty Chemicals
Monomethyl Acetoacetamide Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
Antifouling Agent Market
Specialty Chemicals
Monomethylsilanetriol Market
Specialty Chemicals
Bromocyclopentane Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Ethyl Ascorbic Acid Market