
 Europe Hydrazine Market | 2026-2036
Europe Hydrazine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hydrazine Market Insights
European polymerization initiator procurement is pivoting toward fewer, larger chemical manufacturers with integrated formulation capabilities. Arkema S.A. leverages its backward integration into hydrazine derivatives to secure captive supply for European agrochemical clients. LANXESS AG anchors its position through specialized hydrazine-based blowing agent production serving automotive seating foam manufacturers. Lonza Group AG competes via pharmaceutical-grade hydrazine hydrate purification serving European active pharmaceutical ingredient producers.
Hydrazine refers to a colorless, flammable base with the formula N₂H₄, produced primarily through the Raschig process or ketazine route, functioning as a powerful reducing agent and chemical intermediate across industrial applications. Hydrazine hydrate dominates European product type volumes due to its versatility as a blowing agent precursor and water treatment chemical, while anhydrous hydrazine commands premium positioning for aerospace propulsion applications where moisture exclusion is critical. Aerospace end users concentrate demand for ultra-high-purity grades, whereas fertilizer producers absorb standard industrial hydrate volumes through bulk delivery arrangements.
REACH registration requirements administered by ECHA mandate comprehensive toxicity dossiers for hydrazine hydrate imports, elevating compliance costs for non-European suppliers. The EU Green Deal's chemical sustainability benchmarks are pressuring manufacturers to demonstrate lower-carbon production pathways for hydrazine derivatives. Germany's Federal Institute for Risk Assessment coordinates with EFSA to evaluate residual hydrazine levels in food-contact agricultural applications. Stakeholders must monitor evolving classification debates around hydrazine carcinogenicity status, as any reclassification would cascade through permissible exposure limits and end-use licensing across European manufacturing operations.
Market Dynamics
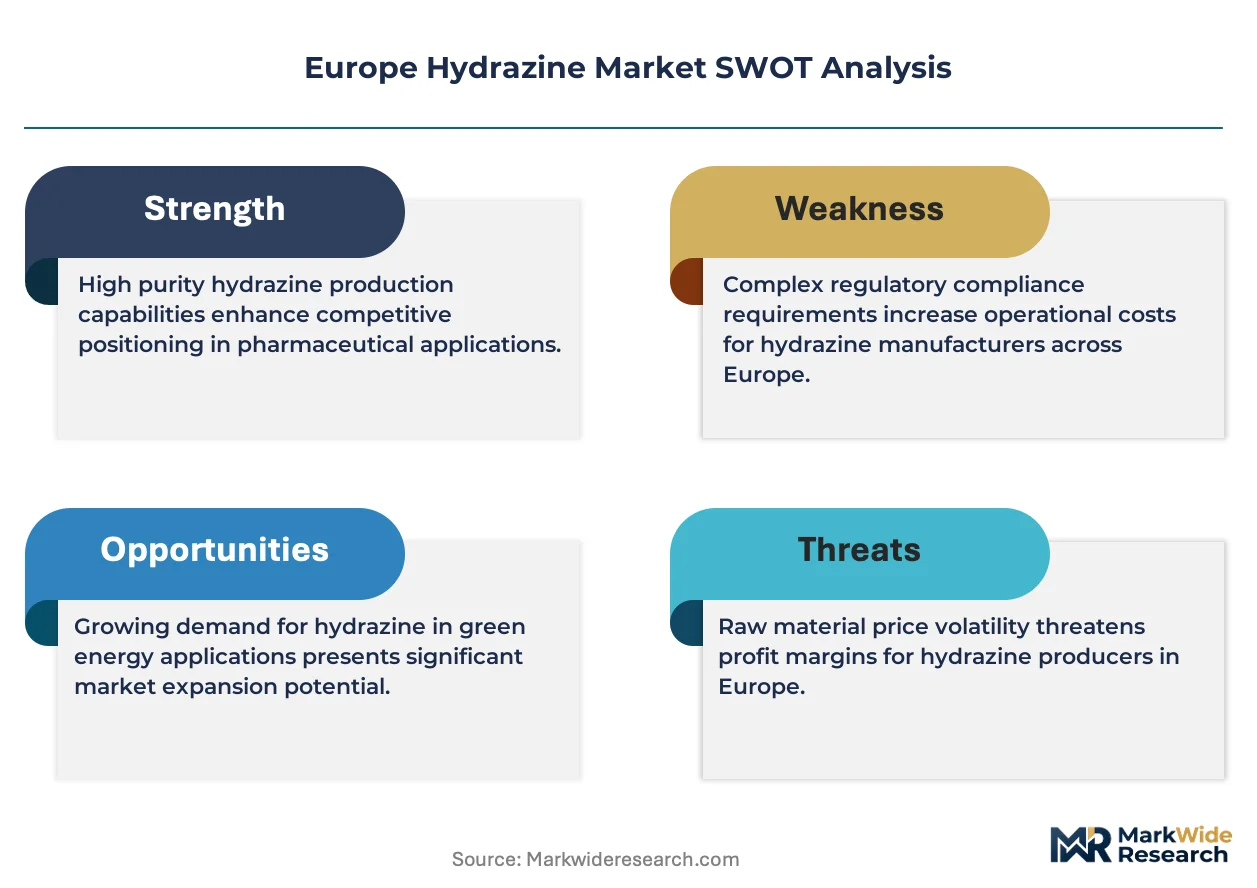
REACH chemical registration protocols administered by ECHA are tightening purity specifications for imported hydrazine hydrate, forcing European formulators to requalify supply chains and concentrate procurement among backward-integrated domestic producers with established dossier compliance.
Growth Catalysts
- Agrochemical polymerization demand:European fertilizer manufacturers are expanding hydrazine-derived blowing agent offtake for controlled-release coating applications, strengthening volume commitments from Rhine-Ruhr chemical corridor buyers.
- EU Green Deal chemical sustainability benchmarks:Manufacturers demonstrating lower-carbon production pathways for hydrazine derivatives gain preferential positioning in public procurement frameworks and industrial offtake agreements.
- Pharmaceutical-grade purification capabilities:Active pharmaceutical ingredient producers across Germany, Switzerland, and France are absorbing expanding volumes of ultra-high-purity hydrazine hydrate for oncology intermediate synthesis.
Market Restraints
- Feedstock energy cost volatility:Natural gas and ammonia input price swings compress margin stability for Raschig process operators, particularly affecting merchant hydrazine hydrate producers without integrated ammonia supply.
- Import supply concentration risk:Non-European hydrazine hydrate suppliers face elevated compliance costs from REACH registration requirements, reducing viable import alternatives and tightening European supply diversity.
- Substitution pressure from azodicarbonamide:Automotive seating foam manufacturers in Central Europe are evaluating alternative blowing agents with lower toxicity profiles, threatening standard-grade hydrazine hydrate volume retention.
Strategic Opportunities
- Underpenetrated Eastern European agrochemical markets:Polish and Romanian fertilizer formulators represent expansion targets for hydrazine-based polymerization initiators as these markets upgrade from commodity nitrogen products.
- EU F-Gas Regulation phase-down:Hydrazine-derived propellants for aerosol applications are capturing substitution demand as hydrofluorocarbon restrictions tighten across European personal care and industrial spray segments.
- CSRD-aligned supply chain disclosure:Hydrazine producers with verified Scope 3 carbon accounting can differentiate in sustainability-linked procurement tenders from European multinational chemical buyers.
Industry Challenges
- Process safety engineering talent scarcity:Specialized expertise in hydrazine handling, storage, and explosion prevention is concentrating among aging workforce cohorts in Germany's specialty chemical sector, constraining operational expansion.
- ECHA carcinogenicity reclassification exposure:Pending toxicity evaluations from Germany's Federal Institute for Risk Assessment could trigger cascading exposure limit reductions and end-use licensing restrictions across European manufacturing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hydrazine Market |
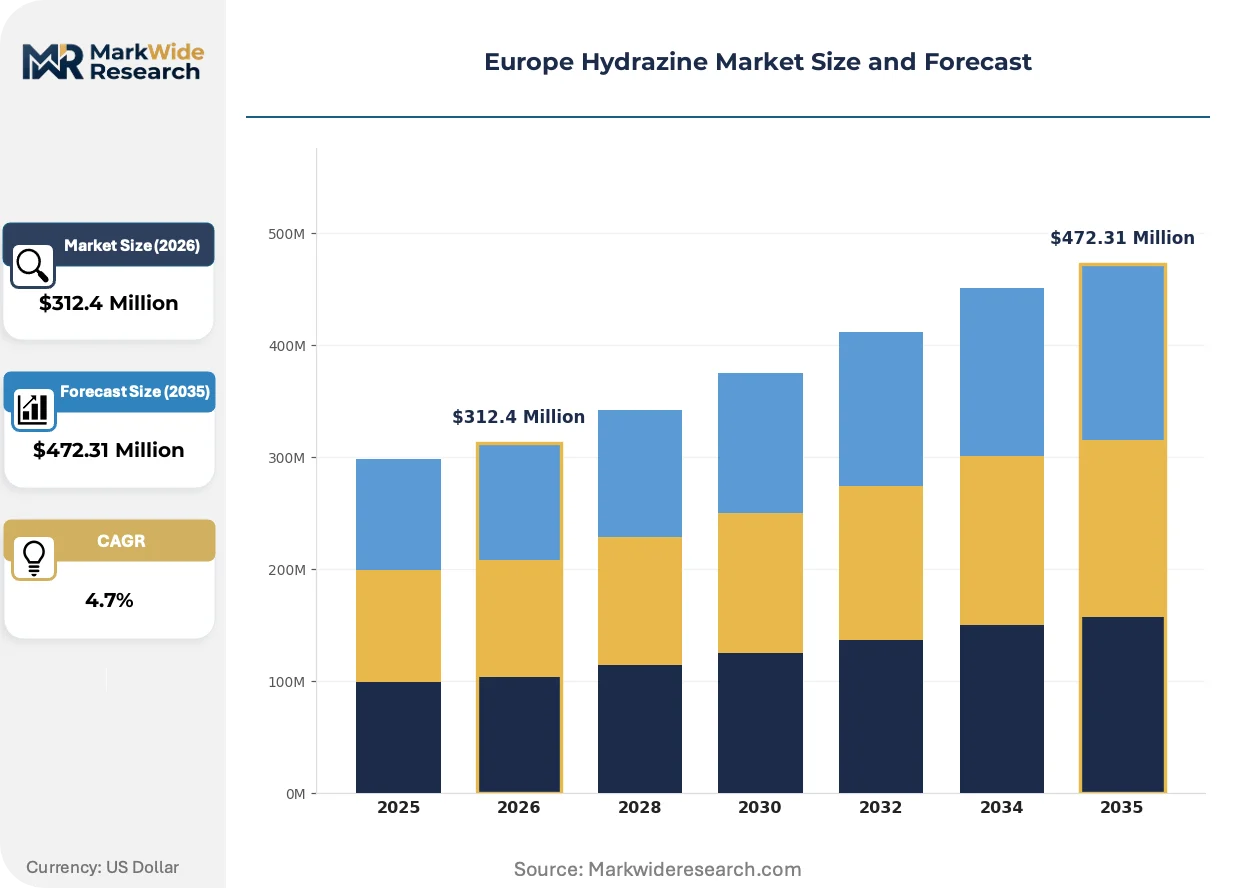
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrazine Hydrate, Anhydrous Hydrazine, Methyl Hydrazine, Dibenzylhydrazine Application: Aerospace, Agriculture, Automotive, Pharmaceuticals End User: Aerospace Industry, Chemical Manufacturers, Fertilizer Producers, Pharmaceutical Companies Delivery Mode: Tank Truck, Drums, ISO Containers, Bulk Delivery |
| Companies Covered | Arkema S.A., LANXESS AG, Lonza Group AG, LGC Science Group Holdings Limited, Otsuka Chemical Co., Ltd., Nippon Carbide Industries Co., Inc., Japan Finechem Co., Inc., Chemtex Speciality Ltd., GFS Chemicals Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hydrazine Market Trends and Innovations
European hydrazine manufacturing is pivoting toward modular process intensification and digitalized purity verification, driven by regulatory pressure for supply chain transparency and buyer demand for batch-level certification documentation.
Continuous-flow reactor technology for hydrazine hydrate synthesis is modularizing production economics for mid-scale European specialty chemical manufacturers. Pharmaceutical-grade formulators in Basel and Frankfurt are adopting these systems to reduce batch-to-batch variability. The technology is modularizing capital deployment patterns, enabling distributed production nodes that bypass traditional large-plant concentration.
REACH registration requirements administered by ECHA are mandating comprehensive toxicity dossier updates for hydrazine hydrate imports. Industrial chemical buyers are demanding supplier-provided exposure scenario documentation for downstream uses. Agrochemical formulators across Germany and France are most affected, accelerating partnerships with domestic producers holding valid registration certificates.
Buyer consolidation among European agrochemical multinationals is compressing supplier qualification cycles and unbundling technical service from commodity supply contracts. Specialty chemical distributors are losing share to direct manufacturer relationships as procurement functions centralize. This pattern is most visible in Germany's Rhine-Ruhr corridor, where three large formulators now account for the majority of polymerization initiator volume.
Europe Hydrazine Market Segmentation
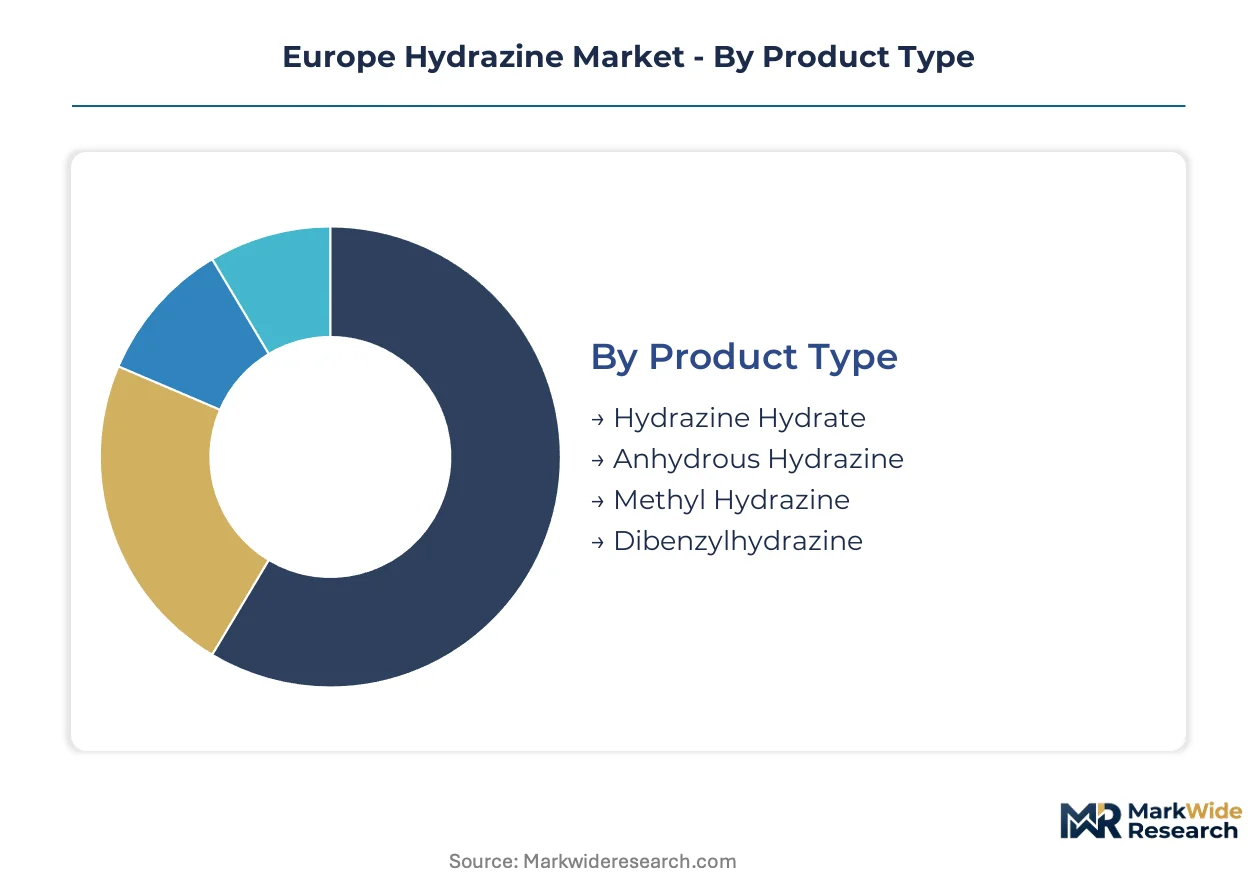
Segmentation in the European hydrazine market reflects divergent purity requirements and regulatory exposure across end-use verticals. Procurement patterns differ sharply between bulk agricultural buyers seeking standardized hydrate grades and aerospace contractors demanding certified anhydrous specifications.
Product Type:
Customization intensity spans from commodity hydrate volumes to aerospace-grade anhydrous specifications requiring moisture exclusion protocols.
- Hydrazine Hydrate:Aqueous solution containing 35-80% hydrazine by weight serves as the workhorse intermediate for blowing agent synthesis and water treatment chemistry. Rhine-Ruhr chemical corridor manufacturers absorb standard industrial grades through bulk delivery arrangements, though REACH registration costs are squeezing non-European import alternatives.
- Anhydrous Hydrazine:Ultra-high-purity grade with <0.5% water content commands premium positioning for satellite propulsion and missile fuel applications. Aerospace end users in France and Germany concentrate procurement among domestic producers with ECHA-validated toxicity dossiers.
- Methyl Hydrazine:Monomethyl derivative specialized for hypergolic rocket fuel formulations.
- Dibenzylhydrazine:Organic-substituted variant serving niche polymerization catalyst applications.
Leading the category by volume: Hydrazine Hydrate. Growing fastest: Anhydrous Hydrazine.
Application:
End-use concentration varies by margin structure, with pharmaceutical and aerospace segments defending price premiums against commoditized agricultural offtake.
- Aerospace:Propulsion-grade hydrazine demand centers on French and German defense contractors plus commercial satellite operators. ESA procurement frameworks specify ultra-high-purity anhydrous grades with batch-level certification documentation.
- Agriculture:Fertilizer manufacturers across Poland and Romania deploy hydrazine-derived polymerization initiators for controlled-release coating technologies. This segment absorbs standard hydrate volumes through seasonal procurement cycles tied to planting calendars.
- Automotive:Seating foam manufacturers in Czech Republic and Slovakia source hydrazine-based blowing agents, though azodicarbonamide substitution pressure is threatening volume retention.
- Pharmaceuticals:Basel and Frankfurt API producers require pharmaceutical-grade hydrate purification for oncology intermediate synthesis.
Dominating by revenue contribution: Aerospace. Expanding most quickly: Pharmaceuticals.
End User:
Customer scale dictates procurement modality, with multinational chemical manufacturers centralizing contracts while regional fertilizer distributors fragment purchasing.
- Aerospace Industry:Defense primes and satellite operators mandate dedicated supply security with explosion-prevention engineering protocols. German and French contractors maintain long-term offtake agreements with backward-integrated domestic producers.
- Chemical Manufacturers:Specialty chemical formulators in Germany's Rhine-Ruhr corridor concentrate polymerization initiator procurement among three large integrated suppliers.
- Fertilizer Producers:Eastern European agricultural compounders represent expansion targets as they upgrade from commodity nitrogen products.
- Pharmaceutical Companies:Swiss and German API manufacturers absorb expanding ultra-high-purity volumes for synthetic chemistry applications.
Highest volume concentration: Chemical Manufacturers. Steepest expansion trajectory: Pharmaceutical Companies.
Delivery Mode:
Logistics configuration tracks customer scale and safety infrastructure, with bulk systems serving integrated producers while packaged formats reach distributed formulators.
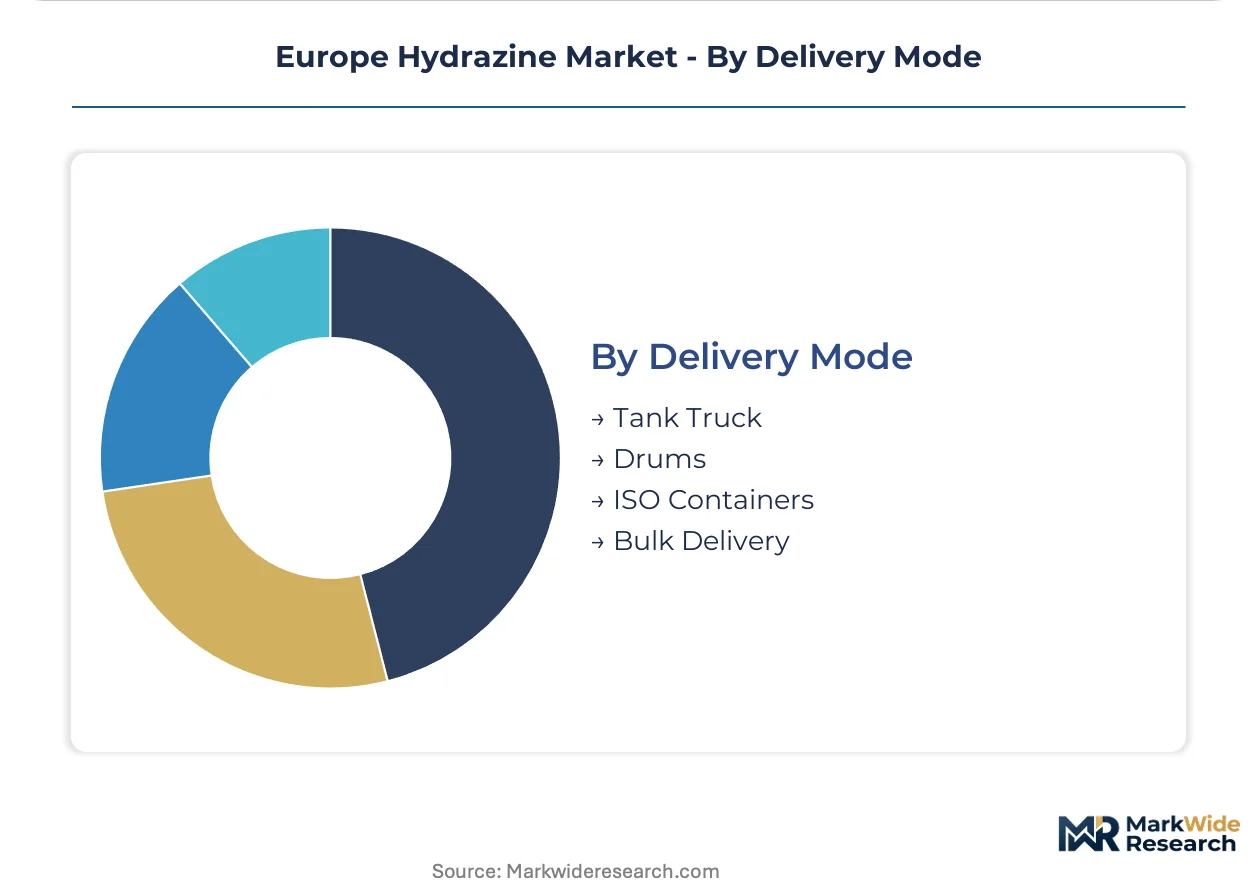
- Tank Truck:Dedicated road transport for high-volume Rhine-Ruhr chemical corridor deliveries. Requires specialized pressure-vessel certification and driver hazardous materials licensing under ADR regulations.
- Drums:Standard 200-liter steel packaging for mid-scale pharmaceutical and specialty chemical buyers. ECHA-mandated exposure scenario documentation accompanies each shipment for downstream use compliance.
- ISO Containers:Intermodal tank systems enabling cross-border European distribution without transloading.
- Bulk Delivery:Pipeline and dedicated storage terminal arrangements for largest integrated chemical manufacturers.
Primary volume channel: Tank Truck. Gaining share fastest: ISO Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's Rhine-Ruhr chemical corridor, where specialty chemical manufacturers maintain integrated procurement relationships with hydrazine derivative suppliers. REACH registration protocols administered by ECHA are reshaping supply chain geography across the continent.
Germany
Fertilizer manufacturers in the Rhine-Ruhr corridor absorb standard hydrazine hydrate volumes for controlled-release coating applications. The Federal Institute for Risk Assessment coordinates toxicity evaluations with EFSA regarding residual hydrazine in food-contact agricultural uses. Ludwigshafen and Leverkusen host backward-integrated chemical producers with established REACH dossier compliance.
France
Aerospace contractors concentrate procurement of ultra-high-purity anhydrous hydrazine for satellite propulsion and missile fuel formulations. ESA procurement frameworks mandate batch-level certification documentation for defense and commercial space applications. Toulouse and Paris-Saclay clusters anchor demand from defense primes and satellite operators.
Switzerland
Basel-based active pharmaceutical ingredient producers require pharmaceutical-grade hydrazine hydrate purification for oncology intermediate synthesis. Swissmedic maintains stringent manufacturing practice standards for synthetic chemistry inputs. The Basel pharmaceutical cluster absorbs expanding ultra-high-purity volumes through specialized distributor relationships.
Poland
Agricultural compounders represent expansion targets for hydrazine-based polymerization initiators as markets upgrade from commodity nitrogen products. EU Green Deal chemical sustainability benchmarks pressure manufacturers to demonstrate lower-carbon production pathways. Warsaw and Łódź fertilizer formulators are consolidating procurement among fewer, larger chemical suppliers.
United Kingdom
Specialty chemical distributors serve pharmaceutical and agrochemical formulators with hydrazine hydrate imports subject to REACH registration requirements. The Health and Safety Executive enforces exposure limits aligned with ECHA carcinogenicity classifications. Manchester and Liverpool chemical trading hubs manage cross-border distribution under post-Brexit regulatory frameworks.
Europe Hydrazine Market Competitive Landscape
German producers anchor one tier; Swiss and French specialists hold differentiated positions in pharmaceutical and aerospace segments. The vendor base concentrates among backward-integrated chemical manufacturers with captive hydrazine derivative production. Three strategic archetypes dominate: integrated specialty chemical conglomerates, pharmaceutical-grade purification specialists, and aerospace-focused propellant suppliers. Competitive moves center on REACH dossier maintenance and modular process intensification technology licensing.
Within the integrated specialty chemical tier, Arkema S.A. and LANXESS AG represent archetypal positions. Arkema exemplifies backward-integrated supply security for European agrochemical clients, while LANXESS anchors blowing agent production serving automotive seating foam manufacturers. Lonza Group AG occupies the pharmaceutical-grade purification specialist position, serving Basel and Frankfurt API producers with ultra-high-purity hydrate capabilities.
| Leading Market Players |
|---|
| Arkema S.A. |
| LANXESS AG |
| Lonza Group AG |
| LGC Science Group Holdings Limited |
| Otsuka Chemical Co., Ltd. |
| Nippon Carbide Industries Co., Inc. |
| Japan Finechem Co., Inc. |
| Chemtex Speciality Ltd. |
| GFS Chemicals Inc. |
| Others |
Pricing and Supply Chain Analysis
Backward integration into ammonia feedstock anchors supply security for Rhine-Ruhr hydrazine producers, simultaneously insulating margin structures from natural gas volatility and enabling premium positioning against import-dependent competitors. This captive supply architecture concentrates pricing power among German integrated manufacturers while REACH compliance costs compress viable alternatives.
Pricing Analysis
Volume-mass fertilizer buyers absorb standard hydrazine hydrate grades through seasonal bulk contracts, while aerospace and pharmaceutical segments defend substantial premiums for certified anhydrous specifications. Three-tier pricing structure across aerospace-certified, pharmaceutical-grade, and industrial-standard levels tracks purity certification and batch documentation intensity. Cost compression in automotive blowing agent tiers is intensifying because azodicarbonamide substitution threatens volume retention. Fertilizer compounders exhibit highest price sensitivity due to commodity nitrogen margin pressure, whereas satellite propulsion contractors prioritize supply security over unit economics.
Supply Chain Analysis
ECHA REACH dossier validation gates supplier qualification, eliminating non-European import alternatives and tightening procurement concentration among domestic producers with established toxicity documentation. Manufacturing concentrates in Germany, France, and Switzerland, with raw material draws from ammonia crackers and natural gas reformers across the Rhine corridor. Single-source vulnerability runs through aging process safety engineering talent pools in German specialty chemical clusters. Distribution runs through dedicated tank truck networks for Rhine-Ruhr integrated buyers, with ISO container intermodal gaining share for cross-border pharmaceutical and aerospace deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe hydrazine market is accelerating into a vertical-integration race where upstream ammonia control and downstream formulation capabilities determine competitive survival. Players lacking captive feedstock or certified purification assets face systematic margin compression.
For Market Incumbents: Anchor supply security through modular process intensification licensing to Eastern European partners, preempting import substitution before Polish and Romanian fertilizer markets consolidate procurement. Invest in pharmaceutical-grade purification capacity expansion at Basel and Frankfurt nodes to capture oncology intermediate synthesis demand from Swiss and German API producers. Defend against azodicarbonamide displacement in automotive seating foam by embedding technical service into long-term blowing agent contracts.
For New Entrants and Emerging Players: Capture underpenetrated Eastern European agrochemical demand by deploying continuous-flow reactor technology for distributed hydrazine hydrate production near Polish fertilizer compounders. Target pharmaceutical-grade hydrate purification as the most penetrable segment, where Swissmedic and EMA certification requirements create defensible moats against commodity competition. Pursue sustainability-linked procurement tenders from CSRD-aligned multinational chemical buyers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty chemical conglomerates seeking backward integration into hydrazine derivatives for captive agrochemical formulation supply. Long-term viability hinges on REACH dossier maintenance capabilities and demonstrated lower-carbon production pathways under EU Green Deal benchmarks. Watch for ECHA carcinogenicity reclassification decisions as the critical inflection signal that would cascade through exposure limits and end-use licensing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Feedstock | Captive supply from Ludwigshafen crackers insulates margin structures from natural gas price volatility. |
| Pharmaceutical-Grade Purification Capacity Expansion | Basel and Frankfurt API producers absorb expanding ultra-high-purity volumes for oncology synthesis. |
| REACH Dossier Maintenance Investment | ECHA-validated toxicity documentation gates supplier qualification for European aerospace contractors. |
| Modular Process Intensification Licensing | Continuous-flow reactor technology enables distributed production nodes bypassing large-plant concentration. |
| Long-Term Supply Agreement with Agrochemical Formulators | Rhine-Ruhr chemical corridor buyers concentrate procurement among three backward-integrated suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with plant managers at Rhine-Ruhr hydrazine derivative facilities, procurement leads at German agrochemical formulators, distribution channel partners serving Swiss pharmaceutical clusters, and technical R&D directors specializing in blowing agent synthesis. Bottom-up volume triangulation across polymerization initiator offtake, propellant procurement, and pharmaceutical hydrate demand reconciled with top-down chemical industry production estimates.
Data-stream reconciliation across customs import volumes, ECHA registration certificates, and downstream formulation capacity underpinned the analytical framework. Segmentation dimensions modeled include product purity tier, end-use industry vertical, delivery logistics configuration, and regional production hub concentration. CAGRs were derived from regression analysis of historical offtake patterns and projected capacity expansion timelines, incorporating natural gas price elasticity assumptions and REACH compliance cost trajectories.
The model holds under stable ECHA carcinogenicity classification and sustained EU Green Deal chemical sustainability benchmarks; deviation in regulatory reclassification or feedstock cost spikes would shift volume and value projections. A model refresh is warranted upon material change in ECHA toxicity evaluation outcomes or German Federal Institute for Risk Assessment exposure limit recommendations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Household Insecticides Market
Chemicals
Coal Tar Market
Chemicals
United Kingdom Methanol Market
Chemicals
Trichloroisocyanuric Acid Market
Chemicals
North America Methanol Market
Chemicals
Global Thiophene Market
Chemicals
Ethyl Chloride Market
Chemicals
Fluorochemicals Market
Chemicals
Acetic Ether Market
Chemicals
Calcium Carbide Market
Chemicals
Precious Metal Plating Chemicals Market
Chemicals
Menadione Market
Chemicals
Mercury (I) Sulphate Market
Chemicals
N-Acetyl D-Neuraminic Acid Market
Chemicals
Zinc Chemicals Market
Chemicals
Fluorine Derivatives Market