
 3-Dimethylacrylic Acid Methyl Ester Market | 2026-2036
3-Dimethylacrylic Acid Methyl Ester Market Size, Share, and Industry Trends Forecast 2026-2036
3-Dimethylacrylic Acid Methyl Ester Market Outlook
REACH registration requirements for specialty monomers is consolidating the European supplier base around established registrants. WeylChem International GmbH leverages its integrated Frankfurt-Höchst manufacturing complex to sustain cost-competitive supply of high-purity methyl ester batches. Qingdao Bangli Chemical Co., Ltd. anchors its position through captive acrylic acid derivatives capacity in Shandong province. TCI Chemicals differentiates via its catalog-grade specialty chemical distribution network spanning Asia-Pacific research markets.
3-Dimethylacrylic acid methyl ester is an unsaturated ester compound synthesized through esterification of dimethylacrylic acid with methanol, typically yielding a colorless liquid with defined boiling point and reactivity suited for radical polymerization applications. The chemical functions primarily as a reactive monomer building block in copolymer systems for coatings, adhesives, and pharmaceutical intermediate synthesis. Monomer-grade product lines dominate current revenue contribution given their direct integration into acrylic copolymer manufacturing for industrial coatings. Batch production technology still occupies the majority of installed capacity, though continuous processing installations are capturing interest from large-volume purchasers seeking lot-to-lot consistency for sealant formulations. Green chemistry process variants represent the fastest-growing technology category as brand-owner sustainability protocols begin filtering into specialty ester procurement specifications.
EPA toxic substance control provisions and OSHA process safety management standards govern US-based handling and synthesis operations, while China's MEE enforces increasingly stringent VOC emission limits at esterification facilities. EMA pharmaceutical quality guidelines and ICH Q3C residual solvent specifications shape demand profiles for GMP-grade methyl ester used in active pharmaceutical ingredient synthesis. Stakeholders must monitor evolving dual-use chemical export control classifications and biobased feedstock certification schemes as these frameworks increasingly determine market access eligibility and premium pricing qualification.
Market Dynamics
REACH registration consolidation in Europe and MEE emission enforcement in China are compressing the supplier base while concentrating production in integrated chemical parks that can absorb compliance costs.
Growth Catalysts
- Pharmaceutical intermediate demand:GMP-grade methyl ester consumption for active pharmaceutical ingredient synthesis is accelerating under EMA and ICH Q3C residual solvent specifications.
- REACH compliance:Registration requirements for specialty monomers are eliminating unregistered competitors and securing volume commitments from established registrants.
- Integrated chemical parks:Shandong and Jiangsu province clusters offer captive feedstock access and shared emission treatment infrastructure that lowers unit production costs.
Market Restraints
- Methanol price volatility:Esterification feedstock costs fluctuate with natural gas and coal pricing, compressing batch producers without long-term supply agreements.
- Supplier concentration risk:European supply depends on a shrinking pool of REACH-registered facilities, creating single-source vulnerability for specialty coatings formulators.
- Substitution pressure:Bio-based acrylate alternatives and methacrylate copolymers threaten methyl ester share in low-performance adhesive applications.
Strategic Opportunities
- Green chemistry certification:Brand-owner sustainability protocols are creating premium pricing tiers for bio-based feedstock variants with third-party certification.
- Continuous processing technology:Large-volume sealant manufacturers are seeking lot-to-lot consistency that batch reactors cannot deliver, opening equipment upgrade contracts.
- Dual-use export controls:Evolving chemical weapons precursor classifications present compliance service opportunities for specialized trade consultants.
Industry Challenges
- Process safety engineering shortage:OSHA PSM and MEE safety audit requirements exceed available qualified personnel for esterification facility upgrades.
- Legacy batch reactor retrofit costs:Capital intensity for continuous processing conversion strains mid-cap producers without project finance access.
- GMP certification timelines:EMA pharmaceutical quality guideline compliance delays market entry for API-grade methyl ester by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3-Dimethylacrylic Acid Methyl Ester Market |
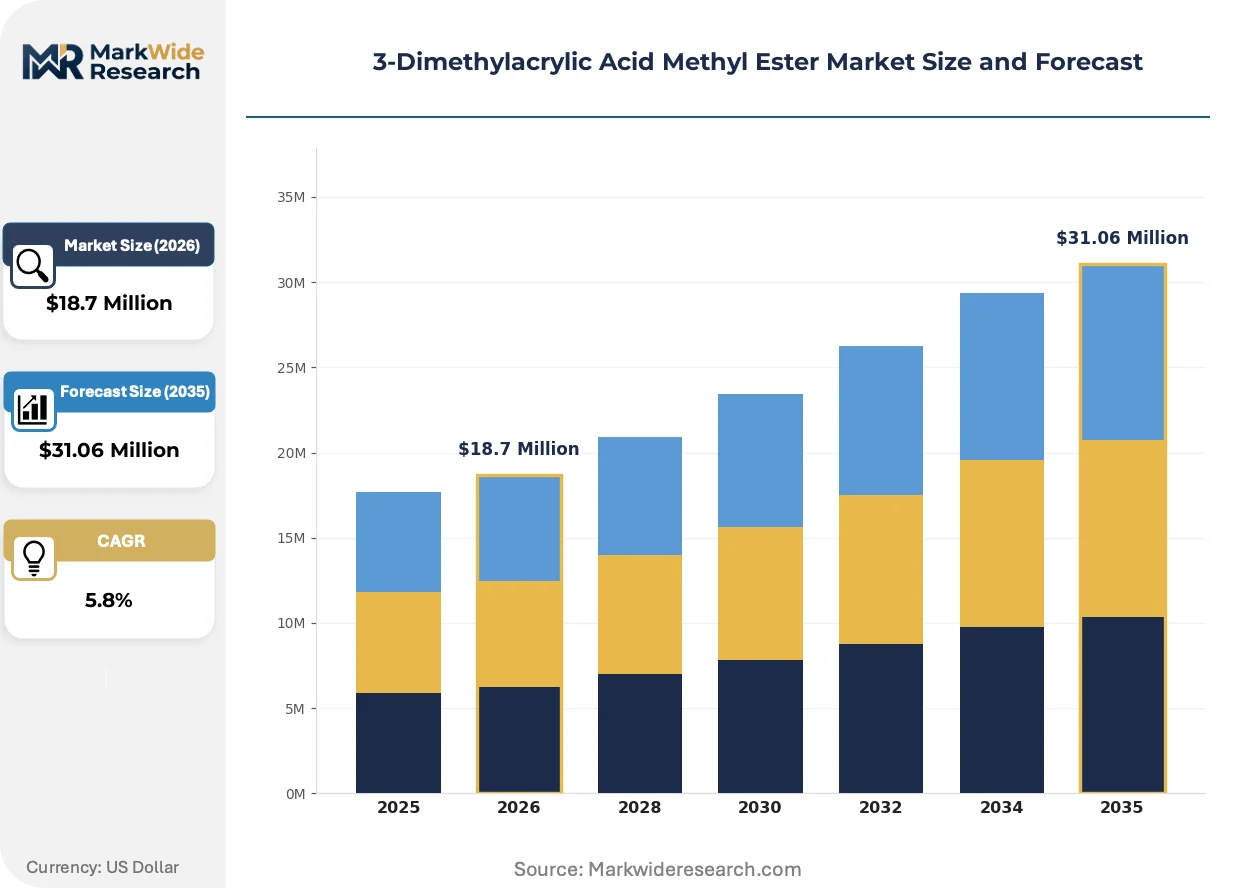
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $31.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monomers, Polymers, Speciality Chemicals, Additives End User: Paint & Coatings, Adhesives, Plastics, Textiles Application: Coating Solutions, Sealants, Ink Formulations, Film Production Technology: Batch Production, Continuous Processing, Polymerization Techniques, Green Chemistry |
| Companies Covered | WeylChem International GmbH, Qingdao Bangli Chemical Co., Ltd., Shandong Xinhua Pharmaceutical Co., Ltd., TCI Chemicals, Synerzine, Inc., Aurora Fine Chemicals, Spectrum Chemical Mfg. Corp., Hefei TNJ Chemical Industry Co., Ltd., Hunan Huateng Pharmaceutical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3-Dimethylacrylic Acid Methyl Ester Market Strategic Shifts
Process intensification and regulatory digitization are restructuring how methyl ester is manufactured, certified, and procured across pharmaceutical and coatings value chains.
Continuous flow reactor technology is decentralizing production economics for 3-dimethylacrylic acid methyl ester. Large sealant formulators in Germany and Japan are specifying continuous-process supply contracts to secure batch-to-batch consistency. This technology is decentralizing volume away from traditional batch-reactor dominant suppliers toward integrated chemical park operators with capital for flow chemistry installation.
REACH Article 33 supply chain communication obligations are forcing downstream disclosure of monomer content in coatings and adhesives. Specialty formulators must now document full substance composition, increasing demand for registered, high-purity grades with complete dossier transparency. Pharmaceutical intermediate buyers in Europe are responding by consolidating supplier lists around established registrants with robust data packages.
Specification-driven procurement is replacing spot-market purchasing for GMP-grade material. Large pharmaceutical manufacturers are embedding methyl ester suppliers into long-term active pharmaceutical ingredient development partnerships rather than transactional sourcing. This pattern is most visible in Switzerland and Germany, where Swissmedic and EMA inspection histories determine supplier qualification speed.
3-Dimethylacrylic Acid Methyl Ester Market Segmentation
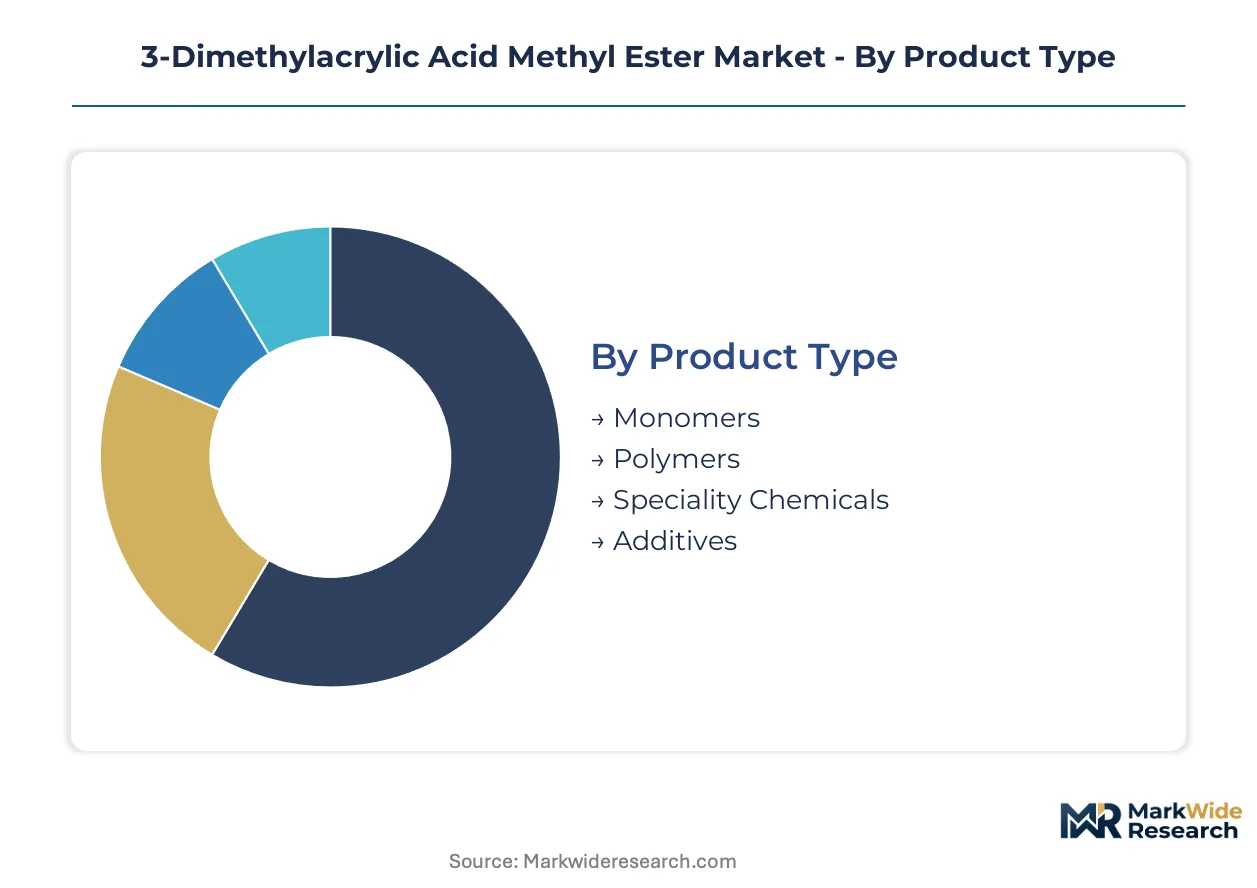
Segmentation reveals how 3-dimethylacrylic acid methyl ester demand fragments across distinct technical specifications and value chain positions. Each category carries different margin profiles, regulatory burdens, and customer consolidation patterns that reshape supplier strategy.
Product Type:
Monomer-grade material commands the volume base while specialty chemical variants capture premium pricing through certification overhead.
- Monomers:Unsaturated ester building blocks with defined boiling points and radical polymerization reactivity. Paint and coatings formulators in Germany and China concentrate purchases around monomer-grade supply for acrylic copolymer production, with REACH registration status determining supplier qualification speed.
- Speciality Chemicals:High-purity grades meeting EMA pharmaceutical quality guidelines and ICH Q3C residual solvent specifications. API manufacturers in Switzerland embed these suppliers into long-term development partnerships rather than transactional sourcing, extending procurement cycles but securing supply priority.
- Polymers:Pre-reacted copolymer intermediates reducing downstream formulation steps.
- Additives:Functional modifiers enhancing UV resistance or adhesion properties in coating systems.
Today's leader: Monomers. Tomorrow's challenger: Speciality Chemicals.
End User:
Application maturity separates established coatings demand from emerging adhesive specifications requiring lot-to-lot consistency.
- Paint & Coatings:The dominant consumption channel integrating methyl ester into industrial and automotive coating systems. Formulators in Japan specify continuous-process supply contracts to secure batch-to-batch uniformity that batch reactors cannot deliver.
- Adhesives:Sealant manufacturers drive specification tightening around viscosity stability and cure predictability. Large-volume purchasers in Germany are capturing interest in continuous processing installations to replace legacy batch supply.
- Plastics:Film and sheet producers utilizing methyl ester as comonomer feedstock.
- Textiles:Fiber treatment and finishing applications requiring specialized emulsion compatibility.
Coatings absorb the volume. Adhesives set the specification pace.
Application:
Functional requirements diverge between surface protection and containment applications.
- Coating Solutions:Protective and decorative film-forming systems dominating current revenue contribution. China's Shandong province chemical parks supply captive acrylic acid derivatives capacity that lowers unit production costs for regional coatings manufacturers.
- Sealants:Gap-filling and bonding formulations demanding precise rheological control. Japanese automotive sealant producers are shifting procurement toward continuous-process suppliers to eliminate lot variation in high-speed assembly lines.
- Ink Formulations:Printing applications requiring rapid solvent release and adhesion balance.
- Film Production:Cast and extruded film manufacturing utilizing methyl ester as processing aid or property modifier.
Coating Solutions anchor current supply. Sealants are climbing the fastest.
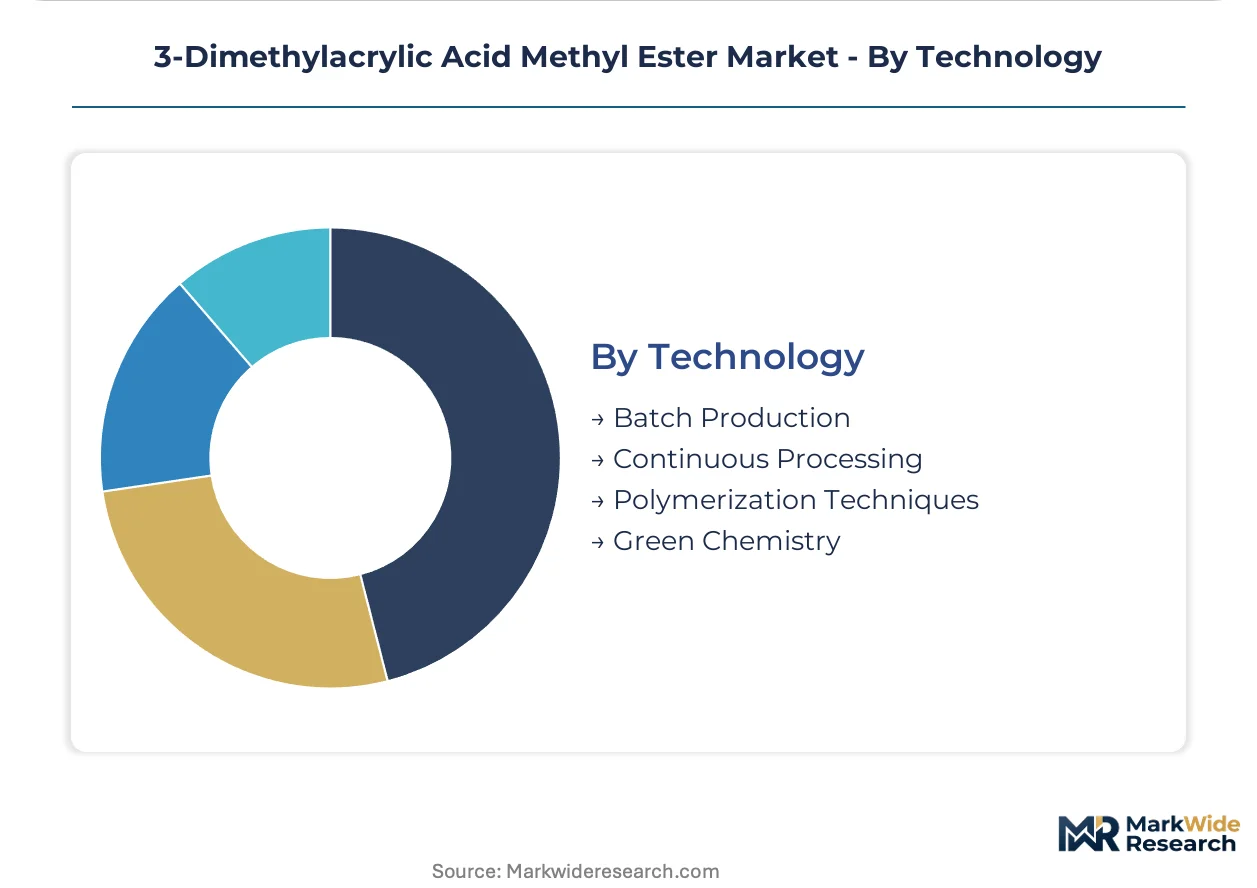
Technology:
Process architecture determines compliance cost absorption and consistency premiums.
- Batch Production:Conventional stirred-tank esterification occupying majority of installed capacity. Mid-cap producers without project finance access face capital intensity strains for continuous conversion retrofitting.
- Green Chemistry:Bio-based feedstock variants with third-party certification expanding most quickly. Brand-owner sustainability protocols in East Asia are creating premium pricing tiers that reshape procurement specifications.
- Continuous Processing:Flow reactor technology decentralizing volume toward integrated chemical park operators with installation capital.
- Polymerization Techniques:Controlled radical and ionic methods for specialized copolymer architectures.
Batch retains the installed base. Green Chemistry gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineering traditions established the foundation for high-purity methyl ester synthesis during the post-war industrial expansion. Japanese precision manufacturing requirements later refined quality specifications for electronic coatings applications. Chinese state-directed chemical park development now concentrates the majority of new capacity installations.
Germany
Automotive sealant manufacturers in Baden-Württemberg drive demand for batch-to-batch consistency in methyl ester supply. ECHA REACH registration requirements filter supplier qualification toward established dossier holders with complete substance data packages. The Frankfurt-Höchst industrial complex maintains integrated production infrastructure serving coatings formulators across the Rhine-Main region.
China
Shandong province chemical parks absorb the largest share of global methyl ester capacity expansion through captive acrylic acid derivative integration. MEE emission enforcement at esterification facilities accelerates consolidation toward integrated operators with shared treatment infrastructure. Qingdao and Yantai port cities anchor export logistics for pharmaceutical intermediate shipments to European API manufacturers.
Japan
Electronic coatings producers in the Kanto region specify continuous-process methyl ester contracts to eliminate lot variation in semiconductor packaging applications. METI industrial chemical safety standards shape handling protocols for high-purity monomer grades. Osaka-based adhesive formulators are capturing specification-setting influence through direct supplier partnership arrangements.
Switzerland
Swissmedic-inspected API manufacturers in Basel embed methyl ester suppliers into multi-year active pharmaceutical ingredient development partnerships. ICH Q3C residual solvent specifications determine qualification speed for GMP-grade material procurement. The country's pharmaceutical quality infrastructure attracts specialty chemical distributors seeking premium-tier positioning.
United States
Industrial coatings formulators in the Gulf Coast petrochemical corridor source methyl ester through established import channels given domestic batch production constraints. EPA toxic substance control provisions govern synthesis operations at remaining US-based esterification facilities. Texas and Louisiana chemical processing clusters focus on alternative acrylate chemistries with larger established demand bases.
3-Dimethylacrylic Acid Methyl Ester Market Competitive Environment
The competitive structure tilts toward integrated chemical park operators with captive feedstock access and compliance cost absorption capacity. Mid-cap batch producers without project finance access face capital intensity strains for continuous processing conversion. Three archetypes dominate: state-affiliated Chinese chemical conglomerates with provincial park integration, European specialty distributors with REACH registration portfolios, and Japanese catalog-grade suppliers serving research-scale demand. Capacity expansion and green chemistry certification represent the dominant competitive vectors reshaping supplier positioning.
Among German-anchored registrants, WeylChem International GmbH occupies a position exemplifying integrated manufacturing complex advantages. Chinese producers including Qingdao Bangli Chemical Co., Ltd. and Shandong Xinhua Pharmaceutical Co., Ltd. represent the state-directed chemical park expansion model. TCI Chemicals sits within the catalog-grade specialty distribution archetype serving Asia-Pacific research markets.
| Leading Market Players |
|---|
| WeylChem International GmbH |
| Qingdao Bangli Chemical Co., Ltd. |
| Shandong Xinhua Pharmaceutical Co., Ltd. |
| TCI Chemicals |
| Synerzine, Inc. |
| Aurora Fine Chemicals |
| Spectrum Chemical Mfg. Corp. |
| Hefei TNJ Chemical Industry Co., Ltd. |
| Hunan Huateng Pharmaceutical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between GMP-compliant pharmaceutical intermediates and industrial monomer grades manifests in both pricing premiums and supplier qualification timelines. REACH-registered European producers command substantial markups over Shandong-based batch operators, while continuous-process supply contracts in Japan and Germany embed consistency guarantees that reshape procurement specifications.
Pricing Analysis
Contractual service bundling separates spot-market methyl ester transactions from integrated supply partnerships. Three-tier pricing structure across GMP-certified, REACH-registered, and commodity-grade levels reflects EMA inspection history and ICH Q3C residual solvent compliance. Price differentiation stems from certification overhead and volume scale commitments. Pricing pressure stems from methanol feedstock volatility linked to natural gas and coal benchmarks. Small-batch coatings formulators exhibit highest price sensitivity; pharmaceutical API manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Methanol supply rests on coal-to-chemical complexes in China and natural gas reforming operations in the Middle East. Dimethylacrylic acid feedstock draws from acrylic acid derivative integration in Shandong province and captive refinery streams in Germany. Esterification capacity concentrates in China, Germany, and Japan. Single-source vulnerability runs through REACH-registered European facilities serving specialty coatings formulators. Distribution runs through integrated chemical park operators with captive logistics infrastructure and catalog-grade distributors serving research-scale demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Pharmaceutical intermediate buyers are consolidating supplier lists around established registrants with robust data packages, elevating specification compliance above transactional pricing.
For Market Incumbents: Acquire continuous processing technology assets to defend sealant formulation contracts against batch-reactor competitors. Backward integration into methanol supply agreements mitigates feedstock volatility exposure. Secure GMP certification ahead of EMA guideline expansions to capture API-grade volume commitments. For New Entrants and Emerging Players: Capture green chemistry certification white space in East Asian brand-owner sustainability protocols. Target adhesives segment procurement shifts toward bio-based feedstock variants with third-party verification. Establish direct supplier partnerships with Osaka-based formulators seeking lot-to-lot consistency guarantees. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap batch producers face capital intensity strains for continuous reactor retrofitting. Five-to-ten year viability favors integrated chemical park operators with captive feedstock access and shared emission treatment infrastructure. Watch MEE enforcement intensity at Shandong esterification facilities as inflection indicator for Chinese supply base restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive methanol supply agreements insulate margin compression from natural gas price volatility. |
| Green Manufacturing Transition | Bio-based feedstock certification unlocks premium pricing tiers in East Asian procurement specifications. |
| Long-term Supply Agreement | Continuous-process contracts with Japanese sealant manufacturers secure batch-to-batch consistency premiums. |
| Capacity Expansion | Flow reactor installations in Jiangsu chemical parks capture volume migrating from legacy batch operators. |
| Joint Venture | Swissmedic-inspected API partnerships in Basel embed suppliers into multi-year development programs. |
Study Parameters
Multiple input streams — primary interviews with specialty chemical plant managers, downstream coatings procurement leads, and pharmaceutical regulatory affairs directors; secondary validation through ECHA registration databases, customs trade flows, and SEC filings from listed chemical conglomerates; plus Cefic and ACC industry reports — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include grade tier, end-use industry, and regional production hub. CAGRs were derived from fitted growth curves applied to normalized baseline data. Forecast inputs incorporated REACH registration timelines and MEE emission enforcement trajectories.
Feedstock price volatility, regulatory reclassification of dual-use chemical export controls, and pharmaceutical quality guideline revisions are the dominant revision risks. Forecasts reflect documented assumptions subject to these vectors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
North America Construction Chemicals Market
Chemicals
South America Construction Chemicals Market
Chemicals
Perchloric Acid Market
Chemicals
Europe Textile Chemicals Market
Chemicals
US Methanol Market
Chemicals
Fungicide Active Ingredients Market
Chemicals
Fluoroantimonic Acid Market
Chemicals
Ferric Oxide Market
Chemicals
Isopropyl Alcohol (IPA) Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Europe Fluorosilicic Acid Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Gold Plating Chemicals Market
Chemicals
Global Pine Chemicals Market
Chemicals
Asia-Pacific Gamma Butyrolactone Market
Chemicals
Global Tetraacetylethylenediamine (TAED) Market