
 Aromatic Polyamine Market | 2026-2036
Aromatic Polyamine Market Size, Share, and Industry Trends Forecast 2026-2036
Aromatic Polyamine Market Outlook
Multi-source procurement from Asian specialty chemical suppliers is expanding as Western formulators reduce sole-source dependency on European aromatics. BASF leverages its Ludwigshafen integrated aromatics complex to sustain captive diaminotoluene supply for European coating customers. Covestro anchors its polyamine derivatives business through backward integration into aniline feedstocks at Antwerp. Silverline Chemicals competes on cost-focused triamine batches for Indian adhesive producers.
Aromatic polyamines constitute nitrogen-rich aromatic compounds featuring two or more amine functional groups attached to benzene or substituted benzene rings, typically synthesized through catalytic hydrogenation of nitroaromatics or nitration of aromatic hydrocarbons followed by reduction. These compounds serve primarily as epoxy curing agents, polyurethane chain extenders, and intermediates for high-performance polymers requiring thermal stability and chemical resistance. Curing agents command the dominant product position due to their indispensability in aerospace-grade epoxy formulations, while diamines represent the fastest-expanding category on wind blade resin demand. Coatings applications generate the deepest margin pools because of qualification barriers in aviation and marine protective systems.
EPA oversight under the Toxic Substances Control Act governs new chemical notifications for modified aromatic amines in US commerce, while REACH registration requirements in Europe mandate full toxicological dossiers for tonnage bands above one metric ton annually. China's MEE enforces emission standards on nitrobenzene reduction facilities that constrain regional production capacity. Stakeholders must monitor regulatory divergence between these jurisdictions to anticipate reformulation costs and supply chain requalification timelines.
Market Dynamics
Epoxy curing agent demand for aerospace composites is concentrating procurement power among wind turbine blade manufacturers and aviation tier-1 suppliers, forcing aromatic polyamine producers to requalify formulations against tightening purity mandates from REACH and EPA.
Growth Catalysts
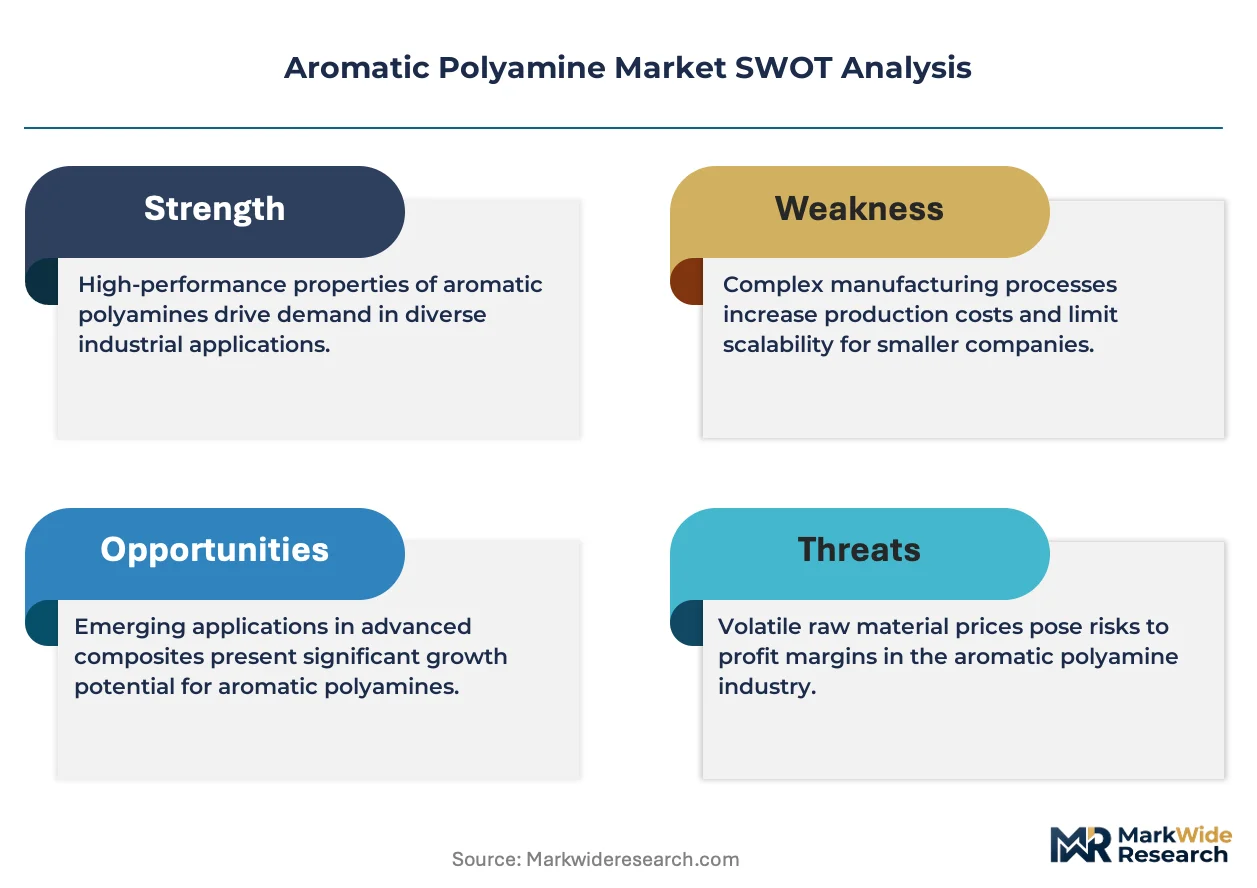
- REACH registration thresholds:European tonnage band requirements above one metric ton annually are consolidating compliant suppliers and eliminating marginal producers from cross-border supply chains.
- Wind blade resin demand:China's domestic epoxy production scaling for turbine manufacturing is pulling diamine consumption upward through backward-integrated chemical parks.
- Catalytic hydrogenation advances:Continuous-flow nitroaromatic reduction technologies are lowering unit production costs for high-purity aromatic amines in specialty applications.
Market Restraints
- Aniline feedstock volatility:Benzene-nitrobenzene price spreads compress margins unpredictably for non-integrated producers lacking captive aromatics supply.
- China MEE emission standards:Nitrobenzene reduction facility constraints cap regional production capacity and extend lead times for export orders.
- Aliphatic amine substitution:Cycloaliphatic curing agents are displacing aromatic variants in select coating applications where UV stability requirements moderate.
Strategic Opportunities
- India adhesive sector expansion:Domestic construction chemical growth is creating demand for cost-optimized triamine batches from regional specialty suppliers.
- EU Green Deal chemistry mandates:Bio-based aromatic amine precursors qualify for sustainable procurement preferences in public infrastructure coatings.
- Digital formulation platforms:AI-accelerated curing kinetics modeling is compressing customer qualification timelines for custom epoxy systems.
Industry Challenges
- Aerospace certification timelines:FAA and EASA material qualification protocols extend 18-36 months, freezing formulation changes for qualified suppliers.
- Process safety expertise scarcity:Nitroaromatic handling and hydrogenation operations require specialized chemical engineering talent concentrated in legacy industrial clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aromatic Polyamine Market |
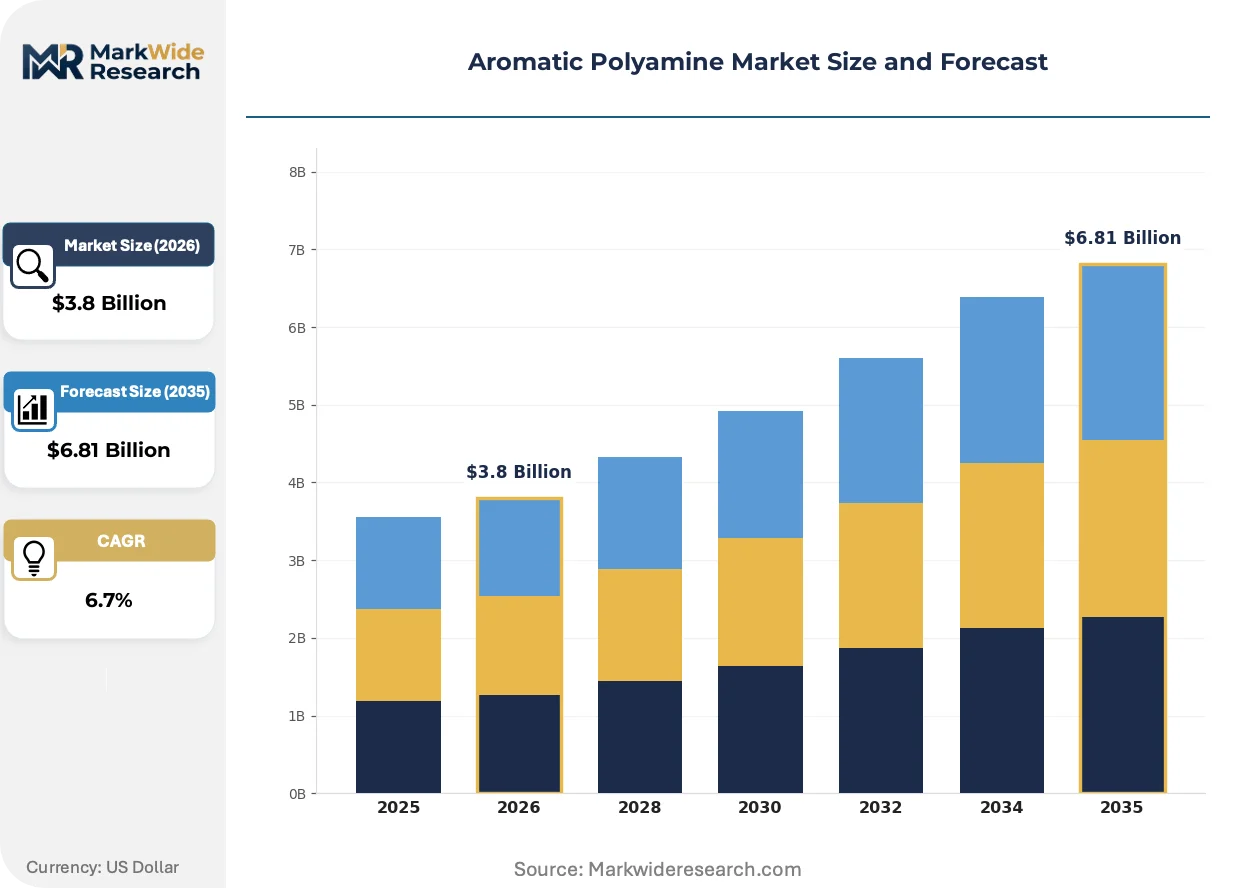
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diamines, Triamines, Polyamides, Curing Agents Application: Coatings, Adhesives, Composites, Inks End User: Aerospace, Automotive, Construction, Electronics Packaging Type: Bags, Drums, Containers, Bottles |
| Companies Covered | Silverline Chemicals, Veera Fragrances, Hindustan Mint & Agro Products, G.J. Chemical, Anderson Development Co., Lackwerke Peters, Coamong, BASF, Covestro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aromatic Polyamine Market Strategic Shifts
Continuous manufacturing technologies and regulatory data transparency requirements are restructuring how aromatic polyamine producers compete on speed-to-qualification rather than scale economies alone.
Flow chemistry for nitroaromatic hydrogenation is decentralizing production economics by enabling smaller-batch, higher-purity output without massive fixed-asset bases. Regional specialty chemical houses in India and Southeast Asia are adopting these skid-mounted systems to serve adhesive and coating formulators with faster turnaround. This technology is decentralizing the historical advantage of integrated aromatics complexes in Europe and North America.
REACH Article 33 supply chain communication obligations now mandate disclosure of Substances of Very High Concern above 0.1% weight concentration in imported aromatic amine formulations. European coating manufacturers are demanding full toxicological dossiers from Asian suppliers, forcing documentation investments that smaller exporters cannot absorb. Aviation-grade epoxy formulators face the steepest compliance burden as they dual-qualify against both ECHA and FAA material standards.
Specification-driven procurement now dominates wind energy sector buying, with blade manufacturers consolidating supplier lists to three qualified aromatic amine sources per region. Long-term offtake agreements with minimum purity guarantees are replacing spot market purchases. This pattern is most visible in China's coastal chemical parks, where turbine OEMs have co-located epoxy resin operations with pre-approved curing agent suppliers.
Aromatic Polyamine Market Segmentation
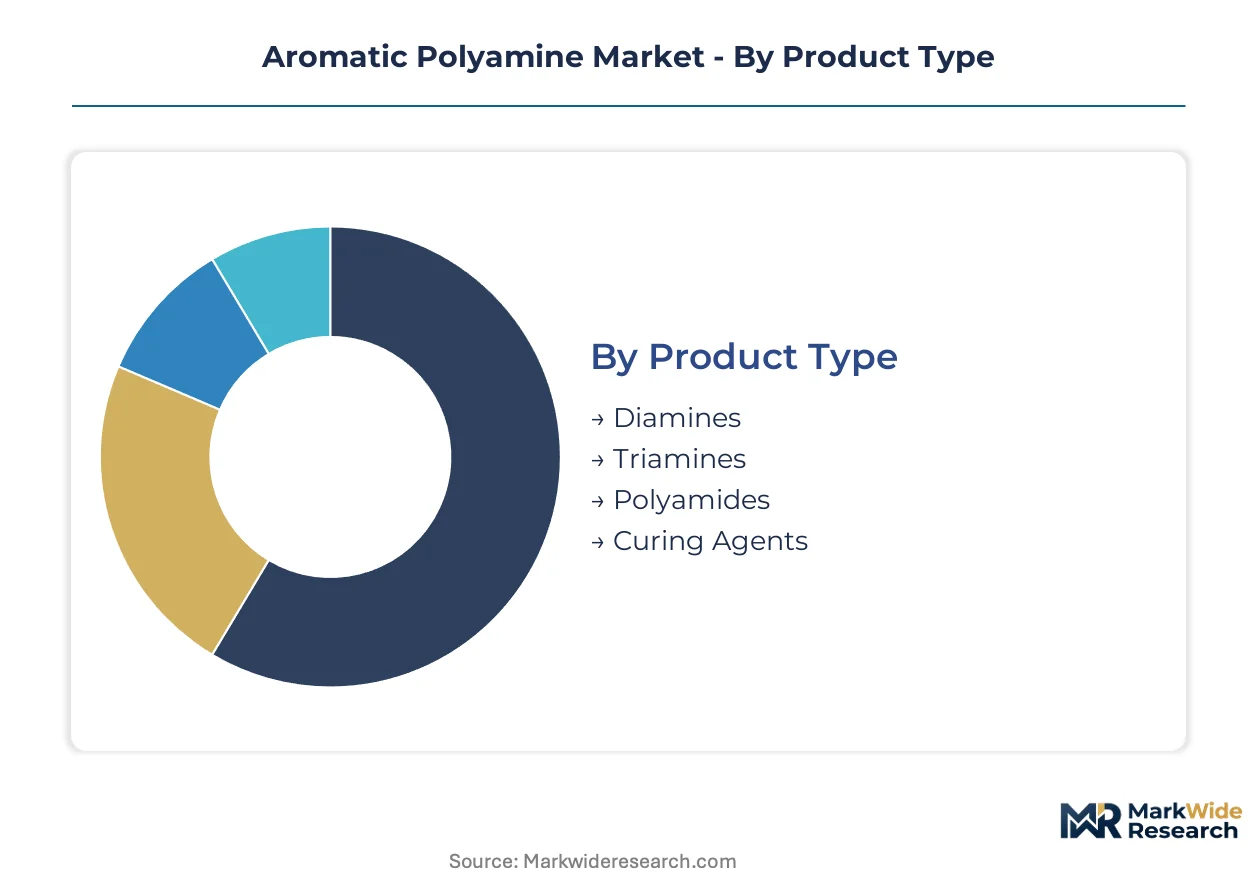
Aromatic polyamine suppliers configure production assets around curing agent specifications that lock in aerospace and wind energy customers for multi-year qualification cycles. Segmentation decisions determine which purity grades justify dedicated hydrogenation trains versus batch flexibility for smaller adhesive accounts.
Product Type:
Capital intensity peaks with continuous-flow hydrogenation systems for aerospace-grade diamines, while batch reactors serve cost-sensitive triamine markets.
- Curing Agents:Epoxy curing formulations for aerospace composites require 99.5%+ purity grades with full REACH dossiers and FAA material qualification. Procurement concentrates among tier-1 aviation suppliers and Chinese wind turbine blade manufacturers driving specification consolidation.
- Diamines:Two-amine aromatic structures synthesized through catalytic nitroaromatic reduction serve as chain extenders in high-performance polyurethanes. Demand from China's coastal chemical parks for wind blade epoxy systems is climbing the fastest among all product types.
- Triamines:Three-amine functionality delivers crosslink density for industrial adhesives and construction sealants. Silverline Chemicals and Indian specialty houses compete on cost-optimized batch production for domestic formulators.
- Polyamides:Amide-linked aromatic backbones provide thermal stability in high-temperature coating systems. Applications remain concentrated in European automotive underbody protection and marine protective coatings.
Most installed capacity flows through Curing Agents. Expansion is steepest in Diamines.
Application:
Margin structure separates aviation-qualified systems from construction-grade volumes, with qualification barriers creating distinct competitive arenas.
- Coatings:Marine and aviation protective systems command premium pricing contingent on ECHA and EPA dual compliance. Formulators in Germany's industrial clusters and US Gulf Coast shipyards anchor demand for high-purity aromatic amine hardeners.
- Composites:Carbon fiber-reinforced epoxy systems for aerospace primary structures and wind turbine blades represent the fastest-expanding application segment. China's turbine OEMs have co-located resin operations with pre-approved curing agent suppliers in coastal chemical parks.
- Adhesives:Structural bonding applications in automotive and construction use cost-optimized triamine formulations. Indian domestic construction chemical growth is pulling regional specialty production upward.
- Inks:Niche flexographic and gravure printing applications utilize aromatic polyamines as pigment dispersants and adhesion promoters. Volume remains limited compared to industrial coating applications.
Coatings generate the deepest margin pools. Composites are gaining share fastest.
End User:
Customer concentration patterns split between specification-driven aviation procurement and volume-driven construction buying.
- Aerospace:FAA and EASA material qualification protocols extend 18-36 months, freezing formulation changes for qualified suppliers. Tier-1 composite manufacturers in Toulouse, Hamburg, and Seattle anchor demand for certified curing agent grades.
- Construction:Domestic infrastructure spending in India and Southeast Asia drives cost-optimized triamine consumption for structural adhesives and concrete bonding agents. Regional specialty suppliers compete on turnaround speed versus purity specifications.
- Automotive:Underbody coatings and structural adhesives utilize aromatic polyamines for chemical resistance and thermal stability. European OEMs in Stuttgart and Wolfsburg specify REACH-compliant formulations for supply chain transparency.
- Electronics:Printed circuit board encapsulants and semiconductor packaging materials require ultra-low ionic content grades. Japanese and South Korean electronics clusters specify JIS and MFDS-aligned purity standards.
Aerospace commands the highest specification barriers. Construction offers the broadest volume base.
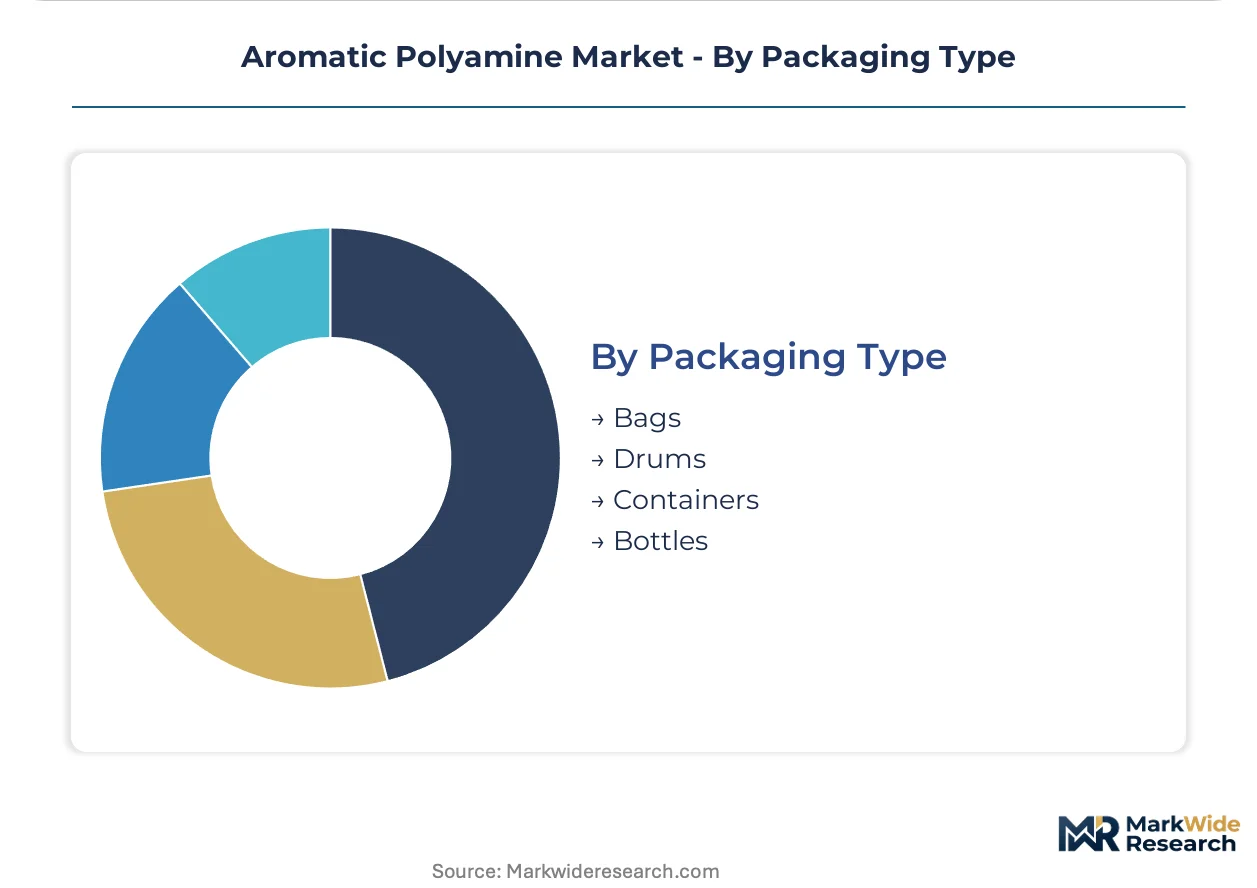
Packaging Type:
Logistics configuration tracks customer scale and regulatory documentation requirements across international supply chains.
- Drums:Standard 200-liter steel drums dominate industrial curing agent shipments to coating and adhesive formulators. REACH Article 33 compliance labeling and SDS documentation accompany EU-bound container loads.
- Containers:Bulk ISO tank containers serve wind blade resin producers in China's coastal chemical parks requiring continuous curing agent supply. Long-term offtake agreements specify minimum purity guarantees replacing spot purchases.
- Bags:Multi-layer laminated bags package powdered polyamide grades for construction adhesive dry blends. Indian and Southeast Asian distributors favor this format for humidity protection in tropical storage.
- Bottles:Laboratory and pilot-scale quantities in amber glass or fluoropolymer bottles serve formulation development and qualification testing. Aviation epoxy developers in Toulouse and Seattle require sample consistency for FAA submission batches.
Drums move the highest volume tonnage. Containers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting aromatic polyamine production toward jurisdictions with lower compliance burdens, as REACH dossier costs and EPA notification timelines widen the cost-of-compliance gap between Western and Asian manufacturing bases.
China
Wind turbine blade manufacturing in Jiangsu and Guangdong provinces consumes the majority of domestic diamine output. MEE emission standards on nitrobenzene reduction facilities constrain capacity expansion in inland provinces. Coastal chemical parks near Shanghai and Ningbo have co-located epoxy resin and curing agent operations to serve turbine OEMs.
Germany
BASF's Ludwigshafen integrated aromatics complex sustains captive diaminotoluene supply for European coating customers. REACH registration thresholds above one metric ton annually eliminate marginal producers from cross-border supply chains. The Rhine-Neckar industrial cluster maintains qualification protocols for aviation-grade epoxy formulators.
United States
EPA oversight under the Toxic Substances Control Act governs new chemical notifications for modified aromatic amines. Aerospace composite manufacturers in Seattle and Wichita anchor demand for certified curing agent grades. Gulf Coast shipyards specify high-purity hardeners for marine protective systems.
India
Domestic construction chemical growth in Maharashtra and Gujarat drives cost-optimized triamine consumption for structural adhesives. Silverline Chemicals competes on batch turnaround speed for regional adhesive producers. BIS standards for industrial chemicals create entry barriers for unqualified imports.
Belgium
Covestro anchors polyamine derivatives production through backward integration into aniline feedstocks at Antwerp. The port city's logistics infrastructure supports bulk ISO tank shipments to wind blade manufacturers. EU Green Deal chemistry mandates incentivize bio-based precursor development for public infrastructure coatings.
Aromatic Polyamine Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty qualification niches requiring extended certification timelines. The vendor base clusters around three archetypes: integrated petrochemical majors with captive aromatics supply, regional specialty houses competing on batch flexibility, and cost-focused batch producers serving construction-grade applications. Dominant competitive moves include backward integration into aniline feedstocks and long-term offtake agreements with wind turbine OEMs.
Within the integrated-major tier, BASF and Covestro exemplify producers leveraging captive feedstock positions to sustain margin stability. Among regional specialty suppliers, Silverline Chemicals occupies a position serving cost-sensitive adhesive markets in South Asia. These three entities represent distinct strategic postures: petrochemical integration, European regulatory compliance depth, and emerging-market volume capture.
| Leading Market Players |
|---|
| Silverline Chemicals |
| Veera Fragrances |
| Hindustan Mint & Agro Products |
| G.J. Chemical |
| Anderson Development Co. |
| Lackwerke Peters |
| Coamong |
| BASF |
| Covestro |
| Others |
Value Chain & Pricing Dynamics
Wind turbine blade manufacturers in China's coastal chemical parks are consolidating supplier lists to three qualified aromatic amine sources per region, forcing supply chains to absorb qualification costs and compressing margins for non-integrated producers lacking captive aniline feedstocks.
Pricing Analysis
Aniline-benzene price spreads transmit directly into aromatic polyamine cost structures, with integrated majors like BASF and Covestro insulating margin stability through captive aromatics supply. Three-tier pricing structure across aerospace-qualified, industrial-grade, and construction-optimized levels separates 99.5%+ purity diamines for aviation from cost-focused triamine batches for adhesives. Pricing pressure stems from REACH dossier investments and EPA notification timelines that smaller exporters cannot absorb. Construction-grade buyers in India and Southeast Asia exhibit highest price sensitivity, while aerospace tier-1 suppliers prioritize qualification continuity over unit cost.
Supply Chain Analysis
Aviation-grade material qualification protocols from FAA and EASA gate supply chain participation, extending 18-36 month timelines that freeze formulation changes and concentrate procurement among pre-approved suppliers. Production gravity centers on China, Germany, and Belgium, with coastal chemical parks near Shanghai and Ningbo co-locating epoxy resin and curing agent operations. Nitrobenzene, aniline, and hydrogen feedstocks anchor raw material dependencies, with benzene-nitrobenzene volatility compressing margins unpredictably. Single-source vulnerability concentrates in European REACH-registered suppliers for aerospace applications. Distribution runs through bulk ISO tank containers for wind blade manufacturers and standard 200-liter drums for coating formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on continuous-flow hydrogenation technologies that lower unit production costs for high-purity grades, alongside specification-driven consolidation that deepens pricing power for qualified suppliers.
For Market Incumbents: Lock in long-term offtake agreements with wind turbine OEMs through minimum purity guarantees that replace spot market exposure. Deepen backward integration into aniline feedstocks to sustain margin stability against benzene price volatility. Invest in REACH dossier maintenance and FAA material qualification continuity to defend against emerging flow-chemistry entrants in India and Southeast Asia.
For New Entrants and Emerging Players: Capture construction adhesive demand in Maharashtra and Gujarat through cost-optimized triamine batches with faster batch turnaround than established suppliers. Deploy skid-mounted continuous-flow systems to serve regional coating formulators without massive fixed-asset bases. Lead with BIS compliance and humidity-protected laminated bag packaging for tropical storage conditions.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialty houses possessing flow-chemistry capabilities and pre-qualified positions in wind energy supply chains. Five-to-ten year viability favors producers with dual ECHA-FAA compliance depth and coastal chemical park access in China. Monitor MEE emission standard enforcement on nitrobenzene reduction facilities as capacity constraint signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Feedstocks | Covestro's Antwerp complex demonstrates margin insulation against benzene-nitrobenzene spread volatility. |
| Continuous-Flow Hydrogenation Deployment | Skid-mounted systems enable Indian specialty houses to compete on batch flexibility without integrated aromatics complexes. |
| Long-Term Supply Agreement with Wind OEMs | Coastal chemical parks near Ningbo co-locate curing agent operations with turbine manufacturers under purity guarantees. |
| REACH Dossier Investment and Maintenance | European coating manufacturers demand full toxicological documentation that eliminates marginal Asian exporters. |
| Bio-Based Precursor Development | EU Green Deal chemistry mandates incentivize sustainable procurement preferences for public infrastructure coatings. |
Study Parameters
Multiple input streams — primary interviews with plant managers and procurement leads at downstream epoxy formulators, technical R&D directors at specialty chemical houses, and distribution channel partners across Asian supply routes — were reconciled against secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from integrated petrochemical majors. Bottom-up capacity and consumption estimates were cross-checked against top-down market sizing through triangulation across modeling approaches.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor projections across the analysis window. Segmentation dimensions modeled include product grade tier, end-use industry application, packaging format, and regional production hub cluster. CAGRs were derived through slope analysis of historical trajectories adjusted for structural shifts in wind blade resin demand and regulatory compliance cost pass-through. Forecast inputs incorporated catalytic hydrogenation technology diffusion rates and MEE emission standard enforcement patterns.
Underlying measurement precision varies by segment; aerospace-qualified curing agents carry tighter precision than construction-grade triamines due to visible procurement concentration and certification documentation. Forecasts reflect assumptions regarding REACH registration continuity, EPA notification timelines, and China domestic epoxy production scaling. A model refresh is warranted upon material change in MEE emission enforcement intensity or FAA-EASA qualification protocol divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Chemical As a Service Market
Chemicals
Brazil Methanol Market
Chemicals
Power Plant Chemicals Market
Chemicals
Calcium Disodium Ethylene Diamine Tetra-Acetate Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
Triethanolamine Market
Chemicals
Europe Methanol Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
p-Coumaric Acid Market
Chemicals
Paraphenylenediamine (PPD) Market
Chemicals
Sodium Cyanide Market
Chemicals
Solder Flux Market